S.Amdt. 801
What it does: Adds SEC. __. RENEWABLE LIQUID FUELS EXCISE TAX CREDIT at the end of subtitle E of title XV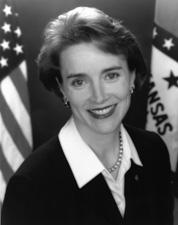 Sen. Blanche L. Lincoln (D-AR)
What it changes
1 change to S.Amdt. 800 · shown in S.Amdt. 800's text
Adds SEC. __. RENEWABLE LIQUID FUELS EXCISE TAX CREDIT at the end of subtitle E of title XV
Adds a sectionIn S.Amdt. 800 as proposed
(b) Report.--Not later than 2 years after the date on which the agreement under subsection (a) is entered into, the National Academy of Sciences shall submit to Congress a report on the study conducted under subsection (a).
Inserted: SEC. __. RENEWABLE LIQUID FUELS EXCISE TAX CREDIT.
Inserted: (a) In General.--Subchapter B of chapter 65 (relating to rules of special application) is amended by inserting after section 6426 the following new section:
Inserted: "SEC. 6426A. CREDIT FOR RENEWABLE LIQUID FUELS.
Inserted: "(a) Allowance of Credits.--There shall be allowed as a credit against the tax imposed by section 4081 an amount equal to the renewable liquid mixture credit.
Inserted: "(b) Renewable Liquid Mixture Credit.--
Inserted: "(1) In general.--For purposes of this section, the renewable liquid mixture credit is the product of the applicable amount and the number of gallons of renewable liquid used by the taxpayer in producing any renewable liquid mixture for sale or use in a trade or business of the taxpayer.
Inserted: "(2) Applicable amount.--For purposes of this section, the applicable amount is $1.00.
Inserted: "(3) Renewable liquid mixture.--For purposes of this section, the term 'renewable liquid mixture' means a mixture of renewable liquid and taxable fuel which--
Inserted: "(A) is sold by the taxpayer producing such mixture to any person for use as a fuel or feedstock, or
Inserted: "(B) is used as a fuel or feedstock by the taxpayer producing such mixture.
Inserted: For purposes of subparagraph (A), a mixture produced by any person at a refinery prior to a taxable event which includes renewable liquid shall be treated as sold at the time of its removal from the refinery (and only at such time) or sold to another person for use as a fuel or feedstock.
Inserted: "(c) Other Definitions.--For purposes of this subsection:
Show 66 more inserted paragraphsShow less
Inserted: "(1) Renewable liquid.--The term 'renewable liquid' means liquid fuels derived from waste and byproduct streams including; agricultural byproducts and wastes, aqua-culture products produced from waste streams, food processing plant byproducts, municipal solid and semi-solid waste streams, industrial waste streams, automotive scrap waste streams, and as further provided by regulations.
Inserted: "(2) Taxable fuel.--The term 'taxable fuel' has the meaning given such term by section 4083(a)(1).
Inserted: "(3) Feedstock.--The term 'feedstock' means any precursor material subject to further processing to make a petrochemical, solvent, or other fuel which has the effect of displacing conventional fuels, or products produced from conventional fuels.
Inserted: "(4) Additional definitions.--Any term used in this section which is also used in section 40B shall have the meaning given such term by section 40B.
Inserted: "(d) Certification for Renewable Liquid Fuel.--No credit shall be allowed under this section unless the taxpayer obtains a certification (in such form and manner as prescribed by the Secretary) from the producer of the renewable liquid fuel, which identifies the product produced.
Inserted: "(e) Mixture Not Used as Fuel, Etc.--
Inserted: "(1) Imposition of tax.--If--
Inserted: "(A) any credit was determined under this section with respect to renewable liquid used in the production of any renewable liquid mixture, and
Inserted: "(B) any person--
Inserted: "(i) separates the renewable liquid from the mixture, or
Inserted: "(ii) without separation, uses the mixture other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the applicable amount and the number of gallons of such renewable liquid.
Inserted: "(2) Applicable laws.--All provisions of law, including penalties, shall, insofar as applicable and not inconsistent with this section, apply in respect of any tax imposed under paragraph (1) as if such tax were imposed by section 4081 and not by this section.
Inserted: "(f) Coordination With Exemption From Excise Tax.--Rules similar to the rules under section 40 (c) shall apply for purposes of this section.
Inserted: "(g) Termination.--This section shall not apply to any sale, use, or removal for any period after December 31, 2010.".
Inserted: (b) Registration Requirement.--Section 4101(a)(1) (relating to registration), as amended by this Act, is amended by inserting "and every person producing or importing renewable liquid as defined in section 6426A(c)(1)" before "shall register with the Secretary".
Inserted: (c) Payments.--Section 6427 is amended by inserting after subsection (f) the following new subsection:
Inserted: "(g) Renewable Liquid Used to Produce Mixture.--
Inserted: "(1) Used to produce a mixture.--If any person produces a mixture described in section 6426A in such person's trade or business, the Secretary shall pay (without interest) to such person an amount equal to the renewable liquid mixture credit with respect to such mixture.
Inserted: "(2) Coordination with other repayment provisions.--No amount shall be payable under paragraph (1) with respect to any mixture with respect to which an amount is allowed as a credit under section 6426A.
Inserted: "(3) Termination.--This subsection shall not apply with respect to any renewable liquid fuel mixture (as defined in section 6426A(b)(3) sold or used after December 31, 2010.".
Inserted: (d) Conforming Amendment.--The last sentence of section 9503(b)(1) is amended by striking "section 6426" and inserting "sections 6426 and 6426A".
Inserted: (e) Clerical Amendment.--The table of sections for subchapter B of chapter 65 is amended by inserting after the item relating to section 6426 the following new item:
Inserted: "Sec. 6426A. Credit for renewable liquid fuels.".
Inserted: (f) Effective Dates.--
Inserted: (1) In general.--Except as otherwise provided in this subsection, the amendments made by this section shall apply to fuel sold or used on or after January 1, 2005.
Inserted: (2) Registration requirement.--The amendment made by subsection (b) shall take effect on the date of the enactment of this Act.
Inserted: SEC. __. RENEWABLE LIQUID INCOME TAX CREDIT.
Inserted: (a) In General.--Subpart D of part IV of subchapter A of chapter 1 (relating to business related credits) is amended by inserting after section 40A the following new section:
Inserted: "SEC. 40B. RENEWABLE LIQUID USED AS FUEL.
Inserted: "(a) General Rule.--For purposes of section 38, the renewable liquid credit determined under this section for the taxable year is an amount equal to the sum of--
Inserted: "(1) the renewable liquid mixture credit, plus
Inserted: "(2) the renewable liquid credit.
Inserted: "(b) Definition of Renewable Liquid Mixture Credit and Renewable Liquid Credit.--For purposes of this section--
Inserted: "(1) Renewable liquid mixture credit.--
Inserted: "(A) In general.--The renewable liquid mixture credit of any taxpayer for any taxable year is $1.00 for each gallon of renewable liquid fuel used by the taxpayer in the production of a qualified renewable liquid fuel mixture.
Inserted: "(B) Qualified renewable liquid mixture.--The term 'qualified renewable liquid mixture' means a mixture of renewable liquid and taxable fuel (as defined in section 4083(a)(1)), which--
Inserted: "(i) is sold by the taxpayer producing such a mixture to any person for use as a fuel or feedstock, or
Inserted: "(ii) is used as a fuel or feedstock by the taxpayer producing such mixture.
Inserted: "(C) Sale or use must be in trade or business, etc.--Renewable liquid used in the production of a qualified renewable liquid fuel mixture shall be taken into account--
Inserted: "(i) only if the sale or use described in subparagraph (B) is in a trade or business of the taxpayer, and
Inserted: "(ii) for the taxable year in which such sale or use occurs.
Inserted: "(2) Renewable liquid credit.--
Inserted: "(A) In general.--The renewable liquid credit of any taxpayer for any taxable year is $1.00 for each gallon of renewable liquid which is not in a mixture with taxable fuel and which during the taxable year--
Inserted: "(i) is used by the taxpayer as a fuel or feedstock in a trade or business, or
Inserted: "(ii) is sold by the taxpayer at retail to a person and placed in the fuel tank of such person's vehicle.
Inserted: "(B) User credit not to apply to renewable liquid sold at retail.--No credit shall be allowed under subparagraph (A)(i) with respect to any renewable liquid which was sold in a retail sale described in subparagraph (A)(ii).
Inserted: "(c) Certification for Renewable Liquid.--No credit shall be allowed under this section unless the taxpayer obtains a certification (in such form and manner as prescribed by the Secretary) from the producer or importer of the renewable liquid fuel which identifies the product produced and percentage of renewable liquid fuel in the product.
Inserted: "(d) Coordination With Credit Against Excise Tax.--The amount of the credit determined under this section with respect to any renewable liquid fuel shall be properly reduced to take into account any benefit provided with respect to such renewable liquid fuel solely by reason of the application of section 6426A or 6427(g).
Inserted: "(e) Definitions and Special Rules.--For purposes of this section, the term 'renewable liquid' means liquid fuels derived from waste and byproduct streams including; agricultural byproducts and wastes, agriculture materials produced from waste streams, food processing plant byproducts, municipal solid and semi-solid waste streams, industrial waste streams, automotive scrap waste streams, as further provided by regulations.
Inserted: "(f) Mixture or Renewable Liquid Not Used as a Fuel, Etc.--
Inserted: "(1) Mixtures.--If--
Inserted: "(A) any credit was determined under this section with respect to renewable liquid used in the production of any qualified renewable liquid mixture, and
Inserted: "(B) any person--
Inserted: "(i) separates the renewable liquid from the mixture, or
Inserted: "(ii) without separation, uses the mixture other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the rate applicable under subsection (b)(1)(A) and the number of gallons of such renewable liquid in such mixture.
Inserted: "(2) Renewable liquid.--If--
Inserted: "(A) any credit was determined under this section with respect to the retail sale of any renewable liquid, and
Inserted: "(B) any person mixes such renewable liquid or uses such renewable liquid other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the rate applicable under subsection (b)(2)(A) and the number of gallons of such renewable liquid.
Inserted: "(3) Applicable laws.--All provisions of law, including penalties, shall, insofar as applicable and not inconsistent with this section, apply in respect of any tax imposed under subparagraph (A) or (B) as if such tax were imposed by section 4081 and not by this chapter.
Inserted: "(g) Pass-Thru in the Case of Estates and Trusts.--Under regulations prescribed by the Secretary, rules similar to the rules of subsection (d) of section 52 shall apply.
Inserted: "(h) Termination.--This section shall not apply to any sale or use after December 31, 2010.".
Inserted: (b) Credit Treated as Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 (relating to current year business credit), as amended by this Act, is amended by striking "plus" at the end of paragraph (23), by striking the period at the end of paragraph (24), and inserting ", plus", and by inserting after paragraph (24) the following new paragraph:
Inserted: "(25) The renewable liquid credit determined under section 40B.".
Inserted: (c) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter I of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 40A the following new item:
Inserted: "Sec. 40B. Renewable liquid used as fuel.".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to fuel produced, and sold as used, on or after January 1, 2005.
Original wording
At the end of subtitle E of title XV (relating to energy policy tax incentives) add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 801. Mrs. LINCOLN submitted an amendment intended to be proposed to amendment SA 800 submitted by Mr. Grassley (for himself and Mr. Baucus) to the bill H.R. 6, Reserved; which was ordered to lie on the table; as follows:
At the end of subtitle E of title XV (relating to energy policy tax incentives) add the following:
SEC. __. RENEWABLE LIQUID FUELS EXCISE TAX CREDIT.
(a) In General.--Subchapter B of chapter 65 (relating to rules of special application) is amended by inserting after section 6426 the following new section:
“SEC. 6426A. CREDIT FOR RENEWABLE LIQUID FUELS.
“(a) Allowance of Credits.--There shall be allowed as a credit against the tax imposed by section 4081 an amount equal to the renewable liquid mixture credit.
“(b) Renewable Liquid Mixture Credit.--
“(1) In general.--For purposes of this section, the renewable liquid mixture credit is the product of the applicable amount and the number of gallons of renewable liquid used by the taxpayer in producing any renewable liquid mixture for sale or use in a trade or business of the taxpayer.
“(2) Applicable amount.--For purposes of this section, the applicable amount is $1.00.
“(3) Renewable liquid mixture.--For purposes of this section, the term ‘renewable liquid mixture' means a mixture of renewable liquid and taxable fuel which--
“(A) is sold by the taxpayer producing such mixture to any person for use as a fuel or feedstock, or
“(B) is used as a fuel or feedstock by the taxpayer producing such mixture.
For purposes of subparagraph (A), a mixture produced by any person at a refinery prior to a taxable event which includes renewable liquid shall be treated as sold at the time of its removal from the refinery (and only at such time) or sold to another person for use as a fuel or feedstock.
“(c) Other Definitions.--For purposes of this subsection:
“(1) Renewable liquid.--The term ‘renewable liquid' means liquid fuels derived from waste and byproduct streams including; agricultural byproducts and wastes, aqua-culture products produced from waste streams, food processing plant byproducts, municipal solid and semi-solid waste streams, industrial waste streams, automotive scrap waste streams, and as further provided by regulations.
“(2) Taxable fuel.--The term ‘taxable fuel' has the meaning given such term by section 4083(a)(1).
“(3) Feedstock.--The term ‘feedstock' means any precursor material subject to further processing to make a petrochemical, solvent, or other fuel which has the effect of displacing conventional fuels, or products produced from conventional fuels.
“(4) Additional definitions.--Any term used in this section which is also used in section 40B shall have the meaning given such term by section 40B.
“(d) Certification for Renewable Liquid Fuel.--No credit shall be allowed under this section unless the taxpayer obtains a certification (in such form and manner as prescribed by the Secretary) from the producer of the renewable liquid fuel, which identifies the product produced.
“(e) Mixture Not Used as Fuel, Etc.--
“(1) Imposition of tax.--If--
“(A) any credit was determined under this section with respect to renewable liquid used in the production of any renewable liquid mixture, and
“(B) any person--
“(i) separates the renewable liquid from the mixture, or
“(ii) without separation, uses the mixture other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the applicable amount and the number of gallons of such renewable liquid.
“(2) Applicable laws.--All provisions of law, including penalties, shall, insofar as applicable and not inconsistent with this section, apply in respect of any tax imposed under paragraph (1) as if such tax were imposed by section 4081 and not by this section.
“(f) Coordination With Exemption From Excise Tax.--Rules similar to the rules under section 40 (c) shall apply for purposes of this section.
“(g) Termination.--This section shall not apply to any sale, use, or removal for any period after December 31, 2010.”.
(b) Registration Requirement.--Section 4101(a)(1) (relating to registration), as amended by this Act, is amended by inserting “and every person producing or importing renewable liquid as defined in section 6426A(c)(1)” before “shall register with the Secretary”.
(c) Payments.--Section 6427 is amended by inserting after subsection (f) the following new subsection:
“(g) Renewable Liquid Used to Produce Mixture.--
“(1) Used to produce a mixture.--If any person produces a mixture described in section 6426A in such person's trade or business, the Secretary shall pay (without interest) to such person an amount equal to the renewable liquid mixture credit with respect to such mixture.
“(2) Coordination with other repayment provisions.--No amount shall be payable under paragraph (1) with respect to any mixture with respect to which an amount is allowed as a credit under section 6426A.
“(3) Termination.--This subsection shall not apply with respect to any renewable liquid fuel mixture (as defined in section 6426A(b)(3) sold or used after December 31, 2010.”.
(d) Conforming Amendment.--The last sentence of section 9503(b)(1) is amended by striking “section 6426” and inserting “sections 6426 and 6426A”.
(e) Clerical Amendment.--The table of sections for subchapter B of chapter 65 is amended by inserting after the item relating to section 6426 the following new item:
“Sec. 6426A. Credit for renewable liquid fuels.”.
(f) Effective Dates.--
(1) In general.--Except as otherwise provided in this subsection, the amendments made by this section shall apply to fuel sold or used on or after January 1, 2005.
(2) Registration requirement.--The amendment made by subsection (b) shall take effect on the date of the enactment of this Act.
SEC. __. RENEWABLE LIQUID INCOME TAX CREDIT.
(a) In General.--Subpart D of part IV of subchapter A of chapter 1 (relating to business related credits) is amended by inserting after section 40A the following new section:
“SEC. 40B. RENEWABLE LIQUID USED AS FUEL.
“(a) General Rule.--For purposes of section 38, the renewable liquid credit determined under this section for the taxable year is an amount equal to the sum of--
“(1) the renewable liquid mixture credit, plus
“(2) the renewable liquid credit.
“(b) Definition of Renewable Liquid Mixture Credit and Renewable Liquid Credit.--For purposes of this section--
“(1) Renewable liquid mixture credit.--
“(A) In general.--The renewable liquid mixture credit of any taxpayer for any taxable year is $1.00 for each gallon of renewable liquid fuel used by the taxpayer in the production of a qualified renewable liquid fuel mixture.
“(B) Qualified renewable liquid mixture.--The term ‘qualified renewable liquid mixture' means a mixture of renewable liquid and taxable fuel (as defined in section 4083(a)(1)), which--
“(i) is sold by the taxpayer producing such a mixture to any person for use as a fuel or feedstock, or
“(ii) is used as a fuel or feedstock by the taxpayer producing such mixture.
“(C) Sale or use must be in trade or business, etc.--Renewable liquid used in the production of a qualified renewable liquid fuel mixture shall be taken into account--
“(i) only if the sale or use described in subparagraph (B) is in a trade or business of the taxpayer, and
“(ii) for the taxable year in which such sale or use occurs.
“(2) Renewable liquid credit.--
“(A) In general.--The renewable liquid credit of any taxpayer for any taxable year is $1.00 for each gallon of renewable liquid which is not in a mixture with taxable fuel and which during the taxable year--
“(i) is used by the taxpayer as a fuel or feedstock in a trade or business, or
“(ii) is sold by the taxpayer at retail to a person and placed in the fuel tank of such person's vehicle.
“(B) User credit not to apply to renewable liquid sold at retail.--No credit shall be allowed under subparagraph (A)(i) with respect to any renewable liquid which was sold in a retail sale described in subparagraph (A)(ii).
“(c) Certification for Renewable Liquid.--No credit shall be allowed under this section unless the taxpayer obtains a certification (in such form and manner as prescribed by the Secretary) from the producer or importer of the renewable liquid fuel which identifies the product produced and percentage of renewable liquid fuel in the product.
“(d) Coordination With Credit Against Excise Tax.--The amount of the credit determined under this section with respect to any renewable liquid fuel shall be properly reduced to take into account any benefit provided with respect to such renewable liquid fuel solely by reason of the application of section 6426A or 6427(g).
“(e) Definitions and Special Rules.--For purposes of this section, the term ‘renewable liquid' means liquid fuels derived from waste and byproduct streams including; agricultural byproducts and wastes, agriculture materials produced from waste streams, food processing plant byproducts, municipal solid and semi-solid waste streams, industrial waste streams, automotive scrap waste streams, as further provided by regulations.
“(f) Mixture or Renewable Liquid Not Used as a Fuel, Etc.--
“(1) Mixtures.--If--
“(A) any credit was determined under this section with respect to renewable liquid used in the production of any qualified renewable liquid mixture, and
“(B) any person--
“(i) separates the renewable liquid from the mixture, or
“(ii) without separation, uses the mixture other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the rate applicable under subsection (b)(1)(A) and the number of gallons of such renewable liquid in such mixture.
“(2) Renewable liquid.--If--
“(A) any credit was determined under this section with respect to the retail sale of any renewable liquid, and
“(B) any person mixes such renewable liquid or uses such renewable liquid other than as a fuel, then there is hereby imposed on such person a tax equal to the product of the rate applicable under subsection (b)(2)(A) and the number of gallons of such renewable liquid.
“(3) Applicable laws.--All provisions of law, including penalties, shall, insofar as applicable and not inconsistent with this section, apply in respect of any tax imposed under subparagraph (A) or (B) as if such tax were imposed by section 4081 and not by this chapter.
“(g) Pass-Thru in the Case of Estates and Trusts.--Under regulations prescribed by the Secretary, rules similar to the rules of subsection (d) of section 52 shall apply.
“(h) Termination.--This section shall not apply to any sale or use after December 31, 2010.”.
(b) Credit Treated as Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 (relating to current year business credit), as amended by this Act, is amended by striking “plus” at the end of paragraph (23), by striking the period at the end of paragraph (24), and inserting “, plus”, and by inserting after paragraph (24) the following new paragraph:
“(25) The renewable liquid credit determined under section 40B.”.
(c) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter I of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 40A the following new item:
“Sec. 40B. Renewable liquid used as fuel.”.
(d) Effective Date.--The amendments made by this section shall apply to fuel produced, and sold as used, on or after January 1, 2005.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
June 20, 2005