S.Amdt. 820
What it does: Adds SEC. __. AMORTIZATION OF DELAY RENTAL PAYMENTS wherever appropriate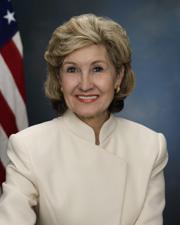 Sen. Kay Bailey Hutchison (R-TX)
What it changes
1 change to H.R. 6
Adds SEC. __. AMORTIZATION OF DELAY RENTAL PAYMENTS wherever appropriate
Adds a sectionInserted: SEC. __. AMORTIZATION OF DELAY RENTAL PAYMENTS.
Inserted: (a) In General.--Section 167 (relating to depreciation) is amended by redesignating subsection (h) as subsection (i) and by inserting after subsection (g) the following new subsection:
Inserted: "(h) Amortization of Delay Rental Payments for Domestic Oil and Gas Wells.--
Inserted: "(1) In general.--Any delay rental payment paid or incurred in connection with the development of oil or gas wells within the United States (as defined in section 638) shall be allowed as a deduction ratably over the 24-month period beginning on the date that such payment was paid or incurred.
Inserted: "(2) Half-year convention.--For purposes of paragraph (1), any payment paid or incurred during the taxable year shall be treated as paid or incurred on the mid-point of such taxable year.
Inserted: "(3) Exclusive method.--Except as provided in this subsection, no depreciation or amortization deduction shall be allowed with respect to such payments.
Inserted: "(4) Treatment upon abandonment.--If any property to which a delay rental payment relates is retired or abandoned during the 24-month period described in paragraph (1), no deduction shall be allowed on account of such retirement or abandonment and the amortization deduction under this subsection shall continue with respect to such payment.
Inserted: "(5) Delay rental payments.--For purposes of this subsection, the term 'delay rental payment' means an amount paid for the privilege of deferring development of an oil or gas well under an oil or gas lease.".
Inserted: (b) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred in taxable years beginning after the date of the enactment of this Act.
Inserted: SEC. __. AMORTIZATION OF GEOLOGICAL AND GEOPHYSICAL EXPENDITURES.
Inserted: (a) In General.--Section 167 (relating to depreciation), as amended by this Act, is amended by redesignating subsection (i) as subsection (j) and by inserting after subsection (h) the following new subsection:
Inserted: "(i) Amortization of Geological and Geophysical Expenditures.--
Show 4 more inserted paragraphsShow less
Inserted: "(1) In general.--Any geological and geophysical expenses paid or incurred in connection with the exploration for, or development of, oil or gas within the United States (as defined in section 638) shall be allowed as a deduction ratably over the 24-month period beginning on the date that such expense was paid or incurred.
Inserted: "(2) Special rules.--For purposes of this subsection, rules similar to the rules of paragraphs (2), (3), and (4) of subsection (h) shall apply.".
Inserted: (b) Conforming Amendment.--Section 263A(c)(3) is amended by inserting "167(h), 167(i)," after "under section".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred in taxable years beginning after the date of the enactment of this Act.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 820. Mrs. HUTCHISON (for herself, Mr. Cornyn, Mr. Inhofe, and Ms. Landrieu) submitted an amendment intended to be proposed by her to the bill H.R. 6, to ensure jobs for our future with secure, affordable, and reliable energy; which was ordered to lie on the table; as follows:
At the appropriate place insert the following:
SEC. __. AMORTIZATION OF DELAY RENTAL PAYMENTS.
(a) In General.--Section 167 (relating to depreciation) is amended by redesignating subsection (h) as subsection (i) and by inserting after subsection (g) the following new subsection:
“(h) Amortization of Delay Rental Payments for Domestic Oil and Gas Wells.--
“(1) In general.--Any delay rental payment paid or incurred in connection with the development of oil or gas wells within the United States (as defined in section 638) shall be allowed as a deduction ratably over the 24-month period beginning on the date that such payment was paid or incurred.
“(2) Half-year convention.--For purposes of paragraph (1), any payment paid or incurred during the taxable year shall be treated as paid or incurred on the mid-point of such taxable year.
“(3) Exclusive method.--Except as provided in this subsection, no depreciation or amortization deduction shall be allowed with respect to such payments.
“(4) Treatment upon abandonment.--If any property to which a delay rental payment relates is retired or abandoned during the 24-month period described in paragraph (1), no deduction shall be allowed on account of such retirement or abandonment and the amortization deduction under this subsection shall continue with respect to such payment.
“(5) Delay rental payments.--For purposes of this subsection, the term ‘delay rental payment' means an amount paid for the privilege of deferring development of an oil or gas well under an oil or gas lease.”.
(b) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred in taxable years beginning after the date of the enactment of this Act.
SEC. __. AMORTIZATION OF GEOLOGICAL AND GEOPHYSICAL EXPENDITURES.
(a) In General.--Section 167 (relating to depreciation), as amended by this Act, is amended by redesignating subsection (i) as subsection (j) and by inserting after subsection (h) the following new subsection:
“(i) Amortization of Geological and Geophysical Expenditures.--
“(1) In general.--Any geological and geophysical expenses paid or incurred in connection with the exploration for, or development of, oil or gas within the United States (as defined in section 638) shall be allowed as a deduction ratably over the 24-month period beginning on the date that such expense was paid or incurred.
“(2) Special rules.--For purposes of this subsection, rules similar to the rules of paragraphs (2), (3), and (4) of subsection (h) shall apply.”.
(b) Conforming Amendment.--Section 263A(c)(3) is amended by inserting “167(h), 167(i),” after “under section”.
(c) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred in taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
June 21, 2005