S.Amdt. 884
What it does: Adds SEC. __. CREDIT FOR INTANGIBLE DRILLING COSTS wherever appropriate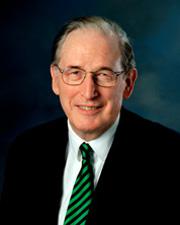 Sen. John D. Rockefeller IV (D-WV)
What it changes
1 change to H.R. 6
Adds SEC. __. CREDIT FOR INTANGIBLE DRILLING COSTS wherever appropriate
Adds a sectionInserted: SEC. __. CREDIT FOR INTANGIBLE DRILLING COSTS.
Inserted: (a) In General.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to business related credits), as amended by this Act, is amended by adding at the end the following new section:
Inserted: "SEC. 45O. INTANGIBLE DRILLING COSTS CREDIT.
Inserted: "(a) In General.--For purposes of section 38, the intangible drilling costs credit for the taxable year is an amount equal to 15 percent of the intangible drilling costs (within the meaning of section 263(c)) paid or incurred during the taxable year in connection with each qualifying natural gas well.
Inserted: "(b) Limitation.--The aggregate amount of credit allowed under this section for all taxable years shall not exceed $50,000 with respect to any qualifying natural gas well.
Inserted: "(c) Qualifying Natural Gas Well.--For purposes of this section, the term 'qualifying natural gas well' means a natural gas well--
Inserted: "(1) which is placed in service before the date that is 3 years after the date of the enactment of this section,
Inserted: "(2) which produces a qualified fuel (as defined in section 29(c)), and
Inserted: "(3) the basis of which is $200,000 or greater.
Inserted: "(d) Denial of Double Benefit.--No deduction shall be allowed under section 263(c) for any cost for which a credit is allowed under this section.".
Inserted: (b) Credit Treated as Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 (relating to general business credit), as amended by this Act, is amended by striking "plus" at the end of paragraph (23), by striking the period at the end of paragraph (24) and inserting ", plus", and by adding at the end the following new paragraph:
Inserted: "(25) the intangible drill costs credit determined under section 45O.".
Show 5 more inserted paragraphsShow less
Inserted: (c) No Carryback of Credit.--Section 39 of the Internal Revenue Code of 1986 (relating to carryback and carryforward of unused credit) is amended by adding at the end the following new subsection:
Inserted: "(e) Special Rule for Intangible Drilling Costs Credit.--No portion of the unused credit which is attributable to the intangible drilling costs credit under section 45O may be taken into account under section 38(a)(3).".
Inserted: (d) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986, as amended by this Act, is amended by inserting after the item relating to section 45N the following new item:
Inserted: "Sec. 45O. Intangible drilling costs credit.".
Inserted: (e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 884. Mr. ROCKEFELLER (for himself, Mr. Bingaman, and Mr. Bunning) submitted an amendment intended to be proposed by him to the bill H.R. 6, to ensure jobs for our future with secure, affordable, and reliable energy; which was ordered to lie on the table; as follows:
At the appropriate place, insert the following:
SEC. __. CREDIT FOR INTANGIBLE DRILLING COSTS.
(a) In General.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to business related credits), as amended by this Act, is amended by adding at the end the following new section:
“SEC. 45O. INTANGIBLE DRILLING COSTS CREDIT.
“(a) In General.--For purposes of section 38, the intangible drilling costs credit for the taxable year is an amount equal to 15 percent of the intangible drilling costs (within the meaning of section 263(c)) paid or incurred during the taxable year in connection with each qualifying natural gas well.
“(b) Limitation.--The aggregate amount of credit allowed under this section for all taxable years shall not exceed $50,000 with respect to any qualifying natural gas well.
“(c) Qualifying Natural Gas Well.--For purposes of this section, the term ‘qualifying natural gas well' means a natural gas well--
“(1) which is placed in service before the date that is 3 years after the date of the enactment of this section,
“(2) which produces a qualified fuel (as defined in section 29(c)), and
“(3) the basis of which is $200,000 or greater.
“(d) Denial of Double Benefit.--No deduction shall be allowed under section 263(c) for any cost for which a credit is allowed under this section.”.
(b) Credit Treated as Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 (relating to general business credit), as amended by this Act, is amended by striking “plus” at the end of paragraph (23), by striking the period at the end of paragraph (24) and inserting “, plus”, and by adding at the end the following new paragraph:
“(25) the intangible drill costs credit determined under section 45O.”.
(c) No Carryback of Credit.--Section 39 of the Internal Revenue Code of 1986 (relating to carryback and carryforward of unused credit) is amended by adding at the end the following new subsection:
“(e) Special Rule for Intangible Drilling Costs Credit.--No portion of the unused credit which is attributable to the intangible drilling costs credit under section 45O may be taken into account under section 38(a)(3).”.
(d) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986, as amended by this Act, is amended by inserting after the item relating to section 45N the following new item:
“Sec. 45O. Intangible drilling costs credit.”.
(e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
June 22, 2005