To protect families most vulnerable to foreclosure due to a sudden loss of income by extending the depreciation incentive to loss companies that have accumulated alternative minimum tax and research and development tax credits.
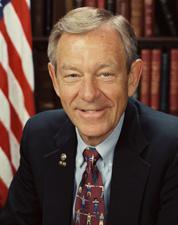 Sen. George V. Voinovich (R-OH)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Amendment SA 4406 as modified agreed to in Senate by Yea-Nay Vote. 76 - 2. Record Vote Number: 91.
April 4, 2008
View full timeline
Roll call votes on amendments in Senate: Amendment SA 4406 as modified agreed to in Senate by Yea-Nay Vote. 76 - 2. Record Vote Number: 91.
April 4, 2008
Senate amendment agreed to: Amendment SA 4406 as modified agreed to in Senate by Yea-Nay Vote. 76 - 2. Record Vote Number: 91.
April 4, 2008
Considered by Senate. (consideration: CR S2591, S2592-2593, S2610; text as modified: CR S2592; text as further modified: CR S2610)
April 4, 2008
Amendment SA 4406 as modified agreed to in Senate by Yea-Nay Vote. 76 - 2. Record Vote Number: 91.
April 4, 2008
Senate amendment submitted
April 3, 2008
Senate amendment proposed (on the floor): Amendment SA 4406 proposed by Senator Voinovich to Amendment SA 4387.(consideration: CR S2403-2407; text: CR S2403-2404)
April 3, 2008
Amendment SA 4406 proposed by Senator Voinovich to Amendment SA 4387. (consideration: CR S2403-2407; text: CR S2403-2404) To protect families most vulnerable to foreclosure due to a sudden loss of income by extending the depreciation incentive to loss companies that have accumulated alternative minimum tax and research and development tax credits.
April 3, 2008
Votes
1 roll call on this amendment
Text
Submitted
SA 4406. Mr. VOINOVICH (for himself, Ms. Stabenow, Mr. Hatch, Mr.
Rockefeller, Mr. Smith, Ms. Cantwell, Mr. Vitter, and Mr. Levin)
submitted an amendment intended to be proposed by him to the bill H.R.
3221, moving the United States toward greater energy independence and
security, developing innovative new technologies, reducing carbon
emissions, creating green jobs, protecting consumers, increasing clean
renewable energy production, and modernizing our energy infrastructure,
and to amend the Internal Revenue Code of 1986 to provide tax
incentives for the production of renewable energy and energy
conservation; which was ordered to lie on the table; as follows:

At the end of title VI, insert the following:

SEC. ___. ELECTION TO ACCELERATE AMT AND R AND D CREDITS IN
LIEU OF BONUS DEPRECIATION.

(a) In General.--Section 168(k), as amended by this Act, is
amended by adding at the end the following new paragraph:
``(5) Election to accelerate amt and r and d credits in
lieu of bonus depreciation.--
``(A) In general.--If a corporation which is an eligible
taxpayer (within the meaning of paragraph (4)) for purposes
of this subsection elects to have this paragraph apply--
``(i) no additional depreciation shall be allowed under
paragraph (1) for any qualified property placed in service
during any taxable year to which paragraph (1) would
otherwise apply, and
``(ii) the limitations described in subparagraph (B) for
such taxable year shall be increased by an aggregate amount
not in excess of the bonus depreciation amount for such
taxable year.
``(B) Limitations to be increased.--The limitations
described in this subparagraph are--

[[Page S2514]]

``(i) the limitation under section 38(c), and
``(ii) the limitation under section 53(c).
``(C) Bonus depreciation amount.--For purposes of this
paragraph--
``(i) In general.--The bonus depreciation amount for any
applicable taxable year is an amount equal to the product of
20 percent and the excess (if any) of--

``(I) the aggregate amount of depreciation which would be
determined under this section for the taxable year if no
election under this paragraph were made and if this
subsection applied only to eligible qualified property, over
``(II) the aggregate amount of depreciation allowable under
this section for the taxable year.

``(ii) Eligible qualified property.--For purposes of clause
(i), the term `eligible qualified property' means qualified
property under paragraph (2), except that in applying
paragraph (2) for purposes of this clause--

``(I) `March 31, 2008' shall be substituted for `December
31, 2007' each place it appears in subparagraph (A) and
clauses (i) and (ii) of subparagraph (E) thereof,
``(II) only adjusted basis attributable to manufacture,
construction, or production after March 31, 2008, and before
January 1, 2009, shall be taken into account under
subparagraph (B)(ii) thereof, and
``(III) in the case of property which is a passenger
aircraft, the written binding contract limitation under
subparagraph (A)(iii)(I) thereof shall not apply.

``(iii) Maximum amount.--The bonus depreciation amount for
any applicable taxable year shall not exceed the applicable
limitation under clause (iv), reduced (but not below zero) by
the bonus depreciation amount for any preceding taxable year.
``(iv) Applicable limitation.--For purposes of clause
(iii), the term `applicable limitation' means, with respect
to any eligible taxpayer, the lesser of--

``(I) $50,000,000, or
``(II) 50 percent of the sum of the amounts determined with
respect to the eligible taxpayer under clauses (ii) and (iii)
of subparagraph (D).

``(v) Aggregation rule.--All corporations which are treated
as a single employer under section 52(a) shall be treated as
1 taxpayer for purposes of applying the limitation under this
subparagraph and determining the applicable limitation under
clause (iv).
``(D) Allocation of bonus depreciation amounts.--
``(i) In general.--Subject to clauses (ii) and (iii), the
taxpayer shall, at such time and in such manner as the
Secretary may prescribe, specify the portion (if any) of the
bonus depreciation amount which is to be allocated to each of
the limitations described in subparagraph (B).
``(ii) Business credit limitation.--The portion of the
bonus depreciation amount allocated to the limitation
described in subparagraph (B)(i) shall not exceed an amount
equal to the portion of the credit allowable under section 38
for the taxable year which is allocable to business credit
carryforwards to such taxable year which are--

``(I) from taxable years beginning before January 1, 2006,
and
``(II) properly allocable (determined under the rules of
section 38(d)) to the research credit determined under
section 41(a).

``(iii) Alternative minimum tax credit limitation.--The
portion of the bonus depreciation amount allocated to the
limitation described in subparagraph (B)(ii) shall not exceed
an amount equal to the portion of the minimum tax credit
allowable under section 53 for the taxable year which is
allocable to the adjusted minimum tax imposed for taxable
years beginning before January 1, 2006.
``(E) Credit refundable.--Any aggregate increases in the
credits allowed under section 38 or 53 by reason of this
paragraph shall, for purposes of this title, be treated as a
credit allowed to the taxpayer under subpart C of part IV of
subchapter A.
``(F) Other rules.--
``(i) Election.--Any election under this paragraph
(including any allocation under subparagraph (D)) may be
revoked only with the consent of the Secretary.
``(ii) Deduction allowed in computing minimum tax.--
Notwithstanding this paragraph, paragraph (2)(G) shall apply
with respect to the deduction computed under this section
(after application of this paragraph) with respect to
property placed in service during any applicable taxable
year.''.
(b) Effective Date.--The amendments made by this section
shall apply to property placed in service after December 31,
2007, in taxable years ending after such date.
______