In the nature of a substitute.
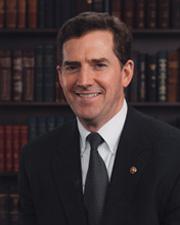 Sen. Jim DeMint (R-SC)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 168 proposed by Senator Grassley for Senator DeMint to Amendment SA 98.(consideration: CR S1485-1488, S1492-1493, S1507-1512, S1523-1524; text: CR S1485-1486)
February 4, 2009
View full timeline
Senate amendment proposed (on the floor): Amendment SA 168 proposed by Senator Grassley for Senator DeMint to Amendment SA 98.(consideration: CR S1485-1488, S1492-1493, S1507-1512, S1523-1524; text: CR S1485-1486)
February 4, 2009
Roll call votes on amendments in Senate: Motion to waive the Budget Act with respect to amendment SA 168 (Sect. 201, S. Con. Res. 21, 110th Congress) rejected in Senate by Yea-Nay Vote. 36 - 61. Record Vote Number: 38.
February 4, 2009
Amendment SA 168 proposed by Senator Grassley for Senator DeMint to Amendment SA 98. (consideration: CR S1485-1488, S1492-1493, S1507-1512, S1523-1524; text: CR S1485-1486) In the nature of a substitute.
February 4, 2009
Point of order raised in Senate with respect to amendment SA 168.
February 4, 2009
Motion to waive the Budget Act with respect to amendment SA 168 (Sect. 201, S. Con. Res. 21, 110th Congress) rejected in Senate by Yea-Nay Vote. 36 - 61. Record Vote Number: 38.
February 4, 2009
Amendment SA 168 ruled out of order by the chair.
February 4, 2009
Senate amendment submitted
February 3, 2009
Votes
1 roll call on this amendment
Text
Submitted
SA 168. Mr. DeMint submitted an amendment intended to be proposed by
him to the bill H.R. 1, making supplemental appropriations for job
preservation and creation, infrastructure investment, energy efficiency
and science, assistance to the unemployed, and State and local fiscal
stabilization, for fiscal year ending September 30, 2009, and for other
purposes; which was ordered to lie on the table; as follows:

Strike all after the enacting clause and insert the
following:

SECTION 1. REDUCTION IN CORPORATE MARGINAL INCOME TAX RATES.

(a) General Rule.--Paragraph (1) of section 11(b) of the
Internal Revenue Code of 1986 is amended--
(1) by inserting ``and'' at the end of subparagraph (A),
(2) by striking ``but does not exceed $75,000,'' in
subparagraph (B) and inserting a period,
(3) by striking subparagraphs (C) and (D), and
(4) by striking the last 2 sentences.
(b) Personal Service Corporations.--Paragraph (2) of
section 11(b) of such Code is amended by striking ``35
percent'' and inserting ``25 percent''.
(c) Conforming Amendments.--Paragraphs (1) and (2) of
section 1445(e) of such Code are each amended by striking
``35 percent'' and inserting ``25 percent''.
(d) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2008.

SEC. 2. REDUCTION IN INDIVIDUAL MARGINAL INCOME TAX RATES.

(a) In General.--Paragraph (2) of section 1(i) of the
Internal Revenue Code of 1986 is amended to read as follows:
``(2) Reduction in rates after 2008.--In the case of
taxable years beginning after 2008, the tables under
subsections (a), (b), (c), (d), and (e) shall be applied--
``(A) by substituting `25%' for `28%' each place it
appears, and
``(B) without regard to--
``(i) the rates on taxable income in excess of the amount
with respect to which the 25 percent rate (determined after
the application of subparagraph (A)) applies, and
``(ii) any limitation on the amount of taxable income to
which the 25 percent rate (determined after the application
of subparagraph (A)) applies.''.
(b) Repeal of EGTRRA Sunset.--Title IX of the Economic
Growth and Tax Relief Reconciliation Act of 2001 (relating to
sunset of provisions of such Act) shall not apply to section
101 of such Act (relating to reduction in income tax rates
for individuals).
(c) Effective Date.--The amendment made by this section
shall apply to taxable years beginning after December 31,
2008.

SEC. 3. REPEAL OF ALTERNATIVE MINIMUM TAX.

(a) In General.--Section 55(a) of the Internal Revenue Code
of 1986 (relating to alternative minimum tax imposed) is
amended by adding at the end the following new flush
sentence:
``No tax shall be imposed by this section for any taxable
year beginning after December 31, 2008, and the tentative
minimum tax for any such taxable year of any taxpayer which
is a corporation shall be zero for purposes of this title.''.
(b) Effective Date.--The amendment made by this section
shall apply to taxable years beginning after December 31,
2008.

SEC. 4. PERMANENT REDUCTIONS IN INDIVIDUAL CAPITAL GAINS AND
DIVIDENDS TAX RATES.

Section 303 of the Jobs and Growth Tax Relief
Reconciliation Act of 2003 (relating to sunset of title) is
repealed.

SEC. 5. ESTATE TAX RELIEF AND REFORM AFTER 2009.

(a) Restoration of Unified Credit Against Gift Tax.--
Paragraph (1) of section 2505(a) of the Internal Revenue Code
of 1986 (relating to general rule for unified credit against
gift tax), after the application of subsection (f), is
amended by striking ``(determined as if the applicable
exclusion amount were $1,000,000)''.
(b) Exclusion Equivalent of Unified Credit Equal to
$5,000,000.--Subsection (c) of section 2010 of the Internal
Revenue Code of 1986 (relating to unified credit against
estate tax) is amended to read as follows:
``(c) Applicable Credit Amount.--
``(1) In general.--For purposes of this section, the
applicable credit amount is the amount of the tentative tax
which would be determined under section 2001(c) if the amount
with respect to which such tentative tax is to be computed
were equal to the applicable exclusion amount.
``(2) Applicable exclusion amount.--
``(A) In general.--For purposes of this subsection, the
applicable exclusion amount is $5,000,000.
``(B) Inflation adjustment.--In the case of any decedent
dying in a calendar year after 2009, the $5,000,000 amount in
subparagraph (A) shall be increased by an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment determined under
section 1(f)(3) for such calendar year by substituting
`calendar year 2008' for `calendar year 1992' in subparagraph
(B) thereof.
If any amount as adjusted under the preceding sentence is not
a multiple of $10,000, such amount shall be rounded to the
nearest multiple of $10,000.''.
(c) Flat Estate and Gift Tax Rates.--
(1) In general.--Subsection (c) of section 2001 of the
Internal Revenue Code of 1986 (relating to imposition and
rate of tax) is amended to read as follows:
``(c) Tentative Tax.--The tentative tax is 15 percent of
the amount with respect to which the tentative tax is to be
computed.''.
(2) Conforming amendments.--
(A) Paragraphs (1) and (2) of section 2102(b) of such Code
are amended to read as follows:
``(1) In general.--A credit in an amount that would be
determined under section 2010 as the applicable credit amount
if the applicable exclusion amount were $60,000 shall be
allowed against the tax imposed by section 2101.
``(2) Residents of possessions of the united states.--In
the case of a decedent who is considered to be a `nonresident
not a citizen of the United States' under section 2209, the
credit allowed under this subsection shall not be less than
the proportion of the amount that would be determined under
section 2010 as the applicable credit amount if the
applicable exclusion amount were $175,000 which the value of
that part of the decedent's gross estate which at the time of
the decedent's death is situated in the United States bears
to the value of the decedent's entire gross estate, wherever
situated.''.
(B) Section 2502(a) of such Code (relating to computation
of tax), after the application of subsection (f), is amended
by adding at the end the following flush sentence:
``In computing the tentative tax under section 2001(c) for
purposes of this subsection, `the last day of the calendar
year in which the gift was made' shall be substituted for
`the date of the decedent's death' each place it appears in
such section.''.
(d) Modifications of Estate and Gift Taxes to Reflect
Differences in Unified Credit Resulting From Different Tax
Rates.--
(1) Estate tax.--
(A) In general.--Section 2001(b)(2) of the Internal Revenue
Code of 1986 (relating to computation of tax) is amended by
striking ``if the provisions of subsection (c) (as in effect
at the decedent's death)'' and inserting ``if the
modifications described in subsection (g)''.
(B) Modifications.--Section 2001 of such Code is amended by
adding at the end the following new subsection:
``(g) Modifications to Gift Tax Payable to Reflect
Different Tax Rates.--For purposes of applying subsection
(b)(2) with respect to 1 or more gifts, the rates of tax
under subsection (c) in effect at the decedent's death shall,
in lieu of the rates of tax in effect at the time of such
gifts, be used both to compute--
``(1) the tax imposed by chapter 12 with respect to such
gifts, and
``(2) the credit allowed against such tax under section
2505, including in computing--
``(A) the applicable credit amount under section
2505(a)(1), and
``(B) the sum of the amounts allowed as a credit for all
preceding periods under section 2505(a)(2).
For purposes of paragraph (2)(A), the applicable credit
amount for any calendar year before 1998 is the amount which
would be determined under section 2010(c) if the applicable
exclusion amount were the dollar amount under section
6018(a)(1) for such year.''.
(2) Gift tax.--Section 2505(a) of such Code (relating to
unified credit against gift tax) is amended by adding at the
end the following new flush sentence:
``For purposes of applying paragraph (2) for any calendar
year, the rates of tax in effect under section 2502(a)(2) for
such calendar year shall, in lieu of the rates of tax in
effect for preceding calendar periods, be used in determining
the amounts allowable as a credit under this section for all
preceding calendar periods.''.
(e) Effective Date.--The amendments made by this section
shall apply to estates of decedents dying, generation-
skipping transfers, and gifts made, after December 31, 2009.
(f) Additional Modifications to Estate Tax.--
(1) In general.--The following provisions of the Economic
Growth and Tax Relief Reconciliation Act of 2001, and the
amendments made by such provisions, are hereby repealed:
(A) Subtitles A and E of title V.
(B) Subsection (d), and so much of subsection (f)(3) as
relates to subsection (d), of section 511.
(C) Paragraph (2) of subsection (b), and paragraph (2) of
subsection (e), of section 521.
The Internal Revenue Code of 1986 shall be applied as if such
provisions and amendments had never been enacted.
(2) Sunset not to apply to title v of egtrra.--Section 901
of the Economic Growth and Tax Relief Reconciliation Act of
2001 shall not apply to title V of such Act.
(3) Repeal of deadwood.--

[[Page S1461]]

(A) Sections 2011, 2057, and 2604 of the Internal Revenue
Code of 1986 are hereby repealed.
(B) The table of sections for part II of subchapter A of
chapter 11 of such Code is amended by striking the item
relating to section 2011.
(C) The table of sections for part IV of subchapter A of
chapter 11 of such Code is amended by striking the item
relating to section 2057.
(D) The table of sections for subchapter A of chapter 13 of
such Code is amended by striking the item relating to section
2604.

SEC. 6. INCREASE IN CHILD TAX CREDIT MADE PERMANENT.

Title IX of the Economic Growth and Tax Relief
Reconciliation Act of 2001 (relating to sunset of provisions
of such Act) shall not apply to sections 201 (relating to
modifications to child tax credit) and 203 (relating to
refunds disregarded in the administration of federal programs
and federally assisted programs) of such Act.

SEC. 7. BASE BROADENING.

(a) In General.--Section 63 of the Internal Revenue Code of
1986 is amended by adding at the end the following new
subsection:
``(h) Restriction of Itemized Deductions After 2008.--In
the case of any taxable year beginning after 2008, no
itemized deductions shall be allowed under this chapter other
than--
``(1) the deduction for qualified residence interest (as
defined in section 163(h)(3)), and
``(2) the deduction allowed under section 170.''.
(b) Effective Date.--The amendment made by this section
shall apply to taxable years beginning after December 31,
2008.
______