To limit the provision of vouchers to individuals with adjusted gross incomes of less than $50,000 or joint filers with adjusted gross incomes of less than $75,000.
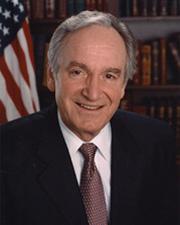 Sen. Tom Harkin (D-IA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Motion to table amendment SA 2300 agreed to in Senate by Yea-Nay Vote. 65 - 32. Record Vote Number: 263.
August 6, 2009
View full timeline
Roll call votes on amendments in Senate: Motion to table amendment SA 2300 agreed to in Senate by Yea-Nay Vote. 65 - 32. Record Vote Number: 263.
August 6, 2009
Senate amendment proposed (on the floor): Amendment SA 2300 proposed by Senator Harkin.(consideration: CR S8946-8948, S8960-8961; text: CR S8946)
August 6, 2009
Amendment SA 2300 proposed by Senator Harkin. (consideration: CR S8946-8948, S8960-8961; text: CR S8946) To limit the provision of vouchers to individuals with adjusted gross incomes of less than $50,000 or joint filers with adjusted gross incomes of less than $75,000.
August 6, 2009
Motion to table amendment SA 2300 agreed to in Senate by Yea-Nay Vote. 65 - 32. Record Vote Number: 263.
August 6, 2009
Senate amendment submitted
August 5, 2009
Votes
1 roll call on this amendment
Text
Submitted
SA 2300. Mr. HARKIN submitted an amendment intended to be proposed by
him to the bill H.R. 3435, making supplemental appropriations for
fiscal

[[Page S8874]]

year 2009 for the Consumer Assistance to Recycle and Save Program;
which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. ___. ELIGIBLE INDIVIDUALS.

(a) In General.--Section 1302(c)(1) of the Supplemental
Appropriations Act, 2009 (Public Law 111-32; 123 Stat. 1910;
49 U.S.C. 32901 note) is amended by adding at the end the
following:
``(H) Eligible individuals.--A voucher may only be issued
under the Program in connection with the purchase of a new
fuel efficient automobile by an individual--
``(i) who filed a return of Federal income tax for a
taxable year beginning in 2008, and, if married for the
taxable year concerned (as determined under section 7703 of
the Internal Revenue Code of 1986), filed a joint return;
``(ii) who is not an individual with respect to whom a
deduction under section 151 of the Internal Revenue Code of
1986 is allowable to another taxpayer for a taxable year
beginning in the calendar year in which the individual's
taxable year begins; and
``(iii) whose adjusted gross income reported in the most
recent return described in clause (i) was not more than
$50,000 ($75,000 in the case of a joint tax return or a
return filed by a head of household (as defined in section
2(b) of the Internal Revenue Code of 1986)).''.
(b) Regulations.--Not later than 7 days after the date of
the enactment of this Act and notwithstanding the
requirements of section 553 of title 5, United States Code,
the Secretary of Transportation shall promulgate final
regulations that require--
(1) each purchaser or leaser of a new fuel efficient
automobile under the Consumer Assistance to Recycle and Save
Program established under section 1302(a) of such Act (Public
Law 111-32; 123 Stat. 1909; 49 U.S.C. 32901 note) to affirm
on a standard form, determined by the Secretary, that such
purchaser or leaser is an individual described by section
1302(c)(1)(H) of such Act, as added by subsection (a); and
(2) each dealer that receives a form described in paragraph
(1) under such program to submit such form to the Secretary.
(c) Fraud Detection.--Upon receipt under paragraph (2) of
subsection (b) of a form described in paragraph (1) of such
subsection, the Secretary shall submit such form to the
Internal Revenue Service to determine whether the purchaser
or leaser has violated section 641 of title 18, United States
Code.
______