To establish a Division of Consumer Financial Protection within the Federal Deposit Insurance Corporation, and for other purposes.
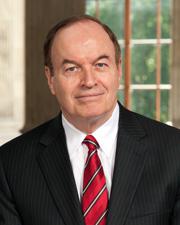 Sen. Richard C. Shelby (R-AL)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Amendment SA 3826 not agreed to in Senate by Yea-Nay Vote. 38 - 61. Record Vote Number: 133.
May 6, 2010
View full timeline
Roll call votes on amendments in Senate: Amendment SA 3826 not agreed to in Senate by Yea-Nay Vote. 38 - 61. Record Vote Number: 133.
May 6, 2010
Senate amendment not agreed to: Amendment SA 3826 not agreed to in Senate by Yea-Nay Vote. 38 - 61. Record Vote Number: 133.
May 6, 2010
Considered by Senate. (consideration: CR S3296, S3305-3311, S3327-3328)
May 6, 2010
Amendment SA 3826 not agreed to in Senate by Yea-Nay Vote. 38 - 61. Record Vote Number: 133.
May 6, 2010
Senate amendment submitted
May 5, 2010
Senate amendment proposed (on the floor): Amendment SA 3826 proposed by Senator Shelby to Amendment SA 3739.(consideration: CR S3148-3149)
May 5, 2010
Amendment SA 3826 proposed by Senator Shelby to Amendment SA 3739. (consideration: CR S3148-3149) To establish a Division of Consumer Financial Protection within the Federal Deposit Insurance Corporation, and for other purposes.
May 5, 2010
Votes
1 roll call on this amendment
Text
Submitted
SA 3826. Mr. SHELBY (for himself, Mr. McConnell, Mr. Bennett, Mr.
Crapo, Mr. Corker, Mr. Johanns, Mrs. Hutchison, Mr. Vitter, Mr.
Bunning, Mr. Chambliss, Mr. Cornyn, Mr. Bond, Mr. Enzi, and Mr.
Alexander) submitted an amendment intended to be proposed to amendment
SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs.
Lincoln)) to the bill S. 3217, to promote the financial stability of
the United States by improving accountability and transparency in the
financial system, to end ``too big to fail'', to protect the American
taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

Strike title X and insert the following:

TITLE X--DIVISION FOR CONSUMER FINANCIAL PROTECTION

SEC. 1001. SHORT TITLE.

This title may be cited as the ``Consumer Financial
Protection Act of 2010''.

SEC. 1002. DEFINITIONS.

Except as otherwise provided in this title, for purposes of
this title, the following definitions shall apply:
(1) Covered person.--The term covered person means--
(A) a depository institution; or
(B) a person other than a depository institution that is
subject to one or more of the enumerated consumer protection
statutes.
(2) Designated transfer date.--The term ``designated
transfer date'' means the date established under section
1042.
(3) Division.--The term ``Division'' means the Division for
Consumer Financial Protection.
(4) Enumerated consumer protection statutes.--The term
``enumerated consumer protection statute'' means--
(A) subsections (c) through (f) of section 43 of the
Federal Deposit Insurance Act (12 U.S.C. 1831t);
(B) the Consumer Leasing Act of 1976 (15 U.S.C. 1667 et
seq.);
(C) the Electronic Fund Transfer Act (15 U.S.C. 1693 et
seq.);
(D) the Equal Credit Opportunity Act (15 U.S.C. 1691 et
seq.);
(E) the Fair Credit Billing Act (15 U.S.C. 1666 et seq.);
(F) the Fair Credit Reporting Act (15 U.S.C. 1681 et seq.),
other than sections 615(e) and 628 of that Act (15 U.S.C.
1681m(e), 1681w);
(G) the Homeowners Protection Act of 1998 (12 U.S.C. 4901,
et seq.);
(H) the Fair Debt Collection Practices Act (15 U.S.C. 1692
et seq.);
(I) sections 502 through 509 of the Gramm-Leach-Bliley Act
(15 U.S.C. 6802-6809);
(J) the Home Mortgage Disclosure Act of 1975 (12 U.S.C.
2801 et seq.);
(K) the Home Ownership and Equity Protection Act of 1994
(15 U.S.C. 1601 note);
(L) the Real Estate Settlement Procedures Act of 1974 (12
U.S.C. 2601 et seq.);
(M) the S.A.F.E. Mortgage Licensing Act of 2008 (12 U.S.C.
5101 et seq.);
(N) the Truth in Lending Act (15 U.S.C. 1601 et seq.);
(O) the Truth in Savings Act (12 U.S.C. 4301 et seq.); and
(P) the authority of the Federal Trade Commission, the
Board of Governors, the Office of Thrift Supervision, and the
National Credit Union Administration to prohibit unfair or
deceptive acts or practices under section 18(f) of the
Federal Trade Commission Act (15 U.S.C. 57a(f))--
(i) only to the same extent that the Board of Governors,
the Office of Thrift Supervision, the National Credit Union
Administration, and the Federal Trade Commission could
exercise such authority over covered persons on the day
before the designated transfer date; and
(ii) except that such authority shall not extend to persons
or activities covered under the Fair Credit Reporting Act
that do not meet the definition in section 603(p) of the Fair
Credit Reporting Act (15 U.S.C. 1681a(p)).
(5) Mortgage loan originator.--The term ``mortgage loan
originator'' means any person (other than an individual) that
takes applications for residential mortgage transactions and
offers or negotiates terms of residential mortgage
transactions.
(6) Nondepository covered person.--The term ``nondepository
covered person'' means any entity that--
(A) is not a depository institution;
(B) is not an affiliate or subsidiary of a depository
institution;
(C) is not subject to supervision or enforcement by a
Federal banking regulator; and
(D) is a financial services provider subject to the
enumerated consumer protection statutes.
(7) Person.--The term ``person'' has the same meaning as in
section 103 of the Truth in Lending Act (15 U.S.C. 1602).
(8) Prudential regulator.--The term ``prudential
regulator'' means the Office of the Comptroller of the
Currency, the Federal Deposit Insurance Corporation, or the
National Credit Union Administration, as appropriate, with
respect to depository institutions and affiliates of
depository institutions supervised by such agencies.
(9) Residential mortgage transaction.--The term
``residential mortgage transaction'' has the same meaning as
in section 103 of the Truth in Lending Act (15 U.S.C. 1602).

Subtitle A--Division of Consumer Protection

SEC. 1011. ESTABLISHMENT OF THE DIVISION.

(a) Division Established.--There is established within the
Federal Deposit Insurance Corporation the Division for
Consumer Protection, which shall regulate, by rule or order,
consumer financial products and services under the enumerated
consumer protection statutes, and where applicable, as
provided for in section 1024, enforce the enumerated consumer
protection statutes.
(b) Director and Deputy Director.--
(1) Director.--The Division shall be headed by a Director,
who shall be appointed by the President, by and with the
advice and consent of the Senate, to serve for a term of 4
years.
(2) Deputy director.--The Director shall designate a Deputy
Director.
(3) Acting director.--In the event of a vacancy in the
position of the Director or during the absence or disability
of the Director, the Deputy Director shall act as Director.
(4) Compensation.--The Director shall be compensated at a
rate prescribed for level II of the Executive Schedule under
section 5313 of title 5, United States Code.

SEC. 1012. ADMINISTRATION.

(a) Specific Functional Units.--
(1) Research.--The Director shall establish a unit, the
functions of which shall include researching, analyzing, and
reporting on--
(A) developments in markets for consumer financial products
or services, including market areas of alternative consumer
financial products or services with high growth rates and
areas of risk to consumers;
(B) consumer awareness, understanding, and use of
disclosures and communications regarding consumer financial
products or services; and
(C) consumer awareness and understanding of costs, risks,
and benefits of consumer financial products or services.
(2) Collecting and tracking complaints.--
(A) In general.--The Director shall establish a unit, the
functions of which shall include establishing a single, toll-
free telephone number, a website, and database to facilitate
the centralized collection, monitoring, and response to
consumer complaints regarding consumer financial products or
services. The Director shall coordinate with other Federal
agencies to route complaints to other Federal regulators,
where appropriate.
(B) Routing calls to states.--To the extent practicable,
State agencies may receive appropriate complaints from the
systems established under subparagraph (A), if--
(i) the State agency system has the functional capacity to
receive calls or electronic reports routed by the Division
systems; and
(ii) the State agency has satisfied any conditions of
participation in the system that the Division may establish,
including treatment of personally identifiable information
and sharing of information on complaint resolution or related
compliance procedures and resources.
(C) Reports to congress.--The Director shall present an
annual report to Congress, not later than March 31 of each
year on the complaints received by the Division in the prior
year regarding consumer financial products and services. Such
report shall include information and analysis about complaint
numbers, types, and, where applicable, information about
resolution of complaints.
(D) Data sharing required.--To facilitate preparation of
the reports required under subparagraph (C), supervision and
enforcement activities, and monitoring of the market for
consumer financial products and services, the Division shall
share consumer complaint information with prudential
regulators, other Federal agencies, and State agencies,
consistent with Federal law applicable to personally
identifiable information. The prudential regulators and other
Federal agencies shall share data relating to consumer
complaints regarding consumer financial products and services
with the Division, consistent with Federal law applicable to
personally identifiable information.
(b) Office of Financial Literacy.--
(1) Establishment.--The Division shall establish an Office
of Financial Literacy, which shall be responsible for
developing and implementing initiatives intended to educate
and empower consumers to make better informed financial
decisions. The Director shall serve as the Vice Chairperson
on the

[[Page S3218]]

Financial Literacy and Education Commission established under
section 513 of the Financial Literacy and Education
Improvement Act (20 U.S.C. 9702).
(2) Other duties.--The Office of Financial Literacy shall
develop and implement a strategy to improve financial
literacy, consistent with the National Strategy for Financial
Education.
(3) Coordination.--The Office of Financial Literacy shall
coordinate with other units within the Division in carrying
out its functions, including working with the research unit
established by the Director to conduct research related to
consumer financial education and counseling.
(4) Report.--Not later than 24 months after the designated
transfer date, and annually thereafter, the Director shall
submit a report on its financial literacy activities and
strategy to improve financial literacy of consumers to--
(A) the Committee on Banking, Housing, and Urban Affairs of
the Senate; and
(B) the Committee on Financial Services of the House of
Representatives.

SEC. 1013. CONSUMER ADVISORY BOARD.

(a) Establishment Required.--The Director shall establish a
Consumer Advisory Board to advise and consult with the
Division in the exercise of its functions under this title,
the enumerated consumer protection statutes, and to provide
information on emerging practices in the consumer financial
products or services industry, including regional trends,
concerns, and other relevant information.
(b) Membership.--In appointing the members of the Consumer
Advisory Board, the Director shall seek to assemble experts
in consumer protection, financial services, and consumer
financial products or services and seek representation of the
interests of nondepository covered persons and consumers,
without regard to party affiliation. Not fewer than 6 members
shall be appointed upon the recommendation of the regional
Federal Reserve Bank Presidents, on a rotating basis.
(c) Meetings.--The Consumer Advisory Board shall meet from
time to time at the call of the Director, but not less
frequently than twice in each year.
(d) Compensation and Travel Expenses.--Members of the
Consumer Advisory Board who are not full-time employees of
the United States shall be allowed travel expenses, including
transportation and subsistence, while away from their homes
or regular places of business.

SEC. 1014. COORDINATION.

The Director shall coordinate with other Federal agencies
and State regulators, as appropriate, to promote consistent
regulatory treatment of consumer financial and investment
products and services.

SEC. 1015. FUNDING.

(a) Fees and Assessments.--
(1) In general.--The Chairperson shall establish, by rule,
an assessment schedule, including the assessment base and
rates, applicable to covered persons subject to section 1023
to recover the costs of the Corporation in carrying out its
responsibilities described under this title. The Chairperson
may, by rule or other action, impose additional assessments
on insured depository institutions to regulate consumer
financial products and services under the enumerated consumer
protection statutes specified in this title.
(2) Limitation.--The assessments imposed by the Chairperson
by rules established pursuant to paragraph (1) shall not
exceed the costs reasonably necessary to cover the expenses
associated with carrying outs its supervisory and rulemaking
responsibilities under this title.
(b) Fund Established.--
(1) In general.--There is established in the Treasury of
the United States, a separate account, to be known as the
Consumer Financial Protection Fund (referred to in this title
as the ``CFP Fund''). Fees and assessments collected under
subsection (a) shall be deposited into the CFP Fund.
(2) Rule of construction.--Any amounts deposited into the
CFP Fund may not be construed to be Government funds or
appropriated monies.
(3) No apportionment.--Any amounts deposited into the CFP
Fund shall not be subject to apportionment for the purpose of
chapter 15 of title 31, United States Code, or under any
other authority.
(4) Use of funds.--Funds in the CFP Fund shall be
immediately available to the Corporation and under the
control of the Corporation, and shall remain available until
expended, to pay the expenses of the Corporation in carrying
out its duties and responsibilities pursuant to this title.
(c) Conforming Amendments.--Section 11(a)(4)(A) of the
Federal Deposit Insurance Act (12 U.S.C. 1821(a)(4)(A)) is
amended--
(1) in clause (ii), by striking ``and'' at the end;
(2) by redesignating clause (iii) as clause (iv); and
(3) by inserting after clause (ii) the following:
``(iii) to carry out additional duties pursuant to the
Consumer Financial Protection Act of 2010; and''.
(d) Funding.--The Chairperson shall dedicate not less than
10 percent of the annual estimated budget of the Corporation,
excluding any funding provided pursuant to section 11(c) of
the Federal Deposit Insurance Act (12 U.S.C. 1821(c)), to
carry out the requirements specified in this title.

SEC. 1016. APPEARANCES BEFORE AND REPORTS TO CONGRESS.

(a) Appearances Before Congress.--The Director shall appear
before the Committee on Banking, Housing, and Urban Affairs
of the Senate and the Committee on Financial Services of the
House of Representatives at semi-annual hearings regarding
the reports required under subsection (b).
(b) Reports Required.--The Director shall, concurrent with
each semi-annual hearing referred to in subsection (a),
prepare and submit to the President and to the Committee on
Banking, Housing, and Urban Affairs of the Senate and the
Committee on Financial Services of the House of
Representatives, a report, beginning with the session
following the designated transfer date.
(c) Contents.--The reports required by subsection (b) shall
include--
(1) a discussion of the significant problems faced by
consumers in shopping for or obtaining consumer financial
products or services;
(2) a justification of the budget request of the previous
year;
(3) a list of the significant rules and orders adopted by
the Corporation, as well as other significant initiatives
conducted by the Division, during the preceding year and the
plan of the Division for rules, orders, or other initiatives
to be undertaken during the upcoming period;
(4) an analysis of complaints about consumer financial
products or services that the Division, in consultation with
the Federal Trade Commission has received and collected in
its central database on complaints during the preceding year;
(5) a list, with a brief statement of the issues, of the
public supervisory and enforcement actions to which the
Division was a party during the preceding year; and
(6) the actions taken regarding rules, orders, and
supervisory actions with respect to nondepository covered
persons which are not credit unions or depository
institutions.

SEC. 1017. EFFECTIVE DATE.

This subtitle shall become effective on the date of
enactment of this Act.

Subtitle B--General Powers of the Division

SEC. 1021. PURPOSE, OBJECTIVES, AND FUNCTIONS.

(a) Purpose.--The Division shall seek to implement and,
where applicable, enforce the enumerated consumer protection
statutes consistently for the purpose of ensuring that
markets for consumer financial products and services are
fair, transparent, and competitive.
(b) Objectives.--The Division is authorized to exercise its
authorities under the enumerated consumer protection statutes
for the purposes of ensuring that, with respect to consumer
financial products and services--
(1) consumers are provided with timely and understandable
information to make responsible decisions about financial
transactions;
(2) consumers are protected from unfair or deceptive acts
and practices;
(3) outdated, unnecessary, or unduly burdensome regulations
are regularly identified and addressed in order to reduce
unwarranted regulatory burdens; and
(4) enumerated consumer protection statutes are enforced
consistently, without regard to the status of a person as a
depository institution, in order to ensure uniform consumer
protection in the marketplace.
(c) Functions.--The primary functions of the Division are--
(1) issuing rules, orders and guidance implementing the
enumerated consumer protection statutes;
(2) collecting, investigating, and responding to consumer
complaints;
(3) collecting, researching, and publishing information
relevant to the functioning of markets for consumer financial
products and services to identify risks to consumers, and the
proper functioning of such markets;
(4) subject to section 1023, supervising nondepository
covered persons for compliance with the enumerated consumer
protection statutes, and taking appropriate enforcement
action to address violations of the enumerated consumer
protection statutes;
(5) conducting financial education programs; and
(6) performing such support activities as may be necessary
or useful to facilitate the other functions of the Division.

SEC. 1022. RULEMAKING AUTHORITY.

(a) In General.--The Division is authorized to exercise its
authorities under the enumerated consumer protection statutes
to implement the provisions of the enumerated consumer
protection statutes.
(b) Rulemaking, Orders, and Guidance.--
(1) In general.--The Division may prescribe rules and issue
orders and guidance, as may be necessary or appropriate to
enable the Division to administer and carry out the
enumerated consumer protection statutes, and to prevent
evasions thereof.
(2) Exclusive rulemaking authority.--Notwithstanding any
other provisions of Federal law, to the extent that a
provision of the enumerated consumer protection statutes
authorizes the Division and another Federal agency to issue
regulations under that provision of law for purposes of
assuring compliance with the enumerated consumer protection
statutes, the Division shall have the exclusive authority to
prescribe rules pursuant to those provisions of law, with
respect to compliance with those provisions of law by covered
persons.
(3) Corporation approval required.--No rule or regulation
of the Division may become effective with respect to any
person,

[[Page S3219]]

unless approved by majority vote of the members of the Board
of Directors of the Corporation.
(c) Preservation of State Regulation of Insurance.--Nothing
in this title shall abrogate or limit in any way section 2 of
the Act of March 9, 1945 (15 U.S.C. 1012) or otherwise grant
the Division authority over the business of insurance.
(d) Limitation on Authority of Division.--The Division
shall have no authority to issue rules, regulations, orders,
or guidance that affect any underwriting standards of
depository institutions or affiliates thereof.

SEC. 1023. SUPERVISION OF NONDEPOSITORY COVERED PERSONS.

(a) Applicability.--
(1) Covered persons.--
(A) Applicability.--
(i) In general.--Except as provided in paragraph (2), this
section shall apply to any person that is--

(I) a type or category of mortgage loan originator that the
Division, in consultation with the Federal Trade Commission,
determines by rule is subject to the requirements of this
section; or
(II) a nondepository covered person that demonstrates a
pattern or practice of violations of the enumerated consumer
protection statutes, that the Division, in consultation with
the Federal Trade Commission, determines by order, after
notice and opportunity for response, is subject to the
requirements of this section.

(ii) Rule of construction.--On and after the effective date
of this section, the Division may consider violations which
occurred during the previous 3 years in making a
determination that a nondepository covered person shall be
subject to this section.
(B) Factors for consideration.--In determining whether a
mortgage loan originator is subject to the requirements of
this section, the Division shall consider the risks to
consumers created by the provision of such consumer financial
products or services and the probability that supervision can
serve to diminish such risks. In making these determinations,
the Division shall consider--
(i) the total financial assets of the mortgage loan
originator;
(ii) the volume of transactions involving consumer
financial products or service in which the mortgage loan
originator engages;
(iii) the complexity and nature of the financial products
or services offered by the mortgage loan originator; and
(iv) the number and nature of any violations of the
enumerated consumer protections statutes by the mortgage loan
originator.
(C) Rule of construction.--Nothing in this section may be
construed to prohibit the Division from exempting any class
of mortgage loan originator or any specific mortgage loan
originator from the requirements of this section.
(2) Certain persons excluded.--This section shall not apply
to persons described in section 1024.
(b) Supervision.--
(1) In general.--The Division shall require reports and
conduct examinations on a periodic basis of persons described
in subsection (a) for purposes of--
(A) assessing compliance with the requirements of the
enumerated consumer protection statutes;
(B) obtaining information about the activities and
compliance systems or procedures of such person; and
(C) detecting and assessing risks to consumers and to
markets for consumer financial products and services.
(2) Risk-based supervision program.--The Division shall
exercise its authority under paragraph (1) in a manner
designed to ensure that such exercise, with respect to
persons described in subsection (a), is based on the
assessment by the Division of the risks posed to consumers,
and taking into consideration, as applicable--
(A) the volume of transactions involving consumer financial
products or services in which the persons described in
subsection (a) engage;
(B) the number and nature of any violations of the
enumerated consumer protection statutes on the part of the
persons described in subsection (a); and
(C) the extent to which such institutions are subject to
oversight by State authorities for consumer protection.
(3) Coordination.--To minimize regulatory burden, the
Division shall coordinate its supervisory activities with the
supervisory activities conducted by Federal regulators and
the State regulatory authorities, including establishing
their respective schedules for examining persons described in
subsection (a) and requirements regarding reports to be
submitted by such persons.
(4) Use of existing reports.--The Division shall, to the
fullest extent possible, use--
(A) reports pertaining to persons described in subsection
(a) that have been provided to a Federal or State agency; and
(B) information that has been reported publicly.
(5) Preservation of authority.--The authority of the
Chairperson to require reports from persons described in
subsection (a), as permitted under paragraph (1), regarding
information under the control of such person, including the
authority to require reports when such information is
maintained, stored, or processed by another person.
(6) Reports of tax law noncompliance.--The Division shall
provide the Commissioner of Internal Revenue with any report
of examination or related information identifying possible
tax law noncompliance.
(7) Registration, recordkeeping and other requirements for
certain persons.--
(A) In general.--The Division shall prescribe rules to
facilitate supervision of persons described in subsection (a)
and assessment and detection of risks to consumers.
(B) Registration.--
(i) In general.--The Division shall prescribe rules
regarding registration requirements for persons described in
subsection (a).
(ii) Exception for related persons.--The Division may not
impose requirements under this section regarding the
registration of a related person.
(iii) Registration information.--Subject to rules
prescribed by the Division, the Division shall publicly
disclose the registration information about persons described
in subsection (a) to facilitate the ability of consumers to
identify persons described in subsection (a) registered with
the Division.
(C) Recordkeeping.--The Division may require a person
described in subsection (a), to generate, provide, or retain
records for the purposes of facilitating supervision of such
persons and assessing and detecting risks to consumers.
(D) Requirements concerning obligations.--The Division may
prescribe rules regarding a person described in subsection
(a), to ensure that such persons are legitimate entities and
are able to perform their obligations to consumers.
(E) Consultation with state agencies.--In developing and
implementing requirements under this paragraph, the Division
shall consult with State regulatory authorities regarding
requirements or systems (including coordinated or combined
systems for registration), where appropriate.
(c) Primary Enforcement Authority.--
(1) The division to have primary enforcement authority.--To
the extent that a Federal law authorizes the Division and
another Federal agency, other than the Federal Trade
Commission, to enforce an enumerated consumer protection
statute, the Division shall have exclusive authority to
enforce that enumerated consumer protection statute with
respect to any person described in subsection (a)(1)(A).
(2) Referral.--Any Federal agency authorized to enforce an
enumerated consumer protection statute may recommend in
writing to the Division that the Division initiate an
enforcement proceeding, as the Division is authorized by that
statute or by this title.
(3) Coordination with the federal trade commission.--
(A) In general.--The Division and the Federal Trade
Commission shall coordinate enforcement actions for
violations of Federal law regarding the offering or provision
of consumer financial products or services by any person
described in subsection (a)(1)(A), or service providers
thereto. In carrying out this subparagraph, the agencies
shall negotiate an agreement to establish procedures for such
coordination, including procedures for notice to the other
agency, where feasible, prior to initiating a civil action to
enforce a Federal law regarding the offering or provision of
consumer financial products or services.
(B) Civil actions.--Whenever a civil action has been filed
by, or on behalf of, the Division or the Federal Trade
Commission for any violation of any provision of Federal law
described in subparagraph (A), or any regulation prescribed
under such provision of law--
(i) the other agency may not, during the pendency of that
action, institute a civil action under such provision of law
against any defendant named in the complaint in such pending
action for any violation alleged in the complaint; and
(ii) the Division or the Federal Trade Commission may
intervene as a party in any such action brought by the other
agency, and, upon intervening--

(I) be heard on all matters arising in such enforcement
action; and
(II) file petitions for appeal in such actions.

(C) Agreement terms.--The terms of any agreement negotiated
under subparagraph (A) may modify or supersede the provisions
of subparagraph (B).
(D) Deadline.--The agencies shall reach the agreement
required under subparagraph (A) not later than 6 months after
the designated transfer date.
(4) Savings provision.--Except as specifically stated in
this title regarding the enumerated consumer protection
statutes, nothing in this title shall be construed as
modifying, limiting, or otherwise affecting the authority of
the Federal Trade Commission under the Federal Trade
Commission Act, or any other provision of law.
(d) Exclusive Rulemaking and Examination Authority.--To the
extent that Federal law authorizes the Division and another
Federal agency to issue regulations or guidance, conduct
examinations, or require reports from a person described in
subsection (a) under that provision of law for purposes of
assuring compliance with the enumerated consumer protection
statutes and any regulations thereunder, the Division shall
have the exclusive authority to prescribe rules, issue
guidance, conduct examinations, require reports, or issue
exemptions with regard to a person described in subsection
(a), subject to those provisions of law.
(e) Service Providers.--A service provider to a person
described in subsection (a) shall be subject to the authority
of the Division under this section, to the same extent as if

[[Page S3220]]

such service provider were engaged in a service relationship
with a bank, and the Division were an appropriate Federal
banking agency under section 7(c) of the Bank Service Company
Act (12 U.S.C. 1867(c)). For purposes of this subsection, a
service provider shall not include persons described in
section 1024.
(f) Enforcement Authority.--The Division may enforce the
requirements of this title with respect to persons described
in subsection (a) pursuant to section 8 of the Federal
Deposit Insurance Act (12 U.S.C. 1818), as if such person
were an insured depository institution.

SEC. 1024. SUPERVISION AND ENFORCEMENT ON CONSUMER
PROTECTION.

The Division shall have no authority to require reports
from, conduct examinations of, or take enforcement action
against an insured depository institution or any affiliate
thereof. The authorities of the Division and the Director
under this title do not alter or affect the authority of the
prudential regulators to require reports from, conduct
examinations of, or take enforcement action against an
insured depository institution or any affiliate thereof for
purposes of assessing and enforcing compliance by such person
with the requirements of the enumerated consumer protection
statutes and obtaining information about the activities
subject to such law and the associated compliance systems or
procedures of such institution or affiliate.

SEC. 1025. DISCLOSURES.

(a) In General.--To the extent that the enumerated consumer
protection statutes require disclosures to consumers, the
Division shall prescribe rules to ensure that such
disclosures make timely, appropriate, and effective
disclosures to consumers of the costs, benefits, and risks
associated with the product or service.
(b) Model Disclosures.--
(1) In general.--Any final rule prescribed by the Division
under this section requiring disclosures may include a model
form that may be used.
(2) Format.--A model form issued pursuant to paragraph (1)
shall contain a clear and conspicuous disclosure that, at a
minimum--
(A) uses plain language comprehensible to consumers;
(B) contains a clear format and design, such as an easily
readable type font; and
(C) succinctly explains the information that must be
communicated to the consumer.
(3) Consumer testing.--Any model form issued by the
Division shall be validated through consumer testing.
(c) Basis for Rulemaking.--In prescribing disclosure rules,
the Division shall consider available evidence about consumer
awareness, understanding of, and responses to disclosures or
communications about the risks, costs, and benefits of
consumer financial products or services.
(d) Safe Harbor.--Any person that uses a model form issued
by the Division shall be deemed to be in compliance with the
disclosure requirements of this section with respect to such
model form.
(e) Trial Disclosure Programs.--
(1) In general.--The Division may permit a person to
conduct a trial program that is limited in time and scope,
subject to specified standards and procedures, for the
purpose of providing trial disclosures to consumers that are
designed to improve upon any model form issued by the
Division.
(2) Safe harbor.--The standards and procedures issued by
the Division shall be designed to encourage persons to
conduct trial disclosure programs. For the purposes of
administering this subsection, the Division may establish a
limited period during which a person conducting a trial
disclosure program shall be deemed to be in compliance with,
or may be exempted from, a requirement of a rule or an
enumerated consumer protection statute.
(3) Public disclosure.--The rules of the Division shall
provide for public disclosure of trial disclosure programs,
which public disclosure may be limited, to the extent
necessary to encourage nondepository covered persons to
conduct effective trials.

Subtitle C--Transfer of Functions and Personnel; Transitional
Provisions

SEC. 1041. TRANSFER OF CONSUMER FINANCIAL PROTECTION
FUNCTIONS.

(a) Defined Terms.--For purposes of this subtitle--
(1) the term ``consumer financial protection functions''
means--
(A) the functions and authorities of the Board of Governors
under the enumerated consumer protection statutes, except
those functions retained by the prudential regulators under
section 1024; and
(B) the functions and authorities of the Federal Trade
Commission under the enumerated consumer laws with respect to
persons subject to the jurisdiction of the Division under
section 1023, except that the Federal Trade Commission shall
retain concurrent enforcement jurisdiction under the
enumerated consumer protection statutes over such persons,
consistent with subsection 1023(c); and
(2) the terms ``transferor agency'' and ``transferor
agencies'' mean, respectively the Board of Governors and the
Federal Trade Commission.
(b) In General.--Except as provided in subsection (c),
consumer financial protection functions are transferred as
follows:
(1) Board of governors.--
(A) Transfer of functions.--All consumer financial
protection functions of the Board of Governors are
transferred to the Division.
(B) Board of governors authority.--The Division shall have
all powers and duties that were vested in the Board of
Governors, relating to consumer financial protection
functions, on the day before the designated transfer date.
(2) Federal trade commission.--
(A) Transfer of functions.--All consumer financial
protection functions of the Federal Trade Commission are
transferred to the Division. Nothing in this title shall be
construed to require a mandatory transfer of any employee of
the Federal Trade Commission to the Division.
(B) Commission authority.--The Division shall have all
powers and duties that were vested in the Federal Trade
Commission relating to consumer financial protection
functions on the day before the designated transfer date.
(c) Transfers of Functions Subject to Examination and
Enforcement Authority Remaining With Transferor Agencies.--
The transfers of functions in subsection (b) do not affect
the authority of the prudential regulators from conducting
examinations or initiating and maintaining enforcement
proceedings in accordance with section 1023.
(d) Effective Date.--Subsections (b) and (c) shall become
effective on the designated transfer date.

SEC. 1042. DESIGNATED TRANSFER DATE.

(a) In General.--Not later than 60 days after the date of
enactment of this Act, the Secretary shall--
(1) in consultation with the Chairman of the Board of
Governors, the Chairperson of the Corporation, the Chairman
of the Federal Trade Commission, the Chairman of the National
Credit Union Administration Board, the Comptroller of the
Currency, the Director of the Office of Thrift Supervision,
the Secretary of the Department of Housing and Urban
Development, and the Director of the Office of Management and
Budget, designate a single calendar date for the transfer of
functions to the Division under section 1041; and
(2) publish notice of that designated date in the Federal
Register.
(b) Changing Designation.--The Secretary--
(1) may, in consultation with the Chairman of the Board of
Governors, the Chairperson of the Federal Deposit Insurance
Corporation, the Chairman of the Federal Trade Commission,
the Chairman of the National Credit Union Administration
Board, the Comptroller of the Currency, the Director of the
Office of Thrift Supervision, the Secretary of the Department
of Housing and Urban Development, and the Director of the
Office of Management and Budget, change the date designated
under subsection (a); and
(2) shall publish notice of any changed designated date in
the Federal Register.
(c) Permissible Dates.--
(1) In general.--Except as provided in paragraph (2), any
date designated under this section shall be not earlier than
180 days, nor later than 18 months, after the date of
enactment of this Act.
(2) Extension of time.--The Secretary may designate a date
that is later than 18 months after the date of enactment of
this Act if the Secretary transmits to appropriate committees
of Congress--
(A) a written determination that orderly implementation of
this title is not feasible before the date that is 18 months
after the date of enactment of this Act;
(B) an explanation of why an extension is necessary for the
orderly implementation of this title; and
(C) a description of the steps that will be taken to effect
an orderly and timely implementation of this title within the
extended time period.
(3) Extension limited.--In no case may any date designated
under this section be later than 24 months after the date of
enactment of this Act.

SEC. 1043. SAVINGS PROVISIONS.

(a) Board of Governors.--
(1) Existing rights, duties, and obligations not
affected.--Section 1041(b)(1) does not affect the validity of
any right, duty, or obligation of the United States, the
Board of Governors (or any Federal reserve bank), or any
other person that--
(A) arises under any provision of law relating to any
consumer financial protection function of the Board of
Governors transferred to the Division by this title; and
(B) existed on the day before the designated transfer date.
(2) Continuation of suits.--No provision of this title
shall abate any proceeding commenced by or against the Board
of Governors (or any Federal reserve bank) before the
designated transfer date with respect to any consumer
financial protection function of the Board of Governors (or
any Federal reserve bank) transferred to the Division by this
title, except that the Division, subject to section 1023,
shall be substituted for the Board of Governors (or Federal
reserve bank) as a party to any such proceeding as of the
designated transfer date.
(b) Federal Trade Commission.--
(1) Existing rights, duties, and obligations not
affected.--Section 1041(b)(5) does not affect the validity of
any right, duty, or obligation of the United States, the
Federal Trade Commission, or any other person, that--
(A) arises under any provision of law relating to any
consumer financial protection

[[Page S3221]]

function of the Federal Trade Commission transferred to the
Division by this title; and
(B) existed on the day before the designated transfer date.
(2) Continuation of suits.--No provision of this title
shall abate any proceeding commenced by or against the
Federal Trade Commission before the designated transfer date
with respect to any consumer financial protection function of
the Federal Trade Commission transferred to the Division by
this title, except that the Division, subject to section
1023, shall be substituted for the Federal Trade Commission
as a party to any such proceeding as of the designated
transfer date.
(c) Continuation of Existing Orders, Rules, Determinations,
Agreements, and Resolutions.--All orders, resolutions,
determinations, agreements, and rules that have been issued,
made, prescribed, or allowed to become effective by any
transferor agency or by a court of competent jurisdiction, in
the performance of consumer financial protection functions
that are transferred by this title and that are in effect on
the day before the designated transfer date, shall continue
in effect according to the terms of those orders,
resolutions, determinations, agreements, and rules, and shall
not be enforceable by or against the Division.
(d) Identification of Rules Continued.--Not later than the
designated transfer date, the Division--
(1) shall, after consultation with the head of each
transferor agency, identify the rules continued under
subsection (g) that will be enforced by the Division; and
(2) shall publish a list of such rules in the Federal
Register.
(e) Status of Rules Proposed or Not Yet Effective.--
(1) Proposed rules.--Any proposed rule of a transferor
agency which that agency, in performing consumer financial
protection functions transferred by this title, has proposed
before the designated transfer date, but has not been
published as a final rule before that date, shall be deemed
to be a proposed rule of the Division.
(2) Rules not yet effective.--Any interim or final rule of
a transferor agency which that agency, in performing consumer
financial protection functions transferred by this title, has
published before the designated transfer date, but which has
not become effective before that date, shall become effective
as a rule of the Division according to its terms.

SEC. 1044. TRANSFER OF CERTAIN PERSONNEL.

(a) In General.--
(1) Certain federal reserve system employees transferred.--
(A) Identifying employees for transfer.--The Division and
the Board of Governors shall--
(i) jointly determine the number of employees of the Board
of Governors necessary to perform or support the consumer
financial protection functions of the Board of Governors that
are transferred to the Division by this title; and
(ii) consistent with the number determined under clause
(i), jointly identify employees of the Board of Governors for
transfer to the Division, in a manner that the Division and
the Board of Governors, in their sole discretion, determine
equitable.
(B) Identified employees transferred.--All employees of the
Board of Governors identified under subparagraph (A)(ii)
shall be transferred to the Division for employment.
(C) Federal reserve bank employees.--Employees of any
Federal reserve bank who, on the day before the designated
transfer date, are performing consumer financial protection
functions on behalf of the Board of Governors shall be
treated as employees of the Board of Governors for purposes
of subparagraphs (A) and (B).
(2) Appointment authority for excepted service and senior
executive service transferred.--
(A) In general.--In the case of employee occupying a
position in the excepted service or the Senior Executive
Service, any appointment authority established pursuant to
law or regulations of the Office of Personnel Management for
filling such positions shall be transferred, subject to
subparagraph (B).
(B) Declining transfers allowed.--An agency or entity may
decline to make a transfer of authority under subparagraph
(A) (and the employees appointed pursuant thereto) to the
extent that such authority relates to positions excepted from
the competitive service because of their confidential,
policy-making, policy-determining, or policy-advocating
character, and non-career positions in the Senior Executive
Service (within the meaning of section 3132(a)(7) of title 5,
United States Code).
(b) Timing of Transfers and Position Assignments.--Each
employee to be transferred under this section shall--
(1) be transferred not later than 90 days after the
designated transfer date; and
(2) receive notice of a position assignment not later than
120 days after the effective date of his or her transfer.
(c) Transfer of Function.--
(1) In general.--Notwithstanding any other provision of
law, the transfer of employees shall be deemed a transfer of
functions for the purpose of section 3503 of title 5, United
States Code.
(2) Priority of this title.--If any provisions of this
title conflict with any protection provided to transferred
employees under section 3503 of title 5, United States Code,
the provisions of this title shall control.
(d) Equal Status and Tenure Positions.--
(1) Employees transferred from board, ftc.--Each employee
transferred under this title from the Board of Governors or
the Federal Trade Commission shall be placed in a position at
the Division with the same status and tenure as that employee
held on the day before the designated transfer date.
(2) Employees transferred from the federal reserve banks.--
(A) Comparability.--Each employee transferred under this
title from a Federal reserve bank shall be placed in a
position with the same status and tenure as that of an
employee transferring to the Division from the Board of
Governors who perform similar functions and have similar
periods of service.
(B) Service periods credited.--For purposes of this
paragraph, periods of service with the Board of Governors or
a Federal reserve bank shall be credited as periods of
service with a Federal agency.
(e) Additional Certification Requirements Limited.--
Examiners transferred to the Division are not subject to any
additional certification requirements before being placed in
a comparable examiner position at the Division examining the
same types of institutions as they examined before they were
transferred.
(f) Personnel Actions Limited.--
(1) 2-Year protection.--Except as provided in paragraph
(2), each transferred employee holding a permanent position
on the day before the designated transfer date may not,
during the 2-year period beginning on the designated transfer
date, be involuntarily separated, or involuntarily reassigned
outside his or her locality pay area, as defined by the
Office of Personnel Management.
(2) Exceptions.--Paragraph (1) does not limit the right of
the Division--
(A) to separate an employee for cause or for unacceptable
performance;
(B) to terminate an appointment to a position excepted from
the competitive service because of its confidential policy-
making, policy-determining, or policy-advocating character;
or
(C) to reassign a supervisory employee outside his or her
locality pay area, as defined by the Office of Personnel
Management, when the Division determines that the
reassignment is necessary for the efficient operation of the
Division.
(g) Pay.--
(1) 2-Year protection.--Except as provided in paragraph
(2), each transferred employee shall, during the 2-year
period beginning on the designated transfer date, receive pay
at a rate equal to not less than the basic rate of pay
(including any geographic differential) that the employee
received during the pay period immediately preceding the date
of transfer.
(2) Exceptions.--Paragraph (1) does not limit the right of
the Division to reduce the rate of basic pay of a transferred
employee--
(A) for cause;
(B) for unacceptable performance; or
(C) with the consent of the employee.
(3) Protection only while employed.--Paragraph (1) applies
to a transferred employee only while that employee remains
employed by the Division.
(4) Pay increases permitted.--Paragraph (1) does not limit
the authority of the Division to increase the pay of a
transferred employee.
(h) Reorganization.--
(1) Between 1st and 3rd year.--
(A) In general.--If the Division determines, during the 2-
year period beginning 1 year after the designated transfer
date, that a reorganization of the staff of the Division is
required--
(i) that reorganization shall be deemed a ``major
reorganization'' for purposes of affording affected employees
retirement under section 8336(d)(2) or 8414(b)(1)(B) of title
5, United States Code;
(ii) before the reorganization occurs, all employees in the
same locality pay area as defined by the Office of Personnel
Management shall be placed in a uniform position
classification system; and
(iii) any resulting reduction in force shall be governed by
the provisions of chapter 35 of title 5, United States Code,
except that the Division shall--

(I) establish competitive areas (as that term is defined in
regulations issued by the Office of Personnel Management) to
include at a minimum all employees in the same locality pay
area as defined by the Office of Personnel Management;
(II) establish competitive levels (as that term is defined
in regulations issued by the Office of Personnel Management)
without regard to whether the particular employees have been
appointed to positions in the competitive service or the
excepted service; and
(III) afford employees appointed to positions in the
excepted service (other than to a position excepted from the
competitive service because of its confidential policy-
making, policy-determining, or policy-advocating character)
the same assignment rights to positions within the Division
as employees appointed to positions in the competitive
service.

(B) Service credit for reductions in force.--For purposes
of this paragraph, periods of service with a Federal home
loan bank, a joint office of the Federal home loan banks, the
Board of Governors, a Federal reserve bank, the Federal
Deposit Insurance Corporation, or the National Credit Union
Administration shall be credited as periods of service with a
Federal agency.
(2) After 3rd year.--

[[Page S3222]]

(A) In general.--If the Division determines, at any time
after the 3-year period beginning on the designated transfer
date, that a reorganization of the staff of the Division is
required, any resulting reduction in force shall be governed
by the provisions of chapter 35 of title 5, United States
Code, except that the Division shall establish competitive
levels (as that term is defined in regulations issued by the
Office of Personnel Management) without regard to types of
appointment held by particular employees transferred under
this section.
(B) Service credit for reductions in force.--For purposes
of this paragraph, periods of service with a Federal home
loan bank, a joint office of the Federal home loan banks, the
Board of Governors, a Federal reserve bank, the Federal
Deposit Insurance Corporation, or the National Credit Union
Administration shall be credited as periods of service with a
Federal agency.
(i) Benefits.--
(1) Retirement benefits for transferred employees.--
(A) In general.--
(i) Continuation of existing retirement plan.--Except as
provided in subparagraph (B), each transferred employee shall
remain enrolled in his or her existing retirement plan,
through any period of continuous employment with the
Division.
(ii) Employer contribution.--The Division shall pay any
employer contributions to the existing retirement plan of
each transferred employee, as required under that plan.
(B) Option for employees transferred from federal reserve
system to be subject to federal employee retirement
program.--
(i) Election.--Any transferred employee who was enrolled in
a Federal Reserve System retirement plan on the day before
his or her transfer to the Division may, during the 1-year
period beginning 6 months after the designated transfer date,
elect to be subject to the Federal employee retirement
program.
(ii) Effective date of coverage.--For any employee making
an election under clause (i), coverage by the Federal
employee retirement program shall begin 1 year after the
designated transfer date.
(C) Division participation in federal reserve system
retirement plan.--
(i) Separate account in federal reserve system retirement
plan established.--Notwithstanding any other provision of
law, and subject to the terms and conditions of this section,
a separate account in the Federal Reserve System retirement
plan shall be established for Division employees who do not
make the election under subparagraph (B).
(ii) Funds attributable to transferred employees remaining
in federal reserve system retirement plan transferred.--The
proportionate share of funds in the Federal Reserve System
retirement plan, including the proportionate share of any
funding surplus in that plan, attributable to a transferred
employee who does not make the election under subparagraph
(B), shall be transferred to the account established under
clause (i).
(iii) Employer contributions deposited.--The Division shall
deposit into the account established under clause (i) the
employer contributions that the Division makes on behalf of
employees who do not make the election under subparagraph
(B).
(iv) Account administration.--The Division shall administer
the account established under clause (i) as a participating
employer in the Federal Reserve System retirement plan.
(D) Definitions.--For purposes of this paragraph--
(i) the term ``existing retirement plan'' means, with
respect to any employee transferred under this section, the
particular retirement plan (including the Financial
Institutions Retirement Fund) and any associated thrift
savings plan of the agency or Federal reserve bank from which
the employee was transferred, which the employee was enrolled
in on the day before the designated transfer date; and
(ii) the term ``Federal employee retirement program'' means
the retirement program for Federal employees established by
chapter 84 of title 5, United States Code.
(2) Benefits other than retirement benefits for transferred
employees.--
(A) During 1st year.--
(i) Existing plans continue.--Each transferred employee
may, for 1 year after the designated transfer date, retain
membership in any other employee benefit program of the
agency or bank from which the employee transferred, including
a dental, vision, long term care, or life insurance program,
to which the employee belonged on the day before the
designated transfer date.
(ii) Employer contribution.--The Division shall reimburse
the agency or bank from which an employee was transferred for
any cost incurred by that agency or bank in continuing to
extend coverage in the benefit program to the employee, as
required under that program or negotiated agreements.
(B) Dental, vision, or life insurance after 1st year.--If,
after the 1-year period beginning on the designated transfer
date, the Division decides not to continue participation in
any dental, vision, or life insurance program of an agency or
bank from which an employee transferred, a transferred
employee who is a member of such a program may, before the
decision of the Division takes effect, elect to enroll,
without regard to any regularly scheduled open season, in--
(i) the enhanced dental benefits established by chapter 89A
of title 5, United States Code;
(ii) the enhanced vision benefits established by chapter
89B of title 5, United States Code; or
(iii) the Federal Employees Group Life Insurance Program
established by chapter 87 of title 5, United States Code,
without regard to any requirement of insurability.
(C) Long term care insurance after 1st year.--If, after the
1-year period beginning on the designated transfer date, the
Division decides not to continue participation in any long
term care insurance program of an agency or bank from which
an employee transferred, a transferred employee who is a
member of such a program may, before the decision of the
Division takes effect, elect to apply for coverage under the
Federal Long Term Care Insurance Program established by
chapter 90 of title 5, United States Code, under the
underwriting requirements applicable to a new active
workforce member (as defined in part 875, title 5, Code of
Federal Regulations).
(D) Employee contribution.--An individual enrolled in the
Federal Employees Health Benefits program shall pay any
employee contribution required by the plan.
(E) Additional funding.--The Division shall transfer to the
Federal Employees Health Benefits Fund established under
section 8909 of title 5, United States Code, an amount
determined by the Director of the Office of Personnel
Management, after consultation with the Division and the
Office of Management and Budget, to be necessary to reimburse
the Fund for the cost to the Fund of providing benefits under
this paragraph.
(F) Credit for time enrolled in other plans.--For employees
transferred under this title, enrollment in a health benefits
plan administered by a transferor agency or a Federal reserve
bank, as the case may be, immediately before enrollment in a
health benefits plan under chapter 89 of title 5, United
States Code, shall be considered as enrollment in a health
benefits plan under that chapter for purposes of section
8905(b)(1)(A) of title 5, United States Code.
(G) Special provisions to ensure continuation of life
insurance benefits.--
(i) In general.--An annuitant (as defined in section
8901(3) of title 5, United States Code) who is enrolled in a
life insurance plan administered by a transferor agency on
the day before the designated transfer date shall be eligible
for coverage by a life insurance plan under sections 8706(b),
8714a, 8714b, and 8714c of title 5, United States Code, or in
a life insurance plan established by the Division, without
regard to any regularly scheduled open season and requirement
of insurability.
(ii) Employee contribution.--An individual enrolled in a
life insurance plan under this subparagraph shall pay any
employee contribution required by the plan.
(iii) Additional funding.--The Division shall transfer to
the Employees' Life Insurance Fund established under section
8714 of title 5, United States Code, an amount determined by
the Director of the Office of Personnel Management, after
consultation with the Division and the Office of Management
and Budget, to be necessary to reimburse the Fund for the
cost to the Fund of providing benefits under this
subparagraph not otherwise paid for by the employee under
clause (ii).
(iv) Credit for time enrolled in other plans.--For
employees transferred under this title, enrollment in a life
insurance plan administered by a transferor agency
immediately before enrollment in a life insurance plan under
chapter 87 of title 5, United States Code, shall be
considered as enrollment in a life insurance plan under that
chapter for purposes of section 8706(b)(1)(A) of title 5,
United States Code.
(3) OPM rules.--The Office of Personnel Management shall
issue such rules as are necessary to carry out this
subsection.
(j) Implementation of Uniform Pay and Classification
System.--Not later than 2 years after the designated transfer
date, the Division shall implement a uniform pay and
classification system for all employees transferred under
this title.
(k) Equitable Treatment.--In administering the provisions
of this section, the Division--
(1) shall take no action that would unfairly disadvantage
transferred employees relative to each other based on their
prior employment by the Board of Governors, the Federal
Deposit Insurance Corporation, the Federal Trade Commission,
the National Credit Union Administration, the Office of the
Comptroller of the Currency, the Office of Thrift
Supervision, a Federal reserve bank, a Federal home loan
bank, or a joint office of the Federal home loan banks; and
(2) may take such action as is appropriate in individual
cases so that employees transferred under this section
receive equitable treatment, with respect to the status,
tenure, pay, benefits (other than benefits under programs
administered by the Office of Personnel Management), and
accrued leave or vacation time of those employees, for prior
periods of service with any Federal agency, including the
Board of Governors, the Corporation, the Federal Trade
Commission, the National Credit Union Administration, the
Office of the Comptroller of the Currency, the Office of
Thrift Supervision, a Federal reserve bank, a Federal home
loan bank, or a joint office of the Federal home loan banks.
(l) Implementation.--In implementing the provisions of this
section, the Division shall

[[Page S3223]]

coordinate with the Office of Personnel Management and other
entities having expertise in matters related to employment to
ensure a fair and orderly transition for affected employees.

Subtitle D--Amendment to the Federal Deposit Insurance Act

SEC. 1051. CORPORATION BOARD MEMBERSHIP.

Section 2(a)(1)(B) of the Federal Deposit Insurance Act (12
U.S.C. 1812(a)(1)(B)) is amended to read as follows:
``(B) the Head of Supervision for the Board of Governors of
the Federal Reserve System; and''.
______