S.Amdt. 3890Senate111th Congress (2009-2011)2nd degree
S.Amdt. 3890
Sponsored by 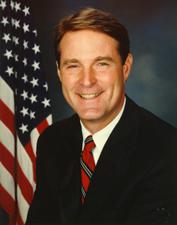 Sen. Evan Bayh (D-IN)
Submitted May 6, 2010
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
May 6, 2010
Text
Submitted
TEXT OF AMENDMENTS

SA 3860. Mr. CARPER (for himself, Mr. Ensign, Mr. Gregg, and Mr.
Johanns) submitted an amendment intended to be proposed to amendment SA
3739 proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln))
to the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 1086, strike line 3 and all that follows through
``Not'' on page 1090, line 9, and insert the following:

[[Page S3365]]

SEC. 971. PROXY ACCESS.

(a) Proxy Access.--Section 14(a) of the Securities Exchange
Act of 1934 (15 U.S.C. 78n(a)) is amended--
(1) by inserting ``(1)'' after ``(a)''; and
(2) by adding at the end the following:
``(2) The rules and regulations prescribed by the
Commission under paragraph (1) may include--
``(A) a requirement that a solicitation of proxy, consent,
or authorization by (or on behalf of) an issuer include a
nominee submitted by a shareholder to serve on the board of
directors of the issuer; and
``(B) a requirement that an issuer follow a certain
procedure in relation to a solicitation described in
subparagraph (A).''.
(b) Regulations.--The Commission may issue rules permitting
the use by shareholders of proxy solicitation materials
supplied by an issuer of securities for the purpose of
nominating individuals to membership on the board of
directors of the issuer, under such terms and conditions as
the Commission determines are in the interests of
shareholders and for the protection of investors.

SEC. 972. DISCLOSURES REGARDING CHAIRMAN AND CEO STRUCTURES.

The Securities Exchange Act of 1934 (15 U.S.C. 78a et seq.)
is amended by inserting after section 14A, as added by this
title, the following:

``SEC. 14B. DISCLOSURES REGARDING CHAIRMAN AND CEO
STRUCTURES.

``Not
______

SA 3861. Mr. CARPER (for himself, Mr. Ensign, Mr. Gregg, Mr. Corker,
and Mr. Johanns) submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 1089, strike line 6 and all that follows through
``SEC. 973.'' on page 1090, line 3, and insert the following:

SEC. 972.

______

SA 3862. Ms. COLLINS submitted an amendment intended to be proposed
by her to the bill S. 3217, to promote the financial stability of the
United States by improving accountability and transparency in the
financial system, to end ``too big to fail'', to protect the American
taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

In section 111(b)(1) of the amendment, strike subparagraph
(A) and insert the following:
(A) the Chairperson of the Council, who--
(i) shall be appointed by the President, by and with the
advice and consent of the Senate, from among individuals
having expertise in the financial services industry; and
(ii) may not, during such service, also serve as the head
of any primary financial regulatory agency;
(B) the Secretary of the Treasury;
______

SA 3863. Ms. COLLINS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 23, between lines 2 and 3, insert the following:
(I) the Chairman of the National Credit Union
Administration; and
______

SA 3864. Ms. COLLINS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 23, between lines 2 and 3, insert the following:
(I) a State insurance commissioner--
(i) to be designated using a selection process determined
by the insurance commissioners of the States; and
(ii) who shall serve for a term of not longer than 2 years;
and
______

SA 3865. Mr. GREGG (for himself and Mr. Johanns) submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

Beginning on page 513, strike line 21 and all that follows
through page 515, line 11.
______

SA 3866. Mr. WYDEN (for himself and Mr. Brown of Massachusetts)
submitted an amendment intended to be proposed by him to the bill S.
3217, to promote the financial stability of the United States by
improving accountability and transparency in the financial system, to
end ``too big to fail'', to protect the American taxpayer by ending
bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

At the end of subtitle A of title I, add the following:

SEC. 123. DISCLOSURE OF FINANCIAL INTERESTS IN THE DECLINE IN
VALUE OF FINANCIAL PRODUCTS.

(a) Recommendations by Council.--Not later than 180 days
after the date of enactment of this Act, the Council shall
make recommendations to the primary financial regulatory
agencies to require any seller of a financial product or
instrument to disclose to the purchaser or prospective
purchaser of that product--
(1) whether the seller has any direct financial interest in
the decline in value of the product; and
(2) whether the seller has any direct financial interest in
the increase in value of the product.
(b) Procedures and Implementation.--The procedural and
implementation provisions of subsections (b) and (c) of
section 120 shall apply to recommendations of the Council
under this section.
______

SA 3867. Mr. ENSIGN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 1034, strike line 8 and all that follows through
line 21, and insert the following:

SEC. 935. CONSIDERATION OF INFORMATION FROM SOURCES OTHER
THAN THE ISSUER IN RATING DECISIONS.

Section 15E of the Securities Exchange Act of 1934 (15
U.S.C. 78o-7), as amended by this subtitle, is amended by
adding at the end the following:
``(v) Information From Sources Other Than the Issuer.--In
producing a credit rating, a nationally recognized
statistical rating organization shall consider information
about an issuer that the nationally recognized statistical
rating organization has, or receives from a source other than
the issuer or the underwriter, that the nationally recognized
statistical rating organization finds credible and
potentially significant to a rating decision.''.
______

SA 3868. Mr. ENSIGN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 1034, strike line 22 and all that follows through
page 1035, line 9, and insert the following:

SEC. 936. QUALIFICATION STANDARDS FOR CREDIT RATING ANALYSTS.

Not later than 1 year after the date of enactment of this
Act, the Commission shall issue rules that are reasonably
designed to ensure that any person employed by a nationally
recognized statistical rating organization to perform credit
ratings--

[[Page S3366]]

(1) meets standards of training, experience, best
practices, and competence necessary to produce accurate
ratings for the categories of issuers whose securities the
person rates;
(2) is tested for knowledge of the credit rating process;
and
(3) is required to participate in annual continuing
education seminars to maintain the standards described in
paragraph (1).
______

SA 3869. Mr. ENSIGN submitted an amendment intended to be proposed to
amendment SA 3787 submitted by Mr. Brown of Ohio (for himself and Mr.
Kaufman) and intended to be proposed to the amendment SA 3739 proposed
by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill
S. 3217, to promote the financial stability of the United States by
improving accountability and transparency in the financial system, to
end ``too big to fail'', to protect the American taxpayer by ending
bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 3 of the amendment, strike lines 11 through 13 and
insert the following:
(2) Financial company.--The term ``financial company''
means--
(A) any nonbank financial company supervised by the Board;
(B) the Federal National Mortgage Association; and
(C) the Federal Home Loan Mortgage Corporation.
______

SA 3870. Mr. KERRY (for himself, Mr. Brown of Massachusetts, and Mr.
Brownback) submitted an amendment intended to be proposed to amendment
SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs.
Lincoln)) to the bill S. 3217, to promote the financial stability of
the United States by improving accountability and transparency in the
financial system, to end ``too big to fail'', to protect the American
taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 370, strike line 14 and all that follows through
page 371, line 19, and insert the following:

Subtitle D--Federal Thrift Charter

SEC. 341. FEDERAL SAVINGS ASSOCIATIONS.

Section 5(a) of the Home Owners' Loan Act (12 U.S.C.
1464(a)) is amended to read as follows:
``(a) In General.--In order to provide thrift institutions
for the deposit of funds and for the extension of credit for
homes and other goods and services, the Comptroller of the
Currency is authorized, under such regulations as the
Comptroller of the Currency may prescribe, to provide for the
chartering, examination, operation, and regulation of
associations to be known as `Federal savings associations'
(including Federal savings banks), giving primary
consideration to the best practices of thrift institutions in
the United States. The lending and investment powers
conferred by this section are intended to encourage such
institutions to provide credit for housing safely and
soundly.''.
______

SA 3871. Mr. CARDIN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 43, between lines 6 and 7, insert the following:
(3) Investment companies and advisers.--In the event that
an investment company required to be registered under the
Investment Company Act of 1940, or the registered investment
adviser to such a company, is subject to supervision by the
Board of Governors, the Council shall, in consultation with
the Commission and in lieu of the prudential standards
outlined in subsections (b) through (f), recommend to the
Board of Governors such alternative enhanced regulatory
requirements as are necessary to prevent or mitigate risks to
the financial stability of the United States that could arise
from the material financial distress of the investment
company or investment adviser. Such alternative requirements
shall not include capital requirements.
On page 91, between lines 23 and 24, insert the following:
(3) Investment companies and advisers.--In the case of an
investment company required to be registered under the
Investment Company Act of 1940, or the registered investment
adviser to such a company, that is supervised by the Board of
Governors, the Board of Governors shall meet its obligations
under this section by adopting the alternative enhanced
regulatory requirements recommended by the Council under
section 115.
______

SA 3872. Mr. BROWN of Massachusetts (for himself, Mr. Kerry, and Mr.
Gregg) submitted an amendment intended to be proposed to amendment SA
3739 proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln))
to the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 485, line 25, strike ``and'' and all that follows
through ``the term'' on page 486, line 1 and insert the
following:
``(3) the term `insured depository institution' does not
include an insured depository institution--
``(A) the activities of which are limited to providing
trust or fiduciary services; and
``(B) that does not--
``(i) accept insured deposits from persons other than
affiliates;
``(ii) exercise discount or borrowing privileges pursuant
to section 19(b)(7) of the Federal Reserve Act (12 U.S.C.
461(b)(7)); or
``(iii) does not make commercial or consumer loans; and
``(4) the term''.
______

SA 3873. Mr. DeMINT (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill S. 3217, to
promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

At the end of title X, insert the following:

SEC. ___. POINT OF ORDER ON LEGISLATION THAT PROVIDES THE
GOVERNMENT WITH NEW POWERS TO GIVE TAXPAYER-
FUNDED BAILOUTS OR ANY OTHER PREFERENTIAL
TREATMENT TO ANY PUBLIC OR PRIVATE INSTITUTION
IN FINANCIAL DISTRESS.

(a) In General.--In the Senate, it shall not be in order to
consider any bill, joint resolution, amendment, motion, or
conference report that provides the Government with new
powers to give taxpayer-funded bailouts or any other
preferential treatment to any public or private institution
in financial distress.
(b) Suspension of Point of Order.--A point of order raised
under subsection (a) shall be suspended in the Senate upon
certification by the Congressional Budget Office that such
bill, joint resolution, amendment, motion or conference
report does not provide the Government with new powers to
give taxpayer-funded bailouts or any other preferential
treatment to any public or private institution in financial
distress.
(c) Waiver and Appeal.--
(1) Waiver.--This section may be waived or suspended only
by an affirmative vote of two-thirds of the Members, duly
chosen and sworn.
(2) Appeal.--An affirmative vote of two-thirds of the
Members of the Senate, duly chosen and sworn, shall be
required to sustain an appeal of the ruling of the Chair on a
point of order raised under this section.
______

SA 3874. Mr. PRYOR (for himself, Mr. Baucus, Mr. Tester, Mrs.
Shaheen, Mr. Johnson, Mr. Bennet, and Mr. Warner) submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

On page 304, strike line 3 and all that follows though page
313, line 21, and insert the following:
(c) Certain Functions of the Board of Governors.--
(1) Comptroller of the currency.--Except as provided in
paragraph (3), there are transferred to the Office of the
Comptroller of the Currency all functions of the Board of
Governors (including any Federal reserve bank) relating to
the supervision of--
(A) any bank holding company (other than a foreign bank)--
(i) having less than $50,000,000,000 in total consolidated
assets; and
(ii) having--

(I) a subsidiary that is an insured depository institution,
if all such insured depository institutions are Federal
depository institutions; or

[[Page S3367]]

(II) a subsidiary that is a Federal depository institution
and a subsidiary that is a State depository institution, if
the total consolidated assets of all subsidiaries that are
Federal depository institutions--

(aa) exceed the total consolidated assets of all subsidiary
State depository institutions that are State member banks;
and
(bb) exceed the total consolidated assets of all subsidiary
State depository institutions that are State nonmember
insured banks and State savings associations; and
(B) any subsidiary (other than a depository institution) of
a bank holding company that is described in subparagraph (A).
(2) Corporation.--Except as provided in paragraph (3),
there are transferred to the Corporation all functions of the
Board of Governors (including any Federal reserve bank)
relating to the supervision of--
(A) any bank holding company (other than a foreign bank)--
(i) having less than $50,000,000,000 in total consolidated
assets; and
(ii) having--

(I) a subsidiary that is an insured depository institution,
if all such insured depository institutions are State
nonmember insured banks or State savings associations; or
(II) a subsidiary that is a State nonmember insured bank or
a State savings association and a subsidiary that is not a
State nonmember insured bank or State savings association, if
the total consolidated assets of all such subsidiaries that
are State nonmember insured banks or State savings
associations--

(aa) exceeds the total consolidated assets of all
subsidiaries that are Federal depository institutions; and
(bb) exceeds the total consolidated assets of all
subsidiaries that are State member banks; and
(B) any subsidiary (other than a depository institution) of
a bank holding company that is described in subparagraph (A).
(3) Rulemaking authority.--No rulemaking authority of the
Board of Governors is transferred to the Office of the
Comptroller of the Currency or the Corporation under this
subsection.
(4) Rule of construction.--Nothing in this subsection may
be construed to transfer to the Office of the Comptroller of
the Currency or the Corporation any functions of the Board of
Governors (including any Federal reserve bank) relating to
the supervision of--
(A) any State member bank;
(B) any bank holding company (other than a foreign bank)--
(i) having less than $50,000,000,000 in total consolidated
assets; and
(ii) having--

(I) a subsidiary that is an insured depository institution,
if all such insured depository institutions are State member
banks; or
(II) a subsidiary that is a State member bank and a
subsidiary that is not a State member bank, if the total
consolidated assets of all subsidiaries that are State member
banks--

(aa) exceed the total consolidated assets of all
subsidiaries that are Federal depository institutions; and
(bb) exceed the total consolidated assets of all
subsidiaries that are State nonmember insured banks and State
savings associations; or
(C) any subsidiary (other than a depository institution) of
a bank holding company that is described in subparagraph (B).
(d) Conforming Amendments.--
(1) Federal deposit insurance act.--Section 3(q) of the
Federal Deposit Insurance Act (12 U.S.C. 1813(q)) is amended
by striking paragraphs (1) through (4) and inserting the
following:
``(1) the Office of the Comptroller of the Currency, in the
case of--
``(A) any national banking association;
``(B) any Federal branch or agency of a foreign bank;
``(C) any bank holding company (other than a foreign
bank)--
``(i) having less than $50,000,000,000 in total
consolidated assets; and
``(ii) having--

``(I) a subsidiary that is an insured depository
institution, if all such insured depository institutions are
Federal depository institutions; or
``(II) a subsidiary that is a Federal depository
institution and a subsidiary that is a State depository
institution, if the total consolidated assets of all
subsidiaries that are Federal depository institutions--

``(aa) exceed the total consolidated assets of all
subsidiary State depository institutions that are State
member banks; and
``(bb) exceed the total consolidated assets of all
subsidiary State depository institutions that are State
nonmember insured banks and State savings associations;
``(D) any subsidiary (other than a depository institution)
of a bank holding company that is described in subparagraph
(C);
``(E) any Federal savings association;
``(F) any savings and loan holding company (other than a
foreign bank)--
``(i) having less than $50,000,000,000 in total
consolidated assets; and
``(ii) having--

``(I) a subsidiary that is an insured depository
institution, if all such insured depository institutions are
Federal depository institutions; or
``(II) a subsidiary that is a Federal depository
institution and a subsidiary that is a State depository
institution, if the total consolidated assets of all
subsidiaries that are Federal depository institutions exceed
the total consolidated assets of all such subsidiaries that
are State depository institutions; and

``(G) any subsidiary (other than a depository institution)
of a savings and loan holding company that is described in
subparagraph (F);
``(2) the Federal Deposit Insurance Corporation, in the
case of--
``(A) any State nonmember insured bank;
``(B) any foreign bank having an insured branch;
``(C) any State savings association;
``(D) any bank holding company (other than a foreign
bank)--
``(i) having less than $50,000,000,000 in total
consolidated assets; and
``(ii) having--

``(I) a subsidiary that is an insured depository
institution, if all such insured depository institutions are
State nonmember insured banks or State savings associations;
or
``(II) a subsidiary that is a State nonmember insured bank
or a State savings association and a subsidiary that is not a
State nonmember insured bank or State savings association, if
the total consolidated assets of all subsidiaries that are
State nonmember insured banks or State savings associations--

``(aa) exceeds the total consolidated assets of all
subsidiaries that are Federal depository institutions; and
``(bb) exceeds the total consolidated assets of all
subsidiaries that are State member banks;
``(E) any subsidiary (other than a depository institution)
of a bank holding company that is described in subparagraph
(D);
``(F) any savings and loan holding company (other than a
foreign bank)--
``(i) having less than $50,000,000,000 in total
consolidated assets; and
``(ii) having--

``(I) a subsidiary that is an insured depository
institution, if all such insured depository institutions are
State depository institutions; or
``(II) a subsidiary that is a Federal depository
institution and a subsidiary that is a State depository
institution, if the total consolidated assets of all
subsidiaries that are State depository institutions exceed
the total consolidated assets of all subsidiaries that are
Federal depository institutions; and

``(G) any subsidiary (other than a depository institution)
of a savings and loan holding company that is described in
subparagraph (F);
``(3) the Board of Governors of the Federal Reserve System,
in the case of--
``(A) any State member bank;
``(B) any branch or agency of a foreign bank with respect
to any provision of the Federal Reserve Act which is made
applicable under the International Banking Act of 1978;
``(C) any foreign bank which does not operate an insured
branch;
``(D) any agency or commercial lending company other than a
Federal agency;
``(E) supervisory or regulatory proceedings arising from
the authority given to the Board of Governors under section
7(c)(1) of the International Banking Act of 1978, including
such proceedings under the Financial Institutions Supervisory
Act of 1966;
``(F) any bank holding company having total consolidated
assets of $50,000,000,000 or more, any bank holding company
that is a foreign bank, and any subsidiary (other than a
depository institution) of such a bank holding company;
``(G) any savings and loan holding company having total
consolidated assets of $50,000,000,000 or more, any savings
and loan holding company that is a foreign bank, and any
subsidiary (other than a depository institution) of such a
savings and loan holding company;
``(H) any bank holding company (other than a foreign
bank)--
``(i) having less than $50,000,000,000 in total
consolidated assets; and
``(ii) having--

``(I) a subsidiary that is an insured depository
institution, if all such insured depository institutions are
State member banks; or
``(II) a subsidiary that is a State member bank and a
subsidiary that is not a State member bank, if the total
consolidated assets of all subsidiaries that are State member
banks--

``(aa) exceed the total consolidated assets of all
subsidiaries that are Federal depository institutions; and
``(bb) exceed the total consolidated assets of all
subsidiaries that are State nonmember insured banks and State
savings associations; and
``(I) any subsidiary (other than a depository institution)
of a bank holding company that is described in subparagraph
(H).''.
(2) Certain references in the bank holding company act of
1956.--
(A) Comptroller of the currency.--On or after the transfer
date, in the case of a bank holding company described in
section 3(q)(1)(C) of the Federal Deposit Insurance Act, as
amended by this Act, any reference in the Bank Holding
Company Act of 1956 (12 U.S.C. 1841 et seq.) to the Board of
Governors shall be deemed to be a reference to the Office of
the Comptroller of the Currency.
(B) Corporation.--On or after the transfer date, in the
case of a bank holding company described in section
3(q)(2)(D) of the Federal Deposit Insurance Act, as amended
by this Act, any reference in the Bank Holding Company Act of
1956 (12 U.S.C. 1841 et seq.) to the Board of Governors shall
be deemed to be a reference to the Corporation.

[[Page S3368]]

(C) Rule of construction.--Notwithstanding subparagraph (A)
or (B), the Board of Governors shall retain all rulemaking
authority under the Bank Holding Company Act of 1956 (12
U.S.C. 1841 et seq.).
(3) Consultation in holding company rulemaking.--
(A) Bank holding companies.--Section 5 of the Bank Holding
Company Act of 1956 (12 U.S.C. 1844) is amended by adding at
the end the following:
``(h) Consultation in Rulemaking.--Before proposing or
adopting regulations under this Act that apply to bank
holding companies having less than $50,000,000,000 in total
consolidated assets, the Board of Governors shall consult
with the Comptroller of the Currency and the Federal Deposit
Insurance Corporation as to the terms of such regulations.''.
______

SA 3875. Mr. COBURN submitted an amendment intended to be proposed to
amendment SA 3775 submitted by Mr. Wyden (for himself and Mr. Grassley)
and intended to be proposed to the amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

At the end of the amendment, insert the following:

SEC. ___. STOP SECRET SPENDING ACT.

(a) Short Title.--This section may be cited as the ``Stop
Secret Spending Act''.
(b) Notice Requirement.--Legislation that has been subject
to a hotline notification may not pass by unanimous consent
unless--
(1) the hotline notification has been posted on the public
website of the Senate for at least 3 calendar days as
provided in subsection (c); and
(2) signed statements from every Member of the Senate
attesting that they have read the legislation (except for a
sense of the Senate measure) and understand its impact
including the cost have been submitted to and printed in the
Congressional Record using the following format: ``I, Senator
____, have read [bill number] and understand its impact,
including the cost, and support its passage.''.
(c) Posting on Senate Webpage.--At the same time as a
hotline notification occurs with respect to any legislation,
the Majority Leader shall post in a prominent place on the
public webpage of the Senate a notice that the legislation
has been hotlined and the legislation's number, title, link
to full text, and sponsor and the estimated cost to implement
and the number of new programs created by the legislation.
(d) Legislative Calendar.--
(1) In general.--The Secretary of the Senate shall
establish for both the Senate Calendar of Business and the
Senate Executive Calendar a separate section entitled
``Notice of Intent To Pass by Unanimous Consent''.
(2) Content.--The section required by paragraph (1) shall--
(A) include any legislation posted as required by
subsection (c) and the date the hotline notification
occurred; and
(B) be updated as appropriate.
(3) Removal.--Items included on the calendar under this
subsection shall be removed from the calendar once passed by
the Senate.
(e) Exceptions.--This section shall not apply--
(1) if a quorum of the Senate is present at the time the
unanimous consent is propounded to pass the bill;
(2) to any legislation relating to an imminent or ongoing
emergency, as jointly agreed to by the Majority and Minority
Leaders; and
(3) to nominations.
(f) Suspension.--The Presiding Officer shall not entertain
any request to suspend this section by unanimous consent.
(g) Hotline Notification Defined.--In this section, the
term ``hotline notification'' means when the Majority Leader
in consultation with the Minority Leader, provides notice of
intent to pass legislation by unanimous consent by contacting
each Senate office with a message on a special alert line
(commonly referred to as the hotline) that provides
information on what bill or bills the Majority Leader is
seeking to pass through unanimous consent.
______

SA 3876. Mr. MENENDEZ (for himself and Mr. Burris) submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

On page 372, line 2, strike ``bank.'' and insert the
following: ``bank.

SEC. 343. WOMEN AND MINORITY ADVANCEMENT.

(a) Definitions.--In this section--
(1) the term ``covered person'' means a person that--
(A) has more than 50 employees; and
(B) makes a proposal to a financial agency for a contract
that has a value of more than $50,000;
(2) the term ``Director'' means a Director of Minority and
Women Advancement appointed under subsection (c);
(3) the term ``diversity'' includes racial, gender, and
ethnic diversity;
(4) the term ``financial agency'' means--
(A) the Department of the Treasury;
(B) the Corporation;
(C) the Federal Housing Finance Agency;
(D) each of the Federal reserve banks;
(E) the Board of Governors;
(F) the National Credit Union Administration;
(G) the Commission;
(H) the Office of the Comptroller of the Currency;
(I) the Council;
(J) the Bureau; and
(K) the Office of National Insurance established under
title V;
(5) the term ``financial agency administrator'' means the
head of a financial agency;
(6) the term ``minority'' has the same meaning as in
section 1204(c) of the Financial Institutions Reform,
Recovery, and Enforcement Act of 1989 (12 U.S.C. 1811 note);
(7) the terms ``minority-owned business'' and ``women-owned
business''--
(A) have the same meanings as in section 21A(r)(4) of the
Federal Home Loan Bank Act (12 U.S.C. 1441a(r)(4)); and
(B) include financial institutions, investment banking
firms, mortgage banking firms, asset management firms,
brokers, dealers, financial services firms, underwriters,
accountants, investment consultants, and providers of legal
services; and
(8) the term ``Office'' means an Office of Minority and
Women Advancement established under subsection (b).
(b) Office of Minority and Women Advancement.--
(1) Establishment.--Not later than 180 days after the date
of enactment of this Act, each financial agency shall
establish an Office of Minority and Women Advancement that
shall--
(A) be responsible for all matters of the financial agency
relating to diversity in management, employment, and business
activities, including contracting and the coordination of
technical assistance, in accordance with such standards and
requirements as the Director of the Office shall establish;
and
(B) advise the financial agency administrator of the impact
of policies and regulations of the financial agency on
minority-owned businesses, women-owned businesses, and
diversity at such businesses.
(2) Transfer of responsibilities.--Each financial agency
that, before the date of enactment of this Act, assigned the
responsibilities described in paragraph (1) (or comparable
responsibilities) to another office of the financial agency
shall ensure that such responsibilities are transferred to
the Office.
(c) Director.--
(1) In general.--The head of the Office of a financial
agency shall be the Director of Minority and Women
Advancement, who shall be appointed by the financial agency
administrator of the financial agency.
(2) Reporting; title.--Each Director shall report directly
to the financial agency administrator and hold a title within
the financial agency of the Director that is comparable to
the title of other senior-level staff members of the
financial agency who act in a managerial capacity and report
directly to the financial agency administrator.
(3) Duties.--Each Director shall--
(A) ensure equal employment opportunity and encourage the
racial, ethnic, and gender diversity of the workforce and
senior management of the subject financial agency;
(B) work to increase--
(i) the participation rates of minority-owned businesses
and women-owned businesses in the programs and contracts of
the subject financial agency; and
(ii) the percentage of the amounts expended by the subject
financial agency that is expended with minority-owned
businesses and women-owned businesses; and
(C) provide guidance to the financial agency administrator
to ensure that the policies and regulations of the financial
agency strengthen minority-owned businesses and women-owned
businesses.
(d) Advancement in All Levels of Business Activities.--Each
Director shall develop and implement standards and procedures
to ensure, to the maximum extent possible, the advancement of
minorities and women, and the use of minority-owned
businesses and women-owned businesses, in all activities of
the financial agency at every level, including in
procurement, insurance, and all types of contracting
(including, as applicable, contracting for the issuance or
guarantee of debt, equity, or security, the sale of assets,
the management of assets, the making of equity investments,
and the implementation of programs to promote economic
recovery).
(e) Contracts.--
(1) In general.--Any process established by a financial
agency for the review and evaluation of a contract proposal
or the employment of a service provider shall give

[[Page S3369]]

consideration to the diversity of the covered person.
(2) Written assurance.--Each covered person shall include
in the contract of the covered person with a financial agency
a written assurance, in a form and manner that the Director
of the financial agency shall prescribe, that the covered
person will ensure, to the maximum extent possible, the
advancement of minorities and women--
(A) in the workforce of the covered person; and
(B) as applicable, by any subcontractor of the covered
person.
(3) Referral system.--Each Director shall establish a
referral process by which the Director may refer a Federal
contractor or subcontractor to the Office of Federal Contract
Compliance Programs of the Department of Labor for further
investigation, and appropriate enforcement, under Executive
Order 11246 (42 U.S.C. 2000e note; relating to
nondiscrimination in employment by Government contractors and
subcontractors), or any successor thereto.
(4) Applicability.--This subsection shall apply to all
contracts of a financial agency for services of any kind,
including the services of investment banking, asset
management entities, broker-dealers, financial services
entities, underwriters, accountants, investment consultants,
and providers of legal services. Nothing in this subsection
may be construed to affect the responsibilities or authority
of the Office of Federal Contract Compliance Programs of the
Department of Labor or the responsibilities of Federal
contractors under Executive Order 11246 (42 U.S.C. 2000e
note; relating to nondiscrimination in employment by
Government contractors and subcontractors), or any successor
thereto.
(f) Reports.--Not later than 90 days before the end of each
fiscal year, the Director of each financial agency shall
submit to Congress a report that contains detailed
information describing the actions taken by the Director and
the financial agency under this section, including--
(1) a statement--
(A) of the total amount paid by the financial agency to
covered persons during--
(i) the period beginning on the date of the most recent
report submitted by the financial agency under this
subsection; or
(ii) in the case of the first report submitted under this
subsection, the first fiscal year following the date of
enactment of this Act; and
(B) that analyzes the amount described in subparagraph (A)
by the type of population involved, as determined by the
Director;
(2) the percentage of the amount described in paragraph (1)
that was paid to minority-owned businesses and women-owned
businesses, analyzed by the type of population involved, as
determined by the Director;
(3) the successes achieved and challenges faced by the
financial agency in operating outreach programs for
minorities and women;
(4) any challenges that the financial agency may face in
hiring and retaining qualified minority and women employees
and contracting with qualified minority-owned businesses and
women-owned businesses;
(5) the efforts that the financial agency has made to
ensure that the financial agency recruits diverse talent; and
(6) any other information, findings, conclusions, or
recommendations for legislative or financial agency action,
as the Director determines appropriate.
(g) Diversity in Financial Agency Workforce.--Each
financial agency shall take affirmative steps to seek
diversity in the workforce of the financial agency at all
levels of the financial agency, consistent with the
demographic diversity of the United States, including--
(1) targeted recruiting at historically Black colleges and
universities, Hispanic-serving institutions, women's
colleges, and colleges that typically serve majority minority
populations;
(2) sponsoring and recruiting at job fairs in urban
communities;
(3) placing employment advertisements in newspapers and
magazines oriented toward minorities and women;
(4) partnering with organizations that focus on developing
opportunities for minorities and women, to place talented
minorities and women in internships, summer employment, and
full-time positions with the financial agency;
(5) where feasible, partnering with inner-city high
schools, girls' high schools, and majority minority high
schools, to establish or enhance financial literacy programs
and provide mentoring;
(6) ensuring that women and minorities are included in the
recruitment process, as staff or in the interview phase of
the process; and
(7) using any other form of mass media communication that
the Director determines is necessary.
(h) Diversity Report Cards.--
(1) Reporting required.--The Commission, in consultation
with the Secretary of Labor and the Equal Employment
Opportunity Commission, shall, by rule, require each issuer
to disclose in the annual report of the issuer on Form 10-K
under the Securities Exchange Act of 1934 (15 U.S.C. 78a et
seq.), comparative percentage data, with separate categories
for race, ethnicity, and gender, concerning--
(A) the 200 most highly compensated officers, executives,
or employees of the issuer (excluding the members of the
board of directors of the issuer);
(B) the total compensation of the 200 most highly
compensated officers, executives, or employees of the issuer
(excluding the members of the board of directors of the
issuer);
(C) all employees of the issuer; and
(D) the total compensation of all employees of the issuer.
(2) Total compensation.--For purposes of this subsection,
total compensation shall be determined in accordance with
section 229.402(c)(2)(x) of title 17, Code of Federal
Regulations, as in effect on the day before the date of
enactment of this Act.

SEC. 344. PRESERVING AND EXPANDING MINORITY DEPOSITORY
INSTITUTIONS.

(a) In General.--Section 308(a) of the Financial
Institutions Reform, Recovery, and Enforcement Act of 1989
(12 U.S.C. 1463 note) is amended by striking ``Director of
the Office of Thrift Supervision'' and inserting ``, the
Chairman of the Board of Governors of the Federal Reserve
System,''
(b) Report.--Section 308 of the Financial Institutions
Reform, Recovery, and Enforcement Act of 1989 (12 U.S.C. 1463
note) is amended by adding at the end the following:
``(c) Reports.--The Secretary of the Treasury and the
Chairman of the Board of Governors of the Federal Reserve
System shall each submit an annual report to Congress
containing a description of actions taken to carry out this
section.''.
(c) Technical and Conforming Amendments.--Section 3(g) of
the Home Owners' Loan Act (12 U.S.C. 1462a(g)) is amended--
(1) in paragraph (1), by striking ``; and'' and inserting a
period;
(2) by striking ``include'' and all that follows through
``any changes'' and inserting ``include a description of any
changes''; and
(3) by striking paragraph (2).
______

SA 3877. Mr. MENENDEZ submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 372, between lines 2 and 3, insert the following:

SEC. 343. GUARANTEES FOR BONDS AND NOTES ISSUED FOR COMMUNITY
OR ECONOMIC DEVELOPMENT PURPOSES.

The Riegle Community Development and Regulatory Improvement
Act of 1994 (12 U.S.C. 4701 et seq.) is amended by inserting
after section 114 (12 U.S.C. 4713) the following:

``SEC. 114A. GUARANTEES FOR BONDS AND NOTES ISSUED FOR
COMMUNITY OR ECONOMIC DEVELOPMENT PURPOSES.

``(a) Definitions.--In this section, the following
definitions shall apply:
``(1) Director.--The term `Director' means the Director of
the Community Development Financial Institutions Fund.
``(2) Eligible community development financial
institution.--The term `eligible community development
financial institution' means a community development
financial institution (as described in section 1805.201 of
title 12, Code of Federal Regulations, or any successor
thereto) certified by the Secretary that has applied to a
qualified issuer for, or been granted by a qualified issuer,
a loan under the Program.
``(3) Eligible community or economic development purpose.--
The term `eligible community or economic development
purpose'--
``(A) means any purpose described in section 108(b); and
``(B) includes the provision of community or economic
development in low-income or underserved rural areas.
``(4) Guarantee.--The term `guarantee' means a written
agreement between the Secretary and a qualified issuer (or
trustee), pursuant to which the Secretary ensures repayment
of the verifiable losses of principal, interest, and call
premium, if any, on notes or bonds issued by a qualified
issuer to finance or refinance loans to eligible community
development financial institutions.
``(5) Loan.--The term `loan' means any credit instrument
that is extended under the Program for any eligible community
or economic development purpose.
``(6) Master servicer.--
``(A) In general.--The term `master servicer' means any
entity approved by the Secretary in accordance with
subparagraph (B) to oversee the activities of servicers, as
provided in subsection (f)(4).
``(B) Approval criteria for master servicers.--The
Secretary shall approve or deny any application to become a
master servicer under the Program not later than 30 days
after the date on which all required information is submitted
to the Secretary, based on the capacity and experience of the
applicant in--
``(i) loan administration, servicing, and loan monitoring;
``(ii) managing regional or national loan intake,
processing, or servicing operational systems and
infrastructure;
``(iii) managing regional or national originator
communication systems and infrastructure;

[[Page S3370]]

``(iv) developing and implementing training and other risk
management strategies on a regional or national basis; and
``(v) compliance monitoring, investor relations, and
reporting.
``(7) Program.--The term `Program' means the guarantee
Program for bonds and notes issued for eligible community or
economic development purposes established under this section.
``(8) Program administrator.--The term `Program
administrator' means an entity designated by the issuer to
perform administrative duties, as provided in subsection
(f)(2).
``(9) Qualified issuer.--
``(A) In general.--The term `qualified issuer' means a
community development financial institution (or any entity,
including a State or local government, designated to issue
notes or bonds on behalf of such community development
financial institution) that meets the qualification
requirements of this paragraph.
``(B) Approval criteria for qualified issuers.--
``(i) In general.--The Secretary shall approve a qualified
issuer for a guarantee under the Program in accordance with
the requirements of this paragraph, and such additional
requirements as the Secretary may establish, by regulation.
``(ii) Terms and qualifications.--A qualified issuer
shall--

``(I) have appropriate expertise, capacity, and experience,
or otherwise be qualified to make loans for eligible
community or economic development purposes;
``(II) provide to the Secretary--

``(aa) an acceptable statement of the proposed sources and
uses of the funds; and
``(bb) a capital distribution plan that meets the
requirements of subsection (c)(1); and

``(III) certify to the Secretary that the bonds or notes to
be guaranteed are to be used for eligible community or
economic development purposes.

``(C) Department opinion; timing.--
``(i) Department opinion.--Not later than 30 days after the
date of a request by a qualified issuer for approval of a
guarantee under the Program, the General Counsel of the Fund
shall provide to the Secretary an opinion regarding
compliance by the issuer with the requirements of the Program
under this section.
``(ii) Timing.--The Secretary shall approve or deny a
guarantee under this section after consideration of the
opinion provided to the Secretary under clause (i), and in no
case later than 45 days after receipt of all required
information by the Secretary with respect to a request for
such guarantee.
``(10) Secretary.--The term `Secretary' means the Secretary
of the Treasury.
``(11) Servicer.--The term `servicer' means an entity
designated by the issuer to perform various servicing duties,
as provided in subsection (f)(3).
``(b) Guarantees Authorized.--The Secretary shall guarantee
payments on bonds or notes issued by any qualified issuer if
the proceeds of the bonds or notes are used in accordance
with this section to make loans to eligible community
development financial institutions--
``(1) for eligible community or economic development
purposes; or
``(2) to refinance loans or notes issued for such purposes.
``(c) General Program Requirements.--
``(1) In general.--A capital distribution plan meets the
requirements of this subsection, if not less than 90 percent
of the principal amount of guaranteed bonds or notes (other
than costs of issuance fees) are used to make loans for any
eligible community or economic development purpose, measured
annually, beginning at the end of the 1-year period beginning
on the issuance date of such guaranteed bonds or notes.
``(2) Relending account.--Not more than 10 percent of the
principal amount of guaranteed bonds or notes, multiplied by
an amount equal to the outstanding principal balance of
issued notes or bonds, minus the risk-share pool amount under
subsection (d), may be held in a relending account and may be
made available for new eligible community or economic
development purposes.
``(3) Limitations on unpaid principal balances.--The
proceeds of guaranteed bonds or notes under the Program may
not be used to pay fees (other than costs of issuance fees),
and shall be held in--
``(A) community or economic development loans;
``(B) a relending account, to the extent authorized under
paragraph (2); or
``(C) a risk-share pool established under subsection (d).
``(4) Repayment.--If a qualified issuer fails to meet the
requirements of paragraph (1) by the end of the 90-day period
beginning at the end of the annual measurement period,
repayment shall be made on that portion of bonds or notes
necessary to bring the bonds or notes that remain outstanding
after such repayment into compliance with the 90 percent
requirement of paragraph (1).
``(5) Prohibited uses.--The Secretary shall, by
regulation--
``(A) prohibit, as appropriate, certain uses of amounts
from the guarantee of a bond or note under the Program,
including the use of such funds for political activities,
lobbying, outreach, counseling services, or travel expenses;
and
``(B) provide that the guarantee of a bond or note under
the Program may not be used for salaries or other
administrative costs of--
``(i) the qualified issuer; or
``(ii) any recipient of amounts from the guarantee of a
bond or note.
``(d) Risk-Share Pool.--Each qualified issuer shall, during
the term of a guarantee provided under the Program, establish
a risk-share pool, capitalized by contributions from eligible
community development financial institution participants an
amount equal to not less than 3 percent of the guaranteed
amount outstanding on the subject notes and bonds.
``(e) Guarantees.--
``(1) In general.--A guarantee issued under the Program
shall--
``(A) be for the full amount of a bond or note, including
the amount of principal, interest, and call premiums;
``(B) be fully assignable and transferable to the capital
market, on terms and conditions that are consistent with
comparable Government-guaranteed bonds, and satisfactory to
the Secretary;
``(C) represent the full faith and credit of the United
States; and
``(D) not exceed 30 years.
``(2) Limitations.--
``(A) Annual number of guarantees.--The Secretary shall
issue not more than 10 guarantees in any calendar year under
the Program.
``(B) Guarantee amount.--The Secretary may not guarantee
any amount under the Program equal to less than $100,000,000,
but the total of all such guarantees in any fiscal year may
not exceed $1,000,000,000.
``(f) Servicing of Transactions.--
``(1) In general.--To maximize efficiencies and minimize
cost and interest rates, loans made under this section may be
serviced by qualified Program administrators, bond servicers,
and a master servicer.
``(2) Duties of program administrator.--The duties of a
Program administrator shall include--
``(A) approving and qualifying eligible community
development financial institution applications for
participation in the Program;
``(B) compliance monitoring;
``(C) bond packaging in connection with the Program; and
``(D) all other duties and related services that are
customarily expected of a Program administrator.
``(3) Duties of servicer.--The duties of a servicer shall
include--
``(A) billing and collecting loan payments;
``(B) initiating collection activities on past-due loans;
``(C) transferring loan payments to the master servicing
accounts;
``(D) loan administration and servicing;
``(E) systematic and timely reporting of loan performance
through remittance and servicing reports;
``(F) proper measurement of annual outstanding loan
requirements; and
``(G) all other duties and related services that are
customarily expected of servicers.
``(4) Duties of master servicer.--The duties of a master
servicer shall include--
``(A) tracking the movement of funds between the accounts
of the master servicer and any other servicer;
``(B) ensuring orderly receipt of the monthly remittance
and servicing reports of the servicer;
``(C) monitoring the collection comments and foreclosure
actions;
``(D) aggregating the reporting and distribution of funds
to trustees and investors;
``(E) removing and replacing a servicer, as necessary;
``(F) loan administration and servicing;
``(G) systematic and timely reporting of loan performance
compiled from all bond servicers' reports;
``(H) proper distribution of funds to investors; and
``(I) all other duties and related services that are
customarily expected of a master servicer.
``(g) Fees.--
``(1) In general.--A qualified issuer that receives a
guarantee issued under this section on a bond or note shall
pay a fee to the Director, in an amount equal to 10 basis
points of the amount of the unpaid principal of the bond or
note guaranteed.
``(2) Payment.--A qualified issuer shall pay the fee
required under this subsection on an annual basis.
``(h) Authorization of Appropriations.--
``(1) In general.--There are authorized to be appropriated
to the Secretary, such sums as are necessary to carry out
this section.
``(2) Use of fees.--To the extent that the amount of funds
appropriated for a fiscal year under paragraph (1) are not
sufficient to carry out this section, the Director may use
the fees collected under subsection (g) for the cost of
providing guarantees of bonds and notes under this section.
``(i) Investment in Guaranteed Bonds Ineligible for
Community Reinvestment Act Purposes.--Notwithstanding any
other provision of law, any investment by a financial
institution in bonds or notes guaranteed under the Program
shall not be taken into account in assessing the record of
such institution for purposes of the Community Reinvestment
Act of 1977 (12 U.S.C. 2901).
``(j) Administration.--
``(1) Regulations.--Not later than 180 days after the date
of enactment of this section, the Secretary shall promulgate
regulations to carry out this section.

[[Page S3371]]

``(2) Implementation.--Not later than 240 days after the
date of enactment of this section, the Secretary shall
implement this section.
``(k) Termination.--This section is repealed, and the
authority provided under this section shall terminate, on
September 30, 2014.''.

SEC. 344. QUALIFIED COMMUNITY DEVELOPMENT FINANCIAL
INSTITUTION BONDS.

(a) Qualified Community Development Financial Institution
Bonds Treated as State and Local Bonds.--Section 150 of the
Internal Revenue Code of 1986 is amended by adding at the end
the following new subsection:
``(f) Qualified Community Development Financial Institution
Bonds.--For purposes of this part and section 103--
``(1) In general.--A qualified community development
financial institution bond shall be treated as a bond of a
political subdivision of a State.
``(2) Qualified community development financial institution
bond.--The term `qualified community development financial
institution bond' means any bond--
``(A) issued by a qualified community development financial
institution (or on behalf of such an institution by a State
or local government),
``(B) designated as a qualified community development
financial institution bond for purposes of this subsection,
and
``(C) issued as part of an issue 95 percent or more of the
net proceeds of which are to be used for an eligible
community or economic development purpose (as defined in
section 114A of the Community Development Banking and
Financial Institutions Act).
``(3) Qualified community development financial
institution.--The term `qualified community development
financial institution' means any organization--
``(A) which is described in section 501(c)(3) and exempt
from tax under section 501(a), and
``(B) which is a qualified issuer as defined in section
114A of the Community Development Banking and Financial
Institutions Act of 1994, or would be a qualified issuer but
for its designation of a State or local government to issue
bonds on its behalf.
``(4) Limitation on amount of bonds designated.--
``(A) In general.--The maximum aggregate face amount of
bonds which may be designated under paragraph (2)(B) by any
issuer shall not exceed the limitation amount allocated to
such issuer under subparagraph (C).
``(B) National limitation.--There is a national qualified
community development financial institution bond limitation
of $500,000,000.
``(C) Allocation of national limitation.--The national
qualified community development financial institution bond
limitation shall be allocated by the Secretary to qualified
issuers receiving guarantees under section 114A of the
Community Development Banking and Financial Institutions Act
of 1994.
``(5) Bonds not treated as private activity bonds.--Bonds
which are part of an issue which meets the requirements of
paragraph (2) shall not be treated as private activity
bonds.''.
(b) No Federal Guarantee.--Subparagraph (A) of section
149(b)(3) of the Internal Revenue Code of 1986 is amended--
(1) by striking ``or'' at the end of clause (iii);
(2) by striking the period at the end of clause (iv) and
inserting ``, or''; and
(3) by adding at the end the following new clause:
``(v) any guarantee of a qualified community development
financial institution bond provided by the Community
Development Financial Institution Fund.''.
(c) Effective Date.--The amendments made by this section
shall apply to bonds issued after the date of enactment of
this Act.
______

SA 3878. Mr. CASEY (for himself, Mr. Brown of Ohio, and Mr. Harkin)
submitted an amendment intended to be proposed to amendment SA 3739
proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to
the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail,'' to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 1044, between lines 2 and 3, insert the following:

SEC. 9__. STUDY ON TRANSACTION FEE.

(a) In General.--The Securities and Exchange Commission and
the Commodity Futures Trading Commission, in coordination
with the Department of the Treasury, shall conduct a study on
the implementation of a transaction fee on all security-based
transactions, including swap and security-based swap
transactions (except those transactions that are primarily
for the purpose of hedging or mitigating risk), stock, debt
instruments, and any other security that the heads of the
Federal agencies described in this subsection determine to be
appropriate to be included in the study.
(b) Purpose.--The purpose of the study shall be to assess--
(1) past experiences with transaction fees, with an
emphasis on fee avoidance or behavior modification, migration
of capital, and impact on individual investors and small and
medium-sized businesses;
(2) the advantages and disadvantages of the implementation
of the transaction fee in the United States alone, as
compared to the introduction of the fee on a global basis;
(3) the potential to generate sufficient revenue to reduce
the deficit, fund job creation, and meet the humanitarian and
global development obligations of the United States;
(4) how a transaction fee needs to be designed in order to
mitigate any negative side effects that may result from the
indirect assessment on the raising of capital;
(5) the impact, if any, a transaction fee would have on the
practice of day trading;
(6) to what extent a financial transaction fee would
contribute to the stabilization of the financial markets in
terms of the effect of the fee on speculation and on
transparency;
(7) whether a transaction fee would prevent a future
financial crisis by targeting certain types of risky
transactions (which transactions shall be determined by the
agencies conducting the study);
(8) the different transaction fee options, with a
particular focus on--
(A) the financial transactions tax and financial activities
tax, as described in the report entitled ``International
Monetary Fund Report: A Fair and Substantial Contribution by
the Financial Sector''; and
(B) implementing the transaction fee on individuals earning
more than $250,000 and corporations;
(9) whether the transaction fee would assist in building
healthy capital, ensuring the ability of the banking system
to finance real economy investments; and
(10) whether excessive risk-taking is or would be prevented
through implementation of a transaction fee.
(c) Public Participation.--The study described in
subsection (a) shall be carried out in a manner to provide to
the public an adequate period of time to provide comments on
the implementation of a transaction fee.
(d) Report.--Not later than 90 days after the date of
enactment of this Act, the Securities and Exchange Commission
and the Commodity Futures Trading Commission, in coordination
with the Department of the Treasury, shall submit to Congress
a report that describes the results of the study.
______

SA 3879. Ms. COLLINS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail,'' to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

At the appropriate place in title I, insert the following:

SEC. __. LEVERAGE AND RISK-BASED CAPITAL REQUIREMENTS.

(a) Definitions.--
(1) Generally applicable leverage capital requirements.--
The term ``generally applicable leverage capital
requirements'' means--
(A) the minimum ratios of tier 1 capital to average total
assets, as established by the appropriate Federal banking
agencies to apply to insured depository institutions under
the prompt corrective action regulations implementing section
38 of the Federal Deposit Insurance Act, regardless of total
consolidated asset size or foreign financial exposure; and
(B) includes the regulatory capital components in the
numerator of that capital requirement, average total assets
in the denominator of that capital requirement, and the
required ratio of the numerator to the denominator.
(2) Generally applicable risk-based capital requirements.--
The term ``generally applicable risk-based capital
requirements'' means--
(A) the risk-based capital requirements as established by
the appropriate Federal banking agencies to apply to insured
depository institutions under the agency's Prompt Corrective
Action regulations that implement section 38 of the Federal
Deposit Insurance Act, regardless of total consolidated asset
size or foreign financial exposure; and
(B) includes the regulatory capital components in the
numerator of those capital requirements, the risk-weighted
assets in the denominator of those capital requirements, and
the required ratio of the numerator to the denominator.
(b) Minimum Capital Requirements.--
(1) Minimum leverage capital requirements.--The appropriate
Federal banking agencies shall establish minimum leverage
capital requirements on a consolidated basis for insured
depository institutions, depository institution holding
companies, and nonbank financial companies identified under
section 113. The minimum leverage capital requirements
established under this paragraph shall not be less than the
generally applicable leverage capital requirements, which
shall serve as a floor for any

[[Page S3372]]

capital requirements the agency may require, nor
quantitatively lower than the generally applicable leverage
capital requirements that were in effect for insured
depository institutions as of the date of enactment of this
Act.
(2) Minimum risk-based capital requirements.--The
appropriate Federal banking agencies shall establish minimum
risk-based capital requirements on a consolidated basis for
insured depository institutions, depository institution
holding companies, and nonbank financial companies identified
under section 113. The minimum risk-based capital
requirements established under this paragraph shall not be
less than the generally applicable risk-based capital
requirements, which shall serve as a floor for any capital
requirements the agency may require, nor quantitatively lower
than the generally applicable risk-based capital requirements
that were in effect for insured depository institutions as of
the date of enactment of this Act.
(3) Capital requirements to address activities that pose
risks to the financial system.--
(A) In general.--Subject to the recommendations of the
Council, in accordance with section 120, the Federal banking
agencies shall develop capital requirements applicable to all
institutions covered by this section that address the risks
that the activities of such institutions pose, not only to
the institution engaging in the activity, but to other public
and private stakeholders in the event of adverse performance,
disruption, or failure of the institution or the activity.
(B) Content.--Such rules shall address, at a minimum, the
risks arising from--
(i) significant volumes of activity in derivatives,
securitized products purchased and sold, financial guarantees
purchased and sold, securities borrowing and lending, and
repurchase agreements and reverse repurchase agreements;
(ii) concentrations in assets for which the values
presented in financial reports are based on models rather
than historical cost or prices deriving from deep and liquid
2-way markets; and
(iii) concentrations in market share for any activity that
would substantially disrupt financial markets if the
institution is forced to unexpectedly cease the activity.
______

SA 3880. Mr. BYRD (for himself and Mr. Rockefeller) submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

At the end of subtitle A of title IX, add the following:

SEC. 919C. PENALTIES FOR FAILURE TO DISCLOSE HEALTH AND
SAFETY LITIGATION, VIOLATIONS, AND IMPACT
INFORMATION.

The Securities Exchange Act of 1934 (15 U.S.C. 78a et seq.)
is amended by inserting after section 21A the following new
section:

``SEC. 21B. HEALTH AND SAFETY DISCLOSURE VIOLATIONS.

``(a) Findings.--Congress finds the following:
``(1) This Act requires issuers of securities to disclose
material facts regarding--
``(A) pending litigation;
``(B) unsafe or unhealthy conditions in a high-risk
workplace that may reasonably be expected to cause the issuer
to face costly wrongful death actions from the heirs of the
deceased;
``(C) unsafe or unhealthy conditions in a high-risk
workplace, or significant violations of law in such a
workplace, that may reasonably be expected to cause reported
financial information not to be necessarily indicative of
future financial conditions or future operating results; and
``(D) events, trends, or uncertainties that may change the
relationship between costs and revenues.
``(2) In numerous industries, including high-risk
industries such as coal mining and oil exploration, health
and safety conditions have long been incompletely and
inconsistently disclosed, discussed, or analyzed by
corporations.
``(3) Investors and the public have a right to know, and a
reasonable expectation to remained informed, about
significant safety and health conditions that could imperil
the workforce of publicly-traded corporations, carrying
odious consequences for workers, families, and communities,
and that can lead to the abrogation of contracts,
environmental or other tort liabilities, and tarnished
corporate reputations.
``(b) Purpose.--The purpose of this section is to
strengthen the maintenance of fair and honest markets by
requiring disclosure of certain health and safety information
and by authorizing elevated penalties for failures to
disclose certain categories of information regarding health
and safety conditions or violations, given that such failures
have too often heretofore been unaddressed.
``(c) Judicial Actions Authorized.--
``(1) Relief and penalties.--Whenever it shall appear that
any issuer has violated subsection (d), the Commission or any
shareholder of the issuer may bring an action in a United
States district court to seek, and the court shall have
jurisdiction to impose--
``(A) equitable relief for the complainant, to be provided
by the issuer; and
``(B) a civil penalty to be paid by the senior executive
officers or the members of the board of directors of the
subject issuer--
``(i) who knew about such violation; or
``(ii) whose duties and decisions affected matters
regarding production or safety and who therefore had reason
to know about such violation, barring malfeasance by other
directors, officers, employees, or agents of the subject
issuer.
``(2) Costs.--Whenever a court issues an order sustaining a
shareholder's charges under paragraph (1), a sum equal to the
aggregate amount of all costs and expenses (including
attorney's fees) that have been reasonably incurred by the
shareholder for, or in connection with, the institution and
prosecution of such proceedings, as determined by the court,
shall be assessed against the issuer. These costs shall be
assessed regardless of the amount or means of relief or
penalties imposed on the issuer or its directors, officers,
employees, or agents.
``(d) Health and Safety-Related Disclosure.--
``(1) Duty to disclose.--At least annually, an issuer shall
disclose to the Commission and the shareholders the
information required under paragraph (2).
``(2) Required disclosures.--The disclosures required under
this paragraph are the following:
``(A) Any pending litigation concerning a health or safety
condition or violation under Federal or State law involving
the issuer, other than ordinary, routine litigation that is
incidental to the business of the issuer, as determined by
the Commission in consultation with the Secretary of Labor.
``(B) Any significant health or safety condition, or
significant health or safety violation, at any business unit
of the issuer in which routine activities pose risk of loss
of life.
``(C) Any significant health or safety condition, or
significant health or safety violation, at any business unit
of the issuer in which routine activities pose risk of
accidents or fatalities, injuries, or illnesses, the
occurrence of which could cause reported financial
information not to be necessarily indicative of future
financial conditions of the issuer, or which could cause a
negative effect on operating results of the issuer or any
subsidiaries thereof.
``(D) Any trend in health or safety conditions or
violations under Federal law, at any business unit of the
issuer, that may change the relationship between costs and
revenues of the issuer or any subsidiaries thereof.
``(e) Means and Amount of Equitable Relief, Damages, and
Penalties.--
``(1) Means and amount of equitable relief and damages.--
The court shall determine the means of equitable relief for a
violation of subsection (d), which may include the immediate
disclosure of significant health or safety conditions or
significant health or safety violations. If the court
determines that a shareholder has sustained damages, the
court may assess the damages against the issuer.
``(2) Amount of civil penalty.--
``(A) Judicial determination.--The court shall determine
the civil penalty for a violation of subsection (d) in light
of the facts and circumstances.
``(B) Amount of penalty.--Unless determined otherwise in
accordance with subparagraph (A), the civil penalty for a
violation of subsection (d) shall be equal to not less than 3
times the amount that may be imposed under other State or
Federal law in connection with the underlying safety or
health conditions or violations that are required to be
disclosed under this title.
``(3) Private actions.--If a person other than the United
States prevails on a claim alleging a violation of subsection
(d), the person shall be entitled to recover 3 times the
amount of damages sustained by the person, as determined by
the court, in light of the facts and circumstances.
``(f) Procedures for Collection.--
``(1) Payment of penalty to treasury.--A civil penalty
imposed under this section shall be payable into the Treasury
of the United States.
``(2) Collection of penalties.--If a person upon whom a
civil penalty under this section is imposed fails to pay such
penalty within the time prescribed in the order of the court,
the Commission may refer the matter to the Attorney General
of the United States, who shall recover such penalty by
action in the appropriate United States district court.
``(3) Remedy not exclusive.--An action authorized by this
section may be brought in addition to any other actions that
the Commission, the Attorney General, or any shareholder is
entitled to bring.
``(4) Jurisdiction and venue.--For purposes of section 27,
an action under this section shall be an action to enforce a
liability or a duty created by this title.
``(g) Definitions.--
``(1) In general.--The Commission, in consultation with the
Secretary of Labor, shall issue rules to define the terms
used in this section for which the Commission determines a
definition to be necessary.
``(2) Definitions.--In this section:
``(A) Pending litigation.--The term `pending litigation'
includes a civil action or administrative proceeding for a
penalty for

[[Page S3373]]

violating a Federal or State health and safety law that--
``(i) is being contested before an administrative law judge
under the Occupational Safety and Health Review Commission or
the Federal Mine Safety and Health Review Commission; or
``(ii) is being otherwise contested or appealed under a
State review board or other body.
``(B) Significant health or safety condition.--The term
`significant health or safety condition' means a condition
that a certified worker or manager could identify as
reasonably likely to be cited, were the condition to be
observed by a Federal inspector, as--
``(i) a significant and substantial health or safety
violation under the Federal Mine Safety and Health Act of
1977 (30 U.S.C. 801 et seq.);
``(ii) a serious or repeated violation under the
Occupational Safety and Health Act of 1970 (29 U.S.C. 651 et
seq.); or
``(iii) another health- or safety-related violation
carrying a high degree of gravity under Federal law.
``(C) Significant health or safety violation.--The term
`significant health or safety violation' means--
``(i) a significant and substantial health or safety
violation under the Federal Mine Safety and Health Act of
1977;
``(ii) a serious or repeated violation under the
Occupational Safety and Health Act of 1970; or
``(iii) another health- or safety-related violation
carrying a high degree of gravity under State or Federal
law.''.
______

SA 3881. Mr. BROWN of Massachusetts submitted an amendment intended
to be proposed to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd
(for himself and Mrs. Lincoln)) to the bill S. 3217, to promote the
financial stability of the United States by improving accountability
and transparency in the financial system, to end ``too big to fail'',
to protect the American taxpayer by ending bailouts, to protect
consumers from abusive financial services practices, and for other
purposes; which was ordered to lie on the table; as follows:

On page 1062, after line 25, insert the following:
(e) Office of Service Member Affairs.--
(1) Establishment.--The Director shall establish within the
Bureau the Office of Service Member Affairs.
(2) Functions.--The Office of Service Member Affairs shall
have such powers and duties as the Director may delegate to
that Office, with respect to the drafting and enforcement of
any special consumer financial protection rules that apply to
members of the Armed Forces.
(3) Administration of office.--There is established the
position of Assistant Director of the Bureau for Service
Member Affairs, who--
(A) shall be appointed by the Director; and
(B) shall carry out such duties as the Director may
delegate to such Assistant Director.
(4) Definition.--As used in this subsection, the term
``member of the Armed Forces'' means any member of the United
States Armed Forces and any member of the National Guard or
Reserves.
______

SA 3882. Mr. CORKER (for himself, Mr. Gregg, Mr. Shelby, Mrs.
Hutchison, Mr. LeMieux, and Mr. Coburn) submitted an amendment intended
to be proposed to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd
(for himself and Mrs. Lincoln)) to the bill S. 3217, to promote the
financial stability of the United States by improving accountability
and transparency in the financial system, to end ``too big to fail'',
to protect the American taxpayer by ending bailouts, to protect
consumers from abusive financial services practices, and for other
purposes; which was ordered to lie on the table; as follows:

On page 1045, strike line 12 and all that follows through
``SEC. 942.'' on page 1052, line 3, and insert the following:
(b) Study on Risk Retention.--
(1) Study.--
(A) In general.--The Board of Governors, in coordination
and consultation with the Comptroller of the Currency, the
Corporation, the Federal Housing Finance Agency, and the
Commission, shall conduct a study of the asset-backed
securitization process.
(B) Issues to be studied.--In conducting the study under
subparagraph (A), the Board of Governors shall evaluate--
(i) the separate and combined impact of--

(I) requiring loan originators or securitizers to retain an
economic interest in a portion of the credit risk for any
asset that the securitizer, through the issuance of an asset-
backed security, transfers, sells, or conveys to a third
party; including--

(aa) whether existing risk retention requirements such as
contractual representations and warranties, and statutory and
regulatory underwriting and consumer protection requirements
are sufficient to ensure the long-term accountability of
originators for loans they originate; and
(bb) methodologies for establishing additional statutory
credit risk retention requirements;

(II) the Financial Accounting Statements 166 and 167 issued
by the Financial Accounting Standards Board, as well as any
other statements issued before or after the date of enactment
of this section the Federal banking agencies determine to be
relevant;

(ii) the impact of the factors described under subsection
(i) of this section on--

(I) different classes of assets, such as residential
mortgages, commercial mortgages, commercial loans, auto
loans, and other classes of assets;
(II) loan originators;
(III) securitizers;
(IV) access of consumers and businesses to credit on
reasonable terms.

(2) Report.--Not later than 18 months after the date of
enactment of this section, the Board of Governors shall
submit to Congress a report on the study conducted under
paragraph (1). Such report shall include statutory and
regulatory recommendations for eliminating any negative
impacts on the continued viability of the asset-backed
securitization markets and on the availability of credit for
new lending identified by the study conducted under paragraph
(1).

SEC. 942. RESIDENTIAL MORTGAGE UNDERWRITING STANDARDS.

(a) Standards Established.--Notwithstanding any other
provision of this Act or any other provision of Federal,
State, or local law, the Federal banking agencies, in
consultation with the Federal Housing Finance Agency and the
Department of Housing and Urban Development, shall jointly
establish specific minimum standards for mortgage
underwriting, including--
(1) a requirement that the mortgagee verify and document
the income and assets relied upon to qualify the mortgagor on
the residential mortgage, including the previous employment
and credit history of the mortgagor;
(2) a down payment requirement that--
(A) is equal to not less than 5 percent of the purchase
price of the property securing the residential mortgage; and
(B) in the case of a first lien residential mortgage loan
with an initial loan to value ratio that is more than 80
percent and not more than 95 percent, includes a requirement
for credit enhancements, as defined by the Federal banking
agencies, until the loan to value ratio of the residential
mortgage loan amortizes to a value that is less than 80
percent of the purchase price;
(3) a method for determining the ability of the mortgagor
to repay the residential mortgage that is based on factors
including--
(A) all terms of the residential mortgage, including
principal payments that fully amortize the balance of the
residential mortgage over the term of the residential
mortgage; and
(B) the debt to income ratio of the mortgagor; and
(4) any other specific standards the Federal banking
agencies jointly determine are appropriate to ensure prudent
underwriting of residential mortgages.
(b) Updates to Standards.--The Federal banking agencies, in
consultation with the Federal Housing Finance Agency and the
Department of Housing and Urban Development--
(1) shall review the standards established under this
section not less frequently than every 5 years; and
(2) based on the review under paragraph (1), may revise the
standards established under this section, as the Federal
banking agencies, in consultation with the Federal Housing
Finance Agency and the Department of Housing and Urban
Development, determine to be necessary.
(c) Compliance.--It shall be a violation of Federal law--
(1) for any mortgage loan originator to fail to comply with
the minimum standards for mortgage underwriting established
under subsection (a) in originating a residential mortgage
loan;
(2) for any company to maintain an extension of credit on a
revolving basis to any person to fund a residential mortgage
loan, unless the company reasonably determines that the
residential mortgage loan funded by such credit was subject
to underwriting standards no less stringent than the minimum
standards for mortgage underwriting established under
subsection (a); or
(3) for any company to purchase, fund by assignment, or
guarantee a residential mortgage loan, unless the company
reasonably determines that the residential mortgage loan was
subject to underwriting standards no less stringent than the
minimum standards for mortgage underwriting established under
subsection (a).
(d) Implementation.--
(1) Regulations required.--The Federal banking agencies, in
consultation with the Federal Housing Finance Agency, shall
issue regulations to implement subsections (a) and (c), which
shall take effect not later than 270 days after the date of
enactment of this Act.
(2) Report required.--If the Federal banking agencies have
not issued final regulations under subsections (a) and (c)
before the date that is 270 days after the date of enactment
of this Act, the Federal banking agencies shall jointly
submit to the Committee on Banking, Housing, and Urban
Affairs of the Senate and the Committee on Financial Services
of the House of Representatives a report that--
(A) explains why final regulations have not been issued
under subsections (a) and (c); and

[[Page S3374]]

(B) provides a timeline for the issuance of final
regulations under subsections (a) and (c).
(e) Enforcement.--Compliance with the rules issued under
this section shall be enforced by--
(1) the primary financial regulatory agency of an entity,
with respect to an entity subject to the jurisdiction of a
primary financial regulatory agency, in accordance with the
statutes governing the jurisdiction of the primary financial
regulatory agency over the entity and as if the action of the
primary financial regulatory agency were taken under such
statutes; and
(2) the Bureau, with respect to a company that is not
subject to the jurisdiction of a primary financial regulatory
agency.
(f) Rule of Construction.--Nothing in this section may be
construed to permit the Federal National Mortgage Association
or the Federal Home Loan Mortgage Corporation to make or
guarantee a residential mortgage loan that does not meet the
minimum underwriting standards established under this
section.
(g) Definitions.--In this section, the following
definitions shall apply:
(1) Company.--The term ``company''--
(A) has the same meaning as in section 2(b) of the Bank
Holding Company Act of 1956 (12 U.S.C. 1841(b)); and
(B) includes a sole proprietorship.
(2) Mortgage loan originator.--The term ``mortgage loan
originator'' means any company that takes residential
mortgage loan applications and offers or negotiates terms of
residential mortgage loans.
(3) Residential mortgage loan.--The term ``residential
mortgage loan''--
(A) means any extension of credit primarily for personal,
family, or household use that is secured by a mortgage, deed
of trust, or other equivalent security interest in a dwelling
or residential real estate upon which is constructed or
intended to be constructed a dwelling; and
(B) does not include a mortgage loan for which mortgage
insurance is provided by the Department of Veterans Affairs.
(4) Extension of credit; dwelling.--The terms ``extension
of credit'' and ``dwelling'' shall have the same meaning as
in section 103 of the Truth in Lending Act (15 U.S.C. 1602).

SEC. 943.

______

SA 3883. Ms. SNOW (for herself and Mr. Pryor), submitted an amendment
intended to be proposed to amendment SA 3739 proposed by Mr. Reid (for
Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217, to
promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. SMALL BUSINESS FAIRNESS AND REGULATORY TRANSPARENCY.

(a) Panel Requirement.--Section 609(d) of title 5, United
States Code, is amended by striking ``means the'' and all
that follows and inserting the following: ``means--
``(1) the Environmental Protection Agency;
``(2) the Consumer Financial Protection Bureau of the
Federal Reserve System; and
``(3) the Occupational Safety and Health Administration of
the Department of Labor.''.
(b) Initial Regulatory Flexibility Analysis.--Section 603
of title 5, United States Code, is amended by adding at the
end the following:
``(d)(1) For a covered agency, as defined in section
609(d)(2), each initial regulatory flexibility analysis shall
include a description of--
``(A) any projected increase in the cost of credit for
small entities;
``(B) any significant alternatives to the proposed rule
which accomplish the stated objectives of applicable statutes
and which minimize any increase in the cost of credit for
small entities; and
``(C) advice and recommendations of representatives of
small entities relating to issues described in subparagraphs
(A) and (B) and subsection (b).
``(2) A covered agency, as defined in section 609(d)(2),
shall, for purposes of complying with paragraph (1)(C)--
``(A) identify representatives of small entities in
consultation with the Chief Counsel for Advocacy of the Small
Business Administration; and
``(B) collect advice and recommendations from the
representatives identified under subparagraph (A) relating to
issues described in subparagraphs (A) and (B) of paragraph
(1) and subsection (b).''.
(c) Final Regulatory Flexibility Analysis.--Section 604(a)
of title 5, United States Code, is amended--
(1) in paragraph (4), by striking ``and'' at the end;
(2) in paragraph (5), by striking the period at the end and
inserting ``; and''; and
(3) by adding at the end the following:
``(6) for a covered agency, as defined in section
609(d)(2), a description of the steps the agency has taken to
minimize any additional cost of credit for small entities.''.
______

SA 3884. Ms. CANTWELL (for herself, Mr. McCain, Mr. Kaufman, Mr.
Harkin, Mr. Feingold, and Mr. Sanders) submitted an amendment intended
to be proposed to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd
(for himself and Mrs. Lincoln)) to the bill S. 3217, to promote the
financial stability of the United States by improving accountability
and transparency in the financial system, to end ``too big to fail'',
to protect the American taxpayer by ending bailouts, to protect
consumers from abusive financial services practices, and for other
purposes; which was ordered to lie on the table; as follows:

At the end of subtitle C of title I, add the following:

SEC. 171. LIMITATIONS ON BANK AFFILIATIONS.

(a) Limitation on Affiliation.--The Banking Act of 1933 (12
U.S.C. 221a et seq.) is amended by inserting before section
21 the following:
``Sec. 20.  Beginning 1 year after the date of enactment of
the Restoring American Financial Stability Act of 2010, no
member bank may be affiliated, in any manner described in
section 2(b), with any corporation, association, business
trust, or other similar organization that is engaged
principally in the issue, flotation, underwriting, public
sale, or distribution at wholesale or retail or through
syndicate participation stocks, bonds, debenture, notes, or
other securities, except that nothing in this section shall
apply to any such organization which shall have been placed
in formal liquidation and which shall transact no business,
except such as may be incidental to the liquidation of its
affairs.''.
(b) Limitation on Compensation.--The Banking Act of 1933
(12 U.S.C. 221 et seq.) is amended by inserting after section
31 the following:
``Sec. 32.  Beginning 1 year after the date of enactment of
the Restoring American Financial Stability Act of 2010, no
officer, director, or employee of any corporation or
unincorporated association, no partner or employee of any
partnership, and no individual, primarily engaged in the
issue, flotation, underwriting, public sale, or distribution,
at wholesale or retail, or through syndicate participation,
of stocks, bonds, or other similar securities, shall serve
simultaneously as an officer, director, or employee of any
member bank, except in limited classes of cases in which the
Board of Governors of the Federal Reserve System may allow
such service by general regulations when, in the judgment of
the Board of Governors, it would not unduly influence the
investment policies of such member bank or the advice given
to customers by the member bank regarding investments.''.
(c) Prohibiting Depository Institutions From Engaging in
Insurance-Related Activities.--
(1) In general.--Beginning 1 year after the date of
enactment of this Act, and notwithstanding any other
provision of law, in no case may a depository institution
engage in the business of insurance or any insurance-related
activity.
(2) Definition.--As used in this section, the term
``business of insurance'' means the writing of insurance or
the reinsuring of risks by an insurer, including all acts
necessary to such writing or reinsuring and the activities
relating to the writing of insurance or the reinsuring of
risks conducted by persons who act as, or are, officers,
directors, agents, or employees of insurers or who are other
persons authorized to act on behalf of such persons.
______

SA 3885. Mrs. HUTCHISON submitted an amendment intended to be
proposed to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for
himself and Mrs. Lincoln)) to the bill S. 3217, to promote the
financial stability of the United States by improving accountability
and transparency in the financial system, to end ``too big to fail'',
to protect the American taxpayer by ending bailouts, to protect
consumers from abusive financial services practices, and for other
purposes; which was ordered to lie on the table; as follows:

On page 370, strike lines 11 through 13 and insert the
following:
(b) Effective Date.--This section, and the amendments made
by this section, shall take effect on the transfer date.

SEC. 333. STUDY ON THE IMPACT OF EXCLUDING CORE DEPOSITS FROM
TREATMENT AS BROKERED DEPOSITS.

(a) Study.--The Board of Governors shall conduct a study to
evaluate--
(1) the treatment of core deposits as brokered deposits for
the purpose of calculating the insurance premiums of banks;
(2) the potential impact on the Deposit Insurance Fund of
ceasing to treat core deposits as brokered deposits;
(3) an assessment of the merits and drawbacks of the
treatment of core deposits as brokered deposits, with respect
to the economy and banking sector of the United States;
(4) the potential stimulative effect on local economies of
excluding core deposits from treatment as brokered deposits;
and
(5) the competitive parity between large institutions and
community banks that

[[Page S3375]]

could result from excluding core deposits from treatment as
brokered deposits.
(b) Report to Congress.--Not later than 1 year after the
date of enactment of this Act, the Board of Governors shall
submit to the Committee on Banking, Housing, and Urban
Affairs of the Senate and the Committee on Financial Services
of the House of Representatives a report on the results of
the study under subsection (a) that includes legislative
recommendations, if any, to address competitive imbalances as
a result of the treatment of core deposits as brokered
deposits.
______

SA 3886. Mr. ROCKEFELLER (for himself and Mr. Byrd) submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

At the end of subtitle A of title IX, add the following:

SEC. 919C. REPORTING REQUIREMENTS REGARDING COAL OR OTHER
MINE SAFETY.

(a) Reporting Mine Safety Information.--Each issuer that is
required to file reports pursuant to section 13(a) or 15(d)
of the Securities Exchange Act of 1934 (15 U.S.C. 78m, 78o)
and that is an operator, or that has a subsidiary that is an
operator, of a coal or other mine shall include, in each
periodic report filed with the Commission under the
securities laws on or after the date of enactment of this
Act, the following information for the time period covered by
such report:
(1) For each coal or other mine of which the issuer or a
subsidiary of the issuer is an operator--
(A) the total number of violations of mandatory health or
safety standards that could significantly and substantially
contribute to the cause and effect of a coal or other mine
safety or health hazard under section 104 of the Federal Mine
Safety and Health Act of 1977 (30 U.S.C. 814) for which the
operator received a citation from the Mine Safety and Health
Administration;
(B) the total number of orders issued under section 104(b)
of such Act (30 U.S.C. 814(b));
(C) the total number of citations and orders for
unwarrantable failure of the mine operator to comply with
mandatory health or safety standards under section 104(d) of
such Act (30 U.S.C. 814(d));
(D) the total number of flagrant violations under section
110(b) of such Act (30 U.S.C. 820(b));
(E) the total number of imminent danger orders issued under
section 107(a) of such Act (30 U.S.C. 817(a)); and
(F) the total dollar value of proposed assessments from the
Mine Safety and Health Administration under such Act (30
U.S.C. 801 et seq.).
(2) A list of such coal or other mines that receive written
notice from the Mine Safety and Health Administration of--
(A) a pattern of violations of mandatory health or safety
standards that are of such nature as could have significantly
and substantially contributed to the cause and effect of coal
or other mine health or safety hazards under section 104(e)
of such Act (30 U.S.C. 814(e)); or
(B) the potential to have such a pattern.
(3) Any pending legal action before the Federal Mine Safety
and Health Review Commission involving such coal or other
mine.
(b) Reporting Shutdowns and Patterns of Violations.--
Beginning on and after the date of enactment of this Act,
each issuer that is an operator, or that has a subsidiary
that is an operator, of a coal or other mine shall file a
current report on Form 8-K (or any successor form), as
required by the Commission, disclosing the following
regarding each coal or other mine of which the issuer or
subsidiary is an operator:
(1) The receipt of an imminent danger order issued under
section 107(a) of the Federal Mine Safety and Health Act of
1977 (30 U.S.C. 817(a)).
(2) The receipt of written notice from the Mine Safety and
Health Administration that the coal or other mine has--
(A) a pattern of violations of mandatory health or safety
standards that are of such nature as could have significantly
and substantially contributed to the cause and effect of coal
or other mine health or safety hazards under section 104(e)
of such Act (30 U.S.C. 814(e)); or
(B) the potential to have such a pattern.
(c) Rule of Construction.--Nothing in this section shall be
construed to affect any obligation of a person to make a
disclosure under any other applicable law in effect before,
on, or after the date of enactment of this Act.
(d) Commission Authority.--
(1) Enforcement.--A violation by any person of this
section, or any rule or regulation of the Commission issued
under this section, shall be treated for all purposes in the
same manner as a violation of the Securities Exchange Act of
1934 (15 U.S.C. 78a et seq.) or the rules and regulations
issued thereunder, consistent with the provisions of this
section, and any such person shall be subject to the same
penalties, and to the same extent, as for a violation of such
Act or such rules or regulations.
(2) Rules and regulations.--The Commission is authorized to
issue such rules or regulations as are necessary or
appropriate for the protection of investors and to carry out
the purposes of this section.
(e) Definitions.--In this section--
(1) the terms ``issuer'' and ``securities laws'' have the
meaning given the terms in section 3 of the Securities
Exchange Act of 1934 (15 U.S.C. 78c);
(2) the term ``coal or other mine'' means a coal or other
mine, as defined in section 3 of the Federal Mine Safety and
Health Act of 1977 (30 U.S.C. 802), that is subject to the
provisions of such Act (30 U.S.C. 801 et seq.); and
(3) the term ``operator'' has the meaning given the term in
section 3 of the Federal Mine Safety and Health Act of 1977
(30 U.S.C. 802).
______

SA 3887. Mr. CARPER (for himself, Mr. Ensign, Mr. Gregg, Mr. Corker,
and Mr. Johanns) submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 1089, strike line 6 and all that follows through
``SEC. 973.''
______

SA 3888. Mr. INHOFE submitted an amendment intended to be proposed to
amendment SA 3217 submitted by Mrs. Feinstein and intended to be
proposed to the amendment SA 2786 proposed by Mr. Reid (for himself,
Mr.Baucus, Mr. Dodd, and Mr. Harkin) to the bill H.R. 3590, entitled
The Patient Protection and Affordable Care Act; which was ordered to
lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. DELAY OF IMPLEMENTATION.

(a) In General.--Notwithstanding any other provision of
law, the Administrator of the Environmental Protection Agency
shall delay the implementation of the final rule entitled
``Lead; Renovation, Repair, and Painting Program; Lead Hazard
Information Pamphlet; Notice of Availability; Final Rule''
(73 Fed. Reg. 21692 (April 22, 2008)), and the final rule
entitled ``Lead; Amendment to the Opt-out and Recordkeeping
Provisions in the Renovation, Repair, and Painting Program'',
signed by the Administrator on April 22, 2010, in each State
until such time as accredited certified renovator classes
have been held in the State, for a period of at least 1 year,
to train contractors in practices necessary for compliance
with the final rules, as determined by the Administrator.
(b) Notification.--The Administrator shall--
(1) monitor each State to determine when classes described
in subsection (a) are offered in the State; and
(2) provide to each Member of Congress representing the
State a notification describing--
(A) the location and time of each such class held in the
State; and
(B) the date on which the classes have been held for the 1-
year period described in subsection (a).
______

SA 3889. Mr. AKAKA (for himself, Mr. Menendez, and Mr. Durbin)
submitted an amendment intended to be proposed to amendment SA 3739
proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to
the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 942, strike line 10 and all that follows through
page 951, line 13, and insert the following:

SEC. 913. ESTABLISHMENT OF A FIDUCIARY DUTY FOR BROKERS,
DEALERS, AND INVESTMENT ADVISERS, AND
HARMONIZATION OF REGULATION.

(a) In General.--
(1) Securities exchange act of 1934.--Section 15 of the
Securities Exchange Act of 1934 (15 U.S.C. 78o), as amended
by this Act, is amended--
(A) by redesignating subsection (i) (relating to security-
based swap agreements), as added by section 303(f) of the
Commodity Futures Modernization Act of 2000 (Public Law 106-
554; 114 Stat. 2763A-455), as subsection (j); and
(B) by adding at the end the following:
``(m) Standard of Conduct.--

[[Page S3376]]

``(1) In general.--Notwithstanding any other provision of
this Act or the Investment Advisers Act of 1940, the
Commission shall promulgate rules to provide that, with
respect to a broker or dealer, when providing personalized
investment advice about securities to a retail customer (and
such other customers as the Commission may by rule provide),
the standard of conduct for such broker or dealer with
respect to such customer shall be the same as the standard of
conduct applicable to an investment adviser under section 211
of the Investment Advisers Act of 1940. The receipt of
compensation based on commission or other standard
compensation for the sale of securities shall not, in and of
itself, be considered a violation of such standard applied to
a broker or dealer. Nothing in this section shall require a
broker or dealer or registered representative to have a
continuing duty of care or loyalty to the customer after
providing personalized investment advice about securities.
``(2) Disclosure of range of products offered.--Where a
broker or dealer sells only proprietary or other limited
range of products, as determined by the Commission, the
Commission shall by rule require that such broker or dealer
provide notice to each retail customer and obtain the consent
or acknowledgment of the customer. The sale of only
proprietary or other limited range of products by a broker or
dealer shall not, in and of itself, be considered a violation
of the standard set forth in paragraph (1).
``(3) Retail customer defined.--For purposes of this
subsection, the term `retail customer' means a natural
person, or the legal representative of such natural person,
who--
``(A) receives personalized investment advice about
securities from a broker or dealer; and
``(B) uses such advice primarily for personal, family, or
household purposes.
``(n) Other Matters.--The Commission shall--
``(1) facilitate the provision of simple and clear
disclosures to investors regarding the terms of their
relationships with brokers, dealers, and investment advisers,
including any material conflicts of interest; and
``(2) examine and, where appropriate, promulgate rules
prohibiting or restricting certain sales practices, conflicts
of interest, and compensation schemes for brokers, dealers,
and investment advisers that the Commission deems contrary to
the public interest and the protection of investors.''.
(2) Investment advisers act of 1940.--Section 211 of the
Investment Advisers Act of 1940 is amended by adding at the
end the following new subsections:
``(f) Standard of Conduct.--
``(1) In general.--The Commission shall promulgate rules to
provide that the standard of conduct for all brokers,
dealers, and investment advisers, when providing personalized
investment advice about securities to retail customers (and
such other customers as the Commission may by rule provide),
shall be to act in the best interest of the customer without
regard to the financial or other interest of the broker,
dealer, or investment adviser providing the advice. In
accordance with such rules, any material conflicts of
interest shall be disclosed and may be consented to by the
customer. Such rules shall provide that such standard of
conduct shall be no less stringent than the standard
applicable to investment advisers under paragraph (1) and (2)
of section 206 of this Act when providing personalized
investment advice about securities, except the Commission
shall not ascribe a meaning to the term `customer' that would
include an investor in a private fund managed by an
investment adviser, where such private fund has entered into
an advisory contract with such adviser. The receipt of
compensation based on commission or fees shall not, in and of
itself, be considered a violation of such standard applied to
a broker, dealer, or investment adviser.
``(2) Retail customer defined.--For purposes of this
subsection, the term `retail customer' means a natural
person, or the legal representative of such natural person,
who--
``(A) receives personalized investment advice about
securities from a broker, dealer, or investment adviser; and
``(B) uses such advice primarily for personal, family, or
household purposes.
``(g) Other Matters.--The Commission shall--
``(1) facilitate the provision of simple and clear
disclosures to investors regarding the terms of their
relationships with brokers, dealers, and investment advisers,
including any material conflicts of interest; and
``(2) examine and, where appropriate, promulgate rules
prohibiting or restricting certain sales practices, conflicts
of interest, and compensation schemes for brokers, dealers,
and investment advisers that the Commission deems contrary to
the public interest and the protection of investors.''.
(b) Harmonization of Enforcement.--
(1) Securities exchange act of 1934.--Section 15 of the
Securities Exchange Act of 1934, as amended by subsection
(a)(1), is further amended by adding at the end the following
new subsection:
``(m) Harmonization of Enforcement.--The enforcement
authority of the Commission with respect to violations of the
standard of conduct applicable to a broker or dealer
providing personalized investment advice about securities to
a retail customer shall include--
``(1) the enforcement authority of the Commission with
respect to such violations provided under this Act; and
``(2) the enforcement authority of the Commission with
respect to violations of the standard of conduct applicable
to an investment advisor under the Investment Advisers Act of
1940, including the authority to impose sanctions for such
violations, and

the Commission shall seek to prosecute and sanction violators
of the standard of conduct applicable to a broker or dealer
providing personalized investment advice about securities to
a retail customer under this Act to same extent as the
Commission prosecutes and sanctions violators of the standard
of conduct applicable to an investment advisor under the
Investment Advisers Act of 1940.''.
(2) Investment advisers act of 1940.--Section 211 of the
Investment Advisers Act of 1940, as amended by subsection
(a)(2), is further amended by adding at the end the following
new subsection:
``(h) Harmonization of Enforcement.--The enforcement
authority of the Commission with respect to violations of the
standard of conduct applicable to an investment adviser shall
include--
``(1) the enforcement authority of the Commission with
respect to such violations provided under this Act; and
``(2) the enforcement authority of the Commission with
respect to violations of the standard of conduct applicable
to a broker or dealer providing personalized investment
advice about securities to a retail customer under the
Securities Exchange Act of 1934, including the authority to
impose sanctions for such violations, and

the Commission shall seek to prosecute and sanction violators
of the standard of conduct applicable to an investment
advisor under this Act to same extent as the Commission
prosecutes and sanctions violators of the standard of conduct
applicable to a broker or dealer providing personalized
investment advice about securities to a retail customer under
the Securities Exchange Act of 1934.''.
______

SA 3890. Mr. BAYH (for himself and Mr. Merkley), submitted an
amendment intended to be proposed to amendment SA 3739 proposed by Mr.
Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to the bill S. 3217,
to promote the financial stability of the United States by improving
accountability and transparency in the financial system, to end ``too
big to fail'', to protect the American taxpayer by ending bailouts, to
protect consumers from abusive financial services practices, and for
other purposes; which was ordered to lie on the table; as follows:

On page 61, after line 24, insert the following:

SEC. 122. INTERNATIONAL REGULATORY COORDINATION FOR THE
REGULATION AND RESOLUTION OF FINANCIAL
INSTITUTIONS.

(a) Definitions.--As used in this section--
(1) Secretary.--The term ``Secretary'' means the Secretary
of the Treasury.
(2) Large, complex financial institution.--The term
``large, complex financial institution'' means a bank holding
company or company treated as a bank holding company for the
purposes of the section 8 of the International Banking Act of
1978 (12 U.S.C. 3106), a company subject to supervision of
the Board of Governors under section 113, or such other
financial company as the Council may determine, which has the
potential to threaten the financial stability of the United
States owing to the size or interconnectedness of the
institution across more than 1 national jurisdiction.
(3) Multilateral financial forums.--The term ``multilateral
financial forums'' means the International Monetary Fund, the
G20, the Financial Stability Board, the Bank for
International Settlement (including the Basel Committee on
Bank Supervision), the International Organization of
Securities Commissions, the International Association of
Insurance Supervisors, the International Association of
Deposit Insurers, the International Accounting Standard
Board, and other relevant institutions and committees as the
Council may determine.
(b) Biannual Reports.--
(1) Reports.--Not later than January 30, 2011, and
biannually thereafter, the Council shall submit public
reports to the Committee on Banking, Housing, and Urban
Affairs of the Senate and the Committee on Financial Services
of the House of Representatives on the status of and
participation of the United States in international
coordination of financial services regulation and supervision
efforts at multilateral financial forums.
(2) Testimony.--At the request of the Committee on Banking,
Housing, and Urban Affairs of the Senate or the Committee on
Financial Services of the House of Representatives, the
Secretary and representatives of the relevant regulatory
agencies charged with international coordination matters,
including the agencies charged with the coordination of
capital and resolution matters and markets oversight, shall
appear before the committee to provide testimony on the
reports submitted under paragraph (1).
(c) Contents of Report.--Each report submitted under
subsection (b) shall contain--
(1) an update on the status of and participation of the
United States in international coordination efforts at the
multilateral financial forums to set minimum standards for
the regulation and supervision of financial services
regulation, in particular with

[[Page S3377]]

respect to large, complex financial institutions, including--
(A) standards on financial firms, including, as relevant--
(i) capital and leverage requirements;
(ii) liquidity requirements;
(iii) consumer protection;
(iv) resolution plans;
(v) contingent capital;
(vi) credit exposure requirements;
(vii) activity limits;
(viii) concentration limits;
(ix) size limits;
(x) public disclosure;
(xi) market transparency;
(xii) executive compensation;
(xiii) risk management; and
(xiv) any other relevant regulatory areas affecting
banking, securities, derivatives, insurance, and other
financial services;
(B) standards on financial markets, including--
(i) credit and lending markets;
(ii) securities and derivatives markets;
(iii) insurance markets; and
(iv) any other financial service markets, including
ensuring the necessary public transparency, integrity, and
stability;
(C) standards on the supervision of financial firms and
markets, including ensuring national and international
regulators have--
(i) adequate access to real-time information;
(ii) engaged in adequate coordination with international
counterparts; and
(iii) made adequate preparation for crisis management; and
(D) an evaluation of--
(i) any gaps in the international coordination of
regulation and supervision of financial services; and
(ii) whether international coordination adequately permits
individual countries to employ a diversity of regulatory
approaches in practice without permitting regulatory
arbitrage or other pressures to relax necessary protections;
(2) an update on the status of and participation of the
United States in international coordination efforts at the
multilateral financial forums to develop adequate cross-
border bankruptcy and resolution regimes, specifically for
large, complex financial institutions, including the
development and maintenance of--
(A) legal regimes at the national and international level
that--
(i) enforce market discipline;
(ii) deter explicit or implicit reliance on the public
treasury; and
(iii) equitably share burdens in restructuring credit
across 1 or more bankruptcy or resolution regimes;
(B) information systems and regulator coordination,
including--
(i) maps of global exposures and cross-exposures emanating
from large complex financial institutions;
(ii) charts of the legal structure and regulatory regimes
governing various subsidiaries and affiliates of large
complex financial institutions; and
(iii) contingency plans for communication and real-time
crisis management with respect to the possible failure of
each relevant key large complex financial institution; and
(C) information systems to--
(i) detect and promptly respond to the insolvency or
illiquidity of 1 or more foreign or United States large
complex financial institutions or markets; and
(ii) mitigate the direct and indirect risks to the economy
of the United States from the failure of the institution or
market;
(3) the dissenting or divergent views of any members of the
Council; and
(4) any other updates the Council determines is
appropriate.
(d) Congressional Consultation.--
(1) In general.--In addition to any other consultation
required by law, before initiating negotiations to enter into
any international agreement on financial regulation,
supervision, or resolution, and from time to time during such
negotiations, the Secretary and representatives of the
relevant regulatory agencies shall consult with the Committee
on Banking, Housing, and Urban Affairs of the Senate and the
Committee on Financial Services of the House of
Representatives.
(2) Scope.--The consultation described in paragraph (1)
shall include consultation with respect to--
(A) the nature of the agreement;
(B) how and to what extent the agreement will achieve the
applicable purposes, policies, priorities, and objectives of
financial, fiscal, and economic stability in the United
States; and
(C) the implementation of the agreement, including any
effect the agreement may have on existing Federal or State
laws.
(e) Study on International Coordination and Diversity.--Not
later than September 30, 2011, the Council shall submit a
report to Congress, including any dissenting or divergent
views of any members of the Council, regarding risks to the
financial, fiscal, and economic stability of the United
States presented by foreign or United States large complex
financial institutions.
______

SA 3891. Mr. CASEY (for himself, Mrs. Gillibrand, and Mr. Schumer)
submitted an amendment intended to be proposed by him to the bill S.
3217, to promote the financial stability of the United States by
improving accountability and transparency in the financial system, to
end ``too big to fail'', to protect the American taxpayer by ending
bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

At the end of subtitle G of title X appropriate place,
insert the following:

SEC. 1078. EMERGENCY MORTGAGE RELIEF.

(a) Use of TARP Funds.--Using the authority available under
sections 101(a) and 115(a) of division A of the Emergency
Economic Stabilization Act of 2008 (12 U.S.C. 5211(a),
5225(a)), the Secretary of the Treasury shall transfer to the
Secretary of Housing and Urban Development $3,000,000,000,
and the Secretary of Housing and Urban Development shall
credit such amount to the Emergency Homeowners' Relief Fund,
which such Secretary shall establish pursuant to section 107
of the Emergency Housing Act of 1975 (12 U.S.C. 2706), as
such Act is amended by this section, for use for emergency
mortgage assistance in accordance with title I of such Act.
(b) Reauthorization of Emergency Mortgage Relief Program.--
Title I of the Emergency Housing Act of 1975 is amended--
(1) in section 103 (12 U.S.C. 2702)--
(A) in paragraph (2)--
(i) by striking ``have indicated'' and all that follows
through ``regulation of the holder'' and inserting ``have
certified'';
(ii) by striking ``(such as the volume of delinquent loans
in its portfolio)''; and
(iii) by striking ``, except that such statement'' and all
that follows through ``purposes of this title''; and
(B) in paragraph (4), by inserting ``or medical
conditions'' after ``adverse economic conditions'';
(2) in section 104 (12 U.S.C. 2703)--
(A) in subsection (b), by striking ``, but such
assistance'' and all that follows through the period at the
end and inserting the following: ``. The amount of assistance
provided to a homeowner under this title shall be an amount
that the Secretary determines is reasonably necessary to
supplement such amount as the homeowner is capable of
contributing toward such mortgage payment, except that the
aggregate amount of such assistance provided for any
homeowner shall not exceed $50,000.'';
(B) in subsection (d), by striking ``interest on a loan or
advance''and all that follows through the end of the
subsection and inserting the following: ``(1) the rate of
interest on any loan or advance of credit insured under this
title shall be fixed for the life of the loan or advance of
credit and shall not exceed the rate of interest that is
generally charged for mortgages on single-family housing
insured by the Secretary of Housing and Urban Development
under title II of the National Housing Act at the time such
loan or advance of credit is made, and (2) no interest shall
be charged on interest which is deferred on a loan or advance
of credit made under this title. In establishing rates, terms
and conditions for loans or advances of credit made under
this title, the Secretary shall take into account a
homeowner's ability to repay such loan or advance of
credit.''; and
(C) in subsection (e), by inserting after the period at the
end of the first sentence the following: ``Any eligible
homeowner who receives a grant or an advance of credit under
this title may repay the loan in full, without penalty, by
lump sum or by installment payments at any time before the
loan becomes due and payable.'';
(3) in section 105 (12 U.S.C. 2704)--
(A) by striking subsection (b);
(B) in subsection (e)--
(i) by inserting ``and emergency mortgage relief payments
made under section 106'' after ``insured under this
section''; and
(ii) by striking ``$1,500,000,000 at any one time'' and
inserting ``$3,000,000,000'';
(C) by redesignating subsections (c), (d), and (e) as
subsections (b), (c), and (d), respectively; and
(D) by adding at the end the following new subsection:
``(e) The Secretary shall establish underwriting guidelines
or procedures to allocate amounts made available for loans
and advances insured under this section and for emergency
relief payments made under section 106 based on the
likelihood that a mortgagor will be able to resume mortgage
payments, pursuant to the requirement under section
103(5).'';
(4) in section 107--
(A) by striking ``(a)''; and
(B) by striking subsection (b);
(5) in section 108 (12 U.S.C. 2707), by adding at the end
the following new subsection:
``(d) Coverage of Existing Programs.--The Secretary shall
allow funds to be administered by a State that has an
existing program that is determined by the Secretary to
provide substantially similar assistance to homeowners. After
such determination is made such State shall not be required
to modify such program to comply with the provisions of this
title.'';
(6) in section 109 (12 U.S.C. 2708)--
(A) in the section heading, by striking ``authorization
and'';
(B) by striking subsection (a);
(C) by striking ``(b)''; and
(D) by striking ``1977'' and inserting ``2011'';
(7) by striking sections 110, 111, and 113 (12 U.S.C. 2709,
2710, 2712); and
(8) by redesignating section 112 (12 U.S.C. 2711) as
section 110.

[[Page S3378]]

SEC. 1079. ADDITIONAL ASSISTANCE FOR NEIGHBORHOOD
STABILIZATION PROGRAM.

Using the authority made available under sections 101(a)
and 115(a) of division A of the Emergency Economic
Stabilization Act of 2008 (12 U.S.C. 5211(a), 5225(a)), the
Secretary of the Treasury shall transfer to the Secretary of
Housing and Urban Development $1,000,000,000, and the
Secretary of Housing and Urban Development shall use such
amounts for assistance to States and units of general local
government for the redevelopment of abandoned and foreclosed
homes, in accordance with the same provisions applicable
under the second undesignated paragraph under the heading
``Community Planning and Development--Community Development
Fund'' in title XII of division A of the American Recovery
and Reinvestment Act of 2009 (Public Law 111-5; 123 Stat.
217) to amounts made available under such second undesignated
paragraph, except as follows:
(1) Notwithstanding the matter of such second undesignated
paragraph that precedes the first proviso, amounts made
available by this section shall remain available until
expended.
(2) The 3rd, 4th, 5th, 6th, 7th, and 15th provisos of such
second undesignated paragraph shall not apply to amounts made
available by this section.
(3) Amounts made available by this section shall be
allocated based on a funding formula for such amounts
established by the Secretary in accordance with section
2301(b) of the Housing and Economic Recovery Act of 2008 (42
U.S.C. 5301 note), except that--
(A) notwithstanding paragraph (2) of such section 2301(b),
the formula shall be established not later than 30 days after
the date of the enactment of this Act;
(B) the Secretary may not establish any minimum grant
amount or size for grants to States;
(C) the Secretary may establish a minimum grant amount for
direct allocations to units of general local government
located within a State, which shall not exceed $1,000,000;
and
(D) each State and local government receiving grant amounts
shall establish procedures to create preferences for the
development of affordable rental housing for properties
assisted with amounts made available by this section.
(4) Paragraph (1) of section 2301(c) of the Housing and
Economic Recovery Act of 2008 shall not apply to amounts made
available by this section.
(5) Section 2302 of the Housing and Economic Recovery Act
of 2008 shall not apply to amounts made available by this
section.
(6) The fourth proviso from the end of such second
undesignated paragraph shall be applied to amounts made
available by this section by substituting ``2013'' for
``2012''.
(7) Notwithstanding section 2301(a) of the Housing and
Economic Recovery Act of 2008, the term ``State'' means any
State of the United States, the District of Columbia, the
Commonwealth of Puerto Rico, the Commonwealth of the Northern
Mariana Islands, Guam, the Virgin Islands, American Samoa,
and other territory or possession of the United States for
purposes of this section and title III of division B of such
Act, as applied to amounts made available by this section.
(8)(A) None of the amounts made available by this section
shall be distributed to--
(i) any organization which has been convicted for a
violation under Federal law relating to an election for
Federal office; or
(ii) any organization which employs applicable individuals.
(B) In this paragraph, the term ``applicable individual''
means an individual who--
(i) is--
(I) employed by the organization in a permanent or
temporary capacity;
(II) contracted or retained by the organization; or
(III) acting on behalf of, or with the express or apparent
authority of, the organization; and
(ii) has been convicted for a violation under Federal law
relating to an election for Federal office.
______

SA 3892. Mr. BINGAMAN (for himself, Ms. Murkowski, Mr. Reid, Mr.
Brownback, Ms. Cantwell, Mr. Cornyn, Mr. Wyden, and Mr. Corker)
submitted an amendment intended to be proposed to amendment SA 3739
proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln)) to
the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 565, between lines 2 and 3, insert the following:
(e) Just and Reasonable Rates.--Section 2(a)(1)(C) of the
Commodity Exchange Act (7 U.S.C. 2(a)(1)(C)) (as amended by
section 717(a)) is amended by adding at the end the
following:
``(vi) Notwithstanding the exclusive jurisdiction of the
Commission with respect to accounts, agreements, and
transactions involving swaps or contracts of sale of a
commodity for future delivery under this Act, no provision of
this Act shall be construed--

``(I) to supersede or limit the authority of the Federal
Energy Regulatory Commission under the Federal Power Act (16
U.S.C. 791a et seq.) or the Natural Gas Act (15 U.S.C. 717 et
seq.); or
``(II) to restrict the Federal Energy Regulatory Commission
from carrying out the duties and responsibilities of the
Federal Energy Regulatory Commission to ensure just and
reasonable rates and protect the public interest under the
Acts described in subclause (I).''.

(f) Public Interest Waiver.--Section 4(c) of the Commodity
Exchange Act (7 U.S.C. 6(c)) (as amended by section 721(d))
is amended by adding at the end the following:
``(6) If the Commission determines that the exemption would
be consistent with the public interest and the purposes of
this Act, the Commission shall, in accordance with paragraphs
(1) and (2), exempt from the requirements of this Act an
agreement, contract, or transaction that is entered into
pursuant to--
``(A) a tariff or rate schedule approved or permitted to
take effect by the Federal Energy Regulatory Commission; or
``(B) a tariff or rate schedule establishing rates or
charges for the sale of electric energy approved or permitted
to take effect by the regulatory body of the State or
municipality having jurisdiction to regulate rates and
charges for the sale of electric energy to consumers within
the State or municipality.''.
______

SA 3893. Mr. CORNYN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 1304, line 11, strike ``person--'' and insert
``covered person--''.
On page 1305, line 2, strike ``practice,'' and insert
``practice that violates this title or applicable rules or
orders issued by the Bureau,''.
On page 1310, between lines 16 and 17, insert the
following:
(3) Fee structure.--
(A) In general.--Neither an attorney general of a State nor
a State regulator may enter into a contingency fee agreement
for legal services relating to a civil action or other
proceeding under this section.
(B) Definition.--For purposes of this paragraph, the term
``contingency fee agreement'' means a contract or other
agreement to provide services under which the amount or the
payment of the fee for the services is contingent in whole or
in part on the outcome of the matter for which the services
were obtained.
______

SA 3894. Mr. CORNYN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail,'' to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 976, strike line 7 and all that follows through
page 977, line 17.
On page 1290, strike line 5 and all that follows through
page 1291, line 9.
On page 1371, strike line 15 and all that follows through
page 1372, line 2.
______

SA 3895. Mr. CORNYN submitted an amendment intended to be proposed to
him to the bill S. 3217, to promote the financial stability of the
United States by improving accountability and transparency in the
financial system, to end ``too big to fail'', to protect the American
taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

At the end of subtitle A of title IX, add the following:

SEC. 919C. SECURITIES LITIGATION ATTORNEY ACCOUNTABILITY AND
TRANSPARENCY.

(a) Disclosures of Payments, Fee Arrangements,
Contributions, and Other Potential Conflicts of Interest
Between Plaintiff and Attorneys.--
(1) Securities exchange act of 1934.--Section 21D(a) of the
Securities Exchange Act of 1934 (15 U.S.C. 78u-4(a)) is
amended by adding at the end the following new paragraphs:
``(10) Disclosures regarding payments.--
``(A) Sworn certifications required.--In any private action
arising under this title, each plaintiff and any attorney for
such

[[Page S3379]]

plaintiff shall provide sworn certifications, which shall be
personally signed by such plaintiff and such attorney,
respectively, and filed with the complaint, that identify any
direct or indirect payment, or promise of any payment, by
such attorney, or any person affiliated with such attorney,
to such plaintiff, or any person affiliated with such
plaintiff, beyond the plaintiff's pro rata share of any
recovery, except as ordered or approved by the court in
accordance with paragraph (4). Upon disclosure of any such
payment or promise of payment, the court shall disqualify the
attorney from representing the plaintiff.
``(B) Definition.--For purposes of this paragraph, the term
`payment' shall include the transfer of money and any other
thing of value, including the provision of services, other
than representation of the plaintiff in the private action
arising under this title.
``(11) Disclosures regarding legal representations.--In any
private action arising under this title, each plaintiff and
any attorney for such plaintiff shall provide sworn
certifications, which shall be personally signed by such
plaintiff and such attorney, respectively, and filed with the
complaint, that identifies the nature and terms of any legal
representation provided by such attorney, or any person
affiliated with such attorney, to such plaintiff, or any
person affiliated with such plaintiff other than the
representation of the plaintiff in the private action arising
under this title. The court may allow such certifications to
be made under seal. The court shall make a determination
whether the nature or terms of the fee arrangement for any
other matter influenced the selection and retention of
counsel in any private action arising under this title and,
if the court so finds, shall disqualify the attorney from
representing the plaintiff in any such action.
``(12) Disclosures regarding contributions.--In any private
action arising under this title, each plaintiff and any
attorney for such plaintiff shall provide sworn
certifications, which shall be personally signed by such
plaintiff and such attorney, respectively, and filed with the
complaint, that identifies any contribution made within five
years prior to the filing of the complaint by such attorney,
any person affiliated with such attorney, or any political
action committee controlled by such attorney, to any elected
official with authority to retain counsel for such plaintiff
or to select or appoint, influence the selection or
appointment of, or oversee any individual or group of
individuals with that authority.
``(13) Disclosure regarding other conflicts of interest.--
In any private action arising under this title, each
plaintiff and any attorney for such plaintiff shall provide
sworn certifications, which shall be personally signed by
such plaintiff and such attorney, respectively, and filed
with the complaint, that identifies any other conflict of
interest (other than one specified in paragraphs (10) through
(12)) between such attorney and such plaintiff. The court
shall make a determination of whether such conflict is
sufficient to disqualify the attorney from representing the
plaintiff.''.
(2) Securities act of 1933.--Section 27(a) of the
Securities Act of 1933 (15 U.S.C. 77z-1(a)) is amended by
adding at the end the following new paragraph:
``(9) Disclosures regarding payments.--
``(A) Sworn certifications required.--In any private action
arising under this title, each plaintiff and any attorney for
such plaintiff shall provide sworn certifications, which
shall be personally signed by such plaintiff and such
attorney, respectively, and filed with the complaint, that
identify any direct or indirect payment, or promise of any
payment, by such attorney, or any person affiliated with such
attorney, to such plaintiff, or any person affiliated with
such plaintiff, beyond the plaintiff's pro rata share of any
recovery, except as ordered or approved by the court in
accordance with paragraph (4). Upon disclosure of any such
payment or promise of payment, the court shall disqualify the
attorney from representing the plaintiff.
``(B) Definition.--For purposes of this paragraph, the term
`payment' shall include the transfer of money and any other
thing of value, including the provision of services, other
than representation of the plaintiff in the private action
arising under this title.
``(10) Disclosures regarding legal representations.--In any
private action arising under this title, each plaintiff and
any attorney for such plaintiff shall provide sworn
certifications, which shall be personally signed by such
plaintiff and such attorney, respectively, and filed with the
complaint, that identifies the nature and terms of any legal
representation provided by such attorney, or any person
affiliated with such attorney, to such plaintiff, or any
person affiliated with such plaintiff other than the
representation of the plaintiff in the private action arising
under this title. The court may allow such certifications to
be made under seal. The court shall make a determination
whether the nature or terms of the fee arrangement for any
other matter influenced the selection and retention of
counsel in any private action arising under this title and,
if the court so finds, shall disqualify the attorney from
representing the plaintiff in any such action.
``(11) Disclosures regarding contributions.--In any private
action arising under this title, each plaintiff and any
attorney for such plaintiff shall provide sworn
certifications, which shall be personally signed by such
plaintiff and such attorney, respectively, and filed with the
complaint, that identifies any contribution made within five
years prior to the filing of the complaint by such attorney,
any person affiliated with such attorney, or any political
action committee controlled by such attorney, to any elected
official with authority to retain counsel for such plaintiff
or to select or appoint, influence the selection or
appointment of, or oversee any individual or group of
individuals with that authority.
``(12) Disclosure regarding other conflicts of interest.--
In any private action arising under this title, each
plaintiff and any attorney for such plaintiff shall provide
sworn certifications, which shall be personally signed by
such plaintiff and such attorney, respectively, and filed
with the complaint, that identifies any other conflict of
interest (other than one specified in paragraphs (9) through
(11)) between such attorney and such plaintiff. The court
shall make a determination of whether such conflict is
sufficient to disqualify the attorney from representing the
plaintiff.''.
(b) Selection of Lead Counsel.--
(1) Securities exchange act of 1934.--Section
21D(a)(3)(B)(v) of the Securities Exchange Act of 1934 (15
U.S.C. 78u-4(a)(3)(B)(v)) is amended by adding at the end the
following: ``In exercising the discretion of the court over
the approval of lead counsel, the court may employ a
competitive bidding process as one of the criteria in the
selection and retention of counsel for the most adequate
plaintiff.''.
(2) Securities act of 1933.--Section 27(a)(3)(B)(v) of the
Securities Act of 1933 (15 U.S.C. 77z-1(a)(3)(B)(v)) is
amended by adding at the end the following: ``In exercising
the discretion of the court over the approval of lead
counsel, the court may employ a competitive bidding process
as one of the criteria in the selection and retention of
counsel for the most adequate plaintiff.''.
(c) Study of Average Hourly Fees in Securities Class
Actions.--
(1) Study and review required.--The Comptroller General of
the United States shall conduct a study and review of fee
awards to lead counsel in securities class actions over the
5-year period preceding the date of enactment of this Act to
determine the effective average hourly rate for lead counsel
in such actions.
(2) Report required.--Not later than 1 year after the date
of enactment of this Act, the Comptroller General shall
submit a report to the Committee on Banking, Housing, and
Urban Affairs of the Senate and the Committee on Financial
Services of the House of Representatives on the results of
the study and review required by this section. The
Comptroller General shall submit an updated study every 3
years thereafter.
(3) Definition.--For purposes of this subsection, the term
``securities class action'' means a private class action
arising under the Securities Act of 1933 (15 U.S.C. 77 et
seq.) or the Securities Exchange Act of 1934 (15 U.S.C. 78 et
seq.) that is brought as a plaintiff class action pursuant to
the Federal Rules of Civil Procedure.
(d) Authority to Impose Civil Penalties in Cease-and-Desist
Proceedings.--
(1) Under the securities act of 1933.--Section 8A of the
Securities Act of 1933 (15 U.S.C. 77h-1) is amended by adding
at the end the following:
``(g) Authority to Impose Money Penalties.--
``(1) Grounds.--In any cease-and-desist proceeding under
subsection (a), the Commission may impose a civil penalty on
a person, if the Commission finds, on the record, after
notice and opportunity for hearing, that--
``(A) the person--
``(i) is violating or has violated any provision of this
title, or any rule or regulation issued under this title; or
``(ii) is or was a cause of the violation of any provision
of this title, or any rule or regulation thereunder; and
``(B) the imposition of the penalty is in the public
interest.
``(2) Maximum amount of penalty.--
``(A) First tier.--The maximum amount of a penalty for each
act or omission described in paragraph (1) shall be $7,500
for a natural person or $75,000 for any other person.
``(B) Second tier.--Notwithstanding subparagraph (A), if
the act or omission described in paragraph (1) involved
fraud, deceit, manipulation, or deliberate or reckless
disregard of a regulatory requirement, the maximum amount of
penalty for each act or omission shall be $75,000 for a
natural person or $375,000 for any other person.
``(C) Third tier.--Notwithstanding subparagraphs (A) and
(B), the maximum amount of penalty for each act or omission
described in paragraph (1) shall be $150,000 for a natural
person or $725,000 for any other person, if--
``(i) the act or omission involved fraud, deceit,
manipulation, or deliberate or reckless disregard of a
regulatory requirement; and
``(ii) the act or omission directly or indirectly resulted
in--

``(I) substantial losses or created a significant risk of
substantial losses to other persons; or
``(II) substantial pecuniary gain to the person who
committed the act or omission.

``(3) Evidence concerning ability to pay.--In any
proceeding in which the Commission may impose a penalty under
this section, a respondent may present evidence of the
ability of the respondent to pay such

[[Page S3380]]

penalty. The Commission may, in its discretion, consider such
evidence in determining whether such penalty is in the public
interest. Such evidence may relate to the extent of the
ability of the respondent to continue in business and the
collectability of a penalty, taking into account any other
claims of the United States or third parties upon the assets
of the respondent and the amount of the assets of the
respondent.''.
(2) Under the securities exchange act of 1934.--Section
21B(a) of the Securities Exchange Act of 1934 (15 U.S.C. 78u-
2(a)) is amended--
(A) by striking the undesignated matter immediately
following paragraph (4);
(B) in the matter preceding paragraph (1), by inserting
after ``opportunity for hearing,'' the following: ``that such
penalty is in the public interest and'';
(C) by redesignating paragraphs (1) through (4) as
subparagraphs (A) through (D), respectively, and adjusting
the subparagraph margins accordingly;
(D) by striking ``In any proceeding'' and inserting the
following:
``(1) In general.--In any proceeding''; and
(E) by adding at the end the following:
``(2) Cease-and-desist proceedings.--In any proceeding
instituted under section 21C against any person, the
Commission may impose a civil penalty, if the Commission
finds, on the record after notice and opportunity for
hearing, that such person--
``(A) is violating or has violated any provision of this
title, or any rule or regulation issued under this title; or
``(B) is or was a cause of the violation of any provision
of this title, or any rule or regulation issued under this
title.''.
(3) Under the investment company act of 1940.--Section
9(d)(1) of the Investment Company Act of 1940 (15 U.S.C. 80a-
9(d)(1)) is amended--
(A) by striking the matter immediately following
subparagraph (C);
(B) in the matter preceding subparagraph (A), by inserting
after ``opportunity for hearing,'' the following: ``that such
penalty is in the public interest, and'';
(C) by redesignating subparagraphs (A) through (C) as
clauses (i) through (iii), respectively, and adjusting the
clause margins accordingly;
(D) by striking ``In any proceeding'' and inserting the
following:
``(A) In general.--In any proceeding''; and
(E) by adding at the end the following:
``(B) Cease-and-desist proceedings.--In any proceeding
instituted pursuant to subsection (f) against any person, the
Commission may impose a civil penalty if the Commission
finds, on the record, after notice and opportunity for
hearing, that such person--
``(i) is violating or has violated any provision of this
title, or any rule or regulation issued under this title; or
``(ii) is or was a cause of the violation of any provision
of this title, or any rule or regulation issued under this
title.''.
(4) Under the investment advisers act of 1940.--Section
203(i)(1) of the Investment Advisers Act of 1940 (15 U.S.C.
80b-3(i)(1)) is amended--
(A) by striking the undesignated matter immediately
following subparagraph (D);
(B) in the matter preceding subparagraph (A), by inserting
after ``opportunity for hearing,'' the following: ``that such
penalty is in the public interest and'';
(C) by redesignating subparagraphs (A) through (D) as
clauses (i) through (iv), respectively, and adjusting the
clause margins accordingly;
(D) by striking ``In any proceeding'' and inserting the
following:
``(A) In general.--In any proceeding''; and
(E) by adding at the end the following:
``(B) Cease-and-desist proceedings.--In any proceeding
instituted pursuant to subsection (k) against any person, the
Commission may impose a civil penalty if the Commission
finds, on the record, after notice and opportunity for
hearing, that such person--
``(i) is violating or has violated any provision of this
title, or any rule or regulation issued under this title; or
``(ii) is or was a cause of the violation of any provision
of this title, or any rule or regulation issued under this
title.''.
______

SA 3896. Mr. GREGG (for himself, Mr. Brown of Massachusetts, and Mr.
Kerry) submitted an amendment intended to be proposed to amendment SA
3739 proposed by Mr. Reid (for Mr. Dodd (for himself and Mrs. Lincoln))
to the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

On page 320, between lines 11 and 12, insert the following:
(g) Parity.--Section 10(a)(1)(A) of the Home Owners' Loan
Act (12 U.S.C. 1467a(a)(1)(A)) is amended to read as follows:
``(A) Savings association.--The term `savings
association'--
``(i) includes a savings bank or cooperative bank which is
deemed by the Director to be a savings association under
subsection (l); and
``(ii) does not include an institution described in section
2(c)(2)(D) of the Bank Holding Company Act of 1956 (12 U.S.C.
1841(c)(2)(D)).''.
______

SA 3897. Mr. DORGAN submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

On page 584, line 7, after the first period insert the
following:
``(k) Clearing of Credit Default Swaps.--
``(1) Submission.--It shall be unlawful for any party to
enter into a credit default swap unless that person shall
submit such credit default swap for clearing to a derivatives
clearing organization that is registered under this Act or a
derivatives clearing organization that is exempt from
registration under section 5b(i) of this Act.
``(2) Prohibition.--Notwithstanding any other provisions in
this section or of this Act, if no derivatives clearing
organization will accept a credit default swap for clearing,
it shall be unlawful for any party to enter into the credit
default swap.
``(3) Limitation on short positions.--
``(A) In general.--It shall be unlawful for a protection
buyer to enter into a credit default swap which establishes a
short position in a reference entity's credit instrument
unless the protection buyer can demonstrate to the
Commission, in such manner and in such form as may be
prescribed by the Commission, that the protection buyer--
``(i) is undertaking such action to establish a legitimate
short position in credit default swaps; or
``(ii) is regulated by the Commission as a swap dealer in
credit default swaps, and is acting as a market-maker or is
otherwise engaged in a financial transaction on behalf of a
customer.
``(B) Legitimate short position in credit default swaps.--A
protection buyer's short position in credit default swaps
shall be considered a legitimate short position in credit
default swaps if--
``(i) the value of the protection buyer's holdings in valid
credit instruments is equal to or greater than the absolute
notional value of the protection buyer's credit default
swaps; and
``(ii) the reference entity or entities for the protection
buyer's credit default swaps in clause (i), whether in a
single-name, or a narrow-based index or a broad-based index
credit default swap transaction, must be the same as the
borrower or issuer, or borrowers or issuers, of the valid
credit instrument or valid credit instruments the protection
buyer owns.
``(C) Determination of the commission.--
``(i) In general.--The Commission and the Securities and
Exchange Commission, shall jointly establish and adopt rules,
regulations, or orders, in accordance with the public
interest, defining the term `valid credit instrument'.
``(ii) Considerations and requirements.--In defining the
term `valid credit instrument', the Commission and the
Securities and Exchange Commission shall consider which
group, category, type, or class of credit instruments can be
effectively hedged using credit default swaps.
``(iii) Rule of construction.--For purposes of this
paragraph, any instrument with an equity risk exposure or
equity-like features shall not be considered by the
Commission to be a valid credit instrument.
``(D) Reporting.--Each protection buyer shall report all of
its legitimate short positions in credit default swaps, as
well as any other credit default swap positions and the valid
credit instruments that it owns to the Commission, in such
manner, in such frequency, and in such form as may be
prescribed by the Commission.
``(E) Holding of short positions in credit default swaps by
swap dealers.--Any swap dealer in credit default swaps
seeking to establish, possess, or otherwise obtain a short
position as the protection buyer of any credit default swap
for more than 60 consecutive calendar days or for more than
two-thirds of the days in any calendar quarter, shall
demonstrate to the Commission, in such manner and in such
form as may be prescribed by the Commission, that--
``(i) the value of the swap dealer's holdings in valid
credit instruments is equal to or greater than the absolute
notional value of the swap dealer's position in credit
default swaps; and
``(ii) the reference entity or entities for the swap
dealer's credit default swaps in clause (i), whether in a
single-name, or a narrow-based index or a broad-based index
credit default swap transaction, must be the same as the
borrower or issuer, or borrowers or issuers, of the valid
credit instrument or valid credit instruments the swap dealer
owns.
``(F) Prohibition on evasions and structuring of
transactions.--No person, including any protection buyer,
protection seller, or counterparty, may take any action in
connection with a credit default swap to structure such swap
for the purpose and with

[[Page S3381]]

the intent of evading the provisions of this subsection.
``(G) Authority of the commission.--The Commission, in
consultation with the Securities and Exchange Commission,
may, in the public interest, for the protection of investors,
for the protection of market participants, and the
maintenance of fair and orderly markets, prohibit any other
action, practice, or conduct in connection with or related to
the direct or indirect purchase or sale of credit default
swaps.
``(4) Definitions.--
``(A) In general.--In this subsection, the following
definitions shall apply:
``(i) Credit default swap.--The term `credit default
swap'--

``(I) means a swap or security-based swap whose payout is
determined by the occurrence of a credit event with respect
to a single referenced credit instrument or reference entity
or multiple referenced credit instruments or reference
entities; and
``(II) is not a debt security registered with the
Securities and Exchange Commission and issued by a
corporation, State, municipality, or sovereign entity.

``(ii) Credit event.--The term `credit event' includes a
default, restructuring, insolvency, bankruptcy, credit
downgrade, and a violation of a debt covenant.
``(iii) Protection buyer.--The term `protection buyer'
means a person that enters into a credit default swap to
obtain a payoff from a third party (commonly referred to as
the `protection seller') upon the occurrence of one or more
credit events.
``(iv) Reference entity.--The term `reference entity' means
any borrower, such as a corporation, State, municipality,
sovereign entity, or special purpose entity, which has issued
a public debt obligation or obtained a loan that is
referenced by a credit default swap.
``(B) Further definition of terms.--The Commission and the
Securities and Exchange Commission, shall jointly establish
and adopt rules, regulations, or orders, in accordance with
the public interest, further defining the terms `credit
default swap', `credit event', `protection buyer', and
`reference entity'.

On page 808, line 8, after the first period, insert the
following:

``SEC. 3C-1. CLEARING OF CREDIT DEFAULT SWAPS.

``(a) Submission.--It shall be unlawful for any party to
enter into a credit default swap unless that person shall
submit such credit default swap for clearing to a clearing
agency that is registered under section 17A of this Act.
``(b) Prohibition.--Notwithstanding any other provisions in
this section or of this Act, if no clearing agency will
accept a credit default swap for clearing, it shall be
unlawful for any party to enter into the credit default swap.
``(c) Limitation on Short Positions.--
``(1) In general.--It shall be unlawful for a protection
buyer to enter into a credit default swap which establishes a
short position in a reference entity's credit unless the
protection buyer can demonstrate to the Commission, in such
manner and in such form as may be prescribed by the
Commission, that the protection buyer--
``(A) is undertaking such action to establish a legitimate
short position in credit default swaps; or
``(B) is regulated by the Commission as a security-based
swap dealer in credit default swaps, and is acting as a
market-maker or otherwise for the purpose of serving clients.
``(2) Legitimate short position in credit default swaps.--A
protection buyer's short position in credit default swaps
shall be considered a legitimate short position in credit
default swaps if --
``(A) the value of the protection buyer's holdings in valid
credit instruments is equal to or greater than the absolute
notional value of the protection buyer's credit default
swaps; and
``(B) the reference entity or entities for the protection
buyer's credit default swaps in subparagraph (A), whether in
a single-name, or a narrow-based index or a broad-based index
credit default swap transaction, must be the same as the
borrower or issuer, or borrowers or issuers, of the valid
credit instrument or valid credit instruments the protection
buyer owns.
``(3) Determination of the commission.--
``(A) In general.--The Commission and the Commodity Futures
Trading Commission, shall jointly establish and adopt rules,
regulations, or orders, in accordance with the public
interest, defining the term `valid credit instrument'.
``(B) Considerations and requirements.--In defining the
term `valid credit instrument', the Commission and the
Commodity Futures Trading Commission shall consider which
group, category, type, or class of credit instruments can be
effectively hedged using credit default swaps.
``(C) Rule of construction.--For purposes of this
subsection, any instrument with an equity risk exposure or
equity-like features shall not be considered by the
Commission to be a valid credit instrument.
``(4) Reporting.--Each protection buyer shall report all of
its legitimate short positions in credit default swaps, as
well as any other credit default swap positions and the valid
credit instruments that it owns to the Commission, in such
manner, in such frequency, and in such form as may be
prescribed by the Commission.
``(5) Holdings of short positions in credit default swaps
by security-based swap dealers.--Any security-based swap
dealer in credit default swaps seeking to establish, possess,
or otherwise obtain a short position as the protection buyer
of any credit default swap for more than 60 consecutive
calendar days or for more than two-thirds of the days in any
calendar quarter, shall demonstrate to the Commission, in
such manner and in such form as may be prescribed by the
Commission, that--
``(A) the value of the security-based swap dealer's long
holdings in valid credit instruments is equal to or greater
than the absolute notional value of the security-based swap
dealer's position in credit default swaps; and
``(B) the reference entity or entities for the security-
based swap dealer's credit default swaps in subparagraph (A),
whether in a single-name, or a narrow-based index or a broad-
based index credit default swap transaction, must be the same
as the borrower or issuer, or borrowers or issuers, of the
valid credit instrument or valid credit instruments the
security-based swaps dealer owns.
``(6) Prohibition on evasions and structuring of
transactions.--No person, including any protection buyer,
protection seller, or counterparty, may take any action in
connection with a credit default swap to structure such swap
for the purpose and with the intent of evading the provisions
of this section.
``(7) Authority of the commission.--The Commission, in
consultation with the Commodity Futures Trading Commission,
may, in the public interest, for the protection of investors,
for the protection of market participants, and the
maintenance of fair and orderly markets, prohibit any other
action, practice, or conduct in connection with or related to
the direct or indirect purchase or sale of credit default
swaps.
``(d) Definitions.--
``(1) In general.--In this section, the following
definitions shall apply:
``(A) Credit default swap.--The term `credit default
swap'--
``(i) means a swap or security-based swap whose payout is
determined by the occurrence of a credit event with respect
to a single referenced credit instrument or reference entity
or multiple referenced credit instruments or reference
entities; and
``(ii) is not a debt security registered with the
Commission and issued by a corporation, State, municipality,
or sovereign entity.
``(B) Credit event.--The term `credit event' includes a
default, restructuring, insolvency, bankruptcy, credit
downgrade, and a violation of a debt covenant.
``(C) Protection buyer.--The term `protection buyer' means
a person that enters into a credit default swap to obtain a
payoff from a third party (commonly referred to as the
`protection seller') upon the occurrence of one or more
credit events.
``(D) Reference entity.--The term `reference entity' means
any borrower, such as a corporation, State, municipality,
sovereign entity, or special purpose entity, which has issued
a public debt obligation or obtained a loan that is
referenced by a credit default swap.
``(2) Further definition of terms.--The Commission and the
Commodity Futures Trading Commission, shall jointly establish
and adopt rules, regulations, or orders, in accordance with
the public interest, further defining the terms `credit
default swap', `credit event', `protection buyer', and
`reference entity'.
______

SA 3898. Mr. ENSIGN proposed an amendment to amendment SA 3733
proposed by Mr. Brown of Ohio (for himself, Mr. Kaufman, Mr. Casey, Mr.
Whitehouse, Mr. Merkley, Mr. Harkin, Mr. Sanders, and Mr. Burris) to
the amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes; as
follows:

On page 2 of the amendment, strike lines 11 through 15 and
insert the following:
(1) Financial company.--The term ``financial company''
means--
(A) any nonbank financial company supervised by the Board;
(B) the Federal National Mortgage Association; and
(C) the Federal Home Loan Mortgage Corporation.
______

SA 3899. Mr. REED submitted an amendment intended to be proposed to
amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself and
Mrs. Lincoln)) to the bill S. 3217, to promote the financial stability
of the United States by improving accountability and transparency in
the financial system, to end ``too big to fail'', to protect the
American taxpayer by ending bailouts, to protect consumers from abusive
financial services practices, and for other purposes; which was ordered
to lie on the table; as follows:

[[Page S3382]]

On page 1219, after line 25, insert the following:
``(e) Office of Military Liaison.--
``(1) In general.--The Director shall establish an Office
of Military Liaison, which shall be responsible for
developing and implementing initiatives for service members
and their families intended to--
``(A) educate and empower service members and their
families to make better informed decisions regarding consumer
financial products and services;
``(B) coordinate with the unit of the Bureau established
under subsection (b)(3), in order to monitor complaints by
service members and their families and responses to those
complaints by the Bureau or other appropriate Federal or
State agency; and
``(C) coordinate efforts among Federal and State agencies,
as appropriate, regarding consumer protection measures
relating to consumer financial products and services offered
to, or used by, service members and their families.
``(2) Coordination.--
``(A) Regional services.--The Director is authorized to
assign employees of the Bureau as may be deemed necessary to
conduct the business of the Office of Military Liaison,
including by establishing and maintaining the functions of
the Office in regional offices of the Bureau located near
military bases, military treatment facilities, or other
similar military facilities.
``(B) Agreements.--The Director is authorized to enter into
memoranda of understanding and similar agreements with the
Department of Defense, including any branch or agency as
authorized by the department, in order to carry out the
business of the Office of Military Liaison.''.
______

SA 3900. Mr. BINGAMAN submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 100, line 23, strike ``and'' and all that follows
through ``(G) any'' on line 24 and insert the following:
(G) net potential obligations to third parties in
connection with credit derivative transactions between the
nonbank financial company supervised by the Board of
Governors or a bank holding company described in subsection
(a) and the third parties that reference the company or
obligations of the company; and
(H) any
______

SA 3901. Mr. CARDIN (for himself, Mr. Enzi, and Mr. Brownback)
submitted an amendment intended to be proposed by him to the bill S.
3217, to promote the financial stability of the United States by
improving accountability and transparency in the financial system, to
end ``too big to fail'', to protect the American taxpayer by ending
bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

At the end of subtitle C of title III, add the following:

SEC. 333. INCREASE IN DEPOSIT AND SHARE INSURANCE AMOUNTS.

(a) Permanent Increase in Deposit Insurance.--Section
11(a)(1)(E) of the Federal Deposit Insurance Act (12 U.S.C.
1821(a)(1)(E)) is amended by striking ``$100,000'' and
inserting ``$250,000''.
(b) Permanent Increase in Share Insurance.--Section
207(k)(5) of the Federal Credit Union Act (12 U.S.C.
1787(k)(5)) is amended by striking ``$100,000'' and inserting
``$250,000''.
(c) Repeal.--Section 136 of the Emergency Economic
Stabilization Act of 2008 (12 U.S.C. 5241) is repealed,
effective on the date of enactment of this Act.
______

SA 3902. Mr. FRANKEN (for himself, Ms. Snowe, Mrs. Murray, Mrs.
Shaheen, Mr. Schumer, Mr. Brown of Ohio, Mr. Merkley, Mr. Casey, and
Mr. Feingold) submitted an amendment intended to be proposed by him to
the bill S. 3217, to promote the financial stability of the United
States by improving accountability and transparency in the financial
system, to end ``too big to fail'', to protect the American taxpayer by
ending bailouts, to protect consumers from abusive financial services
practices, and for other purposes; which was ordered to lie on the
table; as follows:

At the end of title X, add the following:

Subtitle I--Office of the Homeowner Advocate

SEC. 1091. OFFICE OF THE HOMEOWNER ADVOCATE.

(a) Establishment.--There is established in the Department
of the Treasury an office to be known as the ``Office of the
Homeowner Advocate'' (in this subtitle referred to as the
``Office'').
(b) Director.--
(1) In general.--The Director of the Office of the
Homeowner Advocate (in this subtitle referred to as the
``Director'') shall report directly to the Assistant
Secretary of the Treasury for Financial Stability, and shall
be entitled to compensation at the same rate as the highest
rate of basic pay established for the Senior Executive
Service under section 5382 of title 5, United States Code.
(2) Appointment.--The Director shall be appointed by the
Secretary, after consultation with the Secretary of the
Department of Housing and Urban Development, and without
regard to the provisions of title 5, United States Code,
relating to appointments in the competitive service or the
Senior Executive Service.
(3) Qualifications.--An individual appointed under
paragraph (2) shall have--
(A) experience as an advocate for homeowners; and
(B) experience dealing with mortgage servicers.
(4) Restriction on employment.--An individual may be
appointed as Director only if such individual was not an
officer or employee of either a mortgage servicer or the
Department of the Treasury during the 4-year period preceding
the date of such appointment.
(5) Hiring authority.--The Director shall have the
authority to hire staff, obtain support by contract, and
manage the budget of the Office of the Homeowner Advocate.

SEC. 1092. FUNCTIONS OF THE OFFICE.

(a) In General.--It shall be the function of the Office of
the Homeowner Advocate to--
(1) assist homeowners, housing counselors, and housing
lawyers in resolving problems with the Home Affordable
Modification Program of the Making Home Affordable initiative
of the Secretary, authorized under the Emergency Economic
Stabilization Act of 2008 (in this subtitle referred to as
the ``Home Affordable Modification Program'')
(2) identify areas, both individual and systematic, in
which homeowners, housing counselors, and housing lawyers
have problems in dealings with the Home Affordable
Modification Program;
(3) to the extent possible, propose changes in the
administrative practices of the Home Affordable Modification
Program, to mitigate problems identified under paragraph (2);
(4) identify potential legislative changes which may be
appropriate to mitigate such problems; and
(5) implement other programs and initiatives that the
Director deems important to assisting homeowners, housing
counselors, and housing lawyers in resolving problems with
the Home Affordable Modification Program, which may include--
(A) running a triage hotline for homeowners at risk of
foreclosure;
(B) providing homeowners with access to housing counseling
programs of the Department of Housing and Urban Development
at no cost to the homeowner;
(C) developing Internet tools related to the Home
Affordable Modification Program; and
(D) developing training and educational materials.
(b) Authority.--
(1) In general.--Staff designated by the Director shall
have the authority to implement servicer remedies, on a case-
by-case basis, subject to the approval of the Assistant
Secretary of the Treasury for Financial Stability.
(2) Limitations on foreclosures.--No homeowner may be taken
to a foreclosure sale, until the earlier of the date on which
the Office of the Homeowner Advocate case involving the
homeowner is closed, or 60 days since the opening of the
Office of the Homeowner Advocate case involving the homeowner
have passed, except that nothing in this section may be
construed to relieve any loan servicers from any otherwise
applicable rules, directives, or similar guidance under the
Home Affordable Modification Program relating to the
continuation or completion of foreclosure proceedings.
(3) Resolution of homeowner concerns.--The Office shall, to
the extent possible, resolve all homeowner concerns not later
than 30 days after the opening of a case with such homeowner.
(c) Commencement of Operations.--The Office shall commence
its operations, as required by this subtitle, not later than
3 months after the date of enactment of this Act.
(d) Sunset.--The Office shall cease operations as of the
date on which the Home Affordable Modification Program ceases
to operate.

SEC. 1093. RELATIONSHIP WITH EXISTING ENTITIES.

(a) Transfer.--The Office shall coordinate and centralize
all complaint escalations relating to the Home Affordable
Modification Program.
(b) Hotline.--The HOPE hotline (or any successor triage
hotline) shall reroute all complaints relating to the Home
Affordable Modification Program to the Office.
(c) Coordination.--The Office shall coordinate with the
compliance office of the Office of Financial Stability of the
Department of the Treasury and the Homeownership Preservation
Office of the Department of the Treasury.

SEC. 1094. REPORTS TO CONGRESS.

(a) Testimony.--The Director shall be available to testify
before the Committee on

[[Page S3383]]

Banking, Housing, and Urban Affairs of the Senate and the
Committee on Financial Services of the House of
Representatives, not less frequently than 4 times a year, or
at any time at the request of the Chairs of either committee.
(b) Reports.--Once annually, the Director shall provide a
detailed report to Congress on the Home Affordable
Modification Program. Such report shall contain full and
substantive analysis, in addition to statistical information,
including, at a minimum--
(1) data and analysis of the types and volume of complaints
received from homeowners, housing counselors, and housing
lawyers, broken down by category of servicer, except that
servicers may not be identified by name in the report;
(2) a summary of not fewer than 20 of the most serious
problems encountered by Home Affordable Modification Program
participants, including a description of the nature of such
problems;
(3) to the extent known, identification of the 10 most
litigated issues for Home Affordable Modification Program
participants, including recommendations for mitigating such
disputes;
(4) data and analysis on the resolutions of the complaints
received from homeowners, housing counselors, and housing
lawyers;
(5) identification of any programs or initiatives that the
Office has taken to improve the Home Affordable Modification
Program;
(6) recommendations for such administrative and legislative
action as may be appropriate to resolve problems encountered
by Home Affordable Modification Program participants; and
(7) such other information as the Director may deem
advisable.

SEC. 1095. FUNDING.

Amounts made available for the costs of administration of
the Home Affordable Modification Program that are not
otherwise obligated shall be available to carry out the
duties of the Office. Funding shall be maintained at levels
adequate to reasonably carry out the functions of the Office.
______

SA 3903. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 1051, line 2, after the comma insert the following:
``or, with respect to any such transaction, an institution
that sells or transfers assets, either directly or
indirectly, including through an affiliate, to the Federal
Agricultural Mortgage Corporation for the purpose of
securitization,''.
______

SA 3904. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 487, line 15, after the comma insert ``the Federal
Home Loan Bank System, the Federal Farm Credit Banks Funding
Corporation, the Federal Agricultural Mortgage
Corporation,''.
______

SA 3905. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

Beginning on page 648, strike line 11 and all that follows
through page 649, line 2, and insert the following:

stitutions shall contain a capital requirement that is
greater than zero.
______

SA 3906. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 855, strike lines 8 through 20 and insert the
following:

tain a capital requirement that is greater than zero.
______

SA 3907. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 577, strike lines 5 through 24.

______

SA 3908. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

Beginning on page 793, strike line 5 and all that follows
through page 794, line 3.
______

SA 3909. Mr. CHAMBLISS submitted an amendment intended to be proposed
to amendment SA 3739 proposed by Mr. Reid (for Mr. Dodd (for himself
and Mrs. Lincoln)) to the bill S. 3217, to promote the financial
stability of the United States by improving accountability and
transparency in the financial system, to end ``too big to fail'', to
protect the American taxpayer by ending bailouts, to protect consumers
from abusive financial services practices, and for other purposes;
which was ordered to lie on the table; as follows:

On page 612, line 24, strike ``burden'' and insert ``burden
on clearing on the derivatives clearing organization''

____________________