S.Amdt. 4797Senate111th Congress (2009-2011)2nd degree
S.Amdt. 4797
Sponsored by 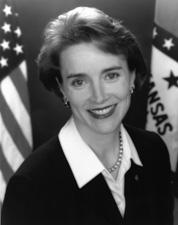 Sen. Blanche L. Lincoln (D-AR)
Submitted December 13, 2010
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
December 13, 2010
Text
Submitted
SA 4797. Mrs. LINCOLN submitted an amendment intended to be proposed
to amendment SA 4753 proposed by Mr. Reid (for himself and Mr.
McConnell) to the bill H.R. 4853, to amend the Internal Revenue Code of
1986 to extend the funding and expenditure authority of the Airport and
Airway Trust Fund, to amend title 49, United States Code, to extend
authorizations for the airport improvement program, and for other
purposes; which was ordered to lie on the table; as follows:

On page 71, between lines 3 and 4, insert the following:

SEC. 760A. TIMBER REIT MODERNIZATION.

(a) In General.--Paragraph (8) of section 856(c) is amended
by striking ``means'' and all that follows and inserting
``means December 31, 2011.''.
(b) Conforming Amendments.--
(1) Subparagraph (I) of section 856(c)(2) is amended by
striking ``the first taxable year

[[Page S8928]]

beginning after the date of the enactment of this
subparagraph'' and inserting ``a taxable year beginning on or
before the termination date''.
(2) Clause (iii) of section 856(c)(5)(H) is amended by
inserting ``in taxable years beginning'' after
``dispositions''.
(3) Clause (v) of section 857(b)(6)(D) is amended by
inserting ``in a taxable year beginning'' after ``sale''.
(4) Subparagraph (G) of section 857(b)(6) is amended by
inserting ``in a taxable year beginning'' after ``In the case
of a sale''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years ending after May 22, 2009.

SEC. 760B. REDUCTION IN CORPORATE RATE FOR QUALIFIED TIMBER
GAIN.

(a) In General.--Paragraph (1) of section 1201(b) is
amended by striking `` `ending' '' and all that follows
through `` `such date' ''.
(b) Conforming Amendment.--Paragraph (3) of section 1201(b)
is amended to read as follows:
``(3) Application of subsection.--The qualified timber gain
for any taxable year shall not exceed the qualified timber
gain which would be determined by not taking into account any
portion of such taxable year after December 31, 2011.''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years ending after May 22, 2009.
______