To provide a point of order against legislation that has the effect of imposing a greater tax liability on taxpayers who are married than if such taxpayers had filed individual tax returns.
What it does: Adds SEC. __. POINT OF ORDER ON LEGISLATION THAT IMPOSES A MARRIAGE TAX PENALTY at the end of subtitle A of title III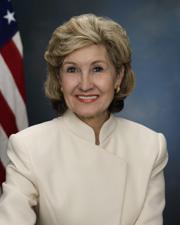 Sen. Kay Bailey Hutchison (R-TX)
What it changes
1 change to S.Con.Res. 13 · shown in the resolution's text
Adds SEC. __. POINT OF ORDER ON LEGISLATION THAT IMPOSES A MARRIAGE TAX PENALTY at the end of subtitle A of title III
Adds a sectionIn S.Con.Res. 13 · Placed on Calendar Senate
(e) Form of the Point of Order.--When the Senate is considering a conference report on, or an amendment between the Houses in relation to, a bill, upon a point of order being made by any Senator pursuant to this section, and such point of order being sustained, such material contained in such conference report or amendment shall be deemed stricken, and the Senate shall proceed to consider the question of whether the Senate shall recede from its amendment and concur with a further amendment, or concur in the House amendment with a further amendment, as the case may be, which further amendment shall consist of only that portion of the conference report or House amendment, as the case may be, not so stricken. Any such motion shall be debatable. In any case in which such point of order is sustained against a conference report (or Senate amendment derived from such conference report by operation of this subsection), no further amendment shall be in order.
Inserted: SEC. __. POINT OF ORDER ON LEGISLATION THAT IMPOSES A MARRIAGE TAX PENALTY.
Inserted: (a) In General.--In the Senate, it shall not be in order, to consider any bill, joint resolution, amendment, motion, or conference report that includes any provision which imposes or increases a marriage tax penalty.
Inserted: (b) Definition.--In this section, the term "marriage penalty" means any provision under which the Federal income tax liability of taxpayers filing a joint return under section 6013 of the Internal Revenue Code of 1986 is greater than such tax liability of such taxpayers if such taxpayers were unmarried and had filed individual tax returns under section 1(c) of such Code.
Inserted: (c) Waiver.--This section may be waived or suspended only by an affirmative vote of three-fifths of the Members, dully chosen and sworn.
Inserted: (d) Appeals.--An affirmative vote of three-fifths of the Members of the Senate, duly chosen and sworn, shall be required to sustain an appeal of the ruling of the Chair on a point of order raised under this section.
Original wording
At the end of subtitle A of title III, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 866. Mrs. HUTCHISON (for herself, Mr. Martinez, Mr. Vitter, Mr. Enzi, Mr. Cornyn, and Mr. Brownback) submitted an amendment intended to be proposed by her to the concurrent resolution S. Con. Res. 13, setting forth the congressional budget for the United States Government for fiscal year 2010, revising the appropriate budgetary levels for fiscal year 2009, and setting forth the appropriate budgetary levels for fiscal years 2011 through 2014; which was ordered to lie on the table; as follows:
At the end of subtitle A of title III, insert the following:
SEC. __. POINT OF ORDER ON LEGISLATION THAT IMPOSES A MARRIAGE TAX PENALTY.
(a) In General.--In the Senate, it shall not be in order, to consider any bill, joint resolution, amendment, motion, or conference report that includes any provision which imposes or increases a marriage tax penalty.
(b) Definition.--In this section, the term “marriage penalty” means any provision under which the Federal income tax liability of taxpayers filing a joint return under section 6013 of the Internal Revenue Code of 1986 is greater than such tax liability of such taxpayers if such taxpayers were unmarried and had filed individual tax returns under section 1(c) of such Code.
(c) Waiver.--This section may be waived or suspended only by an affirmative vote of three-fifths of the Members, dully chosen and sworn.
(d) Appeals.--An affirmative vote of three-fifths of the Members of the Senate, duly chosen and sworn, shall be required to sustain an appeal of the ruling of the Chair on a point of order raised under this section.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 866 proposed by Senator Hutchison.(consideration: CR S4259-4260; text: CR S4259-4260)
April 2, 2009
View full timeline
Senate amendment proposed (on the floor): Amendment SA 866 proposed by Senator Hutchison.(consideration: CR S4259-4260; text: CR S4259-4260)
April 2, 2009
Senate amendment agreed to: Amendment SA 866 agreed to in Senate by Voice Vote.
April 2, 2009
Amendment SA 866 proposed by Senator Hutchison. (consideration: CR S4259-4260; text: CR S4259-4260) To provide a point of order against legislation that has the effect of imposing a greater tax liability on taxpayers who are married than if such taxpayers had filed individual tax returns.
April 2, 2009
Amendment SA 866 agreed to in Senate by Voice Vote.
April 2, 2009
Senate amendment submitted
April 1, 2009