To make technical corrections to the State option to provide dental-only supplemental coverage.
What it does: Adds SEC. --. INCOME TAX DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN wherever appropriate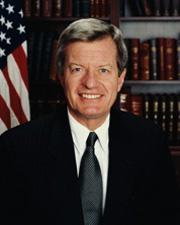 Sen. Max Baucus (D-MT)
Adds SEC. --. INCOME TAX DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN wherever appropriate
Adds a sectionInserted: SEC. --. INCOME TAX DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN.
Inserted: (a) In General.--Part VII of subchapter A of chapter 1 of subtitle A of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by redesignating section 224 as section 225, and
Inserted: (2) by inserting after section 223 the following new section:
Inserted: "SEC. 224. DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN.
Inserted: "(a) Deduction Allowed.--In the case of an individual who is an eligible taxpayer, there shall be allowed as a deduction for the taxable year an amount equal to so much of the qualified child health care costs of the taxpayer for the taxable year as does not exceed the amount that is--
Inserted: "(1) $1,500, multiplied by
Inserted: "(2) the number of qualifying children of the taxpayer.
Inserted: "(b) Definitions.--For purposes of this section--
Inserted: "(1) Eligible taxpayer.--The term 'eligible taxpayer' means a taxpayer whose taxable income for the taxable year does not exceed the exemption amount applicable to such taxpayer under section 55(d) for such taxable year.
Inserted: "(2) Qualified child health care costs.--The term 'qualified child health care costs' means the aggregate amount paid by the taxpayer for medical care (as defined in section 213(d)) for all qualifying children of the taxpayer.
Inserted: "(3) Qualifying child.--The term 'qualifying child' has the meaning given such term by section 24(c).
Show 11 more inserted paragraphsShow less
Inserted: "(c) Identification Requirement.--No deduction shall be allowed under this section to a taxpayer with respect to any qualifying child unless the taxpayer includes the name and taxpayer identification number of such qualifying child on the return of tax for the taxable year.
Inserted: "(d) Denial of Double Benefit.--The amount of the deduction otherwise allowed under this section with respect to any qualifying child for any taxable year shall be reduced by the amount of any deduction allowed under section 213 with respect to such child for such taxable year.
Inserted: "(e) Coordination With SCHIP and Other Health Benefits.--No deduction shall be allowed under this section to a taxpayer with respect to any qualifying child if such child is eligible for any benefit under any health assistance program funded in whole or in part with Federal funds.".
Inserted: (b) Above-the-Line Deduction.--Subsection (a) of section 62 of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(22) Deduction for health care costs of certain children.--The deduction allowed by section 224.".
Inserted: (c) Clerical Amendments.--The table of sections for part VII of subchapter A of chapter 1 of subtitle A of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by striking the item relating to section 224, and
Inserted: (2) by adding at the end the following new items:
Inserted: "Sec. 224. Deduction for health care costs of certain children.
Inserted: "Sec. 225. Cross reference.".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2008.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 95. Mr. DeMINT (for himself and Mr. Vitter) submitted an amendment intended to be proposed by him to the bill H.R. 2, to amend title XXI of the Social Security Act to extend and improve the Children's Health Insurance Program, and for other purposes; as follows:
At the appropriate place, insert the following:
SEC. --. INCOME TAX DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN.
(a) In General.--Part VII of subchapter A of chapter 1 of subtitle A of the Internal Revenue Code of 1986 is amended--
(1) by redesignating section 224 as section 225, and
(2) by inserting after section 223 the following new section:
“SEC. 224. DEDUCTION FOR HEALTH CARE COSTS OF CERTAIN CHILDREN.
“(a) Deduction Allowed.--In the case of an individual who is an eligible taxpayer, there shall be allowed as a deduction for the taxable year an amount equal to so much of the qualified child health care costs of the taxpayer for the taxable year as does not exceed the amount that is--
“(1) $1,500, multiplied by
“(2) the number of qualifying children of the taxpayer.
“(b) Definitions.--For purposes of this section--
“(1) Eligible taxpayer.--The term ‘eligible taxpayer' means a taxpayer whose taxable income for the taxable year does not exceed the exemption amount applicable to such taxpayer under section 55(d) for such taxable year.
“(2) Qualified child health care costs.--The term ‘qualified child health care costs' means the aggregate amount paid by the taxpayer for medical care (as defined in section 213(d)) for all qualifying children of the taxpayer.
“(3) Qualifying child.--The term ‘qualifying child' has the meaning given such term by section 24(c).
“(c) Identification Requirement.--No deduction shall be allowed under this section to a taxpayer with respect to any qualifying child unless the taxpayer includes the name and taxpayer identification number of such qualifying child on the return of tax for the taxable year.
“(d) Denial of Double Benefit.--The amount of the deduction otherwise allowed under this section with respect to any qualifying child for any taxable year shall be reduced by the amount of any deduction allowed under section 213 with respect to such child for such taxable year.
“(e) Coordination With SCHIP and Other Health Benefits.--No deduction shall be allowed under this section to a taxpayer with respect to any qualifying child if such child is eligible for any benefit under any health assistance program funded in whole or in part with Federal funds.”.
(b) Above-the-Line Deduction.--Subsection (a) of section 62 of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(22) Deduction for health care costs of certain children.--The deduction allowed by section 224.”.
(c) Clerical Amendments.--The table of sections for part VII of subchapter A of chapter 1 of subtitle A of the Internal Revenue Code of 1986 is amended--
(1) by striking the item relating to section 224, and
(2) by adding at the end the following new items:
“Sec. 224. Deduction for health care costs of certain children.
“Sec. 225. Cross reference.”.
(d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2008.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
January 29, 2009
View full timeline
Senate amendment submitted
January 29, 2009
Senate amendment proposed (on the floor): Amendment SA 95 proposed by Senator Baucus.(consideration: CR S1042; text: CR S1042)
January 29, 2009
Senate amendment agreed to: Amendment SA 95 agreed to in Senate by Unanimous Consent.
January 29, 2009
Amendment SA 95 proposed by Senator Baucus. (consideration: CR S1042; text: CR S1042) To make technical corrections to the State option to provide dental-only supplemental coverage.
January 29, 2009
Amendment SA 95 agreed to in Senate by Unanimous Consent.
January 29, 2009