To reauthorize for 1 year the Secure Rural Schools and Community Self-Determination Act of 2000 and to provide full funding for the Payments in Lieu of Taxes program for 1 year, and for other purposes.
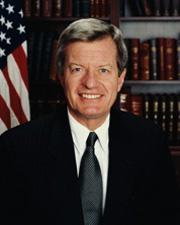 Sen. Max Baucus (D-MT)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 8, 2012
View full timeline
Senate amendment submitted
March 8, 2012
Senate amendment proposed (on the floor): Amendment SA 1825 proposed by Senator Baucus.(consideration: CR S1525-1526, S1527-1528)
March 8, 2012
Roll call votes on amendments in Senate: Amendment SA 1825 under the order of 3/7/2012, having achieved 60 votes in the affirmative, was agreed to in Senate by Yea-Nay Vote. 82 - 16. Record Vote Number: 29.
March 8, 2012
Senate amendment agreed to: Amendment SA 1825 under the order of 3/7/2012, having achieved 60 votes in the affirmative, was agreed to in Senate by Yea-Nay Vote. 82 - 16. Record Vote Number: 29.
March 8, 2012
Amendment SA 1825 proposed by Senator Baucus. (consideration: CR S1525-1526, S1527-1528) To reauthorize for 1 year the Secure Rural Schools and Community Self-Determination Act of 2000 and to provide full funding for the Payments in Lieu of Taxes program for 1 year, and for other purposes.
March 8, 2012
Amendment SA 1825 under the order of 3/7/2012, having achieved 60 votes in the affirmative, was agreed to in Senate by Yea-Nay Vote. 82 - 16. Record Vote Number: 29.
March 8, 2012
Votes
1 roll call on this amendment
Text
Submitted
SA 1825. Mr. BAUCUS (for himself, Mr. Bingaman, Mr. Wyden, Mr.
Merkley, Mr. Tester, Mr. Crapo, Mr. Risch, and Ms. Murkowski) submitted
an amendment intended to be proposed by him to the bill S. 1813, to
reauthorize Federal-aid highway and highway safety construction
programs, and for other purposes; as follows:

At the end of division D, insert the following:

TITLE IV--REAUTHORIZATION OF CERTAIN PROGRAMS

Subtitle A--Secure Rural Schools and Community Self-determination
Program

SEC. 40401. SECURE RURAL SCHOOLS AND COMMUNITY SELF-
DETERMINATION PROGRAM.

(a) Amendments.--The Secure Rural Schools and Community
Self-Determination Act of 2000 (16 U.S.C. 7101 et seq.) is
amended--
(1) in section 3(11)--
(A) in subparagraph (A), by striking ``and'' after the
semicolon at the end;
(B) in subparagraph (B)--
(i) by striking ``fiscal year 2009 and each fiscal year
thereafter'' and inserting ``each of fiscal years 2009
through 2011''; and
(ii) by striking the period at the end and inserting ``;
and''; and
(C) by adding at the end the following:
``(C) for fiscal year 2012 and each fiscal year thereafter,
the amount that is equal to 95 percent of the full funding
amount for the preceding fiscal year.'';
(2) in sections 101, 102, 203, 207, 208, 304, and 402, by
striking ``2011'' each place it appears and inserting
``2012'';
(3) in section 102--
(A) by striking ``2008'' each place it appears and
inserting ``2012'';
(B) in subsection (b)(2)(B), by inserting ``in 2012''
before ``, the election''; and
(C) in subsection (d)--
(i) in paragraph (1)(A), by striking ``paragraph (3)(B)''
and inserting ``subparagraph (D)''; and
(ii) in paragraph (3)--

(I) by striking subparagraph (A) and inserting the
following:

``(A) Notification.--The Governor of each eligible State
shall notify the Secretary concerned of an election by an
eligible county under this subsection not later than
September 30, 2012, and each September 30 thereafter for each
succeeding fiscal year.'';

(II) by redesignating subparagraph (B) as subparagraph (D)
and moving the subparagraph so as to appear at the end of
paragraph (1) of subsection (d); and
(III) by inserting after subparagraph (A) the following:

``(B) Failure to elect.--If the Governor of an eligible
State fails to notify the Secretary concerned of the election
for an eligible county by the date specified in subparagraph
(A)--
``(i) the eligible county shall be considered to have
elected to expend 80 percent of the funds in accordance with
paragraph (1)(A); and
``(ii) the remainder shall be available to the Secretary
concerned to carry out projects in the eligible county to
further the purpose described in section 202(b).'';
(4) in section 103(d)(2), by striking ``fiscal year 2011''
and inserting ``each of fiscal years 2011 and 2012'';
(5) in section 202, by adding at the end the following:
``(c) Administrative Expenses.--A resource advisory
committee may, in accordance with section 203, propose to use
not more than 10 percent of the project funds of an eligible
county for any fiscal year for administrative expenses
associated with operating the resource advisory committee
under this title.'';
(6) in section 204(e)(3)(B)(iii), by striking ``and 2011''
and inserting ``through 2012'';
(7) in section 205(a)(4), by striking ``2006'' each place
it appears and inserting ``2011'';
(8) in section 208(b), by striking ``2012'' and inserting
``2013'';
(9) in section 302(a)(2)(A), by inserting ``and'' after the
semicolon; and
(10) in section 304(b), by striking ``2012'' and inserting
``2013''.
(b) Failure to Make Election.--For each county that failed
to make an election for fiscal year 2011 in accordance with
section 102(d)(3)(A) of the Secure Rural Schools and
Community Self-Determination Act of 2000 (16 U.S.C.
7112(d)(3)(A)), there shall be available to the Secretary of
Agriculture to carry out projects to further the purpose
described in section 202(b) of that Act (16 U.S.C. 7122(b)),
from amounts in the Treasury not otherwise appropriated, the
amount that is equal to 15 percent of the total share of the
State payment that otherwise would have been made to the
county under that Act for fiscal year 2011.

Subtitle B--Payment in Lieu of Taxes Program

SEC. 40411. PAYMENTS IN LIEU OF TAXES.

Section 6906 of title 31, United States Code, is amended by
striking ``2012'' and inserting ``2013''.

[[Page S1545]]

Subtitle C--Offsets

SEC. 40421. TAX REPORTING FOR LIFE SETTLEMENT TRANSACTIONS.

(a) In General.--Subpart B of part III of subchapter A of
chapter 61 of the Internal Revenue Code of 1986 is amended by
adding at the end the following new section:

``SEC. 6050X. RETURNS RELATING TO CERTAIN LIFE INSURANCE
CONTRACT TRANSACTIONS.

``(a) Requirement of Reporting of Certain Payments.--
``(1) In general.--Every person who acquires a life
insurance contract or any interest in a life insurance
contract in a reportable policy sale during any taxable year
shall make a return for such taxable year (at such time and
in such manner as the Secretary shall prescribe) setting
forth--
``(A) the name, address, and TIN of such person,
``(B) the name, address, and TIN of each recipient of
payment in the reportable policy sale,
``(C) the date of such sale,
``(D) the name of the issuer of the life insurance contract
sold and the policy number of such contract, and
``(E) the amount of each payment.
``(2) Statement to be furnished to persons with respect to
whom information is required.--Every person required to make
a return under this subsection shall furnish to each person
whose name is required to be set forth in such return a
written statement showing--
``(A) the name, address, and phone number of the
information contact of the person required to make such
return, and
``(B) the information required to be shown on such return
with respect to such person, except that in the case of an
issuer of a life insurance contract, such statement is not
required to include the information specified in paragraph
(1)(E).
``(b) Requirement of Reporting of Seller's Basis in Life
Insurance Contracts.--
``(1) In general.--Upon receipt of the statement required
under subsection (a)(2) or upon notice of a transfer of a
life insurance contract to a foreign person, each issuer of a
life insurance contract shall make a return (at such time and
in such manner as the Secretary shall prescribe) setting
forth--
``(A) the name, address, and TIN of the seller who
transfers any interest in such contract in such sale,
``(B) the investment in the contract (as defined in section
72(e)(6)) with respect to such seller, and
``(C) the policy number of such contract.
``(2) Statement to be furnished to persons with respect to
whom information is required.--Every person required to make
a return under this subsection shall furnish to each person
whose name is required to be set forth in such return a
written statement showing--
``(A) the name, address, and phone number of the
information contact of the person required to make such
return, and
``(B) the information required to be shown on such return
with respect to each seller whose name is required to be set
forth in such return.
``(c) Requirement of Reporting With Respect to Reportable
Death Benefits.--
``(1) In general.--Every person who makes a payment of
reportable death benefits during any taxable year shall make
a return for such taxable year (at such time and in such
manner as the Secretary shall prescribe) setting forth--
``(A) the name, address, and TIN of the person making such
payment,
``(B) the name, address, and TIN of each recipient of such
payment,
``(C) the date of each such payment, and
``(D) the amount of each such payment.
``(2) Statement to be furnished to persons with respect to
whom information is required.--Every person required to make
a return under this subsection shall furnish to each person
whose name is required to be set forth in such return a
written statement showing--
``(A) the name, address, and phone number of the
information contact of the person required to make such
return, and
``(B) the information required to be shown on such return
with respect to each recipient of payment whose name is
required to be set forth in such return.
``(d) Definitions.--For purposes of this section:
``(1) Payment.--The term `payment' means the amount of cash
and the fair market value of any consideration transferred in
a reportable policy sale.
``(2) Reportable policy sale.--The term `reportable policy
sale' has the meaning given such term in section
101(a)(3)(B).
``(3) Issuer.--The term `issuer' means any life insurance
company that bears the risk with respect to a life insurance
contract on the date any return or statement is required to
be made under this section.
``(4) Reportable death benefits.--The term `reportable
death benefits' means amounts paid by reason of the death of
the insured under a life insurance contract that has been
transferred in a reportable policy sale.''.
(b) Clerical Amendment.--The table of sections for subpart
B of part III of subchapter A of chapter 61 of the Internal
Revenue Code of 1986 is amended by inserting after the item
relating to section 6050W the following new item:

``Sec. 6050X. Returns relating to certain life insurance contract
transactions.''.
(c) Conforming Amendments.--
(1) Subsection (d) of section 6724 of the Internal Revenue
Code of 1986 is amended--
(A) by striking ``or'' at the end of clause (xxiv) of
paragraph (1)(B), by striking ``and'' at the end of clause
(xxv) of such paragraph and inserting ``or'', and by
inserting after such clause (xxv) the following new clause:
``(xxvi) section 6050X (relating to returns relating to
certain life insurance contract transactions), and'', and
(B) by striking ``or'' at the end of subparagraph (GG) of
paragraph (2), by striking the period at the end of
subparagraph (HH) of such paragraph and inserting ``, or'',
and by inserting after such subparagraph (HH) the following
new subparagraph:
``(II) subsection (a)(2), (b)(2), or (c)(2) of section
6050X (relating to returns relating to certain life insurance
contract transactions).''.
(2) Section 6047 of such Code is amended--
(A) by redesignating subsection (g) as subsection (h),
(B) by inserting after subsection (f) the following new
subsection:
``(g) Information Relating to Life Insurance Contract
Transactions.--This section shall not apply to any
information which is required to be reported under section
6050X.'', and
(C) by adding at the end of subsection (h), as so
redesignated, the following new paragraph:
``(4) For provisions requiring reporting of information
relating to certain life insurance contract transactions, see
section 6050X.''.
(d) Effective Date.--The amendments made by this section
shall apply to--
(1) reportable policy sales after December 31, 2012, and
(2) reportable death benefits paid after December 31, 2012.

SEC. 40422. CLARIFICATION OF TAX BASIS OF LIFE INSURANCE
CONTRACTS.

(a) Clarification With Respect to Adjustments.--Paragraph
(1) of section 1016(a) of the Internal Revenue Code of 1986
is amended by striking subparagraph (A) and all that follows
and inserting the following:
``(A) for--
``(i) taxes or other carrying charges described in section
266; or
``(ii) expenditures described in section 173 (relating to
circulation expenditures),
for which deductions have been taken by the taxpayer in
determining taxable income for the taxable year or prior
taxable years; or
``(B) for mortality, expense, or other reasonable charges
incurred under an annuity or life insurance contract;''.
(b) Effective Date.--The amendment made by this section
shall apply to transactions entered into after August 25,
2009.

SEC. 40423. EXCEPTION TO TRANSFER FOR VALUABLE CONSIDERATION
RULES.

(a) In General.--Subsection (a) of section 101 of the
Internal Revenue Code of 1986 is amended by adding at the end
the following new paragraph:
``(3) Exception to valuable consideration rules for
commercial transfers.--
``(A) In general.--The second sentence of paragraph (2)
shall not apply in the case of a transfer of a life insurance
contract, or any interest therein, which is a reportable
policy sale.
``(B) Reportable policy sale.--For purposes of this
paragraph, the term `reportable policy sale' means the
acquisition of an interest in a life insurance contract,
directly or indirectly, if the acquirer has no substantial
family, business, or financial relationship with the insured
apart from the acquirer's interest in such life insurance
contract. For purposes of the preceding sentence, the term
`indirectly' applies to the acquisition of an interest in a
partnership, trust, or other entity that holds an interest in
the life insurance contract.''.
(b) Conforming Amendment.--Paragraph (1) of section 101(a)
of the Internal Revenue Code of 1986 is amended by striking
``paragraph (2)'' and inserting ``paragraphs (2) and (3)''.
(c) Effective Date.--The amendments made by this section
shall apply to transfers after December 31, 2012.

SEC. 40424. PHASED RETIREMENT AUTHORITY.

(a) CSRS.--Chapter 83 of title 5, United States Code, is
amended--
(1) in section 8331--
(A) in paragraph (30) by striking ``and'' at the end;
(B) in paragraph (31) by striking the period at the end and
inserting ``; and''; and
(C) by adding at the end the following:
``(32) `Director' means the Director of the Office of
Personnel Management.'';
(2) by inserting after section 8336 the following:

``Sec.  8336a. Phased retirement

``(a) For the purposes of this section--
``(1) the term `composite retirement annuity' means the
annuity computed when a phased retiree attains full
retirement status;
``(2) the term `full retirement status' means that a phased
retiree has ceased employment and is entitled, upon
application, to a composite retirement annuity;
``(3) the term `phased employment' means the less-than-
full-time employment of a phased retiree;
``(4) the term `phased retiree' means a retirement-eligible
employee who--
``(A) makes an election under subsection (b); and
``(B) has not entered full retirement status;

[[Page S1546]]

``(5) the term `phased retirement annuity' means the
annuity payable under this section before full retirement;
``(6) the term `phased retirement percentage' means the
percentage which, when added to the working percentage for a
phased retiree, produces a sum of 100 percent;
``(7) the term `phased retirement period' means the period
beginning on the date on which an individual becomes entitled
to receive a phased retirement annuity and ending on the date
on which the individual dies or separates from phased
employment;
``(8) the term `phased retirement status' means that a
phased retiree is concurrently employed in phased employment
and eligible to receive a phased retirement annuity;
``(9) the term `retirement-eligible employee'--
``(A) means an individual who, if the individual separated
from the service, would meet the requirements for retirement
under subsection (a) or (b) of section 8336; and
``(B) does not include--
``(i) an individual who, if the individual separated from
the service, would meet the requirements for retirement under
subsection (c), (e), (m), or (n) of section 8336; or
``(ii) a law enforcement officer, firefighter, nuclear
materials courier, air traffic controller, customs and border
protection officer, or member of the Capitol Police or
Supreme Court Police; and
``(10) the term `working percentage' means the percentage
of full-time employment equal the quotient obtained by
dividing--
``(A) the number of hours per pay period to be worked by a
phased retiree as scheduled in accordance with subsection
(b)(2); by
``(B) the number of hours per pay period to be worked by an
employee serving in a comparable position on a full-time
basis.
``(b)(1) With the concurrence of the head of the employing
agency, and under regulations promulgated by the Director, a
retirement-eligible employee who has been employed on a full
time basis for not less than the 3-year period ending on the
date on which the retirement-eligible employee makes an
election under this subsection may elect to enter phased
retirement status.
``(2)(A) Subject to subparagraph (B), at the time of
entering phased retirement status, a phased retiree shall be
appointed to a position for which the working percentage is
50 percent.
``(B) The Director may, by regulation, provide for working
percentages different from the percentage specified under
subparagraph (A), which shall be not less than 20 percent and
not more than 80 percent.
``(C) The working percentage for a phased retiree may not
be changed during the phased retiree's phased retirement
period.
``(D)(i) Not less than 20 percent of the hours to be worked
by a phased retiree shall consist of mentoring.
``(ii) The Director may, by regulation, provide for
exceptions to the requirement under clause (i).
``(3) A phased retiree--
``(A) may not be employed in more than one position at any
time; and
``(B) may transfer to another position in the same or a
different agency, if the transfer does not result in a change
in the working percentage.
``(4) A retirement-eligible employee may make only one
election under this subsection during the retirement-eligible
employee's lifetime.
``(5) A retirement-eligible employee who makes an election
under this subsection may not make an election under section
8343a.
``(c)(1) Except as otherwise provided under this
subsection, the phased retirement annuity for a phased
retiree is the product obtained by multiplying--
``(A) the amount of an annuity computed under section 8339
that would have been payable to the phased retiree if, on the
date on which the phased retiree enters phased retirement
status, the phased retiree had separated from service and
retired under section 8336(a) or (b); by
``(B) the phased retirement percentage for the phased
retiree.
``(2) A phased retirement annuity shall be paid in addition
to the basic pay for the position to which a phased retiree
is appointed during phased employment.
``(3) A phased retirement annuity shall be adjusted in
accordance with section 8340.
``(4)(A) A phased retirement annuity shall not be subject
to reduction for any form of survivor annuity, shall not
serve as the basis of the computation of any survivor
annuity, and shall not be subject to any court order
requiring a survivor annuity to be provided to any
individual.
``(B) A phased retirement annuity shall be subject to a
court order providing for division, allotment, assignment,
execution, levy, attachment, garnishment, or other legal
process on the same basis as other annuities.
``(5) Any reduction of a phased retirement annuity based on
an election under section 8334(d)(2) shall be applied to the
phased retirement annuity after computation under paragraph
(1).
``(6)(A) Any deposit, or election of an actuarial annuity
reduction in lieu of a deposit, for military service or for
creditable civilian service for which retirement deductions
were not made or refunded shall be made by a retirement-
eligible employee at or before the time the retirement-
eligible employee enters phased retirement status. No such
deposit may be made, or actuarial adjustment in lieu thereof
elected, at the time a phased retiree enters full retirement
status.
``(B) Notwithstanding subparagraph (A), if a phased retiree
does not make such a deposit and dies in service as a phased
retiree, a survivor of the phased retiree shall have the same
right to make such deposit as would have been available had
the employee not entered phased retirement status and died in
service.
``(C) If a phased retiree makes an election for an
actuarial annuity reduction under section 8334(d)(2) and dies
in service as a phased retiree, the amount of any deposit
upon which such actuarial reduction shall have been based
shall be deemed to have been fully paid.
``(7) A phased retirement annuity shall commence on the
date on which a phased retiree enters phased employment.
``(8) No unused sick leave credit may be used in the
computation of the phased retirement annuity.
``(d) All basic pay not in excess of the full-time rate of
pay for the position to which a phased retiree is appointed
shall be deemed to be basic pay for purposes of section 8334.
``(e) Under such procedures as the Director may prescribe,
a phased retiree may elect to enter full retirement status at
any time. Upon making such an election, a phased retiree
shall be entitled to a composite retirement annuity.
``(f)(1) Except as provided otherwise under this
subsection, a composite retirement annuity is a single
annuity computed under regulations prescribed by the
Director, equal to the sum of--
``(A) the amount of the phased retirement annuity as of the
date of full retirement, before any reduction based on an
election under section 8334(d)(2), and including any
adjustments made under section 8340; and
``(B) the product obtained by multiplying--
``(i) the amount of an annuity computed under section 8339
that would have been payable at the time of full retirement
if the individual had not elected a phased retirement and as
if the individual was employed on a full-time basis in the
position occupied during the phased retirement period and
before any reduction for survivor annuity or reduction based
on an election under section 8334(d)(2); by
``(ii) the working percentage.
``(2) After computing a composite retirement annuity under
paragraph (1), the Director shall adjust the amount of the
annuity for any applicable reductions for a survivor annuity
and any previously elected actuarial reduction under section
8334(d)(2).
``(3) A composite retirement annuity shall be adjusted in
accordance with section 8340, except that subsection (c)(1)
of that section shall not apply.
``(4) In computing a composite retirement annuity under
paragraph (1)(B)(i), the unused sick leave to the credit of a
phased retiree at the time of entry into full retirement
status shall be adjusted by dividing the number of hours of
unused sick leave by the working percentage.
``(g)(1) Under such procedures and conditions as the
Director may provide, and with the concurrence of the head of
the employing agency, a phased retiree may elect to terminate
phased retirement status and return to a full-time work
schedule.
``(2) Upon entering a full-time work schedule based upon an
election under paragraph (1), the phased retirement annuity
of a phased retiree shall terminate.
``(3) After the termination of a phased retirement annuity
under this subsection, the individual's rights under this
subchapter shall be determined based on the law in effect at
the time of any subsequent separation from service. For
purposes of this subchapter or chapter 84, at time of the
subsequent separation from service, the phased retirement
period shall be treated as if it had been a period of part-
time employment with the work schedule described in
subsection (b)(2).
``(h) For purposes of section 8341--
``(1) the death of a phased retiree shall be deemed to be
the death in service of an employee; and
``(2) the phased retirement period shall be deemed to have
been a period of part-time employment with the work schedule
described in subsection (b)(2).
``(i) Employment of a phased retiree shall not be deemed to
be part-time career employment, as defined in section
3401(2).
``(j) A phased retiree is not eligible to apply for an
annuity under section 8337.
``(k) For purposes of section 8341(h)(4), retirement shall
be deemed to occur on the date on which a phased retiree
enters into full retirement status.
``(l) For purposes of sections 8343 and 8351, and
subchapter III of chapter 84, a phased retiree shall be
deemed to be an employee.
``(m) A phased retiree is not subject to section 8344.
``(n) For purposes of chapter 87, a phased retiree shall be
deemed to be receiving basic pay at the rate of a full-time
employee in the position to which the phased retiree is
appointed.''; and
(3) in the table of sections by inserting after the item
relating to section 8336 the following:

``8336a. Phased retirement.''.
(b) FERS.--Chapter 84 of title 5, United States Code, is
amended--
(1) by inserting after section 8412 the following new
section:

``Sec.  8412a. Phased retirement

``(a) For the purposes of this section--
``(1) the term `composite retirement annuity' means the
annuity computed when a phased retiree attains full
retirement status;

[[Page S1547]]

``(2) the term `full retirement status' means that a phased
retiree has ceased employment and is entitled, upon
application, to a composite retirement annuity;
``(3) the term `phased employment' means the less-than-
full-time employment of a phased retiree;
``(4) the term `phased retiree' means a retirement-eligible
employee who--
``(A) makes an election under subsection (b); and
``(B) has not entered full retirement status;
``(5) the term `phased retirement annuity' means the
annuity payable under this section before full retirement;
``(6) the term `phased retirement percentage' means the
percentage which, when added to the working percentage for a
phased retiree, produces a sum of 100 percent;
``(7) the term `phased retirement period' means the period
beginning on the date on which an individual becomes entitled
to receive a phased retirement annuity and ending on the date
on which the individual dies or separates from phased
employment;
``(8) the term `phased retirement status' means that a
phased retiree is concurrently employed in phased employment
and eligible to receive a phased retirement annuity;
``(9) the term `retirement-eligible employee'--
``(A) means an individual who, if the individual separated
from the service, would meet the requirements for retirement
under subsection (a) or (b) of section 8412; and
``(B) does not include--
``(i) an individual who, if the individual separated from
the service, would meet the requirements for retirement under
subsection (d) or (e) of section 8412; or
``(ii) a law enforcement officer, firefighter, nuclear
materials courier, air traffic controller, customs and border
protection officer, or member of the Capitol Police or
Supreme Court Police; and
``(10) the term `working percentage' means the percentage
of full-time employment equal to the quotient obtained by
dividing--
``(A) the number of hours per pay period to be worked by a
phased retiree as scheduled in accordance with subsection
(b)(2); by
``(B) the number of hours per pay period to be worked by an
employee serving in a comparable position on a full-time
basis.
``(b)(1) With the concurrence of the head of the employing
agency, and under regulations promulgated by the Director, a
retirement-eligible employee who has been employed on a full
time basis for not less than the 3-year period ending on the
date on which the retirement-eligible employee makes an
election under this subsection may elect to enter phased
retirement status.
``(2)(A) Subject to subparagraph (B), at the time of
entering phased retirement status, a phased retiree shall be
appointed to a position for which the working percentage is
50 percent.
``(B) The Director may, by regulation, provide for working
percentages different from the percentage specified under
subparagraph (A), which shall be not less than 20 percent and
not more than 80 percent.
``(C) The working percentage for a phased retiree may not
be changed during the phased retiree's phased retirement
period.
``(D)(i) Not less than 20 percent of the hours to be worked
by a phased retiree shall consist of mentoring.
``(ii) The Director may, by regulation, provide for
exceptions to the requirement under clause (i).
``(3) A phased retiree--
``(A) may not be employed in more than one position at any
time; and
``(B) may transfer to another position in the same or a
different agency, if the transfer does not result in a change
in the working percentage.
``(4) A retirement-eligible employee may make only one
election under this subsection during the retirement-eligible
employee's lifetime.
``(5) A retirement-eligible employee who makes an election
under this subsection may not make an election under section
8420a.
``(c)(1) Except as otherwise provided under this
subsection, the phased retirement annuity for a phased
retiree is the product obtained by multiplying--
``(A) the amount of an annuity computed under section 8415
that would have been payable to the phased retiree if, on the
date on which the phased retiree enters phased retirement
status, the phased retiree had separated from service and
retired under section 8412 (a) or (b); by
``(B) the phased retirement percentage for the phased
retiree.
``(2) A phased retirement annuity shall be paid in addition
to the basic pay for the position to which a phased retiree
is appointed during the phased employment.
``(3) A phased retirement annuity shall be adjusted in
accordance with section 8462.
``(4)(A) A phased retirement annuity shall not be subject
to reduction for any form of survivor annuity, shall not
serve as the basis of the computation of any survivor
annuity, and shall not be subject to any court order
requiring a survivor annuity to be provided to any
individual.
``(B) A phased retirement annuity shall be subject to a
court order providing for division, allotment, assignment,
execution, levy, attachment, garnishment, or other legal
process on the same basis as other annuities.
``(5)(A) Any deposit, or election of an actuarial annuity
reduction in lieu of a deposit, for military service or for
creditable civilian service for which retirement deductions
were not made or refunded, shall be made by a retirement-
eligible employee at or before the time the retirement-
eligible employee enters phased retirement status. No such
deposit may be made, or actuarial adjustment in lieu thereof
elected, at the time a phased retiree enters full retirement
status.
``(B) Notwithstanding subparagraph (A), if a phased retiree
does not make such a deposit and dies in service as a phased
retiree, a survivor of the phased retiree shall have the same
right to make such deposit as would have been available had
the employee not entered phased retirement status and died in
service.
``(6) A phased retirement annuity shall commence on the
date on which a phased retiree enters phased employment.
``(7) No unused sick leave credit may be used in the
computation of the phased retirement annuity.
``(d) All basic pay not in excess of the full-time rate of
pay for the position to which a phased retiree is appointed
shall be deemed to be basic pay for purposes of section 8422
and 8423.
``(e) Under such procedures as the Director may prescribe,
a phased retiree may elect to enter full retirement status at
any time. Upon making such an election, a phased retiree
shall be entitled to a composite retirement annuity.
``(f)(1) Except as provided otherwise under this
subsection, a composite retirement annuity is a single
annuity computed under regulations prescribed by the
Director, equal to the sum of--
``(A) the amount of the phased retirement annuity as of the
date of full retirement, including any adjustments made under
section 8462; and
``(B) the product obtained by multiplying--
``(i) the amount of an annuity computed under section 8412
that would have been payable at the time of full retirement
if the individual had not elected a phased retirement and as
if the individual was employed on a full-time basis in the
position occupied during the phased retirement period and
before any adjustment to provide for a survivor annuity; by
``(ii) the working percentage;
``(2) After computing a composite retirement annuity under
paragraph (1), the Director shall adjust the amount of the
annuity for any applicable reductions for a survivor annuity.
``(3) A composite retirement annuity shall be adjusted in
accordance with section 8462, except that subsection (c)(1)
of that section shall not apply.
``(4) In computing a composite retirement annuity under
paragraph (1)(B)(i), the unused sick leave to the credit of a
phased retiree at the time of entry into full retirement
status shall be adjusted by dividing the number of hours of
unused sick leave by the working percentage.
``(g)(1) Under such procedures and conditions as the
Director may provide, and with the concurrence of the head of
employing agency, a phased retiree may elect to terminate
phased retirement status and return to a full-time work
schedule.
``(2) Upon entering a full-time work schedule based on an
election under paragraph (1), the phased retirement annuity
of a phased retiree shall terminate.
``(3) After termination of the phased retirement annuity
under this subsection, the individual's rights under this
chapter shall be determined based on the law in effect at the
time of any subsequent separation from service. For purposes
of this chapter, at the time of the subsequent separation
from service, the phased retirement period shall be treated
as if it had been a period of part-time employment with the
work schedule described in subsection (b)(2).
``(h) For purposes of subchapter IV--
``(1) the death of a phased retiree shall be deemed to be
the death in service of an employee;
``(2) except for purposes of section 8442(b)(1)(A)(i), the
phased retirement period shall be deemed to have been a
period of part-time employment with the work schedule
described in subsection (b)(2) of this section; and
``(3) for purposes of section 8442(b)(1)(A)(i), the phased
retiree shall be deemed to have been at the full-time rate of
pay for the position occupied.
``(i) Employment of a phased retiree shall not be deemed to
be part-time career employment, as defined in section
3401(2).
``(j) A phased retiree is not eligible to receive an
annuity supplement under section 8421.
``(k) For purposes of subchapter III, a phased retiree
shall be deemed to be an employee.
``(l) For purposes of section 8445(d), retirement shall be
deemed to occur on the date on which a phased retiree enters
into full retirement status.
``(m) A phased retiree is not eligible to apply for an
annuity under subchapter V.
``(n) A phased retiree is not subject to section 8468.
``(o) For purposes of chapter 87, a phased retiree shall be
deemed to be receiving basic pay at the rate of a full-time
employee in the position to which the phased retiree is
appointed.''; and
(2) in the table of sections by inserting after the item
relating to section 8412 the following:

``8412a. Phased retirement.''.

(c) Effective Date.--The amendments made by this section
shall take effect on the effective date of the implementing
regulations issued by the Director of the Office of Personnel
Management.

[[Page S1548]]

SEC. 40425. ROLL-YOUR-OWN CIGARETTE MACHINES.

(a) In General.--Subsection (d) of section 5702 of the
Internal Revenue Code of 1986 is amended by adding at the end
the following new flush sentence:
``Such term shall include any person who for commercial
purposes makes available for consumer use (including such
consumer's personal consumption or use under paragraph (1)) a
machine capable of making cigarettes, cigars, or other
tobacco products. A person making such a machine available
for consumer use shall be deemed the person making the
removal as defined by subsection (j) with respect to any
tobacco products manufactured by such machine.''.
(b) Effective Date.--The amendment made by this section
shall apply to articles removed after the date of the
enactment of this Act.
______