S.Amdt. 3645
What it does: Adds SEC. __. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS at the end of the bill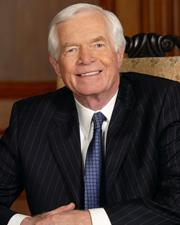 Sen. Thad Cochran (R-MS)
What it changes
1 change to S. 2569 · shown in the bill's text
Adds SEC. __. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS at the end of the bill
Adds a sectionIn S. 2569 · Placed on Calendar Senate
(d) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred after the date of the enactment of this Act.
Inserted: SEC. __. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS.
Inserted: (a) Allowance of Credit.--
Inserted: (1) In general.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by adding at the end the following new section:
Inserted: "SEC. 45S. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS.
Inserted: "(a) In General.--For purposes of section 38, in the case of a shrimp harvester or shrimp processor, the shrimp production and efficiency improvements credit determined under this section for the taxable year shall be an amount equal to $0.50 per pound of wild-caught shrimp lawfully harvested or processed by the taxpayer during the taxable year.
Inserted: "(b) Definitions.--For purposes of this section
Inserted: "(1) Shrimp harvester.--The term 'shrimp harvester' means any vessel with a valid commercial license issued by any State or territory of the United States to harvest shrimp from a wild fishery.
Inserted: "(2) Shrimp processor.--The term 'shrimp processor' means any facility located within the United States with a valid processing license for processing shrimp.
Inserted: "(3) Pound.--The term 'pound' means, with respect to wild-caught shrimp, the round (whole) weight by pound of the wild-caught shrimp, or if such shrimp is not in whole form, the weight by pound of such shrimp equivalent to the round (whole) weight of such shrimp, based on the conversion factors used by the National Marine Fisheries Service. In the case of a shrimp processor, the weight of wild-caught shrimp shall be determined before processing operations are undertaken.
Inserted: "(4) Wild-caught shrimp.--The term 'wild-caught shrimp' means shrimp that qualifies as 'wild fish' according to section 281(9) of the Agricultural Marketing Act of 1946 ( 7 U.S.C. 1638(9)).
Inserted: "(c) Termination.--This section shall not apply to wild-caught shrimp harvested or processed after December 31, 2019.".
Inserted: (2) Credit to be part of general business credit.--
Show 10 more inserted paragraphsShow less
Inserted: (A) In general.--Subsection (b) of section 38 of such Code is amended by striking "plus" at the end of paragraph (35), by striking the period at the end of paragraph (36) and inserting ", plus", and by adding at the end the following new paragraph:
Inserted: "(37) the shrimp production and efficiency improvements credit determined under section 45S(a).".
Inserted: (B) Credit allowable against alternative minimum tax.--Subparagraph (B) of section 38(c)(4) of such Code is amended by redesignating clauses (vii) through (ix) as clauses (viii) through (x), respectively, and by inserting after clause (vi) the following new clause:
Inserted: "(vii) the credit determined under section 45S,".
Inserted: (3) Clerical amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of such Code is amended by adding at the end the following new item:
Inserted: "Sec. 45S. Credit for shrimp production and efficiency improvements.".
Inserted: (4) Effective date.--The amendments made by this subsection shall apply to wild-caught shrimp (as defined in section 45S(b)(4) of the Internal Revenue Code of 1986, as added by this section) harvested or processed after the date of the enactment of this Act, in taxable years ending after such date.
Inserted: (b) Modification to Child Tax Credit Requiring Proof of Citizenship or Residence.--
Inserted: (1) In general.--Subsection (e) of section 24 of the Internal Revenue Code of 1986 is amended by adding "and includes with such return information (in such form and manner as the Secretary prescribes) which establishes that the qualifying child is a citizen, national, or resident of the United States" before the period at the end thereof.
Inserted: (2) Effective date.--The amendment made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Original wording
At the end, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3645. Mr. COCHRAN submitted an amendment intended to be proposed by him to the bill S. 2569, to provide an incentive for businesses to bring jobs back to America; which was ordered to lie on the table; as follows:
At the end, add the following:
SEC. __. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS.
(a) Allowance of Credit.--
(1) In general.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by adding at the end the following new section:
“SEC. 45S. CREDIT FOR SHRIMP PRODUCTION AND EFFICIENCY IMPROVEMENTS.
“(a) In General.--For purposes of section 38, in the case of a shrimp harvester or shrimp processor, the shrimp production and efficiency improvements credit determined under this section for the taxable year shall be an amount equal to $0.50 per pound of wild-caught shrimp lawfully harvested or processed by the taxpayer during the taxable year.
“(b) Definitions.--For purposes of this section
“(1) Shrimp harvester.--The term ‘shrimp harvester' means any vessel with a valid commercial license issued by any State or territory of the United States to harvest shrimp from a wild fishery.
“(2) Shrimp processor.--The term ‘shrimp processor' means any facility located within the United States with a valid processing license for processing shrimp.
“(3) Pound.--The term ‘pound' means, with respect to wild-caught shrimp, the round (whole) weight by pound of the wild-caught shrimp, or if such shrimp is not in whole form, the weight by pound of such shrimp equivalent to the round (whole) weight of such shrimp, based on the conversion factors used by the National Marine Fisheries Service. In the case of a shrimp processor, the weight of wild-caught shrimp shall be determined before processing operations are undertaken.
“(4) Wild-caught shrimp.--The term ‘wild-caught shrimp' means shrimp that qualifies as ‘wild fish' according to section 281(9) of the Agricultural Marketing Act of 1946 ( 7 U.S.C. 1638(9)).
“(c) Termination.--This section shall not apply to wild-caught shrimp harvested or processed after December 31, 2019.”.
(2) Credit to be part of general business credit.--
(A) In general.--Subsection (b) of section 38 of such Code is amended by striking “plus” at the end of paragraph (35), by striking the period at the end of paragraph (36) and inserting “, plus”, and by adding at the end the following new paragraph:
“(37) the shrimp production and efficiency improvements credit determined under section 45S(a).”.
(B) Credit allowable against alternative minimum tax.--Subparagraph (B) of section 38(c)(4) of such Code is amended by redesignating clauses (vii) through (ix) as clauses (viii) through (x), respectively, and by inserting after clause (vi) the following new clause:
“(vii) the credit determined under section 45S,”.
(3) Clerical amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of such Code is amended by adding at the end the following new item:
“Sec. 45S. Credit for shrimp production and efficiency improvements.”.
(4) Effective date.--The amendments made by this subsection shall apply to wild-caught shrimp (as defined in section 45S(b)(4) of the Internal Revenue Code of 1986, as added by this section) harvested or processed after the date of the enactment of this Act, in taxable years ending after such date.
(b) Modification to Child Tax Credit Requiring Proof of Citizenship or Residence.--
(1) In general.--Subsection (e) of section 24 of the Internal Revenue Code of 1986 is amended by adding “and includes with such return information (in such form and manner as the Secretary prescribes) which establishes that the qualifying child is a citizen, national, or resident of the United States” before the period at the end thereof.
(2) Effective date.--The amendment made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 24, 2014