S.Amdt. 3689
What it does: Adds TITLE II--EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE at the end of the bill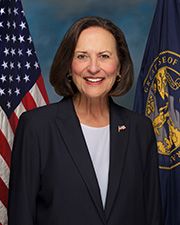 Sen. Deb Fischer (R-NE)
What it changes
1 change to S. 2569 · shown in the bill's text
Adds TITLE II--EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE at the end of the bill
Adds a titleIn S. 2569 · Placed on Calendar Senate
(d) Effective Date.--The amendments made by this section shall apply to amounts paid or incurred after the date of the enactment of this Act.
Inserted: TITLE II--EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE
Inserted: SEC. 201. SHORT TITLE.
Inserted: This title may be cited as the "Strong Families Act"
Inserted: SEC. 202. EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE.
Inserted: (a) In General.--
Inserted: (1) Allowance of credit.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by adding at the end the following new section:
Inserted: "SEC. 45S. EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE.
Inserted: "(a) In General.--For purposes of section 38, in the case of an eligible employer, the paid family and medical leave credit is an amount equal to 25 percent of the amount of wages paid to qualifying employees during any period in which such employees are on family and medical leave.
Inserted: "(b) Limitations.--
Inserted: "(1) In general.--The credit allowed under subsection (a) with respect to any employee for any taxable year shall not exceed the lesser of--
Inserted: "(A) $4,000, or
Inserted: "(B) the product of the wages normally paid to such employee for each hour (or fraction thereof) of services performed for the employer and the number of hours (or fraction thereof) for which family and medical leave is taken.
Show 35 more inserted paragraphsShow less
Inserted: For purposes of subparagraph (B), in the case of any employee who is not paid on an hourly basis, the wages of such employee shall be prorated to an hourly basis under regulations established by the Secretary, in consultation with the Secretary of Labor.
Inserted: "(2) Maximum amount of leave subject to credit.--The amount of family and medical leave that may be taken into account with respect to any employee under subsection (a) for any taxable year shall not exceed 12 weeks.
Inserted: "(c) Eligible Employer.--For purposes of this section--
Inserted: "(1) In general.--The term 'eligible employer' means any employer who has in place a policy that meets the following requirements:
Inserted: "(A) The policy provides--
Inserted: "(i) all qualifying full-time employees with not less than 4 weeks of annual paid family and medical leave, and
Inserted: "(ii) all qualifying employees who are not full-time employees with an amount of annual paid family and medical leave that bears the same ratio to 4 weeks as--
Inserted: "(I) the number of hours the employee is expected to work during any week, bears to
Inserted: "(II) the number of hours an equivalent qualifying full-time employee is expected to work during the week.
Inserted: "(B) The policy requires that the rate of payment under the program is not less than 100 percent of the wages normally paid to such employee for services performed for the employer.
Inserted: "(2) Special rule for certain employers.--
Inserted: "(A) In general.--An added employer shall not be treated as an eligible employer unless such employer provides paid family and medical leave under a policy with a provision that states that the employer--
Inserted: "(i) will not interfere with, restrain, or deny the exercise of or the attempt to exercise, any right provided under the policy, and
Inserted: "(ii) will not discharge or in any other manner discriminate against any individual for opposing any practice prohibited by the policy.
Inserted: "(B) Added employer; added employee.--For purposes of this paragraph--
Inserted: "(i) Added employee.--The term 'added employee' means a qualifying employee who is not covered by title I of the Family and Medical Leave Act of 1993.
Inserted: "(ii) Added employer.--The term 'added employer' means an eligible employer (determined without regard to this paragraph), whether or not covered by that title I, who offers paid family and medical leave to added employees.
Inserted: "(3) Treatment of state-paid benefits.--For purposes of paragraph (1), any leave which is paid by a State or local government shall not be taken into account in determining the amount of paid family and medical leave provided by the employer.
Inserted: "(4) No inference.--Nothing in this subsection shall be construed as subjecting an employer to any penalty, liability, or other consequence (other than ineligibility for the credit allowed by reason of subsection (a)) for failure to comply with the requirements of this subsection.
Inserted: "(d) Qualifying Employees.--For purposes of this section, the term 'qualifying employee' means any employee (as defined in section 3(e) of the Fair Labor Standards Act of 1938) who has been employed by the employer for 1 year or more.
Inserted: "(e) Family and Medical Leave.--For purposes of this section, the term 'family and medical leave' means leave for any purpose described under subparagraph (A), (B), (C), (D), or (E) of paragraph (1), or paragraph (3), of section 102(a) of the Family and Medical Leave Act of 1993, whether the leave is provided under that Act or by a policy of the employer. Such term shall not include any leave provided as paid vacation leave, personal leave, or medical or sick leave (within the meaning of those 3 terms under section 102(d)(2) of that Act).
Inserted: "(f) Wages.--For purposes of this section, the term 'wages' has the meaning given such term by subsection (b) of section 3306 (determined without regard to any dollar limitation contained in such section). Such term shall not include any amount taken into account for purposes of determining any other credit allowed under this subpart.
Inserted: "(g) Election to Have Credit Not Apply.--
Inserted: "(1) In general.--A taxpayer may elect to have this section not apply for any taxable year.
Inserted: "(2) Other rules.--Rules similar to the rules of paragraphs (2) and (3) of section 51(j) shall apply for purposes of this subsection.".
Inserted: (b) Credit Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 is amended by striking "plus" at the end of paragraph (35), by striking the period at the end of paragraph (36) and inserting ", plus", and by adding at the end the following new paragraph:
Inserted: "(37) in the case of an eligible employer (as defined in section 45S(c)), the paid family and medical leave credit determined under section 45S(a).".
Inserted: (c) Credit Allowed Against AMT.--Subparagraph (B) of section 38(c)(4) of the Internal Revenue Code of 1986 is amended by redesignating clauses (vii) through (ix) as clauses (vii) through (x), respectively, and by inserting after clause (vi) the following new clause:
Inserted: "(vii) the credit determined under section 45S,".
Inserted: (d) Conforming Amendments.--
Inserted: (1) Denial of double benefit.--Section 280C(a) of the Internal Revenue Code of 1986 is amended by inserting "45S(a)," after "45P(a),".
Inserted: (2) Election to have credit not apply.--Section 6501(m) of such Code is amended by inserting "45S(g)," after "45H(g),".
Inserted: (3) Clerical amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of such Code is amended by adding at the end the following new item:
Inserted: "Sec. 45S. Employer credit for paid family and medical leave.".
Inserted: (e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Original wording
At the end, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3689. Mrs. FISCHER (for herself and Mr. King) submitted an amendment intended to be proposed by her to the bill S. 2569, to provide an incentive for businesses to bring jobs back to America; which was ordered to lie on the table; as follows:
At the end, insert the following:
TITLE II--EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE
SEC. 201. SHORT TITLE.
This title may be cited as the “Strong Families Act”
SEC. 202. EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE.
(a) In General.--
(1) Allowance of credit.--Subpart D of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 is amended by adding at the end the following new section:
“SEC. 45S. EMPLOYER CREDIT FOR PAID FAMILY AND MEDICAL LEAVE.
“(a) In General.--For purposes of section 38, in the case of an eligible employer, the paid family and medical leave credit is an amount equal to 25 percent of the amount of wages paid to qualifying employees during any period in which such employees are on family and medical leave.
“(b) Limitations.--
“(1) In general.--The credit allowed under subsection (a) with respect to any employee for any taxable year shall not exceed the lesser of--
“(A) $4,000, or
“(B) the product of the wages normally paid to such employee for each hour (or fraction thereof) of services performed for the employer and the number of hours (or fraction thereof) for which family and medical leave is taken.
For purposes of subparagraph (B), in the case of any employee who is not paid on an hourly basis, the wages of such employee shall be prorated to an hourly basis under regulations established by the Secretary, in consultation with the Secretary of Labor.
“(2) Maximum amount of leave subject to credit.--The amount of family and medical leave that may be taken into account with respect to any employee under subsection (a) for any taxable year shall not exceed 12 weeks.
“(c) Eligible Employer.--For purposes of this section--
“(1) In general.--The term ‘eligible employer' means any employer who has in place a policy that meets the following requirements:
“(A) The policy provides--
“(i) all qualifying full-time employees with not less than 4 weeks of annual paid family and medical leave, and
“(ii) all qualifying employees who are not full-time employees with an amount of annual paid family and medical leave that bears the same ratio to 4 weeks as--
“(I) the number of hours the employee is expected to work during any week, bears to
“(II) the number of hours an equivalent qualifying full-time employee is expected to work during the week.
“(B) The policy requires that the rate of payment under the program is not less than 100 percent of the wages normally paid to such employee for services performed for the employer.
“(2) Special rule for certain employers.--
“(A) In general.--An added employer shall not be treated as an eligible employer unless such employer provides paid family and medical leave under a policy with a provision that states that the employer--
“(i) will not interfere with, restrain, or deny the exercise of or the attempt to exercise, any right provided under the policy, and
“(ii) will not discharge or in any other manner discriminate against any individual for opposing any practice prohibited by the policy.
“(B) Added employer; added employee.--For purposes of this paragraph--
“(i) Added employee.--The term ‘added employee' means a qualifying employee who is not covered by title I of the Family and Medical Leave Act of 1993.
“(ii) Added employer.--The term ‘added employer' means an eligible employer (determined without regard to this paragraph), whether or not covered by that title I, who offers paid family and medical leave to added employees.
“(3) Treatment of state-paid benefits.--For purposes of paragraph (1), any leave which is paid by a State or local government shall not be taken into account in determining the amount of paid family and medical leave provided by the employer.
“(4) No inference.--Nothing in this subsection shall be construed as subjecting an employer to any penalty, liability, or other consequence (other than ineligibility for the credit allowed by reason of subsection (a)) for failure to comply with the requirements of this subsection.
“(d) Qualifying Employees.--For purposes of this section, the term ‘qualifying employee' means any employee (as defined in section 3(e) of the Fair Labor Standards Act of 1938) who has been employed by the employer for 1 year or more.
“(e) Family and Medical Leave.--For purposes of this section, the term ‘family and medical leave' means leave for any purpose described under subparagraph (A), (B), (C), (D), or (E) of paragraph (1), or paragraph (3), of section 102(a) of the Family and Medical Leave Act of 1993, whether the leave is provided under that Act or by a policy of the employer. Such term shall not include any leave provided as paid vacation leave, personal leave, or medical or sick leave (within the meaning of those 3 terms under section 102(d)(2) of that Act).
“(f) Wages.--For purposes of this section, the term ‘wages' has the meaning given such term by subsection (b) of section 3306 (determined without regard to any dollar limitation contained in such section). Such term shall not include any amount taken into account for purposes of determining any other credit allowed under this subpart.
“(g) Election to Have Credit Not Apply.--
“(1) In general.--A taxpayer may elect to have this section not apply for any taxable year.
“(2) Other rules.--Rules similar to the rules of paragraphs (2) and (3) of section 51(j) shall apply for purposes of this subsection.”.
(b) Credit Part of General Business Credit.--Section 38(b) of the Internal Revenue Code of 1986 is amended by striking “plus” at the end of paragraph (35), by striking the period at the end of paragraph (36) and inserting “, plus”, and by adding at the end the following new paragraph:
“(37) in the case of an eligible employer (as defined in section 45S(c)), the paid family and medical leave credit determined under section 45S(a).”.
(c) Credit Allowed Against AMT.--Subparagraph (B) of section 38(c)(4) of the Internal Revenue Code of 1986 is amended by redesignating clauses (vii) through (ix) as clauses (vii) through (x), respectively, and by inserting after clause (vi) the following new clause:
“(vii) the credit determined under section 45S,”.
(d) Conforming Amendments.--
(1) Denial of double benefit.--Section 280C(a) of the Internal Revenue Code of 1986 is amended by inserting “45S(a),” after “45P(a),”.
(2) Election to have credit not apply.--Section 6501(m) of such Code is amended by inserting “45S(g),” after “45H(g),”.
(3) Clerical amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 of such Code is amended by adding at the end the following new item:
“Sec. 45S. Employer credit for paid family and medical leave.”.
(e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 24, 2014