S.Amdt. 2761Senate114th Congress (2015-2017)
S.Amdt. 2761
Sponsored by 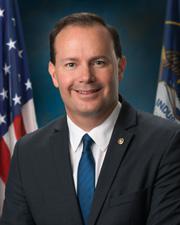 Sen. Mike Lee (R-UT)
Submitted October 29, 2015
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
October 29, 2015
View full timeline
Floor
Senate amendment submitted
October 29, 2015
Floor
Senate amendment submitted
October 29, 2015
Text
Submitted
SA 2761. Mr. LEE submitted an amendment intended to be proposed by
him to the bill H.R. 1314, to amend the Internal Revenue Code of 1986
to provide for a right to an administrative appeal relating to adverse
determinations of tax-exempt status of certain organizations; which was
ordered to lie on the table; as follows:

At the end of title VIII, insert the following:

Subtitle E--Private Disability Insurance Plans

SEC. 851. REDUCTION OF PAYROLL TAX FOR ENROLLMENT IN A
PRIVATE DISABILITY INSURANCE PLAN.

(a) Self-employment Income Tax.--Section 1401 of the
Internal Revenue Code of 1986 is amended--
(1) in subsection (a), by striking ``In addition to'' and
inserting ``Except as provided in subsection (d), in addition
to'', and
(2) by adding at the end the following new subsection:
``(d) Reduction of Tax Rate for Self-employed Individuals
Who Are Enrolled in a Private Disability Insurance Plan.--
``(1) In general.--For any self-employment income received
in any calendar year after 2015 by an applicable individual,
the tax imposed under subsection (a) for each taxable year
shall be equal to--
``(A) for the first calendar year in which such individual
is enrolled in a private disability insurance plan which
satisfies the requirements in paragraph (3), 11.5 percent,
and
``(B) for any subsequent calendar year in which such
individual is enrolled in a private disability insurance
plan, 12.15 percent.
``(2) Penalty rate for termination of coverage.--In the
case of an applicable individual who terminates enrollment in
a private disability insurance plan within 5 years of the
date on which such enrollment began, for any self-employment
income received in the calendar year beginning after the date
of termination, the tax imposed under subsection (a) for any
taxable year beginning in such calendar year shall be equal
to 13.95 percent.
``(3) Applicable individual.--For purposes of this
subsection, the term `applicable individual' means an
individual enrolled in a private disability insurance plan
which satisfies the following requirements:
``(A) The plan shall be subject to regulation and oversight
by the appropriate State insurance regulator.
``(B) The plan shall provide periodic payments to the
enrolled individual which, on an annual basis, are equal to
an amount that is not less than 50 percent of the annual
self-employment income of such individual during the
preceding calendar year.
``(C) The plan shall provide payments to the enrolled
individual for a period of 2 years.
``(D) The plan may not require the enrolled individual to
file an application for disability insurance benefits under
section 223 of the Social Security Act during the first 18
months in which such individual is provided payments under
such plan.
``(E) The plan may, as a condition of receiving payments
under such plan, require the enrolled individual to receive
any medical treatment or vocational rehabilitation which has
been determined as likely to improve the ability of such
individual to return to employment.
``(F) In the case of an individual who has applied for
disability insurance benefits following the period described
in subparagraph (D), the plan shall agree to provide the
Commissioner of Social Security with any records relevant to
the disability determination made under such plan for such
individual.''.
(b) Employer Tax.--Section 3111 of the Internal Revenue
Code of 1986 is amended--

[[Page S7663]]

(1) in subsection (a), by striking ``In addition to'' and
inserting ``Except as provided in subsection (f), in addition
to''; and
(2) by adding at the end of the following new subsection:
``(f) Reduction of Tax Rate for Employers Providing Private
Disability Insurance Plans to Employees.--
``(1) In general.--For any wages paid by an employer in any
calendar year after 2015 to an applicable individual in their
employ, the tax imposed under subsection (a) shall be equal
to--
``(A) for the first calendar year in which such individual
is enrolled in a private disability insurance plan which
satisfies the requirements in paragraph (3), 5.3 percent, and
``(B) for any subsequent calendar year in which such
individual is enrolled in a private disability insurance
plan, 5.95 percent.
``(2) Penalty rate for termination of coverage.--In the
case of an employer who terminates coverage under a private
disability insurance plan for an applicable individual within
5 years of the date on which enrollment in such plan began,
for any wages paid by the employer to such individual
(provided that such individual continues in their employ) in
the calendar year beginning after the date of termination,
the tax imposed under subsection (a) for during such calendar
year shall be equal to 7.75 percent.
``(3) Applicable individual.--For purposes of this
subsection, the term `applicable individual' means an
individual enrolled in a private disability insurance plan
which satisfies the following requirements:
``(A) The plan shall be subject to regulation and oversight
by the appropriate State insurance regulator.
``(B) The plan shall provide periodic payments to the
enrolled individual which, on an annual basis, are equal to
an amount that is not less than 50 percent of the annual
wages paid to such individual during the preceding calendar
year.
``(C) The plan shall provide payments to the enrolled
individual for a period of 2 years.
``(D) The plan may not require the enrolled individual to
file an application for disability insurance benefits under
section 223 of the Social Security Act during the first 18
months in which such individual is provided payments under
such plan.
``(E) The plan may not require the enrolled individual to
contribute to the payment of any insurance premiums for such
plan.
``(F) The plan may, as a condition of receiving payments
under such plan, require the enrolled individual to receive
any medical treatment or vocational rehabilitation which has
been determined as likely to improve the ability of such
individual to return to employment.
``(G) In the case of an individual who has applied for
disability insurance benefits following the period described
in subparagraph (D), the plan shall agree to provide the
Commissioner of Social Security with any records relevant to
the disability determination made under such plan for such
individual.''.
(c) Assistance From Department of Labor.--The Secretary of
the Department of Labor shall provide appropriate guidance
and technical assistance to any State insurance regulator
that requests such guidance and assistance for purposes of
regulation and oversight of private disability insurance
plans described in sections 1401(d)(2) and 3111(f)(2) of the
Social Security Act, as added by this section.
(d) Conforming Amendment.--Section 223(b) of the Social
Security Act (42 U.S.C. 423(b)) is amended by adding at the
end the following: ``An applicable individual (as described
in section 1401(d)(3) or section 3111(f)(3) of the Internal
Revenue Code of 1986) may not file an application for
disability benefits during the first 18 months in which such
individual is provided payments under a private disability
insurance plan which satisfies the requirements under section
1401(d)(3) or section 3111(f)(3) of such Code.''
(e) Effective Date.--The amendments made by this section
shall apply to remuneration paid in any calendar year after
2015.

____________________