To ensure that this Act does not increase the number of uninsured women or increase the number of unintended pregnancies by establishing a women's health care and clinic security and safety fund.
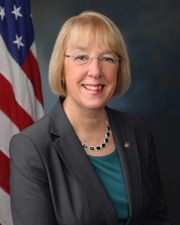 Sen. Patty Murray (D-WA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Motion to table amendment SA 2876 agreed to in Senate by Yea-Nay Vote. 54 - 46. Record Vote Number: 311.(consideration: CR S8341-8342)
December 3, 2015
View full timeline
Roll call votes on amendments in Senate: Motion to table amendment SA 2876 agreed to in Senate by Yea-Nay Vote. 54 - 46. Record Vote Number: 311.(consideration: CR S8341-8342)
December 3, 2015
Considered by Senate. (consideration: CR S8326, S8341-8342)
December 3, 2015
Motion to table amendment SA 2876 agreed to in Senate by Yea-Nay Vote. 54 - 46. Record Vote Number: 311. (consideration: CR S8341-8342)
December 3, 2015
Senate amendment submitted
December 2, 2015
Senate amendment proposed (on the floor): Amendment SA 2876 proposed by Senator Murray to Amendment SA 2874.(consideration: CR S8253-8254, S8255-8264)
December 2, 2015
Senate amendment submitted
December 2, 2015
Amendment SA 2876 proposed by Senator Murray to Amendment SA 2874. (consideration: CR S8253-8254, S8255-8264) To ensure that this Act does not increase the number of uninsured women or increase the number of unintended pregnancies by establishing a women's health care and clinic security and safety fund.
December 2, 2015
Votes
1 roll call on this amendment
Text
Submitted
SA 2876. Mrs. MURRAY (for herself, Mr. Wyden, Mr. Sanders, Mr.
Markey, Mr. Warner, Mr. Coons, and Ms. Stabenow) proposed an amendment
to amendment SA 2874 proposed by Mr. McConnell to the bill H.R. 3762,
to provide for reconciliation pursuant to section 2002 of the
concurrent resolution on the budget for fiscal year 2016; as follows:

Strike section 101 and insert the following:

SEC. 101. SENSE OF THE SENATE.

It is the sense of the Senate that--
(1) comprehensive access to reproductive health care is
critical to improving the health and well-being of women and
their families and is an essential part of their economic
security;
(2) access to affordable contraceptives, including
emergency contraceptives, and medically accurate information
prevents unintended pregnancies, thereby improving the health
of women, children, families, and society as a whole;
(3) it is imperative that women have access to the full
range of reproductive health care services;
(4) women's health care providers, including Planned
Parenthood, provide critical services such as birth control,
cancer screenings, and other services, to millions of men and
women across the United States; and
(5) all women and men should be able to access health care
services without fear or intimidation or threat of violence.

SEC. 101A. WOMEN'S HEALTH CARE AND CLINIC SECURITY AND SAFETY
FUND.

(a) In General.--Title XIX of the Social Security Act (42
U.S.C. 1396 et. seq.) is amended by inserting after section
1941 the following new section:

``women's health care and clinic security and safety fund

``Sec. 1941A.  (a) Establishment.--
``(1) In general.--The Secretary shall establish under this
title a Women's Health Care and Clinic Security and Safety
Fund (in this section referred to as the `Fund') which shall
be available to the Secretary for the purpose of making
payments to women's health clinics or providers for the
provision of eligible services to individuals described in
subsection (b) and for expenditures of women's health clinics
or providers that are attributable to ensuring the security
and safety of such clinics or providers and of their staff
and patients. Payments made from the Fund to women's health
clinics or providers for eligible services or for security
and safety expenditures shall be in addition to any payments
that would otherwise be made to any such clinics or providers
for such services or expenditures.
``(2) Coordination.--The Secretary shall coordinate with
the National Task Force on

[[Page S8309]]

Violence Against Health Care Providers established by the
Attorney General for purposes of submitting an annual report
to Congress on violence against women's health clinics or
providers, including violence against the facilities, staff,
and patients of such clinics or providers, and shall identify
in the report best practices for ensuring the security and
safety of such clinics and providers and their facilities,
staff, and patients.
``(b) Individuals Described.--For purposes of subsection
(a), individuals described in this subsection are any of the
following:
``(1) Any individual who is eligible for medical assistance
under a State plan under this title or a waiver of such plan.
``(2) Any individual who does not have health insurance
coverage.
``(3) Any individual who has health insurance coverage but
is under insured, or who is otherwise determined by a women's
health clinic or provider to need services.
``(c) Definitions.--In this section:
``(1) Eligible services.--The term `eligible services'
means any health care item or service for which medical
assistance is available under any State plan under this title
or under any waiver of any State plan that is in effect on
the date of enactment of this section.
``(2) Women's health clinic or provider defined.--The term
`women's health clinic or provider' means an entity,
including its affiliates, subsidiaries, successors, and
clinics that, as of the date of enactment of this section--
``(A) is an organization described in section 501(c)(3) of
the Internal Revenue Code of 1986 and exempt from tax under
section 501(a) of such Code;
``(B) is an essential community provider described in
section 156.235 of title 45, Code of Federal Regulations (as
in effect on such date of enactment), that is primarily
engaged in family planning services, reproductive health, and
related medical care; and
``(C) provides for abortions, other than an abortion--
``(i) if the pregnancy is the result of an act of rape or
incest; or
``(ii) in the case where a woman suffers from a physical
disorder, physical injury, or physical illness that would, as
certified by a physician, place the woman in danger of death
unless an abortion is performed, including a life-endangering
physical condition caused by or arising from the pregnancy
itself.
``(d) Applications, Determination of Payment Amounts,
Advance Payment.--
``(1) In general.--Not later than March 1, 2016, the
Secretary shall establish a process under which a women's
health provider may request payments from the Fund.
``(2) Determination of payment amounts; advance payment;
retrospective adjustment.--As part of the process established
under paragraph (1), the Secretary shall establish procedures
for--
``(A) ensuring that amounts available for making payments
from the Fund are equitably distributed among all the women's
health clinics or providers that apply for such payments for
a fiscal year;
``(B) making payments under this section for each quarter
of a fiscal year on the basis of advance estimates of
expenditures submitted by women's health clinics or providers
for such payments and such other investigation as the
Secretary may find necessary; and
``(C) making reductions or increases in the payments as
necessary to adjust for any overpayment or underpayment for
prior quarters of such fiscal year.
``(e) Funding.--
``(1) In general.--There shall be available to the Fund,
for expenditures from the Fund, $1,000,000,000 for the period
of fiscal years 2016 through 2025.
``(2) Funding limitation.--Amounts in the Fund shall be
available in advance of appropriations but only if the total
amount obligated from the Fund does not exceed the amount
available to the Fund under paragraph (1). The Secretary may
obligate funds from the Fund only if the Secretary determines
(and the Chief Actuary of the Centers for Medicare & Medicaid
Services and the appropriate budget officer certify) that
there are available in the Fund sufficient amounts to cover
all such obligations incurred consistent with the previous
sentence.''.

SEC. 101B. FAIR SHARE TAX ON HIGH-INCOME TAXPAYERS.

(a) In General.--Subchapter A of chapter 1 of the Internal
Revenue Code of 1986 is amended by adding at the end the
following new part:

``PART VII--FAIR SHARE TAX ON HIGH-INCOME TAXPAYERS

``Sec. 59A. Fair share tax.

``SEC. 59A. FAIR SHARE TAX.

``(a) General Rule.--
``(1) Impositition of tax.--In the case of any high-income
taxpayer, there is hereby imposed for a taxable year (in
addition to any other tax imposed by this subtitle) a tax
equal to the product of--
``(A) the amount determined under paragraph (2), and
``(B) a fraction (not to exceed 1)--
``(i) the numerator of which is the excess of--

``(I) the taxpayer's adjusted gross income, over
``(II) the dollar amount in effect under subsection (c)(1),
and

``(ii) the denominator of which is the dollar amount in
effect under subsection (c)(1).
``(2) Amount of tax.--The amount of tax determined under
this paragraph is an amount equal to the excess (if any) of--
``(A) the tentative fair share tax for the taxable year,
over
``(B) the excess of--
``(i) the sum of--

``(I) the regular tax liability (as defined in section
26(b)) for the taxable year, determined without regard to any
tax liability determined under this section,
``(II) the tax imposed by section 55 for the taxable year,
plus
``(III) the payroll tax for the taxable year, over

``(ii) the credits allowable under part IV of subchapter A
(other than sections 27(a), 31, and 34).
``(b) Tentative Fair Share Tax.--For purposes of this
section--
``(1) In general.--The tentative fair share tax for the
taxable year is 30 percent of the excess of--
``(A) the adjusted gross income of the taxpayer, over
``(B) the modified charitable contribution deduction for
the taxable year.
``(2) Modified charitable contribution deduction.--For
purposes of paragraph (1)--
``(A) In general.--The modified charitable contribution
deduction for any taxable year is an amount equal to the
amount which bears the same ratio to the deduction allowable
under section 170 (section 642(c) in the case of a trust or
estate) for such taxable year as--
``(i) the amount of itemized deductions allowable under the
regular tax (as defined in section 55) for such taxable year,
determined after the application of section 68, bears to
``(ii) such amount, determined before the application of
section 68.
``(B) Taxpayer must itemize.--In the case of any individual
who does not elect to itemize deductions for the taxable
year, the modified charitable contribution deduction shall be
zero.
``(c) High-Income Taxpayer.--For purposes of this section--
``(1) In general.--The term `high-income taxpayer' means,
with respect to any taxable year, any taxpayer (other than a
corporation) with an adjusted gross income for such taxable
year in excess of $1,000,000 (50 percent of such amount in
the case of a married individual who files a separate
return).
``(2) Inflation adjustment.--
``(A) In general.--In the case of a taxable year beginning
after 2016, the $1,000,000 amount under paragraph (1) shall
be increased by an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment determined under
section 1(f)(3) for the calendar year in which the taxable
year begins, determined by substituting `calendar year 2015'
for `calendar year 1992' in subparagraph (B) thereof.
``(B) Rounding.--If any amount as adjusted under
subparagraph (A) is not a multiple of $10,000, such amount
shall be rounded to the next lowest multiple of $10,000.
``(d) Payroll Tax.--For purposes of this section, the
payroll tax for any taxable year is an amount equal to the
excess of--
``(1) the taxes imposed on the taxpayer under sections
1401, 1411, 3101, 3201, and 3211(a) (to the extent such tax
is attributable to the rate of tax in effect under section
3101) with respect to such taxable year or wages or
compensation received during such taxable year, over
``(2) the deduction allowable under section 164(f) for such
taxable year.
``(e) Special Rule for Estates and Trusts.--For purposes of
this section, in the case of an estate or trust, adjusted
gross income shall be computed in the manner described in
section 67(e).
``(f) Not Treated as Tax Imposed by This Chapter for
Certain Purposes.--The tax imposed under this section shall
not be treated as tax imposed by this chapter for purposes of
determining the amount of any credit under this chapter
(other than the credit allowed under section 27(a)) or for
purposes of section 55.''.
(b) Clerical Amendment.--The table of parts for subchapter
A of chapter 1 of the Internal Revenue Code of 1986 is
amended by adding at the end the following new item:

``Part VII--Fair Share Tax on High-Income Taxpayers''.

(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2015.
______