To amend the Internal Revenue Code of 1986 to extend the special rule for seniors relating to the income level for deduction of medical care expenses and to require high-income taxpayers to pay a fair share of taxes.
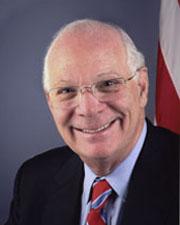 Sen. Benjamin L. Cardin (D-MD)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
December 3, 2015
View full timeline
Senate amendment submitted
December 3, 2015
Senate amendment proposed (on the floor): Amendment SA 2913 proposed by Senator Cardin to Amendment SA 2874.(consideration: CR S8351-8352; text: CR S8351-8352)
December 3, 2015
Senate amendment submitted
December 3, 2015
Senate amendment not agreed to: Amendment SA 2913 not agreed to in Senate by Voice Vote.
December 3, 2015
Amendment SA 2913 proposed by Senator Cardin to Amendment SA 2874. (consideration: CR S8351-8352; text: CR S8351-8352) To amend the Internal Revenue Code of 1986 to extend the special rule for seniors relating to the income level for deduction of medical care expenses and to require high-income taxpayers to pay a fair share of taxes.
December 3, 2015
Amendment SA 2913 not agreed to in Senate by Voice Vote.
December 3, 2015
Text
Submitted
SA 2913. Mr. CARDIN submitted an amendment intended to be proposed to
amendment SA 2874 proposed by Mr. McConnell to the bill H.R. 3762, to
provide for reconciliation pursuant to section 2002 of the concurrent
resolution on the budget for fiscal year 2016; as follows:

At the appropriate place, insert the following:

SEC. ___. EXTENSION OF SPECIAL RULE FOR SENIORS RELATING TO
INCOME LEVEL FOR DEDUCTION OF MEDICAL CARE
EXPENSES.

Subsection (f) of section 213 of the Internal Revenue Code
of 1986 is amended to read as follows:
``(f) Special Rule.--In the case of any taxable year
beginning after December 31, 2012, and ending before January
1, 2024, subsection (a) shall be applied with respect to a
taxpayer by substituting `7.5 percent' for `10 percent' if
such taxpayer or such taxpayer's spouse has attained age 65
before the close of such taxable year.''.

SEC. ___. FAIR SHARE TAX ON HIGH-INCOME TAXPAYERS.

(a) In General.--Subchapter A of chapter 1 of the Internal
Revenue Code of 1986 is amended by adding at the end the
following new part:

``PART VII--FAIR SHARE TAX ON HIGH-INCOME TAXPAYERS

``Sec. 59A. Fair share tax.

``SEC. 59A. FAIR SHARE TAX.

``(a) General Rule.--
``(1) Impositition of tax.--In the case of any high-income
taxpayer, there is hereby imposed for a taxable year (in
addition to any other tax imposed by this subtitle) a tax
equal to the product of--
``(A) the amount determined under paragraph (2), and
``(B) a fraction (not to exceed 1)--
``(i) the numerator of which is the excess of--

``(I) the taxpayer's adjusted gross income, over
``(II) the dollar amount in effect under subsection (c)(1),
and

``(ii) the denominator of which is the dollar amount in
effect under subsection (c)(1).
``(2) Amount of tax.--The amount of tax determined under
this paragraph is an amount equal to the excess (if any) of--
``(A) the tentative fair share tax for the taxable year,
over
``(B) the excess of--
``(i) the sum of--

``(I) the regular tax liability (as defined in section
26(b)) for the taxable year, determined without regard to any
tax liability determined under this section,
``(II) the tax imposed by section 55 for the taxable year,
plus
``(III) the payroll tax for the taxable year, over

``(ii) the credits allowable under part IV of subchapter A
(other than sections 27(a), 31, and 34).
``(b) Tentative Fair Share Tax.--For purposes of this
section--
``(1) In general.--The tentative fair share tax for the
taxable year is 30 percent of the excess of--
``(A) the adjusted gross income of the taxpayer, over
``(B) the modified charitable contribution deduction for
the taxable year.
``(2) Modified charitable contribution deduction.--For
purposes of paragraph (1)--
``(A) In general.--The modified charitable contribution
deduction for any taxable year is an amount equal to the
amount which bears the same ratio to the deduction allowable
under section 170 (section 642(c) in the case of a trust or
estate) for such taxable year as--
``(i) the amount of itemized deductions allowable under the
regular tax (as defined in section 55) for such taxable year,
determined after the application of section 68, bears to
``(ii) such amount, determined before the application of
section 68.
``(B) Taxpayer must itemize.--In the case of any individual
who does not elect to itemize deductions for the taxable
year, the modified charitable contribution deduction shall be
zero.
``(c) High-Income Taxpayer.--For purposes of this section--
``(1) In general.--The term `high-income taxpayer' means,
with respect to any taxable year, any taxpayer (other than a
corporation) with an adjusted gross income for such taxable
year in excess of $1,000,000 (50 percent of such amount in
the case of a married individual who files a separate
return).
``(2) Inflation adjustment.--
``(A) In general.--In the case of a taxable year beginning
after 2016, the $1,000,000 amount under paragraph (1) shall
be increased by an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment determined under
section 1(f)(3) for the calendar year in which the taxable
year begins, determined by substituting `calendar year 2015'
for `calendar year 1992' in subparagraph (B) thereof.
``(B) Rounding.--If any amount as adjusted under
subparagraph (A) is not a multiple of $10,000, such amount
shall be rounded to the next lowest multiple of $10,000.
``(d) Payroll Tax.--For purposes of this section, the
payroll tax for any taxable year is an amount equal to the
excess of--
``(1) the taxes imposed on the taxpayer under sections
1401, 1411, 3101, 3201, and 3211(a) (to the extent such tax
is attributable to the rate of tax in effect under section
3101) with respect to such taxable year or wages or
compensation received during such taxable year, over
``(2) the deduction allowable under section 164(f) for such
taxable year.
``(e) Special Rule for Estates and Trusts.--For purposes of
this section, in the case of an estate or trust, adjusted
gross income shall be computed in the manner described in
section 67(e).
``(f) Not Treated as Tax Imposed by This Chapter for
Certain Purposes.--The tax imposed under this section shall
not be treated as tax imposed by this chapter for purposes of
determining the amount of any credit under this chapter
(other than the credit allowed under section 27(a)) or for
purposes of section 55.''.
(b) Clerical Amendment.--The table of parts for subchapter
A of chapter 1 of the Internal Revenue Code of 1986 is
amended by adding at the end the following new item:

``Part VII--Fair Share Tax on High-Income Taxpayers''.

(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2015.
______