S.Amdt. 2185Senate115th Congress (2017-2019)
S.Amdt. 2185
Sponsored by 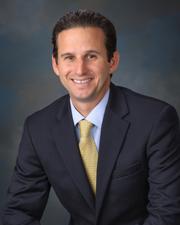 Sen. Brian Schatz (D-HI)
Submitted March 8, 2018
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
March 8, 2018
Text
Submitted
SA 2185. Mr. SCHATZ (for himself, Mr. Brown, and Mr. Blumenthal)
submitted an amendment intended to be proposed by him to the bill S.
2155, to promote economic growth, provide tailored regulatory relief,
and enhance consumer protections, and for other purposes; which was
ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. CREDIT LOCKS.

(a) Credit Locks.--
(1) In general.--The Fair Credit Reporting Act (15 U.S.C.
1681 et seq.) is amended by inserting after section 605B (15
U.S.C. 1681c-2) the following:

[[Page S1611]]

``SEC. 605C. PROTECTION OF CREDIT INFORMATION OF CONSUMERS.

``(a) Secure, Convenient, Accessible, and Cost-Free File
Locks for Consumers.--
``(1) In general.--Subject to paragraph (2), each consumer
reporting agency described in section 603(p) shall provide to
any consumer a secure, convenient, accessible, and cost-free
method that, with the express authorization of the consumer,
allows that consumer reporting agency to release, or prevents
that consumer reporting agency from releasing, any
information in the file of the consumer for the purpose of--
``(A) the marketing or extension of credit or insurance; or
``(B) opening any financial account.
``(2) Prohibitions.--With respect to the method described
in paragraph (1)--
``(A) the method may not be used by the consumer reporting
agency that provides the method, or by any other person, to
collect any information on a consumer that is not necessary
for the purposes of preventing the release of information
described in that paragraph;
``(B) no information collected under the method may be used
for any purpose other than a purpose described in
subparagraph (A);
``(C) in offering the method, a credit reporting agency
described in section 603(p) may not require a consumer to--
``(i) waive any rights of the consumer; or
``(ii) indemnify the credit reporting agency with respect
to any liabilities that arise from offering the method; and
``(D) the method may not be used by any person to market or
advertise any product or service.
``(3) Release of information.--Nothing in this subsection
shall affect the ability of a person with whom a consumer has
an account, contract, or debtor-creditor relationship to
obtain information regarding the consumer for the purposes of
reviewing the account or collecting on the account.
``(b) Regulations.--Not later than 18 months after the date
of enactment of this section, the Bureau shall prescribe
regulations carrying out this section.''.
(2) Table of contents amendment.--The table of contents for
the Fair Credit Reporting Act (15 U.S.C. 1681 et seq.) is
amended by inserting after the item relating to section 605B
the following:

``605C. Protection of credit information of consumers.''.
(b) Permissible Purposes of Credit Reports; Disclosure to
Consumers.--
(1) In general.--The Fair Credit Reporting Act (15 U.S.C.
1681 et seq.) is amended--
(A) in section 604 (15 U.S.C. 1681b)--
(i) in subsection (a)--

(I) in the matter preceding paragraph (1)--

(aa) by striking ``Subject to subsection (c), any'' and
inserting ``Any''; and
(bb) by striking ``a consumer report'' and inserting
``information from the file of a consumer'';

(II) in paragraph (3)--

(aa) by striking subparagraphs (A) and (C);
(bb) by redesignating subparagraph (B) as subparagraph (A);
(cc) by redesignating subparagraphs (D) through (G) as
subparagraphs (B) through (E), respectively; and
(dd) in subparagraph (D), as so redesignated, by striking
``information--'' and all that follows through the period at
the end of clause (ii) and inserting the following:
``information to review an account to determine whether the
consumer continues to meet the terms of the account; or'';
and

(III) by adding at the end the following:

``(7) Pursuant to the express authorization of a consumer,
subject to the method provided under section 605C(a) in the
case of a consumer reporting agency described in section
603(p).'';
(ii) by striking subsection (c); and
(iii) by redesignating subsections (d) through (g) as
subsections (c) through (f), respectively;
(B) in section 609(a)(1) (15 U.S.C. 1681g(a)(1)), by
striking ``request, except that--'' and all that follows
through the period at the end of subparagraph (B) and
inserting the following: ``request, without regard to whether
the information is held by a parent, subsidiary, or affiliate
of the consumer reporting agency.'';
(C) in section 612(a)(1)(A) (15 U.S.C. 1681j(a)(1)(A)), by
striking ``once during any 12-month period''; and
(D) in section 615 (15 U.S.C. 1681m)--
(i) by striking subsection (d); and
(ii) by redesignating subsections (e) through (h) as
subsections (d) through (g), respectively.
(2) Regulations.--Not later than 18 months after the date
of enactment of this Act, the Bureau of Consumer Financial
Protection shall issue regulations carrying out section
609(a)(1) of the Fair Credit Reporting Act (15 U.S.C.
1681g(a)(1)), as amended by paragraph (1)(B).
(3) Technical and conforming amendments.--
(A) Consumer financial protection act of 2010.--Section
1002(12)(F) of the Consumer Financial Protection Act of 2010
(12 U.S.C. 5481(12)(F)) is amended--
(i) by striking ``615(e)'' and inserting ``615(d)''; and
(ii) by striking ``1681m(e)'' and inserting ``1681m(d)''.
(B) Fair credit reporting act.--The Fair Credit Reporting
Act (15 U.S.C. 1681 et seq.) is amended--
(i) in section 603 (15 U.S.C. 1681a)--

(I) in subsection (d)(3), in the matter preceding
subparagraph (A), by striking ``section 604(g)(3)'' and
inserting ``section 604(f)(3)''; and
(II) in subsection (k)(1)(B)--

(aa) in clause (iii), by striking ``section 604(a)(3)(D)''
and inserting ``section 604(a)(3)(B)''; and
(bb) in clause (iv)(I), by striking ``section
604(a)(3)(F)(ii)'' and inserting ``section 604(a)(3)(D)'';
(ii) in section 621 (15 U.S.C. 1681s)--

(I) in subsection (b)(1), in the matter preceding
subparagraph (A), by striking ``persons who furnish
information to such agencies, and users of information that
are subject to section 615(d)'' and inserting ``and persons
who furnish information to such agencies''; and
(II) in subsection (e)(1), in the first sentence, by
striking ``615(e)'' and inserting ``615(d)'';

(iii) in section 623(c)(3) (15 U.S.C. 1681s-2(c)(3)), by
striking ``subsection (e)'' and inserting ``subsection (d)'';
and
(iv) in section 625(b) (15 U.S.C. 1681t(b))--

(I) in paragraph (1)--

(aa) in subparagraph (A), by striking ``subsection (c) or
(e) of section 604'' and inserting ``section 604(d)'';
(bb) by striking subparagraph (D);
(cc) by redesignating subparagraphs (E) through (I) as
subparagraphs (D) through (H), respectively; and
(dd) in subparagraph (H), as so redesignated, by striking
``section 615(h)'' and inserting ``section 615(g)''; and

(II) in paragraph (5)(F), by striking ``(e), (f), and (g)''
and inserting ``(d), (e), and (f)''.

(c) Enhancement of Fraud Alert Protections.--
(1) In general.--Section 605A of the Fair Credit Reporting
Act (15 U.S.C. 1681c-1) is amended--
(A) by striking subsection (a);
(B) by redesignating subsections (b) through (h) as
subsections (a) through (g), respectively;
(C) in subsection (a), as so redesignated--
(i) in the subsection heading, by striking ``Extended'' and
inserting ``Fraud''; and
(ii) in paragraph (1)--

(I) in the matter preceding subparagraph (A), by striking
``submits an identity theft report'' and inserting ``asserts
in good faith a suspicion that the consumer has been or is
about to become a victim of fraud or related crime, including
identity theft, or has been or will be harmed by the
unauthorized disclosure of the financial or personally
identifiable information of the consumer,'';
(II) in subparagraph (A), by striking ``7-year'' and
inserting ``10-year'';
(III) by striking subparagraph (B);
(IV) by redesignating subparagraph (C) as subparagraph (B);
(V) in subparagraph (B), as so redesignated--

(aa) by striking ``extended''; and
(bb) by striking the period at the end and inserting ``;
and''; and

(VI) by adding at the end the following:

``(C) upon the expiration of the period described in
subparagraph (A), or a subsequent 10-year period, and in
response to a direct request by the consumer or such
representative, continue the fraud alert for an additional
period of 10 years if the consumer or such representative
submits an identity theft report.'';
(D) in subsection (b), as so redesignated--
(i) by striking paragraph (2);
(ii) by redesignating paragraphs (1) and (3) as
subparagraphs (A) and (B), respectively, and adjusting the
margins accordingly;
(iii) in the matter preceding subparagraph (A), as so
redesignated, by striking ``Upon the direct request'' and
inserting the following:
``(1) In general.--Upon the direct request''; and
(iv) by adding at the end the following:
``(2) Access to free reports.--If a consumer reporting
agency includes an active duty alert in the file of an active
duty military consumer, the consumer reporting agency shall--
``(A) disclose to the active duty military consumer that
the active duty military consumer may request a free copy of
the file of the active duty military consumer under section
612(d) during each 1-year period beginning on the date on
which the activity duty military alert is requested and
ending on the date of the last day that the active duty alert
applies to the file of the active duty military consumer; and
``(B) not later than 3 business days after the date on
which the active duty military consumer makes a request
described in subparagraph (A), provide to the active duty
military consumer all disclosures required to be made under
section 609, without charge to the active duty military
consumer.'';
(E) by amending subsection (c), as so redesignated, to read
as follows:
``(c) Procedures.--Each consumer reporting agency described
in section 603(p) shall establish and make available to the
public on the Internet website of the consumer reporting
agency policies and procedures to comply with this section,
including policies and procedures--
``(1) that inform consumers of the availability of fraud
alerts, active duty alerts, or the method provided under
section 605C(a), as applicable;
``(2) that allow consumers to request fraud alerts and
active duty alerts in a simple and easy manner; and

[[Page S1612]]

``(3) for asserting in good faith a suspicion that the
consumer has been or is about to become a victim of fraud or
related crime, including identity theft, or has been or will
be harmed by the unauthorized disclosure of the financial or
personally identifiable information of the consumer, for a
consumer requesting a fraud alert.'';
(F) in subsection (d), as so redesignated, by striking
paragraphs (1), (2), and (3) and inserting the following:
``(1) paragraphs (1)(A), (1)(C), and (2) of subsection (a),
in the case of a referral under subsection (a)(1)(B); and
``(2) subsection (b)(1)(A), in the case of a referral under
subsection (b)(1)(B).'';
(G) in subsection (f), as so redesignated, by inserting
``or has been or will be harmed by the unauthorized
disclosure of the financial or personally identifiable
information of the consumer,'' after ``identity theft,''; and
(H) in subsection (g), as so redesignated--
(i) in paragraph (1)--

(I) in the paragraph heading, by striking ``initial'' and
inserting ``fraud alerts'';
(II) in subparagraph (A), by striking ``initial''; and
(III) in subparagraph (B)(i), by striking ``an initial''
and inserting ``a''; and

(ii) in paragraph (2)--

(I) in the paragraph heading, by striking ``extended'' and
inserting ``fraud'';
(II) in subparagraph (A), in the matter preceding clause
(i), by striking ``extended'' and inserting ``fraud''; and
(III) in subparagraph (B), by striking ``an extended'' and
inserting ``a''.

(2) Technical and conforming amendment.--Section 612(d) of
the Fair Credit Reporting Act (15 U.S.C. 1681j(d)) is amended
by striking ``subsections (a)(2) and (b)(2) of section 605A,
as applicable'' and inserting ``section 605A(a)(2)''.
(d) Stopping Errors in Consumer Use and Reporting.--
(1) Legal recourse for consumers.--
(A) Injunctive relief.--The Fair Credit Reporting Act (15
U.S.C. 1681 et seq.) is amended--
(i) in section 616 (15 U.S.C. 1681n)--

(I) in subsection (a), in the subsection heading, by
striking ``(a) In General.--'' and inserting ``(a) Damages.--
'';
(II) by redesignating subsections (c) and (d) as
subsections (d) and (e), respectively; and
(III) by inserting after subsection (b) the following:

``(c) Injunctive Relief.--
``(1) In general.--In addition to any other remedy under
this section, a court may award injunctive relief to require
compliance with the requirements imposed under this title
with respect to any consumer.
``(2) Costs and attorney's fees.--In the event of any
successful action for injunctive relief under this
subsection, a court may award to the prevailing party costs
and reasonable attorney's fees (as determined by the court)
incurred by the prevailing party during the action.''; and
(ii) in section 617 (15 U.S.C. 1681o)--

(I) in subsection (a), in the subsection heading, by
striking ``(a) In General.--'' and inserting ``(a) Damages.--
'';
(II) by redesignating subsection (b) as subsection (c); and
(III) by inserting after subsection (a) the following:

``(b) Injunctive Relief.--
``(1) In general.--In addition to any other remedy under
this section, a court may award injunctive relief to require
compliance with the requirements imposed under this title
with respect to any consumer.
``(2) Costs and attorney's fees.--In the event of any
successful action for injunctive relief under this
subsection, a court may award to the prevailing party costs
and reasonable attorney's fees (as determined by the court)
incurred by the prevailing party during the action.''.
(B) Enforcement by federal trade commission.--Section
621(a)(2)(A) of the Fair Credit Reporting Act (15 U.S.C.
1681s(a)(2)(A)) is amended--
(i) in the subparagraph heading, by striking ``(A) Knowing
violations.--'' and inserting ``(A) Negligent, willful, or
knowing violations.--''; and
(ii) in the first sentence, by inserting ``negligent,
willful, or'' before ``knowing''.
(2) Increased requirements for consumer reporting agencies
and furnishers of information.--
(A) Provision and consideration of documentation provided
by consumers.--The Fair Credit Reporting Act (15 U.S.C. 1681
et seq.) is amended--
(i) in section 611 (15 U.S.C. 1681i)--

(I) in subsection (a)--

(aa) in paragraph (2)--
(AA) in subparagraph (A), in the second sentence, by
inserting ``, including all documentation provided by the
consumer'' after ``received from the consumer or reseller'';
and
(BB) in subparagraph (B), by inserting ``, including all
documentation provided by the consumer,'' after ``from the
consumer or the reseller''; and
(bb) in paragraph (4), by inserting ``, including all
documentation,'' after ``relevant information''; and

(II) in subsection (f)(2)(B)(ii), by inserting ``,
including all documentation,'' after ``relevant
information''; and

(ii) in section 623 (15 U.S.C. 1681s-2)--

(I) in subsection (a)(8)(E), by striking clause (ii) and
inserting the following:

``(ii) review and consider all relevant information,
including all documentation, provided by the consumer with
the notice;''; and

(II) in subsection (b)(1), by striking subparagraph (B) and
inserting the following:

``(B) review and consider all relevant information,
including all documentation, provided by the consumer
reporting agency under section 611(a)(2);''.
(B) Gathering and reporting of information relating to
consumer disputes.--Section 611 of the Fair Credit Reporting
Act (15 U.S.C. 1681i) is amended by adding at the end the
following:
``(g) Gathering and Reporting of Information Relating to
Consumer Disputes.--
``(1) Reports required.--The Bureau shall provide reports
regarding the disputes described in subsection (a)(1)
received by consumer reporting agencies in such intervals and
to such parties as the Bureau deems appropriate.
``(2) Gathering of information.--The Bureau shall prescribe
rules for the gathering of information relating to disputes
described in subsection (a)(1) received by consumer reporting
agencies to be used in generating the reports under paragraph
(1), including rules establishing--
``(A) the type and format of information that the Bureau
shall receive from each consumer reporting agency; and
``(B) the frequency with which the Bureau shall receive the
information from consumer reporting agencies.''.
(C) Accuracy compliance procedures.--Section 607 of the
Fair Credit Reporting Act (15 U.S.C. 1681e) is amended by
striking subsection (b) and inserting the following:
``(b) Accuracy of Report.--
``(1) In general.--A consumer reporting agency shall follow
reasonable procedures when preparing a consumer report to
ensure the maximum possible accuracy of the information
concerning the individual to whom the consumer report
relates.
``(2) Bureau rule to ensure maximum possible accuracy.--
``(A) Proposed rule.--Not later than 1 year after the date
of enactment of the Economic Growth, Regulatory Relief, and
Consumer Protection Act, the Bureau shall issue a proposed
rule establishing the procedures that a consumer reporting
agency shall follow to ensure maximum possible accuracy of
all consumer reports furnished by the agency in compliance
with this subsection.
``(B) Considerations.--When formulating the rule required
under subparagraph (A), the Bureau shall consider if
requiring the matching of the following information would
improve the accuracy of consumer reports:
``(i) The first name and last name of a consumer.
``(ii) The date of birth of a consumer.
``(iii) All 9 digits of the social security number of a
consumer.
``(iv) Any other information that the Bureau determines
would aid in ensuring maximum possible accuracy of all
consumer reports furnished by consumer reporting agencies in
compliance with this subsection.''.
(D) Responsibilities of furnishers of information to
consumer reporting agencies.--Section 623(a)(8)(F)(i)(II) of
the Fair Credit Reporting Act (15 U.S.C. 1681s-
2(a)(8)(F)(i)(II)) is amended by inserting ``, and does not
include any new or additional information that would be
relevant to a reinvestigation'' before the period at the end.
(E) Disclosures to consumers.--Section 609 of the Fair
Credit Reporting Act (15 U.S.C. 1681g) is amended--
(i) in subsection (a)(3)(B)--

(I) in clause (i), by striking ``and'' at the end; and
(II) by striking clause (ii) and inserting the following:

``(ii) the address and telephone number of the person; and
``(iii) the permissible purpose of the person for obtaining
the consumer report, including the specific type of credit
product that is extended, reviewed, or collected, as
described in section 604(a)(3)(A).'';
(ii) in subsection (f)--

(I) by amending paragraph (7)(A) to read as follows:

``(A) supply the consumer with a credit score that--
``(i) is derived from a credit scoring model that is widely
distributed to users by the consumer reporting agency for the
purpose of any extension of credit or other transaction
designated by the consumer who is requesting the credit
score; or
``(ii) is widely distributed to lenders of common consumer
loan products and predicts the future credit behavior of the
consumer; and''; and

(II) in paragraph (8), by inserting ``, except that a
credit score shall be provided free of charge to the consumer
if requested in connection with a free annual consumer report
described in section 612(a)'' before the period at the end;
and

(iii) in subsection (g)(1)--

(I) in subparagraph (A)(ii), by striking ``subparagraph
(D)'' and inserting ``subparagraph (C)'';
(II) in subparagraph (B)(ii), by striking ``consistent with
subparagraph (C)'';
(III) by striking subparagraph (C); and
(IV) by redesignating subparagraphs (D) through (G) as
subparagraphs (C) through (F), respectively.

(F) Notification requirements.--
(i) Adverse information notification.--The Fair Credit
Reporting Act (15 U.S.C. 1681 et seq.) is amended--

(I) in section 612 (15 U.S.C. 1681j), by striking
subsection (b) and inserting the following:

[[Page S1613]]

``(b) Free Disclosure After Notice of Adverse Action or
Offer of Credit on Materially Less Favorable Terms.--
``(1) In general.--Not later than 14 days after the date on
which a consumer reporting agency receives a notification
under subsection (a)(2) or (h)(6) of section 615, or from a
debt collection agency affiliated with the consumer reporting
agency, the consumer reporting agency shall make, without
charge to the consumer, all disclosures required in
accordance with the rules prescribed by the Bureau under
section 609(h).
``(2) Transition period.--During the period beginning on
the effective date of the Stopping Errors in Consumer Use and
Reporting Act of 2017 and ending on the date on which the
Bureau finalizes the rule required under section 609(h), a
consumer reporting agency that is required to make
disclosures under this subsection shall provide to the
consumer a copy of the current credit report on the consumer
and any other disclosures required under this Act or the
Stopping Errors in Consumer Use and Reporting Act of 2017,
without charge to the consumer.''; and

(II) in section 615(a) (15 U.S.C. 1681m(a))--

(aa) by redesignating paragraphs (2), (3), and (4) as
paragraphs (3), (4), and (5), respectively;
(bb) by inserting after paragraph (1) the following:
``(2) direct the consumer reporting agency that provided
the consumer report that was used in the decision to take the
adverse action to provide the consumer with the disclosures
described in section 612(b);''; and
(cc) in paragraph (5), as so redesignated--
(AA) in the matter preceding subparagraph (A), by striking
``of the consumer's right'';
(BB) by striking subparagraph (A) and inserting the
following:
``(A) that the consumer shall receive a copy of the
consumer report with respect to the consumer, free of charge,
from the consumer reporting agency that furnished the
consumer report; and''; and
(CC) in subparagraph (B), by inserting ``of the right of
the consumer'' before ``to dispute''.
(ii) Notification in cases of less favorable terms.--
Section 615(h) of the Fair Credit Reporting Act (15 U.S.C.
1681m(h)) is amended--

(I) in paragraph (1), by striking ``paragraph (6)'' and
inserting ``paragraph (7)'';
(II) in paragraph (2), by striking ``paragraph (6)'' and
inserting ``paragraph (7)'';
(III) in paragraph (5)(C), by striking ``may obtain'' and
inserting ``shall receive'';
(IV) by redesignating paragraphs (6), (7), and (8) as
paragraphs (7), (8), and (9), respectively; and
(V) by inserting after paragraph (5) the following:

``(6) Reports provided to consumers.--A person who uses a
consumer report as described in paragraph (1) shall notify
and direct the consumer reporting agency that provided the
consumer report to provide the consumer with the disclosures
described in section 612(b).''.
(iii) Notification of subsequent submissions of negative
information.--Section 623(a)(7)(A)(ii) of the Fair Credit
Reporting Act (15 U.S.C. 1681s-2(a)(7)(A)(ii)) is amended by
striking ``account, or customer'' and inserting ``or
account''.
(iv) Bureau rule defining certain disclosure
requirements.--Section 609 of the Fair Credit Reporting Act
(15 U.S.C. 1681g) is amended by adding at the end the
following:
``(h) Bureau Rule Defining Certain Disclosure
Requirements.--
``(1) Proposed rule.--Not later than 1 year after the date
of enactment of the Economic Growth, Regulatory Relief, and
Consumer Protection Act, the Bureau shall publish a proposed
rule to implement the disclosure requirements described in
section 612(b).
``(2) Considerations.--In formulating the rule required
under paragraph (1), the Bureau shall consider--
``(A) what information would enable consumers to--
``(i) determine the reasons for which a person--

``(I) took adverse action; or
``(II) offered credit on materially less favorable terms;
and

``(ii) verify the accuracy of that information; and
``(B) how to provide the information described in
subparagraph (A) while protecting consumer privacy, including
procedures to ensure that the information is provided to the
consumer at the appropriate address.''.
(3) Regulatory reform.--Section 621 of the Fair Credit
Reporting Act (15 U.S.C. 1681s) is amended by adding at the
end the following:
``(h) Consumer Reporting Agency Registry.--
``(1) Establishment of registry.--Not later than 180 days
after the date of enactment of the Economic Growth,
Regulatory Relief, and Consumer Protection Act, the Bureau
shall establish 3 publicly available registries of consumer
reporting agencies, including a registry that contains--
``(A) each consumer reporting agency that compiles and
maintains files on consumers on a nationwide basis;
``(B) each nationwide specialty consumer reporting agency;
and
``(C) all other consumer reporting agencies that are not
included under section 603(p) or 603(x).
``(2) Registration requirement.--Each consumer reporting
agency shall register with a registry established by the
Bureau under this subsection in a timeframe established by
the Bureau.''.
(4) Identity theft protection for minors.--
(A) In general.--The Fair Credit Reporting Act (15 U.S.C.
1681 et seq.) is amended by inserting after section 605B (15
U.S.C. 1681c-2) the following:

``SEC. 605C. ADDITIONAL PROTECTIONS FOR CREDIT REPORTS OF
MINOR CONSUMERS.

``(a) Definitions.--In this section--
``(1) the term `blocked file' means a file of a minor
consumer with respect to which, under this section, a
consumer reporting agency--
``(A) maintains with the name, social security number, date
of birth, and, if applicable, any credit information of the
minor consumer;
``(B) may not provide any person with a consumer report of
the minor consumer; and
``(C) blocks the input of any information, except with
permission from a covered guardian of the minor consumer;
``(2) the term `covered guardian' means--
``(A) the legal guardian of a minor child;
``(B) the custodian of a minor child; or
``(C) in the case of a child in foster care, the State
agency or Indian tribe or tribal organization responsible for
the foster care of the child; and
``(3) the term `minor consumer' means a consumer who has
not attained 16 years of age.
``(b) Blocking a File.--A consumer reporting agency that
compiles and maintains files on consumers on a nationwide
basis shall, upon request by, and receipt of appropriate
proof of identity of, a minor consumer or the covered
guardian of a minor consumer--
``(1) create a blocked file for the minor consumer; or
``(2) convert a file of the minor consumer already in
existence to a blocked file.
``(c) Unblocking a File.--A consumer reporting agency that
compiles and maintains files on consumers on a nationwide
basis shall unblock a blocked file--
``(1) upon request by the covered guardian of a minor
consumer;
``(2) if the file was blocked as a result of a material
misrepresentation, including a representation that--
``(A) the consumer was a minor consumer when the consumer
was not a minor consumer as of the date on which the
representation was made; and
``(B) an individual was the covered guardian of a minor
consumer when the individual was not the covered guardian of
the minor consumer as of the date on which the representation
was made;
``(3) on the date of the 16th birthday of the minor
consumer; or
``(4) if the minor consumer becomes emancipated under the
law of the State in which the minor consumer resides, on the
date of the emancipation of the minor consumer.
``(d) Regulations.--The Bureau shall promulgate regulations
to carry out this section.
``(e) Fees.--
``(1) In general.--A credit reporting agency may charge a
fair and reasonable fee, as determined by the Bureau, to
create a blocked file or to unblock a file.
``(2) Exemption.--The Bureau may exempt an individual who
suspects that the individual has been a victim of fraud or
identity theft from a fee described in paragraph (1).
``(f) Exceptions.--Nothing in this section may be construed
as requiring a consumer reporting agency that compiles and
maintains files on consumers on a nationwide basis to prevent
a Federal, State, or local law enforcement agency from
accessing a blocked file.''.
(B) Table of contents amendment.--The table of contents of
the Fair Credit Reporting Act (15 U.S.C. 1681 et seq.) is
amended by inserting after the item relating to section 605B
the following:

``605C. Additional protections for credit reports of minor
consumers.''.
(5) Study of a public credit reporting system.--
(A) Study.--Not later than 180 days after the date of
enactment of this Act, the Comptroller General of the United
States shall conduct a study--
(i) of credit systems in the international credit system
with government-administered consumer credit reporting
systems;
(ii) of available information regarding the accuracy of
government-administered consumer credit reporting systems
that are in existence as of the date on which the Comptroller
General begins conducting the study;
(iii) to evaluate the feasibility of a national,
government-administered consumer credit reporting system;
(iv) of any consumer benefits that might reasonably be
expected to result from a government-administered consumer
credit reporting system; and
(v) of any costs that might result from a government-
administered consumer credit reporting system in the United
States.
(B) Publication of findings.--Not later than 18 months
after the date of enactment of this Act, the Comptroller
General of the United States shall publish the findings of
the study conducted under subparagraph (A).
(6) Effective date.--Except as otherwise provided in this
subsection and the amendments made by this subsection, this
subsection and the amendments made by this subsection shall
take effect on the date that is 180 days after the date of
enactment of this Act.

[[Page S1614]]

______