S.Amdt. 1476Senate116th Congress (2019-2021)2nd degree
S.Amdt. 1476
Sponsored by 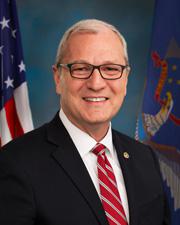 Sen. Kevin Cramer (R-ND)
Submitted March 3, 2020
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
March 3, 2020
Text
Submitted
SA 1476. Mr. CRAMER (for himself and Mr. Cardin) submitted an
amendment intended to be proposed to amendment SA 1407 submitted by Ms.
Murkowski and intended to be proposed to the bill S. 2657, to support
innovation in advanced geothermal research and development, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

TITLE __--NUCLEAR POWER

SEC. _01. SHORT TITLE.

This title may be cited as the ``Nuclear Powers America Act
of 2019''.

SEC. _02. ENERGY CREDIT FOR NUCLEAR ENERGY PROPERTY.

(a) In General.--Section 48(a)(3)(A) of the Internal
Revenue Code of 1986 is amended in clause (vi) by striking
``or'', by inserting ``or'' at the end of clause (vii), and
by adding at the end the following new clause:
``(viii) qualified nuclear energy property,''.
(b) Eligible for 30-Percent Credit.--Section 48(a)(2)(A)(i)
of such Code is amended by striking ``and'' in subclause
(III) and by adding at the end the following new subclause:

``(V) energy property described in paragraph (3)(A)(viii)
but only with respect to property placed in service before
January 1, 2027, and''.

(c) Qualified Nuclear Energy Property.--Section 48(c) of
such Code is amended by adding at the end the following new
paragraph:
``(5) Qualified nuclear energy property.--
``(A) In general.--The term `qualified nuclear energy
property' means any amounts paid or incurred for the
refueling of, and any other expenditures described in section
263(a) with respect to, a qualifying nuclear power plant.
``(B) Qualifying nuclear power plant.--The term `qualifying
nuclear power plant' means a nuclear power plant which--
``(i) submitted an application for license renewal to the
Nuclear Regulatory Commission in accordance with part 54 of
title 10, Code of Federal Regulations, before January 1,
2027, or
``(ii) certified to the Secretary (at such time and in such
form and in such manner as the Secretary prescribes) that
such plant will submit an application for license renewal to
the Nuclear Regulatory Commission in accordance with part 54
of title 10, Code of Federal Regulations, before January 1,
2027.
``(C) Special rules.--
``(i) Basis.--For purposes of subsection (a), the
cumulative amounts paid or incurred by the taxpayer during
the taxable year with respect to a qualifying nuclear power
plant, which are properly chargeable to capital account,
shall be treated as the basis of the

[[Page S1442]]

qualified nuclear energy property placed in service for that
taxable year.
``(ii) Placed in service.--For purposes of subsection (a),
qualified nuclear energy property shall be treated as having
been placed in service on the last day of the taxable year in
which the taxpayer pays or incurs such amounts described in
clause (i).
``(iii) Recapture.--The Secretary shall, by regulations,
provide for recapturing the benefit of any credit allowable
under subsection (a) to any qualifying nuclear power plant
which made a certification pursuant to subparagraph (B) but
does not file an application of license renewal to the
Nuclear Regulatory Commission in accordance with part 54 of
title 10, Code of Federal Regulations, before January 1,
2027.''.
(d) Phaseout of 30-Percent Credit Rate for Nuclear Energy
Property.--Section 48(a) of such Code is amended by adding at
the end the following new paragraph:
``(8) Phaseout for qualified nuclear energy property.--In
the case of qualified nuclear energy property, the energy
percentage determined under paragraph (2) shall be equal to--
``(A) in the case of any property placed in service after
December 31, 2024, and before January 1, 2026, 26 percent,
and
``(B) in the case of any property placed in service after
December 31, 2025, and before January 1, 2027, 22 percent.''.
(e) Coordination With Credit for Production From Advanced
Nuclear Power Facilities.--The last sentence of section
48(a)(3) is amended by inserting ``or 45J'' after ``section
45''.
(f) Transfer of Credit by Certain Public Entities.--
(1) In general.--Section 48 of such Code is amended by
adding at the end the following new subsection:
``(e) Special Rule for Qualified Nuclear Energy Property.--
``(1) In general.--In the case of any qualified nuclear
energy property, if, with respect to a credit under
subsection (a) for any taxable year--
``(A) the taxpayer would be a qualified public entity, and
``(B) such entity elects the application of this subsection
for such taxable year with respect to all (or any portion
specified in such election) of such credit,
the eligible project partner specified in such election (and
not the qualified public entity) shall be treated as the
taxpayer for purposes of this title with respect to such
credit (or such portion thereof).
``(2) Definitions.--For purposes of this subsection--
``(A) Qualified public entity.--The term `qualified public
entity' means--
``(i) a Federal, State, or local government entity, or any
political subdivision, agency, or instrumentality thereof,
``(ii) a mutual or cooperative electric company described
in section 501(c)(12) or section 1381(a)(2), or
``(iii) a not-for-profit electric utility which has or had
received a loan or loan guarantee under the Rural
Electrification Act of 1936.
``(B) Eligible project partner.--The term `eligible project
partner' means--
``(i) any person responsible for operating, maintaining, or
repairing the qualifying nuclear power plant to which the
credit under subsection (a) relates,
``(ii) any person who participates in the provision of the
nuclear steam supply system to the qualifying nuclear power
plant to which the credit under subsection (a) relates,
``(iii) any person who participates in the provision of
nuclear fuel to the qualifying nuclear power plant to which
the credit under subsection (a) relates, or
``(iv) any person who has an ownership interest in such
facility.
``(3) Special rules.--
``(A) Application to partnerships.--In the case of a credit
under subsection (a) which is determined with respect to
qualified nuclear energy property at the partnership level--
``(i) for purposes of paragraph (1)(A), a qualified public
entity shall be treated as the taxpayer with respect to such
entity's distributive share of such credit, and
``(ii) the term `eligible project partner' shall include
any partner of the partnership.
``(B) Taxable year in which credit taken into account.--In
the case of any credit (or portion thereof) with respect to
which an election is made under paragraph (1), such credit
shall be taken into account in the first taxable year of the
eligible project partner ending with, or after, the qualified
public entity's taxable year with respect to which the credit
was determined.
``(C) Treatment of transfer under private use rules.--For
purposes of section 141(b)(1), any benefit derived by an
eligible project partner in connection with an election under
this subsection shall not be taken into account as a private
business use.''.
(2) Special rule for proceeds of transfers for mutual or
cooperative electric companies.--Section 501(c)(12)(I) of
such Code is amended by inserting ``or 48(e)(1)'' after
``section 45J(e)(1)''.
(g) Conforming Amendment.--Section 48(a)(2)(A) of such Code
is amended by striking ``and (7)'' and inserting ``, (7), and
(8)''.
(h) Effective Date.--The amendments made by this section
shall apply to periods after December 31, 2019, in taxable
years ending after such date, under rules similar to the
rules of section 48(m) of the Internal Revenue Code of 1986
(as in effect on the day before the enactment of the Revenue
Reconciliation Act of 1990).
______