S.Amdt. 1482Senate116th Congress (2019-2021)2nd degree
S.Amdt. 1482
Sponsored by 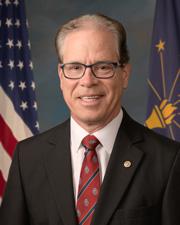 Sen. Mike Braun (R-IN)
Submitted March 4, 2020
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
March 4, 2020
Text
Submitted
SA 1482. Mr. BRAUN (for himself and Ms. Ernst) submitted an amendment
intended to be proposed to amendment SA 1407 proposed by Ms. Murkowski
to the bill S. 2657, to support innovation in advanced geothermal
research and development, and for other purposes; which was ordered to
lie on the table; as follows:

At the end, add the following:

TITLE IV--AMENDMENTS TO THE INTERNAL REVENUE CODE OF 1986

SEC. 4001. ELIMINATION OF PERSONAL CREDIT BASED ON ADJUSTED
GROSS INCOME.

(a) In General.--Subsection (c) of section 30D of the
Internal Revenue Code of 1986 is amended--
(1) in paragraph (2), by inserting ``and (3)'' after
``paragraph (1)'', and
(2) by adding at the end the following new paragraph:
``(3) Elimination of personal credit based on adjusted
gross income.--
``(A) In general.--For purposes of paragraph (2), in the
case of any new qualified plug-in electric drive motor
vehicle which is placed in service by a taxpayer during any
taxable year, if the adjusted gross income of such taxpayer
for such taxable year exceeds the threshold amount, the
amount of the credit otherwise allowable under subsection (a)
for such taxable year shall be reduced to zero.
``(B) Threshold amount.--For purposes of this paragraph,
the term `threshold amount' means--
``(i) in the case of any taxpayer filing a joint return for
the taxable year, $326,600, and
``(ii) in the case of any taxpayer not filing a joint
return for the taxable year, $163,300.
``(C) Inflation adjustment.--
``(i) In general.--In the case of any taxable year
beginning after 2020, each of the dollar amounts in
subparagraph (B) shall be increased by an amount equal to--

``(I) such dollar amount, multiplied by
``(II) the cost-of-living adjustment determined under
section 1(f)(3) for the calendar year in which the taxable
year begins by substituting `calendar year 2019' for
`calendar year 2016' in subparagraph (A)(ii) thereof.

``(ii) Rounding.--If any increase determined under clause
(i) is not a multiple of $100, such increase shall be rounded
to the nearest multiple of $100.''.
(b) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2019.
______