Consumer Identity and Information Security Act of 2003
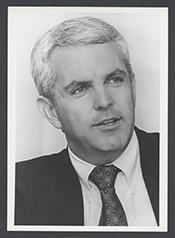 Rep. John B. Shadegg (R-AZ)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Referred to the Subcommittee on Financial Institutions and Consumer Credit.
July 14, 2003
View full timeline
Introduced in House
June 26, 2003
Referred to the Committee on Financial Services, and in addition to the Committees on Ways and Means, and Energy and Commerce, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
June 26, 2003
Referred to the Subcommittee on Social Security.
July 2, 2003
Referred to the Subcommittee on Commerce, Trade and Consumer Protection.
July 11, 2003
Referred to the Subcommittee on Financial Institutions and Consumer Credit.
July 14, 2003
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 2617 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 2617

To protect American consumers from identity theft and other forms of
fraud.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

June 26, 2003

Mr. Shadegg introduced the following bill; which was referred to the
Committee on Financial Services, and in addition to the Committees on
Ways and Means, and Energy and Commerce, for a period to be
subsequently determined by the Speaker, in each case for consideration
of such provisions as fall within the jurisdiction of the committee
concerned

_______________________________________________________________________

A BILL

To protect American consumers from identity theft and other forms of
fraud.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Consumer Identity and Information
Security Act of 2003''.

SEC. 2. PROHIBITED ACTIONS WITH RESPECT TO SOCIAL SECURITY NUMBERS.

(a) Definitions.--For purposes of this section, the following
definitions shall apply:
(1) Display.--The term ``display'' means to intentionally
communicate or otherwise make available (on the Internet or in
any other manner) to the general public an individual's social
security number.
(2) Person.--The term ``person'' means any individual,
partnership, corporation, trust, estate, cooperative,
association, or any other entity.
(3) State.--The term ``State'' means any State of the
United States, the District of Columbia, Puerto Rico, the
Northern Mariana Islands, the United States Virgin Islands,
Guam, American Samoa, and any territory or possession of the
United States.
(b) Prohibited Actions With Respect to an Individual's Social
Security Number.--Subject to subsections (c) and (d), no person may
engage in any of the following:
(1) Display in any manner an individual's social security
number.
(2) Print or otherwise display an individual's social
security number on any card, or other means of access, required
for the individual to access products or services provided by
the person to the individual.
(3) Require an individual to transmit the individual's
social security number over the Internet, unless the connection
is secure or the social security number is encrypted.
(4) Require an individual to use the individual's social
security number to access an Internet Web site, unless a
password, unique personal identification number, or other
authentication device is also required to access the Internet
Web site.
(5) Print or otherwise display an individual's social
security number on any communications by the person to the
individual, unless Federal or State law, or any Federal agency
or any contractor with the Federal Government (under color of
Federal law), requires the individual's social security number
to be included on such documents.
(c) Exception for Certain Communications.--Subsection (b)(5) shall
not apply with respect an individual's social security number included
on documents sent by mail--
(1) in connection with an application or enrollment process
initiated by the individual; or
(2) to establish, amend, or terminate an account held by
the individual with the person; or
(3) to verify the accuracy of the individual's social
security number.
(d) Exception for Prior On-Going Use.--Subsection (b) shall not
apply to the use by a person of an individual's social security number
in a manner that is inconsistent with such subsection if--
(1) the use by such person of the individual's social
security number in such manner began before the date of the
enactment of this Act;
(2) the use by such person of the social security number in
such manner is continuous; and
(3) the person notifies the individual, in writing, before
the end of the 30-day period beginning on the date of the
enactment of this Act and annually thereafter, that the
individual has the right to require such person to stop using
the individual's social security number in a manner
inconsistent with subsection (b).
(e) Individual's Request To Stop Inconsistent Use.--
(1) In general.--If a person receives a written request
from an individual to stop using the individual's social
security number in a manner that is inconsistent with
subsection (b), the person shall fully comply with such request before
the end of the 30-day period beginning on the date of the receipt of
the request.
(2) Denial of products or services prohibited.--A person
may not deny any product or service to an individual, or
otherwise discriminate against such individual in the provision
of any such product or service, solely on the basis that the
individual submitted a request described in paragraph (1).
(f) Coordination With Other Law.--
(1) In general.--No provision of this section shall be
construed as prohibiting or limiting the display or use of an
individual's social security number by any person--
(A) to the extent required or authorized under any
Federal or State law, or by any Federal agency or any
contractor with the Federal Government (under color of
Federal law);
(B) for internal verification or administrative
purposes of the person;
(C) for a public health purpose, including the
protection of the health or safety of an individual in
an emergency situation;
(D) for a national security purpose; or
(E) for a law enforcement purpose, including the
investigation of fraud.
(2) Study and report.--
(A) In general.--The Secretary of Health and Human
Services shall conduct a study and prepare a report on
all of the uses of social security numbers permitted,
required, authorized, or excepted under any Federal law
and State and local uses of social security numbers.
(B) Report.--Not later than 1 year after the date
of enactment of this Act, the Secretary of Health and
Human Services shall submit a report to Congress on the
study conducted under this paragraph.
(C) Contents of report.--The report shall include--
(i) a detailed description of the uses of
an individual's social security number that are
allowed as of the date of enactment of this
Act;
(ii) an evaluation of whether such uses
should be continued or discontinued by
appropriate legislative action; and
(iii) such other recommendations for
legislative or administrative action as the
Secretary determines to be appropriate.
(g) Civil Penalties.--
(1) In general.--Any person who the Attorney General
determines has violated this section shall be subject, in
addition to any other penalties that may be prescribed by law--
(A) to a civil penalty of not less than $5,000 for
each such violation; and
(B) to a civil penalty of not less than $50,000, if
the violations have occurred with such frequency as to
constitute a general business practice.
(2) Determination of violations.--Any knowing violation
committed contemporaneously with respect to the social security
numbers of 2 or more individuals by means of mail,
telecommunication, or otherwise, shall be treated as a separate
violation with respect to each such individual.
(3) Enforcement procedures.--The provisions of section
1128A of the Social Security Act (42 U.S.C. 1320a-7a), other
than subsections (a), (b), (f), (h), (i), (j), (m), and (n) and
the first sentence of subsection (c) of such section, and the
provisions of subsections (d) and (e) of section 205 of such
Act (42 U.S.C. 405) shall apply to a civil penalty action under
this subsection in the same manner as such provisions apply to
a penalty or proceeding under section 1128A(a) of such Act (42
U.S.C. 1320a-7a(a)), except that, for purposes of this
paragraph, any reference in section 1128A of such Act (42
U.S.C. 1320a-7a) to the Secretary shall be deemed to be a
reference to the Attorney General.
(h) Effective Date.--This section shall apply after the end of the
180-day period beginning on the date of the enactment of this Act.

SEC. 3. IMPROPER USE OF CREDIT CARD, DEBIT CARD, AND OTHER PAYMENT
DEVICE NUMBERS.

(a) In General.--Except as provided in subsection (b), no person
that accepts, in connection with the transaction of business, credit
cards, debit cards, or other means of access to a consumer's account
for the purpose of initiating electronic fund transfers shall print, on
any receipt provided to the cardholder or accountholder at the point of
the business transaction--
(1) more than the last 5 digits of the account number of
any such credit card, debit card, or consumer account; or
(2) the expiration date of any such credit card, debit
card, or other means of access to a consumer's account.
(b) Scope of Application.--This section applies only to receipts
that are electronically printed, and shall not apply to transactions in
which the sole means of recording the credit card or debit card account
number, or the account number of a consumer's account, is by
handwriting or by an imprint or copy of the credit card, debit card, or
other means of access.
(c) Definitions.--For purposes of this section, the following
definitions shall apply:
(1) Consumer's account.--The term ``consumer's account'
means an account (as defined in paragraph (2) of section 903 of
the Electronic Fund Transfer Act) of a consumer (as defined in
paragraph (5) of such section).
(2) Credit card.--The term ``credit card'' has the same
meaning as in section 103(k) of the Truth in Lending Act.
(3) Debit card.--The term ``debit card'' means any card
issued by a financial institution to a consumer for use in
initiating electronic fund transfers from the account of the
consumer at such financial institution for the purpose of
transferring money between accounts or obtaining money,
property, labor, or services.
(4) Electronic fund transfer.--The term ``electronic fund
transfer'' has the same meaning as in section 903(6) of the
Electronic Fund Transfer Act.
(d) Effective Date.--This section shall take effect on January 1,
2005, with respect to any cash register or other machine or device that
electronically prints receipts for credit card transactions.
(e) Civil Liability.--Any person who violates this section with
regard to any credit card, debit card, or other means of access to a
consumer's account shall be liable for any damages or expenses,
including reasonable attorney's fees, that the card holder or consumer
incurs as a result of such violation, including losses incurred from
the unauthorized use of the account number of any such credit card,
debit card, or consumer's account as a result of such violation.

SEC. 4. IDENTITY THEFT PREVENTION.

(a) Duty of Issuers of Credit and Debit Cards.--
(1) Credit cards.--Section 132 of the Truth in Lending Act
(15 U.S.C. 1642) is amended--
(A) by inserting ``(a) In General.--'' before ``No
credit''; and
(B) by adding at the end the following:
``(b) Verification of Consumer Identity Upon Receiving a Request
for an Additional Card After a Change of Address.--Each card issuer
shall establish procedures for verifying the identification of a
consumer whenever the card issuer receives a request from a consumer
for an additional credit card with respect to an existing credit
account not later than 30 days after receiving notification of a change
of address for that account.''.
(2) Debit cards.--Section 911 of the Electronic Fund
Transfer Act (15 U.S.C. 1693i) is amended by adding at the end
the following new subsection:
``(d) Verification of Consumer Identity Upon Receiving a Request
After a Change of Address.--Each person who issues to a consumer any
code, card, or other means of access to such consumer's account shall
establish procedures for verifying the identification of the consumer
whenever such person receives a request from a consumer for an
additional card, code, or other means of access to the consumer's
account not later than 30 days after receiving notification of a change
of address for that account.''.
(b) Centralized Reporting System.--The Federal Trade Commission
shall coordinate the establishment of a centralized reporting system in
which all consumer reporting agencies (as defined in section 603 of the
Fair Credit Reporting Act) shall participate that will--
(1) allow any consumer or business to report, through the
use of an nationwide free telephone number and an Internet Web
site address, any suspected violation of section 1028 of title
18, United States Code; and
(2) allow such information to be immediately shared among
all such consumer reporting agencies.

SEC. 5. FRAUD ALERTS.

Section 605 of the Fair Credit Reporting Act (15 U.S.C. 1681c) is
amended by adding at the end the following new subsection:
``(g) Fraud Alerts.--
``(1) Fraud alert defined.--For purposes of this
subsection, the term `fraud alert' means a statement in the
file of a consumer that notifies all prospective users of a
consumer report made with respect to that consumer that--
``(A) the consumer's identity may have been used,
without the consumer's consent, to fraudulently obtain
goods or services in the consumer's name; and
``(B) the consumer does not authorize the issuance
or extension of credit in the name of the consumer
unless the issuer of such credit utilizes reasonable
procedures established by the issuer to verify the
consumer's identity and obtain the consumer's
authorization whenever the card issuer receives a
request for credit.
``(2) Inclusion of fraud alert in consumer file.--Upon the
request of a consumer, or another third party who has the
consumer's consent to request a fraud alert on the consumer's
behalf, and upon receiving proper identification, a consumer
reporting agency shall include a fraud alert in the file of
that consumer and shall maintain the fraud alert for not less
than 1 year, unless the consumer requests a shorter time
period.
``(3) Notice sent by consumer reporting agencies to
users.--A consumer reporting agency shall notify each person
procuring consumer credit information with respect to a
consumer of the existence of a fraud alert in the file of that
consumer, regardless of whether a full credit report, credit
score, or summary report is requested.
``(4) Notice to nationwide consumer reporting agencies.--
Whenever a consumer reporting agency that compiles and
maintains files on consumers on a nationwide basis receives a
request from a consumer, directly or through another consumer
reporting agency, to include a fraud alert in the consumer's
file, the consumer reporting agency shall promptly notify every
other consumer reporting agency that compiles and maintains
files on consumers on a nationwide basis that such request has
been received and each such other agency shall comply with
paragraph (2) in the same manner as if the agency had received
the request directly from the consumer.
``(5) Toll-free telephone number.--Each consumer reporting
agency referred to in paragraph (4) shall establish and
maintain a toll-free telephone number for consumers to request
fraud alerts.
``(6) Procedures to receive fraud alerts.--Any person who
uses a consumer credit report in connection with a credit
transaction shall establish reasonable procedures to receive
fraud alerts transmitted by consumer reporting agencies.
``(7) Violations.--
``(A) Consumer reporting agency.--Any consumer
reporting agency that fails to notify any user of a
consumer credit report of the existence of a fraud
alert in that report shall be in violation of this
section.
``(B) User of a consumer report.--Any user of a
consumer report that fails to comply with
preauthorization procedures contained in a fraud alert
and issues or extends credit in the name of the
consumer to a person other than the consumer shall be
in violation of this section.
``(8) Exempt institutions.--The requirement under this
subsection to place a fraud alert in a consumer file shall not
apply to--
``(A) check services company or a fraud prevention
company, which issues authorizations for the purpose of
approving or processing negotiable instruments,
electronic funds transfers or similar methods of
payments; or
``(B) deposit account information service company,
which issues reports regarding account closures due to
fraud, substantial overdrafts, automated teller machine
abuse, or similar negative information regarding a
consumer, to inquiring banks or other financial
institutions for use only in reviewing a consumer
request for a deposit account at the inquiring bank or
financial institution.
``(9) Policy review and regulation.--
``(A) Review.--Any agency referred to in subsection
(a) or (c) of section 621 shall, upon the request of
any person under the jurisdiction of such agency
pursuant to this title--
``(i) review any policy or procedure
established by such person to carry out the
purposes of this subsection to determine the
effectiveness and reasonableness of the policy
or procedure for such purposes; and
``(ii) make such recommendations to such
person for improvement in such policy or
procedure as the agency may determine to be
appropriate.
``(B) Regulation.--Each agency referred to in
subparagraph (A) shall establish procedures for
conducting reviews under such subparagraph.''.

SEC. 6. BUSINESS GUIDELINES.

(a) In General.--Not later than the end of the 1-year period
beginning on the date of the enactment of this Act, the Federal Trade
Commission, after consultation with the Federal functional regulators
(as defined in section 509(2) of the Gramm-Leach-Bliley Act), shall
establish procedures to--
(1) log and acknowledge the receipt of complaints of any
person who has a reasonable belief that information maintained
in a database of such person relating to any other person has
likely been stolen or compromised;
(2) provide informational materials and guidelines for a
business to follow when customer or other information in the
business' database has likely been stolen or compromised;
(3) provide guidelines for a business to follow in
notifying customers of the likelihood that information
concerning such customers has been stolen or compromised; and
(4) refer complaints described in paragraph (1) to--
(A) each consumer reporting agency that compiles
and maintains files on consumers on a nationwide basis
(as defined in section 603 of the Fair Credit Reporting
Act), together with any recommendation for the
implementation for such fraud alert as the Commission
may determine to be appropriate;
(B) appropriate law enforcement agencies.
(b) Policy Review and Regulation.--
(1) Review.--The Federal Trade Commission and any Federal
functional regulator (as defined in section 509(2) of the
Gramm-Leach-Bliley Act) shall, upon the request of any person
under the jurisdiction of such agency--
(A) review any policy or procedure established by
such person to follow in the event that information
maintained in a database of such person has likely been
stolen or compromised to determine the effectiveness
and reasonableness of the policy or procedure for such
purposes; and
(B) make such recommendations to such person for
improvement in such policy or procedure as the agency
may determine to be appropriate.
(2) Regulation.--Each agency referred to in subparagraph
(A) shall establish procedures for conducting reviews under
such subparagraph.''.

SEC. 7. SPECIFICATION OF CONSTITUTIONAL AUTHORITY FOR ENACTMENT OF LAW.

This Act is enacted pursuant to the power granted Congress under
section 8 of article I of the United States Constitution.
<all>