Patriotic Employers of Guard and Reservists Act of 2004
To amend the Internal Revenue Code of 1986 to provide to employers a tax credit for compensation paid during the period employees are performing service as members of the Ready Reserve or the National Guard.
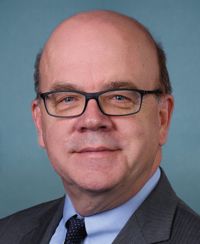 Rep. James P. McGovern (D-MA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Sponsor introductory remarks on measure. (CR 6/25/04 H5067-5068)
June 24, 2004
View full timeline
Introduced in House
June 23, 2004
Referred to the House Committee on Ways and Means.
June 23, 2004
Sponsor introductory remarks on measure. (CR 6/25/04 H5067-5068)
June 24, 2004
Floor Debate
3 membersWhat members said about H.R. 4655 on the floor
Floor Debate
3 membersWhat members said about H.R. 4655 on the floor
Mr. Speaker, I come to the floor today to cover two points. One will cover recent rulings in the FCC regarding the 1996 Telecommunications Act, and the other is we are going to talk about our foreign…
If the gentleman would yield on that point, I agree with the gentleman that the folks who express their dissent and have been expressing their dissent in government, basically giving the other side…
Mr. Speaker, currently over 170,000 National Guard and Reservists are on active duty serving in Afghanistan, Iraq, and elsewhere. President Bush just activated an additional 47,000 Reservists. Most…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 4655 Introduced in House (IH)]

108th CONGRESS
2d Session
H. R. 4655

To amend the Internal Revenue Code of 1986 to provide to employers a
tax credit for compensation paid during the period employees are
performing service as members of the Ready Reserve or the National
Guard.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

June 23, 2004

Mr. McGovern (for himself and Mr. Lantos) introduced the following
bill; which was referred to the Committee on Ways and Means

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to provide to employers a
tax credit for compensation paid during the period employees are
performing service as members of the Ready Reserve or the National
Guard.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Patriotic Employers of Guard and
Reservists Act of 2004''.

SEC. 2. READY RESERVE-NATIONAL GUARD EMPLOYEE CREDIT AND READY RESERVE-
NATIONAL GUARD REPLACEMENT EMPLOYEE CREDIT.

(a) Ready Reserve-National Guard Credit.--
(1) In general.--Subpart D of part IV of subchapter A of
chapter 1 of the Internal Revenue Code of 1986 (relating to
business-related credits) is amended by adding at the end the
following:

``SEC. 45G. READY RESERVE-NATIONAL GUARD EMPLOYEE CREDIT.

``(a) General Rule.--For purposes of section 38, the Ready Reserve-
National Guard employee credit determined under this section for any
taxable year with respect to each Ready Reserve-National Guard employee
of an employer is an amount equal to 50 percent of the lesser of--
``(1) the actual compensation amount with respect to such
employee for such taxable year, or
``(2) $30,000.
``(b) Definition of Actual Compensation Amount.--For purposes of
this section, the term `actual compensation amount' means the amount of
compensation paid or incurred by an employer with respect to a Ready
Reserve-National Guard employee on any day when the employee was absent
from employment for the purpose of performing qualified active duty.
``(c) Limitations.--No credit shall be allowed with respect to any
day that a Ready Reserve-National Guard employee who performs qualified
active duty was not scheduled to work (for reason other than to
participate in qualified active duty).
``(d) Definitions and Special Rules.--For purposes of this
section--
``(1) Qualified active duty.--The term `qualified active
duty' means--
``(A) active duty, other than the training duty
specified in section 10147 of title 10, United States
Code (relating to training requirements for the Ready
Reserve), or section 502(a) of title 32, United States
Code (relating to required drills and field exercises
for the National Guard), in connection with which an
employee is entitled to reemployment rights and other
benefits or to a leave of absence from employment under
chapter 43 of title 38, United States Code, and
``(B) hospitalization incident to such duty.
``(2) Compensation.--The term `compensation' means any
remuneration for employment, whether in cash or in kind, which
is paid or incurred by a taxpayer and which is deductible from
the taxpayer's gross income under section 162(a)(1).
``(3) Ready reserve-national guard employee.--The term
`Ready Reserve-National Guard employee' means an employee who
is a member of the Ready Reserve of a reserve component of an
Armed Force of the United States as described in sections 10142
and 10101 of title 10, United States Code.
``(4) Certain rules to apply.--Rules similar to the rules
of section 52 shall apply.
``(e) Portion of Credit Refundable.--
``(1) In general.--In the case of an employer of a
qualified first responder, the aggregate credits allowed to a
taxpayer under subpart C shall be increased by the lesser of--
``(A) the credit which would be allowed under this
section without regard to this subsection and the
limitation under section 38(c), or
``(B) the amount by which the aggregate amount of
credits allowed by this subpart (determined without
regard to this subsection) would increase if the
limitation imposed by section 38(c) for any taxable
year were increased by the amount of employer payroll
taxes imposed on the taxpayer during the calendar year in which the
taxable year begins.
The amount of the credit allowed under this subsection shall
not be treated as a credit allowed under this subpart and shall
reduce the amount of the credit otherwise allowable under
subsection (a) without regard to section 38(c).
``(2) Employer payroll taxes.--For purposes of this
subsection--
``(A) In general.--The term `employer payroll
taxes' means the taxes imposed by--
``(i) section 3111(b), and
``(ii) sections 3211(a) and 3221(a)
(determined at a rate equal to the rate under
section 3111(b)).
``(B) Special rule.--A rule similar to the rule of
section 24(d)(2)(C) shall apply for purposes of
subparagraph (A).
``(3) Qualified first responder.--For purposes of this
subsection, the term `qualified first responder' means any
person who is--
``(A) employed as a law enforcement official, a
firefighter, or a paramedic, and
``(B) a Ready Reserve-National Guard employee.''.
(2) Credit to be part of general business credit.--
Subsection (b) of section 38 of such Code (relating to general
business credit) is amended by striking ``plus'' at the end of
paragraph (14), by striking the period at the end of paragraph
(15) and inserting ``, plus'', and by adding at the end the
following:
``(16) the Ready Reserve-National Guard employee credit
determined under section 45G(a).''.
(3) Denial of double benefit.--Section 280C(a) of such Code
(relating to rule for employment credits) is amended by
inserting ``45G(a),'' after ``45A(a),''.
(4) Conforming amendment.--The table of sections for
subpart D of part IV of subchapter A of chapter 1 of such Code
is amended by inserting after the item relating to section 45F
the following:

``Sec. 45G. Ready Reserve-National Guard
employee credit.''.
(5) Effective date.--The amendments made by this subsection
shall apply to amounts paid or incurred after September 30,
2004, in taxable years ending after such date.
(b) Ready Reserve-National Guard Replacement Employee Credit.--
(1) In general.--Subpart B of part IV of subchapter A of
chapter 1 of such Code (relating to foreign tax credit, etc.)
is amended by adding after section 30A the following new
section:

``SEC. 30B. READY RESERVE-NATIONAL GUARD REPLACEMENT EMPLOYEE CREDIT.

``(a) Allowance of Credit.--
``(1) In general.--In the case of an eligible taxpayer,
there shall be allowed as a credit against the tax imposed by
this chapter for the taxable year the sum of the employment
credits for each qualified replacement employee under this
section.
``(2) Employment credit.--The employment credit with
respect to a qualified replacement employee of the taxpayer for
any taxable year is equal to 50 percent of the lesser of--
``(A) the individual's qualified compensation
attributable to service rendered as a qualified
replacement employee, or
``(B) $12,000.
``(b) Qualified Compensation.--The term `qualified compensation'
means--
``(1) compensation which is normally contingent on the
qualified replacement employee's presence for work and which is
deductible from the taxpayer's gross income under section
162(a)(1),
``(2) compensation which is not characterized by the
taxpayer as vacation or holiday pay, or as sick leave or pay,
or as any other form of pay for a nonspecific leave of absence,
and
``(3) group health plan costs (if any) with respect to the
qualified replacement employee.
``(c) Qualified Replacement Employee.--For purposes of this
section--
``(1) In general.--The term `qualified replacement
employee' means an individual who is hired to replace a Ready
Reserve-National Guard employee or a Ready Reserve-National
Guard self-employed taxpayer, but only with respect to the
period during which such Ready Reserve-National Guard employee
or Ready Reserve-National Guard self-employed taxpayer
participates in qualified active duty, including time spent in
travel status.
``(2) Ready reserve-national guard employee.--The term
`Ready Reserve-National Guard employee' has the meaning given
such term by section 45G(d)(3).
``(3) Ready reserve-national guard self-employed
taxpayer.--The term `Ready Reserve- National Guard self-
employed taxpayer' means a taxpayer who--
``(A) has net earnings from self-employment (as
defined in section 1402(a)) for the taxable year, and
``(B) is a member of the Ready Reserve of a reserve
component of an Armed Force of the United States as
described in section 10142 and 10101 of title 10,
United States Code.
``(d) Coordination With Other Credits.--The amount of credit
otherwise allowable under sections 51(a) and 1396(a) with respect to
any employee shall be reduced by the credit allowed by this section
with respect to such employee.
``(e) Limitations.--
``(1) Application with other credits.--The credit allowed
under subsection (a) for any taxable year shall not exceed the
excess (if any) of--
``(A) the regular tax for the taxable year reduced
by the sum of the credits allowable under subpart A and
sections 27, 29, and 30, over
``(B) the tentative minimum tax for the taxable
year.
``(2) Disallowance for failure to comply with employment or
reemployment rights of members of the reserve components of the
armed forces of the united states.--No credit shall be allowed
under subsection (a) to a taxpayer for--
``(A) any taxable year, beginning after the date of
the enactment of this section, in which the taxpayer is
under a final order, judgment, or other process issued
or required by a district court of the United States
under section 4323 of title 38 of the United States
Code with respect to a violation of chapter 43 of such
title, and
``(B) the 2 succeeding taxable years.
``(f) General Definitions and Special Rules.--For purposes of this
section--
``(1) Eligible taxpayer.--The term `eligible taxpayer'
means a small business employer or a Ready Reserve-National
Guard self-employed taxpayer.
``(2) Small business employer.--
``(A) In general.--The term `small business
employer' means, with respect to any taxable year, any
employer who employed an average of 50 or fewer
employees on business days during such taxable year.
``(B) Controlled groups.--For purposes of
subparagraph (A), all persons treated as a single
employer under subsection (b), (c), (m), or (o) of
section 414 shall be treated as a single employer.
``(3) Qualified active duty.--The term `qualified active
duty' has the meaning given such term by section 45G(d)(1).
``(4) Special rules for certain manufacturers.--
``(A) In general.--In the case of any qualified
manufacturer--
``(i) subsection (a)(2)(B) shall be applied
by substituting `$20,000' for `$12,000', and
``(ii) paragraph (2)(A) of this subsection
shall be applied by substituting `100' for
`50'.
``(B) Qualified manufacturer.--For purposes of this
paragraph, the term `qualified manufacturer' means any
person if--
``(i) the primary business of such person
is classified in sector 31, 32, or 33 of the
North American Industrial Classification
System, and
``(ii) all of such person's facilities
which are used for production in such business
are located in the United States.
``(5) Carryback and carryforward allowed.--
``(A) In general.--If the credit allowable under
subsection (a) for a taxable year exceeds the amount of
the limitation under subsection (e)(1) for such taxable
year (in this paragraph referred to as the `unused
credit year'), such excess shall be a credit carryback
to each of the 3 taxable years preceding the unused
credit year and a credit carryforward to each of the 20
taxable years following the unused credit year.
``(B) Rules.--Rules similar to the rules of section
39 shall apply with respect to the credit carryback and
credit carryforward under subparagraph (A).
``(6) Certain rules to apply.--Rules similar to the rules
of subsections (c), (d), and (e) of section 52 shall apply.''.
(2) No deduction for compensation taken into account for
credit.--Section 280C(a) of such Code (relating to rule for
employment credits) is amended--
(A) by inserting ``or compensation'' after
``salaries'', and
(B) by inserting ``30B,'' before ``45A(a),''.
(3) Conforming amendment.--Section 55(c)(2) of such Code is
amended by inserting ``30B(e)(1),'' after ``30(b)(3),''.
(4) Clerical amendment.--The table of sections for subpart
B of part IV of subchapter A of chapter 1 of such Code is
amended by adding after the item relating to section 30A the
following new item:

``Sec. 30B. Ready Reserve-National Guard
replacement employee credit.''.
(5) Effective date.--The amendments made by this subsection
shall apply to amounts paid or incurred after September 30,
2004, in taxable years ending after such date.
<all>