Tax Simplification for Americans Act of 2004
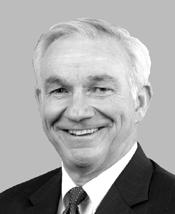 Rep. Max Burns (R-GA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance.
September 7, 2004
View full timeline
Introduced in House
July 15, 2004
Referred to the House Committee on Ways and Means.
July 15, 2004
Mr. Portman moved to suspend the rules and pass the bill, as amended.
July 21, 2004 • 3:29 PM
Considered under suspension of the rules. (consideration: CR H6483-6489)
July 21, 2004 • 3:29 PM
DEBATE - The House proceeded with forty minutes of debate on H.R. 4841.
July 21, 2004 • 3:29 PM
Passed/agreed to in House: On motion to suspend the rules and pass the bill, as amended Agreed to by voice vote.(text: CR H6483-6484)
July 21, 2004 • 4:12 PM
On motion to suspend the rules and pass the bill, as amended Agreed to by voice vote. (text: CR H6483-6484)
July 21, 2004 • 4:12 PM
Motion to reconsider laid on the table Agreed to without objection.
July 21, 2004 • 4:12 PM
Received in the Senate.
July 22, 2004
Read twice and referred to the Committee on Finance.
September 7, 2004
Floor Debate
10 membersWhat members said about H.R. 4841 on the floor
 +5
Floor Debate
10 membersWhat members said about H.R. 4841 on the floor
Mr. Speaker, I move to suspend the rules and pass the bill (H.R. 4841) to amend the Internal Revenue Code of 1986 to simplify certain tax rules for individuals, as amended. Mr. Speaker, I yield…
Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, again I want to restate my commitment to reform our Tax Code in ways that meaningfully benefit America's working families. While I…
Mr. Speaker, I think everybody in this institution knows the high personal regard in which we hold the gentleman from New York (Mr. Houghton), and we certainly regret that he is moving on to other…
Mr. Speaker, I thank the gentleman for yielding me time, and I have been listening to some of the discussion; and, sadly, it tends to revolve around the same themes, and what I would like to do is…
Mr. Speaker, as I sat and listened to this debate, I thought of a very famous quote from Groucho Marx. He said if you are going to go into politics, the first thing you have to learn to do is learn…
Show 5 more
Mr. Speaker, let me thank my friend from Texas for yielding me this time. Mr. Speaker, I have heard my distinguished chairman make his argument many times about the fact that we did this problem as…
Mr. Speaker, I thank the gentleman from Ohio (Mr. Portman) for yielding me time. I thank the committee for allowing me to bring this legislation to the floor today. This is common-sense legislation.…
Mr. Speaker, I particularly want to thank the gentleman from Georgia (Mr. Burns) for this legislation. I really think it is important. We can argue whether it is enough or not. Simplification is an…
Mr. Speaker, I rise in strong support of the Tax Simplification for Americans Act. Mr. Speaker, I rise in strong support of the Tax Simplification for Americans Act. As American taxpayers know too…
Mr. Speaker, I ask unanimous consent that all Members may have 5 legislative days within which to revise and extend their remarks and include extraneous material on H.R. 4840 and
Bill Text
3 versions available
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 4841 Referred in Senate (RFS)]

2d Session
H. R. 4841

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

July 22, 2004

Received

September 7, 2004

Read twice and referred to the Committee on Finance

_______________________________________________________________________

AN ACT

To amend the Internal Revenue Code of 1986 to simplify certain tax
rules for individuals.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Tax Simplification for Americans Act
of 2004''.

SEC. 2. HEAD OF HOUSEHOLD FILING STATUS CHANGED TO SINGLE HEAD OF
HOUSEHOLD.

(a) In General.--The following provisions of the Internal Revenue
Code of 1986 are each amended by striking ``head of a household'' each
place it appears and inserting ``single head of household'':
(1) Subsection (b) of section 1.
(2) Paragraphs (1) and (3) of section 2(b).
(3) The table in section 25B(b).
(4) Clause (iii) of section 151(c)(6)(B).
(5) Clauses (ii) and (iii) of section 151(d)(3)(C).
(6) Subparagraph (A) of section 6012(a)(1).
(b) Other Conforming Amendments.--
(1) Subparagraph (B) of section 63(c)(2) of such Code is
amended by striking ``head of household'' and inserting
``single head of household''.
(2) Section 1 of such Code is amended--
(A) in the heading for subsection (b) by inserting
``Single'' before ``Heads'' ,
(B) in subsection (c) by inserting ``single''
before ``head'', and
(C) in the heading of subsection (c) by inserting
``single'' before ``heads''.
(3) The heading for section 2(b) of such Code is amended to
read as follows: ``Definition of Single Head of Household''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 3. EXPANDED AVAILABILITY OF 1040EZ AND 1040A.

(a) In General.--Chapter 77 of the Internal Revenue Code of 1986
(relating to miscellaneous provisions) is amended by adding at the end
the following new section:

``SEC. 7529. DOLLAR THRESHOLD FOR THE USE OF FORMS 1040EZ AND 1040A.

``(a) In General.--An individual shall not be ineligible to use
Form 1040EZ and Form 1040A for filing individual income tax returns on
the basis of--
``(1) the amount of the taxpayer's taxable interest income,
or
``(2) the amount of the taxpayer's taxable income,
so long as the taxpayer's taxable income does not exceed $100,000.
``(b) Inflation Adjustment.--In the case of any taxable year
beginning in a calendar year after 2004, the $100,000 dollar amount in
subsection (a) shall be increased by an amount equal to--
``(1) such dollar amount, multiplied by
``(2) the cost-of-living adjustment determined under
section 1(f)(3) for such calendar year by substituting
`calendar year 2003' for `calendar year 1992' in subparagraph
(B) thereof.
If any amount as adjusted under the preceding sentence is not a
multiple of $10,000, such amount shall be rounded to the nearest
multiple of $10,000.''.
(b) Clerical Amendment.--The table of sections for chapter 77 of
such Code is amended by adding at the end the following new item:

``Sec. 7529. Dollar threshold for the use
of forms 1040EZ and 1040A.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 4. SIMPLIFICATION THROUGH ELIMINATION OF INOPERATIVE PROVISIONS.

(a) In General.--
(1) Adjustments in tax tables so that inflation will not
result in tax increases.--Paragraph (7) of section 1(f) of the
Internal Revenue Code of 1986 is amended to read as follows:
``(7) Special rule for certain brackets.--In prescribing
tables under paragraph (1) which apply to taxable years
beginning in a calendar year after 1994, the cost-of-living
adjustment used in making adjustments to the dollar amounts at
which the 36 percent rate bracket begins or at which the 39.6
percent rate bracket begins shall be determined under paragraph
(3) by substituting `1993' for `1992'.''.
(2) Earned income credit.--Paragraph (1) of section 32(b)
of such Code is amended--
(A) by striking subparagraphs (B) and (C), and
(B) in subparagraph (A) by striking ``(A) In
general.--In the case of taxable years beginning after
1995'' and moving the table 2 ems to the left.
(3) Annuities; certain proceeds of endowment and life
insurance contracts.--Section 72 of such Code is amended--
(A) in subsection (c)(4) by striking ``; except
that if such date was before January 1, 1954, then the
annuity starting date is January 1, 1954'', and
(B) in subsection (g)(3) by striking ``January 1,
1954, or'' and ``, whichever is later''.
(4) Accident and health plans.--Section 105(f) of such Code
is amended by striking ``or (d)''.
(5) Flexible spending arrangements.--Section 106(c)(1) of
such Code is amended by striking ``Effective on and after
January 1, 1997, gross'' and inserting ``Gross''.
(6) Certain combat zone compensation of members of the
armed forces.--Subsection (c) of section 112 of such Code is
amended--
(A) by striking ``(after June 24, 1950)'' in
paragraph (2), and
(B) striking ``such zone;'' and all that follows in
paragraph (3) and inserting ``such zone.''.
(7) Principal residence.--Section 121(b)(3) of such Code is
amended--
(A) by striking subparagraph (B), and
(B) in subparagraph (A) by striking ``(A) In
general.--'' and moving the text 2 ems to the left.
(8) Certain reduced uniformed services retirement pay.--
Section 122(b)(1) of such Code is amended by striking ``after
December 31, 1965,''.
(9) Mortgage revenue bonds for residences in federal
disaster areas.--Section 143(k) of such Code is amended by
striking paragraph (11).
(10) State legislators' travel expenses away from home.--
Paragraph (4) of section 162(h) of such Code is amended by
striking ``For taxable years beginning after December 31, 1980,
this'' and inserting ``This''.
(11) Health insurance costs of self-employed individuals.--
Paragraph (1) of section 162(l) of such Code is amended to read
as follows:
``(1) Allowance of deduction.--In the case of an individual
who is an employee within the meaning of section 401(c)(1),
there shall be allowed as a deduction under this section an
amount equal to 100 percent of the amount paid during the
taxable year for insurance which constitutes medical care for
the taxpayer and the taxpayer's spouse and dependents.''.
(12) Interest.--
(A) Section 163 of such Code is amended--
(i) by striking paragraph (6) of subsection
(d), and
(ii) by striking paragraph (5) of
subsection (h).
(B) Section 56(b)(1)(C) of such Code is amended by
striking clause (ii) and by redesignating clauses
(iii), (iv), and (v) as clauses (ii), (iii), and (iv),
respectively.
(13) Amounts received by surviving annuitant under joint
and survivor annuity contract.--Subparagraph (A) of section
691(d)(1) of such Code is amended by striking ``after December
31, 1953, and''.
(14) Income taxes of members of armed forces on death.--
Section 692(a)(1) of such Code is amended by striking ``after
June 24, 1950''.
(15) Tax on nonresident alien individuals.--Subparagraph
(B) of section 871(a)(1) of such Code is amended to read as
follows:
``(B) gains described in subsection (b) or (c) of
section 631,''.
(16) Old-age, survivors, and disability insurance.--
Subsection (a) of section 1401 of such Code is amended by
striking ``the following percent'' and all that follows and
inserting ``12.4 percent of the amount of the self-employment
income for such taxable year.''.
(17) Hospital insurance.--Subsection (b) of section 1401 of
such Code is amended by striking ``the following percent'' and
all that follows and inserting ``2.9 percent of the amount of
the self-employment income for such taxable year.''.
(18) Ministers, members of religious orders, and christian
science practitioners.--Paragraph (3) of section 1402(e) of
such Code is amended by striking ``whichever of the following
dates is later: (A)'' and by striking ``; or (B)'' and all that
follows and inserting a period.
(19) Withholding of tax on nonresident aliens.--The first
sentence of subsection (b) of section 1441 of such Code and the
first sentence of paragraph (5) of section 1441(c) of such Code
are each amended by striking ``gains subject to tax'' and all
that follows through ``October 4, 1966'' and inserting ``and
gains subject to tax under section 871(a)(1)(D)''.
(20) Retirement.--Section 7447(i)(3)(B)(ii) of such Code is
amended by striking ``at 4 percent per annum to December 31,
1947, and at 3 percent per annum thereafter'', and inserting
``at 3 percent per annum''.
(21) Annuities to surviving spouses and dependent children
of judges.--
(A) Paragraph (2) of section 7448(a) of such Code
is amended by striking ``or under section 1106 of the
Internal Revenue Code of 1939'' and by striking ``or
pursuant to section 1106(d) of the Internal Revenue
Code of 1939''.
(B) Subsection (g) of section 7448 of such Code is
amended by striking ``or other than pursuant to section
1106 of the Internal Revenue Code of 1939''.
(C) Subsections (g), (j)(1), and (j)(2) of section
7448 of such Code are each amended by striking ``at 4
percent per annum to December 31, 1947, and at 3
percent per annum thereafter'' and inserting ``at 3
percent per annum''.
(b) Effective Date.--
(1) General rule.--Except as otherwise provided in
paragraph (2), the amendments made by subsection (a) shall take
effect on the date of enactment of this Act.
(2) Savings provision.--If--
(A) any provision amended or repealed by subsection
(a) applied to--
(i) any transaction occurring before the
date of the enactment of this Act,
(ii) any property acquired before such date
of enactment, or
(iii) any item of income, loss, deduction,
or credit taken into account before such date
of enactment, and
(B) the treatment of such transaction, property, or
item under such provision would (without regard to the
amendments made by subsection (a)) affect the liability
for tax for periods ending after such date of
enactment,
nothing in the amendments made by subsection (a) shall be
construed to affect the treatment of such transaction,
property, or item for purposes of determining liability for tax
for periods ending after such date of enactment.

Passed the House of Representatives July 21, 2004.

Attest:

JEFF TRANDAHL,

Clerk.