Business Checking Freedom Act of 2003
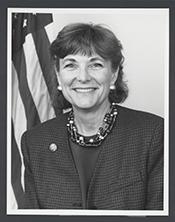 Rep. Sue W. Kelly (R-NY)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Received in the Senate and Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
April 2, 2003
View full timeline
Introduced in House
February 13, 2003
Referred to the House Committee on Financial Services.
February 13, 2003
Referred to the Subcommittee on Financial Institutions and Consumer Credit.
March 5, 2003
Subcommittee Hearings Held.
March 5, 2003
Committee Consideration and Mark-up Session Held.
March 13, 2003
Ordered to be Reported (Amended) by Voice Vote.
March 13, 2003
Reported (Amended) by the Committee on Financial Services. H. Rept. 108-53.
March 31, 2003
Placed on the Union Calendar, Calendar No. 33.
March 31, 2003
Mr. Bachus moved to suspend the rules and pass the bill, as amended.
April 1, 2003 • 12:46 PM
Considered under suspension of the rules. (consideration: CR H2527-2533)
April 1, 2003 • 12:47 PM
DEBATE - The House proceeded with forty minutes of debate on H.R. 758.
April 1, 2003 • 12:47 PM
Passed/agreed to in House: On motion to suspend the rules and pass the bill, as amended Agreed to by voice vote.(text: CR H2527-2529)
April 1, 2003 • 1:21 PM
On motion to suspend the rules and pass the bill, as amended Agreed to by voice vote. (text: CR H2527-2529)
April 1, 2003 • 1:21 PM
Motion to reconsider laid on the table Agreed to without objection.
April 1, 2003 • 1:21 PM
Received in the Senate and Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
April 2, 2003
Floor Debate
8 membersWhat members said about H.R. 758 on the floor

 +3
Floor Debate
8 membersWhat members said about H.R. 758 on the floor
Madam Speaker, I move to suspend the rules and pass the bill (H.R. 758) to allow all businesses to make up to 24 transfers each month from interest-bearing transaction accounts to other transaction…
Mr. Speaker, I thank the gentleman from Alabama (Mr. Bachus) and appreciate all his help on this legislation as well as the time he has yielded to me. I would also like to thank (Mr. Kanjorski), an…
Madam Speaker, I yield myself as much time as I may consume. I rise today in support of H.R. 758, the Business Checking Freedom Act of 2003. By repealing the prohibition on the payment of interest on…
Madam Speaker, it is with a great deal of reluctance that I rise in opposition to this bill. It contains many reasonable provisions, most importantly, the payment of interest on business checking,…
Mr. Speaker, I want to thank the gentleman from Alabama for both yielding me this time and for his work to move this legislation forward. In addition, I want to thank the gentleman from Ohio (Mr.…
Show 3 more

Mr. Speaker, I thank the gentleman for his leadership and for yielding me this time. Mr. Speaker, I rise in support of H.R. 758, the Business Checking Freedom Act, which the gentlewoman from New York…

Mr. Speaker, I rise in support of this bill, which is called the Business Checking Freedom Act; and I think giving banks the ability to pay interest on business checking accounts is a good concept.…
Mr. Speaker, as a co-sponsor of H.R. 758, I want to express my strong support for this legislation, the Business Checking Freedom Act of 2003, legislation designed to help small businesses obtain a…
Bill Text
4 versions available
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 758 Referred in Senate (RFS)]

1st Session
H. R. 758

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

April 2, 2003

Received; read twice and referred to the Committee on Banking, Housing,
and Urban Affairs

_______________________________________________________________________

AN ACT

To allow all businesses to make up to 24 transfers each month from
interest-bearing transaction accounts to other transaction accounts, to
require the payment of interest on reserves held for depository
institutions at Federal reserve banks, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Business Checking Freedom Act of
2003''.

SEC. 2. INTEREST-BEARING TRANSACTION ACCOUNTS AUTHORIZED FOR ALL
BUSINESSES.

(a) Section 2 of Public Law 93-100 (12 U.S.C. 1832) is amended--
(1) by redesignating subsections (b) and (c) as subsections
(c) and (d), respectively; and
(2) by inserting after subsection (a) the following:
``(b) Notwithstanding any other provision of law, any depository
institution may permit the owner of any deposit or account which is a
deposit or account on which interest or dividends are paid and is not a
deposit or account described in subsection (a)(2) to make up to 24
transfers per month (or such greater number as the Board of Governors
of the Federal Reserve System may determine by rule or order), for any
purpose, to another account of the owner in the same institution. An
account offered pursuant to this subsection shall be considered a
transaction account for purposes of section 19 of the Federal Reserve
Act unless the Board of Governors of the Federal Reserve System
determines otherwise.''.
(b) Effective at the end of the 2-year period beginning on the date
of the enactment of this Act, section 2 of Public Law 93-100 (12 U.S.C.
1832) is amended--
(1) in subsection (a)(1), by striking ``but subject to
paragraph (2)'';
(2) by striking paragraph (2) of subsection (a) and
inserting the following new paragraph:
``(2) No provision of this section may be construed as
conferring the authority to offer demand deposit accounts to
any institution that is prohibited by law from offering demand
deposit accounts.''; and
(3) in subsection (b) (as added by subsection (a) of this
section) by striking ``and is not a deposit or account
described in subsection (a)(2)''.

SEC. 3. INTEREST-BEARING TRANSACTION ACCOUNTS AUTHORIZED.

(a) Repeal of Prohibition on Payment of Interest on Demand
Deposits.--
(1) Federal reserve act.--Section 19(i) of the Federal
Reserve Act (12 U.S.C. 371a) is amended to read as follows:
``(i) [Repealed]''.
(2) Home owners' loan act.--The first sentence of section
5(b)(1)(B) of the Home Owners' Loan Act (12 U.S.C.
1464(b)(1)(B)) is amended by striking ``savings association may
not--'' and all that follows through ``(ii) permit any'' and
inserting ``savings association may not permit any''.
(3) Federal deposit insurance act.--Section 18(g) of the
Federal Deposit Insurance Act (12 U.S.C. 1828(g)) is amended to
read as follows:
``(g) [Repealed]''.
(b) Effective Date.--The amendments made by subsection (a) shall
take effect at the end of the 2-year period beginning on the date of
the enactment of this Act.

SEC. 4. PAYMENT OF INTEREST ON RESERVES AT FEDERAL RESERVE BANKS.

(a) In General.--Section 19(b) of the Federal Reserve Act (12
U.S.C. 461(b)) is amended by adding at the end the following new
paragraph:
``(12) Earnings on reserves.--
``(A) In general.--Balances maintained at a Federal
reserve bank by or on behalf of a depository
institution may receive earnings to be paid by the
Federal reserve bank at least once each calendar
quarter at a rate or rates not to exceed the general
level of short-term interest rates.
``(B) Regulations relating to payments and
distribution.--The Board may prescribe regulations
concerning--
``(i) the payment of earnings in accordance
with this paragraph;
``(ii) the distribution of such earnings to
the depository institutions which maintain
balances at such banks or on whose behalf such
balances are maintained; and
``(iii) the responsibilities of depository
institutions, Federal home loan banks, and the
National Credit Union Administration Central
Liquidity Facility with respect to the
crediting and distribution of earnings
attributable to balances maintained, in
accordance with subsection (c)(1)(A), in a
Federal reserve bank by any such entity on
behalf of depository institutions.
``(C) Depository institutions defined.--For
purposes of this paragraph, the term `depository
institution', in addition to the institutions described
in paragraph (1)(A), includes any trust company,
corporation organized under section 25A or having an
agreement with the Board under section 25, or any
branch or agency of a foreign bank (as defined in
section 1(b) of the International Banking Act of
1978).''.
(b) Authorization for Pass Through Reserves for Member Banks.--
Section 19(c)(1)(B) of the Federal Reserve Act (12 U.S.C. 461(c)(1)(B))
is amended by striking ``which is not a member bank''.
(c) Consumer Banking Costs Assessment.--
(1) In general.--The Federal Reserve Act (12 U.S.C. 221 et
seq.) is amended--
(A) by redesignating sections 30 and 31 as sections
31 and 32, respectively; and
(B) by inserting after section 29 the following new
section:

``SEC. 30. SURVEY OF BANK FEES AND SERVICES.

``(a) Annual Survey Required.--The Board of Governors of the
Federal Reserve System shall obtain annually a sample, which is
representative by type and size of the institution (including small
institutions) and geographic location, of the following retail banking
services and products provided by insured depository institutions and
insured credit unions (along with related fees and minimum balances):
``(1) Checking and other transaction accounts.
``(2) Negotiable order of withdrawal and savings accounts.
``(3) Automated teller machine transactions.
``(4) Other electronic transactions.
``(b) Minimum Survey Requirement.--The annual survey described in
subsection (a) shall meet the following minimum requirements:
``(1) Checking and other transaction accounts.--Data on
checking and transaction accounts shall include, at a minimum,
the following:
``(A) Monthly and annual fees and minimum balances
to avoid such fees.
``(B) Minimum opening balances.
``(C) Check processing fees.
``(D) Check printing fees.
``(E) Balance inquiry fees.
``(F) Fees imposed for using a teller or other
institution employee.
``(G) Stop payment order fees.
``(H) Nonsufficient fund fees.
``(I) Overdraft fees.
``(J) Deposit items returned fees.
``(K) Availability of no-cost or low-cost accounts
for consumers who maintain low balances.
``(2) Negotiable order of withdrawal accounts and savings
accounts.--Data on negotiable order of withdrawal accounts and
savings accounts shall include, at a minimum, the following:
``(A) Monthly and annual fees and minimum balances
to avoid such fees.
``(B) Minimum opening balances.
``(C) Rate at which interest is paid to consumers.
``(D) Check processing fees for negotiable order of
withdrawal accounts.
``(E) Fees imposed for using a teller or other
institution employee.
``(F) Availability of no-cost or low-cost accounts
for consumers who maintain low balances.
``(3) Automated teller transactions.--Data on automated
teller machine transactions shall include, at a minimum, the
following:
``(A) Monthly and annual fees.
``(B) Card fees.
``(C) Fees charged to customers for withdrawals,
deposits, and balance inquiries through institution-
owned machines.
``(D) Fees charged to customers for withdrawals,
deposits, and balance inquiries through machines owned
by others.
``(E) Fees charged to noncustomers for withdrawals,
deposits, and balance inquiries through institution-
owned machines.
``(F) Point-of-sale transaction fees.
``(4) Other electronic transactions.--Data on other
electronic transactions shall include, at a minimum, the
following:
``(A) Wire transfer fees.
``(B) Fees related to payments made over the
Internet or through other electronic means.
``(5) Other fees and charges.--Data on any other fees and
charges that the Board of Governors of the Federal Reserve
System determines to be appropriate to meet the purposes of
this section.
``(6) Federal reserve board authority.--The Board of
Governors of the Federal Reserve System may cease the
collection of information with regard to any particular fee or
charge specified in this subsection if the Board makes a
determination that, on the basis of changing practices in the
financial services industry, the collection of such information
is no longer necessary to accomplish the purposes of this
section.
``(c) Annual Report to Congress Required.--
``(1) Preparation.--The Board of Governors of the Federal
Reserve System shall prepare a report of the results of each
survey conducted pursuant to subsections (a) and (b) of this
section and section 136(b)(1) of the Consumer Credit Protection
Act.
``(2) Contents of the report.--In addition to the data
required to be collected pursuant to subsections (a) and (b),
each report prepared pursuant to paragraph (1) shall include a
description of any discernible trend, in the Nation as a whole,
in a representative sample of the 50 States (selected with due
regard for regional differences), and in each consolidated
metropolitan statistical area (as defined by the Director of
the Office of Management and Budget), in the cost and
availability of the retail banking services, including those
described in subsections (a) and (b) (including related fees
and minimum balances), that delineates differences between
institutions on the basis of the type of institution and the
size of the institution, between large and small institutions
of the same type, and any engagement of the institution in
multistate activity.
``(3) Submission to congress.--The Board of Governors of
the Federal Reserve System shall submit an annual report to the
Congress not later than June 1, 2005, and not later than June 1
of each subsequent year.
``(d) Definitions.--For purposes of this section, the term `insured
depository institution' has the meaning given such term in section 3 of
the Federal Deposit Insurance Act, and the term `insured credit union'
has the meaning given such term in section 101 of the Federal Credit
Union Act.''.
(2) Conforming amendment.--
(A) In general.--Paragraph (1) of section 136(b) of
the Truth in Lending Act (15 U.S.C. 1646(b)(1)) is
amended to read as follows:
``(1) Collection required.--The Board shall collect, on a
semiannual basis, from a broad sample of financial institutions
which offer credit card services, credit card price and
availability information including--
``(A) the information required to be disclosed
under section 127(c) of this chapter;
``(B) the average total amount of finance charges
paid by consumers; and
``(C) the following credit card rates and fees:
``(i) Application fees.
``(ii) Annual percentage rates for cash
advances and balance transfers.
``(iii) Maximum annual percentage rate that
may be charged when an account is in default.
``(iv) Fees for the use of convenience
checks.
``(v) Fees for balance transfers.
``(vi) Fees for foreign currency
conversions.''.
(B) Effective date.--The amendment made by
subparagraph (A) shall take effect on January 1, 2004.
(3) Repeal of other report provisions.--Section 1002 of
Financial Institutions Reform, Recovery, and Enforcement Act of
1989 and section 108 of the Riegle-Neal Interstate Banking and
Branching Efficiency Act of 1994 are hereby repealed.
(d) Technical and Conforming Amendments.--Section 19 of the Federal
Reserve Act (12 U.S.C. 461) is amended--
(1) in subsection (b)(4) (12 U.S.C. 461(b)(4)), by striking
subparagraph (C) and redesignating subparagraphs (D) and (E) as
subparagraphs (C) and (D), respectively; and
(2) in subsection (c)(1)(A) (12 U.S.C. 461(c)(1)(A)), by
striking ``subsection (b)(4)(C)'' and inserting ``subsection
(b)''.

SEC. 5. INCREASED FEDERAL RESERVE BOARD FLEXIBILITY IN SETTING RESERVE
REQUIREMENTS.

Section 19(b)(2)(A) of the Federal Reserve Act (12 U.S.C.
461(b)(2)(A)) is amended--
(1) in clause (i), by striking ``the ratio of 3 per
centum'' and inserting ``a ratio not greater than 3 percent
(and which may be zero)''; and
(2) in clause (ii), by striking ``and not less than 8 per
centum,'' and inserting ``(and which may be zero),''.

SEC. 6. TRANSFER OF FEDERAL RESERVE SURPLUSES.

(a) In General.--Section 7(b) of the Federal Reserve Act (12 U.S.C.
289(b)) is amended by adding at the end the following new paragraph:
``(4) Additional transfers to cover interest payments for
fiscal years 2003 through 2007.--
``(A) In general.--In addition to the amounts
required to be transferred from the surplus funds of
the Federal reserve banks pursuant to subsection
(a)(3), the Federal reserve banks shall transfer from
such surplus funds to the Board of Governors of the
Federal Reserve System for transfer to the Secretary of
the Treasury for deposit in the general fund of the
Treasury, such sums as are necessary to equal the net
cost of section 19(b)(12) in each of the fiscal years
2003 through 2007.
``(B) Allocation by federal reserve board.--Of the
total amount required to be paid by the Federal reserve
banks under subparagraph (A) for fiscal years 2003
through 2007, the Board of Governors of the Federal
Reserve System shall determine the amount each such
bank shall pay in such fiscal year.
``(C) Replenishment of surplus fund prohibited.--
During fiscal years 2003 through 2007, no Federal
reserve bank may replenish such bank's surplus fund by
the amount of any transfer by such bank under
subparagraph (A).''.
(b) Technical and Conforming Amendment.--Section 7(a) of the
Federal Reserve Act (12 U.S.C. 289(a)) is amended by adding at the end
the following new paragraph:
``(3) Payment to treasury.--During fiscal years 2003
through 2007, any amount in the surplus fund of any Federal
reserve bank in excess of the amount equal to 3 percent of the
paid-in capital and surplus of the member banks of such bank
shall be transferred to the Secretary of the Treasury for
deposit in the general fund of the Treasury.''.

SEC. 7. RULE OF CONSTRUCTION.

In the case of an escrow account maintained at a depository
institution in connection with a real estate transaction--
(1) the absorption, by the depository institution, of
expenses incidental to providing a normal banking service with
respect to such escrow account;
(2) the forbearance, by the depository institution, from
charging a fee for providing any such banking function; and
(3) any benefit which may accrue to the holder or the
beneficiary of such escrow account as a result of an action of
the depository institution described in subparagraph (1) or (2)
or similar in nature to such action,
shall not be treated as the payment or receipt of interest for purposes
of this Act and any provision of Public Law 93-100, the Federal Reserve
Act, the Home Owners' Loan Act, or the Federal Deposit Insurance Act
relating to the payment of interest on accounts or deposits at
depository institutions, provided, however, that nothing herein shall
be construed so as to require a depository institution that maintains
an escrow account in connection with a real estate transaction to pay
interest on such escrow account or to prohibit such institution from
paying interest on such escrow account. Nor shall anything herein be
construed to preempt the provisions of law of any State dealing with
the payment of interest on escrow accounts maintained in connection
with real estate transactions.

Passed the House of Representatives April 1, 2003.

Attest:

JEFF TRANDAHL,

Clerk.