Business Checking Freedom Act of 2003
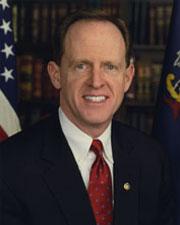 Rep. Patrick J. Toomey (R-PA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Subcommittee Hearings Held.
March 5, 2003
View full timeline
Introduced in House
February 13, 2003
Referred to the House Committee on Financial Services.
February 13, 2003
Referred to the Subcommittee on Financial Institutions and Consumer Credit.
March 5, 2003
Subcommittee Hearings Held.
March 5, 2003
Floor Debate
8 membersWhat members said about H.R. 859 on the floor

 +3
Floor Debate
8 membersWhat members said about H.R. 859 on the floor
Madam Speaker, I move to suspend the rules and pass the bill (H.R. 758) to allow all businesses to make up to 24 transfers each month from interest-bearing transaction accounts to other transaction…
Mr. Speaker, I thank the gentleman from Alabama (Mr. Bachus) and appreciate all his help on this legislation as well as the time he has yielded to me. I would also like to thank (Mr. Kanjorski), an…
Madam Speaker, I yield myself as much time as I may consume. I rise today in support of H.R. 758, the Business Checking Freedom Act of 2003. By repealing the prohibition on the payment of interest on…
Madam Speaker, it is with a great deal of reluctance that I rise in opposition to this bill. It contains many reasonable provisions, most importantly, the payment of interest on business checking,…
Mr. Speaker, I want to thank the gentleman from Alabama for both yielding me this time and for his work to move this legislation forward. In addition, I want to thank the gentleman from Ohio (Mr.…
Show 3 more

Mr. Speaker, I thank the gentleman for his leadership and for yielding me this time. Mr. Speaker, I rise in support of H.R. 758, the Business Checking Freedom Act, which the gentlewoman from New York…

Mr. Speaker, I rise in support of this bill, which is called the Business Checking Freedom Act; and I think giving banks the ability to pay interest on business checking accounts is a good concept.…
Mr. Speaker, as a co-sponsor of H.R. 758, I want to express my strong support for this legislation, the Business Checking Freedom Act of 2003, legislation designed to help small businesses obtain a…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 859 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 859

To repeal the prohibition on the payment of interest on demand
deposits, and for other purposes.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

February 13, 2003

Mr. Toomey (for himself, Mr. Kanjorski, Mrs. Biggert, Mr. Gonzalez, Mr.
Shays, and Ms. Hooley of Oregon) introduced the following bill; which
was referred to the Committee on Financial Services

_______________________________________________________________________

A BILL

To repeal the prohibition on the payment of interest on demand
deposits, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Business Checking Freedom Act of
2003''.

SEC. 2. INTEREST-BEARING TRANSACTION ACCOUNTS AUTHORIZED.

(a) Repeal of Prohibition on Payment of Interest on Demand
Deposits.--
(1) Federal reserve act.--Section 19(i) of the Federal
Reserve Act (12 U.S.C. 371a) is amended to read as follows:
``(i) [Repealed]''.
(2) Home owners' loan act.--The first sentence of section
5(b)(1)(B) of the Home Owners' Loan Act (12 U.S.C.
1464(b)(1)(B)) is amended by striking ``savings association may
not--'' and all that follows through ``(ii) permit any'' and
inserting ``savings association may not permit any''.
(3) Federal deposit insurance act.--Section 18(g) of the
Federal Deposit Insurance Act (12 U.S.C. 1828(g)) is amended to
read as follows:
``(g) [Repealed]''.
(b) Effective Date.--The amendments made by subsection (a) shall
take effect at the end of the 1-year period beginning on the date of
the enactment of this Act.

SEC. 3. RULE OF CONSTRUCTION.

In the case of an escrow account maintained at a depository
institution in connection with a real estate transaction--
(1) the absorption, by the depository institution, of
expenses incidental to providing a normal banking service with
respect to such escrow account;
(2) the forbearance, by the depository institution, from
charging a fee for providing any such banking function; and
(3) any benefit which may accrue to the holder or the
beneficiary of such escrow account as a result of an action of
the depository institution described in subparagraph (1) or (2)
or similar in nature to such action,
shall not be treated as the payment or receipt of interest for purposes
of this Act and any provision of Public Law 93-100, the Federal Reserve
Act, the Home Owners' Loan Act, or the Federal Deposit Insurance Act
relating to the payment of interest on accounts or deposits at
depository institutions.
<all>