Domestic Partner Health Benefits Equity Act
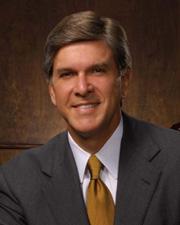 Sen. Gordon H. Smith (R-OR)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S12378-12380)
October 2, 2003
View full timeline
Introduced in Senate
October 2, 2003
Sponsor introductory remarks on measure. (CR S12378)
October 2, 2003
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S12378-12380)
October 2, 2003
Floor Debate
8 membersWhat members said about S. 1702 on the floor



 +3
Floor Debate
8 membersWhat members said about S. 1702 on the floor
Mr. President, the USA PATRIOT Act, the counterterrorism bill that the Bush administration pushed through Congress after the September 11 terrorist attacks, has been the focus of much controversy in…
Mr. President, I am pleased to join my colleagues Senators Pryor, Coleman and Bingaman in introducing the ``Keeping Families Together Act.'' Among other provisions, our bill authorizes a new,…
Mr. President, I rise today to speak about the need for consistent tax treatment of employer-provided health insurance for domestic partners. Today, Senator Bob Graham and I are introducing the…
Mr. President, today I will introduce in the Senate the Reasonable Notice and Search Act. This bill addresses the provision of the USA PATRIOT Act that has caused perhaps the most concern among…
Mr. President, it's a privilege to join my colleagues in introducing the Employment Non-Discrimination Act of 2003. Civil rights is the unfinished business of our nation. Title VII of the Civil…
Show 4 more
Mr. President, I am delighted to join with Senators Kennedy, Chafee, Jeffords and many other colleagues as an original cosponsor of this important legislation, the Employment Non- Discrimination Act…

Mr. President, I rise today on behalf of myself and Senators Durbin, Crapo, Feingold, Sununu, and Bingaman, to introduce the Security and Freedom Ensured Act of 2003, which we call the SAFE Act. This…

Mr. President, I rise today to introduce the Providing Our Support to Troops or POST Act of 2003. This bill would provide free mailing privileges for letters and packages sent from within the United…
Mr. President, I rise today to speak about the need for consistent tax treatment of employer-provided health insurance for domestic partners. Today, Senator Bob Graham and I are introducing the…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 1702 Introduced in Senate (IS)]

108th CONGRESS
1st Session
S. 1702

To amend the Internal Revenue Code of 1986 to extend the exclusion from
gross income for employer-provided health coverage to designated plan
beneficiaries of employees, and for other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

October 2, 2003

Mr. Smith (for himself, Mr. Graham of Florida, Mrs. Boxer, Mr. Chafee,
Mr. Corzine, and Mr. Wyden) introduced the following bill; which was
read twice and referred to the Committee on Finance

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to extend the exclusion from
gross income for employer-provided health coverage to designated plan
beneficiaries of employees, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Domestic Partner Health Benefits
Equity Act''.

SEC. 2. EXTENSION OF EXCLUSION FOR AMOUNTS RECEIVED BY AN EMPLOYEE
THROUGH ACCIDENT OR HEALTH INSURANCE AS REIMBURSEMENT FOR
EXPENSES FOR MEDICAL CARE.

(a) In General.--Section 105(b) of the Internal Revenue Code of
1986 (relating to amounts expended for medical care) is amended--
(1) by striking ``Except in the case'' and inserting the
following:
``(1) In general.--Except in the case'',
(2) by adding at the end of paragraph (1) as redesignated
in paragraph (1) the following new sentence: ``For the purposes
of this subsection, the term `dependents' shall include any
individual who is an eligible beneficiary as defined in the
employer's accident or health insurance arrangement.'', and
(3) by adding at the end the following new paragraph:
``(2) Applicable percentage of exclusion for certain
amounts.--
``(A) In general.--In the case of taxable years
beginning after December 31, 2004, and before January
1, 2011, the exclusion from income applicable by reason
of the third sentence of paragraph (1) shall be equal
to the applicable percentage of the amount which would
(but for this paragraph) be the amount of such
exclusion.
``(B) Applicable percentage.--For purposes of
subparagraph (A), the applicable percentage shall be
determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 3. EXTENSION OF EXCLUSION FOR CONTRIBUTIONS BY EMPLOYER TO
ACCIDENT AND HEALTH PLANS.

(a) In General.--Section 106 of the Internal Revenue Code of 1986
(relating to contributions by employer to accident and health plans) is
amended by adding at the end the following new subsection:
``(d) Coverage Provided for Eligible Beneficiaries of Employees.--
``(1) In general.--Subsection (a) shall not fail to apply
by reason of the coverage of an eligible beneficiary as defined
in the employer's accident or health plan.
``(2) Applicable percentage of exclusion for certain
coverage.--
``(A) In general.--In the case of taxable years
beginning after December 31, 2004, and before January
1, 2011, the exclusion from income applicable by reason
of paragraph (1) shall be equal to the applicable
percentage of the amount which would (but for this
paragraph) be the amount of such exclusion.
``(B) Applicable percentage.--For purposes of
subparagraph (A), the applicable percentage shall be
determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 4. EXTENSION OF DEDUCTION FOR HEALTH INSURANCE COSTS OF SELF-
EMPLOYED INDIVIDUALS.

(a) In General.--Paragraph (1) of section 162(l) of the Internal
Revenue Code of 1986 (relating to special rules for health insurance
costs of self-employed individuals) is amended to read as follows:
``(1) Allowance of deduction.--
``(A) In general.--In the case of an individual who
is an employee within the meaning of section 401(c)(1),
there shall be allowed as a deduction under this
section an amount equal to the amount paid during the
taxable year for insurance which constitutes medical
care for the taxpayer, his spouse, and dependents. For
the purposes of this subparagraph, the term
`dependents' shall include any individual who is an
eligible beneficiary as defined in the insurance
arrangement which constitutes medical care.
``(B) Applicable percentage of deduction for
certain amounts.--
``(i) In general.--In the case of taxable
years beginning after December 31, 2004, and
before January 1, 2011, the deduction
applicable by reason of the second sentence of
subparagraph (A) shall be equal to the
applicable percentage of the amount which would
(but for this subparagraph) be the amount of
such deduction.
``(ii) Applicable percentage.--For purposes
of clause (i), the applicable percentage shall
be determined in accordance with the following
table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2004.

SEC. 5. EXTENSION OF SICK AND ACCIDENT BENEFITS PROVIDED TO MEMBERS OF
A VOLUNTARY EMPLOYEES' BENEFICIARY ASSOCIATION AND THEIR
DEPENDENTS.

(a) In General.--Section 501(c)(9) of the Internal Revenue Code of
1986 (relating to list of exempt organizations) is amended by adding at
the end the following new sentence: ``For purposes of providing for the
payment of sick and accident benefits to members of such an association
and their dependents, the term `dependents' shall include any
individual who is an eligible beneficiary as determined under the terms
of a medical benefit, health insurance, or other program under which
members and their dependents are entitled to sick and accident
benefits.''.
(b) Applicable Percentage of Payment of Certain Sick and Accident
Benefits.--Section 501 of the Internal Revenue Code of 1986 (relating
to exemption from tax on corporations, certain trusts, etc.) is amended
by redesignating subsection (p) as subsection (q) and by inserting
after subsection (o) the following new subsection:
``(p) Applicable Percentage of Payment of Certain Sick and Accident
Benefits.--
``(1) In general.--In the case of taxable years beginning
after December 31, 2004, and before January 1, 2011, the
exemption from tax applicable by reason of the second sentence
of subsection (c)(9) shall be equal to the applicable
percentage of the amount which would (but for this subsection)
be the amount of such exemption.
``(2) Applicable percentage.--For purposes of paragraph
(1), the applicable percentage shall be determined in
accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 6. AMENDMENTS TO VARIOUS DEFINITIONS.

(a) FICA.--
(1) In general.--Section 3121 of the Internal Revenue Code
of 1986 (relating to definitions) is amended by adding at the
end the following new subsection:
``(z) Exclusion of Certain Amounts From Wages.--
``(1) In general.--For purposes of applying subsection (a)
with respect to expenses described in paragraph (2)(B) of such
subsection, the term `dependents' shall include any individual
who is an eligible beneficiary as defined in the plan or system
established by the employer.
``(2) Applicable percentage of exclusion from wages.--
``(A) In general.--In the case of taxable years
beginning after December 31, 2004, and before January
1, 2011, the exclusion from wages applicable by reason
of paragraph (1) shall be equal to the applicable
percentage of the amount which would (but for this
paragraph) be the amount of such exclusion.
``(B) Applicable percentage.--For purposes of
subparagraph (A), the applicable percentage shall be
determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(2) Conforming amendment.--Section 209 of the Social
Security Act (42 U.S.C. 409) is amended by adding at the end
the following new subsection:
``(l)(1) For purposes of applying subsection (a) with respect to
medical or hospitalization expenses described in paragraph (2) thereof,
the term `dependents' shall include any individual who is an eligible
beneficiary as defined in the plan or system established by the
employer.
``(2)(A) In the case of taxable years beginning after December 31,
2004, and before January 1, 2011, the exclusion from wages applicable
by reason of paragraph (1) shall be equal to the applicable percentage
of the amount which would (but for this paragraph) be the amount of
such exclusion.
``(B) For purposes of subparagraph (A), the applicable percentage
shall be determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(b) Railroad Retirement.--
(1) In general.--Section 3231(e) of the Internal Revenue
Code of 1986 (defining compensation) is amended by adding at
the end the following new paragraph:
``(11) Treatment of certain dependents.--
``(A) In general.--For purposes of applying this
subsection with respect to medical or hospitalization
expenses described in paragraph (1)(i), the term
`dependents' shall include any individual who is an
eligible beneficiary as defined in the plan or system
established by the employer.
``(B) Applicable percentage of exclusion from
compensation.--
``(i) In general.--In the case of taxable
years beginning after December 31, 2004, and
before January 1, 2011, the exclusion from
compensation applicable by reason of
subparagraph (A) shall be equal to the
applicable percentage of the amount which would
(but for this subparagraph) be the amount of
such exclusion.
``(ii) Applicable percentage.--For purposes
of clause (i), the applicable percentage shall
be determined in accordance with the following
table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(2) Conforming amendment.--Section 1(h) of the Railroad
Retirement Act of 1974 (45 U.S.C. 231(h)) is amended by adding
at the end the following new paragraph:
``(9)(A) For purposes of applying this subsection, with respect to
medical or hospitalization expenses described in paragraph (6)(v), the
term `dependents' shall include any individual who is an eligible
beneficiary as defined in the plan or system established by the
employer.
``(B)(i) In the case of taxable years beginning after December 31,
2004, and before January 1, 2011, the exclusion from compensation
applicable by reason of subparagraph (A) shall be equal to the
applicable percentage of the amount which would (but for this
subparagraph) be the amount of such exclusion.
``(ii) For purposes of clause (i), the applicable percentage shall
be determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(c) FUTA.--Section 3306 of the Internal Revenue Code of 1986
(relating to definitions) is amended by adding at the end the following
new subsection:
``(v) Exclusion of Certain Amounts From Wages.--
``(1) In general.--For purposes of applying subsection (b)
with respect to expenses described in paragraph (2)(B) of such
subsection, the term `dependents' shall include any individual
who is an eligible beneficiary as defined in the plan or system
established by the employer.
``(2) Applicable percentage of exclusion from wages.--
``(A) In general.--In the case of taxable years
beginning after December 31, 2004, and before January
1, 2011, the exclusion from wages applicable by reason
of paragraph (1) shall be equal to the applicable
percentage of the amount which would (but for this
paragraph) be the amount of such exclusion.
``(B) Applicable percentage.--For purposes of
subparagraph (A), the applicable percentage shall be
determined in accordance with the following table:

``For taxable years beginning in    The applicable percentage is--
calendar year--
2005, 2006, or 2007...........................                  25
2008, 2009, 2010..............................               50.''.
(d) Effective Date.--The amendments made by this section shall
apply to remuneration paid after December 31, 2004.
<all>