Pension Protection and Expansion Act of 2003
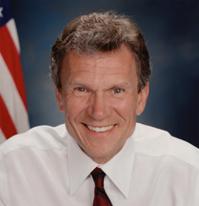 Sen. Thomas A. Daschle (D-SD)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance.
January 7, 2003
View full timeline
Introduced in Senate
January 7, 2003
Sponsor introductory remarks on measure. (CR 1/9/2003 S134)
January 7, 2003
Read twice and referred to the Committee on Finance.
January 7, 2003
Floor Debate
23 membersWhat members said about S. 9 on the floor


 +18
Floor Debate
23 membersWhat members said about S. 9 on the floor
Parliamentary inquiry. Mr. President, parliamentary inquiry: First, I recognize that the Senator has time. But I didn't know if we were going to alternate speakers. Does the Senator from Wyoming…
Mr. President, we did have a meeting with the President yesterday. It was one where we talked about the things that need to be done. The people who were at the meeting are experienced and understand…
I move to lay that motion on the table. The motion to lay on the table was agreed to. Mr. President, I move to reconsider the vote, and I move to lay that motion on the table. The motion to lay on…
Mr. President, I have two amendments at the desk that are intended to address a critical shortage in nutrition funding for schools, food banks and soup kitchens brought about by the Bush…
Mr. President, the amendment is at the desk. I ask unanimous consent that the reading of the amendment be dispensed with. Mr. President, this is a second-degree amendment to the underlying amendment.…
Show 8 more

Mr. President, I strongly support the amendment offered by Senator Mikulski that would prevent Federal agencies from establishing, applying, or enforcing any numerical goal, target, or quota for the…
Mr. President, if the Senator from Alaska will yield, I think there is an understanding that I am going to modify the amendment I have at the desk. I thank the manager. Amendments Nos. 6, 83, 85,…
Mr. President, I thank the Senator from Wyoming for his leadership. I rise in support of his amendment, and, as the Senator from Ohio said, in opposition to the amendment of the Senator from…

Mr. President, I strongly support Senator Mikulski's amendment to prohibit arbitrary, ``one-size-fits-all'' privatization quotas for Federal agencies. Under the amendment, agencies would still be…

I would like to associate myself with the remarks of Senator Leahy regarding the restoration of Section 32 funds that were depleted to finance the Administration's ad-hoc program to provide emergency…

Mr. President, I think the Senator from Maryland has raised a very legitimate point about the use of arbitrary quotas or numerical targets to guide the contracting-out activities of Federal agencies.…

That is correct. Mr. President, I send an amendment to the desk, and I ask unanimous consent that it be considered in lieu of my motion to instruct the conferees that is already at the desk. Mr.…
Mr. President, the 2002 farm bill authorized the Grants for Youth Program, an initiative to develop pilot programs and expand outreach to youth in rural communities and small towns across the Nation.…
Show 11 more

Mr. President, I rise today to engage in a colloquy with the distinguished junior Senator from Maine, the distinguished junior Senator from Maine, the distinguished ranking member of the Agriculture…

Mr. President, I rise in opposition to the Lautenberg amendment. I look over and see both Senators from Louisiana here. I can assure you that money is not just the answer. I remember at Bossier City…
Mr. President, I rise today in support of an amendment offered by Senator Mikulski regarding the use of quotas in contracting out Government jobs. The administration has put forth proposals requiring…
Mr. President, parliamentary inquiry. I announce that the Senator from Iowa (Mr. Harkin) and the Senator from Hawaii (Mr. Inouye) are necessarily absent. I ask to be made a cosponsor. Have the yeas…

Mr. President, will the distinguished chairman of the Transportation Subcommittee, my good friend, the Senator from Alabama, yield for a question? My office was recently visited by the mayor of…
Mr. President, I---- Mr. President, how much time do we have on this side? I thank the Chair. First, I share the concerns of the Senator from Maryland about this problem, and I want to do everything…
I appreciate the efforts of my friend from Wisconsin. I agree that the Summer Food Service Program is important for several reasons. Not only does it provide children with a healthy meal, but many of…

Mr. President, could I just ask---- Not wishing to object, I ask if any disposition has been made on amendment 126. I will wait for the remaining package. If not, I will ask for a vote on it. Mr.…

One minute. The superfund site in Coeur d'Alene, ID, that the Senator from New Jersey referred to, 3 years ago was touted to cost $1 billion to clean up. As a result of a cooperative State plan, in…
Will you give me 1 minute? I want to tell the Senate, 10 years ago I made a speech downtown to 350 people. They were anxiously paying attention. I said: It is this year we are going to reform that…
You are correct Senator. Four million dollars is in the report for this purpose which originated from a request to the Interior Appropriation Subcommittee in the form of a Dear Colleague letter dated…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 9 Introduced in Senate (IS)]

108th CONGRESS
1st Session
S. 9

To amend the Internal Revenue Code of 1986 and the Employee Retirement
Income Security Act of 1974 to protect the retirement security of
American workers by ensuring that pension assets are adequately
diversified and by providing workers with adequate access to, and
information about, their pension plans, and for other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

January 7, 2003

Mr. Daschle (for himself, Mr. Kennedy, Mr. Bingaman, Ms. Mikulski, Mr.
Durbin, Mrs. Clinton, Mr. Rockefeller, Mrs. Murray, Mr. Schumer, Mr.
Dayton, and Mr. Reid) introduced the following bill; which was read
twice and referred to the Committee on Finance

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 and the Employee Retirement
Income Security Act of 1974 to protect the retirement security of
American workers by ensuring that pension assets are adequately
diversified and by providing workers with adequate access to, and
information about, their pension plans, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; TABLE OF CONTENTS.

(a) Short Title.--This Act may be cited as the ``Pension Protection
and Expansion Act of 2003''.
(b) Table of Contents.--

Sec. 1. Short title; table of contents.
TITLE I--DIVERSIFICATION OF PENSION PLAN ASSETS

Sec. 101. Defined contribution plans required to provide employees with
freedom to invest their plan assets.
Sec. 102. Notice of freedom to divest employer securities or real
property.
Sec. 103. Notice that contributions of employer securities are not
endorsements of investment options.
Sec. 104. Rules relating to plan investments in employer stock.
TITLE II--PROTECTION OF PENSION PLAN PARTICIPANTS

Sec. 201. Notice to participants or beneficiaries of blackout periods.
Sec. 202. Inapplicability of relief from fiduciary liability during
suspension of ability of participant or
beneficiary to direct investments.
Sec. 203. Liability for breach of fiduciary duty.
Sec. 204. Increase in maximum bond amount and insurance adequate to
protect interest of participants and
beneficiaries.
Sec. 205. Participation of participants in trusteeship of individual
account plans.
TITLE III--INFORMATION TO ASSIST PENSION PLAN PARTICIPANTS

Sec. 301. Periodic pension benefit statements.
Sec. 302. Defined contribution plans required to provide adequate
investment education to participants.
Sec. 303. Fiduciary duty to provide material information relating to
investment in employer securities.
Sec. 304. Fiduciary responsibility to certify investments in employer
securities as prudent investments.
Sec. 305. Fiduciary rules for plan sponsors designating independent
investment advisers.
Sec. 306. Provisions relating to whistleblower actions involving
pension plans.
Sec. 307. Increase in penalties for coercive interference.
TITLE IV--RETIREMENT SECURITY

Sec. 401. Short title; etc.
Sec. 402. Expansion of retirement savings credit.
Sec. 403. Universal access to direct deposit retirement savings.
Sec. 404. Credit for qualified pension plan contributions of small
employers.
Sec. 405. Alternative method of meeting nondiscrimination requirements
for opt-out plans.
Sec. 406. Protection of participants during conversions to cash balance
or other hybrid defined benefit plans.
TITLE V--WOMEN'S PENSION PROTECTION

Sec. 501. Short title.
Subtitle A--Spousal Consent Required for Distributions From Defined
Contribution Plans

Sec. 511. Application of joint and survivor annuity rules to all
defined contribution plans.
Subtitle B--Division of Pension Benefits Upon Divorce

Sec. 521. Treatment of subsequent qualified domestic relations orders.
Sec. 522. Former spouses treated as surviving spouses in certain cases.
Subtitle C--Protection of Rights of Former Spouses to Pension Benefits
Under Certain Government and Government-Sponsored Retirement Programs

Chapter 1--Civil Service Retirement

Sec. 531. Survivor annuities for widows, widowers, and former spouses
of Federal employees who die before
attaining age for deferred annuity under
Civil Service Retirement System.
Sec. 532. Court orders relating to Federal retirement benefits for
former spouses of Federal employees.
Sec. 533. Interest on amounts paid for certain civil service annuity
benefits wrongfully denied.
Sec. 534. Income averaging of corrected civil service annuity benefit
payments.
Sec. 535. Order of precedence for disposition of amounts remaining in
the Thrift Savings Account of a Federal
employee (or former employee) who dies
before making an effective election
controlling such disposition.
Chapter 2--Railroad Retirement

Sec. 541. Entitlement of divorced spouses to railroad retirement
annuities independent of actual entitlement
of employee.
Sec. 542. Extension of Tier II railroad retirement benefits to
surviving former spouses pursuant to
divorce agreements.
Subtitle D--Modifications of Joint and Survivor Annuity Requirements

Sec. 551. Modifications of joint and survivor annuity requirements.
Subtitle E--Plan Amendments

Sec. 561. Provisions relating to plan amendments.
TITLE VI--OTHER PROVISIONS RELATING TO PENSIONS

Subtitle A--General Provisions

Sec. 601. Employee plans compliance resolution system.
Sec. 602. Extension to all governmental plans of moratorium on
application of certain nondiscrimination
rules applicable to State and local plans.
Sec. 603. Notice and consent period regarding distributions.
Sec. 604. Technical corrections to Saver Act.
Sec. 605. Missing participants.
Sec. 606. Reduced PBGC premium for new plans of small employers.
Sec. 607. Reduction of additional PBGC premium for new and small plans.
Sec. 608. Authorization for PBGC to pay interest on premium overpayment
refunds.
Sec. 609. Substantial owner benefits in terminated plans.
Sec. 610. Benefit suspension notice.
Sec. 611. Interest rate range for additional funding requirements.
Sec. 612. Voluntary early retirement incentive and employment retention
plans maintained by local educational
agencies and other entities.
Sec. 613. Automatic rollovers of certain mandatory distributions.
Sec. 614. 2-year extension of transition rule to pension funding
requirements.
Sec. 615. Acceleration of computation of benefits attributable to
recoveries of employer liability under
section 4062.
Sec. 616. Multiemployer plan funding notice.
Sec. 617. No reduction in unemployment compensation as a result of
pension rollovers.
Sec. 618. Withholding on distributions from governmental section 457
plans.
Sec. 619. Transfer of pension plan liabilities upon dissolution of
joint venture.
Subtitle B--Studies

Sec. 621. Study regarding insurance system for individual account
plans.
Sec. 622. Study regarding fees charged by individual account plans.
Sec. 623. Joint study on revitalizing defined benefit plans.
Sec. 624. Study on floor-offset ESOPS.
Subtitle C--Plan Amendments

Sec. 631. Provisions relating to plan amendments.
TITLE VII--REVENUE OFFSETS

Sec. 700. Amendment of 1986 Code.
Subtitle A--Reversing the Expatriation of Profits Offshore

Sec. 701. Tax treatment of inverted corporate entities.
Sec. 702. Excise tax on stock compensation of insiders in inverted
corporations.
Sec. 703. Reinsurance of United States risks in foreign jurisdictions.
Sec. 704. Study of deductibility of interest on related-party debt.
Subtitle B--Provisions Relating to Tax Shelters

Part I--Economic Substance Doctrine and Tax Shelter Transparency

Sec. 711. Penalty for failing to disclose reportable transaction.
Sec. 712. Accuracy-related penalty for listed transactions and other
reportable transactions having a
significant tax avoidance purpose.
Sec. 713. Modifications of substantial understatement penalty for
nonreportable transactions.
Sec. 714. Tax shelter exception to confidentiality privileges relating
to taxpayer communications.
subpart a--provisions relating to reportable transactions
Sec. 721. Disclosure of reportable transactions.
Sec. 722. Modifications to penalty for failure to register tax
shelters.
Sec. 723. Modification of penalty for failure to maintain lists of
investors.
Sec. 724. Modification of actions to enjoin certain conduct related to
subpart b--other promoter and preparer provisionssactions.
Sec. 731. Understatement of taxpayer's liability by income tax return
preparer.
Sec. 732. Penalty on failure to report interests in foreign financial
accounts.
Sec. 733. Frivolous tax submissions.
Sec. 734. Regulation of individuals practicing before the Department of
Treasury.
Sec. 735. Penalty on promoters of tax shelters.
Subtitle C--Executive Compensation

Sec. 741. Repeal of 1978 Revenue Act limitation on Secretary of the
Treasury's authority to determine year of
inclusion of amounts under private deferred
compensation plans.
Sec. 742. Treatment of nonqualified deferred compensation funded with
assets located outside the United States.
Sec. 743. Inclusion in gross income of funded deferred compensation of
corporate insiders.
Sec. 744. Increase in withholding from supplemental wage payments in
excess of $1,000,000.
Subtitle D--Other Provisions

Sec. 751. Affirmation of consolidated return regulation authority.
Sec. 752. Denial of deduction for certain fines, penalties, and other
amounts.

TITLE I--DIVERSIFICATION OF PENSION PLAN ASSETS

SEC. 101. DEFINED CONTRIBUTION PLANS REQUIRED TO PROVIDE EMPLOYEES WITH
FREEDOM TO INVEST THEIR PLAN ASSETS.

(a) Amendments of Internal Revenue Code.--
(1) Qualification requirement.--Section 401(a) of the
Internal Revenue Code of 1986 (relating to qualified pension,
profit-sharing, and stock bonus plans) is amended by inserting
after paragraph (34) the following new paragraph:
``(35) Diversification requirements for certain defined
contribution plans.--
``(A) In general.--A trust which is part of an
applicable defined contribution plan shall not be
treated as a qualified trust unless the plan meets--
``(i) the diversification requirements of
subparagraphs (B), (C), and (D), and
``(ii) the voting rights requirement of
subparagraph (E).
``(B) Employee contributions and elective deferrals
invested in employer securities or real property.--In
the case of the portion of an applicable individual's
account attributable to employee contributions and
elective deferrals which is invested in employer
securities or employer real property, a plan meets the
requirements of this subparagraph if the applicable
individual may elect to direct the plan to divest any
such securities or real property and to reinvest an
equivalent amount in other investment options meeting
the requirements of subparagraph (D).
``(C) Employer contributions invested in employer
securities or real property.--In the case of the
portion of the account attributable to employer
contributions other than elective deferrals which is
invested in employer securities or employer real
property, a plan meets the requirements of this
subparagraph if each applicable individual who--
``(i) is a participant who has completed at
least 3 years of service, or
``(ii) is a beneficiary of a participant
described in clause (i) or of a deceased
participant,
may elect to direct the plan to divest any such
securities or real property and to reinvest an
equivalent amount in other investment options meeting
the requirements of subparagraph (D).
``(D) Investment options.--
``(i) In general.--The requirements of this
subparagraph are met if the plan offers not
less than 3 investment options, other than
employer securities or employer real property,
to which an applicable individual may direct
the proceeds from the divestment of employer
securities or employer real property pursuant
to this paragraph, each of which is diversified
and has materially different risk and return
characteristics.
``(ii) Time for taking action.--If an
applicable individual makes an election under
this paragraph to reinvest the proceeds from
the divestment of any securities or real
property, the plan administrator shall take
such actions as are necessary to effectuate
such reinvestment before the earlier of--
``(I) the date such actions are
required to be taken without regard to
this clause, or
``(II) 30 days after the date of
such election (or if such election is
made with respect to an investment
period described in clause (iii), 30
days after the close of such period).
The Secretary may extend the period under
subclause (II) in cases with respect to which
the Secretary determines such extension is
necessary to carry out the purposes of this
paragraph.
``(iii) Treatment of certain restrictions
and conditions.--
``(I) Time for making investment
choices.--A plan shall not be treated
as failing to meet the requirements of
this subparagraph merely because the
plan limits the time for divestment and
reinvestment to periodic, reasonable
opportunities occurring no less
frequently than quarterly.
``(II) Certain restrictions and
conditions not allowed.--To the extent
provided in regulations, a plan shall
not meet the requirements of this
subparagraph if the plan imposes
restrictions or conditions with respect
to the investment of employer
securities or employer real property
which are not imposed on the investment
of other assets of the plan. This
subclause shall not apply to any
restrictions or conditions imposed by
reason of the application of securities
laws.
``(E) Voting rights.--
``(i) In general.--An applicable defined
contribution plan shall not be treated as
meeting the requirements of this paragraph
unless the plan meets the requirements of
section 409(e)(2) with respect to publicly
traded employer securities.
``(ii) Exception.--Clause (i) shall not
apply to publicly traded employer securities
acquired by reason of an investment of an
applicable individual in a pooled investment
vehicle. For purposes of this subclause, a
pooled investment vehicle is an investment
option of the plan which is not designed to
invest primarily in employer securities.
``(iii) Assignment of voting rights.--
Nothing in this subparagraph shall be construed
as limiting an applicable individual's ability
to assign the individual's rights under this
subparagraph to another person.
``(F) Applicable defined contribution plan.--For
purposes of this paragraph--
``(i) In general.--The term `applicable
defined contribution plan' means any defined
contribution plan which holds any publicly
traded employer securities.
``(ii) Exception for certain esops.--Such
term does not include an employee stock
ownership plan if--
``(I) there are no contributions to
such plan (or earnings thereunder)
which are held within such plan and are
subject to subsection (k) or (m), and
``(II) such plan is a separate plan
for purposes of section 414(l) with
respect to any other defined benefit
plan or defined contribution plan
maintained by the same employer or
employers.
``(iii) Exception for one participant
plans.--Such term does not include a one-
participant retirement plan.
``(iv) One-participant retirement plan.--
For purposes of clause (iii), the term `one-
participant retirement plan' means a retirement
plan that--
``(I) on the first day of the plan
year covered only one individual (or
the individual and the individual's
spouse) and the individual owned the
plan sponsor (whether or not
incorporated), or covered only one or
more partners (or partners and their
spouses) in the plan sponsor,
``(II) meets the minimum coverage
requirements of section 410(b) without
being combined with any other plan of
the business that covers the employees
of the business,
``(III) does not provide benefits
to anyone except the individual (and
the individual's spouse) or the
partners (and their spouses),
``(IV) does not cover a business
that is a member of an affiliated
service group, a controlled group of
corporations, or a group of businesses
under common control, and
``(V) does not cover a business
that leases employees (within the
meaning of section 414(n)).
For purposes of this clause, the term `partner'
includes a 2-percent shareholder (as defined in
section 1372(b)) of an S corporation.
``(G) Certain plans treated as holding publicly
traded employer securities.--
``(i) In general.--Except as provided in
regulations or in clause (ii), a plan holding
employer securities which are not publicly
traded employer securities shall be treated as
holding publicly traded employer securities if
any employer corporation, or any member of a
controlled group of corporations which includes
such employer corporation, has issued a class
of stock which is a publicly traded employer
security.
``(ii) Exception for certain controlled
groups with publicly traded securities.--Clause
(i) shall not apply to a plan if--
``(I) no employer corporation, or
parent corporation of an employer
corporation, has issued any publicly
traded employer security, and
``(II) no employer corporation, or
parent corporation of an employer
corporation, has issued any special
class of stock which grants particular
rights to, or bears particular risks
for, the holder or issuer with respect
to any corporation described in clause
(i) which has issued any publicly
traded employer security.
``(iii) Definitions.--For purposes of this
subparagraph, the term--
``(I) `controlled group of
corporations' has the meaning given
such term by section 1563(a), except
that `50 percent' shall be substituted
for `80 percent' each place it appears,
``(II) `employer corporation' means
a corporation which is an employer
maintaining the plan, and
``(III) `parent corporation' has
the meaning given such term by section
424(e).
``(H) Other definitions.--For purposes of this
paragraph--
``(i) Applicable individual.--The term
`applicable individual' means--
``(I) any participant in the plan,
and
``(II) any beneficiary who has an
account under the plan with respect to
which the beneficiary is entitled to
exercise the rights of a participant.
``(ii) Elective deferral.--The term
`elective deferral' means an employer
contribution described in section 402(g)(3)(A).
``(iii) Employer security.--The term
`employer security' has the meaning given such
term by section 407(d)(1) of the Employee
Retirement Income Security Act of 1974.
``(iv) Employer real property.--The term
`employer real property' has the meaning given
such term by section 407(d)(2) of the Employee
Retirement Income Security Act of 1974.
``(v) Employee stock ownership plan.--The
term `employee stock ownership plan' has the
meaning given such term by section 4975(e)(7).
``(vi) Publicly traded employer
securities.--The term `publicly traded employer
securities' means employer securities which are
readily tradable on an established securities
market.
``(vii) Year of service.--The term `year of
service' has the meaning given such term by
section 411(a)(5).
``(I) Transition rule for securities or real
property attributable to employer contributions.--
``(i) Rules phased in over 3 years.--
``(I) In general.--In the case of
the portion of an account to which
subparagraph (C) applies and which
consists of employer securities or
employer real property acquired in a
plan year beginning before January 1,
2004, subparagraph (C) shall only apply
to the applicable percentage of such
securities or real property. This
subparagraph shall be applied
separately with respect to each class
of securities and employer real
property.
``(II) Exception for certain
participants aged 55 or over.--
Subclause (I) shall not apply to an
applicable individual who is a
participant who has attained age 55 and
completed at least 3 years of service
before the first plan year beginning
after December 31, 2003.
``(ii) Applicable percentage.--For purposes
of clause (i), the applicable percentage shall
be determined as follows:

``Plan year to which limit applies: The applicable percentage is:
1st...........................................          33 percent
2d............................................          66 percent
3d and following..............................       100 percent.''
(2) Conforming amendments.--
(A) Section 401(a)(28)(B) of such Code (relating to
additional requirements relating to employee stock
ownership plans) is amended by adding at the end the
following new clause:
``(v) Exception.--This subparagraph shall
not apply to an applicable defined contribution
plan (as defined in paragraph (35)(F)).''
(B) Section 409(h)(7) of such Code is amended by
inserting ``or subparagraph (B) or (C) of section
401(a)(35)'' before the period at the end.
(C) Section 4980(c)(3)(A) of such Code is amended
by striking ``if--'' and all that follows and inserting
``if the requirements of subparagraphs (B), (C), and
(D) are met.''
(b) Amendments of ERISA.--
(1) In general.--Section 204 of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1054) is amended by
redesignating subsection (j) as subsection (k) and by inserting
after subsection (i) the following new subsection:
``(j) Diversification Requirements for Certain Individual Account
Plans.--
``(1) In general.--An applicable individual account plan
shall meet--
``(A) the diversification requirements of
paragraphs (2), (3), and (4), and
``(B) the voting rights requirement of paragraph
(5).
``(2) Employee contributions and elective deferrals
invested in employer securities or real property.--In the case
of the portion of an applicable individual's account
attributable to employee contributions and elective deferrals
which is invested in employer securities or employer real
property, a plan meets the requirements of this paragraph if
the applicable individual may elect to direct the plan to
divest any such securities or real property and to reinvest an
equivalent amount in other investment options meeting the
requirements of paragraph (4).
``(3) Employer contributions invested in employer
securities or real property.--In the case of the portion of the
account attributable to employer contributions other than
elective deferrals which is invested in employer securities or
employer real property, a plan meets the requirements of this
paragraph if each applicable individual who--
``(A) is a participant who has completed at least 3
years of service, or
``(B) is a beneficiary of a participant described
in subparagraph (A) or of a deceased participant,
may elect to direct the plan to divest any such securities or
real property and to reinvest an equivalent amount in other
investment options meeting the requirements of paragraph (4).
``(4) Investment options.--
``(A) In general.--The requirements of this
paragraph are met if the plan offers not less than 3
investment options, other than employer securities or
employer real property, to which an applicable
individual may direct the proceeds from the divestment
of employer securities or employer real property pursuant to this
subsection, each of which is diversified and has materially different
risk and return characteristics.
``(B) Time for taking action.--If an applicable
individual makes an election under this subsection to
reinvest the proceeds from the divestment of any
securities or real property, the plan administrator
shall take such actions as are necessary to effectuate
such reinvestment before the earlier of--
``(i) the date such actions are required to
be taken without regard to this subparagraph,
or
``(ii) 30 days after the date of such
election (or if such election is made with
respect to an investment period described in
subparagraph (C), 30 days after the close of
such period).
The Secretary may extend the period under clause (ii)
in cases with respect to which the Secretary determines
such extension is necessary to carry out the purposes
of this subsection.
``(C) Treatment of certain restrictions and
conditions.--
``(i) Time for making investment choices.--
A plan shall not be treated as failing to meet
the requirements of this paragraph merely
because the plan limits the time for divestment
and reinvestment to periodic, reasonable
opportunities occurring no less frequently than
quarterly.
``(ii) Certain restrictions and conditions
not allowed.--To the extent provided in
regulations, a plan shall not meet the
requirements of this paragraph if the plan
imposes restrictions or conditions with respect
to the investment of employer securities or
employer real property which are not imposed on
the investment of other assets of the plan.
This subparagraph shall not apply to any
restrictions or conditions imposed by reason of
the application of securities laws.
``(5) Voting rights.--
``(A) In general.--An applicable individual account
plan shall not be treated as meeting the requirements
of this subsection unless the plan meets the
requirements of section 409(e)(2) of the Internal
Revenue Code of 1986 with respect to publicly traded
employer securities.
``(B) Exception.--Subparagraph (A) shall not apply
to publicly traded employer securities acquired by
reason of an investment of an applicable individual in
a pooled investment vehicle. For purposes of this
subparagraph, a pooled investment vehicle is an
investment option of the plan which is not designed to
invest primarily in employer securities.
``(C) Assignment of voting rights.--Nothing in this
paragraph shall be construed as limiting an applicable
individual's ability to assign the individual's rights
under this subparagraph to another person.
``(6) Applicable individual account plan.--For purposes of
this subsection--
``(A) In general.--The term `applicable individual
account plan' means any individual account plan (as
defined in section 3(34)) which holds any publicly
traded employer securities.
``(B) Exception for certain esops.--Such term does
not include an employee stock ownership plan if--
``(i) there are no contributions to such
plan (or earnings thereunder) which are held
within such plan and are subject to subsection
(k) or (m) of section 401 of the Internal
Revenue Code of 1986, and
``(ii) such plan is a separate plan (for
purposes of section 414(l) of such Code) with
respect to any other defined benefit plan or
individual account plan maintained by the same
employer or employers.
``(C) Exception for one participant plans.--Such
term shall not include a one-participant retirement
plan (as defined in section 101(i)(8)(B)).
``(D) Certain plans treated as holding publicly
traded employer securities.--
``(i) In general.--Except as provided in
regulations or in clause (ii), a plan holding
employer securities which are not publicly
traded employer securities shall be treated as
holding publicly traded employer securities if
any employer corporation, or any member of a
controlled group of corporations which includes
such employer corporation, has issued a class
of stock which is a publicly traded employer
security.
``(ii) Exception for certain controlled
groups with publicly traded securities.--Clause
(i) shall not apply to a plan if--
``(I) no employer corporation, or
parent corporation of an employer
corporation, has issued any publicly
traded employer security, and
``(II) no employer corporation, or
parent corporation of an employer
corporation, has issued any special
class of stock which grants particular
rights to, or bears particular risks
for, the holder or issuer with respect
to any corporation described in clause
(i) which has issued any publicly
traded employer security.
``(iii) Definitions.--For purposes of this
subparagraph, the term--
``(I) `controlled group of
corporations' has the meaning given
such term by section 1563(a) of the
Internal Revenue Code of 1986, except
that `50 percent' shall be substituted
for `80 percent' each place it appears,
``(II) `employer corporation' means
a corporation which is an employer
maintaining the plan, and
``(III) `parent corporation' has
the meaning given such term by section
424(e) of such Code.
``(7) Other definitions.--For purposes of this paragraph--
``(A) Applicable individual.--The term `applicable
individual' means--
``(i) any participant in the plan, and
``(ii) any beneficiary who has an account
under the plan with respect to which the
beneficiary is entitled to exercise the rights
of a participant.
``(B) Elective deferral.--The term `elective
deferral' means an employer contribution described in
section 402(g)(3)(A) of the Internal Revenue Code of
1986.
``(C) Employer security.--The term `employer
security' has the meaning given such term by section
407(d)(1).
``(D) Employer real property.--The term `employer
real property' has the meaning given such term by
section 407(d)(2).
``(E) Employee stock ownership plan.--The term
`employee stock ownership plan' has the meaning given
such term by section 4975(e)(7) of such Code.
``(F) Publicly traded employer securities.--The
term `publicly traded employer securities' means
employer securities which are readily tradable on an
established securities market.
``(G) Year of service.--The term `year of service'
has the meaning given such term by section 203(b)(2).
``(8) Transition rule for securities or real property
attributable to employer contributions.--
``(A) Rules phased in over 3 years.--
``(i) In general.--In the case of the
portion of an account to which paragraph (3)
applies and which consists of employer
securities or employer real property acquired
in a plan year beginning before January 1,
2004, paragraph (3) shall only apply to the
applicable percentage of such securities or
real property. This subparagraph shall be
applied separately with respect to each class
of securities and employer real property.
``(ii) Exception for certain participants
aged 55 or over.--Clause (i) shall not apply to
an applicable individual who is a participant
who has attained age 55 and completed at least
3 years of service before the first plan year
beginning after December 31, 2003.
``(B) Applicable percentage.--For purposes of
subparagraph (A), the applicable percentage shall be
determined as follows:

``Plan year to which limit applies: The applicable percentage is:
1st...........................................          33 percent
2d............................................          66 percent
3d and following..............................       100 percent.''
(2) Fiduciary responsibility.--Section 404 of such Act (29
U.S.C. 1104) is amended by adding at the end the following new
subsection:
``(e) Fiduciary Responsibility With Respect to Diversification
Requirements for Individual Account Plans.--The fiduciary of an
applicable individual account plan (as defined in section 204(j))
shall, in addition to any other fiduciary responsibility or duty, have
a fiduciary responsibility to ensure the plan's compliance with the
requirements of section 204(j).''

SEC. 102. NOTICE OF FREEDOM TO DIVEST EMPLOYER SECURITIES OR REAL
PROPERTY.

(a) In General.--Section 104 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 104) is amended by redesignating
subsection (d) as subsection (e) and by inserting after subsection (c)
the following new subsection:
``(d) Notice of Right To Divest.--Not later than 30 days before the
first date on which an applicable individual of an applicable
individual account plan is eligible to exercise the right under section
204(j) to direct the proceeds from the divestment of employer
securities or employer real property, the plan administrator shall
provide to such individual a notice--
``(1) setting forth such right under such section, and
``(2) describing the importance of diversifying the
investment of retirement account assets.
The Secretary shall prescribe a model notice for purposes of satisfying
the requirements of this subsection which shall be in a form calculated
to be understood by the average plan participant. The notice required
by this subsection may be delivered in written, electronic, or other
appropriate form to the extent that such form is reasonably accessible
to the applicable individual.''
(b) Penalties.--Section 502(c)(7) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1132(c)(7)) is amended by inserting
``or section 104(d)'' after ``section 101(i)''.
(c) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.

SEC. 103. NOTICE THAT CONTRIBUTIONS OF EMPLOYER SECURITIES ARE NOT
ENDORSEMENTS OF INVESTMENT OPTIONS.

(a) In General.--Section 104 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1024), as amended by section 102, is
amended by redesignating subsection (e) as subsection (f) and by
inserting after subsection (d) the following new subsection:
``(e) Notice That Certain Employer Contributions Are Not
Endorsements.--If employer matching contributions or employer
nonelective contributions are made to an applicable individual account
plan (within the meaning of section 204(j)) in the form of employer
securities, the plan administrator of the plan shall include with the
notice required under section 105(a)(1)(A) a statement informing
participants and beneficiaries that the matching or nonelective
contributions should not be treated as an endorsement of such
securities as a better investment option than the other options
provided by the plan. The Secretary shall issue guidance and provide
model notices which meet the requirements of this subsection.''
(b) Penalties.--Section 502(c)(7) of such Act, as amended by
section 102, is amended by striking ``section 104(d)'' and inserting
``subsection (d) or (e) of section 104''.
(c) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.

SEC. 104. RULES RELATING TO PLAN INVESTMENTS IN EMPLOYER STOCK.

(a) In General.--Section 404 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1104) is amended by adding at the end
the following new subsection:
``(f)(1)(A) Except as provided in this subsection, an individual
account plan under which a participant or beneficiary is permitted to
exercise control over assets in his or her account shall provide that
if the plan (or any other plan maintained by the employer which covers
the participant or beneficiary) requires employer contributions other
than elective deferrals to be invested in employer securities or
employer real property, the plan may not permit elective deferrals to
be invested in employer securities or employer real property.
``(B) This subsection shall not apply to an individual account plan
maintained by an employer for any plan year if the employer maintains a
qualified defined benefit plan (as defined in paragraph (3)) for the
plan year.
``(2)(A) A plan which offers as an investment option the purchase
of stock through an open brokerage account or similar investment
vehicle shall not be treated as meeting the requirements of paragraph
(1) unless the plan provides that such option may not be used to
purchase employer securities or employer real property which are to be
held by the plan.
``(B) A plan shall not be treated as failing to meet the
requirements of paragraph (1) merely because elective deferrals are
invested in employer securities or employer real property by reason of
an investment in a pooled investment vehicle. For purposes of this
clause, a pooled investment vehicle is an investment option of the plan
which is not designed to invest primarily in employer securities or
employer real property.
``(3)(A) For purposes of paragraph (1)(B), the term `qualified
defined benefit plan' means, with respect to any individual account
plan, a defined benefit plan--
``(i) which covers at least 90 percent of the employees as
are covered by the individual account plan, and
``(ii) with respect to which the accrued benefit of each
participant, payable at normal retirement age under the plan,
is not less than a benefit which is actuarially equivalent to a
percentage of the participant's final average pay equal to 1
percent multiplied by the number of years of service (not
greater than 20) of the participant.
If a plan provides for benefits payable prior to normal retirement age,
the requirements of clause (ii) shall not be treated as met unless such
benefits are at least equal to the actuarial equivalent of the normal
retirement benefit under the plan.
``(B) In applying clause (ii) of subparagraph (A) to a defined
benefit plan with respect to which a participant's accrued benefit is
equal to a fixed dollar amount multiplied by the number of years of
service--
``(i) the participant's pay during the plan year preceding
the plan year of the determination shall be used in lieu of
final average pay, and
``(ii) the plan shall be treated as satisfying the
requirement of such clause if the average accrued benefit under
the plan of all the participants who are also covered by the
individual account plan meets such requirement.''
(b) Effective Dates.--
(1) In general.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.
(2) Special rule for collectively bargained agreements.--In
the case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, subsection (a) shall be applied to benefits
pursuant to, and individuals covered by, any such agreement by
substituting for ``December 31, 2002'' the earlier of--
(A) the later of--
(i) December 31, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after such date of enactment), or
(B) December 31, 2004.

TITLE II--PROTECTION OF PENSION PLAN PARTICIPANTS

SEC. 201. NOTICE TO PARTICIPANTS OR BENEFICIARIES OF BLACKOUT PERIODS.

(a) In General.--Section 101(i) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1021(i)) is amended--
(1) by striking ``the terms of'' in paragraph (7)(A),
(2) by striking clause (i) of paragraph (8)(B) and
inserting:
``(i) on the first day of the plan year--
``(I) covered only one individual
(or the individual and the individual's
spouse) and the individual owned the
plan sponsor (whether or not
incorporated), or
``(II) covered only one or more
partners (or partners and their
spouses) in the plan sponsor,'',
(3) by striking ``employer'' and ``employer's'' in
paragraph (8)(B)(iii) and inserting ``individual'' and
``individual's'', respectively,
(4) by inserting ``(within the meaning of section 414(n) of
the Internal Revenue Code of 1986)'' after ``employees'' in
paragraph (8)(B)(v), and
(5) by adding at the end of paragraph (8)(B) the following
flush sentence:
``For purposes of this paragraph, an individual shall
be treated as a partner if the individual is so treated
under section 401(a)(35)(F)(iv) of the Internal Revenue
Code of 1986.''
(b) Effective Date.--The amendments made by this section shall take
effect as if included in the provisions of section 306 of Public Law
107-204 (116 Stat. 745 et seq.).

SEC. 202. INAPPLICABILITY OF RELIEF FROM FIDUCIARY LIABILITY DURING
SUSPENSION OF ABILITY OF PARTICIPANT OR BENEFICIARY TO
DIRECT INVESTMENTS.

(a) In General.--Section 404(c)(1) of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1104(c)(1)) is amended--
(1) by redesignating subparagraphs (A) and (B) as clauses
(i) and (ii), respectively, and by inserting ``(A)'' after
``(c)(1)'',
(2) in subparagraph (A)(ii) (as redesignated by paragraph
(1)), by inserting before the period the following: ``, except
that this clause shall not apply in connection with such
participant or beneficiary for any blackout period during which
the ability of such participant or beneficiary to direct the
investment of the assets in his or her account is suspended by
a plan sponsor or fiduciary'', and
(3) by adding at the end the following new subparagraphs:
``(B)(i) If the person referred to in subparagraph (A)(ii) meets
the requirements of this title in connection with authorizing and
implementing the blackout period, such person shall not be liable under
this title for any loss occurring during such period as a result of any
exercise by the participant or beneficiary of control over assets in
his or her account before the period. Matters to be considered in
determining whether such person has satisfied the requirements of this
title include, but are not limited to, whether such person--
``(I) has considered the reasonableness of the expected
blackout period,
``(II) has provided the notice required under section
101(i)(1), and
``(III) has acted in accordance with the requirements of
subsection (a) in determining whether to enter into the
blackout period.
``(ii) For purposes of this subsection, if a blackout period arises
in connection with a change in the investment options offered under the
plan, a participant or beneficiary shall be deemed to have exercised
control over the assets in his or her account prior to the blackout
period if, after notice of the change in investment options is given to
such participant or beneficiary, assets in the account of the
participant or beneficiary are transferred--
``(I) to plan investment options in accordance with the
affirmative election of the participant or beneficiary which
otherwise meets the conditions of this subsection; or
``(II) in the absence of such an election and in the case
in which fiduciary relief was provided under this subsection
for the prior investment options, to plan investment options
with reasonably comparable risk and return characteristics in
accordance with procedures set forth in such notice.
``(C) For purposes of this paragraph, the term `blackout period'
has the meaning given such term by section 101(i)(7).''
(b) Guidance.--The Secretary of Labor, in consultation with the
Secretary of the Treasury, shall, before December 31, 2003, issue
interim final regulations providing guidance, including safe harbors,
on how plan sponsors or any other affected fiduciaries can satisfy
their fiduciary responsibilities during any blackout period during
which the ability of a participant or beneficiary to direct the
investment of assets in his or her individual account is suspended.
(c) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.
(2) Special rule for collectively bargained agreements.--In
the case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, subsection (a) shall be applied to benefits
pursuant to, and individuals covered by, any such agreement by
substituting for ``December 31, 2002'' the earlier of--
(A) the later of--
(i) December 31, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after such date of enactment), or
(B) December 31, 2005.

SEC. 203. LIABILITY FOR BREACH OF FIDUCIARY DUTY.

(a) Liability for Participating in or Concealing Fiduciary
Breach.--
(1) In general.--Section 409 of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1109) is amended by
redesignating subsection (b) as subsection (d) and by inserting
after subsection (a) the following new subsections:
``(b)(1) If an insider with respect to the plan sponsor of an
individual account plan that holds employer securities that are readily
tradable on an established securities market knowingly participates in,
or knowingly undertakes to conceal, an act or omission of fiduciary
responsibility knowing such act or omission is a breach of fiduciary
responsibility, such insider shall be personally liable under this
subsection to the plan or to any participant or beneficiary of the plan
for such breach in the same manner as the fiduciary who commits such
breach.
``(2) For purposes of paragraph (1), the term `insider' means, with
respect to any plan sponsor of a plan to which paragraph (1) applies--
``(A) any officer (as defined in section 240.3b-2 of title
17 of the Code of Federal Regulations, as in effect on the date
of the enactment of this clause) or director with respect to
the plan sponsor, or
``(B) any independent qualified public accountant of the
plan or of the plan sponsor.
``(c) In the case of an individual account plan, any relief
provided under this section shall, to the extent the court may deem
appropriate, inure to the individual account of any individual affected
by the breach (or directly to such individual in the absence of an
individual account). Nothing in this subsection shall be construed to
give rise to any inference of the existence or nonexistence of a right
under this section, section 502, or any other provision of this
title.''
(2) Conforming amendment.--Section 409(d) of such Act (29
U.S.C. 1109(c)), as redesignated by paragraph (1), is amended
by inserting before the period the following: ``, unless such
liability arises under subsection (b)''.
(b) Maintenance of Fiduciary Liability.--Section 404(c)(1)(A)(ii)
of such Act (29 U.S.C. 1104(c)(1)(A)(ii)), as amended by section
202(a), is amended by inserting before the period the following: ``and
shall not be construed to exempt any fiduciary from liability for any
violation of subsection (e) or (g)''.
(c) Effective Dates.--
(1) In general.--The amendments made by this section shall
apply with respect to breaches of fiduciary responsibility
occurring on or after the date of the enactment of this Act.
(2) Relief to individuals.--Section 409(c) of the Employee
Retirement Income Security Act of 1974, as added by this
section, shall apply to actions which are pending on, or
commenced on or after, the date of the enactment of this Act.

SEC. 204. INCREASE IN MAXIMUM BOND AMOUNT AND INSURANCE ADEQUATE TO
PROTECT INTEREST OF PARTICIPANTS AND BENEFICIARIES.

(a) In General.--Section 412(a) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1112) is amended by adding at the end
the following: ``In the case of a plan that holds employer securities
(within the meaning of section 407(d)(1)), this subsection shall be
applied by substituting `$1,000,000' for `$500,000' each place it
appears.''
(b) Additional Requirements for Applicable Individual Account
Plans.--Section 412 of the Employee Retirement Income Security Act of
1974 (29 U.S.C. 1112) is amended by adding at the end the following new
subsection:
``(f) Notwithstanding the preceding provisions of this section,
each fiduciary of an individual account plan which covers more than 100
participants shall be insured, in accordance with regulations
prescribed by the Secretary, to provide reasonable coverage for
failures to meet the requirements of this part.''
(c) Effective Dates.--
(1) In general.--The amendment made by this section shall
take effect on the date on which the regulations required to be
promulgated under section 412(f) of the Employee Retirement
Income Security Act of 1974 become final.
(2) Regulations.--The Secretary of Labor shall prescribe
the regulations necessary to carry out section 412(f) of the
Employee Retirement Income Security Act of 1974, as added by
this section, not later than one year after the date of the
enactment of this Act.

SEC. 205. PARTICIPATION OF PARTICIPANTS IN TRUSTEESHIP OF INDIVIDUAL
ACCOUNT PLANS.

(a) In General.--Section 403(a) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1103(a)) is amended--
(1) by redesignating paragraphs (1) and (2) as
subparagraphs (A) and (B), respectively;
(2) by inserting ``(1)'' after ``(a)''; and
(3) by adding at the end the following new paragraph:
``(2)(A) The assets of a single-employer plan which is an
individual account plan which covers more than 100 participants shall
be held in trust by a joint board of trustees, which shall consist of
two or more trustees representing on an equal basis the interests of
the employer or employers maintaining the plan and the interests of the
participants and their beneficiaries.
``(B)(i) Except as provided in clause (ii), in any case in which
the plan is maintained pursuant to one or more collective bargaining
agreements between one or more employee organizations and one or more
employers, the trustees representing the interests of the participants
and their beneficiaries shall be designated by such employee
organizations.
``(ii) Clause (i) shall not apply with respect to a plan described
in such clause if the employee organization (or all employee
organizations, if more than one) referred to in such clause file with
the Secretary, in such form and manner as shall be prescribed in
regulations of the Secretary, a written waiver of their rights under
clause (i).
``(iii) In any case in which clause (i) does not apply with respect
to a single-employer plan because the plan is not described in clause
(i) or because of a waiver filed pursuant to clause (ii), the trustee
or trustees representing the interests of the participants and their
beneficiaries shall be elected by the participants in accordance with
regulations of the Secretary. An individual shall not be treated as
ineligible for selection as trustee solely because such individual is
an employee of the plan sponsor, except that the employee so selected
may not be a highly compensated employee (as defined in section 414(q)
of the Internal Revenue Code of 1986).
``(iv) The Secretary shall provide by regulation for the
appointment of a neutral, in accordance with the procedures under
section 203(f) of the Labor Management Relations Act, 1947 (29 U.S.C.
173(f)), to cast votes as necessary to resolve tie votes by the
trustees.''
(b) Regulations.--The Secretary of Labor shall prescribe the
initial regulations necessary to carry out the provisions of the
amendments made by this section not later than 90 days after the date
of the enactment of this Act.

TITLE III--INFORMATION TO ASSIST PENSION PLAN PARTICIPANTS

SEC. 301. PERIODIC PENSION BENEFIT STATEMENTS.

(a) Periodic Pension Benefit Statements.--
(1) In general.--Section 105(a) of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1025(a)) is amended to
read as follows:
``(a)(1)(A) The administrator of an individual account plan (other
than a one-participant retirement plan described in section
101(i)(8)(B)) shall furnish a pension benefit statement--
``(i) at least once each calendar quarter to a participant
or beneficiary who has the right to direct the investment of
assets in his or her account under the plan,
``(ii) at least once each calendar year to a participant or
beneficiary who has his or her own account under the plan but
does not have the right to direct the investment of assets in
that account, and
``(iii) upon written request to a plan beneficiary not
described in clause (i) or (ii).
``(B) The administrator of a defined benefit plan shall furnish a
pension benefit statement--
``(i) at least once every 3 years to each participant with
a nonforfeitable accrued benefit, and
``(ii) to a participant or beneficiary of the plan upon
written request.
Information furnished under clause (i) to a participant may be based on
reasonable estimates determined under regulations prescribed by the
Secretary, in consultation with the Pension Benefit Guaranty
Corporation.
``(2)(A) A pension benefit statement under paragraph (1)--
``(i) shall indicate, on the basis of the latest available
information--
``(I) the total benefits accrued, and
``(II) the nonforfeitable pension benefits, if any,
which have accrued, or the earliest date on which
benefits will become nonforfeitable,
``(ii) shall include an explanation of any offsets that may
be applied in determining any accrued benefits described in
clause (i),
``(iii) shall be written in a manner calculated to be
understood by the average plan participant, and
``(iv) may be delivered in written, electronic, or other
appropriate form to the extent such form is reasonably
accessible to the participant or beneficiary.
``(B) In the case of an individual account plan, the pension
benefit statement under clause (i) or (ii) of paragraph (1)(A) shall
include--
``(i) the value of each investment to which assets in the
individual account have been allocated, determined as of the
most recent valuation date under the plan, including the value
of any assets held in the form of employer securities, without
regard to whether such securities were contributed by the plan
sponsor or acquired at the direction of the plan or of the
participant or beneficiary,
``(ii) an explanation of any limitations or restrictions on
any right of the participant or beneficiary under the plan to
direct an investment, and
``(iii) if the percentage of assets in the individual
account that consists of employer securities and employer real
property (as defined in paragraphs (1) and (2), respectively,
of section 407(d)), determined as of the most recent valuation
date under the plan, exceeds 20 percent of the total account, a
notice that the account may be overinvested in employer
securities and employer real property.
Employer securities and employer real property held by a plan by reason
of a pooled investment vehicle described in section 204(j)(5)(B) shall
be excluded for purposes of clause (iii) from the calculation of the
assets in an account that consist of employer securities and employer
real property. Clause (iii) shall not apply to any plan to which
section 204(j) does not apply.
``(3)(A) In the case of a defined benefit plan, the requirements of
paragraph (1)(B)(i) shall be treated as met with respect to a
participant if at least once each year the administrator provides to
the participant at the participant's last known address notice of the
availability of the pension benefit statement and the ways in which the
participant may obtain such statement. Such notice may be delivered in
written, electronic, or other appropriate form to the extent such form
is reasonably accessible to the participant.
``(B) The Secretary may provide that years in which no employee or
former employee benefits (within the meaning of section 410(b) of the
Internal Revenue Code of 1986) under the plan need not be taken into
account in determining the 3-year period under paragraph (1)(B)(i).
``(C) The Secretary may provide that the requirements of paragraph
(2)(A)(i)(II) are met if, at least annually, the plan--
``(i) updates the information described in such paragraph
which is provided in the pension benefit statement, or
``(ii) provides such information in a separate statement.''
(b) Inclusion of Funded Liability Percentage in Annual Report.--
Section 103(d) of the Employee Retirement Income Security Act of 1974
(29 U.S.C. 1023(d)) is amended by redesignating paragraphs (12) and
(13) as paragraphs (13) and (14), respectively, and by adding after
paragraph (11) the following new paragraph:
``(12) In the case of a plan with more than 100
participants, the funded current liability percentage (as
defined in section 302(d)(8)(B)) for the current plan year and
the immediately preceding plan year, including all calculations
necessary to determine such percentage.''
(c) Conforming Amendments.--
(1) Section 105 of the Employee Retirement Income Security
Act of 1974 (29 U.S.C. 1025) is amended by striking subsection
(d).
(2) Section 105(b) of such Act (29 U.S.C. 1025(b)) is
amended to read as follows:
``(b) In no case shall a participant or beneficiary of a plan be
entitled to more than 1 statement described in subsection (a)(1)
(A)(iii) or (B)(ii), whichever is applicable, in any 12-month period.''
(d) Model Statements.--The Secretary of Labor shall develop 1 or
more model benefit statements, written in a manner calculated to be
understood by the average plan participant, that may be used by plan
administrators in complying with the requirements of section 105 of the
Employee Retirement Income Security Act of 1974.
(e) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.
(2) Special rule for collectively bargained agreements.--In
the case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, subsection (a) shall be applied to benefits
pursuant to, and individuals covered by, any such agreement by
substituting for ``December 31, 2003'' the earlier of--
(A) the later of--
(i) December 31, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after such date of enactment), or
(B) December 31, 2005.

SEC. 302. DEFINED CONTRIBUTION PLANS REQUIRED TO PROVIDE ADEQUATE
INVESTMENT EDUCATION TO PARTICIPANTS.

(a) Adequate Investment Education.--
(1) In general.--Section 104 of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1024), as amended by
sections 102 and 103, is amended by redesignating subsection
(f) as subsection (g) and by inserting after subsection (e) the
following new subsection:
``(f)(1) The plan administrator of an individual account plan
(other than a one-participant retirement plan described in section
101(i)(8)(B)) shall furnish at least once each year to each participant
or beneficiary who has the right to direct the investment of assets in
his or her account the model form relating to basic investment
guidelines which is described in paragraph (2).
``(2)(A) The Secretary shall develop and make available to
individual account plans for distribution under paragraph (1) a model
form containing basic guidelines for investing for retirement. Such
guidelines shall include--
``(i) information on the benefits of diversification,
``(ii) information on the essential differences, in terms
of risk and return, of pension plan investments, including
stocks, bonds, mutual funds, and money market investments,
``(iii) information on how an applicable individual's
pension plan investment allocations may differ depending on the
individual's age and years to retirement and on other factors
determined by the Secretary,
``(iv) sources of information where applicable individuals
may learn more about pension rights, individual investing, and
investment advice, and
``(v) such other information related to individual
investing as the Secretary determines appropriate.
``(B) The model form under subparagraph (A) shall include addresses
for Internet sites, and a worksheet, which an applicable individual may
use to calculate--
``(i) the retirement age annuity value of the applicable
individual's nonforfeitable pension benefits under the plan
(determined by reference to varied historical annual rates of
return and annuity interest rates), and
``(ii) other important amounts relating to retirement
savings, including the amount which an applicable individual
would be required to save annually to provide a retirement
income equal to various replacement of their current salary
(adjusted for expected growth prior to retirement).
The Secretary shall develop an Internet site which an applicable
individual may use in making such calculations and the address for such
site shall be included with the form.
``(C) The Secretary shall provide at least 90 days for public
comment before publishing final notice of the model form.
``(3) The model form under paragraph (2)--
``(A) shall be written in a manner calculated to be
understood by the average plan participant, and
``(B) may be delivered in written, electronic, or other
appropriate form to the extent such form is reasonably
accessible to applicable individuals.''
(2) Enforcement.--Section 502(c)(7) of such Act (29 U.S.C.
1132(c)(7)), as amended by sections 102 and 103, is amended by
striking ``subsection (d) or (e)'' and inserting ``subsection
(d), (e), or (f)''.
(b) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to plan years beginning after December 31, 2004.
(2) Special rule for collectively bargained agreements.--In
the case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, subsection (a) shall be applied to benefits
pursuant to, and individuals covered by, any such agreement by
substituting for ``December 31, 2003'' the earlier of--
(A) the later of--
(i) December 31, 2005, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after such date of enactment), or
(B) December 31, 2006.

SEC. 303. FIDUCIARY DUTY TO PROVIDE MATERIAL INFORMATION RELATING TO
INVESTMENT IN EMPLOYER SECURITIES.

(a) In General.--Section 404(c) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1104(c)) is amended by adding at the
end the following new paragraph:
``(4) The plan sponsor and plan administrator of a pension plan
described in paragraph (1) shall, in addition to any other fiduciary
duty or responsibility under this part, have a fiduciary duty to ensure
that each participant and beneficiary under the plan, in connection
with the investment of assets in his or her account in employer
securities, is provided with all reports, proxy statements, and other
communications regarding investment of such assets in employer
securities to the extent that such reports, statements, and
communications are generally required to be provided by the plan
sponsor to investors in connection with such an investment under
applicable securities laws. Such reports, statements, and
communications may be delivered in written, electronic, or other
appropriate form to the extent such form is reasonably accessible to
participants and beneficiaries.''
(b) Enforcement.--Section 502 of such Act (29 U.S.C. 1132) is
amended--
(1) in subsection (a)(6), by striking ``(6), or (7)'' and
inserting ``(6), (7), or (8)'';
(2) by redesignating paragraph (8) of subsection (c) as
paragraph (9); and
(3) by inserting after paragraph (7) of subsection (c) the
following new paragraph:
``(8) The Secretary may assess a civil penalty against any person
of up to $1,000 a day from the date of the person's failure or refusal
to comply with the requirements of section 404(c)(4) until such failure
or refusal is corrected.''
(c) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.

SEC. 304. FIDUCIARY RESPONSIBILITY TO CERTIFY INVESTMENTS IN EMPLOYER
SECURITIES AS PRUDENT INVESTMENTS.

(a) In General.--Section 404 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1104), as amended by this Act, is
amended by adding at the end the following new subsection:
``(g) Certification of Investment Option as Prudent.--In the case
of an applicable individual account plan (as defined in section
204(j))--
``(1) which permits a plan participant or beneficiary to
direct the investment of the assets in his or her account, and
``(2) in connection with an investment option offered under
the plan (other than a pooled investment vehicle described in
section 204(j)(5)(B)), allows the participant or beneficiary to
invest directly in publicly traded employer securities (within
the meaning of section 204(j)),
the named fiduciary of the plan or the fiduciary responsible for
determining plan investment options shall, in addition to any other
fiduciary responsibility or duty, certify to the Secretary in the
annual report required under section 103 that the fiduciary has
evaluated any investment option described in paragraph (2) and found it
to meet the requirements of subsection (a). This subsection shall not
apply in the case of an investment in employer securities made at the
direction of a participant or beneficiary through a brokerage account
available in connection with the plan.''
(b) Inclusion in Report.--Section 103(c) of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1023(c)) is amended by adding at
the end the following new paragraph:
``(6) The certification required under section 404(g).''
(c) Effective Date.--
(1) In general.--The amendment made by this section shall
apply to plan years beginning after the date on which the
Secretary of Labor issues the regulations described in
paragraph (2).
(2) Regulations.--The Secretary of Labor shall prescribe
regulations to implement section 404(g) of the Employee
Retirement Income Security Act of 1974 (as added by subsection
(a)) no later than 1 year after the date of the enactment of
this Act.

SEC. 305. FIDUCIARY RULES FOR PLAN SPONSORS DESIGNATING INDEPENDENT
INVESTMENT ADVISERS.

(a) In General.--Section 404 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1104), as amended by this Act, is
amended by adding at the end the following new subsection:
``(h) Independent Investment Adviser.--
``(1) In general.--In the case of an individual account
plan which permits a plan participant or beneficiary to direct
the investment of the assets in his or her account, if a plan
sponsor or other person who is a fiduciary designates and
monitors a qualified investment adviser pursuant to the
requirements of paragraph (3), such fiduciary--
``(A) shall be deemed to have satisfied the
requirements under this section for the prudent
designation and periodic review of an investment
adviser with whom the plan sponsor or other person who
is a fiduciary enters into an arrangement for the
provision of advice referred to in section
3(21)(A)(ii),
``(B) shall not be liable under this section for
any loss, or by reason of any breach, with respect to
the provision of investment advice given by such
adviser to any plan participant or beneficiary, and
``(C) shall not be liable for any co-fiduciary
liability under subsections (a)(2) and (b) of section
405 with respect to the provision of investment advice
given by such adviser to any plan participant or
beneficiary.
``(2) Qualified investment adviser.--
``(A) In general.--For purposes of this subsection,
the term `qualified investment adviser' means, with
respect to a plan, a person--
``(i) who is a fiduciary of the plan by
reason of the provision of investment advice by
such person to a plan participant or
beneficiary;
``(ii) who--
``(I) is registered as an
investment adviser under the Investment
Advisers Act of 1940 (15 U.S.C. 80b-1
et seq.),
``(II) is registered as an
investment adviser under the laws of
the State in which such adviser
maintains the principal office and place of business of such adviser,
but only if such State laws are consistent with section 203A of the
Investment Advisers Act of 1940 (15 U.S.C. 80b-3a),
``(III) is a bank or similar
financial institution referred to in
section 408(b)(4),
``(IV) is an insurance company
qualified to do business under the laws
of a State, or
``(V) is any other comparably
qualified entity which satisfies such
criteria as the Secretary determines
appropriate, consistent with the
purposes of this subsection, and
``(iii) who meets the requirements of
subparagraph (B).
``(B) Adviser requirements.--The requirements of
this subparagraph are met if every individual employed
(or otherwise compensated) by a person described in
subparagraph (A)(ii) who provides investment advice on
behalf of such person to any plan participant or
beneficiary is--
``(i) an individual described in subclause
(I) of subparagraph (A)(ii),
``(ii) an individual described in subclause
(II) of subparagraph (A)(ii), but only if such
State has an examination requirement to qualify
for registration,
``(iii) registered as a broker or dealer
under the Securities Exchange Act of 1934 (15
U.S.C. 78a et seq.),
``(iv) a registered representative as
described in section 3(a)(18) of the Securities
Exchange Act of 1934 (15 U.S.C. 78c(a)(18)) or
section 202(a)(17) of the Investment Advisers
Act of 1940 (15 U.S.C. 80b-2(a)(17)), or
``(v) any other comparably qualified
individual who satisfies such criteria as the
Secretary determines appropriate, consistent
with the purposes of this subsection.
``(3) Verification requirements.--The requirements of this
paragraph are met if--
``(A) the plan sponsor or other person who is a
fiduciary in designating a qualified investment adviser
receives at the time of the designation, and annually
thereafter, a written verification from the qualified
investment adviser that the investment adviser--
``(i) is and remains a qualified investment
adviser,
``(ii) acknowledges that the investment
adviser is a fiduciary with respect to the plan
and is solely responsible for its investment
advice,
``(iii) has reviewed the plan documents
(including investment options) and has
determined that its relationship with the plan
and the investment advice provided to any plan
participant or beneficiary, including any fees
or other compensation it will receive, will not
constitute a violation of section 406,
``(iv) will, in providing investment advice
to any participant or beneficiary, consider any
employer securities or employer real property
allocated to his or her account, and
``(v) has the necessary insurance coverage
(as determined by the Secretary) for any claim
by any plan participant or beneficiary,
``(B) the plan sponsor or other person who is a
fiduciary in designating a qualified investment adviser
reviews the documents described in paragraph (4)
provided by such adviser and determines that there is
no material reason not to enter into an arrangement for
the provision of advice by such qualified investment
adviser, and
``(C) the plan sponsor or other person who is a
fiduciary in designating a qualified investment
adviser, within 30 days of having information brought
to its attention that the investment adviser is no
longer qualified or that a substantial number of plan
participants or beneficiaries have raised concerns
about the services being provided by the investment
adviser--
``(i) investigates such information and
concerns, and
``(ii) determines that there is no material
reason not to continue the designation of the
adviser as a qualified investment adviser.
``(4) Documentation.--A qualified investment adviser shall
provide the following documents to the plan sponsor or other
person who is a fiduciary in designating the adviser:
``(A) The contract with the plan sponsor or other
person who is a fiduciary for the services to be
provided by the investment adviser to the plan
participants and beneficiaries.
``(B) A disclosure as to any fees or other
compensation that will be received by the investment
adviser for the provision of such investment advice or
as to any fees or other compensation that will be
received as a result of a participant's investment
election.
``(C) The Uniform Application for Investment
Adviser Registration as filed with the Securities and
Exchange Commission or a substantially similar
disclosure application as determined by and filed with
the Secretary.
``(5) Treatment as fiduciary.--Any qualified investment
adviser that acknowledges it is a fiduciary pursuant to
paragraph (3)(A)(ii) shall be deemed a fiduciary under this
part with respect to the provision of investment advice to a
plan participant or beneficiary.''
(b) Fiduciary Liability.--Section 404(c)(1)(B) is amended by
inserting ``(other than a qualified investment adviser)'' after
``fiduciary''.
(c) Effective Date.--The amendment made by this section shall apply
with respect to investment advisers designated after the date of the
enactment of this Act.

SEC. 306. PROVISIONS RELATING TO WHISTLEBLOWER ACTIONS INVOLVING
PENSION PLANS.

(a) Authority To Bring Actions.--Section 502(a) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1132(a)) is amended
by striking ``or'' at the end of paragraph (8), by striking the period
at the end of paragraph (9) and inserting ``; or'', and by adding at
the end the following new paragraph:
``(10) by the Secretary, or other person referred to in
section 510--
``(A) to enjoin any act or practice which violates
section 510 in connection with a pension plan, or
``(B) to obtain--
``(i) either--
``(I) reinstatement with the same
seniority status that the employee
would, but for such violation, have
had, or
``(II) if reinstatement is not
practicable or cannot be ordered
without delay, payment (for such period
as the court determines appropriate) of
the pay, including benefits, that would
have been received if the employee had
been reinstated,
``(ii) payment of back pay, including
benefits and interest, and
``(iii) reasonable attorney fees and costs
based upon the same standards as are used in
awarding attorney fees and costs under
subsection (g)(1).''
(b) Additional Actions Which May Be Brought.--Section 510 of the
Employee Retirement Income Security Act of 1974 (29 U.S.C. 1140) is
amended by striking all after ``person because'' in the second sentence
and inserting ``the person--
``(1) has provided information, caused information to be
provided, or otherwise assisted in an investigation, inquiry,
or proceeding regarding any conduct which the employee
reasonably believes constitutes a violation of this Act or of
the Welfare and Pension Plans Disclosure Act in connection with
a pension plan if the information or assistance is provided to,
or the investigation is conducted by--
``(A) a Federal regulatory or law enforcement
agency,
``(B) any Member of Congress or any committee of
Congress, or
``(C) a person with supervisory authority over the
employee (or any other person working for the employer
who has the authority to investigate, discover, or
terminate misconduct), or
``(2) has (with any knowledge of the employer) filed,
caused to be filed, testified, participated in, or assisted in
a proceeding filed or about to be filed in connection with an
alleged violation of this Act involving a pension plan.
The provisions of section 502 shall be applicable in the enforcement of
this section.''

SEC. 307. INCREASE IN PENALTIES FOR COERCIVE INTERFERENCE.

(a) In General.--Section 511 of the Employment Retirement Income
Security Act of 1974 (29 U.S.C. 1141) is amended--
(1) by striking ``$10,000'' and inserting ``$100,000'', and
(2) by striking ``one year'' and inserting ``5 years''.
(b) Effective Date.--The amendments made by this section shall
apply to violations occurring on and after the date of the enactment of
this Act.

TITLE IV--RETIREMENT SECURITY

SEC. 401. SHORT TITLE; ETC.

(a) Short Title.--This title may be cited as the ``Retirement
Security for All Americans Act''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this title an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.

SEC. 402. EXPANSION OF RETIREMENT SAVINGS CREDIT.

(a) Credit To Be Refundable; Expansion of Eligibility; Credit Made
Permanent.--Subpart C of part IV of subchapter A of chapter 1 (relating
to refundable credits) is amended by redesignating section 35 as
section 36 and by inserting after section 34 the following new section:

``SEC. 35. ELECTIVE DEFERRALS AND INDIVIDUAL RETIREMENT PLAN ACCOUNT
CONTRIBUTIONS BY CERTAIN INDIVIDUALS.

``(a) Allowance of Credit.--In the case of an eligible individual,
there shall be allowed as a credit against the tax imposed by this
subtitle for the taxable year an amount equal to the applicable
percentage of so much of the qualified retirement savings contributions
of the eligible individual for the taxable year as do not exceed
$2,000.
``(b) Applicable Percentage.--For purposes of this section--
``(1) In general.--The applicable percentage is 50 percent,
reduced (but not below zero) by the percentage determined under
paragraph (2).
``(2) Amount of reduction.--The percentage determined under
this paragraph shall be equal to the ratio that--
``(A) the excess of--
``(i) the taxpayer's adjusted gross income
for such taxable year, over
``(ii) the applicable dollar amount, bears
to
``(B) the phaseout range.
``(3) Applicable dollar amount.--The applicable dollar
amount equals $30,000 in the case of a taxpayer filing a joint
return, $22,500 in the case of a taxpayer filing as a head of a
household (as defined in section 2(b)), and $15,000 in the case of all
other taxpayers.
``(4) Phaseout range.--The phaseout range equals $25,000 in
the case of a taxpayer filing a joint return, $18,750 in the
case of a taxpayer filing as a head of a household (as so
defined), and $12,500 in the case of all other taxpayers.
``(c) Eligible Individual.--For purposes of this section--
``(1) In general.--The term `eligible individual' means any
individual if such individual has attained the age of 18 as of
the close of the taxable year.
``(2) Dependents and full-time students not eligible.--The
term `eligible individual' shall not include--
``(A) any individual with respect to whom a
deduction under section 151 is allowed to another
taxpayer for a taxable year beginning in the calendar
year in which such individual's taxable year begins,
and
``(B) any individual who is a student (as defined
in section 151(c)(4)).
``(d) Qualified Retirement Savings Contributions.--For purposes of
this section--
``(1) In general.--The term `qualified retirement savings
contributions' means, with respect to any taxable year, the sum
of--
``(A) the amount of the qualified retirement
contributions (as defined in section 219(e)) made by
the eligible individual,
``(B) the amount of--
``(i) any elective deferrals (as defined in
section 402(g)(3)) of such individual, and
``(ii) any elective deferral of
compensation by such individual under an
eligible deferred compensation plan (as defined
in section 457(b)) of an eligible employer
described in section 457(e)(1)(A), and
``(C) the amount of voluntary employee
contributions by such individual to any qualified
retirement plan (as defined in section 4974(c)).
``(2) Reduction for certain distributions.--
``(A) In general.--The qualified retirement savings
contributions determined under paragraph (1) shall be
reduced (but not below zero) by the aggregate
distributions received by the individual during the
testing period from any entity of a type to which
contributions under paragraph (1) may be made. The
preceding sentence shall not apply to the portion of
any distribution which is not includible in gross
income by reason of a trustee-to-trustee transfer or a
rollover distribution.
``(B) Testing period.--For purposes of subparagraph
(A), the testing period, with respect to a taxable
year, is the period which includes--
``(i) such taxable year,
``(ii) the 2 preceding taxable years, and
``(iii) the period after such taxable year
and before the due date (including extensions)
for filing the return of tax for such taxable
year.
``(C) Excepted distributions.--There shall not be
taken into account under subparagraph (A)--
``(i) any distribution referred to in
section 72(p), 401(k)(8), 401(m)(6), 402(g)(2),
404(k), or 408(d)(4), and
``(ii) any distribution to which section
408A(d)(3) applies.
``(D) Treatment of distributions received by spouse
of individual.--For purposes of determining
distributions received by an individual under
subparagraph (A) for any taxable year, any distribution
received by the spouse of such individual shall be
treated as received by such individual if such
individual and spouse file a joint return for such
taxable year and for the taxable year during which the
spouse receives the distribution.
``(e) Adjusted Gross Income.--For purposes of this section,
adjusted gross income shall be determined without regard to sections
911, 931, and 933.
``(f) Investment in the Contract.--Notwithstanding any other
provision of law, a qualified retirement savings contribution shall not
fail to be included in determining the investment in the contract for
purposes of section 72 by reason of the credit under this section.''.
(b) Credit Treated as Overpayment of Tax.--Section 6401(b)
(relating to excessive credits) is amended--
(1) by striking ``If'' in paragraph (1) and inserting
``Except as provided in paragraph (3)'', and
(2) by adding at the end the following new paragraph:
``(3) Special rule for credit under section 35.--If the
amount allowable as a credit under section 35 (relating to
retirement savings credit) for any taxable year exceeds the tax
imposed for such taxable year by subtitle A (reduced by the
credits allowable under subparts A, B, D, and G of part IV of
subchapter A of chapter 1), the amount of such excess shall be
considered an overpayment and shall be subject to the
provisions of section 6401(1).''.
(c) Transfer of Overpayment To Secure Retirement Savings Bond.--
Section 6402 (relating to authority to make credits or refunds) is
amended by adding at the end the following new subsection:
``(l) Transfer of Overpayment To Secure Retirement Savings Bond.--
``(1) In general.--In the case of any overpayment described
in section 6401(b)(3), the Secretary shall, in the name of the
taxpayer, issue a Secure Retirement savings bond under section
3105(f)(1) of title 31, United States Code, in an amount equal to such
overpayment.
``(2) Joint returns.--In the case of a taxpayer filing a
joint return, any overpayment described in section 6401(b)(3)
shall be divided equally among both spouses, and the Secretary
shall, separately in the name of each spouse, issue a Secure
Retirement savings bond under section 3105(f)(1) of title 31,
United States Code, in an amount equal to such overpayments.''
(d) Secure Retirement Savings Bonds.--Section 3105 of title 31,
United States Code, is amended by adding at the end the following new
subsection:
``(f)(1) The Secretary shall issue Secure Retirement savings bonds
as required under section 6402(l) of the Internal Revenue Code of 1986.
``(2) For purposes of paragraph (1), a Secure Retirement savings
bond is an inflation-indexed savings bond otherwise authorized to be
issued under this section, except that, notwithstanding any other
provision of this section, such bond shall not mature before the
earlier of the date on which the bondholder--
``(A) dies;
``(B) becomes disabled (within the meaning of section
72(m)(7) of the Internal Revenue Code of 1986); or
``(C) attains social security retirement age under section
216(l)(2) of the Social Security Act (without regard to any
early retirement age permitted under such section).
``(3) The Secretary may, in lieu of actually issuing Secure
Retirement savings bonds, provide an annual account statement to the
bondholder reflecting the current value of the bonds, including accrued
interest, nominally issued on behalf of such bondholder.''
(e) Repeal of Nonrefundable Credit.--
(1) Section 25B is hereby repealed.
(2) Subparagraph (B) of section 25(b)(3) is amended by
striking ``and 25B''.
(3) Subparagraph (C) of section 25(e)(1) is amended by
striking ``25B,''.
(4) Sections 26(a)(1), 901(h), and 1400C are each amended
by striking ``24, and 25B'' and inserting ``and 24''.
(5) The table of sections for subpart A of part IV of
subchapter A of chapter 1 is amended by striking the item
relating to section 25B.
(f) Technical Amendments.--
(1) Paragraph (2) of section 1324(b) of title 31, United
States Code, is amended by inserting before the period ``, or
from section 35 of such Code''.
(2) The table of sections for subpart C of part IV of
subchapter A of chapter 1 is amended by striking the last item
and inserting the following new items:

``Sec. 35. Elective deferrals and
individual retirement plan
account contributions by
certain individuals.
``Sec. 36. Overpayments of tax.''.
(g) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 403. UNIVERSAL ACCESS TO DIRECT DEPOSIT RETIREMENT SAVINGS.

(a) In General.--Chapter 43 (relating to qualified pension, etc.,
plans) is amended by adding at the end the following new section:

``SEC. 4980G. REQUIREMENTS FOR EMPLOYERS TO PROVIDE EMPLOYEES ACCESS TO
SALARY REDUCTION CONTRIBUTIONS TO INDIVIDUAL RETIREMENT
PLANS.

``(a) General Rule.--There is hereby imposed a tax on any failure
by an employer to meet the requirements of subsection (d) for a
calendar year.
``(b) Amount.--The amount of the tax imposed by subsection (a) on
any failure for any calendar year shall be $100 with respect to each
employee to whom such failure relates.
``(c) Procedures for Notice and Grace Period.--Not later than 6
months after the date of the enactment of this section, the Secretary
shall prescribe and initiate implementation of procedures for obtaining
from employers confirmation that such employers are in compliance with
the requirements of subsection (d). The Secretary, in the Secretary's
discretion, may prescribe that the confirmation shall be obtained on an
annual or less frequent basis, and may use for this purpose the annual
report or quarterly report for employment taxes, or such other means as
the Secretary may deem advisable. The tax imposed by subsection (a)
shall not be imposed with respect to any failure that ends before the
expiration of 90 days after the employer has responded or has had a
reasonable opportunity to respond to a request for confirmation of
compliance.
``(d) Employee Access to Salary Reduction Contributions to
Individual Retirement Plans.--
``(1) In general.--Every employer which does not maintain a
qualified plan or arrangement for a calendar year shall provide
a salary reduction arrangement for the calendar year which
meets the requirements of paragraphs (3), (4) and (5).
``(2) Qualified plan or arrangement.--For purposes of this
section, an employer is treated as maintaining a qualified plan
or arrangement for a calendar year if the employer maintains
for such year a plan, contract, pension, or trust described in
subparagraph (A) or (B) of section 219(g)(5) or an eligible
deferred compensation plan (within the meaning of section
457(b)) with respect to which contributions are made, or
benefits are accrued, for service in such year.
``(3) Salary reduction arrangement.--For purposes of this
section, the term `salary reduction arrangement' means a
written arrangement of an employer under which--
``(A) an employee eligible to participate in the
arrangement may elect to--
``(i) contribute to an individual
retirement plan established by or on behalf of
the employee by having the employer make direct
deposit payments to the plan by payroll
deduction, or
``(ii) receive the amounts directly as cash
compensation, and
``(B) no other contributions may be made under the
arrangement.
``(4) Participation requirements.--
``(A) In general.--The requirements of this
paragraph are met with respect to a salary reduction
arrangement for a year only if, under the arrangement,
all employees of the employer are eligible to make the
election under paragraph (3)(A).
``(B) Excludable employees.--An employer may
exclude from the requirement under paragraph (3)
employees described in section 410(b)(3) and any
employee who has not completed hours of service for the
employer on a regular basis during a period of at least
30 consecutive days during the calendar year.
``(5) Administrative requirements.--The requirements of
this paragraph are met with respect to any salary reduction
arrangement if, under the arrangement--
``(A) the employer must make the payments elected
under paragraph (3)(A) not later than the close of the
30-day period following the last day of the month with
respect to which the contributions are to be made, or,
if later, the deadline under applicable rules and
regulations for the employer to deposit tax under
section 3102 for wages paid in that month,
``(B) an employee may elect to terminate
participation in the arrangement at any time during the
year, except that if an employee so terminates, the
arrangement may provide that the employee may not elect
to resume participation until the beginning of the next
year,
``(C) each employee eligible to participate may
elect, during the 60-day period before the beginning of
any year (and the 60-day period before the first day
the employee is eligible to participate), to
participate in the arrangement, or to modify the
amounts subject to the arrangement, for such year, and
``(D) immediately before the period for which an
election described in paragraph (3)(A) may be made, the
employer provides a notice to each employee of the
employee's opportunity to make the election and the
maximum amount which may be contributed to an
individual retirement plan on an annual basis.
``(6) Exception for certain small employers.--The
requirements of this subsection shall not apply for any
calendar year to an employer which had not more than 10
employees who received at least $5,000 of compensation from the
employer for the preceding calendar year.
``(7) Use of designated financial institution.--An employer
shall not be treated as failing to satisfy the requirements of
this subsection or any other provision of this title merely
because the employer makes all contributions (or all
contributions on behalf of employees who do not specify an
individual retirement plan, trustee, or issuer to receive the
contributions) to individual retirement plans of a designated
trustee or issuer. The preceding sentence shall not apply
unless each participant is notified in writing that the
participant's balance may be transferred without cost or
penalty to another individual retirement plan in accordance
with subsection (d)(3).
``(8) Model notice.--The Secretary shall provide a model
notice, written in a manner calculated to be understandable to
the average worker, that employers may use to satisfy the
requirement of paragraphs (5)(D) and (7). Model notices shall
be provided in English, in Spanish, and in any other language
deemed appropriate by the Secretary.
``(e) Salary Reduction Contributions Treated Like Other
Contributions to Individual Retirement Plans.--
``(1) Tax treatment unaffected.--The fact that a
contribution to an individual retirement plan is made on behalf
of an employee under a salary reduction arrangement instead of
being made directly by the employee shall not affect the
deductibility or other income tax treatment of the contribution
or of other amounts under this title.
``(2) Salary reduction contributions taken into account.--
Any contribution made on behalf of an employee under a salary
reduction arrangement shall be taken into account in applying
the limitations on contributions to individual retirement plans
and the other provisions of this title applicable to individual
retirement plans as if the contribution had been made to the
plan directly by the employee.''.
(b) Credit for Small Employers Maintaining Salary Reduction
Arrangements Facilitating Employee Contributions to Individual
Retirement Plans.--
(1) In general.--Subpart D of part IV of subchapter A of
chapter 1 (relating to business related credits) is amended by
adding at the end the following new section:

``SEC. 45G. SMALL EMPLOYER SALARY REDUCTION COSTS.

``(a) General Rule.--For purposes of section 38, in the case of an
eligible employer, the small employer salary reduction cost credit
determined under this section for any taxable year is the amount
determined under subsection (b).
``(b) Amount of Credit.--The amount of the credit determined under
this section for any taxable year with respect to an eligible employer
shall be--
``(1) $200 for the taxable year which includes the date
that the arrangement referred to in subsection (a) becomes
effective, and
``(2) $50 for each subsequent taxable year during which the
arrangement is in effect.
``(c) Eligible Employer.--For purposes of this section, the term
`eligible employer' means, with respect to any calendar year in which
the taxable year begins, an employer which maintains a salary reduction
arrangement meeting the requirements of section 4980G(d) and which did
not maintain a qualified plan or arrangement (within the meaning of
section 4980G(d)(2)) for the preceding 2 calendar years.''
(2) Credit allowed as part of general business credit.--
Section 38(b) (defining current year business credit) is
amended by striking ``plus'' at the end of paragraph (14), by
striking the period at the end of paragraph (15) and inserting
``, plus'', and by adding at the end the following new
paragraph:
``(16) in the case of an eligible employer (as defined in
section 45G(c)), the small employer salary reduction cost
credit determined under section 45G(a).''
(c) Clerical Amendments.--
(1) The table of sections for chapter 43 is amended by
adding at the end the following new item:

``Sec. 4980G. Requirements for employers
to provide employees access to
salary reduction contributions
to individual retirement
plans.''.
(2) The table of sections for subpart D of part IV of
subchapter A of chapter 1 is amended by adding at the end the
following new item:

``Sec. 45G. Small employer salary
reduction costs.''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 404. CREDIT FOR QUALIFIED PENSION PLAN CONTRIBUTIONS OF SMALL
EMPLOYERS.

(a) In General.--Subpart D of part IV of subchapter A of chapter 1
(relating to business related credits), as amended by section 403, is
amended by adding at the end the following new section:

``SEC. 45H. SMALL EMPLOYER PENSION PLAN CONTRIBUTIONS.

``(a) General Rule.--For purposes of section 38, in the case of an
eligible employer, the small employer pension plan contribution credit
determined under this section for any taxable year is an amount equal
to 50 percent of the amount which would (but for subsection (f)(1)) be
allowed as a deduction under section 404 for such taxable year for
qualified employer contributions made to any qualified retirement plan
on behalf of any employee who is not a highly compensated employee.
``(b) Credit Limited to 3 Years.--The credit allowable by this
section shall be allowed only with respect to the period of 3 taxable
years beginning with the first taxable year for which a credit is
allowable with respect to a plan under this section.
``(c) Qualified Employer Contribution.--For purposes of this
section--
``(1) Defined contribution plans.--In the case of a defined
contribution plan, the term `qualified employer contribution'
means the amount of nonelective and matching contributions to
the plan made by the employer on behalf of any employee who is
not a highly compensated employee to the extent such amount
does not exceed 3 percent of such employee's compensation from
the employer for the year.
``(2) Defined benefit plans.--In the case of a defined
benefit plan, the term `qualified employer contribution' means
the amount of employer contributions to the plan made on behalf
of any employee who is not a highly compensated employee to the
extent that the accrued benefit of such employee derived from
employer contributions for the year does not exceed the
equivalent (as determined under regulations prescribed by the
Secretary and without regard to contributions and benefits
under the Social Security Act) of 3 percent of such employee's
compensation from the employer for the year.
``(d) Qualified Retirement Plan.--
``(1) In general.--The term `qualified retirement plan'
means any plan described in section 401(a) which includes a
trust exempt from tax under section 501(a) if the plan meets--
``(A) the contribution requirements of paragraph
(2),
``(B) the vesting requirements of paragraph (3),
and
``(C) the distribution requirements of paragraph
(4).
``(2) Contribution requirements.--
``(A) In general.--The requirements of this
paragraph are met if, under the plan--
``(i) the employer is required to make
nonelective contributions of at least 1 percent
of compensation (or the equivalent thereof in
the case of a defined benefit plan) for each
employee who is not a highly compensated
employee who is eligible to participate in the
plan, and
``(ii) allocations of nonelective employer
contributions, in the case of a defined
contribution plan, are either in equal dollar
amounts for all employees covered by the plan
or bear a uniform relationship to the total
compensation, or the basic or regular rate of
compensation, of the employees covered by the
plan (and an equivalent requirement is met with
respect to a defined benefit plan).
``(B) Compensation limitation.--The compensation
taken into account under subparagraph (A) for any year
shall not exceed the limitation in effect for such year
under section 401(a)(17).
``(3) Vesting requirements.--The requirements of this
paragraph are met if the plan satisfies the requirements of
either of the following subparagraphs:
``(A) 3-year vesting.--A plan satisfies the
requirements of this subparagraph if an employee who
has completed at least 3 years of service has a
nonforfeitable right to 100 percent of the employee's
accrued benefit derived from employer contributions.
``(B) 5-year graded vesting.--A plan satisfies the
requirements of this subparagraph if an employee has a
nonforfeitable right to a percentage of the employee's
accrued benefit derived from employer contributions
determined under the following table:

The nonforfeitable
``Years of service:                                      percentage is:
1.............................................                  20
2.............................................                  40
3.............................................                  60
4.............................................                  80
5.............................................                 100.
``(4) Distribution requirements.--In the case of a profit-
sharing or stock bonus plan, the requirements of this paragraph
are met if, under the plan, qualified employer contributions
are distributable only as provided in section 401(k)(2)(B).
``(e) Other Definitions.--For purposes of this section--
``(1) Eligible employer.--
``(A) In general.--The term `eligible employer'
means, with respect to any year, an employer which has
no more than 20 employees who received at least $5,000
of compensation from the employer for the preceding
year.
``(B) Requirement for new qualified employer
plans.--Such term shall not include an employer if,
during the 3-taxable year period immediately preceding
the 1st taxable year for which the credit under this
section is otherwise allowable for a qualified employer
plan of the employer, the employer or any member of any
controlled group including the employer (or any
predecessor of either) established or maintained a
qualified employer plan with respect to which
contributions were made, or benefits were accrued, for substantially
the same employees as are in the qualified employer plan.
``(2) Highly compensated employee.--The term `highly
compensated employee' has the meaning given such term by
section 414(q) (determined without regard to section
414(q)(1)(B)(ii)).
``(f) Special Rules.--
``(1) Disallowance of deduction.--No deduction shall be
allowed for that portion of the qualified employer
contributions paid or incurred for the taxable year which is
equal to the credit determined under subsection (a).
``(2) Election not to claim credit.--This section shall not
apply to a taxpayer for any taxable year if such taxpayer
elects to have this section not apply for such taxable year.
``(3) Aggregation rules.--All persons treated as a single
employer under subsection (a) or (b) of section 52, or
subsection (n) or (o) of section 414, shall be treated as one
person. All eligible employer plans shall be treated as 1
eligible employer plan.
``(g) Recapture of Credit on Forfeited Contributions.--If any
accrued benefit which is forfeitable by reason of subsection (d)(3) is
forfeited, the employer's tax imposed by this chapter for the taxable
year in which the forfeiture occurs shall be increased by 35 percent of
the employer contributions from which such benefit is derived to the
extent such contributions were taken into account in determining the
credit under this section.''.
(b) Credit Allowed as Part of General Business Credit.--Section
38(b) (defining current year business credit), as amended by section
403, is amended by striking ``plus'' at the end of paragraph (15), by
striking the period at the end of paragraph (16) and inserting ``,
plus'', and by adding at the end the following new paragraph:
``(17) in the case of an eligible employer (as defined in
section 45H(e)), the small employer pension plan contribution
credit determined under section 45H(a).''.
(c) Conforming Amendments.--
(1) Section 39(d) is amended by adding at the end the
following new paragraph:
``(11) No carryback of small employer pension plan
contribution credit before january 1, 2004.--No portion of the
unused business credit for any taxable year which is
attributable to the small employer pension plan contribution
credit determined under section 45H may be carried back to a
taxable year beginning before January 1, 2004.''.
(2) Subsection (c) of section 196 is amended by striking
``and'' at the end of paragraph (9), by striking the period at
the end of paragraph (10) and inserting ``, and'', and by
adding at the end the following new paragraph:
``(11) the small employer pension plan contribution credit
determined under section 45H(a).''.
(3) The table of sections for subpart D of part IV of
subchapter A of chapter 1, as amended by section 403, is
amended by adding at the end the following new item:

``Sec. 45H. Small employer pension plan
contributions.''.
(d) Effective Date.--The amendments made by this section shall
apply to contributions paid or incurred in taxable years beginning
after December 31, 2003.

SEC. 405. ALTERNATIVE METHOD OF MEETING NONDISCRIMINATION REQUIREMENTS
FOR OPT-OUT PLANS.

(a) In General.--Section 401(k) (relating to cash or deferred
arrangement) is amended by adding at the end the following new
paragraph:
``(13) Nondiscrimination requirements for opt-out
arrangements.--
``(A) In general.--A cash or deferred arrangement
shall be treated as meeting the requirements of
paragraph (3)(A)(ii) if such arrangement constitutes a
negative election trust (a `NET').
``(B) Negative election trust.--For purposes of
this paragraph, the term `negative election trust'
means an arrangement--
``(i) under which each employee eligible to
participate in the arrangement is treated as
having elected to have the employer make
elective contributions in an amount equal to
the uniform percentage (not less than 3
percent) provided under the arrangement unless
the employee specifically elects not to have
such contributions made, and
``(ii) which meets the other requirements
of this paragraph.
``(C) Participation.--An arrangement meets the
requirements of this subparagraph for any year if,
during the plan year or the preceding plan year,
elective contributions described in subparagraph (B)(i)
are made on behalf of at least 70 percent of employees
other than highly compensated employees eligible to
participate in the arrangement.
``(D) Matching contributions.--The requirements of
this subparagraph are met if, under the arrangement,
the employer makes matching contributions on behalf of
each employee who is not a highly compensated employee
in an amount equal to 50 percent of the elective
contributions of the employee to the extent such
elective contributions do not exceed 5 percent of
compensation. The rules of clauses (ii) and (iii) of
paragraph (12)(B) shall apply for purposes of this
subparagraph.
``(E) Withdrawal and vesting.--The requirements of
this subparagraph are met if the requirements of
subparagraphs (B) and (C) of paragraph (2) are met with
respect to all employer contributions (including
matching contributions) taken into account in
determining whether the requirements of subparagraph
(B) or (D) are met.
``(F) Notice requirements.--The requirements of
this subparagraph are met if each employee eligible to
participate in the arrangement--
``(i) receives a notice explaining the
employee's right under the arrangement to elect
not to have elective contributions made on the
employee's behalf, and
``(ii) has a reasonable period of time
after receipt of such notice and before the
first elective contribution is made to make
such election.
The requirements of clauses (i) and (ii) of paragraph
(12)(D) shall be met with respect to such notice.''.
(b) Matching Contributions.--Section 401(m) (relating to
nondiscrimination test for matching contributions and employee
contributions) is amended by redesignating paragraph (12) as paragraph
(13) and by inserting after paragraph (11) the following new paragraph:
``(12) Alternative method for opt-out plans.--
``(A) In general.--A defined contribution plan
shall be treated as meeting the requirements of
paragraph (2) with respect to matching contributions if
the plan--
``(i) meets the contribution requirements
of subparagraphs (B)(i) and (D) of subsection
(k)(13),
``(ii) meets the participation requirements
of subsection (k)(13)(C),
``(iii) meets the vesting and notice
requirements of subparagraphs (E) and (F) of
subsection (k)(13), and
``(iv) meets the requirements of clauses
(i) and (ii) of paragraph (11)(B).
``(B) Matching contributions under section 403(b)
plans.--An annuity contract under section 403(b) shall
be treated as meeting the requirements of paragraph (2)
with respect to matching contributions on account of an
elective deferral described in section 402(g)(3)(C) if
such contract meets requirements similar to the
requirements under subparagraph (A).''.
(c) Exclusion From Definition of Top-Heavy Plans.--Paragraph (4) of
section 416(d) (relating to other special rules for top-heavy plans),
as amended by section 104(g), is amended by adding at the end the
following new subparagraph:
``(J) Negative election trust.--The term `top-heavy
plan' shall not include a negative election trust under
section 401(k)(13).''.
(d) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2003.

SEC. 406. PROTECTION OF PARTICIPANTS DURING CONVERSIONS TO CASH BALANCE
OR OTHER HYBRID DEFINED BENEFIT PLANS.

(a) Amendment to Internal Revenue Code.--Section 411(d)(6) of the
Internal Revenue Code of 1986 (relating to accrued benefit may not be
decreased by amendment) is amended by adding at the end the following
new subparagraph:
``(F) Treatment of conversions to cash balance or
other hybrid plans.--
``(i) In general.--For purposes of
subparagraph (A), an applicable plan amendment
shall be treated as reducing the accrued
benefit of a participant unless, under the
terms of the plan as in effect after the
amendment, any participant in the plan
immediately before the amendment takes effect
may elect to continue to accrue benefits in the
same manner as under the terms of the plan in
effect before the amendment.
``(ii) Applicable plan amendment.--For
purposes of this subparagraph--
``(I) In general.--The term
`applicable plan amendment' means an
amendment to a defined benefit plan
which has the effect of converting the
plan to a cash balance plan.
``(II) Special rule for coordinated
benefits.--If the benefits of 2 or more
defined benefit plans established or
maintained by an employer are
coordinated in such a manner as to have
the effect of the adoption of an
amendment described in subclause (I),
the sponsor of the defined benefit plan
or plans providing for such
coordination shall be treated as having
adopted such a plan amendment as of the
date such coordination begins.
``(III) Multiple amendments.--The
Secretary shall issue regulations to
prevent the avoidance of the purposes
of this subparagraph through the use of 2 or more plan amendments
rather than a single amendment.
``(iii) Cash balance plan.--For purposes of
this subparagraph--
``(I) In general.--The term `cash
balance plan' means a defined benefit
plan under which the accrued benefit is
determined as an amount other than an
annual benefit commencing at normal
retirement age.
``(II) Regulations to include
similar or other hybrid plans.--The
Secretary shall issue regulations which
provide that a defined benefit plan (or
any portion of such a plan) which has
an effect similar to a plan described
in subclause (I) shall be treated as a
cash balance plan. Such regulations may
provide that if a plan sponsor
represents in communications to
participants and beneficiaries that a
plan amendment results in a plan being
described in the preceding sentence,
such plan shall be treated as a cash
balance plan.
``(iv) Coordination with accrual and
nondiscrimination rules.--If, by reason of an
election under clause (i), a participant is
eligible to continue to accrue benefits in the
same manner as under the terms of the plan in
effect before the amendment, the Secretary
shall prescribe regulations under which--
``(I) the plan shall be treated as
meeting the requirements of
subparagraph (A), (B), or (C) of
section 411(b)(1) if such requirements
are met separately with respect to each
benefit accrual formula under the terms
of the plan, and
``(II) the plan shall, subject to
such terms and conditions as may be
provided in such regulations, not be
treated as failing to meet the
requirements of section 401(a)(4)
merely because only participants as of
the effective date of the amendment are
so eligible, except that this subclause
shall only apply if the plan met the
requirements of section 401(a)(4) under
the terms of the plan as in effect
before the amendment.''.
(b) Amendment to ERISA.--Section 204(g) of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1054(g)) is amended by adding at
the end the following new paragraph:
``(6)(A) For purposes of paragraph (1), an applicable plan
amendment shall be treated as reducing the accrued benefit of a
participant unless, under the terms of the plan as in effect after the
amendment, any participant in the plan immediately before the amendment
takes effect may elect to continue to accrue benefits in the same
manner as under the terms of the plan in effect before the amendment.
``(B) For purposes of this paragraph--
``(i) The term `applicable plan amendment' means an
amendment to a defined benefit plan which has the effect of
converting the plan to a cash balance plan.
``(ii) If the benefits of 2 or more defined benefit plans
established or maintained by an employer are coordinated in
such a manner as to have the effect of the adoption of an
amendment described in clause (i), the sponsor of the defined
benefit plan or plans providing for such coordination shall be
treated as having adopted such a plan amendment as of the date
such coordination begins.
``(iii) The Secretary of the Treasury shall issue
regulations to prevent the avoidance of the purposes of this
paragraph through the use of 2 or more plan amendments rather
than a single amendment.
``(C) For purposes of this paragraph--
``(i) The term `cash balance plan' means a defined benefit
plan under which the accrued benefit is determined as an amount
other than an annual benefit commencing at normal retirement
age.
``(ii) The Secretary of the Treasury shall issue
regulations which provide that a defined benefit plan (or any
portion of such a plan) which has an effect similar to a plan
described in clause (i) shall be treated as a cash balance
plan. Such regulations may provide that if a plan sponsor
represents in communications to participants and beneficiaries
that a plan amendment results in a plan being described in the
preceding sentence, such plan shall be treated as a cash
balance plan.
``(D) If, by reason of an election under subparagraph (A), a
participant is eligible to continue to accrue benefits in the same
manner as under the terms of the plan in effect before the amendment,
the Secretary shall prescribe regulations under which the plan shall be
treated as meeting the requirements of subparagraph (A), (B), or (C) of
section 204(b)(1) if such requirements are met separately with respect
to each benefit formula under the terms.''.
(c) Effective Dates.--
(1) In general.--The amendments made by this section shall
apply to plan amendments taking effect on or after the date of
the enactment of this Act.
(2) Special rule for collectively bargained plans.--In the
case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified by the date of the enactment of this
Act, the amendments made by this section shall not apply to
plan amendments taking effect before the earlier of--
(A) the later of--
(i) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof on or after such date of enactment), or
(ii) January 1, 2004, or
(B) January 1, 2005.

TITLE V--WOMEN'S PENSION PROTECTION

SEC. 501. SHORT TITLE.

This title may be cited as the ``Women's Pension Protection Act of
2003''.

Subtitle A--Spousal Consent Required for Distributions From Defined
Contribution Plans

SEC. 511. APPLICATION OF JOINT AND SURVIVOR ANNUITY RULES TO ALL
DEFINED CONTRIBUTION PLANS.

(a) Application to All Defined Contribution Plans.--
(1) Amendments to erisa.--
(A) In general.--Section 205(a) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C.
1055(a)) is amended by striking ``to which this section
applies''.
(B) Conforming amendments.--
(i) Section 205(b) of such Act (29 U.S.C.
1055(b)) is amended to read as follows:
``(b)(1)(A) In the case of--
``(i) a tax credit employee stock ownership plan (as
defined in section 409(a) of the Internal Revenue Code of
1986), or
``(ii) an employee stock ownership plan (as defined in
section 4975(e)(7) of such Code),
subsection (a) shall not apply to that portion of the employee's
accrued benefit to which the requirements of section 409(h) of such
Code apply.
``(B) Subparagraph (A) shall apply with respect to any participant
only if--
``(i) such plan provides that the participant's
nonforfeitable accrued benefit (reduced by any security
interest held by the plan by reason of a loan outstanding to
such participant) is payable in full, on the death of the
participant, to the participant's surviving spouse (or, if
there is no surviving spouse or the surviving spouse consents
in the manner required under subsection (c)(2), to a designated
beneficiary),
``(ii) such participant does not elect the payment of
benefits in the form of a life annuity, and
``(iii) with respect to such participant, such plan is not
a direct or indirect transferee (in a transfer after December
31, 1984) of a plan to which, at the time of the transfer,
subsection (a) applied (or to which this clause applied with
respect to the participant).
Clause (iii) shall apply only with respect to the transferred assets
(and income therefrom) if the plan separately accounts for such assets
and any income therefrom. A plan shall not be treated as failing to
meet the requirements of this subparagraph merely because the plan
provides that benefits will not be payable to the surviving spouse of
the participant unless the participant and such spouse had been married
throughout the 1-year period ending on the earlier of the participant's
annuity starting date or the date of the participant's death.
``(2) This section shall not apply to a plan which the Secretary of
the Treasury or his delegate has determined is a plan described in
section 404(c) of the Internal Revenue Code of 1986 (or a continuation
thereof) in which participation is substantially limited to individuals
who, before January 1, 1976, ceased employment covered by the plan.''.
(ii) Section 205(e)(2) of such Act (20
U.S.C. 1055(e)(2)) is amended--
(I) by striking ``individual
account plan or participant described
in subparagraph (B) or (C) of
subsection (b)(1)'' and inserting
``individual account plan to which this
section applies, or any participant
described in subsection (b)(1)(B)'',
and
(II) by striking ``50 percent of''.
(2) Amendments to internal revenue code.--
(A) In general.--Section 401(a)(11)(A) of the
Internal Revenue Code of 1986 (relating to requirement
of joint and survivor annuity and preretirement
survivor annuity) is amended by striking the matter
preceding clause (i) and inserting:
``(A) In general.--Except as provided in section
417 and subparagraph (B), a trust forming part of a
plan shall not constitute a qualified trust under this
section unless such plan provides--''.
(B) Conforming amendments.--
(i) Section 401(a)(11) of such Code is
amended by striking subparagraphs (B), (C), and
(D) and inserting the following new
subparagraphs:
``(B) Exception for certain esop benefits.--
``(i) In general.--In the case of--
``(I) a tax credit employee stock
ownership plan (as defined in section
409(a)), or
``(II) an employee stock ownership
plan (as defined in section
4975(e)(7)),
subparagraph (A) shall not apply to that
portion of the employee's accrued benefit to
which the requirements of section 409(h) apply.
``(ii) Nonforfeitable benefit must be paid
in full, etc.--In the case of any participant,
clause (i) shall apply only if--
``(I) such plan provides that the
participant's nonforfeitable accrued
benefit (reduced by any security
interest held by the plan by reason of
a loan outstanding to such participant)
is payable in full, on the death of the
participant, to the participant's
surviving spouse (or, if there is no
surviving spouse or the surviving
spouse consents in the manner
required under section 417(a)(2), to a designated beneficiary),
``(II) such participant does not
elect the payment of benefits in the
form of a life annuity, and
``(III) with respect to such
participant, such plan is not a direct
or indirect transferee (in a transfer
after December 31, 1984) of a plan to
which, at the time of the transfer,
subparagraph (A) applied (or to which
this subclause applied with respect to
the participant).
Subclause (III) shall apply only with respect
to the transferred assets (and income
therefrom) if the plan separately accounts for
such assets and any income therefrom.
``(C) Special rule where participant and spouse
married less than 1 year.--A plan shall not be treated
as failing to meet the requirements of subparagraph
(B)(ii) merely because the plan provides that benefits
will not be payable to the surviving spouse of the
participant unless the participant and such spouse had
been married throughout the 1-year period ending on the
earlier of the participant's annuity starting date or
the date of the participant's death.''.
(ii) Section 401(a)(11) of such Code is
amended by redesignating subparagraphs (E) and
(F) as subparagraphs (D) and (E), respectively.
(iii) Section 417(c)(2) of such Code is
amended--
(I) by striking ``defined
contribution plan or participant
described in clause (ii) or (iii) of
section 401(a)(11)(B)'' and inserting
``defined contribution plan to which
section 401(a)(11) applies, or any
participant described in section
401(a)(11)(B)(ii),''; and
(II) by striking ``50 percent of''.
(b) Special Rules Relating to Defined Contribution Plans.--
(1) Amendments to erisa.--
(A) Loans.--Section 205(c)(4) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C.
1055(c)(4)) is amended by adding at the end the
following flush sentence:
``This paragraph shall not apply to an individual account plan other
than a plan which is subject to the funding standards of section
302.''.
(B) Hardship withdrawals.--Section 205(c) of such
Act (29 U.S.C. 1055(c)) is amended by adding at the end
the following new paragraph:
``(9) Nothing in this section shall be construed as requiring an
individual account plan to obtain the consent of the spouse of a
participant before making a hardship distribution to the
participant.''.
(C) Payments in lieu of annuity.--Section 205 of
such Act (29 U.S.C. 1055) is amended by redesignating
subsection (l) as subsection (m) and by inserting after
subsection (k) the following new subsection:
``(l)(1) For purposes of this section, an individual account plan
required to provide a qualified joint and survivor annuity or a
qualified preretirement survivor annuity shall be treated as
providing--
``(A) a qualified joint and survivor annuity if the plan
provides that the account balance of the participant to which
the participant had a nonforfeitable right (within the meaning
of section 203) will be distributed in a series of periodic
payments (determined in accordance with tables prescribed by
the Secretary of the Treasury) over the joint life expectancy
of the participant and the participant's spouse, and
``(B) a qualified preretirement survivor annuity if the
plan provides that the account balance of the participant (as
of the date of death) to which the participant had a
nonforfeitable right (as so defined) will be distributed to the
surviving spouse, at the option of the spouse, in either such a
series of periodic payments over the life expectancy of the
surviving spouse or any other form of benefit payment that the
plan provides.
A plan shall not be treated as failing to meet the requirements of
subparagraph (A) because the plan provides that a participant may, with
the consent of the spouse, elect at any time to have the plan pay all
of the remaining portion of the account balance in any other form of
benefit payment that the plan provides.
``(2) In the case of a termination of an individual account plan
that provides for payments described in paragraph (1), such plan shall
be treated as meeting the requirements of paragraph (1) only if, for
each participant or surviving spouse eligible to receive such payments
who is not paid the remaining account balance in a lump sum, the plan
administrator purchases from an insurer an irrevocable commitment to
provide--
``(A) the payments described in paragraph (1), or
``(B) either--
``(i) a qualified joint and survivor annuity (and,
if applicable, a qualified preretirement survivor
annuity) in the case of a participant, or
``(ii) a single life annuity or qualified
preretirement survivor annuity, whichever is
applicable, in the case of a surviving spouse of a
participant.
``(3) The requirements of paragraph (2) are met with respect to a
purchase only if, within a reasonable time after the effective date of
the purchase, the individual entitled to payments from the insurer is
provided a copy of the insurance contract or a certificate showing the
insurer's name and address and clearly stating the insurer's obligation
to provide the required payments.''.
(D) Conforming amendment.--Section 206 of such Act
(29 U.S.C. 1056) is amended by adding at the end the
following:
``(g) Final Distributions From Terminated Individual Account
Plans.--In the case of an individual account plan which provides for
payments described in section 205(l)(1), the plan shall provide that,
upon termination of such plan, benefits of married participants and
surviving spouses shall be paid in accordance with section
205(l)(2).''.
(2) Amendments to internal revenue code.--
(A) Loans.--Section 417(a)(4) of the Internal
Revenue Code of 1986 is amended by adding at the end
the following flush sentence:
``This paragraph shall not apply to a defined contribution plan
other than a plan which is subject to the funding standards of
section 412.''
(B) Hardship withdrawals.--Section 417(a) of such
Code is amended by adding at the end the following new
paragraph:
``(8) Hardship distributions.--Nothing in this section or
section 401(a)(11) shall be construed as requiring a defined
contribution plan to obtain the consent of the spouse of a
participant before making a hardship distribution to the
participant.''.
(C) Payments in lieu of annuity.--Section 417 of
such Code (relating to definitions and special rules
for purposes of minimum survivor annuity requirements)
is amended by adding at the end the following new
subsection:
``(g) Special Rules for Defined Contribution Plans.--For purposes
of this section and section 401(a)(11)--
``(1) Payments in lieu of annuities.--A defined
contribution plan required to provide a qualified joint and
survivor annuity or a qualified preretirement survivor annuity
shall be treated as providing--
``(A) a qualified joint and survivor annuity if the
plan provides that the account balance of the
participant to which the participant had a
nonforfeitable right (within the meaning of section
411(a)) will be distributed in a series of periodic
payments (determined in accordance with tables
prescribed by the Secretary) over the joint life
expectancy of the participant and the participant's
spouse, and
``(B) a qualified preretirement survivor annuity if
the plan provides that the account balance of the
participant (as of the date of death) to which the
participant had a nonforfeitable right (as so defined)
will be distributed to the surviving spouse, at the
option of the spouse, in either such a series of
periodic payments over the life expectancy of the
surviving spouse or any other form of benefit payment
that the plan provides.
A plan shall not be treated as failing to meet the requirements
of subparagraph (A) because the plan provides that a
participant may, with the consent of the spouse, elect at any
time to have the plan pay all of the remaining portion of the
account balance in any other form of benefit payment that the
plan provides.
``(2) Terminating plans.--In the case of a termination of a
defined contribution plan that provides for payments described
in paragraph (1), such plan shall be treated as meeting the
requirements of paragraph (1) only if, for each participant or
surviving spouse eligible to receive such payments who is not
paid the remaining account balance in a lump sum, the plan
administrator purchases from an insurer an irrevocable
commitment to provide--
``(A) the payments described in paragraph (1), or
``(B) either--
``(i) a qualified joint and survivor
annuity (and, if applicable, a qualified
preretirement survivor annuity) in the case of
a participant, or
``(ii) a single life annuity or qualified
preretirement survivor annuity, whichever is
applicable, in the case of a surviving spouse
of a participant.
``(3) Notice.--The requirements of paragraph (2) are met
with respect to a purchase only if, within a reasonable time
after the effective date of the purchase, the individual
entitled to payments from the insurer is provided a copy of the
insurance contract or a certificate showing the insurer's name
and address and clearly stating the insurer's obligation to
provide the required payments.''.
(D) Conforming amendment.--Section 401(a) of such
Code (relating to requirements for a qualified trust)
is amended by inserting after paragraph (34) the
following new paragraph:
``(35) Final distributions from terminated defined
contribution plans.--In the case of a defined contribution plan
which provides for payments described in section 417(g)(1), a
trust forming part of such plan shall not be treated as failing
to constitute a qualified trust under this section merely
because the pension plan of which such trust is a part pays,
upon its termination, benefits in accordance with section
417(g)(2).''.
(c) Transfers Between Plans.--
(1) Amendment to erisa.--Section 205(c) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1055(c)), as
amended by this title, is amended by adding at the end the
following new paragraph:
``(10) Nothing in this section shall be treated as requiring a plan
to obtain the consent of the spouse of the participant before making a
direct trustee-to-trustee transfer of any portion of the balance to the
credit of the participant to another pension plan if the other plan is
a plan to which this section applies.''.
(2) Amendment to internal revenue code.--Section 417(a) of
the Internal Revenue Code of 1986, as amended by this title, is
amended by adding at the end the following new paragraph:
``(9) Transfers.--Nothing in this section or section
401(a)(11) shall be treated as requiring a plan to obtain the
consent of the spouse of the participant before making a direct
trustee-to-trustee transfer of any portion of the balance to
the credit of the participant to another plan if the other
plan is a plan to which this section and section 401(a)(11) apply.''
(d) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to plan years
beginning after December 31, 2003.
(2) Special rule for collectively bargained plans.--In the
case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, the amendments made by this section shall not, in
the case of employees covered by any such agreement, apply to
plan years beginning before the earlier of--
(A) the later of--
(i) January 1, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after the date of enactment of this
Act), or
(B) January 1, 2005.
(3) 1 hour of service requirement.--The amendments made by
this section shall apply only in the case of participants who
have at least 1 hour of service under the plan on or after the
date of the enactment of this Act or who have at least 1 hour
of paid leave on or after such date.

Subtitle B--Division of Pension Benefits Upon Divorce

SEC. 521. TREATMENT OF SUBSEQUENT QUALIFIED DOMESTIC RELATIONS ORDERS.

(a) Amendment to ERISA.--Section 206(d)(3)(B) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1056(d)(3)(B)) is
amended by adding at the end the following flush sentence:
``A domestic relations order shall be treated as a qualified
domestic relations order even if it is issued after, or
revises, another domestic relations order, but, subject to
subparagraph (H), only with respect to amounts payable after
the date the order is issued.''
(b) Amendment to Internal Revenue Code.--Section 414(p)(1)(A) of
the Internal Revenue Code of 1986 is amended by adding at the end the
following flush sentence:
``A domestic relations order shall be treated as a
qualified domestic relations order even if it is issued
after, or revises, another domestic relations order,
but, subject to paragraph (7), only with respect to
amounts payable after the date the order is issued.''
(c) Effective Date.--The amendments made by this section shall
apply to transfers made after December 31, 2003.

SEC. 522. FORMER SPOUSES TREATED AS SURVIVING SPOUSES IN CERTAIN CASES.

(a) Amendment to ERISA.--Section 205 of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1055), as amended by this Act,
is amended by redesignating subsection (m) as subsection (n) and by
inserting after subsection (l) the following new subsection:
``(m)(1) For purposes of this section, a former spouse to whom this
subsection applies shall, upon the death of the participant to whom the
former spouse was married, be entitled to receive a qualified joint and
survivor annuity or qualified preretirement survivor annuity in the
same manner, and to the same extent, as if the former spouse were the
surviving spouse of the participant.
``(2) This subsection applies to a former spouse of a participant
if--
``(A) the former spouse was married to the participant for
at least 1 year,
``(B) an election by the former spouse to waive the
benefits of this section was not in effect at the time of the
dissolution of the marriage,
``(C) there is no domestic relations order which
specifically provides that the survivor benefits under the plan
were considered by the participant and the former spouse and
that the survivor benefits were disposed of, and
``(D) the requirements of paragraph (3) are met with
respect to the participant.
``(3)(A) The requirements of this paragraph are met with respect to
a participant if the participant did not at any time after dissolution
of the marriage to the former spouse--
``(i) remarry, or
``(ii) make a subsequent beneficiary designation.
``(B) A participant shall not be treated as having made a
subsequent beneficiary designation under subparagraph (A)(ii) if, at
the time of the death of the participant--
``(i) the participant had accepted a reduction in an
annuity in order to provide a qualified joint and survivor
annuity under this section, or
``(ii) the participant was eligible for a fully subsidized
annuity described in subsection (c)(5) which provides a
qualified joint and survivor annuity or qualified preretirement
survivor annuity.
``(4) This subsection shall not apply to a former spouse unless the
spouse notifies the plan of the spouse's eligibility under this
subsection and provides such information as is necessary to establish
such eligibility.''
(b) Amendment to Internal Revenue Code.--Section 417 of the
Internal Revenue Code of 1986 (relating to definitions and special
rules for purposes of minimum survivor annuity requirements), as
amended by this title, is amended by adding at the end the following
new subsection:
``(h) Treatment of Certain Former Spouses.--
``(1) In general.--For purposes of this section and section
401(a)(11), a former spouse to whom this subsection applies
shall, upon the death of the participant to whom the former
spouse was married, be entitled to receive a qualified joint
and survivor annuity or qualified preretirement survivor
annuity in the same manner, and to the same extent, as if the
former spouse were the surviving spouse of the participant.
``(2) Application.--This subsection applies to a former
spouse of a participant if--
``(A) the former spouse was married to the
participant for at least 1 year,
``(B) an election by the former spouse to waive the
benefits of this section and section 401(a)(11) was not
in effect at the time of the dissolution of the
marriage,
``(C) there is no domestic relations order which
specifically provides that the survivor benefits under
the plan were considered by the participant and the
former spouse and that the survivor benefits were
disposed of, and
``(D) the requirements of paragraph (3) are met
with respect to the participant.
``(3) Participant requirements.--
``(A) In general.--The requirements of this
paragraph are met with respect to a participant if the
participant did not at any time after dissolution of
the marriage to the former spouse--
``(i) remarry, or
``(ii) make a subsequent beneficiary
designation.
``(B) Special rules.--A participant shall not be
treated as having made a subsequent beneficiary
designation under subparagraph (A)(ii) if, at the time
of the death of the participant--
``(i) the participant had accepted a
reduction in an annuity in order to provide a
qualified joint and survivor annuity under this
section, or
``(ii) the participant was eligible for a
fully subsidized annuity described in
subsection (c)(5) which provides a qualified
joint and survivor annuity or qualified
preretirement survivor annuity.
``(4) Notice.--This subsection shall not apply to a former
spouse unless the spouse notifies the plan of the spouse's
eligibility under this subsection and provides such information
as is necessary to establish such eligibility.''
(c) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to benefits which
first become payable (without regard to when the participant
died) in plan years beginning after December 31, 2003.
(2) Special rule for collectively bargained plans.--In the
case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of the enactment
of this Act, the amendments made by this section shall not, in
the case of employees covered by any such agreement, apply to
benefits which first become payable (without regard to when the
participant died) in plan years beginning before the earlier
of--
(A) the later of--
(i) January 1, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after the date of enactment of this
Act), or
(B) January 1, 2005.

Subtitle C--Protection of Rights of Former Spouses to Pension Benefits
Under Certain Government and Government-Sponsored Retirement Programs

CHAPTER 1--CIVIL SERVICE RETIREMENT

SEC. 531. SURVIVOR ANNUITIES FOR WIDOWS, WIDOWERS, AND FORMER SPOUSES
OF FEDERAL EMPLOYEES WHO DIE BEFORE ATTAINING AGE FOR
DEFERRED ANNUITY UNDER CIVIL SERVICE RETIREMENT SYSTEM.

(a) Benefits for Widow or Widower.--Section 8341(f) of title 5,
United States Code, is amended--
(1) in the matter preceding paragraph (1)--
(A) by inserting ``a former employee separated from
the service with title to deferred annuity from the
Fund dies before having established a valid claim for
annuity and is survived by a spouse, or if'' before ``a
Member''; and
(B) by inserting ``of such former employee or
Member'' after ``the surviving spouse'';
(2) in paragraph (1)--
(A) by inserting ``former employee or'' before
``Member commencing''; and
(B) by inserting ``former employee or'' before
``Member dies''; and
(3) in the undesignated sentence following paragraph (2)--
(A) in the matter preceding subparagraph (A), by
inserting ``former employee or'' before ``Member''; and
(B) in subparagraph (B), by inserting ``former
employee or'' before ``Member''.
(b) Benefits for Former Spouse.--Section 8341(h) of title 5, United
States Code, is amended--
(1) in paragraph (1), by adding after the first sentence
``Subject to paragraphs (2) through (5) of this subsection, a
former spouse of a former employee who dies after having
separated from the service with title to a deferred annuity
under section 8338(a) but before having established a valid
claim for annuity is entitled to a survivor annuity under this
subsection, if and to the extent expressly provided for in an
election under section 8339(j)(3) of this title, or in the
terms of any decree of divorce or annulment or any court order
or court-approved property settlement agreement incident to
such decree.''; and
(2) in paragraph (2)--
(A) in subparagraph (A)(ii), by striking ``or
annuitant,'' and inserting ``annuitant, or former
employee''; and
(B) in subparagraph (B)(iii), by inserting ``former
employee or'' before ``Member''.
(c) Protection of Survivor Benefit Rights.--Section 8339(j)(3) of
title 5, United States Code, is amended by inserting at the end the
following:
``The Office shall provide by regulation for the application of
this subsection to the widow, widower, or surviving former spouse of a
former employee who dies after having separated from the service with
title to a deferred annuity under section 8338(a) but before having
established a valid claim for annuity.''
(d) Effective Date.--The amendments made by this section shall take
effect on the date of the enactment of this Act and shall apply only in
the case of a former employee who dies on or after such date.

SEC. 532. COURT ORDERS RELATING TO FEDERAL RETIREMENT BENEFITS FOR
FORMER SPOUSES OF FEDERAL EMPLOYEES.

(a) Civil Service Retirement System.--
(1) In general.--Section 8345(j) of title 5, United States
Code, is amended--
(A) by redesignating paragraph (3) as paragraph
(4); and
(B) by inserting after paragraph (2) the following:
``(3) Payment to a person under a court decree, court order,
property settlement, or similar process referred to under paragraph (1)
shall include payment to a former spouse of the employee, Member, or
annuitant.''
(2) Lump-sum benefits.--Section 8342 of title 5, United
States Code, is amended--
(A) in subsection (c), by striking ``Lump-sum
benefits'' and inserting ``Subject to subsection (j),
lump-sum benefits''; and
(B) in subsection (j)(1)(A), by striking ``the
lump-sum credit under subsection (a)'' and inserting
``any lump-sum credit or lump-sum benefit under this
section''.
(b) Federal Employees Retirement System.--Section 8467 of title 5,
United States Code, is amended--
(1) by redesignating subsection (c) as subsection (d); and
(2) by inserting after subsection (b) the following:
``(c) Payment to a person under a court decree, court order,
property settlement, or similar process referred to under subsection
(a) shall include payment to a former spouse of the employee, Member,
or annuitant.''
(c) Effective Date.--The amendments made by this section shall take
effect on the date of the enactment of this Act.

SEC. 533. INTEREST ON AMOUNTS PAID FOR CERTAIN CIVIL SERVICE ANNUITY
BENEFITS WRONGFULLY DENIED.

(a) In General.--Chapter 77 of title 5, United States Code, is
amended by adding at the end the following:
``Sec. 7704. Interest on amounts paid for certain annuity benefits
wrongfully denied
``(a) In the case of an individual who, on the basis of a timely
appeal to the Merit Systems Protection Board under section 8347(d) or
8461(e), or petition for judicial review under section 7703 from a
final order or decision of the Board in any such appeal, is found by
the relevant authority--
``(1) to have been affected by an erroneous application or
interpretation of subchapter III of chapter 83, chapter 84, or
any other provision of law (or any rule or regulation relating
thereto), and
``(2) to be entitled to receive an amount equal to all or
any part of an annuity not paid to such individual as a result
of such erroneous application or interpretation,
the amount under paragraph (2) may, in the discretion of such
authority, be made payable with interest.
``(b) Any such interest--
``(1) shall be computed in such manner as the Merit Systems
Protection Board or the court (as the case may be) considers
appropriate; and
``(2) shall be payable out of the Civil Service Retirement
and Disability Fund.
``(c) In this section, the term `annuity' means any annuity
(including a survivor annuity) payable out of the Civil Service
Retirement and Disability Fund.''
(b) Conforming Amendments.--
(1) Section 8348(a)(1)(A) of title 5, United States Code,
is amended by striking ``Fund;'' and inserting ``Fund
(including any interest payable under section 7704);''
(2) The table of sections for chapter 77 of title 5, United
States Code, is amended by adding at the end the following:

``7704. Interest on amounts paid for certain annuity benefits
wrongfully denied.''.

SEC. 534. INCOME AVERAGING OF CORRECTED CIVIL SERVICE ANNUITY BENEFIT
PAYMENTS.

(a) In General.--Part I of subchapter Q of chapter 1 of the
Internal Revenue Code of 1986 (relating to income averaging) is amended
by inserting after section 1301 the following:

``SEC. 1302. AVERAGING OF CORRECTED CIVIL SERVICE ANNUITY BENEFIT
PAYMENTS.

``(a) In General.--Unless the taxpayer elects not to have this
section apply for a taxable year, any corrected civil service annuity
benefit payment includible in gross income for such taxable year
(without regard to this section) shall be so included ratably over the
5-taxable year period beginning with such taxable year.
``(b) Corrected Civil Service Annuity Benefit Payment.--For
purposes of subsection (a), the term `corrected civil service annuity
benefit payment' means with respect to an individual the sum of--
``(1) the lump sum payment awarded by reason of a court
order, or decision of the Merit Systems Protection Board, under
which the individual is entitled to receive an amount equal to
all or any part of an annuity not paid to the individual as a
result of an erroneous application or interpretation of
subchapter III of chapter 83 or chapter 84 of title 5, United
States Code, or any other provision of law (or any rule or
regulation relating thereto), plus
``(2) interest on the amount described in paragraph (1)
awarded under section 7704 of title 5, United States Code.
``(c) Annuity.--For purposes of subsection (b), the term `annuity'
has the meaning given to such term by section 7704(c) of title 5,
United States Code.
``(d) Finality of Election.--An election under subsection (a) with
respect to a corrected civil service annuity benefit payment for a
taxable year may not be changed after the due date of the return for
such taxable year.''
(b) Clerical Amendment.--The table of sections for part I of
subchapter Q of chapter 1 of such Code is amended by inserting after
the item relating to section 1301 the following:

``Sec. 1302. Averaging of corrected civil
service annuity benefit
payments.''
(c) Effective Date.--The amendments made by this section shall
apply to payments received after December 31, 2003.

SEC. 535. ORDER OF PRECEDENCE FOR DISPOSITION OF AMOUNTS REMAINING IN
THE THRIFT SAVINGS ACCOUNT OF A FEDERAL EMPLOYEE (OR
FORMER EMPLOYEE) WHO DIES BEFORE MAKING AN EFFECTIVE
ELECTION CONTROLLING SUCH DISPOSITION.

(a) In General.--Section 8433(e) of title 5, United States Code, is
amended--
(1) by striking ``(e)'' and inserting ``(e)(1)'';
(2) by striking all that follows ``paid'' and inserting
``in accordance with paragraph (2).''; and
(3) by adding at the end the following:
``(2)(A) An amount under paragraph (1) shall be paid in a manner
consistent with the provisions of section 8424(d), except that, in
applying the order of precedence under such provisions--
``(i) the widow or widower of the decedent shall be the
first party entitled to receive (instead of any designated
beneficiary); and
``(ii) if there is no widow or widower, the party next
entitled to receive shall be the beneficiary or beneficiaries
designated by the employee or Member (or former employee or
Member) in accordance with the procedures that would otherwise
normally apply, subject to such additional conditions as the
Executive Director shall by regulation prescribe based on
section 205(c)(2) of the Employee Retirement Income Security
Act of 1974 (29 U.S.C. 1055(c)(2)).
``(B) The order of precedence under subparagraph (A) shall not
apply if the widow or widower consents in writing to the application of
the order of precedence under section 8424(d).''
(b) Effective Date.--The amendments made by this section shall take
effect on the 90th day after the date of the enactment of this Act, and
shall apply in the case of any individual who dies on or after such
90th day.

CHAPTER 2--RAILROAD RETIREMENT

SEC. 541. ENTITLEMENT OF DIVORCED SPOUSES TO RAILROAD RETIREMENT
ANNUITIES INDEPENDENT OF ACTUAL ENTITLEMENT OF EMPLOYEE.

Section 2 of the Railroad Retirement Act of 1974 (45 U.S.C. 231a)
is amended--
(1) in subsection (c)(4)(i), by striking ``(A) is entitled
to an annuity under subsection (a)(1) and (B)''; and
(2) in subsection (e)(5), by striking ``or divorced wife''
the second place it appears.

SEC. 542. EXTENSION OF TIER II RAILROAD RETIREMENT BENEFITS TO
SURVIVING FORMER SPOUSES PURSUANT TO DIVORCE AGREEMENTS.

(a) In General.--Section 5 of the Railroad Retirement Act of 1974
(45 U.S.C. 231d) is amended by adding at the end the following:
``(d) Notwithstanding any other provision of law, the payment of
any portion of an annuity computed under section 3(b) to a surviving
former spouse in accordance with a court decree of divorce, annulment,
or legal separation or the terms of any court-approved property
settlement incident to any such court decree shall not be terminated
upon the death of the individual who performed the service with respect
to which such annuity is so computed unless such termination is
otherwise required by the terms of such court decree.''
(b) Effective Date.--The amendment made by this section shall take
effect on the date of the enactment of this Act.

Subtitle D--Modifications of Joint and Survivor Annuity Requirements

SEC. 551. MODIFICATIONS OF JOINT AND SURVIVOR ANNUITY REQUIREMENTS.

(a) Amendments to ERISA.--
(1) Amount of annuity.--
(A) In general.--Paragraph (1) of section 205(a) of
the Employee Retirement Income Security Act of 1974 (29
U.S.C. 1055(a)) is amended by inserting ``or, at the
election of the participant, shall be provided in the
form of a qualified joint and \3/4\ survivor annuity,''
after ``survivor annuity,''.
(B) Definition.--Subsection (d) of section 205 of
such Act (29 U.S.C. 1055) is amended--
(i) by redesignating paragraphs (1) and (2)
as subparagraphs (A) and (B), respectively,
(ii) by inserting ``(1)'' after ``(d)'',
and
(iii) by adding at the end the following
new paragraph:
``(2)(A) For purposes of this section, the term `qualified joint
and \3/4\ survivor annuity' means an annuity--
``(i) for the participant while both the participant and
the spouse are alive with a survivor annuity for the life of
surviving individual (either the participant or the spouse)
equal to 75 percent of the amount of the annuity which is
payable to the participant while both the participant and the
spouse are alive, and
``(ii) which is the actuarial equivalent of a single
annuity for the life of the participant.
``(B) For purposes of this Act, a qualified joint and \3/4\
survivor annuity shall be treated as a qualified joint and survivor
annuity.''
(2) Illustration requirement.--Clause (i) of section
205(c)(3)(A) of such Act (29 U.S.C. 1055(c)(3)(A)) is amended
to read as follows:
``(i) the terms and conditions of each qualified joint and
survivor annuity and qualified joint and \3/4\ survivor annuity
offered, accompanied by an illustration of the benefits under
each such annuity for the particular participant and spouse and
an acknowledgement form to be signed by the participant and the
spouse that they have read and considered the illustration
before any form of retirement benefit is chosen,''.
(b) Amendments to Internal Revenue Code.--
(1) Amount of annuity.--
(A) In general.--Clause (i) of section
401(a)(11)(A) at the Internal Revenue Code of 1986
(relating to requirement of joint and survivor annuity
and preretirement survivor annuity) is amended by
inserting ``or, at the election of the participant,
shall be provided in the form of a qualified joint and
\3/4\ survivor annuity,'' after ``survivor annuity,''.
(B) Definition.--Section 417 (relating to
definitions and special rules for purposes of minimum
survivor annuity requirements) is amended by adding at
the end the following new subsection:
``(i) Definition of Qualified Joint and \3/4\ Survivor Annuity.--
``(1) In general.--For purposes of this section and section
401(a)(11), the term ``qualified joint and \3/4\ survivor
annuity'' means an annuity--
``(A) for the participant while both the
participant and the spouse are alive with a survivor
annuity for the life of surviving individual (either
the participant or the spouse) equal to 75 percent of
the amount of the annuity which is payable to the
participant while both the participant and the spouse
are alive, and
``(B) which is the actuarial equivalent of a single
annuity for the life of the participant.
``(2) Treatment.--For purposes of this title, a qualified
joint and \3/4\ survivor annuity shall be treated as a
qualified joint and survivor annuity.''
(2) Illustration requirement.--Clause (i) of section
417(a)(3)(A) (relating to explanation of joint and survivor
annuity) is amended to read as follows:
``(i) the terms and conditions of each
qualified joint and survivor annuity and
qualified joint and \3/4\ survivor annuity
offered, accompanied by an illustration of the
benefits under each such annuity for the
particular participant and spouse and an
acknowledgement form to be signed by the
participant and the spouse that they have read
and considered the illustration before any form
of retirement benefit is chosen,''.
(c) Effective Dates.--
(1) In general.--The amendments made by this section shall
apply to plan years beginning on or after January 1, 2004.
(2) Special rule for collectively bargained plans.--In the
case of a plan maintained pursuant to 1 or more collective
bargaining agreements between employee representatives and 1 or
more employers ratified on or before the date of enactment of
this Act, the amendments made by this section shall apply to
the first plan year beginning on or after the earlier of--
(A) the later of--
(i) January 1, 2004, or
(ii) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof after the date of enactment of this
Act), or
(B) January 1, 2005.
(3) Form of accrued benefit not treated as decreased by
reason of amendment.--For purposes of sections 204(g) of the
Employee Retirement Income Security Act of 1974 (29 U.S.C.
1054(g)) and 411(d)(6) of the Internal Revenue Code of 1986, a
plan shall not be treated as having decreased the accrued
benefit of a participant solely by reason of the adoption of a
plan amendment required to carry out the amendments made by
this section.

Subtitle E--Plan Amendments

SEC. 561. PROVISIONS RELATING TO PLAN AMENDMENTS.

(a) In General.--If this section applies to any plan or contract
amendment, such plan or contract shall be treated as being operated in
accordance with the terms of the plan during the period described in
subsection (b)(2)(A).
(b) Amendments to Which Section Applies.--
(1) In general.--This section shall apply to any amendment
to any plan or annuity contract which is made--
(A) pursuant to any amendment made by this Act, or
pursuant to any regulation issued under this Act, and
(B) on or before the last day of the first plan
year beginning on or after January 1, 2005.
In the case of a governmental plan (as defined in section
414(d) of the Internal Revenue Code of 1986), this paragraph
shall be applied by substituting ``2007'' for ``2005''.
(2) Conditions.--This section shall not apply to any
amendment unless--
(A) during the period--
(i) beginning on the date the legislative
or regulatory amendment described in paragraph
(1)(A) takes effect (or in the case of a plan
or contract amendment not required by such
legislative or regulatory amendment, the
effective date specified by the plan); and
(ii) ending on the date described in
paragraph (1)(B) (or, if earlier, the date the
plan or contract amendment is adopted),
the plan or contract is operated as if such plan or
contract amendment were in effect; and
(B) such plan or contract amendment applies
retroactively for such period.

TITLE VI--OTHER PROVISIONS RELATING TO PENSIONS

Subtitle A--General Provisions

SEC. 601. EMPLOYEE PLANS COMPLIANCE RESOLUTION SYSTEM.

(a) In General.--The Secretary of the Treasury shall have full
authority to establish and implement the Employee Plans Compliance
Resolution System (or any successor program) and any other employee
plans correction policies, including the authority to waive income,
excise, or other taxes to ensure that any tax, penalty, or sanction is
not excessive and bears a reasonable relationship to the nature,
extent, and severity of the failure.
(b) Improvements.--The Secretary of the Treasury shall continue to
update and improve the Employee Plans Compliance Resolution System (or
any successor program), giving special attention to--
(1) increasing the awareness and knowledge of small
employers concerning the availability and use of the program;
(2) taking into account special concerns and circumstances
that small employers face with respect to compliance and
correction of compliance failures;
(3) extending the duration of the self-correction period
under the Self-Correction Program for significant compliance
failures;
(4) expanding the availability to correct insignificant
compliance failures under the Self-Correction Program during
audit; and
(5) assuring that any tax, penalty, or sanction that is
imposed by reason of a compliance failure is not excessive and
bears a reasonable relationship to the nature, extent, and
severity of the failure.

SEC. 602. EXTENSION TO ALL GOVERNMENTAL PLANS OF MORATORIUM ON
APPLICATION OF CERTAIN NONDISCRIMINATION RULES APPLICABLE
TO STATE AND LOCAL PLANS.

(a) In General.--The following provisions are each amended by
striking ``maintained by a State or local government or political
subdivision thereof (or agency or instrumentality thereof)'':
(1) Section 401(a)(5)(G) of the Internal Revenue Code of
1986.
(2) Section 401(a)(26)(H) of such Code.
(3) Section 401(k)(3)(G) of such Code.
(4) Section 1505(d)(2) of the Taxpayer Relief Act of 1997.
(b) Conforming Amendments.--
(1) The heading for section 401(a)(5)(G) of such Code is
amended to read as follows: ``Governmental plans.--''.
(2) The heading for section 401(a)(26)(H) of such Code is
amended to read as follows: ``Exception for governmental
plans.--''.
(3) Section 401(k)(3)(G) of such Code is amended by
inserting ``Governmental plans.--'' after ``(G)''.
(c) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2002.

SEC. 603. NOTICE AND CONSENT PERIOD REGARDING DISTRIBUTIONS.

(a) Expansion of Period.--
(1) Amendment of internal revenue code.--
(A) In general.--Section 417(a)(6)(A) of the
Internal Revenue Code of 1986 is amended by striking
``90-day'' and inserting ``180-day''.
(B) Modification of regulations.--The Secretary of
the Treasury shall modify the regulations under
sections 402(f), 411(a)(11), and 417 of the Internal
Revenue Code of 1986 by substituting ``180 days'' for
``90 days'' each place it appears in Treasury
Regulations sections 1.402(f)-1, 1.411(a)-11(c), and
1.417(e)-1(b).
(2) Amendment of erisa.--
(A) In general.--Section 205(c)(7)(A) of the
Employee Retirement Income Security Act of 1974 (29
U.S.C. 1055(c)(7)(A)) is amended by striking ``90-day''
and inserting ``180-day''.
(B) Modification of regulations.--The Secretary of
the Treasury shall modify the regulations under part 2
of subtitle B of title I of the Employee Retirement
Income Security Act of 1974 relating to sections 203(e)
and 205 of such Act by substituting ``180 days'' for
``90 days'' each place it appears.
(3) Effective date.--The amendments and modifications made
or required by this subsection shall apply to years beginning
after December 31, 2002.
(b) Notification of Right To Defer.--
(1) In general.--The Secretary of the Treasury shall modify
the regulations under section 411(a)(11) of the Internal
Revenue Code of 1986 and under section 205 of the Employee
Retirement Income Security Act of 1974 to provide that the
description of a participant's right, if any, to defer receipt
of a distribution shall also describe the consequences of
failing to defer such receipt.
(2) Effective date.--
(A) In general.--The modifications required by
paragraph (1) shall apply to years beginning after
December 31, 2002.
(B) Reasonable notice.--A plan shall not be treated
as failing to meet the requirements of section
411(a)(11) of such Code or section 205 of such Act with
respect to any description of consequences described in
paragraph (1) made within 90 days after the Secretary
of the Treasury issues the modifications required by
paragraph (1) if the plan administrator makes a
reasonable attempt to comply with such requirements.

SEC. 604. TECHNICAL CORRECTIONS TO SAVER ACT.

Section 517 of the Employee Retirement Income Security Act of 1974
(29 U.S.C. 1147) is amended--
(1) in subsection (a), by striking ``2001 and 2005 on or
after September 1 of each year involved'' and inserting ``2002,
2006, and 2010'';
(2) in subsection (b), by adding at the end the following
new sentence: ``To effectuate the purposes of this paragraph,
the Secretary may enter into a cooperative agreement, pursuant
to the Federal Grant and Cooperative Agreement Act of 1977 (31
U.S.C. 6301 et seq.), with any appropriate, qualified
entity.'';
(3) in subsection (e)(2)--
(A) by striking ``Committee on Labor and Human
Resources'' in subparagraph (D) and inserting
``Committee on Health, Education, Labor, and
Pensions'';
(B) by striking subparagraph (F) and inserting the
following:
``(F) the Chairman and Ranking Member of the
Subcommittee on Labor, Health and Human Services, and
Education of the Committee on Appropriations of the
House of Representatives and the Chairman and Ranking
Member of the Subcommittee on Labor, Health and Human
Services, and Education of the Committee on
Appropriations of the Senate;'';
(C) by redesignating subparagraph (G) as
subparagraph (J); and
(D) by inserting after subparagraph (F) the
following new subparagraphs:
``(G) the Chairman and Ranking Member of the
Committee on Finance of the Senate;
``(H) the Chairman and Ranking Member of the
Committee on Ways and Means of the House of
Representatives;
``(I) the Chairman and Ranking Member of the
Subcommittee on Employer-Employee Relations of the
Committee on Education and the Workforce of the House
of Representatives; and'';
(4) in subsection (e)(3)(B), by striking ``January 31,
1998'' and inserting ``3 months before the convening of each
summit;'';
(5) in subsection (f)(1)(C), by inserting ``, no later than
90 days prior to the date of the commencement of the National
Summit,'' after ``comment'';
(6) in subsection (g), by inserting ``, in consultation
with the congressional leaders specified in subsection
(e)(2),'' after ``report'' the first place it appears in the
text;
(7) in subsection (i)--
(A) by striking ``for fiscal years beginning on or
after October 1, 1997,''; and
(B) by adding at the end the following new
paragraph:
``(3) Reception and representation authority.--The
Secretary is hereby granted reception and representation
authority limited specifically to the events at the National
Summit. The Secretary shall use any private contributions
accepted in connection with the National Summit prior to
using funds appropriated for purposes of the National Summit pursuant
to this paragraph.''; and
(8) in subsection (k)--
(A) by striking ``shall enter into a contract on a
sole-source basis'' and inserting ``may enter into a
contract on a sole-source basis''; and
(B) by striking ``in fiscal year 1998''.

SEC. 605. MISSING PARTICIPANTS.

(a) In General.--Section 4050 of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1350) is amended by redesignating
subsection (c) as subsection (e) and by inserting after subsection (b)
the following new subsections:
``(c) Multiemployer Plans.--The corporation shall prescribe rules
similar to the rules in subsection (a) for multiemployer plans covered
by this title that terminate under section 4041A.
``(d) Plans Not Otherwise Subject to Title.--
``(1) Transfer to corporation.--The plan administrator of a
plan described in paragraph (4) may elect to transfer a missing
participant's benefits to the corporation upon termination of
the plan.
``(2) Information to the corporation.--To the extent
provided in regulations, the plan administrator of a plan
described in paragraph (4) shall, upon termination of the plan,
provide the corporation information with respect to benefits of
a missing participant if the plan transfers such benefits--
``(A) to the corporation, or
``(B) to an entity other than the corporation or a
plan described in paragraph (4)(B)(ii).
``(3) Payment by the corporation.--If benefits of a missing
participant were transferred to the corporation under paragraph
(1), the corporation shall, upon location of the participant or
beneficiary, pay to the participant or beneficiary the amount
transferred (or the appropriate survivor benefit) either--
``(A) in a single sum (plus interest), or
``(B) in such other form as is specified in
regulations of the corporation.
``(4) Plans described.--A plan is described in this
paragraph if--
``(A) the plan is a pension plan (within the
meaning of section 3(2))--
``(i) to which the provisions of this
section do not apply (without regard to this
subsection), and
``(ii) which is not a plan described in
paragraphs (2) through (11) of section 4021(b),
and
``(B) at the time the assets are to be distributed
upon termination, the plan--
``(i) has missing participants, and
``(ii) has not provided for the transfer of
assets to pay the benefits of all missing
participants to another pension plan (within
the meaning of section 3(2)).
``(5) Certain provisions not to apply.--Subsections (a)(1)
and (a)(3) shall not apply to a plan described in paragraph
(4).''.
(b) Conforming Amendments.--Section 206(f) of such Act (29 U.S.C.
1056(f)) is amended--
(1) by striking ``title IV'' and inserting ``section
4050''; and
(2) by striking ``the plan shall provide that,''.
(c) Effective Date.--The amendments made by this section shall
apply to distributions made after final regulations implementing
subsections (c) and (d) of section 4050 of the Employee Retirement
Income Security Act of 1974 (as added by subsection (a)), respectively,
are prescribed.

SEC. 606. REDUCED PBGC PREMIUM FOR NEW PLANS OF SMALL EMPLOYERS.

(a) In General.--Subparagraph (A) of section 4006(a)(3) of the
Employee Retirement Income Security Act of 1974 (29 U.S.C.
1306(a)(3)(A)) is amended--
(1) in clause (i), by inserting ``other than a new single-
employer plan (as defined in subparagraph (F)) maintained by a
small employer (as so defined),'' after ``single-employer
plan,'',
(2) in clause (iii), by striking the period at the end and
inserting ``, and'', and
(3) by adding at the end the following new clause:
``(iv) in the case of a new single-employer plan (as
defined in subparagraph (F)) maintained by a small employer (as
so defined) for the plan year, $5 for each individual who is a
participant in such plan during the plan year.''.
(b) Definition of New Single-Employer Plan.--Section 4006(a)(3) of
the Employee Retirement Income Security Act of 1974 (29 U.S.C.
1306(a)(3)) is amended by adding at the end the following new
subparagraph:
``(F)(i) For purposes of this paragraph, a single-employer plan
maintained by a contributing sponsor shall be treated as a new single-
employer plan for each of its first 5 plan years if, during the 36-
month period ending on the date of the adoption of such plan, the
sponsor or any member of such sponsor's controlled group (or any
predecessor of either) did not establish or maintain a plan to which
this title applies with respect to which benefits were accrued for
substantially the same employees as are in the new single-employer
plan.
``(ii)(I) For purposes of this paragraph, the term `small employer'
means an employer which on the first day of any plan year has, in
aggregation with all members of the controlled group of such employer,
100 or fewer employees.
``(II) In the case of a plan maintained by two or more contributing
sponsors that are not part of the same controlled group, the employees
of all contributing sponsors and controlled groups of such sponsors
shall be aggregated for purposes of determining whether any
contributing sponsor is a small employer.''.
(c) Effective Date.--The amendments made by this section shall
apply to plans first effective after December 31, 2002.

SEC. 607. REDUCTION OF ADDITIONAL PBGC PREMIUM FOR NEW AND SMALL PLANS.

(a) New Plans.--Subparagraph (E) of section 4006(a)(3) of the
Employee Retirement Income Security Act of 1974 (29 U.S.C.
1306(a)(3)(E)) is amended by adding at the end the following new
clause:
``(v) In the case of a new defined benefit plan, the amount
determined under clause (ii) for any plan year shall be an amount equal
to the product of the amount determined under clause (ii) and the
applicable percentage. For purposes of this clause, the term
`applicable percentage' means--
``(I) 0 percent, for the first plan year.
``(II) 20 percent, for the second plan year.
``(III) 40 percent, for the third plan year.
``(IV) 60 percent, for the fourth plan year.
``(V) 80 percent, for the fifth plan year.
For purposes of this clause, a defined benefit plan (as defined in
section 3(35)) maintained by a contributing sponsor shall be treated as
a new defined benefit plan for each of its first 5 plan years if,
during the 36-month period ending on the date of the adoption of the
plan, the sponsor and each member of any controlled group including the
sponsor (or any predecessor of either) did not establish or maintain a
plan to which this title applies with respect to which benefits were
accrued for substantially the same employees as are in the new plan.''.
(b) Small Plans.--Paragraph (3) of section 4006(a) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1306(a)), as amended
by section 406(b), is amended--
(1) by striking ``The'' in subparagraph (E)(i) and
inserting ``Except as provided in subparagraph (G), the'', and
(2) by inserting after subparagraph (F) the following new
subparagraph:
``(G)(i) In the case of an employer who has 25 or fewer employees
on the first day of the plan year, the additional premium determined
under subparagraph (E) for each participant shall not exceed $5
multiplied by the number of participants in the plan as of the close of
the preceding plan year.
``(ii) For purposes of clause (i), whether an employer has 25 or
fewer employees on the first day of the plan year is determined by
taking into consideration all of the employees of all members of the
contributing sponsor's controlled group. In the case of a plan
maintained by two or more contributing sponsors, the employees of all
contributing sponsors and their controlled groups shall be aggregated
for purposes of determining whether the 25-or-fewer-employees
limitation has been satisfied.''.
(c) Effective Dates.--
(1) Subsection (a).--The amendments made by subsection (a)
shall apply to plans first effective after December 31, 2002.
(2) Subsection (b).--The amendments made by subsection (b)
shall apply to plan years beginning after December 31, 2002.

SEC. 608. AUTHORIZATION FOR PBGC TO PAY INTEREST ON PREMIUM OVERPAYMENT
REFUNDS.

(a) In General.--Section 4007(b) of the Employment Retirement
Income Security Act of 1974 (29 U.S.C. 1307(b)) is amended--
(1) by striking ``(b)'' and inserting ``(b)(1)'', and
(2) by inserting at the end the following new paragraph:
``(2) The corporation is authorized to pay, subject to regulations
prescribed by the corporation, interest on the amount of any
overpayment of premium refunded to a designated payor. Interest under
this paragraph shall be calculated at the same rate and in the same
manner as interest is calculated for underpayments under paragraph
(1).''.
(b) Effective Date.--The amendments made by subsection (a) shall
apply to interest accruing for periods beginning not earlier than the
date of the enactment of this Act.

SEC. 609. SUBSTANTIAL OWNER BENEFITS IN TERMINATED PLANS.

(a) Modification of Phase-In of Guarantee.--Section 4022(b)(5) of
the Employee Retirement Income Security Act of 1974 (29 U.S.C.
1322(b)(5)) is amended to read as follows:
``(5)(A) For purposes of this paragraph, the term `majority owner'
means an individual who, at any time during the 60-month period ending
on the date the determination is being made--
``(i) owns the entire interest in an unincorporated trade
or business,
``(ii) in the case of a partnership, is a partner who owns,
directly or indirectly, 50 percent or more of either the
capital interest or the profits interest in such partnership,
or
``(iii) in the case of a corporation, owns, directly or
indirectly, 50 percent or more in value of either the voting
stock of that corporation or all the stock of that corporation.
For purposes of clause (iii), the constructive ownership rules of
section 1563(e) of the Internal Revenue Code of 1986 shall apply
(determined without regard to section 1563(e)(3)(C)).
``(B) In the case of a participant who is a majority owner, the
amount of benefits guaranteed under this section shall equal the
product of--
``(i) a fraction (not to exceed 1) the numerator of which
is the number of years from the later of the effective date or
the adoption date of the plan to the termination date, and the
denominator of which is 10, and
``(ii) the amount of benefits that would be guaranteed
under this section if the participant were not a majority
owner.''.
(b) Modification of Allocation of Assets.--
(1) Section 4044(a)(4)(B) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1344(a)(4)(B)) is amended by
striking ``section 4022(b)(5)'' and inserting ``section
4022(b)(5)(B)''.
(2) Section 4044(b) of such Act (29 U.S.C. 1344(b)) is
amended--
(A) by striking ``(5)'' in paragraph (2) and
inserting ``(4), (5),'', and
(B) by redesignating paragraphs (3) through (6) as
paragraphs (4) through (7), respectively, and by
inserting after paragraph (2) the following new
paragraph:
``(3) If assets available for allocation under paragraph
(4) of subsection (a) are insufficient to satisfy in full the
benefits of all individuals who are described in that
paragraph, the assets shall be allocated first to benefits
described in subparagraph (A) of that paragraph. Any remaining
assets shall then be allocated to benefits described in
subparagraph (B) of that paragraph. If assets allocated to such
subparagraph (B) are insufficient to satisfy in full the
benefits described in that subparagraph, the assets shall be
allocated pro rata among individuals on the basis of the
present value (as of the termination date) of their respective
benefits described in that subparagraph.''.
(c) Conforming Amendments.--
(1) Section 4021 of the Employee Retirement Income Security
Act of 1974 (29 U.S.C. 1321) is amended--
(A) in subsection (b)(9), by striking ``as defined
in section 4022(b)(6)'', and
(B) by adding at the end the following new
subsection:
``(d) For purposes of subsection (b)(9), the term `substantial
owner' means an individual who, at any time during the 60-month period
ending on the date the determination is being made--
``(1) owns the entire interest in an unincorporated trade
or business,
``(2) in the case of a partnership, is a partner who owns,
directly or indirectly, more than 10 percent of either the
capital interest or the profits interest in such partnership,
or
``(3) in the case of a corporation, owns, directly or
indirectly, more than 10 percent in value of either the voting
stock of that corporation or all the stock of that corporation.
For purposes of paragraph (3), the constructive ownership rules of
section 1563(e) of the Internal Revenue Code of 1986 shall apply
(determined without regard to section 1563(e)(3)(C)).''.
(2) Section 4043(c)(7) of such Act (29 U.S.C. 1343(c)(7)) is
amended by striking ``section 4022(b)(6)'' and inserting ``section
4021(d)''.
(d) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to plan
terminations--
(A) under section 4041(c) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C.
1341(c)) with respect to which notices of intent to
terminate are provided under section 4041(a)(2) of such
Act (29 U.S.C. 1341(a)(2)) after December 31, 2002, and
(B) under section 4042 of such Act (29 U.S.C. 1342)
with respect to which proceedings are instituted by the
corporation after such date.
(2) Conforming amendments.--The amendments made by
subsection (c) shall take effect on January 1, 2003.

SEC. 610. BENEFIT SUSPENSION NOTICE.

(a) Modification of Regulation.--The Secretary of Labor shall
modify the regulation under subparagraph (B) of section 203(a)(3) of
the Employee Retirement Income Security Act of 1974 (29 U.S.C.
1053(a)(3)(B)) to provide that the notification required by such
regulation in connection with any suspension of benefits described in
such subparagraph--
(1) in the case of an employee who returns to service
described in section 203(a)(3)(B)(i) or (ii) of such Act after
commencement of payment of benefits under the plan, shall be
made during the first calendar month or the first 4- or 5-week
payroll period ending in a calendar month in which the plan
withholds payments, and
(2) in the case of any employee who is not described in
paragraph (1)--
(A) may be included in the summary plan description
for the plan furnished in accordance with section
104(b) of such Act (29 U.S.C. 1024(b)), rather than in
a separate notice, and
(B) need not include a copy of the relevant plan
provisions.
(b) Effective Date.--The modification made under this section shall
apply to plan years beginning after December 31, 2002.

SEC. 611. INTEREST RATE RANGE FOR ADDITIONAL FUNDING REQUIREMENTS.

(a) In General.--Subclause (III) of section 412(l)(7)(C)(i) of the
Internal Revenue Code of 1986 is amended--
(1) by striking ``2002 or 2003'' in the text and inserting
``2001, 2002, or 2003'',
(2) by inserting ``(108 percent for plan years beginning in
2001)'' after ``120 percent'', and
(3) by striking ``2002 and 2003'' in the heading and
inserting ``2001, 2002, and 2003''.
(b) Special Rule.--Subclause (III) of section 302(d)(7)(C)(i) of
the Employee Retirement Income Security Act of 1974 (29 U.S.C.
1082(d)(7)(C)(i)) is amended--
(1) by striking ``2002 or 2003'' in the text and inserting
``2001, 2002, or 2003'',
(2) by inserting ``(108 percent for plan years beginning in
2001)'' after ``120 percent'', and
(3) by striking ``2002 and 2003'' in the heading and
inserting ``2001, 2002, and 2003''.
(c) PBGC.--The last sentence of subclause (IV) of section
4006(a)(3)(E)(iii) of such Act (29 U.S.C. 1306(a)(3)(E)(iii)) is
amended to read as follows: ``Any reference to this clause or this
subparagraph by any other sections or subsections (other than sections
4005, 4010, 4011 and 4043) shall be treated as a reference to this
clause or this subparagraph without regard to this subclause.''.
(d) Effective Dates.--
(1) In general.--The amendments made by this section shall
take effect as if included in the amendments made by section
405 of the Job Creation and Worker Assistance Act of 2002.
(2) Election.--The plan sponsor or plan administrator of a
plan may elect whether to have the amendments made by
subsections (a) and (b) apply. Such election shall be made in
such manner and at such time as the Secretary of the Treasury
or his delegate may prescribe and, once made, may not be
revoked. An election to apply such amendments shall not be
treated as a change in actuarial assumptions for purposes of
reports required to be filed with the Secretary of Labor, the
Secretary of the Treasury, or the Pension Benefit Guaranty
Corporation.

SEC. 612. VOLUNTARY EARLY RETIREMENT INCENTIVE AND EMPLOYMENT RETENTION
PLANS MAINTAINED BY LOCAL EDUCATIONAL AGENCIES AND OTHER
ENTITIES.

(a) Voluntary Early Retirement Incentive Plans.--
(1) Treatment as plan providing severance pay.--Section
457(e)(11) of the Internal Revenue Code of 1986 (relating to
certain plans excluded) is amended by adding at the end the
following new subparagraph:
``(D) Certain voluntary early retirement incentive
plans.--
``(i) In general.--If an applicable
voluntary early retirement incentive plan--
``(I) makes payments or supplements
as an early retirement benefit, a
retirement-type subsidy, or a benefit
described in the last sentence of
section 411(a)(9), and
``(II) such payments or supplements
are made in coordination with a defined
benefit plan which is described in
section 401(a) and includes a trust
exempt from tax under section 501(a)
and which is maintained by an
eligible employer described in paragraph (1)(A) or by an education
association described in clause (ii)(II),
such applicable plan shall be treated for
purposes of subparagraph (A)(i) as a bona fide
severance pay plan with respect to such
payments or supplements to the extent such
payments or supplements could otherwise have
been provided under such defined benefit plan
(determined as if section 411 applied to such
defined benefit plan).
``(ii) Applicable voluntary early
retirement incentive plan.--For purposes of
this subparagraph, the term `applicable
voluntary early retirement incentive plan'
means a voluntary early retirement incentive
plan maintained by--
``(I) a local educational agency
(as defined in section 9101 of the
Elementary and Secondary Education Act
of 1965 (20 U.S.C. 7801)), or
``(II) an education association
which principally represents employees
of 1 or more agencies described in
subclause (I) and which is described in
section 501(c) (5) or (6) and exempt
from tax under section 501(a).''
(2) Age discrimination in employment act.--Section 4(l)(1)
of the Age Discrimination in Employment Act of 1967 (29 U.S.C.
623(l)(1)) is amended--
(A) by inserting ``(A)'' after ``(1)'',
(B) by redesignating subparagraphs (A) and (B) as
clauses (i) and (ii), respectively,
(C) by redesignating clauses (i) and (ii) of
subparagraph (B) (as in effect before the amendments
made by subparagraph (B)) as subclauses (I) and (II),
respectively, and
(D) by adding at the end the following:
``(B) A voluntary early retirement incentive plan
that--
``(i) is maintained by--
``(I) a local educational agency
(as defined in section 9101 of the
Elementary and Secondary Education Act
of 1965 (20 U.S.C. 7801), or
``(II) an education association
which principally represents employees
of 1 or more agencies described in
subclause (I) and which is described in
section 501(c) (5) or (6) of the
Internal Revenue Code of 1986 and
exempt from taxation under section
501(a) of such Code, and
``(ii) makes payments or supplements
described in subclauses (I) and (II) of
subparagraph (A)(ii) in coordination with a
defined benefit plan (as so defined) maintained
by an eligible employer described in section
457(e)(1)(A) of such Code or by an education
association described in clause (i)(II),
shall be treated solely for purposes of subparagraph
(A)(ii) as if it were a part of the defined benefit
plan with respect to such payments or supplements.
Payments or supplements under such a voluntary early
retirement incentive plan shall not constitute
severance pay for purposes of section 4(l)(2) of the
Age Discrimination in Employment Act (29 U.S.C.
623(l)(2)).''
(b) Employment Retention Plans.--
(1) In general.--Section 457(f)(2) of the Internal Revenue
Code of 1986 (relating to exceptions) is amended by striking
``and'' at the end of subparagraph (D), by striking the period
at the end of subparagraph (E) and inserting ``, and'', and by
adding at the end the following:
``(F) that portion of any applicable employment
retention plan described in paragraph (4) with respect
to any participant.''
(2) Definitions and rules relating to employment retention
plans.--Section 457(f) of such Code is amended by adding at the
end the following new paragraph:
``(4) Employment retention plans.--For purposes of
paragraph (2)(F)--
``(A) In general.--The portion of an applicable
employment retention plan described in this paragraph
with respect to any participant is that portion of the
plan which provides benefits payable to the participant
not in excess of twice the applicable dollar limit
determined under subsection (e)(15).
``(B) Other rules.--
``(i) Limitation.--Paragraph (2)(F) shall
only apply to the portion of the plan described
in subparagraph (A) for years preceding the
year in which such portion is paid or otherwise
made available to the participant.
``(ii) Treatment.--A plan shall not be
treated for purposes of this title as providing
for the deferral of compensation for any year
with respect to the portion of the plan
described in subparagraph (A).
``(C) Applicable employment retention plan.--The
term `applicable employment retention plan' means an
employment retention plan maintained by--
``(i) a local educational agency (as
defined in section 9101 of the Elementary and
Secondary Education Act of 1965 (20 U.S.C.
7801), or
``(ii) an education association which
principally represents employees of 1 or more
agencies described in clause (i) and which is
described in section 501(c)(5) or (6) and
exempt from taxation under section 501(a), and
``(D) Employment retention plan.--The term
`employment retention plan' means a plan to pay, upon
termination of employment, compensation to an employee
of a local educational agency or education association
described in subparagraph (C) for purposes of--
``(i) retaining the services of the
employee, or
``(ii) rewarding such employee for the
employee's service with 1 or more such agencies
or associations.''
(c) Coordination With ERISA.--Section 3(2)(B) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1002(2)(B)) is
amended by adding at the end the following: ``An applicable voluntary
early retirement incentive plan (as defined in section
457(e)(11)(D)(ii) of the Internal Revenue Code of 1986) making payments
or supplements described in section 457(e)(11)(D)(i) of such Code, and
an applicable employment retention plan (as defined in section
457(f)(4)(C) of such Code) making payments of benefits described in
section 457(f)(4)(A) of such Code, shall, for purposes of this title,
be treated as a welfare plan (and not a pension plan) with respect to
such payments and supplements.''
(d) Effective Dates.--
(1) In general.--The amendments made by this Act shall take
effect on the date of the enactment of this Act.
(2) Tax amendments.--The amendments made by subsections
(a)(1) and (b) shall apply to taxable years ending after the
date of the enactment of this Act.
(3) ERISA amendments.--The amendment made by subsection (c)
shall apply to plan years ending after the date of the
enactment of this Act.
(4) Construction.--Nothing in the amendments made by this
section shall alter or affect the construction of the Internal
Revenue Code of 1986, the Employee Retirement Income Security
Act of 1974, or the Age Discrimination in Employment Act of
1967 as applied to any plan, arrangement, or conduct to which
such amendments do not apply.

SEC. 613. AUTOMATIC ROLLOVERS OF CERTAIN MANDATORY DISTRIBUTIONS.

(a) In General.--Subsections (c) and (d) of section 657 of the
Economic Growth and Tax Relief Reconciliation Act of 2001, as amended
by section 411(t) of the Job Creation and Worker Assistance Act of
2002, are amended to read as follows:
``(c) Regulations.--
``(1) Automatic rollover safe harbor.--Not later than
December 31, 2002, the Secretary of Labor shall prescribe
interim final regulations or other administrative guidance
providing for safe harbors under which the designation of an
institution and investment of funds in accordance with section
401(a)(31)(B) of the Internal Revenue Code of 1986 is deemed to
satisfy the fiduciary requirements of section 404(a) of the
Employee Retirement Income Security Act of 1974 (29 U.S.C.
1104(a)).
``(2) Use of low-cost individual retirement plans.--The
Secretary of the Treasury and the Secretary of Labor may
provide, and shall give consideration to providing, special
relief with respect to the use of low-cost individual
retirement plans for purposes of transfers under section
401(a)(31)(B) of the Internal Revenue Code of 1986 and for
other uses that promote the preservation of assets for
retirement income purposes.
``(d) Effective Date.--The amendments made by this section shall
apply to distributions made after December 31, 2003.''
(b) Effective Date.--The amendment made by this section shall take
effect as if included in the amendments made by, and provisions of,
section 657 of the Economic Growth and Tax Relief Reconciliation Act of
2001.

SEC. 614. 2-YEAR EXTENSION OF TRANSITION RULE TO PENSION FUNDING
REQUIREMENTS.

(a) In General.--Section 769(c) of the Retirement Protection Act of
1994, as added by section 1508 of the Taxpayer Relief Act of 1997, is
amended--
(1) by inserting ``except as provided in paragraph (3),''
before ``the transition rules'', and
(2) by adding at the end the following:
``(3) Special rules.--In the case of plan years beginning
in 2004 and 2005, the following transition rules shall apply in
lieu of the transition rules described in paragraph (2):
``(A) For purposes of section 412(l)(9)(A) of the
Internal Revenue Code of 1986 and section 302(d)(9)(A)
of the Employee Retirement Income Security Act of 1974,
the funded current liability percentage for any plan
year shall be treated as not less than 90 percent.
``(B) For purposes of section 412(m) of the
Internal Revenue Code of 1986 and section 302(e) of the
Employee Retirement Income Security Act of 1974, the
funded current liability percentage for any plan year
shall be treated as not less than 100 percent.
``(C) For purposes of determining unfunded vested
benefits under section 4006(a)(3)(E)(iii) of the
Employee Retirement Income Security Act of 1974, the
mortality table shall be the mortality table used by
the plan.''
(b) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2002.

SEC. 615. ACCELERATION OF COMPUTATION OF BENEFITS ATTRIBUTABLE TO
RECOVERIES OF EMPLOYER LIABILITY UNDER SECTION 4062.

(a) Modification of Average Recovery Percentage of Outstanding
Amount of Benefit Liabilities Payable by Corporation to Participants
and Beneficiaries.--Section 4022(c)(3)(B)(ii) of the Employee
Retirement Income Security Act of 1974 (29 U.S.C. 1322(c)(3)(B)(ii)) is
amended to read as follows:
``(ii) notices of intent to terminate were
provided (or in the case of a termination by
the corporation, a notice of determination
under section 4042 was issued) during the 5-
Federal fiscal year period ending with the
third fiscal year preceding the fiscal year in
which occurs the date of the notice of intent
to terminate (or the notice of determination
under section 4042) with respect to the plan
termination for which the recovery ratio is
being determined.''
(b) Valuation of Section 4062(c) Liability for Determining Amounts
Payable by Corporation to Participants and Beneficiaries.--Section 4044
of the Employee Retirement Income Security Act of 1974 (29 U.S.C. 1362)
is amended by adding at the end the following new subsection:
``(e) Valuation of Section 4062(c) Liability for Determining
Amounts Payable by Corporation to Participants and Beneficiaries.--
``(1) In general.--In the case of a terminated plan, the
value of the recovery of liability under section 4062(c)
allocable as a plan asset under this section for purposes of
determining the amount of benefits payable by the corporation
shall be determined by multiplying--
``(A) the amount of liability under section 4062(c)
as of the termination date of the plan, by
``(B) the applicable section 4062(c) recovery
ratio.
``(2) Section 4062(c) recovery ratio.--For purposes of this
subsection--
``(A) In general.--Except as provided in
subparagraph (C), the term `section 4062(c) recovery
ratio' means the average, determined with respect to
prior plan terminations described in subparagraph (B),
of the ratio which--
``(i) the value of the recovery under
section 4062(c) determined by the corporation
in connection with any such prior termination,
bears to
``(ii) the amount of liability under
section 4062(c) with respect to such plans as
of the termination date in connection with any
such prior termination.
``(B) Prior terminations.--A plan termination
described in this subparagraph is a termination with
respect to which--
``(i) the value of recoveries under section
4062(c) have been determined by the
corporation, and
``(ii) notices of intent to terminate were
provided (or in the case of a termination by
the corporation, a notice of determination
under section 4042 was issued) during the 5-
Federal fiscal year period ending with the
third fiscal year preceding the fiscal year in
which occurs the date of the notice of intent
to terminate (or the notice of determination
under section 4042) with respect to the plan
termination for which the recovery ratio is
being determined.
``(C) Exception.--In the case of a terminated plan
with respect to which the outstanding amount of benefit
liabilities exceeds $20,000,000, the term `section
4062(c) recovery ratio' means, with respect to the
termination of such plan, the ratio of--
``(i) the value of the recoveries on behalf
of the plan under section 4062(c), to
``(ii) the amount of the liability owed
under section 4062(c) as of the date of plan
termination to the trustee appointed under
section 4042 (b) or (c).
``(3) Subsection not to apply.--This subsection shall not
apply with respect to the determination of--
``(A) whether the amount of outstanding benefit
liabilities exceeds $20,000,000, or
``(B) the amount of any liability under section
4062 to the corporation or the trustee appointed under
section 4042 (b) or (c).
``(4) Determinations.--Determinations under this subsection
shall be made by the corporation. Such determinations shall be
binding unless shown by clear and convincing evidence to be
unreasonable.''
(c) Effective Date.--The amendments made by this section shall
apply for any termination for which notices of intent to terminate are
provided (or in the case of a termination by the corporation, a notice
of determination under section 4042 is issued) on or after the date
which is 30 days after the date of enactment of this section.

SEC. 616. MULTIEMPLOYER PLAN FUNDING NOTICE.

(a) In General.--The Employee Retirement Income Security Act of
1974 is amended by inserting after section 4011 the following new
section:

``SEC. 4012. MULTIEMPLOYER PLAN FUNDING NOTICE.

``(a) Notice.--The plan administrator of a multiemployer plan
shall, every three years, provide a notice to plan participants and
beneficiaries of the plan's funding status and the limits on the
corporation's guaranty.
``(b) Time for Providing Notice.--The notice under this section
shall be provided no later than two months after the deadline
(including extensions) for filing the annual report for the previous
plan year and may be issued together with another document, including
the summary annual report required under section 104(b)(3).
``(c) Form and Manner.--The notice under this section--
``(1) shall be provided in a form and manner prescribed in
regulations of the corporation,
``(2) shall be written in a manner so as to be understood
by the average plan participant, and
``(3) may be provided in written, electronic, or other
appropriate form to the extent such form is reasonably
accessible to plan participants and beneficiaries.''
(b) Conforming Amendment.--The table of sections for title IV of
such Act is amended by adding after the item related to section 4011
the following new item:

``4012. Multiemployer plan funding notice.''
(c) Effective Date.--The amendments made by this section shall
apply to plan years beginning after December 31, 2002.

SEC. 617. NO REDUCTION IN UNEMPLOYMENT COMPENSATION AS A RESULT OF
PENSION ROLLOVERS.

(a) In General.--Paragraph (15)(A) of section 3304(a) of the
Internal Revenue Code of 1986 (relating to requirements for State
unemployment laws) is amended by striking ``and'' at the end of clause
(i) and by adding after clause (ii) the following new clause:
``(iii) such pension, retirement or retired
pay, annuity, or similar payment is not
includible in gross income of the individual
for the taxable year in which paid because it
was part of a rollover distribution, and''.
(b) Effective Date.--The amendments made by this section shall
apply to weeks beginning on or after the date of the enactment of this
Act.

SEC. 618. WITHHOLDING ON DISTRIBUTIONS FROM GOVERNMENTAL SECTION 457
PLANS.

(a) In General.--Section 641(f) of the Economic Growth and Tax
Relief Reconciliation Act of 2001 is amended by adding at the end the
following new paragraph:
``(4) Transition rule for certain governmental plans.--In
the case of distributions from an eligible deferred
compensation plan of an employer described in section
457(e)(1)(A) of the Internal Revenue Code of 1986 which are
made after December 31, 2001, and which are part of a series of
distributions which--
``(A) began before January 1, 2002, and
``(B) are payable for not less than 10 years,
the Internal Revenue Code of 1986 may be applied to such
distributions without regard to the amendments made by
subsection (a)(1)(D).''
(b) Effective Date.--The amendment made by subsection (a) shall
take effect as if included in the provisions of section 641 of the
Economic Growth and Tax Relief Reconciliation Act of 2001.

SEC. 619. TRANSFER OF PENSION PLAN LIABILITIES UPON DISSOLUTION OF
JOINT VENTURE.

(a) In General.--Except as provided in subsection (b), the transfer
of liabilities from a defined benefit plan maintained by an
organization exempt from tax under the Internal Revenue Code of 1986
(the ``transferor plan'') to a defined benefit plan which is a
governmental plan (under section 414(d) of the Internal Revenue Code of
1986 (the ``transferee plan'')) shall be treated as meeting the
requirements of section 414(l) of such Code without regard to whether
any assets are transferred to the transferee plan in connection with
the transfer of liabilities.
(b) Requirements.--Subsection (a) shall only apply to a transfer
if--
(1) before the date of the enactment of this Act--
(A) the sponsor of the transferor plan is a tax
exempt organization which was formed as part of a joint
venture between an organization exempt from tax under
this subtitle and the sponsor of the transferee plan;
(B) such joint venture ceased operations within 3
years of its formation;
(C) after the formation of such joint venture but
prior to its cessation of operations, no contributions
to the transferor plan were required under section 412
of the Internal Revenue Code of 1986 and no
contributions to the transferor plan were made; and
(D) the agreements for dissolution of the joint
venture specifically provide for the transfer of
liabilities described in subsection (a);
(2) the liabilities transferred under subsection (a) are
primarily attributable to individuals who had been participants
in the transferee plan prior to the formation of such joint
venture, who had been participants in the transferor plan after
the formation of such joint venture and before its dissolution,
and who became participants in the transferee plan after the
dissolution of such joint venture;
(3) both upon the cessation of the joint venture's
operations and immediately after the transfer of liabilities
described in subsection (a), both the transferor plan and the
transferee plan have sufficient assets to meet benefit
liabilities (determined under section 412 of the Internal
Revenue Code without regard to whether such section otherwise
applies to the plan);
(4) the liabilities transferred under this paragraph do not
exceed 3 percent of the assets of the transferee plan
(determined in accordance with standards established by the
Government Accounting Standards Board); and
(5) the transfer of liabilities described in subsection (a)
occurs within 180 days of the date of the enactment of this
Act.

Subtitle B--Studies

SEC. 621. STUDY REGARDING INSURANCE SYSTEM FOR INDIVIDUAL ACCOUNT
PLANS.

(a) Study.--As soon as practicable after the date of the enactment
of this Act, the Pension Benefit Guaranty Corporation shall undertake a
study relating to the establishment of an insurance system for
individual account plans. In conducting such study, the Corporation
shall consider--
(1) the feasibility of such a system,
(2) the problem with insuring investments in employer
securities, and
(3) options for developing such a system.
(b) Report.--Not later than 2 years after the date of the enactment
of this Act, the Corporation shall report the results of its study,
together with any recommendations for legislative changes, to the
Committees on Ways and Means and Education and the Workforce of the
House of Representatives and the Committees on Finance and Health,
Education, Labor, and Pensions of the Senate.

SEC. 622. STUDY REGARDING FEES CHARGED BY INDIVIDUAL ACCOUNT PLANS.

(a) Study.--As soon as practicable after the date of the enactment
of this Act, the Secretary of Labor shall undertake a study of the
administrative and transaction fees incurred by participants,
beneficiaries, or plans in connection with the investment of assets in
their accounts under individual account plans. In conducting such
study, the Secretary shall consider--
(1) how the fees compare to fees charged for similar
services provided to investors not in individual account plans,
and
(2) whether participants or beneficiaries are adequately
notified of the fees.
(b) Report.--Not later than 2 years after the date of the enactment
of this Act, the Secretary shall report the results of its study,
together with any recommendations for legislative changes, to the
Committees on Ways and Means and Education and the Workforce of the
House of Representatives and the Committees on Finance and Health,
Education, Labor, and Pensions of the Senate.

SEC. 623. JOINT STUDY ON REVITALIZING DEFINED BENEFIT PLANS.

(a) Study.--As soon as practicable after the date of enactment of
this Act, the Secretary of the Treasury, the Secretary of Labor, and
the Executive Director of the Pension Benefit Guaranty Corporation
shall jointly undertake a study on ways to revitalize interest in
defined benefit plans among employers. In conducting such study, the
Secretaries and the Executive Director shall consider--
(1) ways to encourage the establishment of defined benefit
plans by small- and mid-sized employers,
(2) ways to encourage the continued maintenance of defined
benefit plans by larger employers, and
(3) legislative proposals to accomplish the objectives
described in paragraphs (1) and (2).
(b) Report.--Not later than 2 years after the date of the enactment
of this Act, the Secretaries and the Executive Director shall report
the results of the study, together with any recommendations for
legislative changes, to the Committees on Ways and Means and Education
and the Workforce of the House of Representatives and the Committees on
Finance and Health, Education, Labor, and Pensions of the Senate.

SEC. 624. STUDY ON FLOOR-OFFSET ESOPS.

(a) Study.--As soon as practicable after the date of the enactment
of this Act, the Pension Benefit Guaranty Corporation shall undertake a
study to determine the number of floor-offset employee stock ownership
plans still in existence and the extent to which such plans pose a risk
to plan participants or beneficiaries and to the Corporation. Such
study shall consider legislative proposals to address such risks.
(b) Report.--Not later than 1 year after the date of the enactment
of this Act, the Corporation shall report the results of its study,
together with any recommendations for legislative changes, to the
Committees on Ways and Means and Education and the Workforce of the
House of Representatives and the Committees on Finance and Health,
Education, Labor, and Pensions of the Senate.

Subtitle C--Plan Amendments

SEC. 631. PROVISIONS RELATING TO PLAN AMENDMENTS.

(a) In General.--If this section applies to any plan or contract
amendment--
(1) such plan or contract shall be treated as being
operated in accordance with the terms of the plan during the
period described in subsection (b)(2)(A), and
(2) except as provided by the Secretary of the Treasury,
such plan shall not fail to meet the requirements of section
411(d)(6) of the Internal Revenue Code of 1986 and section
204(g) of the Employee Retirement Income Security Act of 1974
by reason of such amendment.
(b) Amendments to Which Section Applies.--
(1) In general.--This section shall apply to any amendment
to any plan or annuity contract which is made--
(A) pursuant to any amendment made by this Act or
the Economic Growth and Tax Relief Reconciliation Act
of 2001, or pursuant to any regulation issued by the
Secretary of the Treasury or the Secretary of Labor
under such Acts, and
(B) on or before the last day of the first plan
year beginning on or after January 1, 2005.
In the case of a governmental plan (as defined in section
414(d) of the Internal Revenue Code of 1986), this paragraph
shall be applied by substituting ``2007'' for ``2005''.
(2) Conditions.--This section shall not apply to any
amendment unless--
(A) during the period--
(i) beginning on the date the legislative
or regulatory amendment described in paragraph
(1)(A) takes effect (or in the case of a plan
or contract amendment not required by such
legislative or regulatory amendment, the
effective date specified by the plan), and
(ii) ending on the date described in
paragraph (1)(B) (or, if earlier, the date the
plan or contract amendment is adopted),
the plan or contract is operated as if such plan or
contract amendment were in effect; and
(B) such plan or contract amendment applies
retroactively for such period.

TITLE VII--REVENUE OFFSETS

SEC. 700. AMENDMENT OF 1986 CODE.

Except as otherwise expressly provided, whenever in this Act an
amendment or repeal is expressed in terms of an amendment to, or repeal
of, a section or other provision, the reference shall be considered to
be made to a section or other provision of the Internal Revenue Code of
1986.

Subtitle A--Reversing the Expatriation of Profits Offshore

SEC. 701. TAX TREATMENT OF INVERTED CORPORATE ENTITIES.

(a) In General.--Subchapter C of chapter 80 (relating to provisions
affecting more than one subtitle) is amended by adding at the end the
following new section:

``SEC. 7874. RULES RELATING TO INVERTED CORPORATE ENTITIES.

``(a) Inverted Corporations Treated as Domestic Corporations.--
``(1) In general.--If a foreign incorporated entity is
treated as an inverted domestic corporation, then,
notwithstanding section 7701(a)(4), such entity shall be
treated for purposes of this title as a domestic corporation.
``(2) Inverted domestic corporation.--For purposes of this
section, a foreign incorporated entity shall be treated as an
inverted domestic corporation if, pursuant to a plan (or a
series of related transactions)--
``(A) the entity completes after March 20, 2002,
the direct or indirect acquisition of substantially all
of the properties held directly or indirectly by a
domestic corporation or substantially all of the
properties constituting a trade or business of a
domestic partnership,
``(B) after the acquisition at least 80 percent of
the stock (by vote or value) of the entity is held--
``(i) in the case of an acquisition with
respect to a domestic corporation, by former
shareholders of the domestic corporation by
reason of holding stock in the domestic
corporation, or
``(ii) in the case of an acquisition with
respect to a domestic partnership, by former
partners of the domestic partnership by reason
of holding a capital or profits interest in the
domestic partnership, and
``(C) the expanded affiliated group which after the
acquisition includes the entity does not have
substantial business activities in the foreign country
in which or under the law of which the entity is
created or organized when compared to the total
business activities of such expanded affiliated group.
``(b) Preservation of Domestic Tax Base In Certain Inversion
Transactions To Which Subsection (a) Does Not Apply.--
``(1) In general.--If a foreign incorporated entity would
be treated as an inverted domestic corporation with respect to
an acquired entity if either--
``(A) subsection (a)(2)(A) were applied by
substituting `after December 31, 1996, and on or before
March 20, 2002' for `after March 20, 2002' and
subsection (a)(2)(B) were applied by substituting `more
than 50 percent' for `at least 80 percent', or
``(B) subsection (a)(2)(B) were applied by
substituting `more than 50 percent' for `at least 80
percent',
then the rules of subsection (c) shall apply to any inversion
gain of the acquired entity during the applicable period and
the rules of subsection (d) shall apply to any related party
transaction of the acquired entity during the applicable
period. This subsection shall not apply for any taxable year if
subsection (a) applies to such foreign incorporated entity for
such taxable year.
``(2) Acquired entity.--For purposes of this section--
``(A) In general.--The term `acquired entity' means
the domestic corporation or partnership substantially
all of the properties of which are directly or
indirectly acquired in an acquisition described in
subsection (a)(2)(A) to which this subsection applies.
``(B) Aggregation rules.--Any domestic person
bearing a relationship described in section 267(b) or
707(b) to an acquired entity shall be treated as an
acquired entity with respect to the acquisition
described in subparagraph (A).
``(3) Applicable period.--For purposes of this section--
``(A) In general.--The term `applicable period'
means the period--
``(i) beginning on the first date
properties are acquired as part of the
acquisition described in subsection (a)(2)(A)
to which this subsection applies, and
``(ii) ending on the date which is 10 years
after the last date properties are acquired as
part of such acquisition.
``(B) Special rule for inversions occurring before
march 21, 2002.--In the case of any acquired entity to
which paragraph (1)(A) applies, the applicable period
shall be the 10-year period beginning on January 1,
2002.
``(c) Tax on Inversion Gains May Not Be Offset.--If subsection (b)
applies--
``(1) In general.--The taxable income of an acquired entity
(or any expanded affiliated group which includes such entity)
for any taxable year which includes any portion of the
applicable period shall in no event be less than the inversion
gain of the entity for the taxable year.
``(2) Credits not allowed against tax on inversion gain.--
Credits shall be allowed against the tax imposed by this
chapter on an acquired entity for any taxable year described in
paragraph (1) only to the extent such tax exceeds the product
of--
``(A) the amount of the inversion gain for the
taxable year, and
``(B) the highest rate of tax specified in section
11(b)(1).
The credit allowed by section 901 may be taken into account
under the preceding sentence only to the extent of the product
of such highest rate and the amount of taxable income from
sources without the United States that is not inversion gain.
``(3) Special rules for partnerships.--In the case of an
acquired entity which is a partnership--
``(A) the limitations of this subsection shall
apply at the partner rather than the partnership level,
``(B) the inversion gain of any partner for any
taxable year shall be equal to the sum of--
``(i) the partner's distributive share of
inversion gain of the partnership for such
taxable year, plus
``(ii) income or gain required to be
recognized for the taxable year by the partner
under section 367(a), 741, or 1001, or under
any other provision of chapter 1, by reason of
the transfer during the applicable period of
any partnership interest of the partner in such
partnership to the foreign incorporated entity,
and
``(C) the highest rate of tax specified in the rate
schedule applicable to the partner under chapter 1
shall be substituted for the rate of tax under
paragraph (2)(B).
``(4) Inversion gain.--For purposes of this section, the
term `inversion gain' means any income or gain required to be
recognized under section 304, 311(b), 367, 1001, or 1248, or
under any other provision of chapter 1, by reason of the
transfer during the applicable period of stock or other
properties by an acquired entity--
``(A) as part of the acquisition described in
subsection (a)(2)(A) to which subsection (b) applies,
or
``(B) after such acquisition to a foreign related
person.
The Secretary may provide that income or gain from the sale of
inventories or other transactions in the ordinary course of a
trade or business shall not be treated as inversion gain under
subparagraph (B) to the extent the Secretary determines such
treatment would not be inconsistent with the purposes of this
section.
``(5) Coordination with section 172 and minimum tax.--Rules
similar to the rules of paragraphs (3) and (4) of section
860E(a) shall apply for purposes of this section.
``(6) Statute of limitations.--
``(A) In general.--The statutory period for the
assessment of any deficiency attributable to the
inversion gain of any taxpayer for any pre-inversion
year shall not expire before the expiration of 3 years
from the date the Secretary is notified by the taxpayer
(in such manner as the Secretary may prescribe) of the
acquisition described in subsection (a)(2)(A) to which
such gain relates and such deficiency may be assessed
before the expiration of such 3-year period
notwithstanding the provisions of any other law or rule
of law which would otherwise prevent such assessment.
``(B) Pre-inversion year.--For purposes of
subparagraph (A), the term `pre-inversion year' means
any taxable year if--
``(i) any portion of the applicable period
is included in such taxable year, and
``(ii) such year ends before the taxable
year in which the acquisition described in
subsection (a)(2)(A) is completed.
``(d) Special Rules Applicable to Related Party Transactions.--
``(1) Annual application for agreements on return
positions.--
``(A) In general.--Each acquired entity to which
subsection (b) applies shall file with the Secretary an
application for an approval agreement under
subparagraph (D) for each taxable year which includes a
portion of the applicable period. Such application
shall be filed at such time and manner, and shall
contain such information, as the Secretary may
prescribe.
``(B) Secretarial action.--Within 90 days of
receipt of an application under subparagraph (A) (or
such longer period as the Secretary and entity may
agree upon), the Secretary shall--
``(i) enter into an agreement described in
subparagraph (D) for the taxable year covered
by the application,
``(ii) notify the entity that the Secretary
has determined that the application was filed
in good faith and substantially complies with
the requirements for the application under
subparagraph (A), or
``(iii) notify the entity that the
Secretary has determined that the application
was not filed in good faith or does not
substantially comply with such requirements.
If the Secretary fails to act within the time
prescribed under the preceding sentence, the entity
shall be treated for purposes of this paragraph as
having received notice under clause (ii).
``(C) Failures to comply.--If an acquired entity
fails to file an application under subparagraph (A), or
the acquired entity receives a notice under
subparagraph (B)(iii), for any taxable year, then for
such taxable year--
``(i) there shall not be allowed any
deduction, or addition to basis or cost of
goods sold, for amounts paid or incurred, or
losses incurred, by reason of a transaction
between the acquired entity and a foreign
related person,
``(ii) any transfer or license of
intangible property (as defined in section
936(h)(3)(B)) between the acquired entity and a
foreign related person shall be disregarded,
and
``(iii) any cost-sharing arrangement
between the acquired entity and a foreign
related person shall be disregarded.
``(D) Approval agreement.--For purposes of
subparagraph (A), the term `approval agreement' means a
prefiling, advance pricing, or other agreement
specified by the Secretary which contains such
provisions as the Secretary determines necessary to
ensure that the requirements of sections 163(j),
267(a)(3), 482, and 845, and any other provision of
this title applicable to transactions between related
persons and specified by the Secretary, are met.
``(2) Modifications of limitation on interest deduction.--
In the case of an acquired entity to which subsection (b)
applies, section 163(j) shall be applied--
``(A) without regard to paragraph (2)(A)(ii)
thereof, and
``(B) by substituting `25 percent' for `50 percent'
each place it appears in paragraph (2)(B) thereof.
``(e) Other Definitions and Special Rules.--For purposes of this
section--
``(1) Rules for application of subsection (a)(2).--In
applying subsection (a)(2) for purposes of subsections (a) and
(b), the following rules shall apply:
``(A) Certain stock disregarded.--There shall not
be taken into account in determining ownership for
purposes of subsection (a)(2)(B)--
``(i) stock held by members of the expanded
affiliated group which includes the foreign
incorporated entity, or
``(ii) stock of such entity which is sold
in a public offering related to the acquisition
described in subsection (a)(2)(A).
``(B) Plan deemed in certain cases.--If a foreign
incorporated entity acquires directly or indirectly
substantially all of the properties of a domestic
corporation or partnership during the 4-year period
beginning on the date which is 2 years before the
ownership requirements of subsection (a)(2)(B) are met
with respect to such domestic corporation or
partnership, such actions shall be treated as pursuant
to a plan.
``(C) Certain transfers disregarded.--The transfer
of properties or liabilities (including by contribution
or distribution) shall be disregarded if such transfers
are part of a plan a principal purpose of which is to
avoid the purposes of this section.
``(D) Special rule for related partnerships.--For
purposes of applying subsection (a)(2) to the
acquisition of a domestic partnership, except as
provided in regulations, all partnerships which are
under common control (within the meaning of section
482) shall be treated as 1 partnership.
``(E) Treatment of certain rights.--The Secretary
shall prescribe such regulations as may be necessary--
``(i) to treat warrants, options, contracts
to acquire stock, convertible debt instruments,
and other similar interests as stock, and
``(ii) to treat stock as not stock.
``(2) Expanded affiliated group.--The term `expanded
affiliated group' means an affiliated group as defined in
section 1504(a) but without regard to section 1504(b)(3),
except that section 1504(a) shall be applied by substituting
`more than 50 percent' for `at least 80 percent' each place it
appears.
``(3) Foreign incorporated entity.--The term `foreign
incorporated entity' means any entity which is, or but for
subsection (a)(1) would be, treated as a foreign corporation
for purposes of this title.
``(4) Foreign related person.--The term `foreign related
person' means, with respect to any acquired entity, a foreign
person which--
``(A) bears a relationship to such entity described
in section 267(b) or 707(b), or
``(B) is under the same common control (within the
meaning of section 482) as such entity.
``(5) Subsequent acquisitions by unrelated domestic
corporations.--
``(A) In general.--Subject to such conditions,
limitations, and exceptions as the Secretary may
prescribe, if, after an acquisition described in
subsection (a)(2)(A) to which subsection (b) applies, a
domestic corporation stock of which is traded on an
established securities market acquires directly or
indirectly any properties of one or more acquired
entities in a transaction with respect to which the
requirements of subparagraph (B) are met, this section
shall cease to apply to any such acquired entity with
respect to which such requirements are met.
``(B) Requirements.--The requirements of the
subparagraph are met with respect to a transaction
involving any acquisition described in subparagraph (A)
if--
``(i) before such transaction the domestic
corporation did not have a relationship
described in section 267(b) or 707(b), and was
not under common control (within the meaning of
section 482), with the acquired entity, or any
member of an expanded affiliated group
including such entity, and
``(ii) after such transaction, such
acquired entity--
``(I) is a member of the same
expanded affiliated group which
includes the domestic corporation or
has such a relationship or is under
such common control with any member of
such group, and
``(II) is not a member of, and does
not have such a relationship and is not
under such common control with any
member of, the expanded affiliated
group which before such acquisition
included such entity.
``(f) Regulations.--The Secretary shall provide such regulations as
are necessary to carry out this section, including regulations
providing for such adjustments to the application of this section as
are necessary to prevent the avoidance of the purposes of this section,
including the avoidance of such purposes through--
``(1) the use of related persons, pass-through or other
noncorporate entities, or other intermediaries, or
``(2) transactions designed to have persons cease to be (or
not become) members of expanded affiliated groups or related
persons.''
(b) Treatment of Agreements.--
(1) Confidentiality.--
(A) Treatment as return information.--Section
6103(b)(2) (relating to return information) is amended
by striking ``and'' at the end of subparagraph (C), by
inserting ``and'' at the end of subparagraph (D), and
by inserting after subparagraph (D) the following new
subparagraph:
``(E) any approval agreement under section
7874(d)(1) to which any preceding subparagraph does not
apply and any background information related to the
agreement or any application for the agreement,''.
(B) Exception from public inspection as written
determination.--Section 6110(b)(1)(B) is amended by
striking ``or (D)'' and inserting ``, (D), or (E)''.
(2) Reporting.--The Secretary of the Treasury shall include
with any report on advance pricing agreements required to be
submitted after the date of the enactment of this Act under
section 521(b) of the Ticket to Work and Work Incentives
Improvement Act of 1999 (Public Law 106-170) a report regarding
approval agreements under section 7874(d)(1) of the Internal
Revenue Code of 1986. Such report shall include information
similar to the information required with respect to advance
pricing agreements and shall be treated for confidentiality
purposes in the same manner as the reports on advance pricing
agreements are treated under section 521(b)(3) of such Act.
(c) Information Reporting.--The Secretary of the Treasury shall
exercise the Secretary's authority under the Internal Revenue Code of
1986 to require entities involved in transactions to which section 7874
of such Code (as added by subsection (a)) applies to report to the
Secretary, shareholders, partners, and such other persons as the
Secretary may prescribe such information as is necessary to ensure the
proper tax treatment of such transactions.
(d) Conforming Amendment.--The table of sections for subchapter C
of chapter 80 is amended by adding at the end the following new item:

``Sec. 7874. Rules relating to inverted
corporate entities.''
(e) Transition Rule for Certain Regulated Investment Companies and
Unit Investment Trusts.--
(1) In general.--Notwithstanding section 7874 of the
Internal Revenue Code of 1986 (as added by subsection (a)), a
regulated investment company, or other pooled fund or trust
specified by the Secretary of the Treasury, may elect to
recognize gain by reason of section 367(a) of such Code with
respect to a transaction under which a foreign incorporated
entity is treated as an inverted domestic corporation under
section 7874(a) of such Code by reason of an acquisition
completed after March 20, 2002, and before January 1, 2003.
(2) Application of excise tax.--For purposes of section
4982 of such Code, gain described in paragraph (1) which would
otherwise be taken into account for calendar year 2002 shall be
taken into account for calendar year 2003.

SEC. 702. EXCISE TAX ON STOCK COMPENSATION OF INSIDERS IN INVERTED
CORPORATIONS.

(a) In General.--Subtitle D is amended by adding at the end the
following new chapter:

``CHAPTER 48--STOCK COMPENSATION OF INSIDERS IN INVERTED CORPORATIONS

``Sec. 5000A. Stock compensation of
insiders in inverted
corporations entities.

``SEC. 5000A. STOCK COMPENSATION OF INSIDERS IN INVERTED CORPORATIONS.

``(a) Imposition of Tax.--In the case of an individual who is a
disqualified individual with respect to any inverted corporation, there
is hereby imposed on such person a tax equal to 20 percent of the value
(determined under subsection (b)) of the specified stock compensation
held (directly or indirectly) by or for the benefit of such individual
or a member of such individual's family (as defined in section 267) at
any time during the 12-month period beginning on the date which is 6
months before the inversion date.
``(b) Value.--For purposes of subsection (a)--
``(1) In general.--The value of specified stock
compensation shall be--
``(A) in the case of a stock option (or other
similar right) or any stock appreciation right, the
fair value of such option or right, and
``(B) in any other case, the fair market value of
such compensation.
``(2) Date for determining value.--The determination of
value shall be made--
``(A) in the case of specified stock compensation
held on the inversion date, on such date,
``(B) in the case of such compensation which is
canceled during the 6 months before the inversion date,
on the day before such cancellation, and
``(C) in the case of such compensation which is
granted after the inversion date, on the date such
compensation is granted.
``(c) Tax To Apply Only If Shareholder Gain Recognized.--Subsection
(a) shall apply to any disqualified individual with respect to an
inverted corporation only if gain (if any) on any stock in such
corporation is recognized in whole or part by any shareholder by reason
of the acquisition referred to in section 7874(a)(2)(A) (determined by
substituting `July 10, 2002' for `March 20, 2002') with respect to such
corporation.
``(d) Exception Where Gain Recognized on Compensation.--Subsection
(a) shall not apply to--
``(1) any stock option which is exercised on the inversion
date or during the 6-month period before such date and to the
stock acquired in such exercise, and
``(2) any specified stock compensation which is sold,
exchanged, or distributed during such period in a transaction
in which gain or loss is recognized in full.
``(e) Definitions.--For purposes of this section--
``(1) Disqualified individual.--The term `disqualified
individual' means, with respect to a corporation, any
individual who, at any time during the 12-month period
beginning on the date which is 6 months before the inversion
date--
``(A) is subject to the requirements of section
16(a) of the Securities Exchange Act of 1934 with
respect to such corporation or any member of the
expanded affiliated group which includes such
corporation, or
``(B) would be subject to such requirements if such
corporation or member were an issuer of equity
securities referred to in such section.
``(2) Inverted corporation; inversion date.--
``(A) Inverted corporation.--The term `inverted
corporation' means any corporation to which subsection
(a) or (b) of section 7874 applies determined--
``(i) by substituting `July 10, 2002' for
`March 20, 2002' in section 7874(a)(2)(A), and
``(ii) without regard to subsection
(b)(1)(A).
Such term includes any predecessor or successor of such
a corporation.
``(B) Inversion date.--The term `inversion date'
means, with respect to a corporation, the date on which
the corporation first becomes an inverted corporation.
``(3) Specified stock compensation.--
``(A) In general.--The term `specified stock
compensation' means payment (or right to payment)
granted by the inverted corporation (or by any member
of the expanded affiliated group which includes such
corporation) to any person in connection with the
performance of services by a disqualified individual
for such corporation or member if the value of such
payment or right is based on (or determined by reference to) the value
(or change in value) of stock in such corporation (or any such member).
``(B) Exceptions.--Such term shall not include--
``(i) any option to which part II of
subchapter D of chapter 1 applies, or
``(ii) any payment or right to payment from
a plan referred to in section 280G(b)(6).
``(4) Expanded affiliated group.--The term `expanded
affiliated group' means an affiliated group (as defined in
section 1504(a) without regard to section 1504(b)(3)); except
that section 1504(a) shall be applied by substituting `more
than 50 percent' for `at least 80 percent' each place it
appears.
``(f) Special Rules.--For purposes of this section--
``(1) Cancellation of restriction.--The cancellation of a
restriction which by its terms will never lapse shall be
treated as a grant.
``(2) Payment or reimbursement of tax by corporation
treated as specified stock compensation.--Any payment of the
tax imposed by this section directly or indirectly by the
inverted corporation or by any member of the expanded
affiliated group which includes such corporation--
``(A) shall be treated as specified stock
compensation, and
``(B) shall not be allowed as a deduction under any
provision of chapter 1.
``(3) Certain restrictions ignored.--Whether there is
specified stock compensation, and the value thereof, shall be
determined without regard to any restriction other than a
restriction which by its terms will never lapse.
``(4) Property transfers.--Any transfer of property shall
be treated as a payment and any right to a transfer of property
shall be treated as a right to a payment.
``(5) Other administrative provisions.--For purposes of
subtitle F, any tax imposed by this section shall be treated as
a tax imposed by subtitle A.
``(g) Regulations.--The Secretary shall prescribe such regulations
as may be necessary or appropriate to carry out the purposes of this
section.''
(b) Denial of Deduction.--
(1) In general.--Paragraph (6) of section 275(a) is amended
by inserting ``48,'' after ``46,''.
(2) $1,000,000 limit on deductible compensation reduced by
payment of excise tax on specified stock compensation.--
Paragraph (4) of section 162(m) is amended by adding at the end
the following new subparagraph:
``(G) Coordination with excise tax on specified
stock compensation.--The dollar limitation contained in
paragraph (1) with respect to any covered employee
shall be reduced (but not below zero) by the amount of
any payment (with respect to such employee) of the tax
imposed by section 5000A directly or indirectly by the
inverted corporation (as defined in such section) or by
any member of the expanded affiliated group (as defined
in such section) which includes such corporation.''
(c) Conforming Amendments.--
(1) The last sentence of section 3121(v)(2)(A) is amended
by inserting before the period ``or to any specified stock
compensation (as defined in section 5000A) on which tax is
imposed by section 5000A''.
(2) The table of chapters for subtitle D is amended by
adding at the end the following new item:

``Chapter 48. Stock compensation of
insiders in inverted
corporations.''
(d) Effective Date.--The amendments made by this section shall take
effect on July 11, 2002; except that periods before such date shall not
be taken into account in applying the periods in subsections (a) and
(e)(1) of section 5000A of the Internal Revenue Code of 1986, as added
by this section.

SEC. 703. REINSURANCE OF UNITED STATES RISKS IN FOREIGN JURISDICTIONS.

(a) In General.--Section 845(a) (relating to allocation in case of
reinsurance agreement involving tax avoidance or evasion) is amended by
striking ``source and character'' and inserting ``amount, source, or
character''.
(b) Effective Date.--The amendments made by this section shall
apply to any risk reinsured after April 11, 2002.

SEC. 704. STUDY OF DEDUCTIBILITY OF INTEREST ON RELATED-PARTY DEBT.

(a) In General.--The Secretary of the Treasury shall conduct a
study of the effectiveness of the current rules limiting the
deductibility for Federal income tax purposes of interest paid or
incurred on related-party indebtedness, including a study of--
(1) whether or not there is a need to modify the rules to
prevent United States subsidiaries of foreign corporations from
shifting income outside of the United States for Federal income
tax purposes, and
(2) whether or not current United States income tax
treaties allow the inappropriate shifting of income outside of
the United States for Federal income tax purposes.
(b) Report.--The Secretary of the Treasury shall, not later than
March 1, 2003, submit to the Committee on Ways and Means of the House
of Representatives and the Committee on Finance of the Senate the
results of the study under subsection (a), including such
recommendations for legislation or changes in treaty policy as the
Secretary determines appropriate.

Subtitle B--Provisions Relating to Tax Shelters

PART I--ECONOMIC SUBSTANCE DOCTRINE AND TAX SHELTER TRANSPARENCY

SEC. 711. PENALTY FOR FAILING TO DISCLOSE REPORTABLE TRANSACTION.

(a) In General.--Part I of subchapter B of chapter 68 (relating to
assessable penalties) is amended by inserting after section 6707 the
following new section:

``SEC. 6707A. PENALTY FOR FAILURE TO INCLUDE REPORTABLE TRANSACTION
INFORMATION WITH RETURN OR STATEMENT.

``(a) Imposition of Penalty.--Any person who fails to include on
any return or statement any information with respect to a reportable
transaction which is required under section 6011 to be included with
such return or statement shall pay a penalty in the amount determined
under subsection (b).
``(b) Amount of Penalty.--
``(1) In general.--Except as provided in paragraphs (2) and
(3), the amount of the penalty under subsection (a) shall be
$50,000.
``(2) Listed transaction.--The amount of the penalty under
subsection (a) with respect to a listed transaction shall be
$100,000.
``(3) Increase in penalty for large entities and high net
worth individuals.--
``(A) In general.--In the case of a failure under
subsection (a) by--
``(i) a large entity, or
``(ii) a high net worth individual,
the penalty under paragraph (1) or (2) shall be twice
the amount determined without regard to this paragraph.
``(B) Large entity.--For purposes of subparagraph
(A), the term `large entity' means, with respect to any
taxable year, a person (other than a natural person)
with gross receipts in excess of $10,000,000 for the
taxable year in which the reportable transaction occurs
or the preceding taxable year. Rules similar to the
rules of paragraph (2) and subparagraphs (B), (C), and
(D) of paragraph (3) of section 448(c) shall apply for
purposes of this subparagraph.
``(C) High net worth individual.--The term `high
net worth individual' means, with respect to a
reportable transaction, a natural person whose net
worth exceeds $2,000,000 immediately before the
transaction.
``(c) Definitions.--For purposes of this section--
``(1) Reportable transaction.--The term `reportable
transaction' means any transaction with respect to which
information is required to be included with a return or
statement because, as determined under regulations prescribed
under section 6011, such transaction is of a type which the
Secretary determines as having a potential for tax avoidance or
evasion.
``(2) Listed transaction.--The term `listed transaction'
means a reportable transaction which is the same as, or similar
to, a transaction specifically identified by the Secretary as a
tax avoidance transaction for purposes of section 6011.
``(d) Authority To Rescind Penalty.--
``(1) In general.--The Commissioner of Internal Revenue may
rescind all or any portion of any penalty imposed by this
section with respect to any violation if--
``(A) the violation is with respect to a reportable
transaction other than a listed transaction,
``(B) the person on whom the penalty is imposed has
a history of complying with the requirements of this
title,
``(C) it is shown that the violation is due to an
unintentional mistake of fact;
``(D) imposing the penalty would be against equity
and good conscience, and
``(E) rescinding the penalty would promote
compliance with the requirements of this title and
effective tax administration.
``(2) Discretion.--The exercise of authority under
paragraph (1) shall be at the sole discretion of the
Commissioner and may be delegated only to the head of the
Office of Tax Shelter Analysis. The Commissioner, in his sole
discretion, may establish a procedure to determine if a penalty
should be referred to the Commissioner or the head of such
Office for a determination under paragraph (1).
``(3) No appeal.--Notwithstanding any other provision of
law, any determination under this subsection may not be
reviewed in any administrative or judicial proceeding.
``(4) Records.--If a penalty is rescinded under paragraph
(1), the Commissioner shall place in the file in the Office of
the Commissioner the opinion of the Commissioner or the head of
the Office of Tax Shelter Analysis with respect to the
determination, including--
``(A) a statement of the facts and circumstances
relating to the violation,
``(B) the reasons for the rescission, and
``(C) the amount of the penalty rescinded.
``(5) Report.--The Commissioner shall each year report to
the Committee on Ways and Means of the House of Representatives
and the Committee on Finance of the Senate--
``(A) a summary of the total number and aggregate
amount of penalties imposed, and rescinded, under this
section, and
``(B) a description of each penalty rescinded under
this subsection and the reasons therefor.
``(e) Penalty Reported to SEC.--In the case of a person--
``(1) which is required to file periodic reports under
section 13 or 15(d) of the Securities Exchange Act of 1934 or
is required to be consolidated with another person for purposes
of such reports, and
``(2) which--
``(A) is required to pay a penalty under this
section with respect to a listed transaction, or
``(B) is required to pay a penalty under section
6662A with respect to any reportable transaction at a
rate prescribed under section 6662A(c),
the requirement to pay such penalty shall be disclosed in such reports
filed by such person for such periods as the Secretary shall specify.
Failure to make a disclosure in accordance with the preceding sentence
shall be treated as a failure to which the penalty under subsection
(b)(2) applies.
``(f) Coordination With Other Penalties.--The penalty imposed by
this section is in addition to any penalty imposed under this title.''
(b) Conforming Amendment.--The table of sections for part I of
subchapter B of chapter 68 is amended by inserting after the item
relating to section 6707 the following:

``Sec. 6707A. Penalty for failure to
include reportable transaction
information with return or
statement.''
(c) Effective Date.--The amendments made by this section shall
apply to returns and statements the due date for which is after the
date of the enactment of this Act.

SEC. 712. ACCURACY-RELATED PENALTY FOR LISTED TRANSACTIONS AND OTHER
REPORTABLE TRANSACTIONS HAVING A SIGNIFICANT TAX
AVOIDANCE PURPOSE.

(a) In General.--Subchapter A of chapter 68 is amended by inserting
after section 6662 the following new section:

``SEC. 6662A. IMPOSITION OF ACCURACY-RELATED PENALTY ON UNDERSTATEMENTS
WITH RESPECT TO REPORTABLE TRANSACTIONS.

``(a) Imposition of Penalty.--If a taxpayer has a reportable
transaction understatement for any taxable year, there shall be added
to the tax an amount equal to 20 percent of the amount of such
understatement.
``(b) Reportable Transaction Understatement.--For purposes of this
section--
``(1) In general.--The term `reportable transaction
understatement' means the sum of--
``(A) the product of--
``(i) the amount of the increase (if any)
in taxable income which results from a
difference between the proper tax treatment of
an item to which this section applies and the
taxpayer's treatment of such item (as shown on
the taxpayer's return of tax), and
``(ii) the highest rate of tax imposed by
section 1 (section 11 in the case of a taxpayer
which is a corporation), and
``(B) the amount of the decrease (if any) in the
aggregate amount of credits determined under subtitle A
which results from a difference between the taxpayer's
treatment of an item to which this section applies (as
shown on the taxpayer's return of tax) and the proper
tax treatment of such item.
For purposes of subparagraph (A), any reduction of the excess
of deductions allowed for the taxable year over gross income
for such year, and any reduction in the amount of capital
losses which would (without regard to section 1211) be allowed
for such year, shall be treated as an increase in taxable
income.
``(2) Items to which section applies.--This section shall
apply to any item which is attributable to--
``(A) any listed transaction, and
``(B) any reportable transaction (other than a
listed transaction) if a significant purpose of such
transaction is the avoidance or evasion of Federal
income tax.
``(c) Higher Penalties for Nondisclosed Listed and Other Avoidance
Transactions.--If the requirement of section 6664(d)(2)(A) is not met
with respect to any portion of any reportable transaction
understatement, then subsection (a) shall be applied by substituting--
``(1) `30 percent' for `20 percent' if such understatement
is attributable to a listed transaction, and
``(2) `25 percent' for `20 percent' in the case of any
other understatement.
``(d) Definitions of Reportable and Listed Transactions.--For
purposes of this section, the terms `reportable transaction' and
`listed transaction' have the respective meanings given to such terms
by section 6707A(c).
``(e) Special Rules.--
``(1) Coordination with penalties, etc., on other
understatements.--In the case of an understatement (as defined
in section 6662(d)(2))--
``(A) the amount of such understatement (determined
without regard to this paragraph) shall be increased by
the aggregate amount of reportable transaction
understatements for purposes of determining whether
such understatement is a substantial understatement
under section 6662(d)(1), but
``(B) the addition to tax under section 6662(a)
shall apply only to the excess of the amount of the
substantial understatement (if any) after the
application of subparagraph (A) over the aggregate
amount of reportable transaction understatements.
``(2) Coordination with fraud penalty.--
``(A) In general.--References to an underpayment in
section 6663 shall be treated as including references
to a reportable transaction understatement.
``(B) No double penalty.--This section shall not
apply to any portion of an understatement on which a
penalty is imposed under section 6663.
``(3) Special rule for amended returns.--Except as provided
in regulations, in no event shall any tax treatment included
with an amendment or supplement to a return of tax be taken
into account in determining the amount of any reportable
transaction understatement if the amendment or supplement is
filed after the earlier of the date the taxpayer is first
contacted by the Secretary regarding the examination of the
return or such other date as is specified by the Secretary.''
(b) Determination of Other Understatements.--Subparagraph (A) of
section 6662(d)(2) is amended by adding at the end the following flush
sentence:
``The excess under the preceding sentence shall be
determined without regard to items to which section
6662A applies.''
(c) Reasonable Cause Exception.--
(1) In general.--Section 6664 is amended by adding at the
end the following new subsection:
``(d) Reasonable Cause Exception for Reportable Transaction
Understatements.--
``(1) In general.--No penalty shall be imposed under
section 6662A with respect to any portion of a reportable
transaction understatement if it is shown that there was a
reasonable cause for such portion and that the taxpayer acted
in good faith with respect to such portion.
``(2) Special rules.--Paragraph (1) shall not apply to any
reportable transaction understatement unless--
``(A) the relevant facts affecting the tax
treatment of the item are adequately disclosed in
accordance with the regulations prescribed under
section 6011,
``(B) there is or was substantial authority for
such treatment, and
``(C) the taxpayer reasonably believed that such
treatment was more likely than not the proper
treatment.
A taxpayer failing to adequately disclose in accordance with
section 6011 shall be treated as meeting the requirements of
subparagraph (A) if the penalty for such failure was rescinded
under section 6707A(d).
``(3) Rules relating to reasonable belief.--For purposes of
paragraph (2)(C)--
``(A) In general.--A taxpayer shall be treated as
having a reasonable belief with respect to the tax
treatment of an item only if such belief--
``(i) is based on the facts and law that
exist at the time the return of tax which
includes such tax treatment is filed, and
``(ii) relates solely to the taxpayer's
chances of success on the merits of such
treatment and does not take into account the
possibility that a return will not be audited,
such treatment will not be raised on audit, or
such treatment will be resolved through
settlement if it is raised.
``(B) Certain opinions may not be relied upon.--
``(i) In general.--An opinion of a tax
advisor may not be relied upon to establish the
reasonable belief of a taxpayer if--
``(I) the tax advisor is described
in clause (ii), or
``(II) the opinion is described in
clause (iii).
``(ii) Disqualified tax advisors.--A tax
advisor is described in this clause if the tax
advisor--
``(I) is a material advisor (within
the meaning of section 6111(b)(1)) who
participates in the organization,
management, promotion, or sale of the
transaction or is related (within the
meaning of section 267 or 707) to any
person who so participates,
``(II) is compensated directly or
indirectly by a material advisor with
respect to the transaction,
``(III) has a fee arrangement with
respect to the transaction which is
contingent on all or part of the
intended tax benefits from the
transaction being sustained, or
``(IV) as determined under
regulations prescribed by the
Secretary, has a continuing financial
interest with respect to the
transaction.
``(iii) Disqualified opinions.--For
purposes of clause (i), an opinion is
disqualified if the opinion--
``(I) is based on unreasonable
factual or legal assumptions (including
assumptions as to future events),
``(II) unreasonably relies on
representations, statements, findings,
or agreements of the taxpayer or any
other person,
``(III) does not identify and
consider all relevant facts, or
``(IV) fails to meet any other
requirement as the Secretary may
prescribe.''
(2) Conforming amendment.--The heading for subsection (c)
of section 6664 is amended by inserting ``for Underpayments''
after ``Exception''.
(d) Conforming Amendments.--
(1) Subparagraph (C) of section 461(i)(3) is amended by
striking ``section 6662(d)(2)(C)(iii)'' and inserting ``section
1274(b)(3)(C)''.
(2) Paragraph (3) of section 1274(b) is amended--
(A) by striking ``(as defined in section
6662(d)(2)(C)(iii))'' in subparagraph (B)(i), and
(B) by adding at the end the following new
subparagraph:
``(C) Tax shelter.--For purposes of subparagraph
(B), the term `tax shelter' means--
``(i) a partnership or other entity,
``(ii) any investment plan or arrangement,
or
``(iii) any other plan or arrangement,
if a significant purpose of such partnership, entity,
plan, or arrangement is the avoidance or evasion of
Federal income tax.''
(3) Section 6662(d)(2) is amended by striking subparagraphs
(C) and (D).
(4) Section 6664(c)(1) is amended by striking ``part'' and
inserting ``section 6662 or 6663''.
(5) Subsection (b) of section 7525 is amended by striking
``section 6662(d)(2)(C)(iii)'' and inserting ``section
1274(b)(3)(C)''.
(6)(A) The heading for section 6662 is amended to read as
follows:

``SEC. 6662. IMPOSITION OF ACCURACY-RELATED PENALTY ON UNDERPAYMENTS.''

(B) The table of sections for part II of subchapter A of
chapter 68 is amended by striking the item relating to section
6662 and inserting the following new items:

``Sec. 6662. Imposition of accuracy-
related penalty on
underpayments.
``Sec. 6662A. Imposition of accuracy-
related penalty on
understatements with respect to
reportable transactions.''
(e) Effective Date.--The amendments made by this section shall
apply to taxable years ending after the date of the enactment of this
Act.

SEC. 713. MODIFICATIONS OF SUBSTANTIAL UNDERSTATEMENT PENALTY FOR
NONREPORTABLE TRANSACTIONS.

(a) Substantial Understatement of Corporations.--Section
6662(d)(1)(B) (relating to special rule for corporations) is amended to
read as follows:
``(B) Special rule for corporations.--In the case
of a corporation other than an S corporation or a
personal holding company (as defined in section 542),
there is a substantial understatement of income tax for
any taxable year if the amount of the understatement
for the taxable year exceeds the lesser of--
``(i) 10 percent of the tax required to be
shown on the return for the taxable year (or,
if greater, $10,000), or
``(ii) $10,000,000.''
(b) Reduction for Understatement of Taxpayer Due to Position of
Taxpayer or Disclosed Item.--
(1) In general.--Section 6662(d)(2)(B)(i) (relating to
substantial authority) is amended to read as follows:
``(i) the tax treatment of any item by the
taxpayer if the taxpayer had reasonable belief
that the tax treatment was more likely than not
the proper treatment, or''.
(2) Conforming amendment.--Section 6662(d) is amended by
adding at the end the following new paragraph:
``(3) Secretarial list.--For purposes of this subsection,
section 6664(d)(2), and section 6694(a)(1), the Secretary may
prescribe a list of positions for which the Secretary believes
there is not substantial authority or there is no reasonable
belief that the tax treatment is more likely than not the
proper tax treatment. Such list (and any revisions thereof)
shall be published in the Federal Register or the Internal
Revenue Bulletin.''
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after the date of the enactment of
this Act.

SEC. 714. TAX SHELTER EXCEPTION TO CONFIDENTIALITY PRIVILEGES RELATING
TO TAXPAYER COMMUNICATIONS.

(a) In General.--Section 7525(b) (relating to section not to apply
to communications regarding corporate tax shelters) is amended to read
as follows:
``(b) Section Not To Apply to Communications Regarding Tax
Shelters.--The privilege under subsection (a) shall not apply to any
written communication which is--
``(1) between a federally authorized tax practitioner and--
``(A) any person,
``(B) any director, officer, employee, agent, or
representative of the person, or
``(C) any other person holding a capital or profits
interest in the person, and
``(2) in connection with the promotion of the direct or
indirect participation of the person in any tax shelter (as
defined in section 1274(b)(3)(C)).''
(b) Effective Date.--The amendment made by this section shall apply
to communications made on or after the date of the enactment of this
Act.

PART II--PROMOTER AND PREPARER RELATED PROVISIONS

Subpart A--Provisions Relating to Reportable Transactions

SEC. 721. DISCLOSURE OF REPORTABLE TRANSACTIONS.

(a) In General.--Section 6111 (relating to registration of tax
shelters) is amended to read as follows:

``SEC. 6111. DISCLOSURE OF REPORTABLE TRANSACTIONS.

``(a) In General.--Each material advisor with respect to any
reportable transaction shall make a return (in such form as the
Secretary may prescribe) setting forth--
``(1) information identifying and describing the
transaction,
``(2) information describing any potential tax benefits
expected to result from the transaction, and
``(3) such other information as the Secretary may
prescribe.
Such return shall be filed not later than the date specified by the
Secretary.
``(b) Definitions.--For purposes of this section--
``(1) Material advisor.--
``(A) In general.--The term `material advisor'
means any person--
``(i) who provides any material aid,
assistance, or advice with respect to
organizing, promoting, selling, implementing,
or carrying out any reportable transaction, and
``(ii) who directly or indirectly derives
gross income in excess of the threshold amount
for such advice or assistance.
``(B) Threshold amount.--For purposes of
subparagraph (A), the threshold amount is--
``(i) $50,000 in the case of a reportable
transaction substantially all of the tax
benefits from which are provided to natural
persons, and
``(ii) $250,000 in any other case.
``(2) Reportable transaction.--The term `reportable
transaction' has the meaning given to such term by section
6707A(c).
``(c) Regulations.--The Secretary may prescribe regulations which
provide--
``(1) that only 1 person shall be required to meet the
requirements of subsection (a) in cases in which 2 or more
persons would otherwise be required to meet such requirements,
``(2) exemptions from the requirements of this section, and
``(3) such rules as may be necessary or appropriate to
carry out the purposes of this section.''
(b) Conforming Amendments.--
(1) The item relating to section 6111 in the table of
sections for subchapter B of chapter 61 is amended to read as
follows:

``Sec. 6111. Disclosure of reportable
transactions.''
(2)(A) So much of section 6112 as precedes subsection (c)
thereof is amended to read as follows:

``SEC. 6112. MATERIAL ADVISORS OF REPORTABLE TRANSACTIONS MUST KEEP
LISTS OF ADVISEES.

``(a) In General.--Each material advisor (as defined in section
6111) with respect to any reportable transaction (as defined in section
6707A(c)) shall maintain, in such manner as the Secretary may by
regulations prescribe, a list--
``(1) identifying each person with respect to whom such
advisor acted as such a material advisor with respect to such
transaction, and
``(2) containing such other information as the Secretary
may by regulations require.
This section shall apply without regard to whether a material advisor
is required to file a return under section 6111 with regard to such
transaction.''
(B) Section 6112 is amended by redesignating subsection (c)
as subsection (b).
(C) Section 6112(b), as redesignated by subparagraph (B),
is amended--
(i) by inserting ``written'' before ``request'' in
paragraph (1)(A), and
(ii) by striking ``shall prescribe'' in paragraph
(2) and inserting ``may prescribe''.
(D) The item relating to section 6112 in the table of
sections for subchapter B of chapter 61 is amended to read as
follows:

``Sec. 6112. Material advisors of
reportable transactions must
keep lists of advisees.''
(3)(A) The heading for section 6708 is amended to read as
follows:

``SEC. 6708. FAILURE TO MAINTAIN LISTS OF ADVISEES WITH RESPECT TO
REPORTABLE TRANSACTIONS.''

(B) The item relating to section 6708 in the table of
sections for part I of subchapter B of chapter 68 is amended to
read as follows:

``Sec. 6708. Failure to maintain lists of
advisees with respect to
reportable transactions.''
(c) Effective Date.--The amendments made by this section shall
apply to transactions with respect to which material aid, assistance,
or advice referred to in section 6111(b)(1)(A)(i) of the Internal
Revenue Code of 1986 (as added by this section) is provided after the
date of the enactment of this Act.

SEC. 722. MODIFICATIONS TO PENALTY FOR FAILURE TO REGISTER TAX
SHELTERS.

(a) In General.--Section 6707 (relating to failure to furnish
information regarding tax shelters) is amended to read as follows:

``SEC. 6707. FAILURE TO FURNISH INFORMATION REGARDING REPORTABLE
TRANSACTIONS.

``(a) In General.--If a person who is required to file a return
under section 6111(a) with respect to any reportable transaction--
``(1) fails to file such return on or before the date
prescribed therefor, or
``(2) files false or incomplete information with the
Secretary with respect to such transaction,
such person shall pay a penalty with respect to such return in the
amount determined under subsection (b).
``(b) Amount of Penalty.--
``(1) In general.--Except as provided in paragraph (2), the
penalty imposed under subsection (a) with respect to any
failure shall be $50,000.
``(2) Listed transactions.--The penalty imposed under
subsection (a) with respect to any listed transaction shall be
an amount equal to the greater of--
``(A) $200,000, or
``(B) 50 percent of the gross income derived by
such person with respect to aid, assistance, or advice
which is provided with respect to the listed
transaction before the date the return including the
transaction is filed under section 6111.
Subparagraph (B) shall be applied by substituting `75 percent'
for `50 percent' in the case of an intentional failure or act
described in subsection (a).
``(c) Reportable and Listed Transactions.--The terms `reportable
transaction' and `listed transaction' have the respective meanings
given to such terms by section 6707A(c).
``(d) Rescission Authority.--The provisions of section 6707A(d)
(relating to authority of Commissioner to rescind penalty) shall apply
to any penalty imposed under this section.''
(b) Clerical Amendment.--The item relating to section 6707 in the
table of sections for part I of subchapter B of chapter 68 is amended
by striking ``tax shelters'' and inserting ``reportable transactions''.
(c) Effective Date.--The amendments made by this section shall
apply to returns the due date for which is after the date of the
enactment of this Act.

SEC. 723. MODIFICATION OF PENALTY FOR FAILURE TO MAINTAIN LISTS OF
INVESTORS.

(a) In General.--Subsection (a) of section 6708 is amended to read
as follows:
``(a) Imposition of Penalty.--
``(1) In general.--If any person who is required to
maintain a list under section 6112(a) fails to make such list
available to the Secretary in accordance with section 6112(b)(1)(A)
within 20 business days after the date of the Secretary's request, such
person shall pay a penalty of $10,000 for each day of such failure
after such 20th day.
``(2) Reasonable cause exception.--No penalty shall be
imposed by paragraph (1) with respect to the failure on any day
if such failure is due to reasonable cause.''
(b) Effective Date.--The amendment made by this section shall apply
to requests made after the date of the enactment of this Act.

SEC. 724. MODIFICATION OF ACTIONS TO ENJOIN CERTAIN CONDUCT RELATED TO
TAX SHELTERS AND REPORTABLE TRANSACTIONS.

(a) In General.--Section 7408 (relating to action to enjoin
promoters of abusive tax shelters, etc.) is amended by redesignating
subsection (c) as subsection (d) and by striking subsections (a) and
(b) and inserting the following new subsections:
``(a) Authority To Seek Injunction.--A civil action in the name of
the United States to enjoin any person from further engaging in
specified conduct may be commenced at the request of the Secretary. Any
action under this section shall be brought in the district court of the
United States for the district in which such person resides, has his
principal place of business, or has engaged in specified conduct. The
court may exercise its jurisdiction over such action (as provided in
section 7402(a)) separate and apart from any other action brought by
the United States against such person.
``(b) Adjudication and Decree.--In any action under subsection (a),
if the court finds--
``(1) that the person has engaged in any specified conduct,
and
``(2) that injunctive relief is appropriate to prevent
recurrence of such conduct,
the court may enjoin such person from engaging in such conduct or in
any other activity subject to penalty under this title.
``(c) Specified Conduct.--For purposes of this section, the term
`specified conduct' means any action, or failure to take action,
subject to penalty under section 6700, 6701, 6707, or 6708.''
(b) Conforming Amendments.--
(1) The heading for section 7408 is amended to read as
follows:

``SEC. 7408. ACTIONS TO ENJOIN SPECIFIED CONDUCT RELATED TO TAX
SHELTERS AND REPORTABLE TRANSACTIONS.''

(2) The table of sections for subchapter A of chapter 67 is
amended by striking the item relating to section 7408 and
inserting the following new item:

``Sec. 7408. Actions to enjoin specified conduct related to tax
shelters and reportable transactions.''
(c) Effective Date.--The amendment made by this section shall take
effect on the day after the date of the enactment of this Act.

Subpart B--Other Promoter and Preparer Provisions

SEC. 731. UNDERSTATEMENT OF TAXPAYER'S LIABILITY BY INCOME TAX RETURN
PREPARER.

(a) Standards Conformed to Taxpayer Standards.--Section 6694(a)
(relating to understatements due to unrealistic positions) is amended--
(1) by striking ``realistic possibility of being sustained
on its merits'' in paragraph (1) and inserting ``reasonable
belief that the tax treatment in such position was more likely
than not the proper treatment'',
(2) by striking ``or was frivolous'' in paragraph (3) and
inserting ``or there was no reasonable basis for the tax
treatment of such position'', and
(3) by striking ``Unrealistic'' in the heading and
inserting ``Improper''.
(b) Amount of Penalty.--Section 6694 is amended--
(1) by striking ``$250'' in subsection (a) and inserting
``$1,000'', and
(2) by striking ``$1,000'' in subsection (b) and inserting
``$5,000''.
(c) Effective Date.--The amendments made by this section shall
apply to documents prepared after the date of the enactment of this
Act.

SEC. 732. PENALTY ON FAILURE TO REPORT INTERESTS IN FOREIGN FINANCIAL
ACCOUNTS.

(a) In General.--Section 5321(a)(5) of title 31, United States
Code, is amended to read as follows:
``(5) Foreign financial agency transaction violation.--
``(A) Penalty authorized.--The Secretary of the
Treasury may impose a civil money penalty on any person
who violates, or causes any violation of, any provision
of section 5314.
``(B) Amount of penalty.--
``(i) In general.--Except as provided in
subparagraph (C), the amount of any civil
penalty imposed under subparagraph (A) shall
not exceed $5,000.
``(ii) Reasonable cause exception.--No
penalty shall be imposed under subparagraph (A)
with respect to any violation if--
``(I) such violation was due to
reasonable cause, and
``(II) the amount of the
transaction or the balance in the
account at the time of the transaction
was properly reported.
``(C) Willful violations.--In the case of any
person willfully violating, or willfully causing any
violation of, any provision of section 5314--
``(i) the maximum penalty under
subparagraph (B)(i) shall be increased to the
greater of--
``(I) $25,000, or
``(II) the amount (not exceeding
$100,000) determined under subparagraph
(D), and
``(ii) subparagraph (B)(ii) shall not
apply.
``(D) Amount.--The amount determined under this
subparagraph is--
``(i) in the case of a violation involving
a transaction, the amount of the transaction,
or
``(ii) in the case of a violation involving
a failure to report the existence of an account
or any identifying information required to be
provided with respect to an account, the
balance in the account at the time of the
violation.''
(b) Effective Date.--The amendment made by this section shall apply
to violations occurring after the date of the enactment of this Act.

SEC. 733. FRIVOLOUS TAX SUBMISSIONS.

(a) Civil Penalties.--Section 6702 is amended to read as follows:

``SEC. 6702. FRIVOLOUS TAX SUBMISSIONS.

``(a) Civil Penalty for Frivolous Tax Returns.--A person shall pay
a penalty of $5,000 if--
``(1) such person files what purports to be a return of a
tax imposed by this title but which--
``(A) does not contain information on which the
substantial correctness of the self-assessment may be
judged, or
``(B) contains information that on its face
indicates that the self-assessment is substantially
incorrect; and
``(2) the conduct referred to in paragraph (1)--
``(A) is based on a position which the Secretary
has identified as frivolous under subsection (c), or
``(B) reflects a desire to delay or impede the
administration of Federal tax laws.
``(b) Civil Penalty for Specified Frivolous Submissions.--
``(1) Imposition of penalty.--Except as provided in
paragraph (3), any person who submits a specified frivolous
submission shall pay a penalty of $5,000.
``(2) Specified frivolous submission.--For purposes of this
section--
``(A) Specified frivolous submission.--The term
`specified frivolous submission' means a specified
submission if any portion of such submission--
``(i) is based on a position which the
Secretary has identified as frivolous under
subsection (c), or
``(ii) reflects a desire to delay or impede
the administration of Federal tax laws.
``(B) Specified submission.--The term `specified
submission' means--
``(i) a request for a hearing under--
``(I) section 6320 (relating to
notice and opportunity for hearing upon
filing of notice of lien), or
``(II) section 6330 (relating to
notice and opportunity for hearing
before levy), and
``(ii) an application under--
``(I) section 6159 (relating to
agreements for payment of tax liability
in installments),
``(II) section 7122 (relating to
compromises), or
``(III) section 7811 (relating to
taxpayer assistance orders).
``(3) Opportunity to withdraw submission.--If the Secretary
provides a person with notice that a submission is a specified
frivolous submission and such person withdraws such submission
within 30 days after such notice, the penalty imposed under
paragraph (1) shall not apply with respect to such submission.
``(c) Listing of Frivolous Positions.--The Secretary shall
prescribe (and periodically revise) a list of positions which the
Secretary has identified as being frivolous for purposes of this
subsection. The Secretary shall not include in such list any position
that the Secretary determines meets the requirement of section
6662(d)(2)(B)(ii)(II).
``(d) Reduction of Penalty.--The Secretary may reduce the amount of
any penalty imposed under this section if the Secretary determines that
such reduction would promote compliance with and administration of the
Federal tax laws.
``(e) Penalties in Addition to Other Penalties.--The penalties
imposed by this section shall be in addition to any other penalty
provided by law.''
(b) Treatment of Frivolous Requests for Hearings Before Levy.--
(1) Frivolous requests disregarded.--Section 6330 (relating
to notice and opportunity for hearing before levy) is amended
by adding at the end the following new subsection:
``(g) Frivolous Requests for Hearing, Etc.--Notwithstanding any
other provision of this section, if the Secretary determines that any
portion of a request for a hearing under this section or section 6320
meets the requirement of clause (i) or (ii) of section 6702(b)(2)(A),
then the Secretary may treat such portion as if it were never submitted
and such portion shall not be subject to any further administrative or
judicial review.''
(2) Preclusion from raising frivolous issues at hearing.--
Section 6330(c)(4) is amended--
(A) by striking ``(A)'' and inserting ``(A)(i)'';
(B) by striking ``(B)'' and inserting ``(ii)'';
(C) by striking the period at the end of the first
sentence and inserting ``; or''; and
(D) by inserting after subparagraph (A)(ii) (as so
redesignated) the following:
``(B) the issue meets the requirement of clause (i)
or (ii) of section 6702(b)(2)(A).''
(3) Statement of grounds.--Section 6330(b)(1) is amended by
striking ``under subsection (a)(3)(B)'' and inserting ``in
writing under subsection (a)(3)(B) and states the grounds for
the requested hearing''.
(c) Treatment of Frivolous Requests for Hearings Upon Filing of
Notice of Lien.--Section 6320 is amended--
(1) in subsection (b)(1), by striking ``under subsection
(a)(3)(B)'' and inserting ``in writing under subsection
(a)(3)(B) and states the grounds for the requested hearing'',
and
(2) in subsection (c), by striking ``and (e)'' and
inserting ``(e), and (g)''.
(d) Treatment of Frivolous Applications for Offers-in-Compromise
and Installment Agreements.--Section 7122 is amended by adding at the
end the following new subsection:
``(e) Frivolous Submissions, Etc.--Notwithstanding any other
provision of this section, if the Secretary determines that any portion
of an application for an offer-in-compromise or installment agreement
submitted under this section or section 6159 meets the requirement of
clause (i) or (ii) of section 6702(b)(2)(A), then the Secretary may
treat such portion as if it were never submitted and such portion shall
not be subject to any further administrative or judicial review.''
(e) Clerical Amendment.--The table of sections for part I of
subchapter B of chapter 68 is amended by striking the item relating to
section 6702 and inserting the following new item:

``Sec. 6702. Frivolous tax submissions.''
(f) Effective Date.--The amendments made by this section shall
apply to submissions made and issues raised after the date on which the
Secretary first prescribes a list under section 6702(c) of the Internal
Revenue Code of 1986, as amended by subsection (a).

SEC. 734. REGULATION OF INDIVIDUALS PRACTICING BEFORE THE DEPARTMENT OF
TREASURY.

(a) Censure; Imposition of Penalty.--
(1) In general.--Section 330(b) of title 31, United States
Code, is amended--
(A) by inserting ``, or censure,'' after
``Department'', and
(B) by adding at the end the following new flush
sentence:
``The Secretary may impose a monetary penalty on any representative
described in the preceding sentence. If the representative was acting
on behalf of an employer or any firm or other entity in connection with
the conduct giving rise to such penalty, the Secretary may impose a
monetary penalty on such employer, firm, or entity if it knew, or
reasonably should have known, of such conduct. Such penalty shall not
exceed the gross income derived (or to be derived) from the conduct
giving rise to the penalty and may be in addition to, or in lieu of,
any suspension, disbarment, or censure.''
(2) Effective date.--The amendments made by this subsection
shall apply to actions taken after the date of the enactment of
this Act.
(b) Tax Shelter Opinions, etc.--Section 330 of such title 31 is
amended by adding at the end the following new subsection:
``(d) Nothing in this section or in any other provision of law
shall be construed to limit the authority of the Secretary of the
Treasury to impose standards applicable to the rendering of written
advice with respect to any entity, transaction plan or arrangement, or
other plan or arrangement, which is of a type which the Secretary
determines as having a potential for tax avoidance or evasion.''

SEC. 735. PENALTY ON PROMOTERS OF TAX SHELTERS.

(a) Penalty on Promoting Abusive Tax Shelters.--Section 6700(a) is
amended by adding at the end the following new sentence:
``Notwithstanding the first sentence, if an activity with respect to
which a penalty imposed under this subsection involves a statement
described in paragraph (2)(A), the amount of the penalty shall be equal
to 50 percent of the gross income derived (or to be derived) from such
activity by the person on which the penalty is imposed.''
(b) Effective Date.--The amendment made by this section shall apply
to activities after the date of the enactment of this Act.

Subtitle C--Executive Compensation

SEC. 741. REPEAL OF 1978 REVENUE ACT LIMITATION ON SECRETARY OF THE
TREASURY'S AUTHORITY TO DETERMINE YEAR OF INCLUSION OF
AMOUNTS UNDER PRIVATE DEFERRED COMPENSATION PLANS.

(a) Repeal.--Section 132 of the Revenue Act of 1978 (Public Law 95-
600) is repealed.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after the date of the enactment of this Act.

SEC. 742. TREATMENT OF NONQUALIFIED DEFERRED COMPENSATION FUNDED WITH
ASSETS LOCATED OUTSIDE THE UNITED STATES.

(a) In General.--Section 83(c) (relating to special rules for
property transferred in connection with performance of services) is
amended by adding at the end the following new paragraph:
``(4) Foreign assets funding nonqualified deferred
compensation arrangements.--
``(A) In general.--In determining whether there is
a transfer of property for purposes of subsection (a),
if assets are--
``(i) designated or otherwise available for
the payment of nonqualified deferred
compensation, and
``(ii) located outside the United States,
such assets shall not be treated as subject to the
claims of creditors.
``(B) Compensation for services performed in
foreign jurisdiction.--Subparagraph (A) shall not apply
to assets located in a foreign jurisdiction if
substantially all of the services to which the
nonqualified deferred compensation relates are
performed in such jurisdiction.
``(C) Regulations.--The Secretary shall prescribe
such regulations as are necessary to carry out the
provisions of this paragraph, including regulations to
exempt arrangements from the application of this
paragraph if--
``(i) the arrangement will not result in an
improper deferral of United States tax, and
``(ii) the assets involved in the
arrangement will be readily accessible in any
insolvency or bankruptcy proceeding.''
(b) Effective Date.--The amendments made by this section shall
apply to amounts deferred after December 31, 2002.

SEC. 743. INCLUSION IN GROSS INCOME OF FUNDED DEFERRED COMPENSATION OF
CORPORATE INSIDERS.

(a) In General.--Subpart A of part I of subchapter D of chapter 1
is amended by adding at the end the following new section:

``SEC. 409A. INCLUSION IN GROSS INCOME OF FUNDED DEFERRED COMPENSATION
OF CORPORATE INSIDERS.

``(a) In General.--If an employer maintains a funded deferred
compensation plan--
``(1) compensation of any disqualified individual which is
deferred under such funded deferred compensation plan shall be
included in the gross income of the disqualified individual or
beneficiary for the 1st taxable year in which there is no
substantial risk of forfeiture of the rights to such
compensation, and
``(2) the tax treatment of any amount made available under
the plan to a disqualified individual or beneficiary shall be
determined under section 72 (relating to annuities, etc.).
``(b) Funded Deferred Compensation Plan.--For purposes of this
section--
``(1) In general.--The term `funded deferred compensation
plan' means any plan providing for the deferral of compensation
unless--
``(A) the employee's rights to the compensation
deferred under the plan are no greater than the rights
of a general creditor of the employer, and
``(B) all amounts set aside (directly or
indirectly) for purposes of paying the deferred
compensation, and all income attributable to such
amounts, remain (until made available to the
participant or other beneficiary) solely the property
of the employer (without being restricted to the
provision of benefits under the plan), and
``(C) the amounts referred to in subparagraph (B)
are available to satisfy the claims of the employer's
general creditors at all times (not merely after
bankruptcy or insolvency).
Such term shall not include a qualified employer plan.
``(2) Special rules.--
``(A) Employee's rights.--A plan shall be treated
as failing to meet the requirements of paragraph (1)(A)
unless--
``(i) the compensation deferred under the
plan is payable only upon separation from
service, death, disability (within the meaning
of section 1614(a)(3) of the Social Security
Act (42 U.S.C. 1382c(a)(3))), or at a specified
time (or pursuant to a fixed schedule), and
``(ii) the plan does not permit the
acceleration of the time such deferred
compensation is payable by reason of any event.
If the employer and employee agree to a modification of
the plan that accelerates the time for payment of any
deferred compensation, then all compensation previously
deferred under the plan shall be includible in gross
income for the taxable year during which such
modification takes effect and the taxpayer shall pay
interest at the underpayment rate on the underpayments
that would have occurred had the deferred compensation
been includible in gross income on the earliest date
that there is no substantial risk of forfeiture of the
rights to such compensation.
``(B) Creditor's rights.--A plan shall be treated
as failing to meet the requirements of paragraph (1)(B)
with respect to amounts set aside in a trust unless--
``(i) the employee has no beneficial
interest in the trust,
``(ii) assets in the trust are available to
satisfy claims of general creditors at all
times (not merely after bankruptcy or
insolvency), and
``(iii) there is no factor that would make
it more difficult for general creditors to
reach the assets in the trust than it would be
if the trust assets were held directly by the
employer in the United States.
Except as provided in regulations prescribed by the
Secretary, such a factor shall include the location of
the trust outside the United States unless
substantially all of the services to which the
nonqualified deferred compensation relates are
performed outside the United States. Such regulations
may exempt any such trust if the trust will not result
in an improper deferral of United States tax, and the
assets involved in the trust will be readily accessible
in any insolvency or bankruptcy proceeding.
``(c) Disqualified Individual.--For purposes of this section, the
term `disqualified individual' means, with respect to a corporation,
any individual--
``(1) who is subject to the requirements of section 16(a)
of the Securities Exchange Act of 1934 with respect to such
corporation, or
``(2) who would be subject to such requirements if such
corporation were an issuer of equity securities referred to in
such section.
``(d) Other Definitions and Special Rules.--For purposes of this
section--
``(1) Qualified employer plan.--The term `qualified
employer plan' means--
``(A) any plan, contract, pension, account, or
trust described in subparagraph (A) or (B) of section
219(g)(5), and
``(B) any other plan of an organization exempt from
tax under subtitle A.
``(2) Plan includes arrangements, etc.--The term `plan'
includes any agreement or arrangement.
``(3) Substantial risk of forfeiture.--The rights of a
person to compensation are subject to a substantial risk of
forfeiture if such person's rights to such compensation are
conditioned upon the future performance of substantial services
by any individual.
``(4) Treatment of earnings.--Except for purposes of
subsection (a)(1) and the last sentence of (b)(2)(A),
references to deferred compensation shall be treated as
including references to income attributable to such
compensation or such income.''
(b) Clerical Amendment.--The table of sections for such subpart A
is amended by adding at the end the following new item:

``Sec. 409A. Inclusion in gross income of
funded deferred compensation of
corporate insiders.''
(c) Effective Date.--The amendments made by this section shall
apply to amounts deferred after December 31, 2002.

SEC. 744. INCREASE IN WITHHOLDING FROM SUPPLEMENTAL WAGE PAYMENTS IN
EXCESS OF $1,000,000.

(a) In General.--If an employer elects under Treasury Regulation
31.3402(g)-1 to determine the amount to be deducted and withheld from
any supplemental wage payment by using a flat percentage rate, the rate
to be used in determining the amount to be so deducted and
withheld shall not be less than 28 percent (or the corresponding rate
in effect under section 1(i)(2) of the Internal Revenue Code of 1986
for taxable years beginning in the calendar year in which the payment
is made).
(b) Special Rule for Large Payments.--
(1) In general.--Notwithstanding subsection (a), if the
supplemental wage payment, when added to all such payments
previously made by the employer to the employee during the
calendar year, exceeds $1,000,000, the rate used with respect
to such excess shall be equal to the maximum rate of tax in
effect under section 1 of such Code for taxable years beginning
in such calendar year.
(2) Aggregation.--All persons treated as a single employer
under subsection (a) or (b) of section 52 of the Internal
Revenue Code of 1986 shall be treated as a single employer for
purposes of this subsection.
(c) Conforming Amendment.--Section 13273 of the Revenue
Reconciliation Act of 1993 (Public Law 103-66) is repealed.
(d) Effective Date.--The provisions of, and the amendment made by,
this section shall apply to payments made after December 31, 2002.

Subtitle D--Other Provisions

SEC. 751. AFFIRMATION OF CONSOLIDATED RETURN REGULATION AUTHORITY.

(a) In General.--Section 1502 (relating to consolidated return
regulations) is amended by adding at the end the following new
sentence: ``In prescribing such regulations, the Secretary may
prescribe rules applicable to corporations filing consolidated returns
under section 1501 that are different from other provisions of this
title that would apply if such corporations filed separate returns.''
(b) Result Not Overturned.--Notwithstanding subsection (a), the
Internal Revenue Code of 1986 shall be construed by treating Treasury
regulation Sec. 1.1502-20(c)(1)(iii) (as in effect on January 1, 2001)
as being inapplicable to the type of factual situation in 255 F.3d 1357
(Fed. Cir. 2001).
(c) Effective Date.--The provisions of this section shall apply to
taxable years beginning before, on, or after the date of the enactment
of this Act.

SEC. 752. DENIAL OF DEDUCTION FOR CERTAIN FINES, PENALTIES, AND OTHER
AMOUNTS.

(a) In General.--Subsection (f) of section 162 (relating to trade
or business expenses) is amended to read as follows:
``(f) Fines, Penalties, and Other Amounts.--
``(1) In general.--Except as provided in paragraph (2), no
deduction otherwise allowable shall be allowed under this
chapter for any amount paid or incurred (whether by suit,
agreement, or otherwise) to, or at the direction of, a
government in relation to the violation of any law or the
investigation or inquiry into the potential violation of any
law.
``(2) Exception for amounts constituting restitution.--
Paragraph (1) shall not apply to any amount which the taxpayer
establishes constitutes restitution for damage or harm caused
by the violation of any law or the potential violation of any
law. This paragraph shall not apply to any amount paid or
incurred as reimbursement to the government for the costs of
any investigation or litigation.
``(3) Treatment of certain nongovernmental regulatory
entities.--For purposes of paragraph (1), amounts paid or
incurred to, or at the direction of, the following
nongovernmental entities shall be treated as amounts paid or
incurred to, or at the direction of, a government:
``(A) Any nongovernmental entity which exercises
self-regulatory powers (including imposing sanctions)
in connection with a qualified board or exchange (as
defined in section 1256(g)(7)).
``(B) To the extent provided in regulations, any
nongovernmental entity which exercises self-regulatory
powers (including imposing sanctions) as part of
performing an essential governmental function.''
(b) Effective Date.--The amendment made by this section shall apply
to amounts paid or incurred after the date of the enactment of this
Act, except that such amendment shall not apply to amounts paid or
incurred under any binding order or agreement entered into on or before
such date.
<all>