Contract With Investors
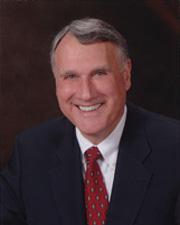 Sen. Jon Kyl (R-AZ)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Sponsor introductory remarks on measure. (CR S225-226)
January 13, 2003
View full timeline
Introduced in Senate
January 7, 2003
Read twice and referred to the Committee on Finance.
January 7, 2003
Sponsor introductory remarks on measure. (CR S225-226)
January 13, 2003
Floor Debate
11 membersWhat members said about S. 96 on the floor

 +6
Floor Debate
11 membersWhat members said about S. 96 on the floor
Mr. President, I rise to introduce legislation to authorize the distribution of judgment funds to eligible tribal members of the Gila River Indian Community in Arizona. Identical legislation…
Mr. President, today I join Senators Boxer, Chafee, and others to introduce The Toxic Clean Up and Polluter Pays Renewal Act for. For more than 20 years, the polluter pays principle has been a…
Mr. President, I rise today to join Senator Hutchison in introducing the Air Cargo Security Act, a bill that passed the Senate by Unanimous Consent in the 107th Congress. Today Senator Hutchison and…
Mr. President, I rise today with my colleague, Senator DeWine, to introduce legislation which will help maintain our leadership in a field Thomas Edison invented over 100 years ago, lighting. The…
Mr. President, today I am introducing legislation to repeal the death tax permanently, effective January 1, 2005. While I strongly believe that Congress must make all of the tax cuts enacted in 2001…
Show 6 more
Mr. President, I rise today to introduce the Clean Water Infrastructure Financing Act of 2003, legislation which will reauthorize the highly successful, but undercapitalized, Clean Water State…
Mr. President, as another semester begins, many college students are worrying not only about their course loads and class work, but about how they will pay for school. Today, the average cost of…

Mr. President, today I am reintroducing a bill that addresses a critical gap that now exists in the funding for the clean- up of the Nation's most toxic waste sites. The Toxic Clean-up Polluter Pays…
Mr. President, I rise today to introduce, along with my colleague Senator Feinstein, the Air Cargo Security Act. Since the 9/11 attacks, we in Congress, working with the Administration, the aviation…
Mr. President, I am pleased to introduce legislation that codifies the exclusion of irrevocable funeral trusts from Supplemental Security Income, SSI, resource calculations. Irrevocable funeral…
Mr. President, I ask unanimous consent that the text of the bill be printed in the Record.
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 96 Introduced in Senate (IS)]

108th CONGRESS
1st Session
S. 96

To repeal the sunset of the provisions of the Economic Growth and Tax
Relief Reconciliation Act of 2001, and for other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

January 7, 2003

Mr. Kyl introduced the following bill; which was read twice and
referred to the Committee on Finance

_______________________________________________________________________

A BILL

To repeal the sunset of the provisions of the Economic Growth and Tax
Relief Reconciliation Act of 2001, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Contract With Investors''.

SEC. 2. REPEAL OF SUNSET.

Title IX of the Economic Growth and Tax Relief Reconciliation Act
of 2001 (Public Law 107-16) is repealed.

SEC. 3. ACCELERATION OF INDIVIDUAL INCOME TAX RATE REDUCTIONS.

(a) In General.--The table contained in section 1(i)(2) of the
Internal Revenue Code of 1986 (relating to reductions in rates after
June 30, 2001) is amended--
(1) by striking ``and 2003'',
(2) by striking ``2004 and 2005'' and inserting ``2003'',
and
(3) by striking ``2006'' and inserting ``2004''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 4. REPEAL OF ESTATE AND GENERATION-SKIPPING TRANSFER TAXES
ACCELERATED TO 2005.

(a) Estate Tax Repeal.--Section 2210 of the Internal Revenue Code
of 1986 (relating to termination) is amended--
(1) by striking ``December 31, 2009'' and inserting
``December 31, 2004'' both places it appears,
(2) by striking ``January 1, 2010'' in subsection (b) and
inserting ``January 1, 2005'', and
(3) by striking ``December 31, 2020'' in subsection (b)(1)
and inserting ``December 31, 2014''.
(b) Generation-Skipping Transfer Tax Repeal.--Section 2664 of such
Code (relating to termination) is amended by striking ``December 31,
2009'' and inserting ``December 31, 2004''.
(c) Conforming Amendments.--
(1) The table contained in section 2010(c) of such Code is
amended--
(A) by striking ``and 2005'',
(B) by inserting a period after ``$1,500,000'', and
(C) by striking the last 2 items.
(2) Section 1014(f) of such Code is amended by striking
``December 31, 2009'' and inserting ``December 31, 2004''.
(3) Section 1022 of such Code is amended--
(A) by striking ``December 31, 2009'' in the
heading and in subsection (a)(1) and inserting
``December 31, 2004'', and
(B) in subsection (d)(4)(A)--
(i) by striking ``2010'' and inserting
``2005'',
(ii) by striking ``2009'' in clause (ii)
and inserting ``2004''.
(4) The table contained in section 2001(c)(2)(B) of such
Code is amended--
(A) by inserting a period after ``48 percent'', and
(B) by striking the last 3 items.
(5) Section 2001(c)(2)(A) of such Code is amended by
striking ``2010'' and inserting ``2005''.
(6) The item in the table of sections for part II of
subchapter O of chapter 1 of such Code relating to section 1022
is amended by striking ``December 31, 2009'' and inserting
``December 31, 2004''.
(7) Section 501(d) of the Economic Growth and Tax Relief
Reconciliation Act of 2001 (Public Law 107-16) is amended by
striking ``December 31, 2009'' and inserting ``December 31,
2004''.
(8) Paragraph (3) of section 511(f) of the Economic Growth
and Tax Relief Reconciliation Act of 2001 (Public Law 107-16)
is amended by striking ``December 31, 2009'' and inserting
``December 31, 2004''.
(9) Paragraph (2) of section 521(e) of the Economic Growth
and Tax Relief Reconciliation Act of 2001 (Public Law 107-16)
is amended by striking ``December 31, 2009'' and inserting
``December 31, 2004''.
(10) Subsection (f) of section 542 of the Economic Growth
and Tax Relief Reconciliation Act of 2001 (Public Law 107-16)
is amended by striking ``December 31, 2009'' each place it
appears and inserting ``December 31, 2004''.
(d) Effective Date.--The amendments made by this section shall take
effect on the date of the enactment of this Act.

SEC. 5. REDUCTION OF MAXIMUM CAPITAL GAINS RATES FOR INDIVIDUALS.

(a) In General.--Section 1(h) of the Internal Revenue Code of 1986
(relating to maximum capital gains rate) is amended to read as follows:
``(h) Maximum Capital Gains Rate.--
``(1) In general.--If a taxpayer has a net capital gain for
any taxable year, the tax imposed by this section for such
taxable year shall not exceed the sum of--
``(A) a tax computed on taxable income reduced by
the net capital gain, at the rates and in the same
manner as if this subsection had not been enacted, plus
``(B) 10 percent of the taxpayer's net capital gain
(or, if less, taxable income).
``(2) Net capital gain taken into account as investment
income.--For purposes of this subsection, the net capital gain
for any taxable year shall be reduced (but not below zero) by
the amount which the taxpayer elects to take into account as
investment income for the taxable year under section
163(d)(4)(B)(iii).''.
(b) Minimum Tax.--
(1) In general.--Subparagraph (A) of section 55(b)(1) of
the Internal Revenue Code of 1986 (relating to amount of
tentative tax) is amended by redesignating clauses (ii) and
(iii) as clauses (iii) and (iv), respectively, and by inserting
after clause (i) the following new clause:
``(ii) Maximum rate of tax on net capital
gain.--The amount determined under the first
sentence of clause (i) shall not exceed the sum
of--
``(I) the amount determined under
such first sentence computed at the
rates and in the same manner as if this
clause had not been enacted on the
taxable excess reduced by the net
capital gain, plus
``(II) a tax of 10 percent of the
lesser of the net capital gain or the
taxable excess.''.
(2) Conforming amendment.--Section 55(b) of such Code is
amended by striking paragraph (3).
(c) Conforming Amendments.--
(1) Section 57(a)(7) of the Internal Revenue Code of 1986
is amended by striking the last sentence.
(2) Paragraph (1) of section 1445(e) of such Code is
amended by striking ``20 percent'' and inserting ``10
percent''.
(3)(A) The second sentence of section 7518(g)(6)(A) of such
Code is amended by striking ``20 percent'' and inserting ``10
percent''.
(B) The second sentence of section 607(h)(6)(A) of the
Merchant Marine Act, 1936 is amended by striking ``20 percent''
and inserting ``10 percent''.
(d) Effective Dates.--
(1) In general.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.
(2) Withholding.--The amendment made by subsection (c)(2)
shall apply to amounts paid after December 31, 2002.

SEC. 6. INCREASE IN LIMITATION ON CAPITAL LOSSES APPLICABLE TO
INDIVIDUALS.

(a) In General.--Paragraph (1) of section 1211(b) of the Internal
Revenue Code of 1986 (relating to limitation on capital losses for
taxpayers other than corporations) is amended by striking ``$3,000
($1,500'' and inserting ``$10,000 ($5,000''.
(b) Adjustment for Inflation.--Section 1211 of the Internal Revenue
Code of 1986 (relating to limitation on capital losses) is amended by
adding at the end the following new subsection:
``(c) Adjustment for Inflation.--
``(1) In general.--In the case of any taxable year
beginning in a calendar year after 2003, the $10,000 and $5,000
amounts contained in subsection (b)(1) shall each be increased
by an amount equal to--
``(A)(i) such amount, multiplied by
``(ii) the cost-of-living adjustment determined
under section 1(f)(3) for the calendar year in which
the taxable year begins by substituting `calendar year
2002' for `calendar year 1992' in subparagraph (B)
thereof.
``(B) Rounding.--If any increase determined under
paragraph (1) is not a multiple of $5, such increase
shall be rounded to the next highest multiple of $5.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 7. ACCELERATION OF INCREASE IN CONTRIBUTIONS TO CERTAIN RETIREMENT
PLANS.

(a) IRAs.--
(1) In general.--Subparagraph (A) of section 219(b)(5) of
the Internal Revenue Code of 1986 (defining deductible amount)
is amended to read as follows:
``(A) The deductible amount shall be $5,000.''.
(2) Inflation adjustment.--Section 219(b)(5)(C) of such
Code is amended--
(A) by striking ``2008'' and inserting ``2003'',
and
(B) by striking ``2007'' and inserting ``2002''.
(b) 401(k) Plans.--
(1) In general.--Paragraph (1) of section 402(g) of such
Code is amended--
(A) by striking ``the applicable dollar amount'' in
subparagraph (A) and inserting ``$15,000'',
(B) by striking subparagraph (B),
(C) by redesignating subparagraph (C) as
subparagraph (B), and
(D) by striking ``the applicable dollar amount
under subparagraph (B)'' in subparagraph (B) (as
redesignated by subparagraph (C)) and inserting ``the
dollar amount in subparagraph (A)''.
(2) Inflation adjustment.--Section 402(g)(4) of such Code
is amended--
(A) by striking ``2006'' and inserting ``2003'',
and
(B) by striking ``2005'' and inserting ``2002''.
(3) Conforming amendment.--Section 401(a)(30) of such Code
is amended by striking ``section 402(g)(1)(A)'' and inserting
``section 402(g)(1)''.
(c) 457 Plans.--
(1) In general.--Subparagraph (A) of section 457(b)(2) of
such Code is amended by striking ``the applicable dollar
amount'' and inserting ``$15,000''.
(2) Inflation adjustment.--Section 457(e)(15) of such Code
is amended to read as follows:
``(15) Cost-of-living adjustment.--In the case of taxable
years beginning after December 31, 2003, the Secretary shall
adjust the $15,000 amount under subsection (b)(2)(A) at the
same time and in the same manner as under section 415(d),
except that the base period shall be the calendar quarter
beginning July 1, 2002, and any increase under this paragraph
which is not a multiple of $500 shall be rounded to the next
lowest multiple of $500.''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 8. AGE FOR BEGINNING MANDATORY DISTRIBUTIONS INCREASED TO 75.

(a) Qualified Pension Plans.--Subparagraphs (B)(iv) and (C) of
section 401(a)(9) of the Internal Revenue Code of 1986 (relating to
required distributions) are each amended by striking ``70\1/2\'' each
place it appears and inserting ``75''.
(b) Individual Retirement Plans.--
(1) Paragraph (1) of section 219(d) of such Code is
amended--
(A) by striking ``70\1/2\'' in the text and
inserting ``75'', and
(B) by striking ``70\1/2\'' in the heading and
inserting ``75''.
(2) Subsection (b) of section 408 of such Code is amended
by striking ``70\1/2\'' and inserting ``75''.
(c) Roth IRA's.--Paragraph (4) of section 408A(c) of such Code is
amended--
(1) by striking ``70\1/2\'' in the text and inserting
``75'', and
(2) by striking ``70\1/2\'' in the heading and inserting
``75''.
(d) Section 457  Plans.--Clause (i) of section 457(d)(1)(A) of such
Code is amended by striking ``70\1/2\'' and inserting ``75''.
(e) Effective Date.--The amendments made by this section shall
apply to distributions after December 31, 2002.

SEC. 9. EXCLUSION OF DIVIDEND INCOME FROM TAX.

(a) In General.--Part III of subchapter B of chapter 1 of the
Internal Revenue Code of 1986 (relating to amounts specifically
excluded from gross income) is amended by inserting after section 115
the following new section:

``SEC. 116. EXCLUSION OF DIVIDENDS RECEIVED BY INDIVIDUALS.

``(a) Exclusion From Gross Income.--Gross income does not include
100 percent of the amounts received during the taxable year by an
individual as dividends from domestic, publicly traded, C corporations
(within the meaning of section 1297(f)(3)).
``(b) Certain Dividends Excluded.--Subsection (a) shall not apply
to any dividend from a corporation which, for the taxable year of the
corporation in which the distribution is made, or for the next
preceding taxable year of the corporation, is a corporation exempt from
tax under section 501 (relating to certain charitable, etc.,
organization) or section 521 (relating to farmers' cooperative
associations).
``(c) Special Rules.--For purposes of this section--
``(1) Exclusion not to apply to capital gain dividends from
regulated investment companies and real estate investment
trusts.--For treatment of capital gain dividends, see sections
854(a) and 857(c).
``(2) Certain nonresident aliens ineligible for
exclusion.--In the case of a nonresident alien individual,
subsection (a) shall apply only--
``(A) in determining the tax imposed for the
taxable year pursuant to section 871(b)(1) and only in
respect of dividends which are effectively connected
with the conduct of a trade or business within the
United States, or
``(B) in determining the tax imposed for the
taxable year pursuant to section 877(b).
``(3) Dividends from employee stock ownership plans.--
Subsection (a) shall not apply to any dividend described in
section 404(k).''.
(b) Conforming Amendments.--
(1)(A) Subparagraph (A) of section 135(c)(4) of such Code
is amended by inserting ``116,'' before ``137''.
(B) Subsection (d) of section 135 of such Code is amended
by redesignating paragraph (4) as paragraph (5) and by
inserting after paragraph (3) the following new paragraph:
``(4) Coordination with section 116.--This section shall be
applied before section 116.''.
(2) Subsection (c) of section 584 of such Code is amended
by adding at the end thereof the following new flush sentence:
``The proportionate share of each participant in the amount of
dividends received by the common trust fund and to which section 116
applies shall be considered for purposes of such section as having been
received by such participant.''.
(3) Subsection (a) of section 643 of such Code is amended
by redesignating paragraph (7) as paragraph (8) and by
inserting after paragraph (6) the following new paragraph:
``(7) Dividends.--There shall be included the amount of any
dividends excluded from gross income pursuant to section
116.''.
(4) Section 854(a) of such Code is amended by inserting
``section 116 (relating to exclusion of dividends received by
individuals) and'' after ``For purposes of''.
(5) Section 857(c) of such Code is amended to read as
follows:
``(c) Restrictions Applicable to Dividends Received From Real
Estate Investment Trusts.--
``(1) Treatment for section 116.--For purposes of section
116 (relating to exclusion of dividends received by
individuals), a capital gain dividend (as defined in subsection
(b)(3)(C)) received from a real estate investment trust which
meets the requirements of this part shall not be considered as
a dividend.
``(2) Treatment for section 243.--For purposes of section
243 (relating to deductions for dividends received by
corporations), a dividend received from a real estate
investment trust which meets the requirements of this part
shall not be considered as a dividend.''.
(6) The table of sections for part III of subchapter B of
chapter 1 of such Code is amended by inserting after the item
relating to section 115 the following new item:

``Sec. 116. Exclusion of dividends
received by individuals.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 10. SENSE OF THE SENATE REGARDING A CONTRACT WITH INVESTORS.

It is the sense of the Senate that--
(1) Congress should pass legislation to safeguard American
workers' pension and retirement accounts,
(2) Congress should modernize this country's international
tax provisions in order to permit United States companies to
better compete internationally,
(3) Congress should repeal redundant, outdated, and
unscientific regulatory burdens on investors and United States
companies and perform a cost benefit analysis before enacting
new burdens on United States businesses and investors,
(4) Congress should enact meaningful tort reform, and
(5) Congress should enact meaningful tax reform that
simplifies the Federal tax code and reduces the cost recovery
periods that businesses are forced to use to recover the costs
of capital.
<all>