Fair Flat Tax Act of 2005
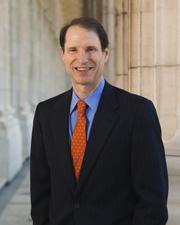 Sen. Ron Wyden (D-OR)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Sponsor introductory remarks on measure. (CR S12146-12148)
November 1, 2005
View full timeline
Introduced in Senate
October 27, 2005
Sponsor introductory remarks on measure. (CR S12009-12010)
October 27, 2005
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S12010-12013)
October 27, 2005
Sponsor introductory remarks on measure. (CR S12146-12148)
November 1, 2005
Floor Debate
7 membersWhat members said about S. 1927 on the floor
 +2
Floor Debate
7 membersWhat members said about S. 1927 on the floor
Mr. President, millions of Americans are now going through a paperwork nightmare, trying to complete their taxes. They are trying to find their 1099s and their W-2s and their schedule this and…
Mr. President, America can do better than making a policeman walking the beat pay a higher Federal tax rate than someone who makes their money on capital gains and dividends. Unfortunately, the…
Mr. President, Senator Specter, Senator Brownback, and I introduce today the Second Chance Act of 2005, which takes direct aim at reducing recidivism rates for our nation's ex-offenders and improving…
Mr. President, today I am proposing a Fair Flat Tax Act that will finally provide real tax relief to America's hurting middle class. It will do so by making the tax system simpler, flatter and…
Mr. President, today I am proposing a Fair Flat Tax Act that will finally provide real tax relief to America's hurting middle class. It will do so by making the tax system simpler, flatter and…
Show 5 more
Mr. President, I have sought recognition to introduce, along with Senators Biden and Brownback, the Second Chance Act of 2005: Community Safety through Recidivism Prevention. This legislation is…
Mr. President, I am please to join with Chairman Specter and Senator Biden today as we introduce a bill that will have a dramatic and positive effect in the lives of individuals re-entering society…
Mr. President, I rise today to introduce legislation focused on a devastating condition known as inflammatory bowel disease (IBD). I am pleased that Senator Cochran has once again joined me in the…

Mr. President, will the Senator yield for a question? I would like to ask the Senator from Oregon through the Chair--first, I would like to tell him that about 10 or 15 years ago, in my hometown, my…

Mr. President, I ask unanimous consent that the order for the quorum call be rescinded. Mr. President, it is my understanding the Senator from New Hampshire is going to make some remarks and I ask…
Bill Text
Latest available legislative text
        [Congressional Bills 109th Congress]
[From the U.S. Government Publishing Office]
[S. 1927 Introduced in Senate (IS)]

109th CONGRESS
1st Session
S. 1927

To amend the Internal Revenue Code of 1986 to make the Federal income
tax system simpler, fairer, and more fiscally responsible, and for
other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

October 27, 2005

Mr. Wyden introduced the following bill; which was read twice and
referred to the Committee on Finance

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to make the Federal income
tax system simpler, fairer, and more fiscally responsible, and for
other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; AMENDMENT OF 1986 CODE; TABLE OF CONTENTS.

(a) Short Title.--This Act may be cited as the ``Fair Flat Tax Act
of 2005''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this Act an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.
(c) Table of Contents.--The table of contents for this Act is as
follows:

Sec. 1. Short title; amendment of 1986 Code; table of contents.
Sec. 2. Purpose.
TITLE I--INDIVIDUAL INCOME TAX REFORMS

Sec. 101. 3 progressive individual income tax rates for all forms of
income.
Sec. 102. Increase in basic standard deduction.
Sec. 103. Refundable credit for State and local income, sales, and real
and personal property taxes.
Sec. 104. Earned income child credit and earned income credit for
childless taxpayers.
Sec. 105. Repeal of individual alternative minimum tax.
Sec. 106. Termination of various exclusions, exemptions, deductions,
and credits.
TITLE II--CORPORATE AND BUSINESS INCOME TAX REFORMS

Sec. 201. Corporate flat tax.
Sec. 202. Treatment of travel on corporate aircraft.
Sec. 203. Termination of various preferential treatments.
Sec. 204. Elimination of tax expenditures that subsidize inefficiencies
in the health care system.
Sec. 205. Pass-through business entity transparency.
TITLE III--TECHNICAL AND CONFORMING AMENDMENTS; SUNSET

Sec. 301. Technical and conforming amendments.
Sec. 302. Sunset.

SEC. 2. PURPOSE.

The purpose of this Act is to amend the Internal Revenue Code of
1986--
(1) to make the Federal individual income tax system
simpler, fairer, and more transparent by--
(A) recognizing the overall Federal, State, and
local tax burden on individual Americans, especially
the regressive nature of State and local taxes, and
providing a Federal income tax credit for State and
local income, sales, and property taxes,
(B) providing for an earned income tax credit for
childless taxpayers and a new earned income child
credit,
(C) repealing the individual alternative minimum
tax,
(D) increasing the basic standard deduction and
maintaining itemized deductions for principal residence
mortgage interest and charitable contributions,
(E) reducing the number of exclusions, exemptions,
deductions, and credits, and
(F) treating all income equally,
(2) to make the Federal corporate income tax rate a flat 35
percent and eliminate special tax preferences that favor
particular types of businesses or activities, and
(3) to partially offset the Federal budget deficit through
the increased revenues resulting from these reforms.

TITLE I--INDIVIDUAL INCOME TAX REFORMS

SEC. 101. 3 PROGRESSIVE INDIVIDUAL INCOME TAX RATES FOR ALL FORMS OF
INCOME.

(a) Married Individuals Filing Joint Returns and Surviving
Spouses.--The table contained in section 1(a) is amended to read as
follows:

``If taxable income is:             The tax is:
Not over $25,000...............
15% of taxable income.
Over $25,000 but not over
$120,000.
$3,750, plus 25% of the excess
over $25,000
Over $120,000..................
$27,500, plus 35% of the excess
over $120,000''.
(b) Heads of Households.--The table contained in section 1(b) is
amended to read as follows:

``If taxable income is:             The tax is:
Not over $16,000...............
15% of taxable income.
Over $16,000 but not over
$105,000.
$2,400, plus 25% of the excess
over $16,000
Over $105,000..................
$24,650, plus 35% of the excess
over $105,000''.
(c) Unmarried Individuals (Other Than Surviving Spouses and Heads
of Households).--The table contained in section 1(c) is amended to read
as follows:

``If taxable income is:             The tax is:
Not over $15,000...............
15% of taxable income.
Over $15,000 but not over
$70,000.
$2,250, plus 25% of the excess
over $15,000
Over $70,000...................
$16,000, plus 35% of the excess
over $70,000''.
(d) Married Individuals Filing Separate Returns.--The table
contained in section 1(d) is amended to read as follows:

``If taxable income is:             The tax is:
Not over $12,500...............
15% of taxable income.
Over $12,500 but not over
$60,000.
$1,875, plus 25% of the excess
over $12,500
Over $60,000...................
$13,750, plus 35% of the excess
over $60,000''.
(e) Conforming Amendments to Inflation Adjustment.--Section 1(f) is
amended--
(1) by striking ``1993''in paragraph (1) and inserting
``2006'',
(2) by striking ``except as provided in paragraph (8)'' in
paragraph (2)(A),
(3) by striking ``1992'' in paragraph (3)(B) and inserting
``2005'',
(4) by striking paragraphs (7) and (8), and
(5) by striking ``Phaseout of Marriage Penalty in 15-
Percent Bracket;'' in the heading thereof.
(f) Repeal of Rate Differential for Capital Gains and Dividends.--
(1) Repeal of 2003 rate reduction.--Section 303 of the Jobs
and Growth Tax Relief Reconciliation Act of 2003 is amended by
striking ``December 3, 2008'' and inserting ``December 31,
2005''.
(2) Termination of pre-2003 capital gain rate
differential.--Section 1(h) is amended (after the application
of paragraph (1)) by adding at the end the following new
paragraph:
``(13) Termination.--This section shall not apply to
taxable years beginning after December 31, 2005.''.
(g) Additional Conforming Amendments.--
(1) Section 1 is amended by striking subsection (i).
(2) The Internal Revenue Code of 1986 is amended by
striking ``calendar year 1992'' each place it appears and
inserting ``calendar year 2005''.
(3) Section 1445(e)(1) (after the application of subsection
(g)(1)) is amended by striking ``(or, to the extent provided in
regulations, 20 percent)''.
(h) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 102. INCREASE IN BASIC STANDARD DEDUCTION.

(a) In General.--Paragraph (2) of section 63(c) (defining standard
deduction) is amended to read as follows:
``(2) Basic standard deduction.--For purposes of paragraph
(1), the basic standard deduction is--
``(A) 200 percent of the dollar amount in effect
under subparagraph (C) for the taxable year in the case
of--
``(i) a joint return, or
``(ii) a surviving spouse (as defined in
section 2(a)),
``(B) $26,250 in the case of a head of household
(as defined in section 2(b)), or
``(C) $15,000 in any other case.''.
(b) Conforming Amendment to Inflation Adjustment.--Section
63(c)(4)(B)(i) is amended by striking ``(2)(B), (2)(C), or''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 103. REFUNDABLE CREDIT FOR STATE AND LOCAL INCOME, SALES, AND REAL
AND PERSONAL PROPERTY TAXES.

(a) General Rule.--Subpart C of part IV of subchapter A of chapter
1 (relating to refundable credits) is amended by redesignating section
36 as section 37 and by inserting after section 35 the following new
section:

``SEC. 36. CREDIT FOR STATE AND LOCAL INCOME, SALES, AND REAL AND
PERSONAL PROPERTY TAXES.

``(a) Allowance of Credit.--In the case of an individual, there
shall be allowed as a credit against the tax imposed by this subtitle
for the taxable year an amount equal to 10 percent of the qualified
State and local taxes paid by the taxpayer for such year.
``(b) Qualified State and Local Taxes.--For purposes of this
section, the term `qualified State and local taxes' means--
``(1) State and local income taxes,
``(2) State and local general sales taxes,
``(3) State and local real property taxes, and
``(4) State and local personal property taxes.
``(c) Definitions and Special Rules.--For purposes of this
section--
``(1) State or local taxes.--A State or local tax includes
only a tax imposed by a State, a possession of the United
States, or a political subdivision of any of the foregoing, or
by the District of Columbia.
``(2) General sales taxes.--
``(A) In general.--The term `general sales tax'
means a tax imposed at one rate with respect to the
sale at retail of a broad range of classes of items.
``(B) Application of rules.--Rules similar to the
rules under subparagraphs (C), (D), (E), (F), (G), and
(H) of section 164(b)(5) shall apply.
``(3) Personal property taxes.--The term `personal property
tax' means an ad valorem tax which is imposed on an annual
basis in respect of personal property.
``(4) Application of rules to property taxes.--Rules
similar to the rules of subsections (c) and (d) of section 164
shall apply.
``(5) No credit for married individuals filing separate
returns.--If the taxpayer is a married individual (within the
meaning of section 7703), this section shall apply only if the
taxpayer and the taxpayer's spouse file a joint return for the
taxable year.
``(6) Denial of credit to dependents.--No credit shall be
allowed under this section to any individual with respect to
whom a deduction under section 151 is allowable to another
taxpayer for a taxable year beginning in the calendar year in
which such individual's taxable year begins.
``(7) Denial of double benefit.--Any amount taken into
account in determining the credit allowable under this section
may not be taken into account in determining any credit or
deduction under any other provision of this chapter.''.
(b) Technical Amendments.--
(1) Paragraph (2) of section 1324(b) of title 31, United
States Code, is amended by inserting ``or from section 36 of
such Code'' before the period at the end.
(2) The table of sections for subpart C of part IV of
subchapter A of chapter 1 is amended by striking the item
relating to section 36 and inserting the following:

``Sec. 36. Credit for state and local income, sales, and real and
personal property taxes.
``Sec. 37. Overpayments of tax.''.
(c) Report Regarding Use of Credit by Renters.--Not later than 180
days after the date of the enactment of this Act, the Secretary of the
Treasury shall report to the Committee on Finance of the Senate and the
Committee on Ways and Means of the House of Representatives
recommendations regarding the treatment of a portion of rental payments
in a manner similar to real property taxes under section 36 of the
Internal Revenue Code of 1986 (as added by this section).
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 104. EARNED INCOME CHILD CREDIT AND EARNED INCOME CREDIT FOR
CHILDLESS TAXPAYERS.

(a) In General.--Subsection (a) of section 32 (relating to earned
income) is amended to read as follows:
``(a) Allowance of Earned Income Child Credit and Earned Income
Credit.--
``(1) In general.--There shall be allowed as a credit
against the tax imposed by this subtitle for the taxable year--
``(A) in the case of any eligible individual with 1
or more qualifying children, an amount equal to the
earned income child credit amount, and
``(B) in the case of any eligible individual with
no qualifying children, an amount equal to the earned
income credit amount.
``(2) Earned income child credit amount.--For purposes of
this section, the earned income child credit amount is equal to
the sum of--
``(A) the credit percentage of so much of the
taxpayer's earned income for the taxable year as does
not exceed the earned income limit amount, plus
``(B) the supplemental child credit amount
determined under subsection (n) for such taxable year.
``(3) Earned income credit amount.--For purposes of this
section, the earned income credit amount is equal to the credit
percentage of so much of the taxpayer's earned income for the
taxable year as does not exceed the earned income limit amount.
``(4) Limitation.--The amount of the credit allowable to a
taxpayer under paragraph (2)(A) or (3) for any taxable year
shall not exceed the excess (if any) of--
``(A) the credit percentage of the earned income
amount, over
``(B) the phaseout percentage of so much of the
adjusted gross income (or, if greater, the earned
income) of the taxpayer for the taxable year as exceeds
the phaseout amount.''.
(b) Supplemental Child Credit Amount.--Section 32 is amended by
adding at the end the following new subsection:
``(n) Supplemental Child Credit Amount.--
``(1) In general.--For purposes of subsection (a)(2)(B),
the supplemental child credit amount for any taxable year is
equal to the lesser of--
``(A) the credit which would be allowed under
section 24 for such taxable year without regard to the
limitation under section 24(b)(3) with respect to any
qualifying child as defined under subsection (c)(3), or
``(B) the amount by which the aggregate amount of
credits allowed by subpart A for such taxable year
would increase if the limitation imposed by section
24(b)(3) were increased by the excess (if any) of--
``(i) 15 percent of so much of the
taxpayer's earned income which is taken into
account in computing taxable income for the
taxable year as exceeds $10,000, or
``(ii) in the case of a taxpayer with 3 or
more qualifying children (as so defined), the
excess (if any) of--
``(I) the taxpayer's social
security taxes for the taxable year,
over
``(II) the credit allowed under
this section for the taxable year.
The amount of the credit allowed under this subsection shall
not be treated as a credit allowed under subpart A and shall
reduce the amount of credit otherwise allowable under section
24(a) without regard to section 24(b)(3).
``(2) Social security taxes.--For purposes of paragraph
(1)--
``(A) In general.--The term `social security taxes'
means, with respect to any taxpayer for any taxable
year--
``(i) the amount of the taxes imposed by
section 3101 and 3201(a) on amounts received by
the taxpayer during the calendar year in which
the taxable year begins,
``(ii) 50 percent of the taxes imposed by
section 1401 on the self-employment income of
the taxpayer for the taxable year, and
``(iii) 50 percent of the taxes imposed by
section 3211(a)(1) on amounts received by the
taxpayer during the calendar year in which the
taxable year begins.
``(B) Coordination with special refund of social
security taxes.--The term `social security taxes' shall
not include any taxes to the extent the taxpayer is
entitled to a special refund of such taxes under
section 6413(c).
``(C) Special rule.--Any amounts paid pursuant to
an agreement under section 3121(l) (relating to
agreements entered into by American employers with
respect to foreign affiliates) which are equivalent to
the taxes referred to in subparagraph (A)(i) shall be
treated as taxes referred to in such paragraph.
``(3) Inflation adjustment.--In the case of any taxable
year beginning in a calendar year after 2005, the $10,000
amount contained in paragraph (1)(B) shall be increased by an
amount equal to--
``(A) such dollar amount, multiplied by
``(B) the cost-of-living adjustment determined
under section 1(f)(3) for the calendar year in which
the taxable year begins, determined by substituting
`calendar year 2000' for `calendar year 1992' in
subparagraph (B) thereof.
Any increase determined under the preceding sentence shall be
rounded to the nearest multiple of $50.''.
(c) Conforming Amendment.--Section 24(d) is amended by adding at
the end the following new paragraph:
``(4) Termination.--This subsection shall not apply with
respect to any taxable year beginning after December 31,
2005.''.
(d) Certain Treatment of Earned Income Made Permanent.--Clause (vi)
of section 32(c)(2)(B) is amended to read as follows:
``(vi) a taxpayer may elect to treat
amounts excluded from gross income by reason of
section 112 as earned income.''.
(e) Repeal of Disqualified Investment Income Test.--Subsection (i)
of section 32 is repealed.
(f) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 105. REPEAL OF INDIVIDUAL ALTERNATIVE MINIMUM TAX.

(a) In General.--Section 55(a) (relating to alternative minimum tax
imposed) is amended by adding at the end the following new flush
sentence:
``For purposes of this title, the tentative minimum tax on any taxpayer
other than a corporation for any taxable year beginning after December
31, 2005, shall be zero.''.
(b) Modification of Limitation on Use of Credit for Prior Year
Minimum Tax Liability.--Subsection (c) of section 53 (relating to
credit for prior year minimum tax liability) is amended to read as
follows:
``(c) Limitation.--
``(1) In general.--Except as provided in paragraph (2), the
credit allowable under subsection (a) for any taxable year
shall not exceed the excess (if any) of--
``(A) the regular tax liability of the taxpayer for
such taxable year reduced by the sum of the credits
allowable under subparts A, B, D, E, and F of this
part, over
``(B) the tentative minimum tax for the taxable
year.
``(2) Taxable years beginning after 2005.--In the case of
any taxable year beginning after 2005, the credit allowable
under subsection (a) to a taxpayer other than a corporation for
any taxable year shall not exceed 90 percent of the regular tax
liability of the taxpayer for such taxable year reduced by the
sum of the credits allowable under subparts A, B, D, E, and F
of this part.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 106. TERMINATION OF VARIOUS EXCLUSIONS, EXEMPTIONS, DEDUCTIONS,
AND CREDITS.

(a) In General.--Subchapter C of chapter 90 (relating to provisions
affecting more than one subtitle) is amended by adding at the end the
following new section:

``SEC. 7875. TERMINATION OF CERTAIN PROVISIONS.

``The following provisions shall not apply to taxable years
beginning after December 31, 2005:
``(1) Section 44 (relating to credit for expenditures to
provide access to disabled individuals).
``(2) Section 62(a)(2)(D) (relating to deduction for
certain expenses of elementary and secondary school teachers).
``(3) Section 67 (relating to 2-percent floor on
miscellaneous itemized deductions).
``(4) Section 74(c) (relating to exclusion of certain
employee achievement awards).
``(5) Section 79 (relating to exclusion of group-term life
insurance purchased for employees).
``(6) Section 104(a)(1) (relating to exclusion of workmen's
compensation).
``(7) Section 104(a)(2) (relating to exclusion of damages
for physical injuries and sickness).
``(8) Section 107 (relating to exclusion of rental value of
parsonages).
``(9) Section 119 (relating to exclusion of meals or
lodging furnished for the convenience of the employer).
``(10) Section 125 (relating to exclusion of cafeteria plan
benefits).
``(11) Section 132 (relating to certain fringe benefits),
except with respect to subsection (a)(5) thereof (relating to
exclusion of qualified transportation fringe).
``(12) Section 163(h)(4)(A)(i)(II) (relating to definition
of qualified residence).
``(13) Section 165(d) (relating to deduction for wagering
losses).
``(14) Section 217 (relating to deduction for moving
expenses).
``(15) Section 454 (relating to deferral of tax on
obligations issued at discount).
``(16) Section 501(c)(9) (relating to tax-exempt status of
voluntary employees' beneficiary associations).
``(17) Section 911 (relating to exclusion of earned income
of citizens or residents of the United States living abroad).
``(18) Section 912 (relating to exemption for certain
allowances).''.
(b) Conforming Amendment.--The table of sections for subchapter C
of chapter 90 is amended by adding at the end the following new item:

``Sec. 7875. Termination of certain provisions.''.

TITLE II--CORPORATE AND BUSINESS INCOME TAX REFORMS

SEC. 201. CORPORATE FLAT TAX.

(a) In General.--Subsection (b) of section 11 (relating to tax
imposed) is amended to read as follows:
``(b) Amount of Tax.--The amount of tax imposed by subsection (a)
shall be equal to 35 percent of the taxable income.''.
(b) Conforming Amendments.--
(1) Section 280C(c)(3)(B)(ii)(II) is amended by striking
``maximum rate of tax under section 11(b)(1)'' and inserting
``rate of tax under section 11(b)''.
(2) Sections 860E(e)(2)(B), 860E(e)(6)(A)(ii),
860K(d)(2)(A)(ii), 860K(e)(1)(B)(ii), 1446(b)(2)(B), and
7874(e)(1)(B) are each amended by striking ``highest rate of
tax specified in section 11(b)(1)'' and inserting ``rate of tax
specified in section 11(b)''.
(3) Section 904(b)(3)(D)(ii) is amended by striking
``(determined without regard to the last sentence of section
11(b)(1))''.
(4) Section 962 is amended by striking subsection (c) and
by redesignating subsection (d) as subsection (c).
(5) Section 1201(a) is amended by striking ``(determined
without regard to the last 2 sentences of section 11(b)(1))''.
(6) Section 1561(a) is amended--
(A) by striking paragraph (1) and by redesignating
paragraphs (2), (3), and (4) as paragraphs (1), (2),
and (3), respectively,
(B) by striking ``The amounts specified in
paragraph (1), the'' and inserting ``The'',
(C) by striking ``paragraph (2)'' and inserting
``paragraph (1)'',
(D) by striking ``paragraph (3)'' both places it
appears and inserting ``paragraph (2)'',
(E) by striking ``paragraph (4)'' and inserting
``paragraph (3)'', and
(F) by striking the fourth sentence.
(7) Subsection (b) of section 1561 is amended to read as
follows:
``(b) Certain Short Taxable Years.--If a corporation has a short
taxable year which does not include a December 31 and is a component
member of a controlled group of corporations with respect to such
taxable year, then for purposes of this subtitle, the amount to be used
in computing the accumulated earnings credit under section 535(c)(2)
and (3) of such corporation for such taxable year shall be the amount
specified in subsection (a)(1) divided by the number of corporations
which are component members of such group on the last day of such
taxable year. For purposes of the preceding sentence, section 1563(b)
shall be applied as if such last day were substituted for December
31.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 202. TREATMENT OF TRAVEL ON CORPORATE AIRCRAFT.

(a) In General.--Section 162 (relating to trade or business
expenses) is amended by redesignating subsection (q) as subsection (r)
and b inserting after subsection (p) the following new subsection:
``(q) Treatment of Travel on Corporate Aircraft.--The rate at which
an amount allowable as a deduction under this chapter for the use of an
aircraft owned by the taxpayer is determined shall not exceed the rate
at which an amount paid or included in income by an employee of such
taxpayer for the personal use of such aircraft is determined.''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2005.

SEC. 203. TERMINATION OF VARIOUS PREFERENTIAL TREATMENTS.

(a) In General.--Section 7875, as added by section 106, is
amended--
(1) by inserting ``(or transactions in the case of sections
referred to in paragraphs (21), (22), (23), (24), and (27))''
after ``taxable years beginning'', and
(2) by adding at the end the following new paragraphs:
``(19) Section 43 (relating to enhanced oil recovery
credit).
``(20) Section 263(c) (relating to intangible drilling and
development costs in the case of oil and gas wells and
geothermal wells).
``(21) Section 382(l)(5) (relating to exception from net
operating loss limitations for corporations in bankruptcy
proceeding).
``(22) Section 451(i) (relating to special rules for sales
or dispositions to implement Federal Energy Regulatory
Commission or State electric restructuring policy).
``(23) Section 453A (relating to special rules for
nondealers), but only with respect to the dollar limitation
under subsection (b)(1) thereof and subsection (b)(3) thereof
(relating to exception for personal use and farm property).
``(24) Section 460(e)(1) (relating to special rules for
long-term home construction contracts or other short-term
construction contracts).
``(25) Section 613A (relating to percentage depletion in
case of oil and gas wells).
``(26) Section 616 (relating to development costs).
``(27) Sections 861(a)(6), 862(a)(6), 863(b)(2), 863(b)(3),
and 865(b) (relating to inventory property sales source rule
exception).''.
(b) Full Tax Rate on Nuclear Decommissioning Reserve Fund.--
Subparagraph (B) of section 468A(e)(2) is amended to read as follows:
``(B) Rate of tax.--For purposes of subparagraph
(A), the rate set forth in this subparagraph is 35
percent.''.
(c) Deferral of Active Income of Controlled Foreign Corporations.--
Section 952 (relating to subpart F income defined) is amended by adding
at the end the following new subsection:
``(e) Special Application of Subpart.--
``(1) In general.--For taxable years beginning after
December 31, 2005, notwithstanding any other provision of this
subpart, the term `subpart F income' means, in the case of any
controlled foreign corporation, the income of such corporation
derived from any foreign country.
``(2) Applicable rules.--Rules similar to the rules under
the last sentence of subsection (a) and subsection (d) shall
apply to this subsection.''.
(d) Deferral of Active Financing Income.--Section 953(e)(10) is
amended--
(1) by striking ``2006'' and inserting ``2005'', and
(2) by striking ``2007'' and inserting ``2006''.
(e) Depreciation on Equipment in Excess of Alternative Depreciation
System.--Section 168(g)(1) (relating to alternative depreciation
system) is amended by striking ``and'' at the end of subparagraph (D),
by adding ``and'' at the end of subparagraph (E), and by inserting
after subparagraph (E) the following new subparagraph:
``(F) notwithstanding subsection (a), any tangible
property placed in service after December 31, 2005,''.
(f) Effective Date.--The amendments made by subsections (b), (c),
and (d) shall apply to taxable years beginning after December 31, 2005.

SEC. 204. ELIMINATION OF TAX EXPENDITURES THAT SUBSIDIZE INEFFICIENCIES
IN THE HEALTH CARE SYSTEM.

Not later than 180 days after the date of the enactment of this
Act, the Secretary of the Treasury shall report to the Committee on
Finance of the Senate and the Committee on Ways and Means of the House
of Representatives recommendations regarding the elimination of Federal
tax incentives which subsidize inefficiencies in the health care system
and if eliminated would result in Federal budget savings of not less
than $10,000,000,000 annually.

SEC. 205. PASS-THROUGH BUSINESS ENTITY TRANSPARENCY.

Not later than 90 days after the date of the enactment of this Act,
the Secretary of the Treasury shall report to the Committee on Finance
of the Senate and the Committee on Ways and Means of the House of
Representatives regarding the implementation of additional reporting
requirements with respect to any pass-through entity with the goal of
the reduction of tax avoidance through the use of such entities, In
addition, the Secretary shall develop procedures to share such report
data with State revenue agencies under the disclosure requirements of
section 6103(d) of the Internal Revenue Code of 1986.

TITLE III--TECHNICAL AND CONFORMING AMENDMENTS; SUNSET

SEC. 301. TECHNICAL AND CONFORMING AMENDMENTS.

The Secretary of the Treasury or the Secretary's delegate shall not
later than 90 days after the date of the enactment of this Act, submit
to the Committee on Ways and Means of the House of Representatives and
the Committee on Finance of the Senate a draft of any technical and
conforming changes in the Internal Revenue Code of 1986 which are
necessary to reflect throughout such Code the purposes of the
provisions of, and amendments made by, this Act.

SEC. 302. SUNSET.

(a) In General.--All provisions of, and amendments made by, this
Act shall not apply to taxable years beginning after December 31, 2010.
(b) Application of Code.--The Internal Revenue Code of 1986 shall
be applied and administered to taxable years described in subsection
(a) as if the provisions of, and amendments made by, this Act had never
been enacted.
<all>