Mr. Speaker, I rise this evening in order to consider the bereavement resolution in memory of our beloved colleague. Mr. Speaker and colleagues, it is with a profound sense of sadness, as well as a…
Mr. Speaker, I rise this evening in order to consider the bereavement resolution in memory of our beloved colleague.
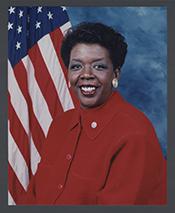
Mr. Speaker and colleagues, it is with a profound sense of sadness, as well as a deep sense of privilege that I rise this evening to commemorate and to celebrate the life of our friend, colleague, and sister, Congresswoman Stephanie Tubbs Jones of Ohio's 11th District. This evening, we do this with the deepest gratitude for her life, and on behalf of our entire Ohio delegation, the people of our State, her home city of Cleveland, and citizens far and wide, who were blessed to know and walk, work, worship and smile along with Stephanie.
On the day of her funeral, the Cleveland Plain Dealer, or actually it was the day after, the Sunday Plain Dealer, had a very large photo of the memorial service held in Cleveland, Ohio. And the headline read, Stephanie Tubbs Jones, 1949 to 2008: Tears flow, laughter rolls during memorial service. And the paper goes on to recount so many beautiful, beautiful remarks and remembrances that people across this country attributed to her life. We will be placing this in the Congressional Record, as well as I would like to read from my home paper, the Toledo Blade, way on the other side of the State from where Stephanie represented. It stated, a leader passes, the loss of her fighting spirit will be keenly felt, deeply mourned and difficult to replace.
I think particularly this evening of her son, Mervyn. We wish him comfort, and we wish him her strength as he mourns her passing.
We all know that when one met Stephanie, you knew you had met strength. You knew you had met someone who endured struggle. She had a keen intelligence, a high-minded idealism, and wow, her charisma just overflowed.
The other day I was in my district and I met a man from Cleveland who had gone to school with Stephanie. And I said, tell me, was Stephanie always that enthusiastic? He said, ``Marcy, I went to law school with her. She never changed.''
And from the time she was in her late teens and early 20s to her service here, she had the same boundless energy, drive and positive spirit.
She was a devoted wife, a beloved mother, a sister to us all, and an elected leader, in that order. And she relished all of her life's roles. Her drive and energy were genuine, and they were infectious. And she carved a nobler path for America with her election as the first African American woman from Ohio to serve in the U.S. Congress. We Ohioans were very proud of her.
I know that I, like my colleagues, have so many vivid lasting memories of Stephanie. Upon her first swearing in, I still recall a little table in a reception hall here where I was able to present her with a single red rose as she was sitting next to her predecessor, Congressman Louis Stokes, and how she poignantly responded. She knew the steepness of the climb.
I recall my efforts to comfort her on the loss of her husband, and she immediately reciprocated as she shared with me, over my Blackberry, a favorite poem from which she drew succor.
Imagine how many memories each of us has, how many thousands of lives she touched, representing a district and State that tested her talents, her spirit, and her conscience daily. She served people well beyond her district, logging thousands of miles in freedom's cause.
I don't think I saw Stephanie too many times without that little valise in the back room here. She was always going somewhere. She held a hard job, and she put her entire being into it. She literally gave herself to us. And in her memory, we should dedicate ourselves to her unfinished work.
One can imagine how few women have ever served in the Congress from our State. To those afforded the privilege, there is a priceless bond that links our spirits and provides support.
Stephanie was such a valued sister. Though her years with us were far too short, her impact endures well beyond the years. She made history. She spoke her conscience, and she reveled in every step of the journey.
Thanks be to God, she did not suffer in the end. The Lord spared her that, perhaps as, through her life, she had endured too much personal sadness and loss that would have broken lesser spirits.
In loss, Stephanie's strength strengthens us. Her enduring personal legacy of character and endurance, beyond her milestone achievements, remain the portrait of her life. Our delegation is especially honored to fittingly commemorate her life and achievements here this evening.
[From the Sunday Plain Dealer, Aug. 31, 2008]
Stephanie Tubbs Jones, 1949-2008: Tears Flow, Laughter Rolls During
Memorial Service
(By Tony Brown)
It was a moment that surely would have earned one of the
wide, knowing smiles remembered so well by all the friends of
Stephanie Tubbs Jones.
Rep. Tim Ryan of Niles, the man Tubbs Jones used to call
her ``white son,'' and fellow Congressman Kendrick Meek of
Florida, whom she nicknamed her ``black son,'' had just
finished moving tributes to their congressional ``mom.''
That's when Mervyn Jones II, her real son, slipped out of
his front-row seat to join his ``brothers'' in an intimate,
tearful embrace in front of thousands gathered to bid
farewell to the first black woman elected to Congress from
Ohio.
The three remained locked in each other's arms well into
remarks made by former Rep. Louis Stokes, the man whose seat
Tubbs Jones inherited in 1989.
After the men returned to their places, Sen. Barack Obama--
the son of a black father and a white mother who grew up to
become the first black presidential nominee of a major U.S.
political party--turned in his chair to console a still-
sobbing Meek.
In that moment, amid the grieving and the laughter and the
consolation and the stories and the campaign rhetoric of the
celebration of a life well-lived, everyone under the vaulted
ceiling of Public Hall--all friends of Tubbs Jones--shared in
that group hug.
It was a hug that encircled the woman whose body lay in a
flag-draped casket that rested on a square of red carpet in
front of the stage: Rep. Stephanie Tubbs Jones, who died of a
burst brain aneurysm on Aug. 20 at the age of 58.
Friend was a word heard over and over as the nation's most
powerful Democratic leaders, fresh from Obama's nomination in
Denver, joined religious leaders and Tubbs Jones' beloved
constituents, family and sorority sisters in testifying to
the immensity of Tubbs Jones' spirit.
Former President Bill Clinton, not scheduled to speak but
unable to help himself, called his relationship with Tubbs
Jones ``16 years of astonishing friendship.''
So astonishing that Tubbs Jones continued to support a
failing presidential bid by his wife, Sen. Hillary Clinton,
well after many of the congresswoman's constituents had voted
for Obama.
``She was not a fair-weather friend,'' Hillary Clinton told
the crowd.
``I certainly know what that means. Now, her friendship was
not uncritical. When she was your friend, she felt it her
responsibility to inform you of all the matters that needed
improvement.''
Obama, Clinton's opponent for the party's presidential
nomination, also counted himself among Tubbs Jones' buddies.
``I am here today to pay tribute to an extraordinary
American and a devoted public servant, a mother, a daughter,
a sister, a wife and a dear friend to so many here in
Cleveland, so many in Ohio and so many across America.
``And during the most recent contest, Stephanie and I were
on different sides, and we would see each other, she would
say to me, ``This is what it means to be a friend for me.'
All I could say is, `I understand.' ''
There were more words of praise and prayer from elected
officials, some quoting Shakespeare and Scripture, during the
three-hour-and-47-minute marathon of tributes.
Speakers included Sen. Sherrod Brown, Mayor Frank Jackson,
Cuyahoga County Commissioner Jimmy Dimora, Rep. Carolyn
Kilpatrick of Michigan and Ohio Gov. Ted Strickland.
And they told plenty of funny and poignant stories.
Perhaps the funniest and most poignant was recounted by
Bill Clinton, who recalled accompanying Tubbs Jones to Puerto
Rico on a primary campaign visit for his wife.
``Now, how Stephanie became a native Puerto Rican in 15
minutes, I'll never know,'' Clinton said, warming to his
subject.
They went into a shop, Clinton said, where Tubbs Jones
admired a piece of locally made jewelry. Clinton bought it
surreptitiously and presented it to her.
``She looked at me and laughed and she said, `You know, I
really like this,' she says. `It's not often a man'll give a
woman a piece of jewelry and not want anything for it.' I
totally lost it.''
So did Clinton's audience. As the laughter died down, the
former president moved in for the kicker.
``I looked at her and said, `Stephanie, you have given me
and our family more, you have given your people and this
country more than you will ever know.' ''
In addition to the eloquent politicians who were gathered,
there were plenty of just plain friends who laughed and wept
and patted each other on the back to the rhythm of hymns like
``Amazing Grace'' and ``Canaan's Happy Shore.''
Some of the late arrivals almost didn't make it into the
funeral.
At 11:30 a.m., about 30 minutes after the service began,
Secret Service officers blocked the entrance. ``The event is
closed,'' one told approaching visitors.
Within minutes, the number lingering at the entrance grew
to more than a dozen. They spoke in shared disbelief.
``Stephanie would not want this,'' one woman said angrily.
Someone in charge agreed. Within minutes, the officers
stepped aside. Newcomers flowed into the cavernous auditorium
until well past noon.
One of the most moving speakers the Friends of Stephanie
heard Saturday was no politician or preacher.
She was a 16-year-old named Tiffany Robertson, a member of
an all-girls health careers class at Cleveland's Martin
Luther King Jr. High School that Tubbs Jones took under her
wing two years ago.
`` `This is the future,' '' Tiffany recalled Jones telling
the girls.
The congresswoman took time from her political and
legislative schedule to visit the class and take them places.
She took them to church one Sunday, but Tiffany had to work.
So Jones dropped by the workplace with Tiffany's classmates
in tow.
``We're family,'' Tiffany told her classmates, who stood in
a show of unity with their peer.
``We got to stick together. We got to carry on her legacy.
She was steward, protector and advocate to us.
``I will miss her as a friend.''
``There's a famous song a few years back . . . and the
refrain of the song says, `If you have a choice, to sit it
out or dance, I hope you dance.' And we all know that
Stephanie didn't sit it out, she danced.''--Tim Ryan, U.S.
Representative from Ohio.
``Stephanie was the kind of political leader who needed
hours to go grocery shopping because everyone she saw wanted
a moment of her time, and she willingly gave it. Because if
you met Stephanie, she was your friend.''--Ted Strickland,
Ohio Governor.
``Oftentimes, late at night, on the campaign trail, whether
the news had been good or bad, she would have a look in her
eye. Sometimes she would grab my hand, and she would say,
`Oh, I miss my husband, I wish he were here.' Well, they are
together now.''--Hillary Clinton, U.S. Senator.
``That's not the air show. The rumbling you hear is the
rearrangement of chairs in heaven.''--Dennis Eckart, Former
Representative standing outside Public Hall as a jet roared
by.
``I considered her my congresswoman as well. We talked all
the time about statewide issues.''--Michael Coleman, Columbus
Mayor.
``Whenever Stephanie came in contact with young people, she
inspired them, she taught them, she mentored them, she stayed
in touch with them. Her legacy is in their legacy.''--Sherrod
Brown, U.S. Senator from Ohio.
``Whenever we talked on the phone, she would say,
`Congresswoman, I love ya.' And I'd say: `I love you, too.'
She was a great congressman. She was a good friend. Thanks,
Stephanie, I love ya.''--Louis Stokes, former U.S.
Representative from Ohio.
``For Stephanie, it wasn't enough to rise up from modest
circumstances and break so many barriers herself. She had to
reach back and pull others through the doors she opened.''--
Barack Obama, Democratic presidential nominee.
``I want to let you know, Cleveland, that you were
represented by one of the best . . .Ladies and gentlemen, she
lived a life that was worth living.''--Kendrick Meek, U.S.
Representative from South Carolina.
``I'll always know her as Aunt Stephanie. She had a big
smile.''--Erin Norton, 24, of Cleveland, whose uncle lived
next to Tubbs Jones.
``All the good things she started, it's like she's still
living.''--Schuvar Murray, 37, of Cleveland.
Mr. Speaker, I would like to call on the distinguished Member from Cleveland, the colleague of Congresswoman Jones, Congressman Dennis Kucinich.
Mr. Speaker, I yield 2 minutes to the distinguished chairman of the Ways and Means Committee from New York City, our beloved colleague, Charles Rangel.
(Mr. RANGEL asked and was given permission to revise and extend his remarks.)
Mr. Speaker, I yield 1\1/2\ minutes to the distinguished gentleman from Georgia (Mr. Scott).
Mr. Speaker, I yield 1\1/2\ minutes to Stephanie's colleague from the State of Ohio, Congressman Zack Space.
Mr. Speaker, I'd like to yield a minute and a half to Stephanie's distinguished colleague from Ohio, our dear friend, Congressman Charles Wilson.
Does the gentleman yield?
Would the gentleman be kind enough to yield us any remaining time he might have so we can complete the speakers on our side.
I thank the gentleman very much.
Mr. Speaker, would you please tell me how much time we have remaining then?
Thank you very much.
I would like then to yield 2 minutes to our fine colleague from the State of California, who was such a close associate and friend of Stephanie's, Congresswoman Lois Capps.
Mr. Speaker, I'd like to yield 2 minutes to the Representative from California who was a close colleague of Stephanie's, Congresswoman Susan Davis.
Mr. Speaker, I would like to yield 1 minute to the distinguished gentlelady from Chicago, Congresswoman Jan Schakowsky, who was a real soul sister to Stephanie.
I would now like to yield time to the distinguished Congressman from North Dakota, Congressman Earl Pomeroy, a friend of Stephanie's for many years.
I thank the gentleman for his remarks and presence this evening.
I would like to yield 2 minutes now to one of Stephanie's sisters here from the State of Texas, Congresswoman Sheila Jackson-Lee.
(Ms. JACKSON-LEE of Texas asked and was given permission to revise and extend her remarks.)
Mr. Speaker, I would like to place in the Record the names of the very able staff of Congresswoman Stephanie Tubbs Jones. This staff has endured great sadness, and they have tried to carry on with their leader being in spiritual guidance but not there personally.
And I would like to thank, from her district office, Betty Pinkney, her district director; Beverly Charles, her senior liaison; Theresa Lang Coaxum, her health liaison; Sharon Cole, business liaison; Saulette Reed, her office manager.
And here in Washington, Kimberley Alton, her legislative director; Lalla King Green, her scheduler; Eric Hammond, her staff assistant; Aaron Wasserman, her legislative correspondent; Darrell Doss, her tax counsel; Athena Abdullah, her health counsel; Nicole Y. Williams, her communications director; and Patrice Willoughby, dear Patrice, her chief of staff and counsel, who has tried to stand in Stephanie's place during these very difficult days.
And, finally, from the Committee on Standards, Dawn Kelly Mobley, the counsel to the chairwoman.
These are wonderful, wonderful staff people who have Stephanie's heart, and we want to do everything we can to help them through this very difficult time. And we thank them for their service to Stephanie and serving the people of the 11th District and the people of our country.
Also, Mr. Speaker, I would like to place in the Record before I call on our final speaker this story: There were many tributes paid to Stephanie at the service in Cleveland. One of the most moving speakers, the friends of Stephanie, heard Saturday from no politician or preacher but from a young 16 year old named Tiffany, a member of an all girls health careers class at Cleveland Martin Luther King Junior
High School that Stephanie took under her wing 2 years ago. Tiffany recalled Jones telling the girls ``This is the future. You are the future.'' And the Congresswoman took time from her political and legislative schedule to visit the class and take them places. She took them to church one Sunday, but Tiffany had to work that day. So Stephanie dropped by to the workplace with Tiffany's classmates in tow. Stephanie kept her eye on every one of them. ``We're family,'' Tiffany told her classmates, who stood in a show of unity with their peer. She said, ``We've got to stick together. We have got to carry on in her legacy. She was steward, protector, and advocate to us. I will miss her as a friend.''
Stephanie had friends of all ages. We thank her for her leadership and for the seeds that she planted in the new growth forest that is growing in Cleveland and growing across this country to which she devoted her life.
Mr. Speaker, I would like to call as our final speaker in this bereavement resolution Stephanie's very good friend from the State of Missouri, Congressman Emanuel Cleaver.
Mr. Speaker, in concluding this first hour this evening in honor of our dear colleague Stephanie Tubbs Jones, let me just say that Stephanie Tubbs Jones was a true mother of this Republic. Let the record show that. Let the record comfort her son in years hence.
And I want to say to our dear, dear friend and colleague Congressman Regula, whose district sort of held Stephanie's up on the southern side, I want to thank him so very much, the dean of the Republican side of the aisle, for being here throughout this evening and through the wonderful participation of her colleagues of various persuasions here on the floor. The friendships went beyond party, and I thank the gentleman for his participation.
Thank you, Congressman Regula, and I want to thank all of our colleagues who have participated this evening. I can guarantee you that every word that is on the Record will come to comfort Mervyn and the Tubbs Jones family, their church family, her sisterhood, all the people of Cleveland, all the people who have known Stephanie across our Nation. I want to thank our colleagues for their generosity and for their good hearts.
Mr. Speaker, I would like to say that the Ohio delegation stands beside those from the Congressional Black Caucus, who will have the second hour this evening in remembrance of Stephanie Tubbs Jones. We thank them very much for doing this. I know how very much their words will mean not just today but in future years to those who love Stephanie always.
Mr. Speaker, I yield back the balance of my time.