Financial Aid Accountability and Transparency Act of 2007
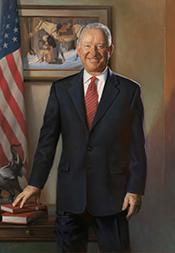 Rep. Howard P. "Buck" McKeon (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Referred to the Subcommittee on Higher Education, Lifelong Learning, and Competitiveness.
July 9, 2007
View full timeline
Introduced in House
April 23, 2007
Referred to the Committee on Education and Labor, and in addition to the Committee on Financial Services, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
April 23, 2007
Referred to the Subcommittee on Financial Institutions and Consumer Credit.
June 7, 2007
Referred to the Subcommittee on Higher Education, Lifelong Learning, and Competitiveness.
July 9, 2007
Floor Debate
24 membersWhat members said about H.R. 1994 on the floor


 +19
Floor Debate
24 membersWhat members said about H.R. 1994 on the floor
Mr. Chairman, I yield myself such time as I may consume. We are dealing with legislation today that seeks to prevent a repetition of events that caused one of the most serious financial crises in…
Mr. Speaker, I move to suspend the rules and pass the bill (H.R. 890) to establish requirements for lenders and institutions of higher education in order to protect students and other borrowers…
Thank you, Mr. Chairman. I would like to thank you and Mel Watt, Mr. Bachus and Mr. Miller and others who have worked so hard on this bill. It is a very complicated issue. You have done a spectacular…
I am grateful to my friend the ranking member and to the chairman, and I do oppose the manager's amendment and the bill. And I don't think there is any difference of opinion about the crisis in the…
Mr. Chairman, I yield myself such time as I may consume. Mr. Chairman, I rise in support of this legislation. I believe that it does, in fact, address abusive practices which, unfortunately, are in…
Show 8 more
I dearly wish that this bill was the one being described by so many people on the other side of the aisle. That sounds like a really tough bill. And this bill, I hope, will become tougher as we go…
Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, I rise in support of this legislation and thank Chairman Miller and Chairman Hinojosa, Ranking Member Keller, and their staffs and…

Mr. Chairman, I rise today in strong support of H.R. 3915, the Mortgage Reform and Anti-Predatory Lending Act of 2007, introduced by my distinguished colleague from North Carolina, Representative…
Mr. Speaker, I would like to thank the chairman and the ranking member for their leadership on this issue. Mr. Speaker, not one of us would be here if it wasn't for the ability to afford a college…

I thank Chairman Frank and my colleagues, Congressmen Watt and Miller, from the great State of North Carolina, who passed legislation in the State legislature first and helped build a strong…

I thank the gentleman for yielding. Mr. Chairman, I would like to thank Chairman Frank and Ranking Member Bachus for working with Members from both sides of the aisle to craft legislation to help…

Mr. Chairman, I rise in support of the ``Mortgage Reform and Anti-Predatory Lending Act of 2007.'' Homeowners in Colorado and nationwide continue to face an impending crisis. Millions of borrowers…
I thank the gentleman for yielding. And I appreciate the Freudian slip by Congressman Chairman Miller. I still am Republican. I am reminded every day when my parking space is now out in Maryland that…
Show 11 more
Mr. Chairman, I rise in support of H.R. 3915, the Mortgage Reform and Anti-Predatory Lending Act of 2007, legislation to combat abusive practices and improve oversight of the mortgage industry. The…

I would like to thank the gentleman from Alabama for recognizing me and yielding me the time, and I greatly appreciate the leadership of the chairman and ranking member on the Committee of Financial…

Mr. Speaker, I rise in strong support of H.R. 890, the Student Loan Sunshine Act. This is the legislation that cannot wait. Given the daily revelations of scandals, conflicts of interest and cozy…

Mr. Chairman, I rise in support, but I want to express some concerns I have with the bill. I have been a long-time advocate of antipredatory legislation that will eliminate abusive lending practices…
Mr. Chairman, I offer an amendment. Mr. Chairman, I've long said that predatory lending is a complex problem that requires a comprehensive solution. The adoption of my amendment will make this bill…

Mr. Chairman, I thank the chairman of the full committee for yielding time, and I thank the ranking member of the full committee who has worked with us and recognized that there is a serious problem…

Mr. Speaker, I rise in support of H.R. 890, the Student Loan Sunshine Act and I thank Chairman George Miller for bringing this bill to the floor. With the rising cost of college, students and…

I thank the ranking member for yielding time, and I appreciate his leadership and friendship on the committee. He has worked very hard on this issue, as has the whole committee. But we have come to…
Mr. Speaker, let me thank both Mr. George Miller and Mr. McKeon. I am in total agreement with them on this legislation. I also would like to thank the staff for their working on this. I think it is a…

I thank the gentleman. I do rise in opposition to this bill and to explain a line of reasoning that the Wall Street Journal and other critics have pointed out on their editorial pages. This proposal,…

Mr. Speaker, in a time when most students graduate with at least $20,000 in debt, it is more important than ever that students can find loans with low interest rates that are easy to pay back. In the…
Bill Text
Latest available legislative text
        [Congressional Bills 110th Congress]
[From the U.S. Government Publishing Office]
[H.R. 1994 Introduced in House (IH)]

110th CONGRESS
1st Session
H. R. 1994

To provide more transparency in the financial aid process and to ensure
that students are receiving the best information about financial aid
opportunities.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

April 23, 2007

Mr. McKeon (for himself and Mr. Keller of Florida) introduced the
following bill; which was referred to the Committee on Education and
Labor, and in addition to the Committee on Financial Services, for a
period to be subsequently determined by the Speaker, in each case for
consideration of such provisions as fall within the jurisdiction of the
committee concerned

_______________________________________________________________________

A BILL

To provide more transparency in the financial aid process and to ensure
that students are receiving the best information about financial aid
opportunities.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Financial Aid Accountability and
Transparency Act of 2007''.

SEC. 2. ACCOUNTABILITY AND TRANSPARENCY.

Title I of the Higher Education Act of 1965 (20 U.S.C. 1001 et
seq.) is amended by adding at the end the following:

``PART E--INSTITUTIONAL REQUIREMENTS RELATED TO STUDENT LOANS

``SEC. 151. DEFINITIONS.

``In this part:
``(1) Agent.--The term `agent', when used with respect to
an institution of higher education, means an organization such
as an alumni association or booster club.
``(2) Lender.--
``(A) In general.--The term `lender'--
``(i) means a creditor, except that such
term shall not include an issuer of credit
under a residential mortgage transaction; and
``(ii) includes an agent of a lender.
``(B) Incorporation of tila definitions.--The terms
`creditor' and `residential mortgage transaction' have
the meanings given such terms in section 103 of the
Truth in Lending Act (15 U.S.C. 1602).
``(3) Loan.--
``(A) Student loan.--The term `student loan'
means--
``(i) any Federal student loan; or
``(ii) a private educational loan.
``(B) Federal student loan.--The term `Federal
student loan' means any loan made, insured, or
guaranteed under title IV of this Act.
``(C) Federal direct loan.--The term `Federal
Direct loan' means any loan made under part D of title
IV of this Act.
``(D) Private educational loan.--The term `private
educational loan' means a private loan provided by a
lender that--
``(i) is not made, insured, or guaranteed
under title IV; and
``(ii) is issued by a lender for
postsecondary educational expenses to a
student, or the parent of the student,
regardless of whether the loan is provided
through the educational institution that the
student attends or directly to the student or
parent from the lender.
``(4) Postsecondary educational expenses.--The term
`postsecondary educational expenses' means any of the expenses
that are included as part of a student's cost of attendance, as
defined under section 472.
``(5) Recommend.--An institution shall be considered to
recommend any lender if the institution communicates to any
student or parent of any student any recommendation, referral,
promotion, or endorsement of any lender or the loan products of
any lender.

``SEC. 152. RECOMMENDED LENDERS.

``No institution of higher education or agent of an institution of
higher education may recommend any lender unless--
``(1) the institution has adopted a formal written policy
concerning the procedures and criteria by which the institution
will select lenders for inclusion in or exclusion from those
recommendations;
``(2) the policy, procedures, and criteria adopted by the
institution are disclosed in accordance with section 153(a);
and
``(3) if the institution recommends--
``(A) any lender for making a Federal student loan,
other than a Federal Direct loan, the institution
recommends a minimum of 3 eligible lenders (as that
term is defined in section 435) that are not affiliated
lenders (as determined in accordance with regulations
of the Secretary) for making such loans; and
``(B) any lender for making a private educational
loan, the institution recommends a minimum of 3 lenders
that are not affiliated lenders (as so determined) for
making such loans.

``SEC. 153. DISCLOSURES.

``(a) Lender Recommendations.--An institution of higher education
shall disclose, on its website and in the informational materials
listed in subsection (d), the policy, procedures, and criteria that the
institution has adopted in accordance with section 152(1), and the
process by which the institution adopted such policy, procedures, and
criteria.
``(b) Model Disclosure Form for Loan Options.--
``(1) Requirement.--The Secretary shall develop and
prescribe an easy-to-read model disclosure form that will
provide students with the relevant information about the terms
and conditions for both Federal loans and private educational
loans for use by both institutions of higher education and
lenders.
``(2) Consultation.--In developing the model disclosure
forms required by this subsection, the Secretary shall consult
with--
``(A) students;
``(B) representatives from institutions of higher
education, including financial aid administrators,
registrars, business officers, and student affairs
officials;
``(C) lenders;
``(D) loan servicers; and
``(E) guaranty agencies.
``(3) Information on federal student loans.--The model
disclosure forms under this subsection with respect to Federal
student loans shall include at a minimum the following
information with respect to loans provided through each lender
recommended by the institution and, in the case of a Federal
Direct loan, with respect to loans provided through the
institution:
``(A) the interest rate of the loan;
``(B) any fees associated with the loan;
``(C) the repayment terms available on the loan;
``(D) the opportunity for deferment or forbearance
with the loan, including whether the loan payments can
be deferred if the student is in school; and
``(E) contact information for the lender.
``(4) Information on private educational loans.--The model
disclosure forms under this subsection with respect to private
educational loans shall include at a minimum the following
information with respect to loans made by each lender
recommended by the institution:
``(A) the method of determining the interest rate
of the loan;
``(B) types of repayment plans that are available;
``(C) whether, and under what conditions, early
repayment may be available without penalty;
``(D) other borrower benefits such as in-school
deferments;
``(E) late payment penalties; and
``(F) such other information as the Secretary may
require.
``(5) Deadline.--The model disclosure forms required by
this subsection shall be developed and prescribed within one
year after the date of enactment of the Financial Aid
Accountability and Transparency Act of 2007.
``(c) Disclosures by Institutions of Higher Education.--An
institution of higher education that participates in the Federal
student loan programs under part B of title IV of this Act, or any
institution that recommends any lender of private educational loans for
its students, shall disclose, on its website and in the informational
materials described in subsection (e)--
``(1) a statement that--
``(A) indicates that students are not limited to or
required to use the lenders the institutions
recommends; and
``(B) the institution is required to process the
documents required to obtain a loan from any eligible
lender the student selects;
``(2) at a minimum, all of the information provided by the
model disclosure form prescribed under subsection (b) with
respect to any lender recommended by the institution for
Federal student loans and, as applicable, private educational
loans;
``(3) disclose the maximum amount of Federal grant and loan
aid available to students in an easy-to-understand format; and
``(4) the institution's cost of attendance (as determined
under section 472).
``(d) Disclosures for Federal Direct Loans.--An institution of
higher education that participates in the Federal Direct loan program
shall disclose, on its website and in the informational materials
described in subsection (e), the information required under paragraphs
(2), (3), and (4) of subsection (c), and the policies, procedures, and
criteria the institution used to make the determination to participate
in such Federal Direct loan program.
``(e) Informational Materials.--The informational materials
described in this subsection are any publications, mailings, or
electronic messages or media distributed to prospective or current
students that describe, discuss, or relate to the financial aid
opportunities available to students at an institution of higher
education.

``SEC. 154. CODE OF CONDUCT.

``(a) Code of Conduct Required.--Each institution of higher
education that participates in the Federal student loan program or has
students that obtain private educational loans shall--
``(1) develop a code of conduct in accordance with
subsection (b) with which its employees, trustees, and
directors are required to comply with respect to student loans;
``(2) publish the code of conduct prominently on its
website; and
``(3) administer and enforce such code in accordance with
the requirements of this section.
``(b) Contents of Code.--
``(1) In general.--The code required by this section shall
contain a limitation on the acceptance of gifts, payments, or
other financial benefits (including the opportunity to purchase
stock) provided to officers and employees of the institution
(and, when appropriate, family members of such officers and
employees) by any lender or guaranty agency that present or may
present a conflict of interest or the appearance of a conflict
of interest with the responsibilities of such officer or
employee with respect to student loans or other financial aid.
``(2) Fees from lenders for service prohibited.--The code
required by this section shall prohibit any officer or employee
who is employed in the financial aid office of the institution,
or who otherwise has responsibilities with respect to student
loans or other financial aid, from accepting from any lender or
affiliate of any lender any fee, payment, or other financial
benefit (including the opportunity to purchase stock) as
compensation for consulting services, serving on an advisory
council, or otherwise advising such lender or affiliate.
``(3) Permitted exclusions from gift limitations.--An
institution may exclude from treatment as a gift, payment, or
other financial benefit under the code of conduct required by
this section--
``(A) standard informational material related to a
loan, such as a brochure;
``(B) reimbursement for necessary transportation,
lodging, and related expenses (including food and
refreshments) for travel to a meeting in connection
with serving on an advisory council, if such
reimbursement is for travel for a period not exceeding
2 days and 1 night for each such meeting;
``(C) training or informational material furnished
to an officer, employee, or agent of an institution as
an integral part of a training session or through
participation in an advisory council that is designed
to improve the lender's service to the institution, if
such training or participation contributes to the
professional development of the employee or agent of
the institution; and
``(D) favorable terms, conditions, and borrower
benefits on an educational loan provided to a student,
or a parent of a student, employed by the covered
institution.
``(c) Training and Compliance.--An institution of higher education
shall administer and enforce a code of conduct required by this section
by, at a minimum, requiring all of its officers and employees with
responsibilities with respect to student loans or other financial aid
to obtain training annually in compliance with the code.
``(d) Ban on Education Loan Arrangements.--An institution of higher
education shall be prohibited from entering into an education loan
arrangement. For purposes of this section, an education loan
arrangement is an arrangement between an institution of higher
education (or an agent of the institution) and a lender under which--
``(1) a lender provides or issues student loans to students
attending the institution or to parents of such students;
``(2) the institution recommends the lender or the loan
products of the lender; and
``(3) the lender pays a fee or provides other material
benefits to the institution or officers, employees, or agents
of the institution.
``(e) Ban on Staffing Assistance.--
``(1) Prohibition.--An institution of higher education
shall be prohibited from requesting or accepting from any
lender any assistance with call center staffing or financial
aid office staffing.
``(2) Certain assistance permitted.--Nothing in paragraph
(1) shall be construed to prohibit an institution from
requesting or accepting assistance from a lender related to--
``(A) professional development training for
financial aid administrators; or
``(B) providing educational counseling materials,
financial literacy materials, or debt management
materials to borrowers, provided that such materials
disclose to borrowers the identification of any lender
that assisted in preparing or providing such materials.

``SEC. 155. RULE OF CONSTRUCTION.

``Nothing in this part shall be construed to prohibit an
institution of higher education from negotiating with lenders for
reduced interest rates or fees on student loans for students or
parents.''.

SEC. 3. DISCLOSURES REQUIRED FOR PRIVATE EDUCATIONAL LOANS.

(a) In General.--Section 128 of the Truth in Lending Act (15 U.S.C.
1638) is amended by adding at the end the following new subsection:
``(e) Disclosures Required for Private Educational Loans.--
``(1) In general.--In addition to any other disclosures
required under this chapter with respect to a consumer credit
transaction, a creditor shall provide any consumer with the
following information, and obtain the acknowledgment of the
consumer under paragraph (3), before executing any contract or
agreement between the creditor and the consumer relating to any
extension of credit consisting of or involving a private
educational loan:
``(A) The consumer may qualify for Federal
financial assistance for education through a program
under title IV of the Higher Education Act of 1965 (20
U.S.C. 1070 et seq.).
``(B) In many cases, a Federal student loan may
provide the consumer with more beneficial terms and
conditions , including a lower annual percentage rate
and fewer and lower fees, than private educational
loans.
``(C) The consumer may obtain additional
information concerning such Federal financial
assistance at the website of the Department of
Education.
``(2) Clear and conspicuous disclosure.--The disclosure
required under paragraph (1) shall be placed in a conspicuous
and prominent location on or with any written application,
solicitation, or other document or paper relating to any
extension of credit consisting of or involving a private
educational loan for which such disclosure is required.
``(3) Written acknowledgment of receipt.--In each case in
which a disclosure is provided pursuant to paragraph (1), a
creditor shall obtain a written acknowledgment from the
consumer that the consumer has read and understood the
disclosure.
``(4) Definitions.--For purposes of this subsection, the
terms `Federal student loan' and `private educational loan'
have the same meanings as in section 151 of the Higher
Education Act of 1965.
``(5) Regulations.--In prescribing regulations to implement
this subsection, the Board shall consult with the Secretary of
Education.''.
(b) Effective Date.--The amendments made by subsection (a) shall
apply with respect to any credit consisting of or involving a private
educational loan that is extended pursuant to a contract or agreement
entered into after July 1, 2007.
<all>