Jobs and Growth Tax Relief Reconciliation Act of 2003
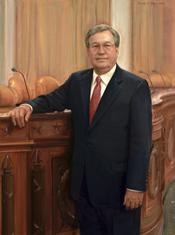 Rep. William M. Thomas (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Became Public Law No: 108-27.
May 28, 2003
View full timeline
Introduced in House
February 27, 2003
Referred to the House Committee on Ways and Means.
February 27, 2003
Ordered to be Reported (Amended) by the Yeas and Nays: 24 - 15.
May 6, 2003
Reported (Amended) by the Committee on Ways and Means. H. Rept. 108-94.
May 8, 2003
Placed on the Union Calendar, Calendar No. 49.
May 8, 2003
Rules Committee Resolution H. Res. 227 Reported to House. Rule provides for consideration of H.R. 2 with 1 hour of general debate. Rule provides for debate in the House equally divided and controlled by the chairman and ranking minority member of the Committee on Ways and Means. The amendment recommended by the Committee on Ways and Means now printed in the bill (H.Rept. 108-94) shall be considered as adopted. The rule waives all points of order against the bill, as amended, and against its consideration. Finally, the rule provides one motion to recommit with or without instructions.
May 8, 2003 • 10:00 PM
Rule H. Res. 227 passed House.
May 9, 2003 • 11:20 AM
Considered under the provisions of rule H. Res. 227. (consideration: CR H3902-3956)
May 9, 2003 • 11:21 AM
Rule provides for consideration of H.R. 2 with 1 hour of general debate. Rule provides for debate in the House equally divided and controlled by the chairman and ranking minority member of the Committee on Ways and Means. The amendment recommended by the Committee on Ways and Means now printed in the bill (H.Rept. 108-94) shall be considered as adopted. The rule waives all points of order against the bill, as amended, and against its consideration. Finally, the rule provides one motion to recommit with or without instructions.
May 9, 2003 • 11:21 AM
DEBATE - The House proceeded with one hour of debate on H.R. 2.
May 9, 2003 • 11:22 AM
The previous question was ordered pursuant to the rule.
May 9, 2003 • 1:18 PM
Mr. Rangel moved to recommit with instructions to Ways and Means.
May 9, 2003 • 1:19 PM
Floor summary: READING OF MOTION - The House proceeded with the reading of the proposed amendment in the nature of a substitute contained in the motion to recommit.
May 9, 2003 • 1:20 PM
Subsequently, unanimous consent was granted to dispense with further reading of the motion to recommit with instructions.
May 9, 2003 • 1:32 PM
Point of order sustained against the motion to recommit with instructions.
May 9, 2003 • 1:33 PM
Mr. Thomas raised a point of order against the motion to recommit with instructions. The provisions of the motion to recommit with instructions are not germane. Sustained by the Chair.
May 9, 2003 • 1:33 PM
Mr. Rangel appealed the ruling of the chair. The question was then put on sustaining the ruling of the chair.
May 9, 2003 • 1:34 PM
Mr. Thomas moved to table the appeal of the ruling of the Chair.
May 9, 2003 • 1:34 PM
On motion to table the appeal of the ruling of the Chair Agreed to by recorded vote: 222 - 202 (Roll No. 180).
May 9, 2003 • 1:50 PM
Mr. Moore moved to recommit with instructions to Ways and Means. (consideration: CR H3940-3956; text: CR H3940-3953)
May 9, 2003 • 1:50 PM
Floor summary: DEBATE - The House proceeded with 10 minutes of debate on the Moore motion to recommit with instructions. The instructions contained in the motion seek to require the bill to be reported back to the House with an amendment that provides that the bill's provisions will not take effect until the Federal budget is in balance.
May 9, 2003 • 1:51 PM
The previous question on the motion to recommit with instructions was ordered without objection.
May 9, 2003 • 1:58 PM
On motion to recommit with instructions Failed by recorded vote: 202 - 218 (Roll no. 181).
May 9, 2003 • 2:14 PM
Passed/agreed to in House: On passage Passed by recorded vote: 222 - 203 (Roll no. 182).(text: CR H3910-3913)
May 9, 2003 • 2:30 PM
On passage Passed by recorded vote: 222 - 203 (Roll no. 182). (text: CR H3910-3913)
May 9, 2003 • 2:30 PM
Motion to reconsider laid on the table Agreed to without objection.
May 9, 2003 • 2:30 PM
The title of the measure was amended. Agreed to without objection.
May 9, 2003 • 2:30 PM
Received in the Senate.
May 12, 2003
Senate struck all after the Enacting Clause and substituted the language of S.1054 amended.
May 15, 2003
Passed Senate in lieu of S.1054 with an amendment by Yea-Nay Vote. 51 - 49. Record Vote Number: 179. (consideration: CR S6474-6475; text as passed Senate: CR 5/20/2003 S6741-6786)
May 15, 2003
Senate insists on its amendment, asks for a conference, appoints conferees Grassley; Hatch; Nickles; Lott; Baucus; Rockefeller; Breaux.
May 15, 2003
Message on Senate action sent to the House.
May 20, 2003
Mr. Thomas asked unanimous consent that the House disagree to the Senate amendment, and agree to a conference. (consideration: CR H4534-4542, H4625-4706)
May 22, 2003 • 10:28 AM
On motion that the House disagree to the Senate amendment, and agree to a conference Agreed to without objection. (consideration: CR H4625-4706)
May 22, 2003 • 10:29 AM
Mr. Stenholm moved that the House instruct conferees. (text: CR H4534)
May 22, 2003 • 10:29 AM
DEBATE - The House proceeded with one hour of debate on the Stenholm motion to instruct conferees. The instructions contained in the motion seek to require the managers on the part of the House to include in the conference report the fiscal relief provided to States by section 371 of the Senate amendment and to the maximum extent possible within the scope of conference, agree to a conference report that will neither increase the Federal budget deficit nor increase the amount of the debt subject to the public debt limit.
May 22, 2003 • 10:29 AM
The previous question was ordered without objection.
May 22, 2003 • 11:42 AM
On motion that the House instruct conferees Agreed to by voice vote.
May 22, 2003 • 11:43 AM
Motion to reconsider laid on the table Agreed to without objection.
May 22, 2003 • 11:43 AM
The Speaker appointed conferees: Thomas, DeLay, and Rangel.
May 22, 2003 • 11:43 AM
Conference papers: Senate report and manager's statement held at the desk in Senate.
May 22, 2003
Conference report filed: Conference report H. Rept. 108-126 filed.(text of conference report: CR H4625-4706)
May 22, 2003 • 8:44 PM
Conference report H. Rept. 108-126 filed. (text of conference report: CR H4625-4706)
May 22, 2003 • 8:44 PM
Conference committee actions: Conferees agreed to file conference report.
May 22, 2003 • 10:45 PM
Conferees agreed to file conference report.
May 22, 2003
Rules Committee Resolution H. Res. 253 Reported to House. Rule provides for consideration of the conference report to H.R. 2.
May 22, 2003 • 10:45 PM
Rule H. Res. 253 passed House.
May 23, 2003 • 12:07 AM
Mr. Thomas brought up conference report H. Rept. 108-126 for consideration under the provisions of H. Res. 253. (consideration: CR H4716-4730)
May 23, 2003 • 12:08 AM
DEBATE - The House proceeded with one hour of debate on the conference report.
May 23, 2003 • 12:08 AM
The previous question was ordered pursuant to the rule.
May 23, 2003 • 1:38 AM
Conference report agreed to in House: On agreeing to the conference report Agreed to by the Yeas and Nays: 231 - 200 (Roll no. 225).
May 23, 2003 • 1:55 AM
Motions to reconsider laid on the table Agreed to without objection.
May 23, 2003 • 1:55 AM
On agreeing to the conference report Agreed to by the Yeas and Nays: 231 - 200 (Roll no. 225).
May 23, 2003 • 1:55 AM
Conference report considered in Senate. (consideration: CR S7071-7089)
May 23, 2003
Conference report agreed to in Senate: Senate agreed to conference report by Yea-Nay Vote. 51 - 50. Record Vote Number: 196.
May 23, 2003
Senate agreed to conference report by Yea-Nay Vote. 51 - 50. Record Vote Number: 196.
May 23, 2003
Message on Senate action sent to the House.
May 23, 2003
Presented to President.
May 23, 2003
Signed by President.
May 28, 2003
Became Public Law No: 108-27.
May 28, 2003
Voting History
6 votes recorded • Roll call available
SENATE
Roll Call AvailableMay 23, 2003 at 9:39 AM
On the Conference Report H.R. 2
Majority required: 1/2 (50%)
Tie-breaker: Vice President cast a Yea vote
50 - 50
HOUSE
Roll Call AvailableMay 23, 2003 at 1:56 AM
On Agreeing to the Conference Report
Majority required: 1/2 (50%)
231 - 200
SENATE
Roll Call AvailableMay 15, 2003 at 11:18 PM
On Passage of the Bill H.R. 2
Majority required: 1/2 (50%)
51 - 49
Show 3 more votes
HOUSE
Roll Call AvailableMay 9, 2003 at 2:31 PM
On Passage
Majority required: 1/2 (50%)
222 - 203
HOUSE
Roll Call AvailableMay 9, 2003 at 2:15 PM
On Motion to Recommit with Instructions
Majority required: 1/2 (50%)
202 - 218
HOUSE
Roll Call AvailableMay 9, 2003 at 1:51 PM
Table Appeal from the Ruling of the Chair
Majority required: 1/2 (50%)
222 - 202
Floor Debate
23 membersWhat members said about H.R. 2 on the floor

 +18
Floor Debate
23 membersWhat members said about H.R. 2 on the floor
Mr. Speaker, I rise tonight with several of my colleagues in support of the Republicans' jobs and growth package, H.R. 2, which we are scheduled to vote on tomorrow; and in fact, this vote is so…
Mr. Speaker, will the gentleman yield? Mr. Speaker, I appreciate the gentleman yielding to me. These issues about creating jobs and dealing with the economy are extremely important to families. I…
Mr. Speaker, by direction of the Committee on Rules, I call up House Resolution 227 and ask for its immediate consideration. Mr. Speaker, for the purpose of debate only, I yield the customary 30…
Mr. Speaker, pursuant to clause 3 (h)(2)(A)(iii) of rule XIII, I submitted the following macroeconomic impact analysis: In accordance with House Rule XIII.3(h)(2), this document, prepared by the…
Mr. Speaker, I yield myself such time as I may consume. (Mr. FROST asked and was given permission to revise and extend his remarks, and include extraneous material.) Mr. Speaker, the rule poses a…
Show 8 more

Mr. Speaker, this is a day that I do not think our country will ever forget. It is a day of infamy. It is a day that the Republican majority has decided that it is their way or the highway. If they…
Mr. Speaker, pursuant to House Resolutions 227, I call up the bill (H.R. 2) to amend the Internal Revenue Code of 1986 to provide additional tax incentives to encourage economic growth, and ask for…
Mr. Speaker, I want to thank my good friend and colleague, the gentleman from South Carolina (Mr. Wilson), for yielding time; and if I may, I would like my colleague to yield just a few moments of…
Mr. Speaker, we have heard it before, we can afford tax cuts, large increases in national defense and still balance the budget. This is not a new idea. We heard it 22 years ago from President Reagan…
Mr. Speaker, just like last year when the Democrats did not have a budget, this year they do not have an economic plan. They have a press release that they rushed to the floor today, had it put into…
Mr. Speaker, I thank my good friend and the distinguished ranking member, the gentleman from Texas (Mr. Frost) for yielding me time. Mr. Speaker, my colleague and good friend, the gentleman from New…

Mr. Speaker, I rise today in strong support of H.R. 2, the Jobs and Growth Act of 2003. Now that we have won the battle for Baghdad and liberated the people of Iraq from despotism, it is time to win…

Mr. Speaker, I thank the gentleman for yielding me this time. We just heard a representation of what their bill is going to do. We ought to judge the credibility of those representations. The…
Show 11 more
Mr. Speaker, I rise in support of the Jobs and Growth Tax Reconciliation Act. This bill is going to provide much- needed tax relief for individuals and businesses to help create jobs today, while…
Mr. Speaker, I rise in opposition to this outrageous rule and its outrageous tax cut. We are not even given time to debate this bill. We can have democracy in Iraq, but not here on the House floor.…

Mr. Speaker, I oppose this closed rule and the underlying bill. As everyone here knows, our economy is in very bad shape. Unemployment is at 6 percent and millions of Americans are unable to find…

Mr. Speaker, I rise in strong support of this rule. When we won the majority back in 1994, we decided that we were going to guarantee that the minority had something that we on numerous occasions…
Mr. Speaker, I rise in very strong support of this legislation that deserves bipartisan support. The jobs and growth package that is before us today is projected by independent economists to generate…

Mr. Speaker, I rise today to support H.R. 2, the President's Jobs and Growth Tax Act of 2003. There is no need for further debate on this bill: America needs economic stimulus, and it needs it now.…

Mr. Speaker, I rise in strong opposition to the Thomas tax plan. The reckless tax cut contained in the Thomas plan is unfair and is irresponsible. Mr. Speaker, I rise in strong opposition to the…
Mr. Speaker, I rise in support of this legislation to strengthen our economy, to create jobs and to provide tax relief to millions of America's workers and their families. This is a sensible,…
Mr. Speaker, I thank the gentleman, the chairman of the full committee, for his work on this legislation and would urge my colleagues to adopt it. Let me start with a point of agreement with the…
Mr. Speaker, I thank the chairman for yielding me the time, and I thank my colleague from Ohio who just spoke. One thing that excites me about this bill is it will create 1.2 million new jobs by the…
Mr. Speaker, what are Republicans afraid of? Are they afraid of the anger of millions of unemployed when they found out Republicans are passing yet another massive tax cut while unemployment benefits…
Bill Text
7 versions available
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 2 Enrolled Bill (ENR)]

H.R.2

One Hundred Eighth Congress

of the

United States of America

AT THE FIRST SESSION

Begun and held at the City of Washington on Tuesday,
the seventh day of January, two thousand and three

An Act

To provide for reconciliation pursuant to section 201 of the concurrent
resolution on the budget for fiscal year 2004.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; REFERENCES; TABLE OF CONTENTS.

(a) Short Title.--This Act may be cited as the ``Jobs and Growth
Tax Relief Reconciliation Act of 2003''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this Act an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.
(c) Table of Contents.--The table of contents of this Act is as
follows:
Sec. 1. Short title; references; table of contents.

TITLE I--ACCELERATION OF CERTAIN PREVIOUSLY ENACTED TAX REDUCTIONS

Sec. 101. Acceleration of increase in child tax credit.
Sec. 102. Acceleration of 15-percent individual income tax rate bracket
expansion for married taxpayers filing joint returns.
Sec. 103. Acceleration of increase in standard deduction for married
taxpayers filing joint returns.
Sec. 104. Acceleration of 10-percent individual income tax rate bracket
expansion.
Sec. 105. Acceleration of reduction in individual income tax rates.
Sec. 106. Minimum tax relief to individuals.
Sec. 107. Application of EGTRRA sunset to this title.

TITLE II--GROWTH INCENTIVES FOR BUSINESS

Sec. 201. Increase and extension of bonus depreciation.
Sec. 202. Increased expensing for small business.

TITLE III--REDUCTION IN TAXES ON DIVIDENDS AND CAPITAL GAINS

Sec. 301. Reduction in capital gains rates for individuals; repeal of 5-
year holding period requirement.
Sec. 302. Dividends of individuals taxed at capital gain rates.
Sec. 303. Sunset of title.

TITLE IV--TEMPORARY STATE FISCAL RELIEF

Sec. 401. Temporary State fiscal relief.

TITLE V--CORPORATE ESTIMATED TAX PAYMENTS FOR 2003

Sec. 501. Time for payment of corporate estimated taxes.

TITLE I--ACCELERATION OF CERTAIN PREVIOUSLY ENACTED TAX REDUCTIONS

SEC. 101. ACCELERATION OF INCREASE IN CHILD TAX CREDIT.

(a) In General.--The item relating to calendar years 2001 through
2004 in the table contained in paragraph (2) of section 24(a) (relating
to per child amount) is amended to read as follows:

``2003 or 2004............................................

$1,000''.

(b) Advance Payment of Portion of Increased Credit in 2003.--
(1) In general.--Subchapter B of chapter 65 (relating to
abatements, credits, and refunds) is amended by inserting after
section 6428 the following new section:

``SEC. 6429. ADVANCE PAYMENT OF PORTION OF INCREASED CHILD CREDIT FOR
2003.

``(a) In General.--Each taxpayer who was allowed a credit under
section 24 on the return for the taxpayer's first taxable year
beginning in 2002 shall be treated as having made a payment against the
tax imposed by chapter 1 for such taxable year in an amount equal to
the child tax credit refund amount (if any) for such taxable year.
``(b) Child Tax Credit Refund Amount.--For purposes of this
section, the child tax credit refund amount is the amount by which the
aggregate credits allowed under part IV of subchapter A of chapter 1
for such first taxable year would have been increased if--
``(1) the per child amount under section 24(a)(2) for such year
were $1,000,
``(2) only qualifying children (as defined in section 24(c)) of
the taxpayer for such year who had not attained age 17 as of
December 31, 2003, were taken into account, and
``(3) section 24(d)(1)(B)(ii) did not apply.
``(c) Timing of Payments.--In the case of any overpayment
attributable to this section, the Secretary shall, subject to the
provisions of this title, refund or credit such overpayment as rapidly
as possible and, to the extent practicable, before October 1, 2003. No
refund or credit shall be made or allowed under this section after
December 31, 2003.
``(d) Coordination With Child Tax Credit.--
``(1) In general.--The amount of credit which would (but for
this subsection and section 26) be allowed under section 24 for the
taxpayer's first taxable year beginning in 2003 shall be reduced
(but not below zero) by the payments made to the taxpayer under
this section. Any failure to so reduce the credit shall be treated
as arising out of a mathematical or clerical error and assessed
according to section 6213(b)(1).
``(2) Joint returns.--In the case of a payment under this
section with respect to a joint return, half of such payment shall
be treated as having been made to each individual filing such
return.
``(e) No Interest.--No interest shall be allowed on any overpayment
attributable to this section.''.
(2) Clerical amendment.--The table of sections for subchapter B
of chapter 65 is amended by adding at the end the following new
item:

``Sec. 6429. Advance payment of portion of increased child
credit for 2003.''.

(c) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
beginning after December 31, 2002.
(2) Subsection (b).--The amendments made by subsection (b)
shall take effect on the date of the enactment of this Act.

SEC. 102. ACCELERATION OF 15-PERCENT INDIVIDUAL INCOME TAX RATE BRACKET
EXPANSION FOR MARRIED TAXPAYERS FILING JOINT RETURNS.

(a) In General.--The table contained in subparagraph (B) of section
1(f)(8) (relating to applicable percentage) is amended by inserting
before the item relating to 2005 the following new item:

``2003 and 2004...................................
200''.

(b) Conforming Amendments.--
(1) Section 1(f)(8)(A) is amended by striking ``2004'' and
inserting ``2002''.
(2) Section 302(c) of the Economic Growth and Tax Relief
Reconciliation Act of 2001 is amended by striking ``2004'' and
inserting ``2002''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 103. ACCELERATION OF INCREASE IN STANDARD DEDUCTION FOR MARRIED
TAXPAYERS FILING JOINT RETURNS.

(a) In General.--The table contained in paragraph (7) of section
63(c) (relating to applicable percentage) is amended by inserting
before the item relating to 2005 the following new item:

``2003 and 2004...................................
200''.

(b) Conforming Amendment.--Section 301(d) of the Economic Growth
and Tax Relief Reconciliation Act of 2001 is amended by striking
``2004'' and inserting ``2002''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 104. ACCELERATION OF 10-PERCENT INDIVIDUAL INCOME TAX RATE BRACKET
EXPANSION.

(a) In General.--Clause (i) of section 1(i)(1)(B) (relating to the
initial bracket amount) is amended by striking ``($12,000 in the case
of taxable years beginning before January 1, 2008)'' and inserting
``($12,000 in the case of taxable years beginning after December 31,
2004, and before January 1, 2008)''.
(b) Inflation Adjustment.--Subparagraph (C) of section 1(i)(1) is
amended to read as follows:
``(C) Inflation adjustment.--In prescribing the tables
under subsection (f) which apply with respect to taxable years
beginning in calendar years after 2000--
``(i) except as provided in clause (ii), the Secretary
shall make no adjustment to the initial bracket amounts for
any taxable year beginning before January 1, 2009,
``(ii) there shall be an adjustment under subsection
(f) of such amounts which shall apply only to taxable years
beginning in 2004, and such adjustment shall be determined
under subsection (f)(3) by substituting `2002' for `1992'
in subparagraph (B) thereof,
``(iii) the cost-of-living adjustment used in making
adjustments to the initial bracket amounts for any taxable
year beginning after December 31, 2008, shall be determined
under subsection (f)(3) by substituting `2007' for `1992'
in subparagraph (B) thereof, and
``(iv) the adjustments under clauses (ii) and (iii)
shall not apply to the amount referred to in subparagraph
(B)(iii).
If any amount after adjustment under the preceding sentence is
not a multiple of $50, such amount shall be rounded to the next
lowest multiple of $50.''.
(c) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.
(2) Tables for 2003.--The Secretary of the Treasury shall
modify each table which has been prescribed under section 1(f) of
the Internal Revenue Code of 1986 for taxable years beginning in
2003 and which relates to the amendment made by subsection (a) to
reflect such amendment.

SEC. 105. ACCELERATION OF REDUCTION IN INDIVIDUAL INCOME TAX RATES.

(a) In General.--The table contained in paragraph (2) of section
1(i) (relating to reductions in rates after June 30, 2001) is amended
to read as follows:

--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
The corresponding percentages shall be substituted for  the following percentages:
``In the case of taxable years  ---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
beginning during calendar year:     28%      31%      36%                                                                                                                                                       39.6%
--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
2001.............................   27.5%    30.5%    35.5%                                                                                                                                                      39.1%
2002.............................   27.0%    30.0%    35.0%                                                                                                                                                      38.6%
2003 and thereafter..............   25.0%    28.0%    33.0%                                                                                                                                                     35.0%''.
--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------

(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2002.

SEC. 106. MINIMUM TAX RELIEF TO INDIVIDUALS.

(a) In General.--
(1) Subparagraph (A) of section 55(d)(1) is amended by striking
``$49,000 in the case of taxable years beginning in 2001, 2002,
2003, and 2004'' and inserting ``$58,000 in the case of taxable
years beginning in 2003 and 2004''.
(2) Subparagraph (B) of section 55(d)(1) is amended by striking
``$35,750 in the case of taxable years beginning in 2001, 2002,
2003, and 2004'' and inserting ``$40,250 in the case of taxable
years beginning in 2003 and 2004''.
(b) Effective Date.--The amendments made by subsection (a) shall
apply to taxable years beginning after December 31, 2002.

SEC. 107. APPLICATION OF EGTRRA SUNSET TO THIS TITLE.

Each amendment made by this title shall be subject to title IX of
the Economic Growth and Tax Relief Reconciliation Act of 2001 to the
same extent and in the same manner as the provision of such Act to
which such amendment relates.

TITLE II--GROWTH INCENTIVES FOR BUSINESS

SEC. 201. INCREASE AND EXTENSION OF BONUS DEPRECIATION.

(a) In General.--Section 168(k) (relating to special allowance for
certain property acquired after September 10, 2001, and before
September 11, 2004) is amended by adding at the end the following new
paragraph:
``(4) 50-percent bonus depreciation for certain property.--
``(A) In general.--In the case of 50-percent bonus
depreciation property--
``(i) paragraph (1)(A) shall be applied by substituting
`50 percent' for `30 percent', and
``(ii) except as provided in paragraph (2)(C), such
property shall be treated as qualified property for
purposes of this subsection.
``(B) 50-percent bonus depreciation property.--For purposes
of this subsection, the term `50-percent bonus depreciation
property' means property described in paragraph (2)(A)(i)--
``(i) the original use of which commences with the
taxpayer after May 5, 2003,
``(ii) which is acquired by the taxpayer after May 5,
2003, and before January 1, 2005, but only if no written
binding contract for the acquisition was in effect before
May 6, 2003, and
``(iii) which is placed in service by the taxpayer
before January 1, 2005, or, in the case of property
described in paragraph (2)(B) (as modified by subparagraph
(C) of this paragraph), before January 1, 2006.
``(C) Special rules.--Rules similar to the rules of
subparagraphs (B) and (D) of paragraph (2) shall apply for
purposes of this paragraph; except that references to September
10, 2001, shall be treated as references to May 5, 2003.
``(D) Automobiles.--Paragraph (2)(E) shall be applied by
substituting `$7,650' for `$4,600' in the case of 50-percent
bonus depreciation property.
``(E) Election of 30-percent bonus.--If a taxpayer makes an
election under this subparagraph with respect to any class of
property for any taxable year, subparagraph (A)(i) shall not
apply to all property in such class placed in service during
such taxable year.''.
(b) Extension of Certain Dates for 30-Percent Bonus Depreciation
Property.--
(1) Portion of basis taken into account.--
(A) Subparagraphs (B)(ii) and (D)(i) of section 168(k)(2)
are each amended by striking ``September 11, 2004'' each place
it appears in the text and inserting ``January 1, 2005''.
(B) Clause (ii) of section 168(k)(2)(B) is amended by
striking ``pre-september 11, 2004'' in the heading and
inserting ``pre-january 1, 2005''.
(2) Acquisition date.--Clause (iii) of section 168(k)(2)(A) is
amended by striking ``September 11, 2004'' each place it appears
and inserting ``January 1, 2005''.
(3) Election.--Clause (iii) of section 168(k)(2)(C) is amended
by adding at the end the following: ``The preceding sentence shall
be applied separately with respect to property treated as qualified
property by paragraph (4) and other qualified property.''.
(c) Conforming Amendments.--
(1) The subsection heading for section 168(k) is amended by
striking ``September 11, 2004'' and inserting ``January 1, 2005''.
(2) The heading for clause (i) of section 1400L(b)(2)(C) is
amended by striking ``30-percent additional allowance property''
and inserting ``Bonus depreciation property under section 168(k)''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years ending after May 5, 2003.

SEC. 202. INCREASED EXPENSING FOR SMALL BUSINESS.

(a) In General.--Paragraph (1) of section 179(b) (relating to
dollar limitation) is amended to read as follows:
``(1) Dollar limitation.--The aggregate cost which may be taken
into account under subsection (a) for any taxable year shall not
exceed $25,000 ($100,000 in the case of taxable years beginning
after 2002 and before 2006).''.
(b) Increase in Qualifying Investment at Which Phaseout Begins.--
Paragraph (2) of section 179(b) (relating to reduction in limitation)
is amended by inserting ``($400,000 in the case of taxable years
beginning after 2002 and before 2006)'' after ``$200,000''.
(c) Off-the-Shelf Computer Software.--Paragraph (1) of section
179(d) (defining section 179 property) is amended to read as follows:
``(1) Section 179 property.--For purposes of this section, the
term `section 179 property' means property--
``(A) which is--
``(i) tangible property (to which section 168 applies),
or
``(ii) computer software (as defined in section
197(e)(3)(B)) which is described in section
197(e)(3)(A)(i), to which section 167 applies, and which is
placed in service in a taxable year beginning after 2002
and before 2006,
``(B) which is section 1245 property (as defined in section
1245(a)(3)), and
``(C) which is acquired by purchase for use in the active
conduct of a trade or business.
Such term shall not include any property described in section 50(b)
and shall not include air conditioning or heating units.''.
(d) Adjustment of Dollar Limit and Phaseout Threshold for
Inflation.--Subsection (b) of section 179 (relating to limitations) is
amended by adding at the end the following new paragraph:
``(5) Inflation adjustments.--
``(A) In general.--In the case of any taxable year
beginning in a calendar year after 2003 and before 2006, the
$100,000 and $400,000 amounts in paragraphs (1) and (2) shall
each be increased by an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment determined under
section 1(f)(3) for the calendar year in which the taxable
year begins, by substituting `calendar year 2002' for
`calendar year 1992' in subparagraph (B) thereof.
``(B) Rounding.--
``(i) Dollar limitation.--If the amount in paragraph
(1) as increased under subparagraph (A) is not a multiple
of $1,000, such amount shall be rounded to the nearest
multiple of $1,000.
``(ii) Phaseout amount.--If the amount in paragraph (2)
as increased under subparagraph (A) is not a multiple of
$10,000, such amount shall be rounded to the nearest
multiple of $10,000.''.
(e) Revocation of Election.--Paragraph (2) of section 179(c)
(relating to election irrevocable) is amended by adding at the end the
following new sentence: ``Any such election or specification with
respect to any taxable year beginning after 2002 and before 2006 may be
revoked by the taxpayer with respect to any property, and such
revocation, once made, shall be irrevocable.''.
(f) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

TITLE III--REDUCTION IN TAXES ON DIVIDENDS AND CAPITAL GAINS

SEC. 301. REDUCTION IN CAPITAL GAINS RATES FOR INDIVIDUALS; REPEAL OF
5-YEAR HOLDING PERIOD REQUIREMENT.

(a) In General.--
(1) Sections 1(h)(1)(B) and 55(b)(3)(B) are each amended by
striking ``10 percent'' and inserting ``5 percent (0 percent in the
case of taxable years beginning after 2007)''.
(2) The following sections are each amended by striking ``20
percent'' and inserting ``15 percent'':
(A) Section 1(h)(1)(C).
(B) Section 55(b)(3)(C).
(C) Section 1445(e)(1).
(D) The second sentence of section 7518(g)(6)(A).
(E) The second sentence of section 607(h)(6)(A) of the
Merchant Marine Act, 1936.
(b) Conforming Amendments.--
(1) Section 1(h) is amended--
(A) by striking paragraphs (2) and (9),
(B) by redesignating paragraphs (3) through (8) as
paragraphs (2) through (7), respectively, and
(C) by redesignating paragraphs (10), (11), and (12) as
paragraphs (8), (9), and (10), respectively.
(2) Paragraph (3) of section 55(b) is amended by striking ``In
the case of taxable years beginning after December 31, 2000, rules
similar to the rules of section 1(h)(2) shall apply for purposes of
subparagraphs (B) and (C).''.
(3) Paragraph (7) of section 57(a) is amended--
(A) by striking ``42 percent'' the first place it appears
and inserting ``7 percent'', and
(B) by striking the last sentence.
(c) Transitional Rules for Taxable Years Which Include May 6,
2003.--For purposes of applying section 1(h) of the Internal Revenue
Code of 1986 in the case of a taxable year which includes May 6, 2003--
(1) The amount of tax determined under subparagraph (B) of
section 1(h)(1) of such Code shall be the sum of--
(A) 5 percent of the lesser of--
(i) the net capital gain determined by taking into
account only gain or loss properly taken into account for
the portion of the taxable year on or after May 6, 2003
(determined without regard to collectibles gain or loss,
gain described in section 1(h)(6)(A)(i) of such Code, and
section 1202 gain), or
(ii) the amount on which a tax is determined under such
subparagraph (without regard to this subsection),
(B) 8 percent of the lesser of--
(i) the qualified 5-year gain (as defined in section
1(h)(9) of the Internal Revenue Code of 1986, as in effect
on the day before the date of the enactment of this Act)
properly taken into account for the portion of the taxable
year before May 6, 2003, or
(ii) the excess (if any) of--

(I) the amount on which a tax is determined under
such subparagraph (without regard to this subsection),
over
(II) the amount on which a tax is determined under
subparagraph (A), plus

(C) 10 percent of the excess (if any) of--
(i) the amount on which a tax is determined under such
subparagraph (without regard to this subsection), over
(ii) the sum of the amounts on which a tax is
determined under subparagraphs (A) and (B).
(2) The amount of tax determined under subparagraph (C) of
section (1)(h)(1) of such Code shall be the sum of--
(A) 15 percent of the lesser of--
(i) the excess (if any) of the amount of net capital
gain determined under subparagraph (A)(i) of paragraph (1)
of this subsection over the amount on which a tax is
determined under subparagraph (A) of paragraph (1) of this
subsection, or
(ii) the amount on which a tax is determined under such
subparagraph (C) (without regard to this subsection), plus
(B) 20 percent of the excess (if any) of--
(i) the amount on which a tax is determined under such
subparagraph (C) (without regard to this subsection), over
(ii) the amount on which a tax is determined under
subparagraph (A) of this paragraph.
(3) For purposes of applying section 55(b)(3) of such Code,
rules similar to the rules of paragraphs (1) and (2) of this
subsection shall apply.
(4) In applying this subsection with respect to any pass-thru
entity, the determination of when gains and losses are properly
taken into account shall be made at the entity level.
(5) For purposes of applying section 1(h)(11) of such Code, as
added by section 302 of this Act, to this subsection, dividends
which are qualified dividend income shall be treated as gain
properly taken into account for the portion of the taxable year on
or after May 6, 2003.
(6) Terms used in this subsection which are also used in
section 1(h) of such Code shall have the respective meanings that
such terms have in such section.
(d) Effective Dates.--
(1) In general.--Except as otherwise provided by this
subsection, the amendments made by this section shall apply to
taxable years ending on or after May 6, 2003.
(2) Withholding.--The amendment made by subsection (a)(2)(C)
shall apply to amounts paid after the date of the enactment of this
Act.
(3) Small business stock.--The amendments made by subsection
(b)(3) shall apply to dispositions on or after May 6, 2003.

SEC. 302. DIVIDENDS OF INDIVIDUALS TAXED AT CAPITAL GAIN RATES.

(a) In General.--Section 1(h) (relating to maximum capital gains
rate), as amended by section 301, is amended by adding at the end the
following new paragraph:
``(11) Dividends taxed as net capital gain.--
``(A) In general.--For purposes of this subsection, the
term `net capital gain' means net capital gain (determined
without regard to this paragraph) increased by qualified
dividend income.
``(B) Qualified dividend income.--For purposes of this
paragraph--
``(i) In general.--The term `qualified dividend income'
means dividends received during the taxable year from--

``(I) domestic corporations, and
``(II) qualified foreign corporations.

``(ii) Certain dividends excluded.--Such term shall not
include--

``(I) any dividend from a corporation which for the
taxable year of the corporation in which the
distribution is made, or the preceding taxable year, is
a corporation exempt from tax under section 501 or 521,
``(II) any amount allowed as a deduction under
section 591 (relating to deduction for dividends paid
by mutual savings banks, etc.), and
``(III) any dividend described in section 404(k).

``(iii) Coordination with section 246(c).--Such term
shall not include any dividend on any share of stock--

``(I) with respect to which the holding period
requirements of section 246(c) are not met (determined
by substituting in section 246(c)(1) `60 days' for `45
days' each place it appears and by substituting `120-
day period' for `90-day period'), or
``(II) to the extent that the taxpayer is under an
obligation (whether pursuant to a short sale or
otherwise) to make related payments with respect to
positions in substantially similar or related property.

``(C) Qualified foreign corporations.--
``(i) In general.--Except as otherwise provided in this
paragraph, the term `qualified foreign corporation' means
any foreign corporation if--

``(I) such corporation is incorporated in a
possession of the United States, or
``(II) such corporation is eligible for benefits of
a comprehensive income tax treaty with the United
States which the Secretary determines is satisfactory
for purposes of this paragraph and which includes an
exchange of information program.

``(ii) Dividends on stock readily tradable on united
states securities market.--A foreign corporation not
otherwise treated as a qualified foreign corporation under
clause (i) shall be so treated with respect to any dividend
paid by such corporation if the stock with respect to which
such dividend is paid is readily tradable on an established
securities market in the United States.
``(iii) Exclusion of dividends of certain foreign
corporations.--Such term shall not include any foreign
corporation which for the taxable year of the corporation
in which the dividend was paid, or the preceding taxable
year, is a foreign personal holding company (as defined in
section 552), a foreign investment company (as defined in
section 1246(b)), or a passive foreign investment company
(as defined in section 1297).
``(iv) Coordination with foreign tax credit
limitation.--Rules similar to the rules of section
904(b)(2)(B) shall apply with respect to the dividend rate
differential under this paragraph.
``(D) Special rules.--
``(i) Amounts taken into account as investment
income.--Qualified dividend income shall not include any
amount which the taxpayer takes into account as investment
income under section 163(d)(4)(B).
``(ii) Extraordinary dividends.--If an individual
receives, with respect to any share of stock, qualified
dividend income from 1 or more dividends which are
extraordinary dividends (within the meaning of section
1059(c)), any loss on the sale or exchange of such share
shall, to the extent of such dividends, be treated as long-
term capital loss.
``(iii) Treatment of dividends from regulated
investment companies and real estate investment trusts.--A
dividend received from a regulated investment company or a
real estate investment trust shall be subject to the
limitations prescribed in sections 854 and 857.''.
(b) Exclusion of Dividends From Investment Income.--Subparagraph
(B) of section 163(d)(4) (defining net investment income) is amended by
adding at the end the following flush sentence:
``Such term shall include qualified dividend income (as defined
in section 1(h)(11)(B)) only to the extent the taxpayer elects
to treat such income as investment income for purposes of this
subsection.''.
(c) Treatment of Dividends From Regulated Investment Companies.--
(1) Subsection (a) of section 854 (relating to dividends
received from regulated investment companies) is amended by
inserting ``section 1(h)(11) (relating to maximum rate of tax on
dividends) and'' after ``For purposes of''.
(2) Paragraph (1) of section 854(b) (relating to other
dividends) is amended by redesignating subparagraph (B) as
subparagraph (C) and by inserting after subparagraph (A) the
following new subparagraph:
``(B) Maximum rate under section 1(h).--
``(i) In general.--If the aggregate dividends received
by a regulated investment company during any taxable year
are less than 95 percent of its gross income, then, in
computing the maximum rate under section 1(h)(11), rules
similar to the rules of subparagraph (A) shall apply.
``(ii) Gross income.--For purposes of clause (i), in
the case of 1 or more sales or other dispositions of stock
or securities, the term `gross income' includes only the
excess of--

``(I) the net short-term capital gain from such
sales or dispositions, over
``(II) the net long-term capital loss from such
sales or dispositions.

``(iii) Dividends from real estate investment trusts.--
For purposes of clause (i)--

``(I) paragraph (3)(B)(ii) shall not apply, and
``(II) in the case of a distribution from a trust
described in such paragraph, the amount of such
distribution which is a dividend shall be subject to
the limitations under section 857(c).

``(iv) Dividends from qualified foreign corporations.--
For purposes of clause (i), dividends received from
qualified foreign corporations (as defined in section
1(h)(11)) shall also be taken into account in computing
aggregate dividends received.''.
(3) Subparagraph (C) of section 854(b)(1), as redesignated by
paragraph (2), is amended by striking ``subparagraph (A)'' and
inserting ``subparagraph (A) or (B)''.
(4) Paragraph (2) of section 854(b) is amended by inserting
``the maximum rate under section 1(h)(11) and'' after ``for
purposes of''.
(5) Subsection (b) of section 854 is amended by adding at the
end the following new paragraph:
``(5) Coordination with section 1(h)(11).--For purposes of
paragraph (1)(B), an amount shall be treated as a dividend only if
the amount is qualified dividend income (within the meaning of
section 1(h)(11)(B)).''.
(d) Treatment of Dividends Received From Real Estate Investment
Trusts.--Section 857(c) (relating to restrictions applicable to
dividends received from real estate investment trusts) is amended to
read as follows:
``(c) Restrictions Applicable to Dividends Received From Real
Estate Investment Trusts.--
``(1) Section 243.--For purposes of section 243 (relating to
deductions for dividends received by corporations), a dividend
received from a real estate investment trust which meets the
requirements of this part shall not be considered a dividend.
``(2) Section 1(h)(11).--For purposes of section 1(h)(11)
(relating to maximum rate of tax on dividends)--
``(A) rules similar to the rules of subparagraphs (B) and
(C) of section 854(b)(1) shall apply to dividends received from
a real estate investment trust which meets the requirements of
this part, and
``(B) for purposes of such rules, such a trust shall be
treated as receiving qualified dividend income during any
taxable year in an amount equal to the sum of--
``(i) the excess of real estate investment trust
taxable income computed under section 857(b)(2) for the
preceding taxable year over the tax payable by the trust
under section 857(b)(1) for such preceding taxable year,
and
``(ii) the excess of the income subject to tax by
reason of the application of the regulations under section
337(d) for the preceding taxable year over the tax payable
by the trust on such income for such preceding taxable
year.''.
(e) Conforming Amendments.--
(1) Paragraph (3) of section 1(h), as redesignated by section
301, is amended to read as follows:
``(3) Adjusted net capital gain.--For purposes of this
subsection, the term `adjusted net capital gain' means the sum of--
``(A) net capital gain (determined without regard to
paragraph (11)) reduced (but not below zero) by the sum of--
``(i) unrecaptured section 1250 gain, and
``(ii) 28-percent rate gain, plus
``(B) qualified dividend income (as defined in paragraph
(11)).''.
(2) Subsection (f) of section 301 is amended adding at the end
the following new paragraph:
``(4) For taxation of dividends received by individuals at
capital gain rates, see section 1(h)(11).''.
(3) Paragraph (1) of section 306(a) is amended by adding at the
end the following new subparagraph:
``(D) Treatment as dividend.--For purposes of section
1(h)(11) and such other provisions as the Secretary may
specify, any amount treated as ordinary income under this
paragraph shall be treated as a dividend received from the
corporation.''.
(4)(A) Subpart C of part II of subchapter C of chapter 1
(relating to collapsible corporations) is repealed.
(B)(i) Section 338(h) is amended by striking paragraph (14).
(ii) Sections 467(c)(5)(C), 1255(b)(2), and 1257(d) are each
amended by striking ``, 341(e)(12),''.
(iii) The table of subparts for part II of subchapter C of
chapter 1 is amended by striking the item related to subpart C.
(5) Section 531 is amended by striking ``equal to'' and all
that follows and inserting ``equal to 15 percent of the accumulated
taxable income.''.
(6) Section 541 is amended by striking ``equal to'' and all
that follows and inserting ``equal to 15 percent of the
undistributed personal holding company income.''.
(7) Section 584(c) is amended by adding at the end the
following new flush sentence:
``The proportionate share of each participant in the amount of
dividends received by the common trust fund and to which section
1(h)(11) applies shall be considered for purposes of such paragraph as
having been received by such participant.''.
(8) Paragraph (5) of section 702(a) is amended to read as
follows:
``(5) dividends with respect to which section 1(h)(11) or part
VIII of subchapter B applies,''.
(f) Effective Date.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
beginning after December 31, 2002.
(2) Regulated investment companies and real estate investment
trusts.--In the case of a regulated investment company or a real
estate investment trust, the amendments made by this section shall
apply to taxable years ending after December 31, 2002; except that
dividends received by such a company or trust on or before such
date shall not be treated as qualified dividend income (as defined
in section 1(h)(11)(B) of the Internal Revenue Code of 1986, as
added by this Act).

SEC. 303. SUNSET OF TITLE.

All provisions of, and amendments made by, this title shall not
apply to taxable years beginning after December 31, 2008, and the
Internal Revenue Code of 1986 shall be applied and administered to such
years as if such provisions and amendments had never been enacted.

TITLE IV--TEMPORARY STATE FISCAL RELIEF

SEC. 401. TEMPORARY STATE FISCAL RELIEF.

(a) $10,000,000,000 for a Temporary Increase of the Medicaid
FMAP.--
(1) Permitting maintenance of fiscal year 2002 fmap for last 2
calendar quarters of fiscal year 2003.--Subject to paragraph (5),
if the FMAP determined without regard to this subsection for a
State for fiscal year 2003 is less than the FMAP as so determined
for fiscal year 2002, the FMAP for the State for fiscal year 2002
shall be substituted for the State's FMAP for the third and fourth
calendar quarters of fiscal year 2003, before the application of
this subsection.
(2) Permitting maintenance of fiscal year 2003 fmap for first 3
quarters of fiscal year 2004.--Subject to paragraph (5), if the
FMAP determined without regard to this subsection for a State for
fiscal year 2004 is less than the FMAP as so determined for fiscal
year 2003, the FMAP for the State for fiscal year 2003 shall be
substituted for the State's FMAP for the first, second, and third
calendar quarters of fiscal year 2004, before the application of
this subsection.
(3) General 2.95 percentage points increase for last 2 calendar
quarters of fiscal year 2003 and first 3 calendar quarters of
fiscal year 2004.--Subject to paragraphs (5), (6), and (7), for
each State for the third and fourth calendar quarters of fiscal
year 2003 and for the first, second, and third calendar quarters of
fiscal year 2004, the FMAP (taking into account the application of
paragraphs (1) and (2)) shall be increased by 2.95 percentage
points.
(4) Increase in cap on medicaid payments to territories.--
Subject to paragraphs (6) and (7), with respect to the third and
fourth calendar quarters of fiscal year 2003 and the first, second,
and third calendar quarters of fiscal year 2004, the amounts
otherwise determined for Puerto Rico, the Virgin Islands, Guam, the
Northern Mariana Islands, and American Samoa under subsections (f)
and (g) of section 1108 of the Social Security Act (42 U.S.C. 1308)
shall each be increased by an amount equal to 5.90 percent of such
amounts.
(5) Scope of application.--The increases in the FMAP for a
State under this subsection shall apply only for purposes of title
XIX of the Social Security Act and shall not apply with respect
to--
(A) disproportionate share hospital payments described in
section 1923 of such Act (42 U.S.C. 1396r-4);
(B) payments under title IV or XXI of such Act (42 U.S.C.
601 et seq. and 1397aa et seq.); or
(C) any payments under XIX of such Act that are based on
the enhanced FMAP described in section 2105(b) of such Act (42
U.S.C. 1397ee(b)).
(6) State eligibility.--
(A) In general.--Subject to subparagraph (B), a State is
eligible for an increase in its FMAP under paragraph (3) or an
increase in a cap amount under paragraph (4) only if the
eligibility under its State plan under title XIX of the Social
Security Act (including any waiver under such title or under
section 1115 of such Act (42 U.S.C. 1315)) is no more
restrictive than the eligibility under such plan (or waiver) as
in effect on September 2, 2003.
(B) State reinstatement of eligibility permitted.--A State
that has restricted eligibility under its State plan under
title XIX of the Social Security Act (including any waiver
under such title or under section 1115 of such Act (42 U.S.C.
1315)) after September 2, 2003, is eligible for an increase in
its FMAP under paragraph (3) or an increase in a cap amount
under paragraph (4) in the first calendar quarter (and
subsequent calendar quarters) in which the State has reinstated
eligibility that is no more restrictive than the eligibility
under such plan (or waiver) as in effect on September 2, 2003.
(C) Rule of construction.--Nothing in subparagraph (A) or
(B) shall be construed as affecting a State's flexibility with
respect to benefits offered under the State medicaid program
under title XIX of the Social Security Act (42 U.S.C. 1396 et
seq.) (including any waiver under such title or under section
1115 of such Act (42 U.S.C. 1315)).
(7) Requirement for certain states.--In the case of a State
that requires political subdivisions within the State to contribute
toward the non-Federal share of expenditures under the State
medicaid plan required under section 1902(a)(2) of the Social
Security Act (42 U.S.C. 1396a(a)(2)), the State shall not require
that such political subdivisions pay a greater percentage of the
non-Federal share of such expenditures for the third and fourth
calendar quarters of fiscal year 2003 and the first, second and
third calendar quarters of fiscal year 2004, than the percentage
that was required by the State under such plan on April 1, 2003,
prior to application of this subsection.
(8) Definitions.--In this subsection:
(A) FMAP.--The term ``FMAP'' means the Federal medical
assistance percentage, as defined in section 1905(b) of the
Social Security Act (42 U.S.C. 1396d(b)).
(B) State.--The term ``State'' has the meaning given such
term for purposes of title XIX of the Social Security Act (42
U.S.C. 1396 et seq.).
(9) Repeal.--Effective as of October 1, 2004, this subsection
is repealed.
(b) $10,000,000,000 to Assist States in Providing Government
Services.--The Social Security Act (42 U.S.C. 301 et seq.) is amended
by inserting after title V the following:

``TITLE VI--TEMPORARY STATE FISCAL RELIEF

``SEC. 601. TEMPORARY STATE FISCAL RELIEF.

``(a) Appropriation.--There is authorized to be appropriated and is
appropriated for making payments to States under this section,
$5,000,000,000 for each of fiscal years 2003 and 2004.
``(b) Payments.--
``(1) Fiscal year 2003.--From the amount appropriated under
subsection (a) for fiscal year 2003, the Secretary of the Treasury
shall, not later than the later of the date that is 45 days after
the date of enactment of this Act or the date that a State provides
the certification required by subsection (e) for fiscal year 2003,
pay each State the amount determined for the State for fiscal year
2003 under subsection (c).
``(2) Fiscal year 2004.--From the amount appropriated under
subsection (a) for fiscal year 2004, the Secretary of the Treasury
shall, not later than the later of October 1, 2003, or the date
that a State provides the certification required by subsection (e)
for fiscal year 2004, pay each State the amount determined for the
State for fiscal year 2004 under subsection (c).
``(c) Payments Based on Population.--
``(1) In general.--Subject to paragraph (2), the amount
appropriated under subsection (a) for each of fiscal years 2003 and
2004 shall be used to pay each State an amount equal to the
relative population proportion amount described in paragraph (3)
for such fiscal year.
``(2) Minimum payment.--
``(A) In general.--No State shall receive a payment under
this section for a fiscal year that is less than--
``(i) in the case of 1 of the 50 States or the District
of Columbia, \1/2\ of 1 percent of the amount appropriated
for such fiscal year under subsection (a); and
``(ii) in the case of the Commonwealth of Puerto Rico,
the United States Virgin Islands, Guam, the Commonwealth of
the Northern Mariana Islands, or American Samoa, \1/10\ of
1 percent of the amount appropriated for such fiscal year
under subsection (a).
``(B) Pro rata adjustments.--The Secretary of the Treasury
shall adjust on a pro rata basis the amount of the payments to
States determined under this section without regard to this
subparagraph to the extent necessary to comply with the
requirements of subparagraph (A).
``(3) Relative population proportion amount.--The relative
population proportion amount described in this paragraph is the
product of--
``(A) the amount described in subsection (a) for a fiscal
year; and
``(B) the relative State population proportion (as defined
in paragraph (4)).
``(4) Relative state population proportion defined.--For
purposes of paragraph (3)(B), the term `relative State population
proportion' means, with respect to a State, the amount equal to the
quotient of--
``(A) the population of the State (as reported in the most
recent decennial census); and
``(B) the total population of all States (as reported in
the most recent decennial census).
``(d) Use of Payment.--
``(1) In general.--Subject to paragraph (2), a State shall use
the funds provided under a payment made under this section for a
fiscal year to--
``(A) provide essential government services; or
``(B) cover the costs to the State of complying with any
Federal intergovernmental mandate (as defined in section 421(5)
of the Congressional Budget Act of 1974) to the extent that the
mandate applies to the State, and the Federal Government has
not provided funds to cover the costs.
``(2) Limitation.--A State may only use funds provided under a
payment made under this section for types of expenditures permitted
under the most recently approved budget for the State.
``(e) Certification.--In order to receive a payment under this
section for a fiscal year, the State shall provide the Secretary of the
Treasury with a certification that the State's proposed uses of the
funds are consistent with subsection (d).
``(f) Definition of State.--In this section, the term `State' means
the 50 States, the District of Columbia, the Commonwealth of Puerto
Rico, the United States Virgin Islands, Guam, the Commonwealth of the
Northern Mariana Islands, and American Samoa.
``(g) Repeal.--Effective as of October 1, 2004, this title is
repealed.''.

TITLE V--CORPORATE ESTIMATED TAX PAYMENTS FOR 2003

SEC. 501. TIME FOR PAYMENT OF CORPORATE ESTIMATED TAXES.

Notwithstanding section 6655 of the Internal Revenue Code of 1986,
25 percent of the amount of any required installment of corporate
estimated tax which is otherwise due in September 2003 shall not be due
until October 1, 2003.

Speaker of the House of Representatives.

Vice President of the United States and
President of the Senate.