To prevent unspent SCHIP funds from reverting to the Treasury rather than being used to provide coverage for low-income children.
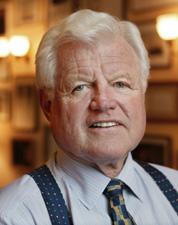 Sen. Edward M. Kennedy (D-MA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 2699 proposed by Senator Nickles for Senator Kennedy.(consideration: CR 3/12/2004 S2655-2656; text: CR 3/12/2004 S2656)
March 11, 2004
View full timeline
Senate amendment proposed (on the floor): Amendment SA 2699 proposed by Senator Nickles for Senator Kennedy.(consideration: CR 3/12/2004 S2655-2656; text: CR 3/12/2004 S2656)
March 11, 2004
Senate amendment agreed to: Amendment SA 2699 agreed to in Senate by Unanimous Consent.
March 11, 2004
Amendment SA 2699 proposed by Senator Nickles for Senator Kennedy. (consideration: CR 3/12/2004 S2655-2656; text: CR 3/12/2004 S2656) To prevent unspent SCHIP funds from reverting to the Treasury rather than being used to provide coverage for low-income children.
March 11, 2004
Amendment SA 2699 agreed to in Senate by Unanimous Consent.
March 11, 2004
Senate amendment submitted
March 8, 2004
Text
Submitted
TEXT OF AMENDMENTS

SA 2692. Mrs. HUTCHISON (for herself, Mr. Brownback, Mr. Bunning, Mr.
Chambliss,  and Mr. Fitzgerald) submitted an amendment intended to be
proposed by her to the bill S. 1637, to amend the Internal Revenue Code
of 1986 to comply with the World Trade Organization rulings on the FSC/
ETI benefit in a manner that preserves jobs and production activities
in the United States, to reform and simplify the international taxation
rules of the United States, and for other purposes; which was ordered
to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. FULL ELIMINATION OF THE MARRIAGE PENALTY FOR 2005.

(a) Standard Deduction.--Paragraph (7) of section 63(c) of
the Internal Revenue Code of 1986 (relating to applicable
percentage) is amended by striking ``174'' and inserting
``200''.
(b) 15-Percent Bracket.--Subparagraph (B) of section
1(f)(8) of the Internal Revenue Code of 1986 (relating to
applicable percentage) is amended by striking ``180'' and
inserting ``200''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2003.
(d) Application of EGTRRA Sunset to This Section.--Each
amendment made by this section shall be subject to title IX
of the Economic Growth and Tax Relief Reconciliation Act of
2001 to the same extent and in the same manner as the
provision of such Act to which such amendment relates.
______

SA 2693. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

On page 3, line 9, increase the amount by $2,352,000,000.
On page 3, line 10, increase the amount by $7,253,000,000.
On page 3, line 11, increase the amount by $196,000,000.
On page 3, line 17, increase the amount by $2,352,000,000.
On page 3, line 18, increase the amount by $7,253,000,000.
On page 3, line 19, increase the amount by $196,000,000.
On page 4, line 4, increase the amount by $4,901,000,000.
On page 4, line 12, increase the amount by $1,176,000,000.
On page 4, line 13, increase the amount by $3,627,000,000.
On page 4, line 14, increase the amount by $98,000,000.
On page 4, line 20, increase the amount by $1,176,000,000.
On page 4, line 21, increase the amount by $3,627,000,000.
On page 4, line 22, increase the amount by $98,000,000.
On page 5, line 3, decrease the amount by $1,176,000,000.
On page 5, line 4, decrease the amount by $4,803,000,000.
On page 5, line 5, decrease the amount by $4,901,000,000.
On page 5, line 6, decrease the amount by $4,901,000,000.
On page 5, line 7, decrease the amount by $4,901,000,000.
On page 5, line 11, decrease the amount by $1,176,000,000.
On page 5, line 12, decrease the amount by $4,803,000,000.
On page 5, line 13, decrease the amount by $4,901,000,000.
On page 5, line 14, decrease the amount by $4,901,000,000.
On page 5, line 15, decrease the amount by $4,901,000,000.
On page 15, line 16, increase the amount by $4,901,000,000.
On page 15, line 17, increase the amount by $1,176,000,000.
On page 15, line 21, increase the amount by $3,627,000,000.
On page 15, line 25, increase the amount by $98,000,000.
On page 39, line 18, increase the amount by $4,901,000,000.
On page 39, line 19, increase the amount by $1,176,000,000.
On page 40, line 2, increase the amount by $3,627,000,000.
______

SA 2694. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. SENATE OF THE SENATE CONCERNING AN INCREASE IN THE
MINIMUM WAGE.

(a) In General.--It is the sense of the Senate that this
resolution assumes that legislation increasing the Federal
minimum wage will be enacted that will contain the provisions
described in subsection (b).
(b) Minimum Wage.--The provisions described in this
subsection are the following:
(1) In general.--Section 6(a)(1) of the Fair Labor
Standards Act of 1938 (29 U.S.C. 206(a)(1)) is amended to
read as follows:
``(1) except as otherwise provided in this section, not
less than--
``(A) $5.85 an hour, beginning on the 60th day after the
date of enactment of the Fair Minimum Wage Act of 2003;
``(B) $6.45 an hour, beginning 12 months after that 60th
day; and
``(C) $7.00 an hour, beginning 24 months after that 60th
day;''.
(2) Applicability of minimum wage to the commonwealth of
the northern mariana islands.--
(A) In general.--Section 6 of the Fair Labor Standards Act
of 1938 (29 U.S.C. 206) shall apply to the Commonwealth of
the Northern Mariana Islands.
(B) Transition.--Notwithstanding subparagraph (A), the
minimum wage applicable to the Commonwealth of the Northern
Mariana Islands under section 6(a)(1) of the Fair Labor
Standards Act of 1938 (29 U.S.C. 206(a)(1)) shall be--
(i) $3.55 an hour, beginning on the 60th day after the date
of enactment of the legislation involved; and
(ii) increased by $0.50 an hour (or such lesser amount as
may be necessary to equal the minimum wage under section
6(a)(1) of such Act), beginning 6 months after the date of
enactment of this Act and every 6 months thereafter until the
minimum wage applicable to the Commonwealth of the Northern
Mariana Islands under this subsection is equal to the minimum
wage set forth in such section.
(3) Effective Date.--The amendment made by paragraph (1)
shall take effect 60 days after the date of enactment of the
legislation involved.
______

SA 2695. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

On page 28, after line 7, insert the following:

SEC. __. RESERVE FUND TO ELIMINATE OVERPAYMENTS TO REGIONAL
PPOS AND OTHER MEDICARE ADVANTAGE PLANS IN
ORDER TO ASSURE A LEVEL PLAYING FIELD BETWEEN
CONVENTIONAL MEDICARE AND PRIVATE SECTOR
ALTERNATIVE, PRESERVE MEDICARE BENEFICIARIES'
RIGHT TO CHOOSE THEIR DOCTOR, IMPROVE THE
FINANCIAL STATUS OF MEDICARE TRUST FUNDS, AND
REDUCE THE DEFICIT.

If the Committee on Finance of the Senate reports a bill or
a joint resolution, or an amendment thereto is offered, or a
conference report thereon is submitted, that eliminates the
stabilization fund for Medicare regional PPOs or other
provisions of law that raise Medicare expenditures by
providing excess payments to Medicare Advantage Plans, and
applies the savings from such payment changes to reducing the
Medicare prescription drug coverage gap, improving the
financial status of the Medicare trust funds, or reducing the
deficit, the chairman of the Committee on the Budget may
revise committee allocations and other appropriate aggregates
in this resolution for this purpose.
______

SA 2696. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

[[Page S2311]]

On page 3, line 9, increase the amount by $1,332,000,000.
On page 3, line 10, increase the amount by $4,560,000,000.
On page 3, line 11, increase the amount by $220,000,000.
On page 3, line 12, increase the amount by $52,000,000.
On page 3, line 17, increase the amount by $1,332,000,000.
On page 3, line 18, increase the amount by $4,560,000,000.
On page 3, line 19, increase the amount by $220,000,000.
On page 3, line 20, increase the amount by $52,000,000.
On page 4, line 4, increase the amount by $3,082,000,000.
On page 4, line 12, increase the amount by $666,000,000.
On page 4, line 13, increase the amount by $2,280,000,000.
On page 4, line 14, increase the amount by $110,000,000.
On page 4, line 15, increase the amount by $26,000,000.
On page 4, line 20, increase the amount by $666,000,000.
On page 4, line 21, increase the amount by $2,280,000,000.
On page 4, line 22, increase the amount by $110,000,000.
On page 4, line 23, increase the amount by $26,000,000.
On page 5, line 3, decrease the amount by $666,000,000.
On page 5, line 4, decrease the amount by $2,946,000,000.
On page 5, line 5, decrease the amount by $3,056,000,000.
On page 5, line 6, decrease the amount by $3,082,000,000.
On page 5, line 7, decrease the amount by $3,082,000,000.
On page 5, line 11, decrease the amount by $666,000,000.
On page 5, line 12, decrease the amount by $2,946,000,000.
On page 5, line 13, decrease the amount by $3,056,000,000.
On page 5, line 14, decrease the amount by $3,082,000,000.
On page 5, line 15, decrease the amount by $3,082,000,000.
On page 15, line 16, increase the amount by $3,082,000,000.
On page 15, line 17, increase the amount by $666,000,000.
On page 15, line 21, increase the amount by $2,280,000,000.
On page 15, line 25, increase the amount by $110,000,000.
On page 16, line 4, increase the amount by $26,000,000.
On page 39, line 18, increase the amount by $3,082,000,000.
On page 39, line 19, increase the amount by $666,000,000.
On page 40, line 2, increase the amount by $2,280,000,000.
______

SA 2697. Mr. DeWINE (for himself and Mr. Leahy) submitted an
amendment intended to be proposed by him to the concurrent resolution
S. Con. Res. 95, setting forth the congressional budget for the United
States Government for fiscal year 2005 and including the appropriate
budgetary levels for fiscal years 2006 through 2009; which was ordered
to lie on the table; as follows:

On page 8, line 21, strike ``$30,140,000,000'' and insert
``$30,470,000,000''.
On page 23, line 5, strike ``-$100,000,000'' and insert
``-$430,000,000''.
______

SA 2698. Mrs. FEINSTEIN (for herself and Mr. Graham of Florida)
submitted an amendment intended to be proposed by her to the bill S.
1637, to amend the Internal Revenue Code of 1986 to comply with the
World Trade Organization rulings on the FSC/ETI benefit in a manner
that preserves jobs and production activities in the United States, to
reform and simplify the international taxation rules of the United
States, and for other purposes; which was ordered to lie on the table;
as follows:

At the end add the following:

SEC. __. CREDIT FOR ELECTRICITY PRODUCED FROM CERTAIN
RENEWABLE RESOURCES TO INCLUDE OPEN-LOOP
BIOMASS FACILITIES.

(a) In General.--Section 45(c)(1) (defining qualified
energy resources) is amended by striking ``and'' at the end
of subparagraph (B), by striking the period at the end of
subparagraph (C) and inserting ``, and'', and by adding at
the end the following new subparagraph:
``(D) open-loop biomass.''.
(b) Facilities Described.--Section 45(c)(3) (defining
qualified facility) is amended by adding at the end the
following new subparagraph:
``(D) Open-loop biomass facility.--
``(i) In general.--In the case of a facility using open-
loop biomass to produce electricity, the term `qualified
facility' means any facility owned by the taxpayer which is
originally placed in service before January 1, 2006.
``(ii) Special rules for preeffective date facilities.--In
the case of any facility described in clause (i) which is
placed in service before the date of the enactment of this
subparagraph--

``(I) subsection (a)(1) shall be applied by substituting `1
cent' for `1.5 cents', and
``(II) the 5-year period beginning on such date of
enactment shall be substituted for the 10-year period in
subsection (a)(2)(A)(ii).

``(iii) Credit eligibility.--In the case of any facility
described in clause (i), if the owner of such facility is not
the producer of the electricity, the person eligible for the
credit allowable under subsection (a) shall be the lessee or
the operator of such facility.
``(iv) Limit on reductions for tax-exempt bond financing,
etc.--If the amount of the credit determined under subsection
(a) with respect to any facility described in clause (i) is
required to be reduced under paragraph (3) of subsection (b),
the fraction under such paragraph shall in no event be
greater than \1/2\.''.
(c) Open-Loop Biomass Defined.--Section 45(c) (relating to
definitions) is amended by adding at the end the following
new paragraph:
``(5) Open-loop biomass.--
``(A) In general.--The term `open-loop biomass' means any
solid, nonhazardous, cellulosic waste material which is
segregated from other waste materials and which is derived
from--
``(i) any of the following forest-related resources: mill
and harvesting residues, precommercial thinnings, slash, and
brush,
``(ii) solid wood waste materials, including waste pallets,
crates, dunnage, manufacturing and construction wood wastes
(other than pressure-treated, chemically-treated, or painted
wood wastes), and landscape or right-of-way tree trimmings,
but not including municipal solid waste, gas derived from the
biodegradation of solid waste, or paper which is commonly
recycled, or
``(iii) agriculture sources, including orchard tree crops,
vineyard, grain, legumes, sugar, and other crop by-products
or residues.
``(B) Exceptions.--Such term does not include--
``(i) closed-loop biomass, or
``(ii) any agricultural livestock waste nutrients.''.
(d) Effective Date.--The amendments made by this section
shall apply to electricity produced and sold after the date
of the enactment of this Act, in taxable years ending after
such date.
______

SA 2699. Mr. KENNEDY (for himself and Mr. Rockefeller) submitted an
amendment intended to be proposed by him to the concurrent resolution
S. Con. Res. 95, setting forth the congressional budget for the United
States Government for fiscal year 2005 and including the appropriate
budgetary levels for fiscal years 2006 through 2009; which was ordered
to lie on the table; as follows:

On page 26, line 4, after ``measures'' insert ``and
including legislation to reallocate and maintain expiring
SCHIP funds rather than allowing such funds to revert to the
Treasury''.
______

SA 2700. Mr. LAUTENBERG (for himself, Mr. Chafee, Mrs. Dole, and Mr.
Lieberman) submitted an amendment intended to be proposed by him to the
bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with
the World Trade Organization rulings on the FSC/ETI benefit in a manner
that preserves jobs and production activities in the United States, to
reform and simplify the international taxation rules of the United
States, and for other purposes; which was ordered to lie on the table;
as follows:

On page 179, after line 25, add the following:

SEC. __. EXCLUSION OF GAIN OR LOSS ON SALE OR EXCHANGE OF
CERTAIN BROWNFIELD SITES FROM UNRELATED
BUSINESS TAXABLE INCOME.

(a) In General.--Subsection (b) of section 512 (relating to
unrelated business taxable income) is amended by adding at
the end the following new paragraph:
``(18) Treatment of gain or loss on sale or exchange of
certain brownfield sites.--
``(A) In general.--Notwithstanding paragraph (5)(B), there
shall be excluded any gain or loss from the qualified sale,
exchange, or other disposition of any qualifying brownfield
property by an eligible taxpayer.
``(B) Eligible taxpayer.--For purposes of this paragraph--
``(i) In general.--The term `eligible taxpayer' means, with
respect to a property, any organization exempt from tax under
section 501(a) which--

``(I) acquires from an unrelated person a qualifying
brownfield property, and
``(II) pays or incurs eligible remediation expenditures
with respect to such property in an amount which exceeds the
greater of $550,000 or 12 percent of the fair market value of
the property at the time such property was acquired by the
eligible taxpayer, determined as if there was not a presence
of a hazardous substance, pollutant, or contaminant on the
property which is complicating the expansion, redevelopment,
or reuse of the property.

``(ii) Exception.--Such term shall not include any
organization which is--

``(I) potentially liable under section 107 of the
Comprehensive Environmental Response, Compensation, and
Liability Act of 1980 with respect to the qualifying
brownfield property,

[[Page S2312]]

``(II) affiliated with any other person which is so
potentially liable through any direct or indirect familial
relationship or any contractual, corporate, or financial
relationship (other than a contractual, corporate, or
financial relationship which is created by the instruments by
which title to any qualifying brownfield property is conveyed
or financed or by a contract of sale of goods or services),
or
``(III) the result of a reorganization of a business entity
which was so potentially liable.

``(C) Qualifying brownfield property.--For purposes of this
paragraph--
``(i) In general.--The term `qualifying brownfield
property' means any real property which is certified, before
the taxpayer incurs any eligible remediation expenditures
(other than to obtain a Phase I environmental site
assessment), by an appropriate State agency (within the
meaning of section 198(c)(4)) in the State in which such
property is located as a brownfield site within the meaning
of section 101(39) of the Comprehensive Environmental
Response, Compensation, and Liability Act of 1980 (as in
effect on the date of the enactment of this paragraph).
``(ii) Request for certification.--Any request by an
eligible taxpayer for a certification described in clause (i)
shall include a sworn statement by the eligible taxpayer and
supporting documentation of the presence of a hazardous
substance, pollutant, or contaminant on the property which is
complicating the expansion, redevelopment, or reuse of the
property given the property's reasonably anticipated future
land uses or capacity for uses of the property (including a
Phase I environmental site assessment and, if applicable,
evidence of the property's presence on a local, State, or
Federal list of brownfields or contaminated property) and
other environmental assessments prepared or obtained by the
taxpayer.
``(D) Qualified sale, exchange, or other disposition.--For
purposes of this paragraph--
``(i) In general.--A sale, exchange, or other disposition
of property shall be considered as qualified if--

``(I) such property is transferred by the eligible taxpayer
to an unrelated person, and
``(II) within 1 year of such transfer the eligible taxpayer
has received a certification from the Environmental
Protection Agency or an appropriate State agency (within the
meaning of section 198(c)(4)) in the State in which such
property is located that, as a result of the eligible
taxpayer's remediation actions, such property would not be
treated as a qualifying brownfield property in the hands
of the transferee.
``(ii) Request for certification.--Any request by an
eligible taxpayer for a certification described in clause (i)
shall be made not later than the date of the transfer and
shall include a sworn statement by the eligible taxpayer
certifying the following:

``(I) Remedial actions which comply with all applicable or
relevant and appropriate requirements (consistent with
section 121(d) of the Comprehensive Environmental Response,
Compensation, and Liability Act of 1980) have been
substantially completed, such that there are no hazardous
substances, pollutants, or contaminants which complicate the
expansion, redevelopment, or reuse of the property given the
property's reasonably anticipated future land uses or
capacity for uses of the property.
``(II) The reasonably anticipated future land uses or
capacity for uses of the property are more economically
productive or environmentally beneficial than the uses of the
property in existence on the date of the certification
described in subparagraph (C)(i). For purposes of the
preceding sentence, use of property as a landfill or other
hazardous waste facility shall not be considered more
economically productive or environmentally beneficial.
``(III) A remediation plan has been implemented to bring
the property into compliance with all applicable local,
State, and Federal environmental laws, regulations, and
standards and to ensure that the remediation protects human
health and the environment.
``(IV) The remediation plan described in subclause (III),
including any physical improvements required to remediate the
property, is either complete or substantially complete, and,
if substantially complete, sufficient monitoring, funding,
institutional controls, and financial assurances have been
put in place to ensure the complete remediation of the
property in accordance with the remediation plan as soon as
is reasonably practicable after the sale, exchange, or other
disposition of such property.
``(V) Public notice that such request for certification
would be made was completed before the date of such request.
Such notice shall be in the same form and manner as required
for public participation required under section 117(a) of the
Comprehensive Environmental Response, Compensation, and
Liability Act of 1980 (as in effect on the date of the
enactment of this paragraph).

``(iii) Attachment to tax returns.--A copy of each of the
requests for certification described in clause (ii) of
subparagraph (C) and this subparagraph shall be included in
the tax return of the eligible taxpayer (and, where
applicable, of the qualifying partnership) for the taxable
year during which the transfer occurs.
``(E) Eligible remediation expenditures.--For purposes of
this paragraph--
``(i) In general.--The term `eligible remediation
expenditures' means, with respect to any qualifying
brownfield property, any amount paid or incurred by the
eligible taxpayer to an unrelated third person to obtain a
Phase I environmental site assessment of the property, and
any amount so paid or incurred after the date of the
certification described in subparagraph (C)(i) for goods and
services necessary to obtain a certification described in
subparagraph (D)(i) with respect to such property, including
expenditures--

``(I) to manage, remove, control, contain, abate, or
otherwise remediate a hazardous substance, pollutant, or
contaminant on the property,
``(II) to obtain a Phase II environmental site assessment
of the property, including any expenditure to monitor,
sample, study, assess, or otherwise evaluate the release,
threat of release, or presence of a hazardous substance,
pollutant, or contaminant on the property,
``(III) to obtain environmental regulatory certifications
and approvals required to manage the remediation and
monitoring of the hazardous substance, pollutant, or
contaminant on the property, and
``(IV) regardless of whether it is necessary to obtain a
certification described in subparagraph (D)(i)(II), to obtain
remediation cost-cap or stop-loss coverage, re-opener or
regulatory action coverage, or similar coverage under
environmental insurance policies, or financial guarantees
required to manage such remediation and monitoring.
``(ii) Exceptions.--Such term shall not include--

``(I) any portion of the purchase price paid or incurred by
the eligible taxpayer to acquire the qualifying brownfield
property,
``(II) environmental insurance costs paid or incurred to
obtain legal defense coverage, owner/operator liability
coverage, lender liability coverage, professional liability
coverage, or similar types of coverage,
``(III) any amount paid or incurred to the extent such
amount is reimbursed, funded, or otherwise subsidized by
grants provided by the United States, a State, or a political
subdivision of a State for use in connection with the
property, proceeds of an issue of State or local government
obligations used to provide financing for the property the
interest of which is exempt from tax under section 103, or
subsidized financing provided (directly or indirectly) under
a Federal, State, or local program provided in connection
with the property, or
``(IV) any expenditure paid or incurred before the date of
the enactment of this paragraph.

For purposes of subclause (III), the Secretary may issue
guidance regarding the treatment of government-provided funds
for purposes of determining eligible remediation
expenditures.
``(F) Determination of gain or loss.--For purposes of this
paragraph, the determination of gain or loss shall not
include an amount treated as gain which is ordinary income
with respect to section 1245 or section 1250 property,
including amounts deducted as section 198 expenses which are
subject to the recapture rules of section 198(e), if the
taxpayer had deducted such amounts in the computation of its
unrelated business taxable income.
``(G) Special rules for partnerships.--
``(i) In general.--In the case of an eligible taxpayer
which is a partner of a qualifying partnership which
acquires, remediates, and sells, exchanges, or otherwise
disposes of a qualifying brownfield property, this paragraph
shall apply to the eligible taxpayer's distributive share of
the qualifying partnership's gain or loss from the sale,
exchange, or other disposition of such property.
``(ii) Qualifying partnership.--The term `qualifying
partnership' means a partnership which--

``(I) has a partnership agreement which satisfies the
requirements of section 514(c)(9)(B)(vi) at all times
beginning on the date of the first certification received by
the partnership under subparagraph (C)(i),
``(II) satisfies the requirements of subparagraphs (B)(i),
(C), (D), and (E), if `qualified partnership' is substituted
for `eligible taxpayer' each place it appears therein (except
subparagraph (D)(iii)), and
``(III) is not an organization which would be prevented
from constituting an eligible taxpayer by reason of
subparagraph (B)(ii).

``(iii) Requirement that tax-exempt partner be a partner
since first certification.--This paragraph shall apply with
respect to any eligible taxpayer which is a partner of a
partnership which acquires, remediates, and sells, exchanges,
or otherwise disposes of a qualifying brownfield property
only if such eligible taxpayer was a partner of the
qualifying partnership at all times beginning on the date of
the first certification received by the partnership under
subparagraph (C)(i) and ending on the date of the sale,
exchange, or other disposition of the property by the
partnership.
``(iv) Regulations.--The Secretary shall prescribe such
regulations as are necessary to prevent abuse of the
requirements of this subparagraph, including abuse through--

``(I) the use of special allocations of gains or losses, or
``(II) changes in ownership of partnership interests held
by eligible taxpayers.

``(H) Special rules for multiple properties.--
``(i) In general.--An eligible taxpayer or a qualifying
partnership of which the eligible taxpayer is a partner may
make a 1-time election to apply this paragraph to more than 1
qualifying brownfield property by

[[Page S2313]]

averaging the eligible remediation expenditures for all such
properties acquired during the election period. If the
eligible taxpayer or qualifying partnership makes such an
election, the election shall apply to all qualified sales,
exchanges, or other dispositions of qualifying brownfield
properties the acquisition and transfer of which occur during
the period for which the election remains in effect.
``(ii) Election.--An election under clause (i) shall be
made with the eligible taxpayer's or qualifying partnership's
timely filed tax return (including extensions) for the first
taxable year for which the taxpayer or qualifying partnership
intends to have the election apply. An election under clause
(i) is effective for the period--

``(I) beginning on the date which is the first day of the
taxable year of the return in which the election is included
or a later day in such taxable year selected by the eligible
taxpayer or qualifying partnership, and
``(II) ending on the date which is the earliest of a date
of revocation selected by the eligible taxpayer or qualifying
partnership, the date which is 8 years after the date
described in subclause (I), or, in the case of an election by
a qualifying partnership of which the eligible taxpayer is a
partner, the date of the termination of the qualifying
partnership.

``(iii) Revocation.--An eligible taxpayer or qualifying
partnership may revoke an election under clause (i)(II) by
filing a statement of revocation with a timely filed tax
return (including extensions). A revocation is effective as
of the first day of the taxable year of the return in which
the revocation is included or a later day in such taxable
year selected by the eligible taxpayer or qualifying
partnership. Once an eligible taxpayer or qualifying
partnership revokes the election, the eligible taxpayer or
qualifying partnership is ineligible to make another election
under clause (i) with respect to any qualifying brownfield
property subject to the revoked election.
``(I) Recapture.--If an eligible taxpayer excludes gain or
loss from a sale, exchange, or other disposition of property
to which an election under subparagraph (H) applies, and such
property fails to satisfy the requirements of this paragraph,
the unrelated business taxable income of the eligible
taxpayer for the taxable year in which such failure occurs
shall be determined by including any previously excluded gain
or loss from such sale, exchange, or other disposition
allocable to such taxpayer, and interest shall be determined
at the overpayment rate established under section 6621 on any
resulting tax for the period beginning with the due date of
the return for the taxable year during which such sale,
exchange, or other disposition occurred, and ending on the
date of payment of the tax.
``(J) Related persons.--For purposes of this paragraph, a
person shall be treated as related to another person if--
``(i) such person bears a relationship to such other person
described in section 267(b) (determined without regard to
paragraph (9) thereof), or section 707(b)(1), determined by
substituting `25 percent' for `50 percent' each place it
appears therein, and
``(ii) in the case such other person is a nonprofit
organization, if such person controls directly or indirectly
more than 25 percent of the governing body of such
organization.''
(b) Exclusion From Definition of Debt-Financed Property.--
Section 514(b)(1) (defining debt-financed property) is
amended by striking ``or'' at the end of subparagraph (C), by
striking the period at the end of subparagraph (D) and
inserting ``; or'', and by inserting after subparagraph (D)
the following new subparagraph:
``(E) any property the gain or loss from the sale,
exchange, or other disposition of which would be excluded by
reason of the provisions of section 512(b)(18) in computing
the gross income of any unrelated trade or business.''.
(c) Effective Date.--The amendments made by this section
shall apply to any gain or loss on the sale, exchange, or
other disposition of any property acquired by the taxpayer
after the date of the enactment of this Act.
______

SA 2701. Mr. WARNER (for himself, Mr. Stevens, Mr. Inhofe, Mr.
Roberts, Ms. Collins, Mr. Chambliss, Mr. Graham of South Carolina, and
Mr. Talent) submitted an amendment intended to be proposed by him to
the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

On page 4, line 4, increase the amount by $699,700,000.
On page 4, line 5, increase the amount by $262,000,000.
On page 4, line 6, increase the amount by $358,000,000.
On page 4, line 7, increase the amount by $405,000,000.
On page 4, line 8, increase the amount by $432,000,000.
On page 4, line 12, increase the amount by $5,506,000,000.
On page 4, line 13, increase the amount by $1,855,000,000.
On page 4, line 14, increase the amount by $799,000,000.
On page 4, line 15, increase the amount by $550,000,000.
On page 4, line 16, increase the amount by $480,000,000.
On page 4, line 20, decrease the amount by $5,506,000,000.
On page 4, line 21, decrease the amount by $1,855,000,000.
On page 4, line 22, decrease the amount by $799,000,000.
On page 4, line 23, decrease the amount by $550,000,000.
On page 4, line 24, decrease the amount by $480,000,000.
On page 5, line 3, increase the amount by $5,506,000,000.
On page 5, line 4, increase the amount by $7,362,000,000.
On page 5, line 5, increase the amount by $8,161,000,000.
On page 5, line 6, increase the amount by $8,711,000,000.
On page 5, line 7, increase the amount by $9,191,000,000.
On page 5, line 11, increase the amount by $5,506,000,000.
On page 5, line 12, increase the amount by $7,362,000,000.
On page 5, line 13, increase the amount by $8,161,000,000.
On page 5, line 14, increase the amount by $8,711,000,000.
On page 5, line 15, increase the amount by $9,191,000,000.
On page 7, line 25, increase the amount by $6,900,000,000.
On page 8, line 1, increase the amount by $5,409,000,000.
On page 8, line 5, increase the amount by $1,594,000,000.
On page 8, line 9, increase the amount by $442,000,000.
On page 8, line 13, increase the amount by $145,000,000.
On page 8, line 17, increase the amount by $48,000,000.
On page 22, line 9, increase the amount by $97,000,000.
On page 22, line 10, increase the amount by $97,000,000.
On page 22, line 13, increase the amount by $262,000,000.
On page 22, line 14, increase the amount by $262,000,000.
On page 22, line 17, increase the amount by $358,000,000.
On page 22, line 18, increase the amount by $358,000,000.
On page 22, line 21, increase the amount by $405,000,000.
On page 22, line 22, increase the amount by $405,000,000.
On page 22, line 25, increase the amount by $432,000,000.
On page 23, line 1, increase the amount by $432,000,000.
On page 39, line 18, increase the amount by $6,900,000,000.
On page 39, line 19, increase the amount by $5,409,000,000.
On page 40, line 2, increase the amount by $1,594,000,000.
______

SA 2702. Mrs. DOLE submitted an amendment intended to be proposed by
her to the concurrent resolution S. Con. Res. 95, setting forth the
congressional budget for the United States Government for fiscal year
2005 and including the appropriate budgetary levels for fiscal years
2006 through 2009; which was ordered to lie on the table; as follows:

On page 18, line 4, increase the amount by $156,000,000.
On page 18, line 5, increase the amount by $135,000,000.
On page 18, line 8, increase the amount by $162,000,000.
On page 18, line 9, increase the amount by $160,000,000.
On page 18, line 12, increase the amount by $169,000,000.
On page 18, line 13, increase the amount by $170,000,000.
On page 18, line 16, increase the amount by $175,000,000.
On page 18, line 17, increase the amount by $175,000,000.
On page 18, line 20, increase the amount by $180,000,000.
On page 18, line 21, increase the amount by $180,000,000.
On page 23, line 5, decrease the amount by $156,000,000.
On page 23, line 6, decrease the amount by $135,000,000.
On page 23, line 9, decrease the amount by $162,000,000.
On page 23, line 10, decrease the amount by $160,000,000.
On page 23, line 13, decrease the amount by $169,000,000.
On page 23, line 14, decrease the amount by $170,000,000.
On page 23, line 17, decrease the amount by $175,000,000.
On page 23, line 18, decrease the amount by $175,000,000.
On page 23, line 21, decrease the amount by $180,000,000.
On page 23, line 22, decrease the amount by $180,000,000.

____________________