To provide for the extension of the special net operating loss carryover provision.
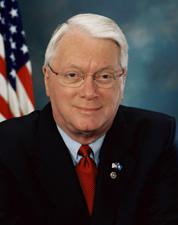 Sen. Jim Bunning (R-KY)
Text
Submitted
SA 2882. Mr. GRASSLEY (for Mr. Bunning (for himself, Mrs. Lincoln, Mr. Santorum, Mr. Conrad, and Mr. Baucus)) proposed an amendment to amendment SA 2686 proposed by Mr. Bunning (for himself, Ms. Stabenow, Mrs. Feinstein, Mr. Levin, Mr. Kohl, and Mr. Rockefeller) to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; as follows:
At the end of the matter proposed to be inserted at the end of the bill, add the following:
SEC. __. FIVE-YEAR CARRYBACK OF NET OPERATING LOSSES.
(a) In General.--Subparagraph (H) of section 172(b)(1) is amended--
(1) by inserting “5-year carryback of certain losses.--” after “(H)”, and
(2) by striking “or 2002” and inserting “, 2002, or 2003”.
(b) Rules Relating to Certain Extended Net Operating Losses.--Section 172 is amended by redesignating subsection (k) as subsection (l) and by inserting after subsection (j) the following new subsection:
“(k) Rules Relating to Certain Extended Net Operating Losses.--For purposes of this section, in the case of a taxpayer which has a net operating loss for any taxable year ending during 2003 and does not make an election under subsection (j), such taxpayer shall be deemed to have made an election under paragraphs (4)(E) and (2)(C)(iii) of section 168(k) with respect to all classes of property for such taxable year.
(c) Temporary Suspension of 90 Percent Limit on Certain NOL Carryovers.--Section 56(d)(1)(A)(ii)(I) (relating to general rule defining alternative tax net operating loss deduction) is amended--
(1) by striking “or 2002” and inserting “, 2002, or 2003”, and
(2) by striking “and 2002” and inserting “, 2002, and 2003”.
(d) Technical Corrections.--
(1) Subparagraph (H) of section 172(b)(1) is amended by striking “a taxpayer which has”.
(2) Section 102(c)(2) of the Job Creation and Worker Assistance Act of 2002 (Public Law 107-147) is amended by striking “before January 1, 2003” and inserting “after December 31, 1990”.
(3)(A) Subclause (I) of section 56(d)(1)(A)(i) is amended by striking “attributable to carryovers”.
(B) Subclause (I) of section 56(d)(1)(A)(ii) is amended--
(i) by striking “for taxable years” and inserting “from taxable years”, and
(ii) by striking “carryforwards” and inserting “carryovers”.
(e) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the amendments made by this section shall apply to net operating losses for taxable years ending after December 31, 2002.
(2) Technical corrections.--The amendments made by subsection (d) shall take effect as if included in the amendments made by section 102 of the Job Creation and Worker Assistance Act of 2002.
(3) Election.--In the case of a net operating loss for a taxable year ending during 2003--
(A) any election made under section 172(b)(3) of such Code may (notwithstanding such section) be revoked before April 15, 2004, and
(B) any election made under section 172(j) of such Code shall (notwithstanding such section) be treated as timely made if made before April 15, 2004.
(4) Special rule for taxpayers with taxable years ending during january.--Any taxpayer which has a taxable year ending during January may elect under this paragraph to apply section 172(b)(1)(H) of the Internal Revenue Code of 1986 (as amended by this section) to its taxable year ending in 2004 rather than its taxable year ending in 2003. If such election is made, then section 172(k) of such Code (as added by this section) shall be applied to the taxpayer's taxable year ending in 2004. Such election shall be made in such manner and at such time as may be prescribed by the Secretary of the Treasury. Such election, once made, shall be irrevocable.
(c) Prior Section To Have No Effect.--Notwithstanding section 311(e) of this Act, such section, and the amendments made by such section, shall not take effect.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 22, 2004
View full timeline
Senate amendment submitted
March 22, 2004
Senate amendment proposed (on the floor): Amendment SA 2882 proposed by Senator Grassley for Senator Bunning to Amendment SA 2687.(consideration: CR S2851-2852; text: CR S2851-2852)
March 22, 2004
Senate amendment agreed to: Amendment SA 2882 agreed to in Senate by Unanimous Consent.
March 22, 2004
Amendment SA 2882 proposed by Senator Grassley for Senator Bunning to Amendment SA 2687. (consideration: CR S2851-2852; text: CR S2851-2852) To provide for the extension of the special net operating loss carryover provision.
March 22, 2004
Amendment SA 2882 agreed to in Senate by Unanimous Consent.
March 22, 2004