S.Amdt. 558
What it does: Adds SEC. ____. EXPANSION OF DEDUCTION FOR HIGHER EDUCATION EXPENSES at the end of subtitle C of title V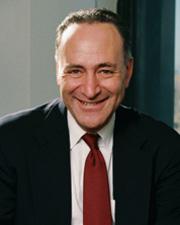 Sen. Charles E. Schumer (D-NY)
What it changes
1 change to S. 1054 · shown in the bill's text
Adds SEC. ____. EXPANSION OF DEDUCTION FOR HIGHER EDUCATION EXPENSES at the end of subtitle C of title V
Adds a sectionIn S. 1054 · Placed on Calendar Senate
(c) Effective Date.--The amendments made by this section shall apply to amounts paid or accrued after the date of enactment of this section in taxable years ending after such date.
Inserted: SEC. ____. EXPANSION OF DEDUCTION FOR HIGHER EDUCATION EXPENSES.
Inserted: (a) In General.--
Inserted: (1) Amount of deduction.--Subsection (b) of section 222 (relating to deduction for qualified tuition and related expenses) is amended to read as follows:
Inserted: "(b) Limitations.--
Inserted: "(1) Dollar limitations.--
Inserted: "(A) In general.--Except as provided in paragraph (2), the amount allowed as a deduction under subsection (a) with respect to the taxpayer for any taxable year shall not exceed the applicable dollar limit.
Inserted: "(B) Applicable dollar limit.--The applicable dollar limit for any taxable year shall be determined as follows:
Inserted: Applicable "Taxable year: dollar amount:
Inserted: 2003......................................................$8,000 ....
Inserted: 2004 and thereafter......................................$12,000.....
Inserted: "(2) Limitation based on modified adjusted gross income.--
Inserted: "(A) In general.--The amount which would (but for this paragraph) be taken into account under subsection (a) shall be reduced (but not below zero) by the amount determined under subparagraph (B).
Show 46 more inserted paragraphsShow less
Inserted: "(B) Amount of reduction.--The amount determined under this subparagraph equals the amount which bears the same ratio to the amount which would be so taken into account as--
Inserted: "(i) the excess of--
Inserted: "(I) the taxpayer's modified adjusted gross income for such taxable year, over
Inserted: "(II) $65,000 ($130,000 in the case of a joint return), bears to
Inserted: "(ii) $15,000 ($30,000 in the case of a joint return).
Inserted: "(C) Modified adjusted gross income.--For purposes of this paragraph, the term 'modified adjusted gross income' means the adjusted gross income of the taxpayer for the taxable year determined--
Inserted: "(i) without regard to this section and sections 911, 931, and 933, and
Inserted: "(ii) after the application of sections 86, 135, 137, 219, 221, and 469. For purposes of the sections referred to in clause (ii), adjusted gross income shall be determined without regard to the deduction allowed under this section.
Inserted: "(D) Inflation adjustments.--
Inserted: "(i) In general.--In the case of any taxable year beginning in a calendar year after 2003, both of the dollar amounts in subparagraph (B)(i)(II) shall be increased by an amount equal to--
Inserted: "(I) such dollar amount, multiplied by
Inserted: "(II) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting 'calendar year 2002' for 'calendar year 1992' in subparagraph (B) thereof.
Inserted: "(ii) Rounding.--If any amount as adjusted under clause (i) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50.".
Inserted: (2) Qualified tuition and related expenses of eligible students.--
Inserted: (A) In general.--Section 222(a) (relating to allowance of deduction) is amended by inserting "of eligible students" after "expenses".
Inserted: (B) Definition of eligible student.--Section 222(d) (relating to definitions and special rules) is amended by redesignating paragraphs (2) through (6) as paragraphs (3) through (7), respectively, and by inserting after paragraph (1) the following new paragraph:
Inserted: "(2) Eligible student.--The term 'eligible student' has the meaning given such term by section 25A(b)(3).".
Inserted: (3) Effective date.--The amendments made by this subsection shall apply to payments made in taxable years beginning after December 31, 2002 and before January 1, 2009.
Inserted: (b) Interest on Higher Education Loans.--
Inserted: (1) In general.--Subpart A of part IV of subchapter A of chapter 1 (relating to nonrefundable personal credits) is amended by inserting after section 25B the following new section:
Inserted: "SEC. 25C. INTEREST ON HIGHER EDUCATION LOANS.
Inserted: "(a) Allowance of Credit.--In the case of an individual, there shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to the interest paid by the taxpayer during the taxable year on any qualified education loan.
Inserted: "(b) Maximum Credit.--
Inserted: "(1) In general.--Except as provided in paragraph (2), the credit allowed by subsection (a) for the taxable year shall not exceed $1,500.
Inserted: "(2) Limitation based on modified adjusted gross income.--
Inserted: "(A) In general.--If the modified adjusted gross income of the taxpayer for the taxable year exceeds $50,000 ($100,000 in the case of a joint return), the amount which would (but for this paragraph) be allowable as a credit under this section shall be reduced (but not below zero) by the amount which bears the same ratio to the amount which would be so allowable as such excess bears to $20,000 ($40,000 in the case of a joint return).
Inserted: "(B) Modified adjusted gross income.--The term 'modified adjusted gross income' means adjusted gross income determined without regard to sections 911, 931, and 933.
Inserted: "(C) Inflation adjustment.--In the case of any taxable year beginning after 2003, the $50,000 and $100,000 amounts referred to in subparagraph (A) shall be increased by an amount equal to--
Inserted: "(i) such dollar amount, multiplied by
Inserted: "(ii) the cost-of-living adjustment determined under section (1)(f)(3) for the calendar year in which the taxable year begins, by substituting '2002' for '1992'.
Inserted: "(D) Rounding.--If any amount as adjusted under subparagraph (C) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50.
Inserted: "(c) Dependents Not Eligible for Credit.--No credit shall be allowed by this section to an individual for the taxable year if a deduction under section 151 with respect to such individual is allowed to another taxpayer for the taxable year beginning in the calendar year in which such individual's taxable year begins.
Inserted: "(d) Limit on Period Credit Allowed.--A credit shall be allowed under this section only with respect to interest paid on any qualified education loan during the first 60 months (whether or not consecutive) in which interest payments are required. For purposes of this paragraph, any loan and all refinancings of such loan shall be treated as 1 loan.
Inserted: "(e) Definitions.--For purposes of this section--
Inserted: "(1) Qualified education loan.--The term 'qualified education loan' has the meaning given such term by section 221(e)(1).
Inserted: "(2) Dependent.--The term 'dependent' has the meaning given such term by section 152.
Inserted: "(f) Special Rules.--
Inserted: "(1) Denial of double benefit.--No credit shall be allowed under this section for any amount taken into account for any deduction under any other provision of this chapter.
Inserted: "(2) Married couples must file joint return.--If the taxpayer is married at the close of the taxable year, the credit shall be allowed under subsection (a) only if the taxpayer and the taxpayer's spouse file a joint return for the taxable year.
Inserted: "(3) Marital status.--Marital status shall be determined in accordance with section 7703.".
Inserted: (2) Conforming amendment.--The table of sections for subpart A of part IV of subchapter A of chapter 1 is amended by inserting after the item relating to section 25B the following new item:
Inserted: "Sec. 25C. Interest on higher education loans.".
Inserted: (3) Effective date.--The amendments made by this subsection shall apply to any qualified education loan (as defined in section 25C(e)(1) of the Internal Revenue Code of 1986, as added by this section) incurred on, before, or after the date of the enactment of this Act, but only with respect to any loan interest payment due after December 31, 2002 and before January 1, 2009.
Inserted: (c) Elimination of 20 Percent Dividend Exclusion.--
Inserted: (1) In general.--Subparagraph (B) of section 116(a)(2) (relating to partial exclusion of received by individuals), as added by section 201 of this Act, is amended by striking "(20 percent in the case of taxable years beginning after 2007)".
Inserted: (2) Effective date.--The amendment made by this subsection shall apply to taxable years beginning after December 31, 2003.
Original wording
At the end of subtitle C of title V, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 558. Mr. SCHUMER (for himself, Mr. Biden, Mrs. Boxer, Mr. Durbin, and Ms. Cantwell) submitted an amendment intended to be proposed by him to the bill S. 1054, to provide for reconciliation pursuant to section 201 of the concurrent resolution on the budget for fiscal year 2004; which was ordered to lie on the table; as follows:
At the end of subtitle C of title V, insert the following:
SEC. ____. EXPANSION OF DEDUCTION FOR HIGHER EDUCATION EXPENSES.
(a) In General.--
(1) Amount of deduction.--Subsection (b) of section 222 (relating to deduction for qualified tuition and related expenses) is amended to read as follows:
“(b) Limitations.--
“(1) Dollar limitations.--
“(A) In general.--Except as provided in paragraph (2), the amount allowed as a deduction under subsection (a) with respect to the taxpayer for any taxable year shall not exceed the applicable dollar limit.
“(B) Applicable dollar limit.--The applicable dollar limit for any taxable year shall be determined as follows:
Applicable
“Taxable year: dollar amount:
2003......................................................$8,000 ....
2004 and thereafter......................................$12,000.....
“(2) Limitation based on modified adjusted gross income.--
“(A) In general.--The amount which would (but for this paragraph) be taken into account under subsection (a) shall be reduced (but not below zero) by the amount determined under subparagraph (B).
“(B) Amount of reduction.--The amount determined under this subparagraph equals the amount which bears the same ratio to the amount which would be so taken into account as--
“(i) the excess of--
“(I) the taxpayer's modified adjusted gross income for such taxable year, over
“(II) $65,000 ($130,000 in the case of a joint return), bears to
“(ii) $15,000 ($30,000 in the case of a joint return).
“(C) Modified adjusted gross income.--For purposes of this paragraph, the term ‘modified adjusted gross income' means the adjusted gross income of the taxpayer for the taxable year determined--
“(i) without regard to this section and sections 911, 931, and 933, and
“(ii) after the application of sections 86, 135, 137, 219, 221, and 469. For purposes of the sections referred to in clause (ii), adjusted gross income shall be determined without regard to the deduction allowed under this section.
“(D) Inflation adjustments.--
“(i) In general.--In the case of any taxable year beginning in a calendar year after 2003, both of the dollar amounts in subparagraph (B)(i)(II) shall be increased by an amount equal to--
“(I) such dollar amount, multiplied by
“(II) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting ‘calendar year 2002' for ‘calendar year 1992' in subparagraph (B) thereof.
“(ii) Rounding.--If any amount as adjusted under clause (i) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50.”.
(2) Qualified tuition and related expenses of eligible students.--
(A) In general.--Section 222(a) (relating to allowance of deduction) is amended by inserting “of eligible students” after “expenses”.
(B) Definition of eligible student.--Section 222(d) (relating to definitions and special rules) is amended by redesignating paragraphs (2) through (6) as paragraphs (3) through (7), respectively, and by inserting after paragraph (1) the following new paragraph:
“(2) Eligible student.--The term ‘eligible student' has the meaning given such term by section 25A(b)(3).”.
(3) Effective date.--The amendments made by this subsection shall apply to payments made in taxable years beginning after December 31, 2002 and before January 1, 2009.
(b) Interest on Higher Education Loans.--
(1) In general.--Subpart A of part IV of subchapter A of chapter 1 (relating to nonrefundable personal credits) is amended by inserting after section 25B the following new section:
“SEC. 25C. INTEREST ON HIGHER EDUCATION LOANS.
“(a) Allowance of Credit.--In the case of an individual, there shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to the interest paid by the taxpayer during the taxable year on any qualified education loan.
“(b) Maximum Credit.--
“(1) In general.--Except as provided in paragraph (2), the credit allowed by subsection (a) for the taxable year shall not exceed $1,500.
“(2) Limitation based on modified adjusted gross income.--
“(A) In general.--If the modified adjusted gross income of the taxpayer for the taxable year exceeds $50,000 ($100,000 in the case of a joint return), the amount which would (but for this paragraph) be allowable as a credit under this section shall be reduced (but not below zero) by the amount which bears the same ratio to the amount which would be so allowable as such excess bears to $20,000 ($40,000 in the case of a joint return).
“(B) Modified adjusted gross income.--The term ‘modified adjusted gross income' means adjusted gross income determined without regard to sections 911, 931, and 933.
“(C) Inflation adjustment.--In the case of any taxable year beginning after 2003, the $50,000 and $100,000 amounts referred to in subparagraph (A) shall be increased by an amount equal to--
“(i) such dollar amount, multiplied by
“(ii) the cost-of-living adjustment determined under section (1)(f)(3) for the calendar year in which the taxable year begins, by substituting ‘2002' for ‘1992'.
“(D) Rounding.--If any amount as adjusted under subparagraph (C) is not a multiple of $50, such amount shall be rounded to the nearest multiple of $50.
“(c) Dependents Not Eligible for Credit.--No credit shall be allowed by this section to an individual for the taxable year if a deduction under section 151 with respect to such individual is allowed to another taxpayer for the taxable year beginning in the calendar year in which such individual's taxable year begins.
“(d) Limit on Period Credit Allowed.--A credit shall be allowed under this section only with respect to interest paid on any qualified education loan during the first 60 months (whether or not consecutive) in which interest payments are required. For purposes of this paragraph, any loan and all refinancings of such loan shall be treated as 1 loan.
“(e) Definitions.--For purposes of this section--
“(1) Qualified education loan.--The term ‘qualified education loan' has the meaning given such term by section 221(e)(1).
“(2) Dependent.--The term ‘dependent' has the meaning given such term by section 152.
“(f) Special Rules.--
“(1) Denial of double benefit.--No credit shall be allowed under this section for any amount taken into account for any deduction under any other provision of this chapter.
“(2) Married couples must file joint return.--If the taxpayer is married at the close of the taxable year, the credit shall be allowed under subsection (a) only if the taxpayer and the taxpayer's spouse file a joint return for the taxable year.
“(3) Marital status.--Marital status shall be determined in accordance with section 7703.”.
(2) Conforming amendment.--The table of sections for subpart A of part IV of subchapter A of chapter 1 is amended by inserting after the item relating to section 25B the following new item:
“Sec. 25C. Interest on higher education loans.”.
(3) Effective date.--The amendments made by this subsection shall apply to any qualified education loan (as defined in section 25C(e)(1) of the Internal Revenue Code of 1986, as added by this section) incurred on, before, or after the date of the enactment of this Act, but only with respect to any loan interest payment due after December 31, 2002 and before January 1, 2009.
(c) Elimination of 20 Percent Dividend Exclusion.--
(1) In general.--Subparagraph (B) of section 116(a)(2) (relating to partial exclusion of received by individuals), as added by section 201 of this Act, is amended by striking “(20 percent in the case of taxable years beginning after 2007)”.
(2) Effective date.--The amendment made by this subsection shall apply to taxable years beginning after December 31, 2003.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
May 14, 2003