To reinstate for millionaires a top individual income tax rate of 39.6 percent, the pre-May 2003 rates of tax on capital gains and dividends, and to repeal the reduction and termination of the phase out of personal exemptions and overall limitation on itemized deductions, until the Federal budget deficit is eliminated.
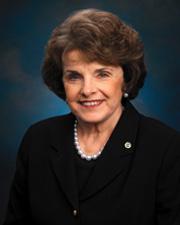 Sen. Dianne Feinstein (D-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
November 17, 2005
View full timeline
Senate amendment submitted
November 17, 2005
Roll call votes on amendments in Senate: Motion to waive the Budget Act with respect to amendment SA 2610 rejected in Senate by Yea-Nay Vote. 40 - 59. Record Vote Number: 333.
November 17, 2005
Senate amendment proposed (on the floor): Amendment SA 2610 proposed by Senator Feinstein.
November 17, 2005
Amendment SA 2610 proposed by Senator Feinstein. (consideration: CR S13081-13085, S13089-13090, S13102-13103; text: CR S13082) To reinstate for millionaires a top individual income tax rate of 39.6 percent, the pre-May 2003 rates of tax on capital gains and dividends, and to repeal the reduction and termination of the phase out of personal exemptions and overall limitation on itemized deductions, until the Federal budget deficit is eliminated.
November 17, 2005
Point of order raised in Senate with respect to amendment SA 2610.
November 17, 2005
Motion to waive the Budget Act with respect to amendment SA 2610 rejected in Senate by Yea-Nay Vote. 40 - 59. Record Vote Number: 333.
November 17, 2005
Amendment SA 2610 ruled out of order by the chair.
November 17, 2005
Votes
1 roll call on this amendment
Text
Submitted
SA 2610. Mrs. FEINSTEIN (for herself and Mr. Kerry) proposed an
amendment to the bill S. 2020, to provide for reconciliation pursuant
to section 202(b) of the concurrent resolution on the budget for fiscal
year 2006; as follows:

At the end of the bill, insert the following:

SEC. __. REINSTATEMENT FOR MILLIONAIRES OF 39.6 PERCENT
INCOME TAX RATE, PRE-MAY 2003 CAPITAL GAIN AND
DIVIDEND RATES, AND DEDUCTION LIMITATIONS UNTIL
BUDGET DEFICIT ELIMINATED.

(a) Repeal of Top Income Tax Rate Reductions.--
(1) In general.--Section 1(i) (relating to rate reductions)
is amended by redesignating paragraph (3) as paragraph (4)
and by inserting after paragraph (2) the following new
paragraph:
``(3) Exception for taxpayers with taxable income of
$1,000,000, or more.--Notwithstanding paragraph (2), in the
case of taxable years beginning in a calender year after
2005, the last item in the fourth column of the table under
paragraph (2) shall be applied by substituting `39.6%' for
`35.0%' with respect to taxable income in excess of
$1,000,000 ($500,000 in the case of taxpayers to whom
subsection (d) applies).''.
(2) Effective date.--The amendment made by this subsection
shall apply to taxable years beginning after December 31,
2005.
(3) Application of egtrra sunset.--The amendment made by
this subsection shall be subject to title IX of the Economic
Growth and Tax Relief Reconciliation Act of 2001 to the same
extent and in the same manner as the provision of such Act to
which such amendment relates.
(b) Restoration of Pre-May 2003 Tax Rates on Capital Gains
and Dividends for Individuals In Top Rate Bracket.--
(1) In general.--Section 1(h) is amended by adding at the
end the following new paragraph:
``(12) Increased rates for individuals in the top rate
bracket.--
``(A) Dividends.--In no event shall the qualified dividend
income of a taxpayer for any taxable year exceed the excess
(if any) of--
``(i) the minimum dollar amount to which the 39.6 rate
applies under subsection (i) for the taxable year, over
``(ii) taxable income, reduced by adjusted net capital gain
(determined without regard to this paragraph).
``(B) Capital gains.--If a taxpayer has a net capital gain
for any taxable year, the taxpayer's tax shall be increased
by an amount equal to 5 percent of the lesser of--
``(i) the taxpayer's adjusted net capital gain, determined
after application of subparagraph (A) and by only taking into
account gain or loss properly allocable to the portion of the
taxable year after December 31, 2005, or
``(ii) taxable income in excess of the minimum dollar
amount to which the 39.6 rate applies under subsection (i)
for the taxable year.''
(2) Application to minimum tax.--Section 55(b)(3) is
amended by adding at the end the following new sentence:
``The rules of section 1(h)(12) shall apply for purposes of
this paragraph.''
(3) Effective dates.--
(A) Capital gains.--Section 1(h)(12)(B) of the Internal
Revenue Code of 1986 (as added by paragraph (1)) shall apply
to taxable years beginning after December 31, 2005.
(B) Dividend rates.--Section 1(h)(12)(A) of such Code (as
added by paragraph (1)) shall apply to dividends received
after December 31, 2005.
(4) Application of jgtrra sunset.--The amendment made by
this subsection shall be subject to section 303 of the Jobs
and Growth Tax Relief Reconciliation Act of 2003 to the same
extent and in the same manner as the provision of such Act to
which such amendment relates.
(c) Repeal of the Scheduled Phase Out and Termination of
the Limitations on Personal Exemptions and Itemized
Deductions.--
(1) Repeal.--
(A) Personal exemptions.--Section 1(d)(3) is amended by
adding at the end the following:
``(6) Reduction of phase out and termination not to
apply.--Subparagraphs (E) and (F) shall not apply to a
taxpayer whose adjusted gross income for the taxable year
exceeds $1,000,000 ($500,000 in the case of a married
individual filing a separate return).''
(B) Itemized deductions.--Section 68 is amended by adding
at the end the following:
``(h) Reduction of Phase Out and Termination Not to
Apply.--Subsections (f) and (g) shall not apply to a taxpayer
whose adjusted gross income for the taxable year exceeds
$1,000,000 ($500,000 in the case of a married individual
filing a separate return).''
(2) Effective date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.
(3) Application of egtrra sunset.--The amendments made by
this section shall be subject to title IX of the Economic
Growth and Tax Relief Reconciliation Act of 2001 to the same
extent and in the same manner as the provision of such Act to
which such amendment relates.
(d) Sunset of Amendments if Budget Deficit Eliminated.--
(1) In general.--The amendments made by this section shall
not apply to taxable years beginning after the first calendar
year for which the certification described in paragraph
(2)(B) is made.
(2) Estimates and certification.--
(A) In general.--Not later than October 15 of each calendar
year beginning after 2005, the Director of the Office of
Management and Budget, in consultation with the Secretary of
the Treasury, shall estimate--
(i) the Federal budget deficit for the fiscal year ending
in the calendar year, and
(ii) the Federal budget deficit for the fiscal year
beginning in the calendar year (determined as if the
amendments made by this section were not in effect for
taxable years beginning in the following calendar year).
(B) Certification.--The Director of the Office of
Management and Budget shall certify to the President of the
United States and to the Congress the first calendar year for
which the Director estimates under subparagraph (A) that
there will be no Federal budget deficit for both of the
fiscal years for which the estimate was made.
______