To express the sense of the Senate that protecting middle-class families from the alternative minimum tax should be a higher priority for Congress in 2006 than extending a tax cut that does not expire until the end of 2008.
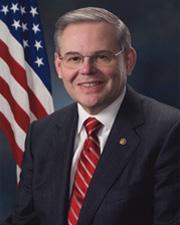 Sen. Robert Menendez (D-NJ)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
February 2, 2006
View full timeline
Senate amendment submitted
February 2, 2006
Senate amendment proposed (on the floor): Amendment SA 2705 proposed by Senator Menendez to Amendment SA 2707.(consideration: CR S496-498; text: CR S496)
February 2, 2006
Senate amendment agreed to: Amendment SA 2705 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 9.
February 2, 2006
Roll call votes on amendments in Senate: Amendment SA 2705 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 9.
February 2, 2006
Amendment SA 2705 proposed by Senator Menendez to Amendment SA 2707. (consideration: CR S496-498; text: CR S496) To express the sense of the Senate that protecting middle-class families from the alternative minimum tax should be a higher priority for Congress in 2006 than extending a tax cut that does not expire until the end of 2008.
February 2, 2006
Amendment SA 2705 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 9.
February 2, 2006
Votes
1 roll call on this amendment
Text
Submitted
SA 2705. Mr. MENENDEZ (for himself, Mr. Schumer, Mr. Kerry, Mrs.
Feinstein, Mrs. Clinton, Mr. Lautenberg, and Ms. Stabenow) submitted an
amendment intended to be proposed to amendment SA 2707 proposed by Mr.
Frist (for Mr. Grassley (for himself and Mr. Baucus)) to the bill H.R.
4297, to provide for reconciliation pursuant to section 201(b) of the
concurrent resolution on the budget for fiscal year 2006; as follows:

At the appropriate place, insert the following:

SEC. __. SENSE OF THE SENATE REGARDING PROTECTING MIDDLE-
CLASS FAMILIES FROM THE ALTERNATIVE MINIMUM
TAX.

(a) Findings.--The Senate finds that--
(1) the alternative minimum tax was originally enacted in
1969 as a supplemental tax on wealthy tax evaders, but has
evolved into a tax on millions of middle-class working
families, particularly families in which both parents work,
and families with 2 or more children;
(2) by the end of the decade, the alternative minimum tax
will ensnare more than 30,000,000 taxpayers, the majority of
which will have adjusted gross incomes below $100,000, and
the National Taxpayer Advocate has thus identified it as the
most serious problem facing individual taxpayers;
(3) the alternative minimum tax is often portrayed as a tax
that is most problematic for residents of States such as New
York, California, Massachusetts, and New Jersey, but the
truth is that many other States have a significant percentage
of taxpayers affected by the alternative minimum tax,
including Oregon, Maryland, Virginia, Minnesota, Ohio, Maine,
Georgia, North Carolina, and Pennsylvania, so the problem is
of national importance;
(4) a family with 2 children will become subject to the
alternative minimum tax at about $67,500 of income in 2006,
and a family with 5 children will start owing the alternative
minimum tax at about $54,000 of income, if Congress fails to
act;

[[Page S517]]

(5) the year 2006 is the ``tipping point'' for the
alternative minimum tax, as the number of taxpayers affected
nationally will explode from 3,600,000 to 19,000,000 if
Congress fails to act;
(6) in 2004, only 6.2 percent of families earning $100,000
to $200,000 a year were subject to the alternative minimum
tax, and that number will explode to nearly 50 percent if
Congress fails to act;
(7) if alternative minimum tax relief is extended through
2006, about two-thirds of the benefits will be realized by
families earning under $200,000, with more than half of the
total benefits going to families with incomes between
$100,000 and $200,000;
(8) starting in 2008, the average married couple with 2
children earning $75,000 or more will find that more than
half of the tax cuts they have been expecting from the
various laws passed since 2001 will be ``taken back'' via the
alternative minimum tax; and
(9) the temporary relief from the alternative minimum tax
(provided in 2001 and extended twice in 2003 and 2004)
expired at the end of 2005, but the tax reductions on
dividends and capital gains do not expire until the end of
2008, making immediate action on those provisions a less
urgent matter.
(b) Sense of the Senate.--It is the sense of the Senate
that protecting middle-class families from the alternative
minimum tax should be a higher priority for Congress in 2006
than extending a tax cut that does not expire until the end
of 2008.
______