To address the treatment of primary mortgages in bankruptcy, and for other purposes.
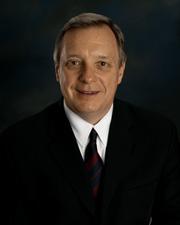 Sen. Richard J. Durbin (D-IL)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
April 3, 2008
View full timeline
Senate amendment submitted
April 3, 2008
Senate amendment proposed (on the floor): Amendment SA 4388 proposed by Senator Durbin to Amendment SA 4387.(consideration: CR S2370-2371, S2375-2380, S2380-2396, S2402-2403)
April 3, 2008
Roll call votes on amendments in Senate: Motion to table amendment SA 4388 agreed to in Senate by Yea-Nay Vote. 58 - 36. Record Vote Number: 88.
April 3, 2008
Amendment SA 4388 proposed by Senator Durbin to Amendment SA 4387. (consideration: CR S2370-2371, S2375-2380, S2380-2396, S2402-2403) To address the treatment of primary mortgages in bankruptcy, and for other purposes.
April 3, 2008
Motion to table amendment SA 4388 agreed to in Senate by Yea-Nay Vote. 58 - 36. Record Vote Number: 88.
April 3, 2008
Votes
1 roll call on this amendment
Text
Submitted
SA 4388. Mr. DURBIN (for himself, Mr. Reid, Mr. Obama, Mrs. Clinton,
Mr. Whitehouse, Mr. Schumer, Mrs. Feinstein, Mr. Menendez, Mrs. Boxer,
Mr. Brown, Mr. Kennedy, Mr. Harkin, Mr. Kerry, Mr. Reed, and Mr. Biden)
submitted an amendment intended to be proposed to amendment SA 4387
submitted by Mr. Dodd (for himself and Mr. Shelby) to the bill H.R.
3221, moving the United States toward greater energy independence and
security, developing innovative new technologies, reducing carbon
emissions, creating green jobs, protecting consumers, increasing clean
renewable energy production, and modernizing our energy infrastructure,
and to amend the Internal Revenue Code of 1986 to provide tax
incentives for the production of renewable energy and energy
conservation; which was ordered to lie on the table; as follows:

At the end, add the following:

TITLE __--BANKRUPTCY

SEC. __1. SHORT TITLE.

This title may be cited as the ``Helping Families Save
Their Homes in Bankruptcy Act of 2008''.

Subtitle A--Minimizing Foreclosures

SEC. __21. DEFINITIONS.

Section 101 of title 11, United States Code, is amended--
(1) by redesignating paragraphs (40A) and (40B) as
paragraphs (40B) and (40C), respectively;
(2) by inserting after paragraph (40) the following:
``(40A) The term `nontraditional mortgage' means a security
interest in the debtor's principal residence that secures a
debt for a loan that at any period during the term of the
loan provides for the deferral of payment of principal or
interest through permitting periodic payments that do not
cover the full amount of interest due or that cover only the
interest due, except that such term excludes--
``(A) a loan that at any period during the term of the loan
provides for the deferral of payment of principal through
permitting periodic payments that cover only the interest
due, if the creditor demonstrates that it determined in good
faith at the time the loan was consummated, after undergoing
a

[[Page S2496]]

full underwriting process based on verified and documented
information, that the debtor had a reasonable ability to
repay at the full interest and principal payment amount
(assuming an initial 30 year full amortization), and payments
under the loan resulted in a debt-to-income ratio of the
debtor in an amount equal to or less than that which would
have been permitted under guidelines and directives
established by the Secretary of Housing and Urban Development
pursuant to section 203.33 of title 24, Code of Federal
Regulations, for loans subject to such section;
``(B) a home equity line of credit that is in a subordinate
lien position; and
``(C) a reverse mortgage.'';
(3) by redesignating paragraphs (53B) through (53D) as
paragraphs (53C), (53D), (53E), and (53F), respectively; and
(4) by inserting after paragraph (53A) the following:
``(53B) The term `subprime mortgage' means a security
interest in the debtor's principal residence that secures a
debt for a loan that has an annual percentage rate that is
greater than--
``(A) the sum of 3 percent plus the yield on United States
Treasury securities having comparable periods of maturity, if
the loan is secured by a first mortgage or first deed of
trust; or
``(B) the sum of 5 percent plus the yield on United States
Treasury securities having comparable periods of maturity, if
the loan is secured by a subordinate mortgage or subordinate
deed of trust.

Without regard to whether such loan is subject to or
reportable under the Home Mortgage Disclosure Act, the
difference between the annual percentage rate of such loan
and the yield on United States Treasury securities having
comparable periods of maturity shall be determined using the
procedures and calculation methods applicable to loans that
are subject to the reporting requirements of such Act, except
that such yield shall be determined as of the 15th day of the
month preceding the month in which a completed application is
submitted for such loan. If such loan provides for a fixed
interest rate for an introductory period and then resets or
adjusts to a variable interest rate, the determination of the
annual percentage rate shall be based on the greater of the
introductory rate and the fully indexed rate. For purposes of
this paragraph, the term `fully indexed rate' means the
prevailing index rate on a residential mortgage loan at the
time at which the loan is made, plus the margin that will
apply after the expiration of an introductory interest
rate.''.

SEC. __22. SPECIAL RULES FOR MODIFICATION OF LOANS SECURED BY
RESIDENCES.

(a) In General.--Section 1322(b) of title 11, United States
Code, is amended--
(1) in paragraph (10), by striking ``and'' at the end;
(2) by redesignating paragraph (11) as paragraph (12); and
(3) by inserting after paragraph (10) the following:
``(11) notwithstanding paragraph (2) and otherwise
applicable nonbankruptcy law--
``(A) modify an allowed secured claim for a debt incurred
prior to the effective date of this paragraph secured by a
nontraditional mortgage, or a subprime mortgage, and any lien
subordinate to such claim, on the debtor's principal
residence, as described in subparagraph (B), if, after
deduction from the debtor's current monthly income of the
expenses permitted for debtors described in section
1325(b)(3) of this title (other than amounts contractually
due to creditors holding such allowed secured claims and
additional payments necessary to maintain possession of that
residence), the debtor has insufficient remaining income to
retain possession of the residence by curing a default and
maintaining payments while the case is pending, as provided
under paragraph (5);
``(B) provide for payment of such claim--
``(i) in an amount equal to the amount of the allowed
secured claim;
``(ii) for a period that is the longer of 30 years (reduced
by the period for which the loan has been outstanding) or the
remaining term of such loan, beginning on the date of the
order for relief under this chapter; and
``(iii) at a rate of interest accruing after such date
calculated at a fixed annual percentage rate, in an amount
equal to the most recently published annual yield on
conventional mortgages published by the Board of Governors of
the Federal Reserve System, as of the applicable time set
forth in the rules of the Board, plus a reasonable premium
for risk; and
``(C) if a claim has been modified to an amount below the
original principal of the loan pursuant to subparagraph
(B)(i) and the debtor's principal residence is sold during
the term of the plan, the holder of the claim shall be
entitled to receive, in addition to the unpaid portion of the
allowed secured claim, the net proceeds of the sale, or the
amount of the holder's allowed unsecured claim, whichever is
less; and''.
(b) Conforming Amendment.--Section 1325(a)(5) of title 11,
United States Code, is amended by inserting before ``with
respect'' the following: ``except as otherwise provided in
section 1322(b)(11) of this title,''.

SEC. __23. WAIVER OF COUNSELING REQUIREMENT WHEN HOMES ARE IN
FORECLOSURE.

Section 109(h) of title 11, United States Code, is amended
by adding at the end the following:
``(5) Paragraph (1) shall not apply with respect to a
debtor who files with the court a certification that a
foreclosure sale of the debtor's principal residence has been
scheduled.''.

Subtitle B--Providing Other Debtor Protections

SEC. __41. COMBATING EXCESSIVE FEES.

Section 1322(c) of title 11, the United States Code, is
amended--
(1) in paragraph (1), by striking ``and'' at the end;
(2) in paragraph (2), by striking the period at the end and
inserting a semicolon; and
(3) by adding at the end the following:
``(3) the plan need not provide for the payment of, and the
debtor, the debtor's property, and property of the estate
shall not be liable for, any fee, cost, or charge,
notwithstanding section 506(b), that arises in connection
with a claim secured by the debtor's principal residence if
the event that gives rise to such fee, cost, or charge occurs
while the case is pending but before the discharge order,
except to the extent that--
``(A) notice of such fees, costs or charges is filed with
the court, and served on the debtor and the trustee, before
the expiration of the earlier of--
``(i) 1 year after the event that gives rise to such fee,
cost, or charge occurs; or
``(ii) 60 days before the closing of the case; and
``(B) such fees, costs, or charges are lawful, reasonable,
and provided for in the agreement under which such claim or
security interest arose;
``(4) the failure of a party to give notice described in
paragraph (3) shall be deemed a waiver of any claim for fees,
costs, or charges described in paragraph (3) for all
purposes, and any attempt to collect such fees, costs, or
charges shall constitute a violation of section 524(a)(2) of
this title or, if the violation occurs before the date of
discharge, of section 362(a) of this title; and
``(5) a plan may provide for the waiver of any prepayment
penalty on a claim secured by the principal residence of the
debtor.''.

SEC. __42. MAINTAINING DEBTORS' LEGAL CLAIMS.

Section 554(e) of title 11, United States Code, is amended
by adding at the end the following:
``(e) In any action in State or Federal court with respect
to a claim or defense asserted by an individual debtor in
such action that was not scheduled under section 521(a)(1) of
this title, the trustee shall be allowed a reasonable time to
request joinder or substitution as the real party in
interest. If the trustee does not request joinder or
substitution in such action, the debtor may proceed as the
real party in interest, and no such action shall be dismissed
on the ground that it is not prosecuted in the name of the
real party in interest or on the ground that the debtor's
claims were not properly scheduled in a case under this
title.''.

SEC. __43. RESOLVING DISPUTES.

Section 1334 of title 28, United States Code, is amended by
adding at the end the following: ``Notwithstanding any
agreement for arbitration that is subject to chapter 1 of
title 9, in any core proceeding under section 157(b) of this
title involving an individual debtor whose debts are
primarily consumer debts, the court may hear and determine
the proceeding, and enter appropriate orders and judgments,
in lieu of referral to arbitration.''.

SEC. __44. ENACTING A HOMESTEAD FLOOR FOR DEBTORS OVER 55
YEARS OF AGE.

(a) In General.--Section 522(b)(3) of title 11, United
States Code, is amended--
(1) in subparagraph (B), by striking ``and'' at the end;
(2) in subparagraph (C), by striking the period at the end
and inserting ``; and''; and
(3) by adding at the end and inserting the following:
``(D) if the debtor, as of the date of the filing of the
petition, is 55 years old or older, the debtor's aggregate
interest, not to exceed $75,000 in value, in real property or
personal property that the debtor or a dependent of the
debtor uses as a principal residence, or in a cooperative
that owns property that the debtor or a dependent of the
debtor uses as a principal residence.''.
(b) Exemption Authority.--Section 522(d)(1) of title 11,
United States Code, is amended by inserting ``or, if the
debtor is 55 years of age or older, $75,000 in value,''
before ``in real property''.

SEC. __45. DISALLOWING CLAIMS FROM VIOLATIONS OF CONSUMER
PROTECTION LAWS.

Section 502(b) of title 11, United States Code, is
amended--
(1) in paragraph (8), by striking ``or'' at the end;
(2) in paragraph (9), by striking the period at the end and
inserting ``; or''; and
(3) by adding at the end the following:
``(10) the claim is subject to any remedy for damages or
rescission due to failure to comply with any applicable
requirement under the Truth in Lending Act (15 U.S.C. 1601 et
seq.), or any other provision of applicable State or Federal
consumer protection law that was in force when the
noncompliance took place, notwithstanding the prior entry of
a foreclosure judgment.''.
______