To amend the Internal Revenue Code of 1986 to allow companies to utilize existing alternative minimum tax credits to create and maintain American jobs through new domestic investments, and for other purposes.
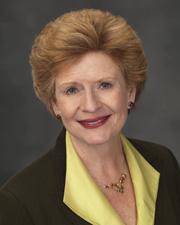 Sen. Debbie Stabenow (D-MI)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment agreed to: Amendment SA 3382 agreed to in Senate by Voice Vote.
March 4, 2010
View full timeline
Senate amendment agreed to: Amendment SA 3382 agreed to in Senate by Voice Vote.
March 4, 2010
Considered by Senate. (consideration: CR S1126, S1151)
March 4, 2010
Amendment SA 3382 agreed to in Senate by Voice Vote.
March 4, 2010
Senate amendment submitted
March 3, 2010
Senate amendment proposed (on the floor): Amendment SA 3382 proposed by Senator Stabenow to Amendment SA 3336.(consideration: CR S1001-1003; text: CR S1002-1003)
March 3, 2010
Amendment SA 3382 proposed by Senator Stabenow to Amendment SA 3336. (consideration: CR S1001-1003; text: CR S1002-1003) To amend the Internal Revenue Code of 1986 to allow companies to utilize existing alternative minimum tax credits to create and maintain American jobs through new domestic investments, and for other purposes.
March 3, 2010
Text
Submitted
SA 3382. Ms. STABENOW (for herself, Mr. Hatch, Mr. Schumer, Mr.
Crapo, Mr. Risch, Ms. Snowe, Mr. Brown of Ohio, and Mr. Enzi) submitted
an amendment intended to be proposed to amendment SA 3336 proposed by
Mr. Baucus to the bill H.R. 4213, to amend the Internal Revenue Code of
1986 to extend certain expiring provisions, and for other purposes; as
follows:

At the end of title VI, add the following:

SEC. 602. ELECTION TO TEMPORARILY UTILIZE UNUSED AMT CREDITS
DETERMINED BY DOMESTIC INVESTMENT.

(a) In General.--Section 53 is amended by adding at the end
the following new subsection:
``(g) Election for Corporations With Unused Credits.--
``(1) In general.--If a corporation elects to have this
subsection apply, then notwithstanding any other provision of
law, the limitation imposed by subsection (c) for any such
taxable year shall be increased by the AMT credit adjustment
amount.
``(2) AMT credit adjustment amount.--For purposes of
paragraph (1), the term `AMT credit adjustment amount' means
with respect to any taxable year beginning in 2010, the
lesser of--
``(A) 50 percent of a corporation's minimum tax credit
determined under subsection (b), or
``(B) 10 percent of new domestic investments made during
such taxable year.
``(3) New domestic investments.--For purposes of this
subsection, the term `new domestic investments' means the
cost of qualified property (as defined in section
168(k)(2)(A)(i))--
``(A) the original use of which commences with the taxpayer
during the taxable year, and
``(B) which is placed in service in the United States by
the taxpayer during such taxable year.
``(4) Credit refundable.--For purposes of subsections (b)
and (c) of section 6401, the aggregate increase in the
credits allowable under part IV of subchapter A for any
taxable year resulting from the application of this
subsection shall be treated as allowed under subpart C of
such part (and not to any other subpart).
``(5) Election.--
``(A) In general.--An election under this subsection shall
be made at such time and in such manner as prescribed by the
Secretary, and once effective, may be revoked only with the
consent of the Secretary.
``(B) Interim elections.--Until such time as the Secretary
prescribes a manner for making an election under this
subsection, a taxpayer is treated as having made a valid
election by providing written notification to the Secretary
and the Commissioner of Internal Revenue of such election.
``(6) Treatment of certain partnership investments.--For
purposes of this subsection, any corporation's allocable
share of any new domestic investments by a partnership more
than 90 percent of the capital and profits interest in which
is owned by such corporation (directly or indirectly) at all
times during the taxable year in which an election under this
subsection is in effect shall be considered new domestic
investments of such corporation for such taxable year.
``(7) No double benefit.--Notwithstanding clause (iii)(II)
of section 172(b)(1)(H), any taxpayer which has previously
made an election under such section shall be deemed to have
revoked such election by the making of its first election
under this subsection.
``(8) Regulations.--The Secretary may issue such
regulations or other guidance as may be necessary or
appropriate to carry out this subsection, including to
prevent fraud and abuse under this subsection.
``(9) Termination.--This subsection shall not apply to any
taxable year that begins after December 31, 2010.''.
(b) Quick Refund of Refundable Credit.--Section 6425 is
amended by adding at the end the following new subsection:
``(e) Allowance of AMT Credit Adjustment Amount.--The
amount of an adjustment under this section as determined
under subsection (c)(2) for any taxable year may be increased
to the extent of the corporation's AMT credit adjustment
amount determined under section 53(g) for such taxable
year.''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2009.

SEC. 603. INFORMATION REPORTING FOR RENTAL PROPERTY EXPENSE
PAYMENTS.

(a) In General.--Section 6041 is amended by adding at the
end the following new subsection:
``(h) Treatment of Rental Property Expense Payments.--
``(1) In general.--Solely for purposes of subsection (a)
and except as provided in paragraph (2), a person receiving
rental income from real estate shall be considered to be
engaged in a trade or business of renting property.
``(2) Exceptions.--Paragraph (1) shall not apply to--
``(A) any individual, including any individual who is an
active member of the uniformed services, if substantially all
rental income is derived from renting the principal residence
(within the meaning of section 121) of such individual on a
temporary basis,
``(B) any individual who receives rental income of not more
than the minimal amount, as determined under regulations
prescribed by the Secretary, and
``(C) any other individual for whom the requirements of
this section would cause hardship, as determined under
regulations prescribed by the Secretary.''.
(b) Effective Date.--The amendment made by this section
shall apply to payments made after December 31, 2010.
______