To index tax thresholds imposed under the legislation to prevent the government from using inflation to impose those taxes on individuals currently making less than $200,000 and families making less than $250,000.
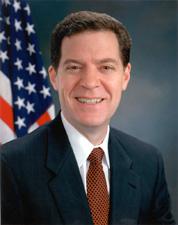 Sen. Sam Brownback (R-KS)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 3697 proposed by Senator Brownback.(consideration: CR S2074-2075; text: CR S2074)
March 25, 2010
View full timeline
Senate amendment proposed (on the floor): Amendment SA 3697 proposed by Senator Brownback.(consideration: CR S2074-2075; text: CR S2074)
March 25, 2010
Roll call votes on amendments in Senate: Motion to table amendment SA 3697 agreed to in Senate by Yea-Nay Vote. 56 - 42. Record Vote Number: 98.
March 25, 2010
Amendment SA 3697 proposed by Senator Brownback. (consideration: CR S2074-2075; text: CR S2074) To index tax thresholds imposed under the legislation to prevent the government from using inflation to impose those taxes on individuals currently making less than $200,000 and families making less than $250,000.
March 25, 2010
Motion to table amendment SA 3697 agreed to in Senate by Yea-Nay Vote. 56 - 42. Record Vote Number: 98.
March 25, 2010
Senate amendment submitted
March 24, 2010
Votes
1 roll call on this amendment
Text
Submitted
SA 3697. Mr. BROWNBACK submitted an amendment intended to be proposed
by him to the bill H.R. 4872, to provide for reconciliation pursuant to
Title II of the concurrent resolution on the budget for fiscal year
2010 (S. Con. Res. 13); which was ordered to lie on the table; as
follows:

At the end of section 1402(a), insert the following:
(5) Inflation adjustment.--Section 1411 of the Internal
Revenue Code of 1986, as added by paragraph (1), is amended
by adding at the end the following new subsection:
``(f) Adjustment for Inflation.--In the case of any taxable
year beginning after December 31, 2013, each of the dollar
amounts under paragraphs (1) and (3) of subsection (b),
subparagraphs (A) and (C) of section 3101(b)(2), and clauses
(i) and (iii) of section 1401(b)(2)(A) shall be increased by
an amount equal to--
``(1) such amount, multiplied by
``(2) the cost-of-living adjustment determined under
section 1(f)(3) for the calendar year in which such taxable
year begins by substituting `calendar year 2012' for
`calendar year 1992' in subparagraph (B) thereof.
If any increase determined under this subsection is not a
multiple of $1,000, such increase shall be rounded to the
next lowest multiple of $1,000.''.
______