To amend the Internal Revenue Code of 1986 to extend the time for closing on a principal residence eligible for the first-time homebuyer credit.
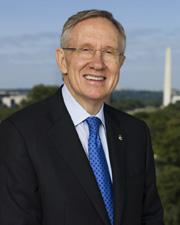 Sen. Harry Reid (D-NV)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 4344 proposed by Senator Reid, previously proposed to SA 4301 and subsequently withdrawn, notwithstanding the impendency of a motion to concur in the House amendment to the Senate amendment to H.R. 4213 with an amendment (SA 4369), by Unanimous Consent.(consideration: CR S4969-4971; text: CR S4970)
June 16, 2010
View full timeline
Senate amendment proposed (on the floor): Amendment SA 4344 proposed by Senator Reid, previously proposed to SA 4301 and subsequently withdrawn, notwithstanding the impendency of a motion to concur in the House amendment to the Senate amendment to H.R. 4213 with an amendment (SA 4369), by Unanimous Consent.(consideration: CR S4969-4971; text: CR S4970)
June 16, 2010
Roll call votes on amendments in Senate: Amendment SA 4344 agreed to in Senate by Yea-Nay Vote. 60 - 37. Record Vote Number: 191.
June 16, 2010
Senate amendment agreed to: Amendment SA 4344 agreed to in Senate by Yea-Nay Vote. 60 - 37. Record Vote Number: 191.
June 16, 2010
Considered by Senate. (consideration: CR S4958)
June 16, 2010
SA 4344 fell when SA 4301 withdrawn. (consideration: CR S4959)
June 16, 2010
Amendment SA 4344 proposed by Senator Reid, previously proposed to SA 4301 and subsequently withdrawn, notwithstanding the impendency of a motion to concur in the House amendment to the Senate amendment to H.R. 4213 with an amendment (SA 4369), by Unanimous Consent. (consideration: CR S4969-4971; text: CR S4970)
June 16, 2010
Amendment SA 4344 agreed to in Senate by Yea-Nay Vote. 60 - 37. Record Vote Number: 191.
June 16, 2010
Amendment SA 4344, previously proposed notwithstanding the impendency of the motion to concur in the House amendment to the Senate amendment to the bill (H.R. 4213), and subsequently agreed to, is considered to have been proposed to and incorporated into amendment SA 4369, pursuant to the order of 6/15/2010.
June 16, 2010
Considered by Senate. (consideration: CR S4914)
June 15, 2010
Senate amendment submitted
June 14, 2010
Amendment SA 4344 proposed by Senator Reid to Amendment SA 4301. (consideration: CR S4877-4878; text: CR S4877) To amend the Internal Revenue Code of 1986 to extend the time for closing on a principal residence eligible for the first-time homebuyer credit.
June 14, 2010
Votes
1 roll call on this amendment
Text
Submitted
SA 4344. Mr. REID proposed an amendment to amendment SA 4301 proposed
by Mr. Baucus to the bill H.R. 4213, to amend the Internal Revenue Code
of 1986 to extend certain expiring provisions, and for other purposes;
as follows:

At the end of part I of subtitle B of title II, insert the
following:

SEC. --. FIRST-TIME HOMEBUYER CREDIT.

(a) In General.--Paragraph (2) of section 36(h) is amended
by striking ``paragraph (1) shall be applied by substituting
`July 1, 2010' '' and inserting ``and who purchases such
residence before October 1, 2010, paragraph (1) shall be
applied by substituting `October 1, 2010' ''.
(b) Conforming Amendment.--Subparagraph (B) of section
36(h)(3) is amended by inserting ``and for `October 1, 2010'
'' after ``for `July 1, 2010' ''.
(c) Effective Date.--The amendments made by subsections (a)
and (b) shall apply to residences purchased after June 30,
2010.
(d) Offset.--
(1) Disallowance of deduction for punitive damages.--
(A) In general.--Section 162(g) (relating to treble damage
payments under the antitrust laws) is amended--
(i) by redesignating paragraphs (1) and (2) as
subparagraphs (A) and (B), respectively,
(ii) by striking ``If'' and inserting:
``(1) Treble damages.--If'', and
(iii) by adding at the end the following new paragraph:
``(2) Punitive damages.--No deduction shall be allowed
under this chapter for any amount paid or incurred for
punitive damages in connection with any judgment in, or
settlement of, any action. This paragraph shall not apply to
punitive damages described in section 104(c).''.
(B) Conforming amendment.--The heading for section 162(g)
is amended by inserting ``Or Punitive Damages'' after
``Laws''.
(2) Inclusion in income of punitive damages paid by insurer
or otherwise.--
(A) In general.--Part II of subchapter B of chapter 1
(relating to items specifically included in gross income) is
amended by adding at the end the following new section:

``SEC. 91. PUNITIVE DAMAGES COMPENSATED BY INSURANCE OR
OTHERWISE.

``Gross income shall include any amount paid to or on
behalf of a taxpayer as insurance or otherwise by reason of
the taxpayer's liability (or agreement) to pay punitive
damages.''.
(B) Reporting requirements.--Section 6041 (relating to
information at source) is amended by adding at the end the
following new subsection:
``(h) Section To Apply to Punitive Damages Compensation.--
This section shall apply to payments by a person to or on
behalf of another person as insurance or otherwise by reason
of the other person's liability (or agreement) to pay
punitive damages.''.
(C) Conforming amendment.--The table of sections for part
II of subchapter B of chapter 1 is amended by adding at the
end the following new item:

``Sec. 91. Punitive damages compensated by insurance or otherwise.''.
(3) Effective date.--The amendments made by this subsection
shall apply to damages paid or incurred after December 31,
2011.
______