To prevent a tax increase on American businesses and to provide certainty to job creators by extending certain expiring tax credits relating to energy.
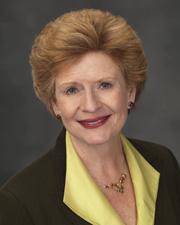 Sen. Debbie Stabenow (D-MI)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Amendment SA 1812, under the order of 3/7/12, not having achieved 60 votes in the affirmative, not agreed to in Senate by Yea-Nay Vote. 49 - 49. Record Vote Number: 39.
March 13, 2012
View full timeline
Roll call votes on amendments in Senate: Amendment SA 1812, under the order of 3/7/12, not having achieved 60 votes in the affirmative, not agreed to in Senate by Yea-Nay Vote. 49 - 49. Record Vote Number: 39.
March 13, 2012
Senate amendment not agreed to: Amendment SA 1812, under the order of 3/7/12, not having achieved 60 votes in the affirmative, not agreed to in Senate by Yea-Nay Vote. 49 - 49. Record Vote Number: 39.
March 13, 2012
Senate amendment proposed (on the floor): Amendment SA 1812 proposed by Senator Stabenow.(consideration: CR S1597-1599; text: CR S1597-1599)
March 13, 2012
Amendment SA 1812 proposed by Senator Stabenow. (consideration: CR S1597-1599; text: CR S1597-1599) To prevent a tax increase on American businesses and to provide certainty to job creators by extending certain expiring tax credits relating to energy.
March 13, 2012
Amendment SA 1812, under the order of 3/7/12, not having achieved 60 votes in the affirmative, not agreed to in Senate by Yea-Nay Vote. 49 - 49. Record Vote Number: 39.
March 13, 2012
Senate amendment submitted
March 7, 2012
Votes
1 roll call on this amendment
Text
Submitted
SA 1812. Ms. STABENOW submitted an amendment intended to be proposed
by her to the bill S. 1813, to reauthorize Federal-aid highway and
highway safety construction programs, and for other purposes; which was
ordered to lie on the table; as follows:

At the end of division D, insert the following:

SEC. ____. EXTENSION OF CREDIT FOR ENERGY-EFFICIENT EXISTING
HOMES.

(a) In General.--Paragraph (2) of section 25C(g) of the
Internal Revenue Code of 1986 is amended by striking
``December 31, 2011'' and inserting ``December 31, 2012''.
(b) Effective Date.--The amendment made by this section
shall apply to property placed in service after December 31,
2011.

[[Page S1465]]

SEC. ____. EXTENSION OF CREDIT FOR CERTAIN PLUG-IN ELECTRIC
VEHICLES.

(a) In General.--Subsection (f) of section 30 of the
Internal Revenue Code of 1986 is amended by striking
``December 31, 2011'' and inserting ``December 31, 2012''.
(b) Effective Date.--The amendment made by this section
shall apply to vehicles acquired after December 31, 2011.

SEC. ____. EXTENSION OF CREDIT FOR ALTERNATIVE FUEL VEHICLE
REFUELING PROPERTY.

(a) Extension.--Paragraph (2) of section 30C(g) of the
Internal Revenue Code of 1986 is amended by striking
``December 31, 2011.'' and inserting ``December 31, 2012''.
(b) Effective Date.--The amendment made by this section
shall apply to property placed in service after December 31,
2011.

SEC. ____. EXTENSION OF CELLULOSIC BIOFUEL PRODUCER CREDIT.

(a) In General.--Subparagraph (H) of section 40(b)(6) of
the Internal Revenue Code of 1986 is amended to read as
follows:
``(H) Application of paragraph.--
``(i) In general.--This paragraph shall apply with respect
to qualified cellulosic biofuel production after December 31,
2008, and before January 1, 2014.
``(ii) No carryover to certain years after expiration.--If
this paragraph ceases to apply for any period by reason of
clause (i), rules similar to the rules of subsection (e)(2)
shall apply.''.
(b) Conforming Amendment.--
(1) In general.--Paragraph (2) of section 40(e) of the
Internal Revenue Code of 1986 is amended by striking ``or
subsection (b)(6)(H)''.
(2) Effective date.--The amendment made by this subsection
shall take effect as if included in section 15321(b) of the
Heartland, Habitat, and Horticulture Act of 2008.

SEC. ____. ALGAE TREATED AS A QUALIFIED FEEDSTOCK FOR
PURPOSES OF THE CELLULOSIC BIOFUEL PRODUCER
CREDIT, ETC.

(a) In General.--Subclause (I) of section 40(b)(6)(E)(i) of
the Internal Revenue Code of 1986 is amended to read as
follows:

``(I) is derived by, or from, qualified feedstocks, and''.

(b) Qualified Feedstock; Special Rules for Algae.--
Paragraph (6) of section 40(b) of the Internal Revenue Code
of 1986 is amended by redesignating subparagraphs (F), (G),
and (H), as amended by this Act, as subparagraphs (H), (I),
and (J), respectively, and by inserting after subparagraph
(E) the following new subparagraphs:
``(F) Qualified feedstock.--For purposes of this paragraph,
the term `qualified feedstock' means--
``(i) any lignocellulosic or hemicellulosic matter that is
available on a renewable or recurring basis, and
``(ii) any cultivated algae, cyanobacteria, or lemna.
``(G) Special rules for algae.--In the case of fuel which
is derived by, or from, feedstock described in subparagraph
(F)(ii) and which is sold by the taxpayer to another person
for refining by such other person into a fuel which meets the
requirements of subparagraph (E)(i)(II) and the refined fuel
is not excluded under subparagraph (E)(iii)--
``(i) such sale shall be treated as described in
subparagraph (C)(i),
``(ii) such fuel shall be treated as meeting the
requirements of subparagraph (E)(i)(II) and as not being
excluded under subparagraph (E)(iii) in the hands of such
taxpayer, and
``(iii) except as provided in this subparagraph, such fuel
(and any fuel derived from such fuel) shall not be taken into
account under subparagraph (C) with respect to the taxpayer
or any other person.''.
(c) Algae Treated as a Qualified Feedstock for Purposes of
Bonus Depreciation for Biofuel Plant Property.--
(1) In general.--Subparagraph (A) of section 168(l)(2) of
the Internal Revenue Code of 1986 is amended by striking
``solely to produce cellulosic biofuel'' and inserting
``solely to produce second generation biofuel (as defined in
section 40(b)(6)(E))''.
(2) Conforming amendments.--Subsection (l) of section 168
of such Code is amended--
(A) by striking ``cellulosic biofuel'' each place it
appears in the text thereof and inserting ``second generation
biofuel'',
(B) by striking paragraph (3) and redesignating paragraphs
(4) through (8) as paragraphs (3) through (7), respectively,
(C) by striking ``Cellulosic'' in the heading of such
subsection and inserting ``Second Generation'', and
(D) by striking ``cellulosic'' in the heading of paragraph
(2) and inserting ``second generation''.
(d) Conforming Amendments.--
(1) Section 40 of the Internal Revenue Code of 1986, as
amended by subsection (b), is amended--
(A) by striking ``cellulosic biofuel'' each place it
appears in the text thereof and inserting ``second generation
biofuel'',
(B) by striking ``Cellulosic'' in the headings of
subsections (b)(6), (b)(6)(E), and (d)(3)(D) and inserting
``Second generation'', and
(C) by striking ``cellulosic'' in the headings of
subsections (b)(6)(C), (b)(6)(D), (b)(6)(H), (d)(6), and
(e)(3) and inserting ``second generation''.
(2) Clause (ii) of section 40(b)(6)(E) of such Code is
amended by striking ``Such term shall not'' and inserting
``The term `second generation biofuel' shall not''.
(3) Paragraph (1) of section 4101(a) of such Code is
amended by striking ``cellulosic biofuel'' and inserting
``second generation biofuel''.
(e) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to fuels sold or
used after the date of the enactment of this Act.
(2) Application to bonus depreciation.--The amendments made
by subsection (c) shall apply to property placed in service
after the date of the enactment of this Act.

SEC. ____. EXTENSION OF INCENTIVES FOR BIODIESEL AND
RENEWABLE DIESEL.

(a) Credits for Biodiesel and Renewable Diesel Used as
Fuel.--Subsection (g) of section 40A of the Internal Revenue
Code of 1986 is amended by striking ``December 31, 2011'' and
inserting ``December 31, 2012''.
(b) Excise Tax Credits and Outlay Payments for Biodiesel
and Renewable Diesel Fuel Mixtures.--
(1) Paragraph (6) of section 6426(c) of the Internal
Revenue Code of 1986 is amended by striking ``December 31,
2011'' and inserting ``December 31, 2012''.
(2) Subparagraph (B) of section 6427(e)(6) of such Code is
amended by striking ``December 31, 2011'' and inserting
``December 31, 2012''.
(c) Effective Date.--The amendments made by this section
shall apply to fuel sold or used after December 31, 2011.

SEC. ____. EXTENSION OF PRODUCTION CREDIT FOR REFINED COAL.

(a) In General.--Subparagraph (B) of section 45(d)(8) of
the Internal Revenue Code of 1986 is amended by striking
``January 1, 2012'' and inserting ``January 1, 2013''.
(b) Effective Date.--The amendment made by this section
shall apply to facilities placed in service after December
31, 2011.

SEC. ____. EXTENSION OF PRODUCTION CREDIT.

(a) In General.--Section 45(d) of the Internal Revenue Code
of 1986 is amended by striking ``January 1, 2014'' each place
it appears in paragraphs (2), (3), (4), (6), (7), (9), and
(11) and inserting ``January 1, 2015''.
(b) Wind Facilities.--Paragraph (1) of section 45(d) of the
Internal Revenue Code of 1986 is amended by striking
``January 1, 2013'' and inserting ``January 1, 2014''.
(c) Increased Credit Amount for Indian Coal Facilities
Placed in Service Before 2009.--Subparagraph (A) of section
45(e)(10) of the Internal Revenue Code of 1986 is amended by
striking ``7-year period'' each place it appears and
inserting ``8-year period''.
(d) Conforming Amendments.--Subsection (e) of section 1603
of division B of the American Recovery and Reinvestment Act
of 2009 is amended--
(1) by striking ``January 1, 2013'' in paragraph (1) and
inserting ``January 1, 2014'', and
(2) by striking ``January 1, 2014'' in paragraph (2) and
inserting ``January 1, 2015''.
(e) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to facilities
placed in service after December 31, 2012.
(2) Indian coal.--The amendment made by subsection (c)
shall take effect on the date of the enactment of this Act.

SEC. ____. EXTENSION OF CREDIT FOR ENERGY-EFFICIENT NEW
HOMES.

(a) In General.--Subsection (g) of section 45L of the
Internal Revenue Code of 1986 is amended by striking
``December 31, 2011'' and inserting ``December 31, 2012''.
(b) Effective Date.--The amendment made by this section
shall apply to homes acquired after December 31, 2011.

SEC. ____. EXTENSION OF CREDIT FOR ENERGY-EFFICIENT
APPLIANCES.

(a) In General.--Section 45M(b) of the Internal Revenue
Code of 1986 is amended by striking ``2011'' each place it
appears other than in the provisions specified in subsection
(b), and inserting ``2011 or 2012''.
(b) Provisions Specified.--The provisions of section 45M(b)
of the Internal Revenue Code of 1986 specified in this
subsection are subparagraph (C) of paragraph (1) and
subparagraph (E) of paragraph (2).
(c) Effective Date.--The amendments made by this section
shall apply to appliances produced after December 31, 2011.

SEC. ____. EXTENSION OF ELECTION OF INVESTMENT TAX CREDIT IN
LIEU OF PRODUCTION CREDIT.

(a) In General.--Clause (ii) of section 48(a)(5)(C) of the
Internal Revenue Code of 1986 is amended by striking ``or
2013'' and inserting ``2013, or 2014''.
(b) Wind Facilities.--Clause (i) of section 48(a)(5)(C) of
the Internal Revenue Code of 1986 is amended by striking
``Any qualified facility'' and all that follows and inserting
``Any facility which is--

``(I) a qualified facility (within the meaning of section
45) described in paragraph (1) of section 45(d) if such
facility is placed in service in 2009, 2010, 2011, 2012, or
2013, or
``(II) a qualifying offshore wind facility, if such
facility is placed in service in 2012, 2013, or 2014.''.

(c) Qualifying Offshore Wind Facility.--Paragraph (5) of
section 48(a) of the Internal Revenue Code of 1986 is amended
by adding at the end the following new subparagraph:
``(E) Qualifying offshore wind facility.--For purposes of
this paragraph--
``(i) In general.--The term `qualifying offshore wind
facility' means an offshore facility using wind to produce
electricity.
``(ii) Offshore facility.--The term `offshore facility'
means any facility located in the inland navigable waters of
the United States, including the Great Lakes, or in the
coastal waters of the United States, including the
territorial seas of the United States,

[[Page S1466]]

the exclusive economic zone of the United States, and the
Outer Continental Shelf of the United States. For purposes of
the preceding sentence, the term `United States' has the
meaning given in section 638(1).''.
(d) Effective Date.--The amendments made by this section
shall apply to facilities placed in service after December
31, 2011.

SEC. ____. EXPANSION OF QUALIFYING ADVANCED ENERGY PROJECT
CREDIT.

(a) In General.--Subparagraph (B) of section 48C(d)(1) of
the Internal Revenue Code of 1986 is amended by striking
``$2,300,000,000'' and inserting ``$4,600,000,000''.
(b) Effective Date.--The amendment made by this section
shall take effect on the date of the enactment of this Act.

SEC. ____. EXTENSION OF SPECIAL ALLOWANCE FOR CELLULOSIC
BIOFUEL PLANT PROPERTY.

(a) In General.--Subparagraph (D) of section 168(l)(2) of
the Internal Revenue Code of 1986 is amended by striking
``January 1, 2013'' and inserting ``January 1, 2014''.
(b) Conforming Amendment.--Paragraph (4) of section 168(l)
of the Internal Revenue Code of 1986, as redesignated by this
Act, is amended--
(1) by striking ``and'' at the end of subparagraph (A),
(2) by redesignating subparagraph (B) as subparagraph (C),
and
(3) by inserting after subparagraph (A) the following new
subparagraph:
``(B) by substituting `January 1, 2014' for `January 1,
2013' in clause (i) thereof, and''.

SEC. ____. EXTENSION OF SUSPENSION OF LIMITATION ON
PERCENTAGE DEPLETION FOR OIL AND GAS FROM
MARGINAL WELLS.

(a) In General.--Clause (ii) of section 613A(c)(6)(H) of
the Internal Revenue Code of 1986 is amended by striking
``January 1, 2012'' and inserting ``January 1, 2013''.
(b) Effective Date.--The amendment made by this section
shall apply to taxable years beginning after December 31,
2011.

SEC. ____. EXTENSION OF ALTERNATIVE FUELS EXCISE TAX CREDITS.

(a) In General.--Sections 6426(d)(5), 6426(e)(3), and
6427(e)(6)(C) of the Internal Revenue Code of 1986 are each
amended by striking ``December 31, 2011'' and inserting
``December 31, 2012''.
(b) Effective Date.--The amendments made by this section
shall apply to fuel sold or used after December 31, 2011.

SEC. ____. EXTENSION OF GRANTS FOR SPECIFIED ENERGY PROPERTY
IN LIEU OF TAX CREDITS.

(a) In General.--Subsection (a) of section 1603 of division
B of the American Recovery and Reinvestment Act of 2009, as
amended by section 707 of the Tax Relief, Unemployment
Insurance Reauthorization, and Job Creation Act of 2010, is
amended--
(1) by striking ``or 2011'' in paragraph (1) and inserting
``2011, or 2012'', and
(2) in paragraph (2)--
(A) by striking ``after 2011'' and inserting ``after
2012'', and
(B) by striking ``or 2011'' and inserting ``2011, or
2012''.
(b) Conforming Amendment.--Subsection (j) of section 1603
of division B of such Act, as so amended, is amended by
striking ``2012'' and inserting ``2013''.
(c) Effective Date.--The amendments made by this section
shall apply to property placed in service after December 31,
2011.
______