Of a perfecting nature.
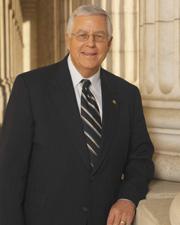 Sen. Michael B. Enzi (R-WY)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment agreed to: Amendment SA 741 agreed to in Senate by Yea-Nay Vote. 70 - 24. Record Vote Number: 112.
May 6, 2013
View full timeline
Senate amendment agreed to: Amendment SA 741 agreed to in Senate by Yea-Nay Vote. 70 - 24. Record Vote Number: 112.
May 6, 2013
Roll call votes on amendments in Senate: Amendment SA 741 agreed to in Senate by Yea-Nay Vote. 70 - 24. Record Vote Number: 112.
May 6, 2013
Considered by Senate. (consideration: CR S3081, S3081-3082)
May 6, 2013
Amendment SA 741 agreed to in Senate by Yea-Nay Vote. 70 - 24. Record Vote Number: 112.
May 6, 2013
Considered by Senate. (consideration: CR S2985)
April 25, 2013
Senate amendment submitted
April 24, 2013
Senate amendment proposed (on the floor): Amendment SA 741 proposed by Senator Reid for Senator Enzi.(consideration: CR S2926-2927; text: CR S2926-2927)
April 24, 2013
Amendment SA 741 proposed by Senator Reid for Senator Enzi. (consideration: CR S2926-2927; text: CR S2926-2927) Of a perfecting nature.
April 24, 2013
Votes
1 roll call on this amendment
Amendments
1 amendmentOffered to this amendment
Amendments
1 amendmentOffered to this amendment
Text
Submitted
SA 741. Mr. REID (for Mr. Enzi (for himself, Mr. Durbin, Mr.
Alexander, and Ms. Heitkamp)) proposed an amendment to the bill S. 743,
to restore States' sovereign rights to enforce State and local sales
and use tax laws, and for other purposes; as follows:

Beginning on page 2, line 10, strike ``if the Streamlined''
and all that follows through page 11, line 5, and insert the
following:
if any changes to the Streamlined Sales and Use Tax Agreement
made after the date of the enactment of this Act are not in
conflict with the minimum simplification requirements in
subsection (b)(2). A State may exercise authority under this
Act beginning 180 days after the State publishes notice of
the State's intent to exercise the authority under this Act,
but no earlier than the first day of the calendar quarter
that is at least 180 days after the date of the enactment of
this Act.
(b) Alternative.--A State that is not a Member State under
the Streamlined Sales and Use Tax Agreement is authorized
notwithstanding any other provision of law to require all
sellers not qualifying for the small seller exception
described in subsection (c) to collect and remit sales and
use taxes with respect to remote sales sourced to that State,
but only if the State adopts and implements the minimum
simplification requirements in paragraph (2). Such authority
shall commence beginning no earlier than the first day of the
calendar quarter that is at least 6 months after the date
that the State--
(1) enacts legislation to exercise the authority granted by
this Act--
(A) specifying the tax or taxes to which such authority and
the minimum simplification requirements in paragraph (2)
shall apply; and
(B) specifying the products and services otherwise subject
to the tax or taxes identified by the State under
subparagraph (A) to which the authority of this Act shall not
apply; and
(2) implements each of the following minimum simplification
requirements:
(A) Provide--
(i) a single entity within the State responsible for all
State and local sales and use tax administration, return
processing, and audits for remote sales sourced to the State;
(ii) a single audit of a remote seller for all State and
local taxing jurisdictions within that State; and
(iii) a single sales and use tax return to be used by
remote sellers to be filed with the single entity responsible
for tax administration.
A State may not require a remote seller to file sales and use
tax returns any more frequently than returns are required for
nonremote sellers or impose requirements on remote sellers
that the State does not impose on nonremote sellers with
respect to the collection of sales and use taxes under this
Act. No local jurisdiction may require a remote seller to
submit a sales and use tax return or to collect sales and use
taxes other than as provided by this paragraph.
(B) Provide a uniform sales and use tax base among the
State and the local taxing jurisdictions within the State
pursuant to paragraph (1).
(C) Source all remote sales in compliance with the sourcing
definition set forth in section 4(7).
(D) Provide--
(i) information indicating the taxability of products and
services along with any product and service exemptions from
sales and use tax in the State and a rates and boundary
database;
(ii) software free of charge for remote sellers that
calculates sales and use taxes due on each transaction at the
time the transaction is completed, that files sales and use
tax returns, and that is updated to reflect rate changes as
described in subparagraph (H); and
(iii) certification procedures for persons to be approved
as certified software providers.
For purposes of clause (iii), the software provided by
certified software providers shall be capable of calculating
and filing sales and use taxes in all States qualified under
this Act.
(E) Relieve remote sellers from liability to the State or
locality for the incorrect collection, remittance, or
noncollection of sales and use taxes, including any penalties
or interest, if the liability is the result of an error or
omission made by a certified software provider.
(F) Relieve certified software providers from liability to
the State or locality for the incorrect collection,
remittance, or noncollection of sales and use taxes,
including any penalties or interest, if the liability is the
result of misleading or inaccurate information provided by a
remote seller.
(G) Relieve remote sellers and certified software providers
from liability to the State or locality for incorrect
collection, remittance, or noncollection of sales and use
taxes, including any penalties or interest, if the liability
is the result of incorrect information or software provided
by the State.
(H) Provide remote sellers and certified software providers
with 90 days notice of a rate change by the State or any
locality in the State and update the information described in
subparagraph (D)(i) accordingly and relieve any remote seller
or certified software provider from liability for collecting
sales and use taxes at the immediately preceding effective
rate during the 90-day notice period if the required notice
is not provided.
(c) Small Seller Exception.--A State is authorized to
require a remote seller to collect sales and use taxes under
this Act only if the remote seller has gross annual receipts
in total remote sales in the United States in the preceding
calendar year exceeding $1,000,000. For purposes of
determining whether the threshold in this section is met, the
gross annual receipts from remote sales of 2 or more persons
shall be aggregated if--
(1) such persons are related to the remote seller within
the meaning of subsections (b) and (c) of section 267 or
section 707(b)(1) of the Internal Revenue Code of 1986; or
(2) such persons have 1 or more ownership relationships and
such relationships were designed with a principal purpose of
avoiding the application of these rules.

[[Page S2972]]

SEC. 3. LIMITATIONS.

(a) In General.--Nothing in this Act shall be construed
as--
(1) subjecting a seller or any other person to franchise,
income, occupation, or any other type of taxes, other than
sales and use taxes;
(2) affecting the application of such taxes; or
(3) enlarging or reducing State authority to impose such
taxes.
(b) No Effect on Nexus.--This Act shall not be construed to
create any nexus or alter the standards for determining nexus
between a person and a State or locality.
(c) No Effect on Seller Choice.--Nothing in this Act shall
be construed to deny the ability of a remote seller to deploy
and utilize a certified software provider of the seller's
choice.
(d) Licensing and Regulatory Requirements.--Nothing in this
Act shall be construed as permitting or prohibiting a State
from--
(1) licensing or regulating any person;
(2) requiring any person to qualify to transact intrastate
business;
(3) subjecting any person to State or local taxes not
related to the sale of products or services; or
(4) exercising authority over matters of interstate
commerce.
(e) No New Taxes.--Nothing in this Act shall be construed
as encouraging a State to impose sales and use taxes on any
products or services not subject to taxation prior to the
date of the enactment of this Act.
(f) No Effect on Intrastate Sales.--The provisions of this
Act shall apply only to remote sales and shall not apply to
intrastate sales or intrastate sourcing rules. States granted
authority under section 2(a) shall comply with all intrastate
provisions of the Streamlined Sales and Use Tax Agreement.
(g) No Effect on Mobile Telecommunications Sourcing Act.--
Nothing in this Act shall be construed as altering in any
manner or preempting the Mobile Telecommunications Sourcing
Act (4 U.S.C. 116-126).

SEC. 4. DEFINITIONS AND SPECIAL RULES.

In this Act:
(1) Certified software provider.--The term ``certified
software provider'' means a person that--
(A) provides software to remote sellers to facilitate State
and local sales and use tax compliance pursuant to section
2(b)(2)(D)(ii); and
(B) is certified by a State to so provide such software.
(2) Locality; local.--The terms ``locality'' and ``local''
refer to any political subdivision of a State.
(3) Member state.--The term ``Member State''--
(A) means a Member State as that term is used under the
Streamlined Sales and Use Tax Agreement as in effect on the
date of the enactment of this Act; and
(B) does not include any associate member under the
Streamlined Sales and Use Tax Agreement.
(4) Person.--The term ``person'' means an individual,
trust, estate, fiduciary, partnership, corporation, limited
liability company, or other legal entity, and a State or
local government.
(5) Remote sale.--The term ``remote sale'' means a sale
into a State, as determined under the sourcing rules under
paragraph (7), in which the seller would not legally be
required to pay, collect, or remit State or local sales and
use taxes unless provided by this Act.
(6) Remote seller.--The term ``remote seller'' means a
person that makes remote sales in the State.
(7) Sourced.--For purposes of a State granted authority
under section 2(b), the location to which a remote sale is
sourced refers to the location where the product or service
sold is received by the purchaser, based on the location
indicated by instructions for delivery that the purchaser
furnishes to the seller. When no delivery location is
specified, the remote sale is sourced to the customer's
address that is either known to the seller or, if not known,
obtained by the seller during the consummation of the
transaction, including the address of the customer's payment
instrument if no other address is available. If an address is
unknown and a billing address cannot be obtained, the remote
sale is sourced to the address of the seller from which the
remote sale was made. A State granted authority under section
2(a) shall comply with the sourcing provisions of the
Streamlined Sales and Use Tax Agreement.
(8) State.--The term ``State'' means each of the several
States, the District of Columbia, the Commonwealth of Puerto
Rico, Guam, American Samoa, the United States Virgin Islands,
the Commonwealth of the Northern Mariana Islands, and any
other territory or possession of the United States, and any
tribal organization (as defined in section 4 of the Indian
Self-Determination and Education Assistance Act (25 U.S.C.
450b)).
______