Renewable Fuels and Transportation Infrastructure Enhancement Act of 2003
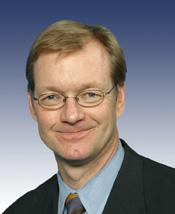 Rep. Kenny C. Hulshof (R-MO)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Referred to the House Committee on Ways and Means.
September 17, 2003
View full timeline
Introduced in House
September 17, 2003
Referred to the House Committee on Ways and Means.
September 17, 2003
Floor Debate
24 membersWhat members said about H.R. 3119 on the floor
 +19
Floor Debate
24 membersWhat members said about H.R. 3119 on the floor
Mr. Chairman, this Member rises in strong support of H.R. 3550, the Transportation Equity Act: A Legacy for Users. This Member would like to begin by thanking the distinguished gentleman from Alaska…
Mr. Chairman, I yield myself such time as I may consume. Mr. Chairman, I feel somewhat like the sinner appearing before the bishop when Your Honorable is in the Chair; but with all due respect, I do…
Mr. Chairman, I yield myself 6 minutes. Mr. Chairman, I am very deeply touched by the words of the gentleman from Alaska (Mr. Young), our committee chairman. We have worked closely together on…
Mr. Chairman, I thank the gentleman for yielding me time. Our transportation system continues to face tremendous challenges. Tens of thousands of lives are lost each year on our highways. More…
Mr. Chairman, I want to thank the gentleman from Minnesota (Mr. Oberstar), my partner in this endeavor, very much for those extremely kind words and for yielding me this time. It is always a pleasure…
Show 8 more
Mr. Chairman, I rise in strong support of this very important legislation, which will improve our transportation infrastructure and create millions of jobs, and I want to thank the gentleman from…
Mr. Chairman, I thank my colleague for yielding me this time. I rise in support of H.R. 3550, a bill that is bipartisanly crafted by both the gentleman from Alaska (Chairman Young) and the gentleman…
Mr. Chairman, I rise today in strong support of H.R. 3550, the Transportation Equity Act: A Legacy For Users, or affectionately known as TEA LU. I want to begin by extending my appreciation to the…

Mr. Chairman, I thank the gentleman from Alaska (Chairman Young), the gentleman from Wisconsin (Mr. Petri), the gentleman from Minnesota (Ranking Member Oberstar), and the gentleman from Illinois…
Mr. Chairman, I thank the gentleman for yielding me time. It is a pleasure to be on the floor this morning to talk about some of the advantages that are in the 6-year reauthorization of our…
Mr. Chairman, I would first like to salute the chairman of our committee for bringing us to this day and to the gentleman from Minnesota (Mr. Oberstar) and my colleague, the gentleman from Illinois…

Mr. Chairman, I yield myself such time as I may consume. Mr. Chairman, included in this bill is a provision drawn from H.R. 3119, the ``Renewable Fuels and Transportation Infrastructure Enhancement…
Mr. Chairman, I rise today to quote the words of President Dwight Eisenhower, the father of our, Highway Trust Fund, who rightly said ``A network of modern roads is as necessary to defense as it is…
Show 11 more
Mr. Chairman, I want to thank my colleague, the gentleman from North Dakota (Mr. Pomeroy), for yielding me this time. I want to add my condolences also to our colleague, the gentleman from Missouri…
Mr. Chairman, I want to thank the gentleman for yielding me this time. I rise in strong support of this legislation. First of all, I want to commend the gentleman from Alaska (Mr. Young), the…

Mr. Chairman, the gentleman from Alaska has dedicated years to this bill. I applaud him for that. I know it is less dollars than he would like to see because he does understand the problems we face…

Mr. Chairman, I stand in support of H.R. 3550, the Transportation Equity Act: A Legacy for Users (TEA-LU). In my congressional district, the rural highways that served our Nation for decades can no…
Mr. Chairman, I want to give a piece of praise this morning to the gentleman from Alaska (Mr. Young), the gentleman from Wisconsin (Mr. Petri), the gentleman from Minnesota (Mr. Oberstar) and the…
Mr. Chairman, I want to join the others associating myself with the remarks of the gentleman from Ohio (Mr. LaTourette) in thanking the gentleman from Alaska (Mr. Young), the gentleman from Wisconsin…
Mr. Chairman, I am delighted to rise in support of a piece of legislation that I think is very important not only to the folks back home in Kansas but to the folks of this country, and I am here to…

Mr. Chairman, I appreciate the gentleman's courtesy in permitting me to speak in support of what is the most important jobs and environmental bill of this session. Because of the structure that has…
Mr. Chairman, I thank the gentleman for yielding me this time. There are many good things in this highway bill. One that I would like to highlight at this particular point came out of the Committee…
Mr. Chairman, let me rise to thank the chairman and the ranking member for their leadership and also the subcommittee chair and ranking member. I am talking about the gentleman from Alaska (Mr.…
Mr. Chairman, I rise today in support of H.R. 3550, the Transportation Act--A Legacy for Users (TEA-LU). I am pleased that my good friends Chairman Don Young and Ranking Member Jim Oberstar of the…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 3119 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 3119

To amend the Internal Revenue Code of 1986 to allow a credit against
income tax for biodiesel used as a fuel.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

September 17, 2003

Mr. Hulshof (for himself, Mr. Pomeroy, Mr. Nussle, Mr. Young of Alaska,
Mr. Oberstar, Mr. Stenholm, Mrs. Emerson, Mr. Graves, Mr. Skelton, Mr.
Akin, and Mr. Boehner) introduced the following bill; which was
referred to the Committee on Ways and Means

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to allow a credit against
income tax for biodiesel used as a fuel.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Renewable Fuels and Transportation
Infrastructure Enhancement Act of 2003''.

SEC. 2. ALCOHOL FUEL AND BIODIESEL MIXTURES EXCISE TAX CREDIT.

(a) In General.--Subchapter B of chapter 65 of the Internal Revenue
Code of 1986 (relating to rules of special application) is amended by
inserting after section 6425 the following new section:

``SEC. 6426. CREDIT FOR ALCOHOL FUEL AND BIODIESEL MIXTURES.

``(a) Allowance of Credits.--There shall be allowed as a credit
against the tax imposed by section 4081 an amount equal to the sum of--
``(1) the alcohol fuel mixture credit, plus
``(2) the biodiesel mixture credit.
``(b) Alcohol Fuel Mixture Credit.--
``(1) In general.--For purposes of this section, the
alcohol fuel mixture credit is the product of the applicable
amount and the number of gallons of alcohol used by the
taxpayer in producing any alcohol fuel mixture.
``(2) Applicable amount.--For purposes of this subsection--
``(A) In general.--Except as provided in
subparagraph (B), the applicable amount is 52 cents (51
cents in the case of any sale or use after 2004).
``(B) Mixtures not containing ethanol.--In the case
of an alcohol fuel mixture in which none of the alcohol
consists of ethanol, the applicable amount is 60 cents.
``(3) Alcohol fuel mixture.--For purposes of this
subsection, the term `alcohol fuel mixture' means a mixture of
alcohol and a taxable fuel which--
``(A) is sold by the taxpayer producing such
mixture to any person for use as a fuel,
``(B) is used as a fuel by the taxpayer producing
such mixture, or
``(C) is removed from the refinery by a person
producing such mixture.
``(4) Other definitions.--For purposes of this subsection--
``(A) Alcohol.--The term `alcohol' includes
methanol and ethanol but does not include--
``(i) alcohol produced from petroleum,
natural gas, or coal (including peat), or
``(ii) alcohol with a proof of less than
190 (determined without regard to any added
denaturants).
Such term also includes an alcohol gallon equivalent of
ethyl tertiary butyl ether or other ethers produced
from such alcohol.
``(B) Taxable fuel.--The term `taxable fuel' has
the meaning given such term by section 4083(a)(1).
``(5) Termination.--This subsection shall not apply to any
sale or use for any period after December 31, 2010.
``(c) Biodiesel Mixture Credit.--
``(1) In general.--For purposes of this section, the
biodiesel mixture credit is the product of the applicable
amount and the number of gallons of biodiesel used by the
taxpayer in producing any qualified biodiesel mixture.
``(2) Applicable amount.--For purposes of this subsection--
``(A) In general.--Except as provided in
subparagraph (B), the applicable amount is 50 cents.
``(B) Amount for agri-biodiesel.--
``(i) In general.--Subject to clause (ii),
in the case of any biodiesel which is agri-
biodiesel, the applicable amount is $1.00.
``(ii) Certification for agri-biodiesel.--
Clause (i) shall apply only if the taxpayer
described in paragraph (1) obtains a
certification (in such form and manner as
prescribed by the Secretary) from the producer
of the agri-biodiesel which identifies the
product produced.
``(3) Definitions.--Any term used in this subsection which
is also used in section 40A shall have the meaning given such
term by section 40A.
``(4) Termination.--This subsection shall not apply to any
sale or use for any period after December 31, 2005.
``(d) Mixture Not Used as a Fuel, etc.--
``(1) Imposition of tax.--If--
``(A) any credit was determined under this section
with respect to alcohol or biodiesel used in the
production of any alcohol fuel mixture or qualified
biodiesel mixture, respectively, and
``(B) any person--
``(i) separates such alcohol or biodiesel
from the mixture, or
``(ii) without separation, uses the mixture
other than as a fuel,
then there is hereby imposed on such person a tax equal
to the product of the applicable amount and the number
of gallons of such alcohol or biodiesel.
``(2) Applicable laws.--All provisions of law, including
penalties, shall, insofar as applicable and not inconsistent
with this section, apply in respect of any tax imposed under
paragraph (1) as if such tax were imposed by section 4081 and
not by this section.''.
(b) Registration Requirement.--Section 4101(a) of such Code
(relating to registration) is amended by inserting ``and every person
producing biodiesel (as defined in section 40A(d)(1)) or alcohol (as
defined in section 6426(b)(4)(A))'' after ``4091''.
(c) Conforming Amendments.--
(1) Section 40(c) of such Code is amended by striking
``section 4081(c), or section 4091(c)'' and inserting ``section
4091(c), section 6426, section 6427(e), or section 6427(f)''.
(2) Section 40(d)(4)(B) of such Code is amended by striking
``or 4081(c)''.
(3) Section 40(e)(1) of such Code is amended--
(A) by striking ``2007'' in subparagraph (A) and
inserting ``2010'', and
(B) by striking ``2008'' in subparagraph (B) and
inserting ``2011''.
(4) Section 40(h) of such Code is amended--
(A) by striking ``2007'' in paragraph (1) and
inserting ``2010'', and
(B) by striking ``, 2006, or 2007'' in the table
contained in paragraph (2) and inserting ``through
2010''.
(5) Section 4041(b)(2)(B) of such Code is amended by
striking ``a substance other than petroleum or natural gas''
and inserting ``coal (including peat)''.
(6) Paragraph (1) of section 4041(k) of such Code is
amended to read as follows:
``(1) In general.--Under regulations prescribed by the
Secretary, in the case of the sale or use of any liquid at
least 10 percent of which consists of alcohol (as defined in
section 6426(b)(4)(A)), the rate of the tax imposed by
subsection (c)(1) shall be the comparable rate under section
4091(c).''.
(7) Section 4081 of such Code is amended by striking
subsection (c).
(8) Paragraph (2) of section 4083(a) of such Code is
amended to read as follows:
``(2) Gasoline.--The term `gasoline'--
``(A) includes any gasoline blend, other than
qualified methanol or ethanol fuel (as defined in
section 4041(b)(2)(B)) or a denaturant of alcohol (as
defined in section 6426(b)(4)(A)), and
``(B) includes, to the extent prescribed in
regulations--
``(i) any gasoline blend stock, and
``(ii) any product commonly used as an
additive in gasoline.
For purposes of subparagraph (B)(i), the term `gasoline blend
stock' means any petroleum product component of gasoline.''.
(9) Section 6427 of such Code is amended by inserting after
subsection (d) the following new subsection:
``(e) Alcohol or Biodiesel Used To Produce Alcohol Fuel and
Biodiesel Mixtures or Used as Fuels.--Except as provided in subsection
(k)--
``(1) Used to produce a mixture.--If any person produces a
mixture described in section 6426 in such person's trade or
business, the Secretary shall pay (without interest) to such
person an amount equal to the alcohol fuel mixture credit or
the biodiesel mixture credit with respect to such mixture.
``(2) Used as fuel.--If alcohol (as defined in section
40(d)(1)) or biodiesel (as defined in section 40A(d)(1)) or
agri-biodiesel (as defined in section 40A(d)(2)) which is not
in a mixture with a taxable fuel (as defined in section
4083(a)(1))--
``(A) is used by any person as a fuel in a trade or
business, or
``(B) is sold by any person at retail to another
person and placed in the fuel tank of such person's
vehicle,
the Secretary shall pay (without interest) to such person an
amount equal to the alcohol credit (as determined under section
40(b)(2)) or the biodiesel credit (as determined under section
40A(b)(2)) with respect to such fuel.
``(3) Coordination with other repayment provisions.--No
amount shall be payable for any period under paragraph (1) with
respect to any mixture with respect to which an amount may be
claimed by such person as a credit under section 6426 for such
period.
``(4) Termination.--This subsection shall not apply with
respect to--
``(A) any alcohol fuel mixture (as defined in
section 6426(b)(3)) or alcohol (as so defined) sold or
used after December 31, 2010, and
``(B) any qualified biodiesel mixture (within the
meaning of section 6426(c)(1)) or biodiesel (as so
defined) or agri-biodiesel (as so defined) sold or used
after December 31, 2005.''.
(10) Subsection (f) of section 6427 of such Code is amended
to read as follows:
``(f) Aviation Fuel Used To Produce Certain Alcohol Fuels.--
``(1) In general.--Except as provided in subsection (k), if
any aviation fuel on which tax was imposed by section 4091 at
the regular tax rate is used by any person in producing a
mixture described in section 4091(c)(1)(A) which is sold or
used in such person's trade or business, the Secretary shall
pay (without interest) to such person an amount equal to the
excess of the regular tax rate over the incentive tax rate with
respect to such fuel.
``(2) Definitions.--For purposes of paragraph (1)--
``(A) Regular tax rate.--The term `regular tax
rate' means the aggregate rate of tax imposed by
section 4091 determined without regard to subsection (c) thereof.
``(B) Incentive tax rate.--The term `incentive tax
rate' means the aggregate rate of tax imposed by
section 4091 with respect to fuel described in
subsection (c)(2) thereof.
``(3) Coordination with other repayment provisions.--No
amount shall be payable under paragraph (1) with respect to any
aviation fuel with respect to which an amount is payable under
subsection (d) or (l).
``(4) Termination.--This subsection shall not apply with
respect to any mixture sold or used after September 30,
2007.''.
(11) Paragraphs (1) and (2) of section 6427(i) of such Code
are amended by inserting ``(f),'' after ``(d),''.
(12) Section 6427(i)(3) of such Code is amended--
(A) by striking ``subsection (f)'' both places it
appears in subparagraph (A) and inserting ``subsection
(e)(1)'',
(B) by striking ``gasoline, diesel fuel, or
kerosene used to produce a qualified alcohol mixture
(as defined in section 4081(c)(3))'' in subparagraph
(A) and inserting ``a mixture described in section
6426'',
(C) by striking ``subsection (f)(1)'' in
subparagraph (B) and inserting ``subsection (e)(1)'',
(D) by striking ``20 days of the date of the filing
of such claim'' in subparagraph (B) and inserting ``45
days of the date of the filing of such claim (20 days
in the case of an electronic claim)'', and
(E) by striking ``alcohol mixture'' in the heading
and inserting ``alcohol fuel and biodiesel mixture''.
(13) Section 6427(o) of such Code is amended--
(A) by striking paragraph (1) and inserting the
following new paragraph:
``(1) any tax is imposed by section 4081, and'',
(B) by striking ``such gasohol'' in paragraph (2)
and inserting ``the alcohol fuel mixture (as defined in
section 6426(b)(3))'',
(C) by striking ``gasohol'' both places it appears
in the matter following paragraph (2) and inserting
``alcohol fuel mixture'', and
(D) by striking ``Gasohol'' in the heading and
inserting ``Alcohol Fuel Mixture''.
(14) Section 9503(b)(1) of such Code is amended by adding
at the end the following new flush sentence:
``For purposes of this paragraph, taxes received under sections
4041 and 4081 shall be determined without reduction for credits
under section 6426.''.
(15) Section 9503(b)(4) of such Code is amended--
(A) by adding ``or'' at the end of subparagraph
(C),
(B) by striking the comma at the end of
subparagraph (D)(iii) and inserting a period, and
(C) by striking subparagraphs (E) and (F).
(16) Section 9503(c)(2)(A)(i)(III) of such Code is amended
by inserting ``(other than subsection (e) thereof)'' after
``section 6427''.
(17) Section 9503(e)(2) of such Code is amended by striking
subparagraph (B) and by redesignating subparagraphs (C), (D),
and (E) as subparagraphs (B), (C), and (D), respectively.
(18) The table of sections for subchapter B of chapter 65
of such Code is amended by inserting after the item relating to
section 6425 the following new item:

``Sec. 6426. Credit for alcohol fuel and biodiesel mixtures.''.
(d) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to fuel sold or
used after December 31, 2003.
(2) Repeal of general fund retention of certain alcohol
fuels taxes.--The amendments made by subsection (c)(15) shall
apply to fuel sold or used after September 30, 2003.
(e) Format for Filing.--The Secretary of the Treasury shall
describe the electronic format for filing claims described in section
6427(i)(3)(B) of the Internal Revenue Code of 1986 (as amended by
subsection (b)(12)(C)) not later than October 31, 2003.

SEC. 3. INCENTIVES FOR BIODIESEL.

(a) In General.--Subpart D of part IV of subchapter A of chapter 1
of the Internal Revenue Code of 1986 (relating to business related
credits) is amended by inserting after section 40 the following new
section:

``SEC. 40A. BIODIESEL USED AS FUEL.

``(a) General Rule.--For purposes of section 38, the biodiesel
fuels credit determined under this section for the taxable year is an
amount equal to the sum of--
``(1) the biodiesel mixture credit, plus
``(2) the biodiesel credit.
``(b) Definition of Biodiesel Mixture Credit and Biodiesel
Credit.--For purposes of this section--
``(1) Biodiesel mixture credit.--
``(A) In general.--The biodiesel mixture credit of
any taxpayer for any taxable year is 50 cents for each
gallon of biodiesel used by the taxpayer in the
production of a qualified biodiesel mixture.
``(B) Qualified biodiesel mixture.--The term
`qualified biodiesel mixture' means a mixture of
biodiesel and diesel fuel which--
``(i) is sold by the taxpayer producing
such mixture to any person for use as a fuel,
``(ii) is used as a fuel by the taxpayer
producing such mixture, or
``(iii) is removed from the refinery by a
person producing such mixture.
``(C) Sale or use must be in trade or business,
etc.--Biodiesel used in the production of a qualified
biodiesel mixture shall be taken into account--
``(i) only if the sale or use described in
subparagraph (B) is in a trade or business of
the taxpayer, and
``(ii) for the taxable year in which such
sale or use occurs.
``(D) Casual off-farm production not eligible.--No
credit shall be allowed under this section with respect
to any casual off-farm production of a qualified
biodiesel mixture.
``(2) Biodiesel credit.--
``(A) In general.--The biodiesel credit of any
taxpayer for any taxable year is 50 cents for each
gallon of biodiesel which is not in a mixture with
diesel fuel and which during the taxable year--
``(i) is used by the taxpayer as a fuel in
a trade or business, or
``(ii) is sold by the taxpayer at retail to
a person and placed in the fuel tank of such
person's vehicle.
``(B) User credit not to apply to biodiesel sold at
retail.--No credit shall be allowed under subparagraph
(A)(i) with respect to any biodiesel which was sold in
a retail sale described in subparagraph (A)(ii).
``(3) Credit for agri-biodiesel.--
``(A) In general.--Subject to subparagraph (B), in
the case of any biodiesel which is agri-biodiesel,
paragraphs (1)(A) and (2)(A) shall be applied by
substituting `$1.00' for `50 cents'.
``(B) Certification for agri-biodiesel.--
Subparagraph (A) shall apply only if the taxpayer
described in paragraph (1)(A) or (2)(A) obtains a
certification (in such form and manner as prescribed by
the Secretary) from the producer of the agri-biodiesel
which identifies the product produced.
``(c) Coordination With Credit Against Excise Tax.--The amount of
the credit determined under this section with respect to any agri-
biodiesel shall, under regulations prescribed by the Secretary, be
properly reduced to take into account any benefit provided with respect
to such agri-biodiesel solely by reason of the application of section
6426 or 6427(e).
``(d) Definitions and Special Rules.--For purposes of this
section--
``(1) Biodiesel.--The term `biodiesel' means the monoalkyl
esters of long chain fatty acids derived from plant or animal
matter which meet--
``(A) the registration requirements for fuels and
fuel additives established by the Environmental
Protection Agency under section 211 of the Clean Air
Act (42 U.S.C. 7545), and
``(B) the requirements of the American Society of
Testing and Materials D6751.
``(2) Agri-biodiesel.--The term `agri-biodiesel' means
biodiesel derived solely from virgin oils. Such term shall
include esters derived from vegetable oils from soybeans, corn,
sunflower seeds, cottonseeds, canola, crambe, rapeseeds,
safflowers, flaxseeds, rice bran, and mustard seeds, and from
animal fats.
``(3) Mixture or biodiesel not used as a fuel, etc.--
``(A) Mixtures.--If--
``(i) any credit was determined under this
section with respect to biodiesel used in the
production of any qualified biodiesel mixture,
and
``(ii) any person--
``(I) separates such biodiesel from
the mixture, or
``(II) without separation, uses the
mixture other than as a fuel,
then there is hereby imposed on such person a tax equal
to the product of the rate applicable under subsection
(b)(1)(A) and the number of gallons of the mixture.
``(B) Biodiesel.--If--
``(i) any credit was determined under this
section with respect to the retail sale of any
biodiesel, and
``(ii) any person mixes such biodiesel or
uses such biodiesel other than as a fuel,
then there is hereby imposed on such person a tax equal
to the product of the rate applicable under subsection
(b)(1)(A) and the number of gallons of such biodiesel.
``(C) Applicable laws.--All provisions of law,
including penalties, shall, insofar as applicable and
not inconsistent with this section, apply in respect of
any tax imposed under subparagraph (A) as if such tax
were imposed by section 4081 and not by this chapter.
``(4) Pass-thru in the case of estates and trusts.--Under
regulations prescribed by the Secretary, rules similar to the
rules of subsection (d) of section 52 shall apply.
``(e) Termination.--This section shall not apply to any fuel sold
after December 31, 2005.''.
(b) Credit Treated as Part of General Business Credit.--Section
38(b) of such Code (relating to current year business credit) is
amended by striking ``plus'' at the end of paragraph (14), by striking
the period at the end of paragraph (15) and inserting ``, plus'', and
by adding at the end the following new paragraph:
``(16) the biodiesel fuels credit determined under section
40A(a).''.
(c) Conforming Amendments.--
(1) Section 39(d) of such Code is amended by adding at the
end the following new paragraph:
``(11) No carryback of biodiesel fuels credit before
effective date.--No portion of the unused business credit for
any taxable year which is attributable to the biodiesel fuels
credit determined under section 40A may be carried back to a
taxable year ending on or before December 31, 2003.''.
(2)(A) Section 87 is of such Code amended to read as
follows:

``SEC. 87. ALCOHOL AND BIODIESEL FUELS CREDITS.

``Gross income includes--
``(1) the amount of the alcohol fuel credit determined with
respect to the taxpayer for the taxable year under section
40(a), and
``(2) the biodiesel fuels credit determined with respect to
the taxpayer for the taxable year under section 40A(a).''.
(B) The item relating to section 87 in the table of
sections for part II of subchapter B of chapter 1 of such Code
is amended by striking ``fuel credit'' and inserting ``and
biodiesel fuels credits''.
(3) Section 196(c) of such Code is amended by striking
``and'' at the end of paragraph (9), by striking the period at
the end of paragraph (10) and inserting ``, and'', and by
adding at the end the following new paragraph:
``(11) the biodiesel fuels credit determined under section
40A(a).''.
(4) The table of sections for subpart D of part IV of
subchapter A of chapter 1 of such Code is amended by adding
after the item relating to section 40 the following new item:

``Sec. 40A. Biodiesel used as fuel.''.
(d) Effective Date.--The amendments made by this section shall
apply to fuel sold after December 31, 2003, in taxable years ending
after such date.
<all>