Beginning Farmers and Ranchers Tax Incentive Act of 2003
A bill to amend the Internal Revenue Code of 1986 to provide an exclusion for gain from the sale of farmland to encourage the continued use of the property for farming, and for other purposes.
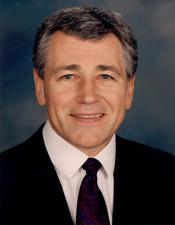 Sen. Chuck Hagel (R-NE)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S9974)
July 25, 2003
View full timeline
Introduced in Senate
July 25, 2003
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S9974)
July 25, 2003
Floor Debate
10 membersWhat members said about S. 1464 on the floor
 +5
Floor Debate
10 membersWhat members said about S. 1464 on the floor
I rise today to introduce the International Marriage Broker Regulation Act of 2003. This legislation will provide much needed protections for the thousands of foreign women who meet their American…
Mr. President, the Alaska Land Transfer Acceleration Act of 2003 will transfer millions of acres of land to Alaska Natives, the State of Alaska and to Native Corporations by 2009. The Federal…
Mr. President, today I once again join with Senators John McCain and Tim Johnson in introducing legislation that addresses the longstanding problem of mismanagement of assets held by the United…
Mr. President, I rise to introduce legislation to serve as the basis for much needed reforms to the Federal Government's management of Indian trust funds and trust assets within the U.S. Department…
Mr. President, I rise today to join my colleague from Massachusetts, Senator Kennedy, in introducing legislation addressing the critical issue of bacterial resistance to antibiotics arising from…
Show 7 more
Mr. President, it is a privilege to join Senator Snowe, Senator Reed, and Senator Bingaman in introducing The Preservation of Antibiotics for Medical Treatment Act. Our legislation is both important…
Mr. President, I rise today to introduce the Cumberland Island National Seashore Wilderness Boundary Act. With the introduction of this important legislation, we will be able to better preserve and…
Mr. President, I rise today to discuss S. 1464, legislation I recently introduced with Senator Dorgan to provide a capital gains tax incentive to agricultural producers on the sale of their farm or…
Mr. President, today Senator Alexander and I introduce legislation to award a Congressional Gold Medal to Clarksville, Tennessee native Wilma Rudolph for her contributions to women's athletics and…
Mr. President, I ask unanimous consent that the text of the bill be printed in the Record.
Mr. President, I ask unanimous consent that the text of the bill be printed in the Record.
Mr. President, I ask unanimous consent that the text of the bill be printed in the Record.
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 1464 Introduced in Senate (IS)]

108th CONGRESS
1st Session
S. 1464

To amend the Internal Revenue Code of 1986 to provide an exclusion for
gain from the sale of farmland to encourage the continued use of the
property for farming, and for other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

July 25 (legislative day, July 21), 2003

Mr. Hagel (for himself and Mr. Dorgan) introduced the following bill;
which was read twice and referred to the Committee on Finance

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to provide an exclusion for
gain from the sale of farmland to encourage the continued use of the
property for farming, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Beginning Farmers and Ranchers Tax
Incentive Act of 2003''.

SEC. 2. EXCLUSION OF GAIN FROM SALE OF CERTAIN FARMLAND.

(a) In General.--Part III of subchapter B of chapter 1 of the
Internal Revenue Code of 1986 (relating to items specifically excluded
from gross income) is amended by adding after section 121 the following
new section:

``SEC. 121A. EXCLUSION OF GAIN FROM SALE OF QUALIFIED FARM PROPERTY.

``(a) Exclusion.--In the case of a natural person, gross income
shall not include--
``(1) 100 percent of the gain from the sale or exchange of
qualified farm property to a first-time farmer (as defined in
section 147(c)(2)(C) (determined without regard to clause
(i)(II) thereof)) who certifies that the use of such property
shall be as a farm for farming purposes for not less than 10
years after such sale or exchange,
``(2) 50 percent of the gain from the sale or exchange of
qualified farm property to any other person who certifies that
the use of such property shall be as a farm for farming
purposes for not less than 10 years after such sale or
exchange, and
``(3) 25 percent of the gain from the sale or exchange of
qualified farm property to any other person for any other use.
``(b) Limitation on Amount of Exclusion.--
``(1) In general.--The amount of gain excluded from gross
income under subsection (a) with respect to any taxable year
shall not exceed $500,000 ($250,000 in the case of a married
individual filing a separate return), reduced by the aggregate
amount of gain excluded under subsection (a) for all preceding
taxable years.
``(2) Special rule for joint returns.--The amount of the
exclusion under subsection (a) on a joint return for any
taxable year shall be allocated equally between the spouses for
purposes of applying the limitation under paragraph (1) for any
succeeding taxable year.
``(c) Qualified Farm Property.--
``(1) Qualified farm property.--For purposes of this
section, the term `qualified farm property' means real property
located in the United States if, during periods aggregating 3
years or more of the 5-year period ending on the date of the
sale or exchange of such real property--
``(A) such real property was used as a farm for
farming purposes by the taxpayer or a member of the
family of the taxpayer, and
``(B) there was material participation by the
taxpayer (or such a member) in the operation of the
farm.
``(2) Definitions.--For purposes of this subsection, the
terms `member of the family', `farm', and `farming purposes'
have the respective meanings given such terms by paragraphs
(2), (4), and (5) of section 2032A(e).
``(3) Special rules.--For purposes of this section, rules
similar to the rules of paragraphs (4) and (5) of section
2032A(b) and paragraphs (3) and (6) of section 2032A(e) shall
apply.
``(d) Other Rules.--For purposes of this section, rules similar to
the rules of subsection (e) and subsection (f) of section 121 shall
apply.
``(e) Treatment of Disposition or Change in Use of Property.--
``(1) In general.--If, as of the close of any taxable year,
there is a recapture event with respect to any qualified farm
property transferred to the taxpayer in a sale or exchange
described in paragraph (1) or (2) of subsection (a), then the
tax of the taxpayer under this chapter for such taxable year
shall be increased by an amount equal to the product of--
``(A) the applicable recapture percentage, and
``(B) 10 percent of the taxpayer's adjusted basis
in the property on the date such property was
transferred to the taxpayer.
``(2) Applicable recapture percentage.--
``(A) In general.--For purposes of this subsection,
the applicable recapture percentage shall be determined
from the following table:

``If the recapture event occurs in: The applicable recapture percentage
is:
Years 1 through 5....................          100
Year 6...............................           80
Year 7...............................           60
Year 8...............................           40
Year 9...............................           20
Years 10 and thereafter..............            0.
``(B) Years.--For purposes of subparagraph (A),
year 1 shall begin on the date of the sale or exchange
described in paragraph (1) or (2) of subsection (a).
``(3) Recapture event defined.--For purposes of this
subsection, the term `recapture event' means--
``(A) Cessation of operation.--The cessation of the
operation of any property the sale or exchange of which
to the taxpayer is described in paragraph (1) or (2) of
subsection (a) as a farm for farming purposes.
``(B) Change in ownership.--
``(i) In general.--Except as provided in
clause (ii), the disposition of a taxpayer's
interest in any property the sale or exchange
of which to the taxpayer is described in
paragraph (1) or (2) of subsection (a).
``(ii) Agreement to assume recapture
liability.--Clause (i) shall not apply if the
person acquiring such interest in the property
agrees in writing to assume the recapture
liability of the person disposing of such
interest in effect immediately before such
disposition. In the event of such an
assumption, the person acquiring the interest
in the property shall be treated as the
taxpayer for purposes of assessing any
recapture liability (computed as if there had
been no change in ownership).
``(4) Special rules.--
``(A) No credits against tax.--Any increase in tax
under this subsection shall not be treated as a tax
imposed by this chapter for purposes of determining the
amount of any credit under subpart A, B, or D of this
part.
``(B) No recapture by reason of hardship.--The
increase in tax under this subsection shall not apply
to any disposition of property or cessation of the
operation of any property as a farm for farming
purposes by reason of any hardship as determined by the
Secretary.''.
(b) Conforming Amendment.--The table of sections for part III of
subchapter B of chapter 1 of the Internal Revenue Code of 1986 is
amended by adding after the item relating to section 121 the following
new item:

``Sec. 121A. Exclusion of gain from sale of qualified farm property.''.
(c) Effective Date.--The amendment made by this section shall apply
to any sale or exchange on or after the date of the enactment of this
Act, in taxable years ending after such date.
<all>