Permanent Estate Tax Relief Act of 2006
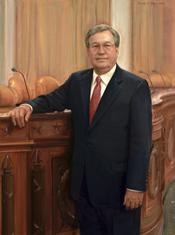 Rep. William M. Thomas (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read the second time. Placed on Senate Legislative Calendar under General Orders. Calendar No. 496.
June 26, 2006
View full timeline
Introduced in House
June 19, 2006
Referred to the House Committee on Ways and Means.
June 19, 2006
Rules Committee Resolution H. Res. 885 Reported to House. Rule provides for consideration of H.R. 5638 with 1 hour of general debate. Previous question shall be considered as ordered without intervening motions except motion to recommit with or without instructions. Measure will be considered read. A specified amendment is in order.
June 21, 2006 • 6:54 PM
Rule H. Res. 885 passed House.
June 22, 2006 • 12:48 PM
Mr. Thomas moved to consider.
June 22, 2006
Ms. Pelosi rose on the question of consideration and pursuant to clause 3, rule 16, demanded a vote on the question of consideration.
June 22, 2006 • 1:09 PM
On motion to consider Agreed to by recorded vote: 238 - 188 (Roll no. 312).
June 22, 2006
Considered under the provisions of rule H. Res. 885. (consideration: CR H4445-4467)
June 22, 2006 • 1:23 PM
Rule provides for consideration of H.R. 5638 with 1 hour of general debate. Previous question shall be considered as ordered without intervening motions except motion to recommit with or without instructions. Measure will be considered read. A specified amendment is in order.
June 22, 2006 • 1:24 PM
DEBATE - The House proceeded with one hour of debate on H.R. 5638.
June 22, 2006 • 1:24 PM
DEBATE - The House continued with debate on H.R. 5638.
June 22, 2006 • 1:25 PM
The previous question was ordered pursuant to the rule.
June 22, 2006 • 2:48 PM
Mr. Rangel moved to recommit with instructions to Ways and Means. (consideration: CR H4461-4464; text: CR H4461-4462)
June 22, 2006 • 2:48 PM
Floor summary: DEBATE - The House proceeded with ten minutes of debate on the motion to recommit with instructions, pending reservation of a a point of order.
June 22, 2006 • 2:49 PM
Point of order sustained against the motion to recommit with instructions.
June 22, 2006 • 2:53 PM
Mr. Thomas raised a point of order against the motion to recommit with instructions. Mr. Thomas stated that the provisions of the motion to recommit were not germane to the bill. Sustained by the Chair.
June 22, 2006 • 2:53 PM
Mr. Rangel appealed the ruling of the chair.
June 22, 2006 • 2:58 PM
Mr. Thomas moved to table the motion to appeal the ruling of the chair
June 22, 2006 • 3:05 PM
On motion to table the motion to appeal the ruling of the chair Agreed to by the Yeas and Nays: 229 - 195 (Roll no. 313).
June 22, 2006 • 3:28 PM
Mr. Pomeroy moved to recommit with instructions to Ways and Means. (consideration: CR H4464-4466; text: CR H4464-4465)
June 22, 2006 • 3:28 PM
DEBATE - The House proceeded with 10 minutes of debate on the Pomeroy motion to recommit with instructions. The instructions contained in the motion seek to require the bill to be reported back to the House with an amendment inserting a complete new text entitled "Certain and Immediate Estate Tax Relief Act of 2006".
June 22, 2006 • 3:29 PM
The previous question on the motion to recommit with instructions was ordered without objection. (consideration: CR H4465)
June 22, 2006 • 3:34 PM
On motion to recommit with instructions Failed by recorded vote: 182 - 236 (Roll no. 314). (consideration: CR H4464-4466)
June 22, 2006 • 3:51 PM
Passed/agreed to in House: On passage Passed by recorded vote: 269 - 156 (Roll no. 315).(text: CR H4445-4448)
June 22, 2006 • 4:00 PM
Motion to reconsider laid on the table Agreed to without objection.
June 22, 2006 • 4:00 PM
On passage Passed by recorded vote: 269 - 156 (Roll no. 315). (text: CR H4445-4448)
June 22, 2006 • 4:00 PM
Received in the Senate. Read the first time. Placed on Senate Legislative Calendar under Read the First Time.
June 23, 2006
Read the second time. Placed on Senate Legislative Calendar under General Orders. Calendar No. 496.
June 26, 2006
Voting History
4 votes recorded • Roll call available
HOUSE
Roll Call AvailableJune 22, 2006 at 4:00 PM
On Passage
Majority required: 1/2 (50%)
269 - 156
HOUSE
Roll Call AvailableJune 22, 2006 at 3:51 PM
On Motion to Recommit with Instructions
Majority required: 1/2 (50%)
182 - 236
HOUSE
Roll Call AvailableJune 22, 2006 at 3:28 PM
Table Appeal of the Ruling of the Chair
Majority required: 1/2 (50%)
229 - 195
Floor Debate
22 membersWhat members said about H.R. 5638 on the floor



 +17
Floor Debate
22 membersWhat members said about H.R. 5638 on the floor
Mr. Speaker, pursuant to House Resolution 885, I call up the bill (H.R. 5638) to amend the Internal Revenue Code of 1986 to increase the unified credit against the estate tax to an exclusion…
Mr. Speaker, I rise in opposition to the bill, H.R. 5638, the ``Permanent Estate Tax Relief Act of 2006.'' Mr. Speaker, I have voted for estate tax relief before but I oppose this bill because it is…
Mr. Speaker, I yield myself such time as I may consume. (Ms. SLAUGHTER asked and was given permission to revise and extend her remarks.) Mr. Speaker, I appreciate my Republican colleagues for…
Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, some may ask, why now are we taking up this bill? Why have we decided, that is, the majority, that at a time that our Nation is at…
Mr. Speaker, by direction of the Committee on Rules, I call up House Resolution 885 and ask for its immediate consideration. Mr. Speaker, for the purpose of debate only, I yield the customary 30…
Show 8 more

Mr. Speaker, I rise on the question of consideration. It is inappropriate to consider this bill until the Republican leadership schedules a vote on an increase in the minimum wage, which they are now…

This has nothing to do with the economy and everything to do with fiscal responsibility. Mr. Speaker, over the last 5\1/2\ years, this Republican majority has repeatedly pushed tax legislation that…

Mr. Speaker, I am disappointed with this bill and regret that I cannot support it. I do not support repeal of the estate tax, but I have long supported reforming it. So, I took hope when I heard that…
Mr. Speaker, I rise in opposition to H.R. 5638, the Permanent Estate Tax Relief Act of 2006, and I urge my colleagues to join me in voting against it. As a part-time farmer myself, I support tax…

Mr. Speaker, I thank the gentleman for yielding. To start out, let's have a little truth in labeling. The chairman of the Ways and Means Committee calls it a compromise bill. Compromise involves some…
Mr. Speaker, one of the interesting things about sitting through the debate and hearing all of the various points and wanting desperately to respond to each and every one of them, and not having the…
Mr. Speaker, the rule before us allows only one alternative. You know, it has been said before but it deserves repeating today: As our troops fight for democracy in Iraq, we ought to show that we can…

Thank you, Mr. Rangel, very much. What the other side wants you to believe today is that this is tax relief for the average American. What the majority whip said a couple of moments ago was…
Show 11 more
Mr. Speaker, the Chairman of the Ways and Means Committee has made a diligent and sincere effort to seek a compromise position on the estate tax issue, and he should be commended here in the House…
Mr. Speaker, I rise in opposition to this bill. I believe that estate taxes at 2001 levels were inherently unfair. And I voted to reform those levels by increasing the exemption and lowering the tax…
Mr. Speaker, last Thursday the House Republican Majority defeated a Democratic effort to increase the minimum wage. The current federal minimum wage, $5.15 per hour, has not been increased since…
Mr. Speaker, I am pleased to be able to be on the floor in support of this important piece of legislation. I am also grateful to the chairman not only for this piece of legislation but for the…

Mr. Speaker, I rise today in opposition to this this so-called ``Compromise'' Estate Tax proposal. This bill does make compromises--it compromises our children's futures, it compromises the future of…
Mr. Speaker, I thank the gentleman for yielding time on this important issue. I do rise in support of the permanent Estate Tax Relief Act of 2006, although I am mindful, as I listen to my good friend…

Mr. Speaker, today I rise in support of a permanent solution to the ``estate tax'' or what many call the ``death tax.'' Whatever name it goes by, it is a tax on the American dream. This country was…
Mr. Speaker, I want to begin by saying to my friend from Indiana, I think it would be helpful for this Congress to have the information about all of the family farms that have gone out of business in…

I thank the ranking leader for yielding me the time. Mr. Speaker, once again this House will consider an estate tax cut for the wealthiest people in the United States. Once again the Republican…
Mr. Speaker, I rise today to oppose the Permanent Estate Tax Relief Act of 2006. This legislation will exempt estates up to $5 million for an individual and $10 million for a couple; will tax the…
Thank you so much for yielding me time. I think we are getting closer to the truth when the previous speaker spoke out as to why we have an inheritance tax in the first place. And while he talked…
Bill Text
3 versions available
        [Congressional Bills 109th Congress]
[From the U.S. Government Publishing Office]
[H.R. 5638 Placed on Calendar Senate (PCS)]

Calendar No. 496
109th CONGRESS
2d Session
H. R. 5638

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

June 23, 2006

Read the first time

June 26, 2006

Read the second time and placed on the calendar

_______________________________________________________________________

AN ACT

To amend the Internal Revenue Code of 1986 to increase the unified
credit against the estate tax to an exclusion equivalent of $5,000,000
and to repeal the sunset provision for the estate and generation-
skipping taxes, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Permanent Estate Tax Relief Act of
2006''.

SEC. 2. REFORM AND EXTENSION OF ESTATE TAX AFTER 2009.

(a) Restoration of Unified Credit Against Gift Tax.--Paragraph (1)
of section 2505(a) of the Internal Revenue Code of 1986 (relating to
general rule for unified credit against gift tax), after the
application of subsection (g), is amended by striking ``(determined as
if the applicable exclusion amount were $1,000,000)''.
(b) Exclusion Equivalent of Unified Credit Equal to $5,000,000.--
Subsection (c) of section 2010 of such Code (relating to unified credit
against estate tax) is amended to read as follows:
``(c) Applicable Credit Amount.--
``(1) In general.--For purposes of this section, the
applicable credit amount is the amount of the tentative tax
which would be determined under the rate schedule set forth in
section 2001(c) if the amount with respect to which such
tentative tax is to be computed were the applicable exclusion
amount.
``(2) Applicable exclusion amount.--
``(A) In general.--For purposes of this subsection,
the applicable exclusion amount is $5,000,000.
``(B) Inflation adjustment.--In the case of any
decedent dying in a calendar year after 2010, the
dollar amount in subparagraph (A) shall be increased by
an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment
determined under section 1(f)(3) for such
calendar year by substituting `calendar year
2009' for `calendar year 1992' in subparagraph
(B) thereof.
If any amount as adjusted under the preceding sentence
is not a multiple of $100,000, such amount shall be
rounded to the nearest multiple of $100,000.''.
(c) Rate Schedule.--
(1) In general.--Subsection (c) of section 2001 of such
Code (relating to rate schedule) is amended to read as follows:
``(c) Rate Schedule.--The tentative tax is equal to the sum of--
``(1) the product of the rate specified in section
1(h)(1)(C) in effect on the date of the decedent's death
multiplied by so much of the sum described in subsection (b)(1)
as does not exceed $25,000,000, and
``(2) the product of twice the rate specified in section
1(h)(1)(C) in effect on the date of the decedent's death
multiplied by so much of the sum described in subsection (b)(1)
as equals or exceeds $25,000,000.''.
(2) Conforming amendment.--Section 2502(a) of such Code
(relating computation of tax), after the application of
subsection (g), is amended by adding at the end the following
flush sentence:
``In computing the tentative tax under section 2001(c) for purposes of
this subsection, `the last day of the calendar year in which the gift
was made' shall be substituted for `the date of the decedent's death'
each place it appears in such section.''.
(d) Modifications of Estate and Gift Taxes to Reflect Differences
in Unified Credit Resulting From Different Tax Rates.--
(1) Estate tax.--
(A) In general.--Section 2001(b)(2) of such Code
(relating to computation of tax) is amended by striking
``if the provisions of subsection (c) (as in effect at
the decedent's death)'' and inserting ``if the
modifications described in subsection (g)''.
(B) Modifications.--Section 2001 of such Code is
amended by adding at the end the following new
subsection:
``(g) Modifications to Gift Tax Payable to Reflect Different Tax
Rates.--For purposes of applying subsection (b)(2) with respect to 1 or
more gifts, the rates of tax under subsection (c) in effect at the
decedent's death shall, in lieu of the rates of tax in effect at the
time of such gifts, be used both to compute--
``(1) the tax imposed by chapter 12 with respect to such
gifts, and
``(2) the credit allowed against such tax under section
2505, including in computing--
``(A) the applicable credit amount under section
2505(a)(1), and
``(B) the sum of the amounts allowed as a credit
for all preceding periods under section 2505(a)(2).
For purposes of paragraph (2)(A), the applicable credit amount
for any calendar year before 1998 is the amount which would be
determined under section 2010(c) if the applicable exclusion
amount were the dollar amount under section 6018(a)(1) for such
year.''.
(2) Gift tax.--Section 2505(a) of such Code (relating to
unified credit against gift tax), after the application of
subsection (g), is amended by adding at the end the following
new flush sentence:
``For purposes of applying paragraph (2) for any calendar year, the
rates of tax used in computing the tax under section 2502(a)(2) for
such calendar year shall, in lieu of the rates of tax in effect for
preceding calendar periods, be used in determining the amounts
allowable as a credit under this section for all preceding calendar
periods.''.
(e) Repeal of Deduction for State Death Taxes.--
(1) In general.--Section 2058 of such Code (relating to
State death taxes) is amended by adding at the end the
following:
``(c) Termination.--This section shall not apply to the estates of
decedents dying after December 31, 2009.''.
(2) Conforming amendment.--Section 2106(a)(4) of such Code
is amended by adding at the end the following new sentence:
``This paragraph shall not apply to the estates of decedents
dying after December 31, 2009.''.
(f) Effective Date.--The amendments made by this section shall
apply to estates of decedents dying, generation-skipping transfers, and
gifts made, after December 31, 2009.
(g) Additional Modifications to Estate Tax.--
(1) In general.--The following provisions of the Economic
Growth and Tax Relief Reconciliation Act of 2001, and the
amendments made by such provisions, are hereby repealed:
(A) Subtitles A and E of title V.
(B) Subsection (d), and so much of subsection
(f)(3) as relates to subsection (d), of section 511.
(C) Paragraph (2) of subsection (b), and paragraph
(2) of subsection (e), of section 521.
The Internal Revenue Code of 1986 shall be applied as if such
provisions and amendments had never been enacted.
(2) Sunset not to apply to title v of egtrra.--Section 901
of the Economic Growth and Tax Relief Reconciliation Act of
2001 shall not apply to title V of such Act.
(3) Repeal of deadwood.--
(A) Sections 2011, 2057, and 2604 of the Internal
Revenue Code of 1986 are hereby repealed.
(B) The table of sections for part II of subchapter
A of chapter 11 of such Code is amended by striking the
item relating to section 2011.
(C) The table of sections for part IV of subchapter
A of chapter 11 of such Code is amended by striking the
item relating to section 2057.
(D) The table of sections for subchapter A of
chapter 13 of such Code is amended by striking the item
relating to section 2604.

SEC. 3. UNIFIED CREDIT INCREASED BY UNUSED UNIFIED CREDIT OF DECEASED
SPOUSE.

(a) In General.--Subsection (c) of section 2010 of the Internal
Revenue Code of 1986 (defining applicable credit amount), as amended by
section 2(b), is amended by striking paragraph (2) and inserting the
following new paragraphs:
``(2) Applicable exclusion amount.--For purposes of this
subsection, the applicable exclusion amount is the sum of--
``(A) the basic exclusion amount, and
``(B) in the case of a surviving spouse, the
aggregate deceased spousal unused exclusion amount.
``(3) Basic exclusion amount.--
``(A) In general.--For purposes of this subsection,
the basic exclusion amount is $5,000,000.
``(B) Inflation adjustment.--In the case of any
decedent dying in a calendar year after 2010, the
dollar amount in subparagraph (A) shall be increased by
an amount equal to--
``(i) such dollar amount, multiplied by
``(ii) the cost-of-living adjustment
determined under section 1(f)(3) for such
calendar year by substituting `calendar year
2009' for `calendar year 1992' in subparagraph
(B) thereof.
If any amount as adjusted under the preceding sentence
is not a multiple of $100,000, such amount shall be
rounded to the nearest multiple of $100,000.
``(4) Aggregate deceased spousal unused exclusion amount.--
For purposes of this subsection, the term `aggregate deceased
spousal unused exclusion amount' means the lesser of--
``(A) the basic exclusion amount, or
``(B) the sum of the deceased spousal unused
exclusion amounts of the surviving spouse.
``(5) Deceased spousal unused exclusion amount.--For
purposes of this subsection, the term `deceased spousal unused
exclusion amount' means, with respect to the surviving spouse
of any deceased spouse dying after December 31, 2009, the
excess (if any) of--
``(A) the applicable exclusion amount of the
deceased spouse, over
``(B) the amount with respect to which the
tentative tax is determined under section 2001(b)(1) on
the estate of such deceased spouse.
``(6) Special rules.--
``(A) Election required.--A deceased spousal unused
exclusion amount may not be taken into account by a
surviving spouse under paragraph (5) unless the
executor of the estate of the deceased spouse files an
estate tax return on which such amount is computed and
makes an election on such return that such amount may
be so taken into account. Such election, once made,
shall be irrevocable. No election may be made under
this subparagraph if such return is filed after the
time prescribed by law (including extensions) for
filing such return.
``(B) Examination of prior returns after expiration
of period of limitations with respect to deceased
spousal unused exclusion amount.--Notwithstanding any
period of limitation in section 6501, after the time
has expired under section 6501 within which a tax may
be assessed under chapter 11 or 12 with respect to a
deceased spousal unused exclusion amount, the Secretary
may examine a return of the deceased spouse to make
determinations with respect to such amount for purposes
of carrying out this subsection.
``(7) Regulations.--The Secretary shall prescribe such
regulations as may be necessary or appropriate to carry out
this subsection.''.
(b) Conforming Amendments.--
(1) Paragraph (1) of section 2505(a) of such Code, as
amended by section 2, is amended to read as follows:
``(1) the applicable credit amount under section 2010(c)
which would apply if the donor died as of the end of the
calendar year, reduced by''.
(2) Section 2631(c) of such Code is amended by striking
``the applicable exclusion amount'' and inserting ``the basic
exclusion amount''.
(3) Section 6018(a)(1) of such Code, after the application
of section 2(g), is amended by striking ``applicable exclusion
amount'' and inserting ``basic exclusion amount''.
(c) Effective Date.--The amendments made by this section shall
apply to estates of decedents dying, generation-skipping transfers, and
gifts made, after December 31, 2009.

SEC. 4. DEDUCTION FOR QUALIFIED TIMBER GAIN.

(a) In General.--Part I of subchapter P of chapter 1 of the
Internal Revenue Code of 1986 is amended by adding at the end the
following new section:

``SEC. 1203. DEDUCTION FOR QUALIFIED TIMBER GAIN.

``(a) In General.--In the case of a taxpayer which elects the
application of this section for a taxable year, there shall be allowed
a deduction against gross income equal to 60 percent of the lesser of--
``(1) the taxpayer's qualified timber gain for such year,
or
``(2) the taxpayer's net capital gain for such year.
``(b) Qualified Timber Gain.--For purposes of this section, the
term `qualified timber gain' means, with respect to any taxpayer for
any taxable year, the excess (if any) of--
``(1) the sum of the taxpayer's gains described in
subsections (a) and (b) of section 631 for such year, over
``(2) the sum of the taxpayer's losses described in such
subsections for such year.
``(c) Special Rules for Pass-Thru Entities.--In the case of any
qualified timber gain of a pass-thru entity (as defined in section
1(h)(10))--
``(1) the election under this section shall be made
separately by each taxpayer subject to tax on such gain, and
``(2) the Secretary may prescribe such regulations as are
appropriate to apply this section to such gain.
``(d) Termination.--No disposition of timber after December 31,
2008, shall be taken into account under subsection (b).''.
(b) Coordination With Maximum Capital Gains Rates.--
(1) Taxpayers other than corporations.--Paragraph (2) of
section 1(h) of such Code is amended to read as follows:
``(2) Reduction of net capital gain.--For purposes of this
subsection, the net capital gain for any taxable year shall be
reduced (but not below zero) by the sum of--
``(A) the amount which the taxpayer takes into
account as investment income under section
163(d)(4)(B)(iii), and
``(B) in the case of a taxable year with respect to
which an election is in effect under section 1203, the
lesser of--
``(i) the amount described in paragraph (1)
of section 1203(a), or
``(ii) the amount described in paragraph
(2) of such section.''.
(2) Corporations.--Section 1201 of such Code is amended by
redesignating subsection (b) as subsection (c) and inserting
after subsection (a) the following new subsection:
``(b) Qualified Timber Gain not Taken Into Account.--For purposes
of this section, in the case of a corporation with respect to which an
election is in effect under section 1203, the net capital gain for any
taxable year shall be reduced (but not below zero) by the corporation's
qualified timber gain (as defined in section 1203(b)).''.
(c) Deduction Allowed Whether or not Individual Itemizes Other
Deductions.--Subsection (a) of section 62 of such Code is amended by
inserting before the last sentence the following new paragraph:
``(21) Qualified timber gains.--The deduction allowed by
section 1203.''.
(d) Deduction Allowed in Computing Adjusted Current Earnings.--
Subparagraph (C) of section 56(g)(4) of such Code is amended by adding
at the end the following new clause:
``(vii) Deduction for qualified timber
gain.--Clause (i) shall not apply to any
deduction allowed under section 1203.''.
(e) Deduction Allowed in Computing Taxable Income of Electing Small
Business Trusts.--Subparagraph (C) of section 641(c)(2) of such Code is
amended by inserting after clause (iii) the following new clause:
``(iv) The deduction allowed under section
1203.''.
(f) Conforming Amendments.--
(1) Subparagraph (B) of section 172(d)(2) of such Code is
amended to read as follows:
``(B) the exclusion under section 1202 and the
deduction under section 1203 shall not be allowed.''.
(2) Paragraph (4) of section 642(c) of such Code is amended
by striking the first sentence and inserting the following:
``To the extent that the amount otherwise allowable as a
deduction under this subsection consists of gain described in
section 1202(a) or qualified timber gain (as defined in section
1203(b)), proper adjustment shall be made for any exclusion
allowable to the estate or trust under section 1202 and for any
deduction allowable to the estate or trust under section
1203.''.
(3) Paragraph (3) of section 643(a) of such Code is amended
by striking the last sentence and inserting the following:
``The exclusion under section 1202 and the deduction under
section 1203 shall not be taken into account.''.
(4) Subparagraph (C) of section 643(a)(6) of such Code is
amended to read as follows:
``(C) Paragraph (3) shall not apply to a foreign
trust. In the case of such a trust--
``(i) there shall be included gains from
the sale or exchange of capital assets, reduced
by losses from such sales or exchanges to the
extent such losses do not exceed gains from
such sales or exchanges, and
``(ii) the deduction under section 1203
shall not be taken into account.''.
(5) Paragraph (4) of section 691(c) of such Code is amended
by inserting ``1203,'' after ``1202,''.
(6) Paragraph (2) of section 871(a) of such Code is amended
by striking ``section 1202'' and inserting ``sections 1202 and
1203''.
(7) The table of sections for part I of subchapter P of
chapter 1 of such Code is amended by adding at the end the
following new item:

``Sec. 1203. Deduction for qualified timber gain.''.
(g) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to taxable years ending after the date of the enactment
of this Act.
(2) Taxable years which include date of enactment.--In the
case of any taxable year which includes the date of the
enactment of this Act, for purposes of the Internal Revenue
Code of 1986, the taxpayer's qualified timber gain shall not
exceed the excess that would be described in section 1203(b) of
such Code, as added by this section, if only dispositions of
timber after such date were taken into account.

Passed the House of Representatives June 22, 2006.

Attest:

KAREN L. HAAS,

Clerk.
Calendar No. 496

109th CONGRESS

2d Session

H. R. 5638

_______________________________________________________________________

AN ACT

To amend the Internal Revenue Code of 1986 to increase the unified
credit against the estate tax to an exclusion equivalent of $5,000,000
and to repeal the sunset provision for the estate and generation-
skipping taxes, and for other purposes.

_______________________________________________________________________

June 26, 2006

Read the second time and placed on the calendar