To provide tax relief to growers affected by citrus canker.
What it does: Inserts new text wherever appropriate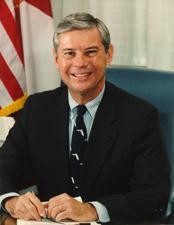 Sen. Bob Graham (D-FL)
Inserts new text wherever appropriate
InsertsInserted: SEC. . CITRUS CANKER TREE RELIEF.
Inserted: (a) Ratable Inclusion.
Inserted: (1) In general.--Part I of subchapter Q of chapter 1 (relating to income averaging) is amended by inserting after section 1301 the following new section:
Inserted: "SEC. 1302. RATABLE INCOME INCLUSION FOR CITRUS CANKER TREE PAYMENTS.
Inserted: "(a) In general.--At the election of the taxpayer, any amount taken into account as income or gain by reason of receiving a citrus canker tree payment shall be included in the income of the taxpayer ratably over the 10-year period beginning with the taxable year in which the payment is received or accrued by the taxpayer. Such election shall be made on the return of tax for such taxable year in such manner as the Secretary prescribed, and, once made shall be irrevocable.
Inserted: "(b) Citrus Canker Tree Payment.--For purposes of subsection (a), the term 'citrus canker tree payment' means a payment made to an owner of a commercial citrus grove to recover income that was lost as a result of the removal of commercial citrus trees to control canker under the amendments to the citrus canker regulations (7 C.F.R. 301) made by the final rule published in the Federal Register by the Secretary of Agriculture on June 18, 2001 (66 Fed. Reg. 32713, Docket No. 00-37-4)."
Inserted: (2) Clerical amendment.--The table of sections for part I of subchapter Q of chapter is amended by inserting after the item relating to section 1301 the following new item:
Inserted: SEC. 1302. RATABLE INCOME INCLUSION FOR CITRUS CANKER TREE PAYMENTS.".
Inserted: (b) Expansion of period within which converted Citrus Tree Property Must be Replaced.--Section 1033 (relating to period within which property must be replaced) is amended by redesignating subsection (k) as subsection (1) and by inserting after subsection (j) the following new subsection:
Inserted: "(k) Commercial Trees Destroyed Because of Citrus Tree Canker.--In the case of commercial citrus trees which are compulsorily or involuntarily converted under a public order as a result of the citrus tree canker, clause (i) of subsection (a)(2)(B) shall be applied as if such clause reads: '4 years after close of the first taxable year in which any part of the gain upon conversion is realized, or such additional period after the close of such taxable year as determined appropriate by the Secretary on a regional basis if a State or Federal plant health authority determines with respect to such region that the land on which such trees grew is not free from the bacteria that causes citrus tree canker'.".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning before, on, or after the date of the enactment of this Act.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 649. Mr. GRAHAM of Florida submitted an amendment intended to be proposed by him to the bill S. 1054, to provide for reconciliation pursuant to section 201 of the concurrent resolution on the budget for fiscal year 2004; as follows:
At the appropriate place insert the following:
SEC. . CITRUS CANKER TREE RELIEF.
(a) Ratable Inclusion.
(1) In general.--Part I of subchapter Q of chapter 1 (relating to income averaging) is amended by inserting after section 1301 the following new section:
“SEC. 1302. RATABLE INCOME INCLUSION FOR CITRUS CANKER TREE PAYMENTS.
“(a) In general.--At the election of the taxpayer, any amount taken into account as income or gain by reason of receiving a citrus canker tree payment shall be included in the income of the taxpayer ratably over the 10-year period beginning with the taxable year in which the payment is received or accrued by the taxpayer. Such election shall be made on the return of tax for such taxable year in such manner as the Secretary prescribed, and, once made shall be irrevocable.
“(b) Citrus Canker Tree Payment.--For purposes of subsection (a), the term ‘citrus canker tree payment' means a payment made to an owner of a commercial citrus grove to recover income that was lost as a result of the removal of commercial citrus trees to control canker under the amendments to the citrus canker regulations (7 C.F.R. 301) made by the final rule published in the Federal Register by the Secretary of Agriculture on June 18, 2001 (66 Fed. Reg. 32713, Docket No. 00-37-4).”
(2) Clerical amendment.--The table of sections for part I of subchapter Q of chapter is amended by inserting after the item relating to section 1301 the following new item:
SEC. 1302. RATABLE INCOME INCLUSION FOR CITRUS CANKER TREE PAYMENTS.”.
(b) Expansion of period within which converted Citrus Tree Property Must be Replaced.--Section 1033 (relating to period within which property must be replaced) is amended by redesignating subsection (k) as subsection (1) and by inserting after subsection (j) the following new subsection:
“(k) Commercial Trees Destroyed Because of Citrus Tree Canker.--In the case of commercial citrus trees which are compulsorily or involuntarily converted under a public order as a result of the citrus tree canker, clause (i) of subsection (a)(2)(B) shall be applied as if such clause reads: ‘4 years after close of the first taxable year in which any part of the gain upon conversion is realized, or such additional period after the close of such taxable year as determined appropriate by the Secretary on a regional basis if a State or Federal plant health authority determines with respect to such region that the land on which such trees grew is not free from the bacteria that causes citrus tree canker'.”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning before, on, or after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
May 15, 2003
View full timeline
Senate amendment submitted
May 15, 2003
Senate amendment proposed (on the floor): Amendment SA 649 proposed by Senator Baucus for Senator Graham FL.(consideration: CR S6451-6456; text: CR S6455)
May 15, 2003
Senate amendment agreed to: Amendment SA 649 agreed to in Senate by Unanimous Consent.
May 15, 2003
Amendment SA 649 proposed by Senator Baucus for Senator Graham FL. (consideration: CR S6451-6456; text: CR S6455) To provide tax relief to growers affected by citrus canker.
May 15, 2003
Amendment SA 649 agreed to in Senate by Unanimous Consent.
May 15, 2003