To increase funds made available for assessments of critical reservoirs and dams in the State of Hawaii.
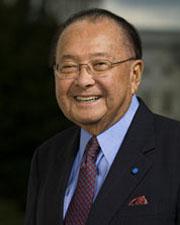 Sen. Daniel K. Inouye (D-HI)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Amendment SA 3673 not agreed to in Senate by Yea-Nay Vote. 43 - 53. Record Vote Number: 109.
May 3, 2006
View full timeline
Roll call votes on amendments in Senate: Amendment SA 3673 not agreed to in Senate by Yea-Nay Vote. 43 - 53. Record Vote Number: 109.
May 3, 2006
Senate amendment not agreed to: Amendment SA 3673 not agreed to in Senate by Yea-Nay Vote. 43 - 53. Record Vote Number: 109.
May 3, 2006
Senate amendment proposed (on the floor): Amendment SA 3673 proposed by Senator Inouye.
May 3, 2006
Amendment SA 3673 proposed by Senator Inouye. (consideration: CR S3966-3967; text: CR S3966) To increase funds made available for assessments of critical reservoirs and dams in the State of Hawaii.
May 3, 2006
Amendment SA 3673 not agreed to in Senate by Yea-Nay Vote. 43 - 53. Record Vote Number: 109.
May 3, 2006
Senate amendment submitted
April 27, 2006
Votes
1 roll call on this amendment
Text
Submitted
AMENDMENTS SUBMITTED AND PROPOSED

SA 3671. Mr. COLEMAN submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered
to lie on the table.
SA 3672. Mr. CORNYN (for himself and Mrs. Hutchison)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra.
SA 3673. Mr. INOUYE submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3674. Mr. NELSON, of Florida submitted an amendment
intended to be proposed by him to the bill H.R. 4939, supra;
which was ordered to lie on the table.
SA 3675. Mr. MENENDEZ (for himself, Mr. Lautenberg, Mr.
Inouye, Mrs. Clinton, and Mr. Lieberman) submitted an
amendment intended to be proposed by him to the bill H.R.
4939, supra.
SA 3676. Mr. BENNETT (for himself and Mr. Kohl) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3677. Mr. VOINOVICH (for himself and Mr. DeWine)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra; which was ordered to lie on the table.
SA 3678. Mr. MENENDEZ (for himself, Mr. Leahy, Mr. Durbin,
Mr. Sarbanes, and Mr. Lautenberg) submitted an amendment
intended to be proposed by him to the bill H.R. 4939, supra;
which was ordered to lie on the table.
SA 3679. Mr. SPECTER submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3680. Mr. FEINGOLD submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3681. Mr. VITTER submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3682. Mr. BIDEN submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3683. Mr. BIDEN submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3684. Ms. LANDRIEU submitted an amendment intended to be
proposed by her to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3685. Mr. LIEBERMAN submitted an amendment intended to
be proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3686. Mr. KENNEDY (for himself, Mr. Biden, and Mr.
Leahy) submitted an amendment intended to be proposed by him
to the bill H.R. 4939, supra; which was ordered to lie on the
table.
SA 3687. Mr. KENNEDY (for himself and Mr. Leahy) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3688. Mr. KENNEDY submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra.
SA 3689. Mr. KENNEDY submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3690. Mr. KENNEDY submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3691. Mr. KENNEDY submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3692. Mr. FRIST (for himself, Mr. Santorum, and Mr.
Ensign) submitted an amendment intended to be proposed by him
to the bill H.R. 4939, supra; which was ordered to lie on the
table.
SA 3693. Mr. OBAMA (for himself and Mr. Coburn) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra.
SA 3694. Mr. OBAMA (for himself and Mr. Coburn) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra.
SA 3695. Mr. OBAMA (for himself and Mr. Coburn) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra.
SA 3696. Mr. OBAMA (for himself and Mr. Coburn) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3697. Mr. OBAMA (for himself and Mr. Coburn) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra.
SA 3698. Mr. BURNS (for himself and Mr. Rockefeller)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra; which was ordered to lie on the table.
SA 3699. Mr. CORNYN (for himself, Ms. Landrieu, Mrs.
Hutchison, and Mr. Nelson, of Florida) submitted an amendment
intended to be proposed by him to the bill H.R. 4939, supra.
SA 3700. Mr. DOMENICI (for himself, Mr. Grassley, and Mr.
Stevens) submitted an amendment intended to be proposed by
him to the bill H.R. 4939, supra; which was ordered to lie on
the table.
SA 3701. Mr. ALLARD (for himself, Mr. Durbin, and Ms.
Mikulski) submitted an amendment intended to be proposed by
him to the bill H.R. 4939, supra.
SA 3702. Mr. CHAMBLISS (for himself and Mr. Isakson)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra.
SA 3703. Mr. KOHL submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3704. Mr. THUNE submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3705. Mr. OBAMA submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3706. Mr. LEVIN (for himself, Mr. Dorgan, Ms. Stabenow,
and Mr. Conrad) submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3707. Mr. FRIST submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3708. Mr. BYRD submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra.
SA 3709. Mr. BYRD (for himself, Mr. Carper, and Mr.
Lautenberg) proposed an amendment to the bill H.R. 4939,
supra.
SA 3710. Mr. LEVIN (for himself, Ms. Collins, and Mr. Reed)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra.
SA 3711. Mr. NELSON, of Florida submitted an amendment
intended to be proposed by him to the bill H.R. 4939, supra;
which was ordered to lie on the table.
SA 3712. Mr. ALLARD submitted an amendment intended to be
proposed to amendment SA 3645 proposed by Mr. SALAZAR (for
himself and Mr. Baucus) to the bill H.R. 4939, supra; which
was ordered to lie on the table.
SA 3713. Mr. BURR proposed an amendment to the bill H.R.
4939, supra.
SA 3714. Mrs. MURRAY (for Mr. Harkin) proposed an amendment
to the bill H.R. 4939, supra.

[[Page S3725]]

SA 3715. Mr. CONRAD (for himself, Mrs. Clinton, and Mr.
Dodd) proposed an amendment to the bill H.R. 4939, supra.
SA 3716. Mrs. MURRAY (for Mr. Kennedy (for himself, Mr.
Biden, and Mr. Leahy)) proposed an amendment to the bill H.R.
4939, supra.
SA 3717. Mr. BIDEN submitted an amendment intended to be
proposed by him to the bill H.R. 4939, supra; which was
ordered to lie on the table.
SA 3718. Mr. BIDEN (for himself and Mr. DeWine) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3719. Mr. BIDEN (for himself and Mr. DeWine) submitted
an amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3720. Mr. NELSON, of Florida submitted an amendment
intended to be proposed by him to the bill H.R. 4939, supra;
which was ordered to lie on the table.
SA 3721. Mr. NELSON, of Florida (for himself, Mr. Menendez,
Mr. Lieberman, Mr. Lautenberg, Mr. Kerry, and Mr. Reid)
submitted an amendment intended to be proposed by him to the
bill H.R. 4939, supra; which was ordered to lie on the table.
SA 3722. Mr. CORNYN (for himself and Mr. Kyl) proposed an
amendment to the bill H.R. 4939, supra.
SA 3723. Mr. SCHUMER (for himself and Mr. Reid) proposed an
amendment to the bill H.R. 4939, supra.
SA 3724. Mr. SCHUMER proposed an amendment to the bill H.R.
4939, supra.
SA 3725. Mr. SMITH (for himself and Mr. Wyden) submitted an
amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3726. Mr. SMITH (for himself and Mr. Wyden) submitted an
amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
SA 3727. Mr. DODD (for himself and Mr. Lott) submitted an
amendment intended to be proposed by him to the bill H.R.
4939, supra; which was ordered to lie on the table.
______

TEXT OF AMENDMENTS

SA 3671. Mr. COLEMAN submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 196, between lines 17 and 18, insert the following:

FEDERAL FUNDING FOR FIXED GUIDEWAY PROJECTS

Sec. 2901. The Federal Transit Administration's Dear
Colleague letter dated April 29, 2005 (C-05-05), which
requires fixed guideway projects to achieve a ``medium''
cost-effectiveness rating for the Federal Transit
Administration to recommend such projects for funding, shall
not apply to the Northstar Corridor Commuter Rail Project in
Minnesota.
______

SA 3672. Mr. CORNYN (for himself and Mrs. Hutchison) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

At the end of chapter 7 of title II, insert the following:

NATIONAL EMERGENCY GRANTS

Sec. __. In distributing unobligated funds described in
section 132(a)(2)(A) of the Workforce Investment Act of 1998
(29 U.S.C. 2862(a)(2)(A)) and appropriated for fiscal year
2006 for national emergency grants under section 173 of such
Act (29 U.S.C. 2918) (not including funds available for
Community-Based Job Training Grants under section 171(d) of
such Act (29 U.S.C. 2916(d)), the Secretary shall give
priority to States that--
(1) received national emergency grants under such section
173 to assist--
(A) individuals displaced by Hurricane Katrina; or
(B) individuals displaced by Hurricane Rita;
(2) continue to assist individuals described in
subparagraph (A), or individuals described in subparagraph
(B), of paragraph (1); and
(3) can demonstrate an ongoing need for funds to assist
individuals described in subparagraph (A), or individuals
described in subparagraph (B), of paragraph (1).
______

SA 3673. Mr. INOUYE submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

On page 246, line 1, strike ``$500,000'' and all that
follows through line 8 and insert ``$1,400,000, to remain
available until expended, for assistance with assessments of
critical reservoirs and dams in the State of Hawaii,
including the monitoring of dam structures: Provided, That
the amount provided under this heading is designated as an
emergency requirement pursuant to section 402 of H. Con. Res.
95 (109th Congress), the concurrent resolution on the budget
for fiscal year 2006.''.
______

SA 3674. Mr. NELSON of Florida submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 194, between lines 3 and 4, insert the following:

RECONSTITUTION AND REPAIR OF SANTA ROSA ISLAND RANGE COMPLEX AND
REPLACEMENT OF RANGE BUILDING, EGLIN AIR FORCE BASE, FLORIDA

Sec. 2806. (a) The amount appropriated by this chapter
under the heading ``Military Construction, Air Force'' is
hereby increased by $162,000,000.
(b) Of the amount appropriated by this chapter under the
heading ``Military Construction, Air Force'', as increased by
subsection (a), $162,000,000 shall be made available for the
reconstitution and repair of the Santa Rosa Island Range
Complex and the replacement of a range building at Eglin Air
Force Base, Florida.
(c) The amount made available under subsection (a) is
designated as an emergency requirement pursuant to section
402 of H. Con. Res. 95 (109th Congress), the concurrent
resolution on the budget for fiscal year 2006.
______

SA 3675. Mr. MENENDEZ (for himself, Mr. Lautenberg, Mr. Inouye, Mrs.
Clinton, and Mr. Lieberman) submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; as follows:

On page 237, between lines 6 and 7, insert the following:
For an additional amount for the training of employees of
the Bureau of Customs and Border Protection, $10,000,000, to
remain available until September 30, 2007: Provided, That the
amount provided under this heading is designated as an
emergency requirement pursuant to section 402 of H. Con. Res.
95 (109th Congress), the concurrent resolution on the budget
for fiscal year 2006.

On page 237, between lines 10 and 11, insert the following:
For an additional amount for the purchase of new container
inspection technology at ports in developing countries and
the training of local authorities, pursuant to section 70109
of title 46, United States Code, on the use of such
technology, $50,000,000, to remain available until September
30, 2007: Provided, That the amount provided under this
heading is designated as an emergency requirement pursuant to
section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.
For an additional amount for the implementation of section
70105 of title 46, United States Code, $12,000,000, to remain
available until September 30, 2007: Provided, That the amount
provided under this heading is designated as an emergency
requirement pursuant to section 402 of H. Con. Res. 95 (109th
Congress), the concurrent resolution on the budget for fiscal
year 2006.

TRANSPORTATION SECURITY ADMINISTRATION

transportation vetting and credentialing

For an additional amount for the implementation of section
70105 of title 46, United States Code, $13,000,000, to remain
available until September 30, 2007, of which $250,000 shall
be made available for the Secretary of Homeland Security's
preparation and submission to Congress of a plan, not later
than September 30, 2006, with specific annual benchmarks, to
inspect 100 percent of the cargo containers destined for the
United States: Provided, That the amount provided under this
heading is designated as an emergency requirement pursuant to
section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.

On page 237, line 25, strike ``$132,000,000'' and insert
``$232,000,000'': Provided, That the amount provided under
this heading is designated as an emergency requirement
pursuant to section 402 of H. Con. Res. 95 (109th Congress),
the concurrent resolution on the budget for fiscal year 2006.
______

SA 3676. Mr. BENNETT (for himself and Mr. Kohl) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

On page 135, after line 26, insert the following:

WILDLIFE HABITAT INCENTIVE PROGRAM

Sec. 2___. Funds made available for the wildlife habitat
incentive program established under section 1240N of the Food
Security Act of 1985 (16 U.S.C. 3839bb-1) under section
211(b) of the Agricultural Risk Protection Act of 2000
(Public Law 106-224; 7 U.S.C. 1421 note) and section 820 of
the Agriculture, Rural Development, Food and Drug
Administration, and Related Agencies Appropriations Act, 2001
(Public Law 106-387; 114 Stat. 1549A-59) shall remain
available until expended to carry out obligations made for
fiscal year 2001 and are not available for new obligations.

[[Page S3726]]

______

SA 3677. Mr. VOINOVICH (for himself and Mr. DeWine) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

On page 253, between lines 19 and 20, insert the following:

RICKENBACKER AIRPORT, COLUMBUS, OHIO

Sec. ____. The project numbered 4651 in section 1702 of the
Safe, Accountable, Flexible, Efficient Transportation Equity
Act: A Legacy for Users (119 Stat. 1434) is amended by
striking ``Grading, paving'' and all that follows through
``Airport'' and inserting ``Grading, paving, roads, and the
transfer of rail-to-truck for the intermodal facility at
Rickenbacker Airport, Columbus, OH''.
______

SA 3678. Mr. MENENDEZ (for himself, Mr. Leahy, Mr. Durbin, Mr.
Sarbanes, and Mr. Lautenberg) submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 89, line 9, strike ``$69,800,000'' and insert in
lieu thereof ``$129,800,000''.
______

SA 3679. Mr. SPECTER submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

PROHIBITION ON USE OF FUNDS FOR DOMESTIC ELECTRONIC SURVEILLANCE FOR
FOREIGN INTELLIGENCE PURPOSES UNLESS CONGRESS IS KEPT FULLY AND
CURRENTLY INFORMED

Sec. 7032. (a) Prohibition.--No funds appropriated by this
or any other Act may be obligated or expended to carry out
the NSA program, or any other program of electronic
surveillance within the United States for foreign
intelligence purposes, unless each of the following is met:
(1) The Select Committee on Intelligence of the Senate and
the Permanent Select Committee on Intelligence of the House
of Representatives, and each member of such committee, are
kept fully and currently informed of such program in
accordance with section 502 of the National Security Act of
1947 (50 U.S.C. 413a).
(2) The Committees on the Judiciary of the Senate and the
House of Representatives are kept fully and currently
informed of such program in accordance with section 503 of
the National Security Act of 1947 (50 U.S.C. 413b).
(b) Sense of Congress.--It is the sense of Congress that
the Executive Branch should inform the members of the
Committees on the Judiciary of the Senate and the House of
Representatives on the NSA program and any other program
described in subsection (a) in sufficient detail so as to
facilitate and ensure the discharge by such Committees of
their oversight responsibilities to determine the
constitutionality of Executive Branch actions.
(c) NSA Program Defined.--In this section, the term ``NSA
program'' means the program of the National Security Agency
on electronic surveillance within the United States for
foreign intelligence purposes the existence of which has been
acknowledged by President George W. Bush and other Executive
Branch officials on and after December 17, 2005, any
unacknowledged part of the program, and any associated
National Security Agency programs or activities.
______

SA 3680. Mr. FEINGOLD submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:
Sec.__. (A) The United States shall redeploy U.S. forces
from Iraq by December 31st, 2006, maintaining only a minimal
force sufficient for engaging directly in targeted counter-
terrorism activities, training Iraqi security forces, and
protecting U.S. infrastructure and personnel.
(B) Not later than 30 days after the enactment of this Act,
the President shall direct the Secretary of Defense, in
consultation with the Secretary of State, to provide to
Congress a report that includes the strategy for the
redeployment of U.S. forces Iraq by December 31st, 2006. The
strategy shall include the following:
(1) A flexible timeline for redeployment U.S. forces from
Iraq by December 31st, 2006;
(2) The number, size, and character of U.S. military units
needed in Iraq beyond December 31st, 2006, for purposes of
counter-terrorism activities, training Iraqi security forces,
and protecting U.S. infrastructure and personnel;
(3) A strategy for addressing the regional implications of
redeploying U.S. troops on a diplomatic, political, and
development level;
(4) A strategy for ensuring the safety and security of U.S.
forces in Iraq during and after the redeployment, and a
contingency plan for addressing dramatic changes in security
conditions that may require a limited number of U.S. forces
to remain in Iraq after December 31st, 2006; and
(5) A strategy for redeploying U.S. forces to effectively
engage and defeat global terrorist networks that threaten the
United States.
______

SA 3681. Mr. VITTER submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

Beginning on page 161, strike line 17 and all that follows
through page 162, line 4, and insert the following:

at the Inner Harbor Navigation Canal; and $80,000,000 shall
be used for incorporation of certain non-Federal levees in
Plaquemines Parish, and in Jefferson Parish in the vicinity
of Jean Lafitte, into the existing Federal levee system:
Provided further, That any project using funds appropriated
under this heading shall be initiated only after non-Federal
interests have entered into binding agreements with the
Secretary to pay 100 percent of the operation, maintenance,
repair, replacement, and rehabilitation costs of the project
and to hold and save the United States free from damages due
to the construction or operation and maintenance of the
project, except for damages due to the fault or negligence of
the United States or its contractors: Provided further, That
$621,500,000 of the amount shall be available only
______

SA 3682. Mr. BIDEN submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

At the appropriate place, insert:

SEC. _. SENSE OF THE SENATE ON LEGISLATION REPEALING FOSSIL
FUEL ENERGY TAX BREAKS.

(a) Findings.--The Senate finds the following:
(1) President Bush stated the following on April 20, 2005:
``With oil at more than $50 a barrel . . . energy companies
do not need taxpayer-funded incentives to explore for oil and
gas.''.
(2) President Bush stated the following on April 25, 2006:
``Record oil prices and large cash flows . . . mean that
Congress has to understand that these energy companies don't
need unnecessary tax breaks. ''.
(3) The price of a barrel of crude oil recently exceeded
$75, and remains above $72.
(4) The average price of a gallon of regular gasoline is
currently over $2.90, and exceeds $3 in many parts of the
country.
(5) Since 2001, the median family income has not kept pace
with the cost of living, and the price of a gallon of regular
gas has increased over 100 percent.
(6) There have been 2,600 mergers in the oil and gas
industry in the past decade.
(7) The profits of the oil and gas industry reached
historic highs last year, including over $36 billion in
profits for Exxon Mobil, the most ever for a single
corporation.
(8) On March 14 of this year, the Senate Committee on the
Judiciary conducted an antitrust oversight hearing on the
effect of oil and gas industry consolidation on consumer
prices, and at that hearing the chief executives of six major
oil and gas companies stated under oath that they do not need
additional incentives to conduct their businesses.
(9) The aggregate budget deficit of the United States for
the period of fiscal years 2002 to 2011 is projected to total
$2.7 trillion.
(b) Sense of the Senate.--It is the sense of the Senate
that the Committee on Finance shall, within 90 days of the
date of the enactment of this Act, report legislation that
repeals the provisions of, and the amendments made by,
subtitle B of title XIII of the Energy Policy Act of 2005.
______

SA 3683. Mr. BIDEN submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. RESTORATION OF PHASEOUT OF PERSONAL EXEMPTIONS AND
OVERALL LIMITATION ON ITEMIZED DEDUCTIONS IN
ORDER TO FUND ONGOING OPERATIONS IN IRAQ AND
AFGHANISTAN.

(a) Personal Exemptions.--Paragraph (3) of section 151(d)
of the Internal Revenue Code of 1986 (relating to exemption
amount) is amended by striking subparagraphs (E) and (F).
(b) Limitations on Itemized Deductions.--Section 68 of the
Internal Revenue Code of 1986 is amended by striking
subsections (f) and (g).
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.

[[Page S3727]]

______

SA 3684. Ms. LANDRIEU submitted an amendment intended to be proposed
by her to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 1, line 1 of the amendment, insert ``as long as
$5,200,000,000 is provided under this heading'' after
``That''.
______

SA 3685. Mr. LIEBERMAN submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

strategic language security

Sec. 7032. (a) Annual Reports.--Not later than six months
after the date of the enactment of this Act, and annually
thereafter, the head of each covered agency shall submit to
Congress a report setting forth the following:
(1) The number of employees of such agency who speak, read,
or both speak and read a foreign language, set forth by--
(A) language in which speaking, reading, or both speaking
and reading proficiency exists;
(B) for each employee who speaks, reads, or both speaks and
reads such language proficiently, the level of speaking or
reading proficiency, as applicable, and the date such
proficiency was obtained; and
(C) for each such language--
(i) the rank and category of each employee who speaks such
language at any level of proficiency; and
(ii) the rank and category of each employee who reads such
language at any level of proficiency.
(2) The pedagogical capability of such agency with respect
to speaking or reading proficiency in various languages,
including--
(A) the number of full time and part-time instructors in
each language;
(B) the extent and nature of distance learning facilities;
(C) the extent and nature of field and overseas learning
facilities; and
(D) the availability and use of textbooks, dictionaries,
audio and video instructional materials, and online
instructional sites and materials.
(3) An estimate of the needs of such agency over the next
three to five years for personnel with speaking, reading, or
both speaking and reading proficiency in various foreign
languages, including--
(A) the number of personnel needed with speaking, reading,
or both speaking and reading proficiency in each such
language; and
(B) the percentage of each rank and category of personnel
of such agency of which personnel referred to in subparagraph
(A) would consist.
(4) An identification of the languages for which such
agency currently has a limited current need for personnel
with speaking, reading, or both speaking and reading
proficiency, but for which such agency could have an expanded
future need for such personnel, and an identification of the
minimum number of personnel with speaking, reading, or both
speaking and reading proficiency in such languages that is
required by such agency to maintain sufficient national
security readiness with respect to such languages.
(5) A description of any plans of such agency to employee,
or secure by contract, personnel with speaking, reading, or
both speaking and reading proficiency in each language
identified under paragraph (4) in order to meet the future
need of such agency for such personnel as described in that
paragraph.
(b) Covered Agency Defined.--In section, the term ``covered
agency'' means the following:
(1) The Department of Defense.
(2) The Department of State.
(3) The Office of the Director of National Intelligence
with respect to--
(A) the Office of the Director of National Intelligence;
and
(B) each agency under the direction of the Office of the
Director of National Intelligence.
______

SA 3686. Mr. KENNEDY (for himself, Mr. Biden, and Mr. Leahy)
submitted an amendment intended to be proposed by him to the bill H.R.
4939, making emergency supplemental appropriations for the fiscal year
ending September 30, 2006, and for other purposes; which was ordered to
lie on the table; as follows:

On page 126, between lines 12 and 13, insert the following:

UNITED STATES STRATEGY TO PROMOTE DEMOCRACY IN IRAQ

Sec. 1406. (a) Of the funds provided in this chapter for
the Economic Support Fund, not less than $96,000,000 should
be made available through the Bureau of Democracy, Human
Rights, and Labor of the Department of State, in coordination
with the United States Agency for International Development
where appropriate, to United States nongovernmental
organizations for the purpose of supporting broad-based
democracy assistance programs in Iraq that promote the long
term development of civil society, political parties,
election processes, and parliament in that country.
(b) The President shall include in each report submitted to
Congress under the United States Policy in Iraq Act (section
1227 of Public Law 109-163; 50 U.S.C. 1541 note; 119 Stat.
3465) a report on the extent to which funds appropriated in
this Act support a short-term and long-term strategy to
promote and develop democracy in Iraq. The report shall
include the following:
(1) A description of the objectives of the Secretary of
State to promote and develop democracy at the national,
regional, and provincial levels in Iraq, including
development of civil society, political parties, and
government institutions.
(2) The strategy to achieve such objectives.
(3) The schedule to achieve such objectives.
(4) The progress made toward achieving such objectives.
(5) The principal official within the United States
Government responsible for coordinating and implementing
democracy funding for Iraq.
______

SA 3687. Mr. KENNEDY (for himself and Mr. Leahy) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

On page 126, between lines 12 and 13, insert the following:

REPORTS TO CONGRESS ON PREPAREDNESS FOR CIVIL WAR IN IRAQ

Sec. 1406. (a) Reports Required.--Not later than 30 days
after the date of the enactment of this Act, and every 90
days thereafter, the President shall submit to Congress a
report setting for the determination of the President as to
whether there is a civil war in Iraq.
(b) Elements.--Each report required by subsection (a) shall
include the following:
(1) The criteria underlying the determination contained in
such report, including an assessment of--
(A) levels of sectarian violence;
(B) the numbers of civilians displaced;
(C) the degree to which government security forces exercise
effective control over major urban areas;
(D) the extent to which units of the security forces
(including army, police, and special forces) respond to
militia and party leaders rather than to their national
commands;
(E) the extent to which militias have organized or
conducted hostile actions against United States military
forces;
(F) the extent to which militias are providing security;
and
(G) the number of civilian casualties as a result of
sectarian violence.
(2) If in such report the President determines that there
is not a civil war in Iraq, a description (in unclassified
form) of--
(A) the efforts of the United States Government to help
avoid civil war in Iraq;
(B) the strategy to protect the Armed Forces of the United
States in the event of civil war in Iraq; and
(C) the strategy to ensure that the Armed Forces of the
United States will not take sides in the event of civil war
in Iraq.
(3) If in such report the President determines that there
is a civil war in Iraq, a description (in unclassified form)
of--
(A) the mission and duration of the Armed Forces of the
United States in Iraq;
(B) the strategy to protect the Armed Forces of the United
States while they remain in Iraq; and
(C) the strategy to ensure that the Armed Forces of the
United States will not take sides in the civil war in Iraq.
______

SA 3688. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; as follows:

At the appropriate place, insert the following:

SEC. __. FUNDING FOR THE COVERED COUNTERMEASURES PROCESS
FUND.

For an additional amount for funding the Covered
Countermeasures Process Fund under section 319F-4 of the
Public Health Service Act (42 U.S.C. 247d-6e), $289,000,000:
Provided, That the amounts provided for under this section
shall be designated as an emergency requirement pursuant to
section 402 of H. Con. Res. 95 (109th Congress): Provided
further, That amounts provided for under this section shall
remain available until expended.
______

SA 3689. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. FUNDING FOR THE COVERED COUNTERMEASURES PROCESS
FUND.

For an additional amount for funding the Covered
Countermeasures Process Fund under section 319F-4 of the
Public Health

[[Page S3728]]

Service Act (42 U.S.C. 247d-6e), $289,000,000: Provided, That
no funds appropriated under this Act or any other provision
of law shall be used to issue a declaration under section
319F-3(b) of such Act (42 U.S.C. 247d-6d(b)) that specifies
any countermeasure other than a vaccine for pandemic
influenza: Provided further, That the amounts provided for
under this section shall be designated as an emergency
requirement pursuant to section 402 of H. Con. Res. 95 (109th
Congress): Provided further, That amounts provided for under
this section shall remain available until expended.
______

SA 3690. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

TITLE __--PUBLIC READINESS AND EMERGENCY PREPAREDNESS

SEC. __01. SHORT TITLE,

This title may be cited as the ``Responsible Public
Readiness and Emergency Preparedness Act''.

SEC. __02. REPEAL.

The Public Readiness and Emergency Preparedness Act
(division C of the Department of Defense, Emergency
Supplemental Appropriations to Address Hurricanes in the Gulf
of Mexico, and Pandemic Influenza Act, 2006 (Public Law 109-
148)) is repealed.

SEC. __03. NATIONAL BIODEFENSE INJURY COMPENSATION PROGRAM.

(a) Establishment.--Section 224 of the Public Health
Service Act (42 U.S.C. 233) is amended by adding at the end
the following:
``(q) Biodefense Injury Compensation Program.--
``(1) Establishment.--There is established the Biodefense
Injury Compensation Program (referred to in this subsection
as the `Compensation Program') under which compensation may
be paid for death or any injury, illness, disability, or
condition that is likely (based on best available evidence)
to have been caused by the administration of a covered
countermeasure to an individual pursuant to a declaration
under subsection (p)(2).
``(2) Administration and interpretation.--The statutory
provisions governing the Compensation Program shall be
administered and interpreted in consideration of the program
goals described in paragraph (4)(B)(iii).
``(3) Procedures and standards.--The Secretary shall by
regulation establish procedures and standards applicable to
the Compensation Program that follow the procedures and
standards applicable under the National Vaccine Injury
Compensation Program established under section 2110, except
that the regulations promulgated under this paragraph shall
permit a person claiming injury or death related to the
administration of any covered countermeasure to file either--
``(A) a civil action for relief under subsection (p); or
``(B) a petition for compensation under this subsection.
``(4) Injury table.--
``(A) Inclusion.--For purposes of receiving compensation
under the Compensation Program with respect to a
countermeasure that is the subject of a declaration under
subsection (p)(2), the Vaccine Injury Table under section
2114 shall be deemed to include death and the injuries,
disabilities, illnesses, and conditions specified by the
Secretary under subparagraph (B)(ii).
``(B) Injuries, disabilities, illnesses, and conditions.--
``(i) Institute of medicine.--Not later than 30 days after
making a declaration described in subsection (p)(2), the
Secretary shall enter into a contract with the Institute of
Medicine, under which the Institute shall, within 180 days of
the date on which the contract is entered into, and
periodically thereafter as new information, including
information derived from the monitoring of those who were
administered the countermeasure, becomes available, provide
its expert recommendations on the injuries, disabilities,
illnesses, and conditions whose occurrence in one or more
individuals are likely (based on best available evidence) to
have been caused by the administration of a countermeasure
that is the subject of the declaration.
``(ii) Specification by secretary.--Not later than 30 days
after the receipt of the expert recommendations described in
clause (i), the Secretary shall, based on such
recommendations, specify those injuries, disabilities,
illnesses, and conditions deemed to be included in the
Vaccine Injury Table under section 2114 for the purposes
described in subparagraph (A).
``(iii) Program goals.--The Institute of Medicine, under
the contract under clause (i), shall make such
recommendations, the Secretary shall specify, under clause
(ii), such injuries, disabilities, illnesses, and conditions,
and claims under the Compensation Program under this
subsection shall be processed and decided taking into account
the following goals of such program:

``(I) To encourage persons to develop, manufacture, and
distribute countermeasures, and to administer covered
countermeasures to individuals, by limiting such persons'
liability for damages related to death and such injuries,
disabilities, illnesses, and conditions.
``(II) To encourage individuals to consent to the
administration of a covered countermeasure by providing
adequate and just compensation for damages related to death
and such injuries, disabilities, illnesses, or conditions.
``(III) To provide individuals seeking compensation for
damages related to the administration of a countermeasure
with a non-adversarial administrative process for obtaining
adequate and just compensation.

``(iv) Use of best available evidence.--The Institute of
Medicine, under the contract under clause (i), shall make
such recommendations, the Secretary shall specify, under
clause (ii), such injuries, disabilities, illnesses, and
conditions, and claims under the Compensation Program under
this subsection shall be processed and decided using the best
available evidence, including information from adverse event
reporting or other monitoring of those individuals who were
administered the countermeasure, whether evidence from
clinical trials or other scientific studies in humans is
available.
``(v) Application of section 2115.--With respect to section
2115(a)(2) as applied for purposes of this subsection, an
award for the estate of the deceased shall be--

``(I) if the deceased was under the age of 18, an amount
equal to the amount that may be paid to a survivor or
survivors as death benefits under the Public Safety Officers'
Benefits Program under subpart 1 of part L of title I of the
Omnibus Crime Control and Safe Streets Act of 1968 (42 U.S.C.
3796 et seq.); or
``(II) if the deceased was 18 years of age or older, the
greater of--

``(aa) the amount described in subclause (I); or
``(bb) the projected loss of employment income, except that
the amount under this item may not exceed an amount equal to
400 percent of the amount that applies under item (aa).
``(vi) Application of section 2116.--Section 2116(b) shall
apply to injuries, disabilities, illnesses, and conditions
initially specified or revised by the Secretary under clause
(ii), except that the exceptions contained in paragraphs (1)
and (2) of such section shall not apply.
``(C) Rule of construction.--Section 13632 (a)(3) of Public
Law 103-66 (107 Stat. 646) (making revisions by Secretary to
the Vaccine Injury Table effective on the effective date of a
corresponding tax) shall not be construed to apply to any
revision to the Vaccine Injury Table made under regulations
under this paragraph.
``(5) Application.--The Compensation Program applies to any
death or injury, illness, disability, or condition that is
likely (based on best available evidence) to have been caused
by the administration of a covered countermeasure to an
individual pursuant to a declaration under subsection (p)(2).
``(6) Special masters.--
``(A) Hiring.--In accordance with section 2112, the judges
of the United States Claims Court shall appoint a sufficient
number of special masters to address claims for compensation
under this subsection.
``(B) Budget authority.--There are appropriated to carry
out this subsection such sums as may be necessary for fiscal
year 2006 and each fiscal year thereafter. This subparagraph
constitutes budget authority in advance of appropriations and
represents the obligation of the Federal Government.
``(7) Covered countermeasure.--For purposes of this
subsection, the term `covered countermeasure' has the meaning
given to such term in subsection (p)(7)(A).
``(8) Funding.--Compensation made under the Compensation
Program shall be made from the same source of funds as
payments made under subsection (p).''.
(b) Effective Date.--This section shall take effect as of
November 25, 2002 (the date of enactment of the Homeland
Security Act of 2002 (Pub. L. 107-296; 116 Stat. 2135)).

SEC. __04. INDEMNIFICATION FOR MANUFACTURERS AND HEALTH CARE
PROFESSIONALS WHO ADMINISTER MEDICAL PRODUCTS
NEEDED FOR BIODEFENSE.

Section 224(p) of the Public Health Service Act (42 U.S.C.
233(p)) is amended--
(1) in the subsection heading by striking ``Smallpox'';
(2) in paragraph (1), by striking ``against smallpox'';
(3) in paragraph (2)--
(A) in the paragraph heading, by striking ``against
smallpox''; and
(B) in subparagraph (B), by striking clause (ii);
(4) by striking paragraph (3) and inserting the following:
``(3) Exclusivity; offset.--
``(A) Exclusivity.--With respect to an individual to which
this subsection applies, such individual may bring a claim
for relief under--
``(i) this subsection;
``(ii) subsection (q); or
``(iii) part C.
``(B) Election of alternatives.--An individual may only
pursue one remedy under subparagraph (A) at any one time
based on the same incident or series of incidents. An
individual who elects to pursue the remedy under subsection
(q) or part C may decline any compensation awarded with
respect to such remedy and subsequently pursue the remedy
provided for under this subsection. An individual who elects
to pursue the remedy provided for under this subsection may

[[Page S3729]]

not subsequently pursue the remedy provided for under
subsection (q) or part C.
``(C) Statute of limitations.--For purposes of determining
how much time has lapsed when applying statute of limitations
requirements relating to remedies under subparagraph (A), any
limitation of time for commencing an action, or filing an
application, petition, or claim for such remedies, shall be
deemed to have been suspended for the periods during which an
individual pursues a remedy under such subparagraph.
``(D) Offset.--The value of all compensation and benefits
provided under subsection (q) or part C of this title for an
incident or series of incidents shall be offset against the
amount of an award, compromise, or settlement of money
damages in a claim or suit under this subsection based on the
same incident or series of incidents.'';
(5) in paragraph (6)--
(A) in subparagraph (A), by inserting ``or under subsection
(q) or part C'' after ``under this subsection''; and
(B) by redesignating subparagraph (B) as subparagraph (C);
(C) by inserting after subparagraph (A), the following:
``(B) Grossly negligent, reckless, or illegal conduct and
willful misconduct.--For purposes of subparagraph (A),
grossly negligent, reckless, or illegal conduct or willful
misconduct shall include the administration by a qualified
person of a covered countermeasure to an individual who was
not within a category of individuals covered by a declaration
under subsection (p)(2) with respect to such countermeasure
where the qualified person fails to have had reasonable
grounds to believe such individual was within such a
category.''; and
(D) by adding at the end the following:
``(D) Liability of the united states.--The United States
shall be liable under this subsection with respect to a claim
arising out of the manufacture, distribution, or
administration of a covered countermeasure regardless of
whether--
``(i) the cause of action seeking compensation is alleged
as negligence, strict liability, breach of warranty, failure
to warn, or other action; or
``(ii) the covered countermeasure is designated as a
qualified anti-terrorism technology under the SAFETY Act (6
U.S.C. 441 et seq.).''
``(E) Governing law.--Notwithstanding the provisions of
section 1346(b)(1) and chapter 171 of title 28, United States
Code, as they relate to governing law, the liability of the
United States as provided in this subsection shall be in
accordance with the law of the place of injury.
``(F) Military personnel and united states citizens
overseas.--
``(i) Military personnel.--The liability of the United
States as provided in this subsection shall extend to claims
brought by United States military personnel.
``(ii) Claims arising in a foreign country.--
Notwithstanding the provisions of section 2680(k) of title
28, United States Code, the liability of the United States as
provided for in the subsection shall extend to claims based
on injuries arising in a foreign country where the injured
party is a member of the United States military, is the
spouse or child of a member of the United States military, or
is a United States citizen.
``(iii) Governing law.--With regard to all claims brought
under clause (ii), and notwithstanding the provisions of
section 1346(b)(1) and chapter 171 of title 28, United States
Code, and of subparagraph (C), as they relate to governing
law, the liability of the United States as provided in this
subsection shall be in accordance with the law of the
claimant's domicile in the United States or most recent
domicile with the United States.''; and
(6) in paragraph (7)--
(A) by striking subparagraph (A) and inserting the
following:
``(A) Covered countermeasure.--The term `covered
countermeasure', means--
``(i) a substance that is--

``(I)(aa) used to prevent or treat smallpox (including the
vaccinia or another vaccine); or
``(bb) vaccinia immune globulin used to control or treat
the adverse effects of vaccinia inoculation; and
``(II) specified in a declaration under paragraph (2); or

``(ii) a drug (as such term is defined in section 201(g)(1)
of the Federal Food, Drug, and Cosmetic Act), biological
product (as such term is defined in section 351(i) of this
Act), or device (as such term is defined in section 201(h) of
the Federal Food, Drug, and Cosmetic Act) that--

``(I) the Secretary determines to be a priority (consistent
with sections 302(2) and 304(a) of the Homeland Security Act
of 2002) to treat, identify, or prevent harm from any
biological, chemical, radiological, or nuclear agent
identified as a material threat under section 319F-
2(c)(2)(A)(ii), or to treat, identify, or prevent harm from a
condition that may result in adverse health consequences or
death and may be caused by administering a drug, biological
product, or device against such an agent;
``(II) is--

``(aa) authorized for emergency use under section 564 of
the Federal Food, Drug, and Cosmetic Act, so long as the
manufacturer of such drug, biological product, or device
has--
``(AA) made all reasonable efforts to obtain applicable
approval, clearance, or licensure; and
``(BB) cooperated fully with the requirements of the
Secretary under such section 564; or
``(bb) approved or licensed solely pursuant to the
regulations under subpart I of part 314 or under subpart H of
part 601 of title 21, Code of Federal Regulations (as in
effect on the date of enactment of the National Biodefense
Act of 2005); and

``(III) is specified in a declaration under paragraph
(2).''; and

(B) in subparagraph (B)--
(i) by striking clause (ii), and inserting the following:
``(ii) a health care entity, a State, or a political
subdivision of a State under whose auspices such
countermeasure was administered;'' and
(vi) in clause (viii), by inserting before the period ``if
such individual performs a function for which a person
described in clause (i), (ii), or (iv) is a covered person''.
______

SA 3691. Mr. KENNEDY submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

TITLE __--PUBLIC READINESS AND EMERGENCY PREPAREDNESS

SEC. __01. SHORT TITLE,

This title may be cited as the ``Responsible Public
Readiness and Emergency Preparedness Act''.

SEC. __02. REPEAL.

The Public Readiness and Emergency Preparedness Act
(division C of the Department of Defense, Emergency
Supplemental Appropriations to Address Hurricanes in the Gulf
of Mexico, and Pandemic Influenza Act, 2006 (Public Law 109-
148)) is repealed.

SEC. __03. NATIONAL BIODEFENSE INJURY COMPENSATION PROGRAM.

(a) Establishment.--Section 224 of the Public Health
Service Act (42 U.S.C. 233) is amended by adding at the end
the following:
``(q) Biodefense Injury Compensation Program.--
``(1) Establishment.--There is established the Biodefense
Injury Compensation Program (referred to in this subsection
as the `Compensation Program') under which compensation may
be paid for death or any injury, illness, disability, or
condition that is likely (based on best available evidence)
to have been caused by the administration of a covered
countermeasure to an individual pursuant to a declaration
under subsection (p)(2).
``(2) Administration and interpretation.--The statutory
provisions governing the Compensation Program shall be
administered and interpreted in consideration of the program
goals described in paragraph (4)(B)(iii).
``(3) Procedures and standards.--The Secretary shall by
regulation establish procedures and standards applicable to
the Compensation Program that follow the procedures and
standards applicable under the National Vaccine Injury
Compensation Program established under section 2110, except
that the regulations promulgated under this paragraph shall
permit a person claiming injury or death related to the
administration of any covered countermeasure to file either--
``(A) a civil action for relief under subsection (p); or
``(B) a petition for compensation under this subsection.
``(4) Injury table.--
``(A) Inclusion.--For purposes of receiving compensation
under the Compensation Program with respect to a
countermeasure that is the subject of a declaration under
subsection (p)(2), the Vaccine Injury Table under section
2114 shall be deemed to include death and the injuries,
disabilities, illnesses, and conditions specified by the
Secretary under subparagraph (B)(ii).
``(B) Injuries, disabilities, illnesses, and conditions.--
``(i) Institute of medicine.--Not later than 30 days after
making a declaration described in subsection (p)(2), the
Secretary shall enter into a contract with the Institute of
Medicine, under which the Institute shall, within 180 days of
the date on which the contract is entered into, and
periodically thereafter as new information, including
information derived from the monitoring of those who were
administered the countermeasure, becomes available, provide
its expert recommendations on the injuries, disabilities,
illnesses, and conditions whose occurrence in one or more
individuals are likely (based on best available evidence) to
have been caused by the administration of a countermeasure
that is the subject of the declaration.
``(ii) Specification by secretary.--Not later than 30 days
after the receipt of the expert recommendations described in
clause (i), the Secretary shall, based on such
recommendations, specify those injuries, disabilities,
illnesses, and conditions deemed to be included in the
Vaccine Injury Table under section 2114 for the purposes
described in subparagraph (A).
``(iii) Program goals.--The Institute of Medicine, under
the contract under clause (i), shall make such
recommendations, the Secretary shall specify, under clause
(ii), such injuries, disabilities, illnesses, and conditions,
and claims under the Compensation

[[Page S3730]]

Program under this subsection shall be processed and decided
taking into account the following goals of such program:

``(I) To encourage persons to develop, manufacture, and
distribute countermeasures, and to administer covered
countermeasures to individuals, by limiting such persons'
liability for damages related to death and such injuries,
disabilities, illnesses, and conditions.
``(II) To encourage individuals to consent to the
administration of a covered countermeasure by providing
adequate and just compensation for damages related to death
and such injuries, disabilities, illnesses, or conditions.
``(III) To provide individuals seeking compensation for
damages related to the administration of a countermeasure
with a non-adversarial administrative process for obtaining
adequate and just compensation.

``(iv) Use of best available evidence.--The Institute of
Medicine, under the contract under clause (i), shall make
such recommendations, the Secretary shall specify, under
clause (ii), such injuries, disabilities, illnesses, and
conditions, and claims under the Compensation Program under
this subsection shall be processed and decided using the best
available evidence, including information from adverse event
reporting or other monitoring of those individuals who were
administered the countermeasure, whether evidence from
clinical trials or other scientific studies in humans is
available.
``(v) Application of section 2115.--With respect to section
2115(a)(2) as applied for purposes of this subsection, an
award for the estate of the deceased shall be--

``(I) if the deceased was under the age of 18, an amount
equal to the amount that may be paid to a survivor or
survivors as death benefits under the Public Safety Officers'
Benefits Program under subpart 1 of part L of title I of the
Omnibus Crime Control and Safe Streets Act of 1968 (42 U.S.C.
3796 et seq.); or
``(II) if the deceased was 18 years of age or older, the
greater of--

``(aa) the amount described in subclause (I); or
``(bb) the projected loss of employment income, except that
the amount under this item may not exceed an amount equal to
400 percent of the amount that applies under item (aa).
``(vi) Application of section 2116.--Section 2116(b) shall
apply to injuries, disabilities, illnesses, and conditions
initially specified or revised by the Secretary under clause
(ii), except that the exceptions contained in paragraphs (1)
and (2) of such section shall not apply.
``(C) Rule of construction.--Section 13632 (a)(3) of Public
Law 103-66 (107 Stat. 646) (making revisions by Secretary to
the Vaccine Injury Table effective on the effective date of a
corresponding tax) shall not be construed to apply to any
revision to the Vaccine Injury Table made under regulations
under this paragraph.
``(5) Application.--The Compensation Program applies to any
death or injury, illness, disability, or condition that is
likely (based on best available evidence) to have been caused
by the administration of a covered countermeasure to an
individual pursuant to a declaration under subsection (p)(2).
``(6) Special masters.--
``(A) Hiring.--In accordance with section 2112, the judges
of the United States Claims Court shall appoint a sufficient
number of special masters to address claims for compensation
under this subsection.
``(B) Budget authority.--There are appropriated to carry
out this subsection such sums as may be necessary for fiscal
year 2006 and each fiscal year thereafter. This subparagraph
constitutes budget authority in advance of appropriations and
represents the obligation of the Federal Government.
``(7) Covered countermeasure.--For purposes of this
subsection, the term `covered countermeasure' has the meaning
given to such term in subsection (p)(7)(A).
``(8) Funding.--Compensation made under the Compensation
Program shall be made from the same source of funds as
payments made under subsection (p).''.
(b) Effective Date.--This section shall take effect as of
November 25, 2002 (the date of enactment of the Homeland
Security Act of 2002 (Pub. L. 107-296; 116 Stat. 2135)).

SEC. __04. INDEMNIFICATION FOR MANUFACTURERS AND HEALTH CARE
PROFESSIONALS WHO ADMINISTER MEDICAL PRODUCTS
NEEDED FOR BIODEFENSE.

Section 224(p) of the Public Health Service Act (42 U.S.C.
233(p)) is amended--
(1) in the subsection heading by striking ``Smallpox'';
(2) in paragraph (1), by striking ``against smallpox'';
(3) in paragraph (2)--
(A) in the paragraph heading, by striking ``against
smallpox''; and
(B) in subparagraph (B), by striking clause (ii);
(4) by striking paragraph (3) and inserting the following:
``(3) Exclusivity; offset.--
``(A) Exclusivity.--With respect to an individual to which
this subsection applies, such individual may bring a claim
for relief under--
``(i) this subsection;
``(ii) subsection (q); or
``(iii) part C.
``(B) Election of alternatives.--An individual may only
pursue one remedy under subparagraph (A) at any one time
based on the same incident or series of incidents. An
individual who elects to pursue the remedy under subsection
(q) or part C may decline any compensation awarded with
respect to such remedy and subsequently pursue the remedy
provided for under this subsection. An individual who elects
to pursue the remedy provided for under this subsection may
not subsequently pursue the remedy provided for under
subsection (q) or part C.
``(C) Statute of limitations.--For purposes of determining
how much time has lapsed when applying statute of limitations
requirements relating to remedies under subparagraph (A), any
limitation of time for commencing an action, or filing an
application, petition, or claim for such remedies, shall be
deemed to have been suspended for the periods during which an
individual pursues a remedy under such subparagraph.
``(D) Offset.--The value of all compensation and benefits
provided under subsection (q) or part C of this title for an
incident or series of incidents shall be offset against the
amount of an award, compromise, or settlement of money
damages in a claim or suit under this subsection based on the
same incident or series of incidents.'';
(5) in paragraph (6)--
(A) in subparagraph (A), by inserting ``or under subsection
(q) or part C'' after ``under this subsection''; and
(B) by redesignating subparagraph (B) as subparagraph (C);
(C) by inserting after subparagraph (A), the following:
``(B) Grossly negligent, reckless, or illegal conduct and
willful misconduct.--For purposes of subparagraph (A),
grossly negligent, reckless, or illegal conduct or willful
misconduct shall include the administration by a qualified
person of a covered countermeasure to an individual who was
not within a category of individuals covered by a declaration
under subsection (p)(2) with respect to such countermeasure
where the qualified person fails to have had reasonable
grounds to believe such individual was within such a
category.''; and
(D) by adding at the end the following:
``(D) Liability of the united states.--The United States
shall be liable under this subsection with respect to a claim
arising out of the manufacture, distribution, or
administration of a covered countermeasure regardless of
whether--
``(i) the cause of action seeking compensation is alleged
as negligence, strict liability, breach of warranty, failure
to warn, or other action; or
``(ii) the covered countermeasure is designated as a
qualified anti-terrorism technology under the SAFETY Act (6
U.S.C. 441 et seq.).''
``(E) Governing law.--Notwithstanding the provisions of
section 1346(b)(1) and chapter 171 of title 28, United States
Code, as they relate to governing law, the liability of the
United States as provided in this subsection shall be in
accordance with the law of the place of injury.
``(F) Military personnel and united states citizens
overseas.--
``(i) Military personnel.--The liability of the United
States as provided in this subsection shall extend to claims
brought by United States military personnel.
``(ii) Claims arising in a foreign country.--
Notwithstanding the provisions of section 2680(k) of title
28, United States Code, the liability of the United States as
provided for in the subsection shall extend to claims based
on injuries arising in a foreign country where the injured
party is a member of the United States military, is the
spouse or child of a member of the United States military, or
is a United States citizen.
``(iii) Governing law.--With regard to all claims brought
under clause (ii), and notwithstanding the provisions of
section 1346(b)(1) and chapter 171 of title 28, United States
Code, and of subparagraph (C), as they relate to governing
law, the liability of the United States as provided in this
subsection shall be in accordance with the law of the
claimant's domicile in the United States or most recent
domicile with the United States.''; and
(6) in paragraph (7)--
(A) by striking subparagraph (A) and inserting the
following:
``(A) Covered countermeasure.--The term `covered
countermeasure', means--
``(i) a substance that is--

``(I)(aa) used to prevent or treat smallpox (including the
vaccinia or another vaccine); or
``(bb) vaccinia immune globulin used to control or treat
the adverse effects of vaccinia inoculation; and
``(II) specified in a declaration under paragraph (2); or

``(ii) a drug (as such term is defined in section 201(g)(1)
of the Federal Food, Drug, and Cosmetic Act), biological
product (as such term is defined in section 351(i) of this
Act), or device (as such term is defined in section 201(h) of
the Federal Food, Drug, and Cosmetic Act) that--

``(I) the Secretary determines to be a priority (consistent
with sections 302(2) and 304(a) of the Homeland Security Act
of 2002) to treat, identify, or prevent harm from any
biological, chemical, radiological, or nuclear agent
identified as a material threat under section 319F-
2(c)(2)(A)(ii), or to treat, identify, or prevent harm from a
condition that may result in adverse health consequences or
death and may be caused by administering a drug, biological
product, or device against such an agent;

[[Page S3731]]

``(II) is--

``(aa) authorized for emergency use under section 564 of
the Federal Food, Drug, and Cosmetic Act, so long as the
manufacturer of such drug, biological product, or device
has--
``(AA) made all reasonable efforts to obtain applicable
approval, clearance, or licensure; and
``(BB) cooperated fully with the requirements of the
Secretary under such section 564; or
``(bb) approved or licensed solely pursuant to the
regulations under subpart I of part 314 or under subpart H of
part 601 of title 21, Code of Federal Regulations (as in
effect on the date of enactment of the National Biodefense
Act of 2005); and

``(III) is specified in a declaration under paragraph
(2).''; and

(B) in subparagraph (B)--
(i) by striking clause (ii), and inserting the following:
``(ii) a health care entity, a State, or a political
subdivision of a State under whose auspices such
countermeasure was administered;'' and
(vi) in clause (viii), by inserting before the period ``if
such individual performs a function for which a person
described in clause (i), (ii), or (iv) is a covered person''.

SEC. __05. PREPAREDNESS AND RESPONSE.

(a) In General.--The Secretary of Labor and the Secretary
of Health and Human Services shall develop and issue
workplace standards, recommendations and plans to protect
health care workers and first responders, including police,
firefighters, and emergency medical personnel from workplace
exposure to pandemic influenza. Such standards,
recommendations and plans shall set forth appropriate
measures to protect workers both in preparation for a
potential pandemic influenza occurrence and in response to an
actual occurrence of pandemic influenza.
(b) Workplace Safety and Health Standards.--
(1) In general.--Within 6 months after the date of the
enactment of this Act, pursuant to section 6(c) of the
Occupational Safety and Health Act, the Secretary of Labor,
in consultation with the Director of the National Institute
for Occupational Safety and Health, shall develop and issue
an emergency temporary standard for the protection of health
care workers and first responders against occupational
exposure to pandemic influenza, including avian influenza
caused by the H5N1 virus. Within 6 months after the issuance
of an emergency standard, the Secretary of Labor shall issue
a final permanent standard for occupational exposure to
pandemic influenza under section 6(b) of the Occupational
Safety and Health Act. The emergency temporary standard and
final permanent standard shall provide, at a minimum, for the
following:
(A) The development and implementation of an exposure
control plan to protect workers from airborne and contact
hazards in conformance with the Guideline for Protecting
Workers Against Avian Flu issued by the Occupational Safety
and Health Administration March 2004, the Centers for Disease
Control and Prevention Interim Recommendations for Infection
Control in Health-Care Facilities Caring for Patients with
Known or Suspected Avian Influenza issued May 21, 2004, and
the World Health Organization (WHO) Global Influenza
Preparedness Plan issued April 2005.
(B) Personal protective equipment, in conformance with the
requirements of 29 CFR 1910.134 and 29 CFR 1910.132.
(C) Training and information in conformance with the OSHA
Bloodborne Pathogens standard under 29 CFR 1910.1030(g).
(D) Appropriate medical surveillance for workers exposed to
the pandemic influenza virus, including the H5N1 virus.
(E) Immunization against the pandemic influenza virus, if
such a vaccine has been approved by the Food and Drug
Administration and is available.
(2) Effective date.--The emergency standard issued under
paragraph (1) shall take effect not later than 90 days after
the promulgation of such standard, except that the effective
date for any requirements for engineering controls shall go
into effect not later than 90 days after the promulgation of
the final permanent standard. The provisions of the emergency
temporary standard shall remain in effect until the final
permanent standard is in effect.
(c) Pandemic Influenza Preparedness Plan Revisions.--
(1) Minimal requirements.--Within 30 days after the date of
the enactment of this Act, the Secretary of Health and Human
Services shall revise the provisions of the pandemic
influenza plan of the Department of Health and Human Services
to conform with the minimal worker protection requirements
set forth in subsection (b).
(2) Final standard.--Within 30 days of the promulgation of
a final standard under subsection (b), the Secretary of
Health and Human Services shall modify the pandemic influenza
plan of the Department of Health and Human Services to
conform with the provisions of the occupational safety and
health standard issued by the Secretary of Labor.

SEC. __06. RELATION TO STATES AND POLITICAL SUBDIVISIONS
RECEIVING FUNDS UNDER SECTION 319 OF PHSA.

An award of a grant, cooperative agreement, or contract may
not be made to any State or political subdivision of a State
under any program receiving funds under section 319 of the
Public Health Service Act (42 U.S.C. 247d) unless the State
or political subdivision agrees to comply with the standards
issued under section __05 for protecting health care workers
and first responders from pandemic influenza.

SEC. __07. PROTECTION OF POULTRY WORKERS.

(a) In General.--Not later than 30 days after the date of
the enactment of this Act, the Secretary of Health and Human
Services, in coordination with the Secretary of Agriculture,
the Secretary of Interior, and the Secretary of Labor, shall
convene a meeting of experts, representatives of the poultry
industry, representatives of poultry workers and other
appropriate parties to evaluate the risks to poultry workers
posed by exposure to the H5N1 virus, the likelihood of
transmission of the virus from birds to poultry workers and
the necessary measures to protect poultry workers from
exposure.
(b) Revision of Preparedness Plan.--Not later than 30 days
after the meeting under subsection (a), the Secretary shall
revise the HHS Pandemic Influenza Plan to include the
findings and recommendations of the participants in the
meeting.
(c) Implementation of Recommendations.--The Secretary of
Health and Human Services, the Secretary of Agriculture, the
Secretary of Interior, and the Secretary of Labor shall take
the recommended steps to implement the recommendations of the
participants in the meeting under subsection (a).
______

SA 3692. Mr. FRIST (for himself, Mr. Santorum, and Mr. Ensign)
submitted an amendment intended to be proposed by him to the bill H.R.
4939, making emergency supplemental appropriations for the fiscal year
ending September 30, 2006, and for other purposes; which was ordered to
lie on the table; as follows:

Sec. __. None of the funds appropriated or otherwise made
available by this Act or any other Act may be obligated or
expended in connection with United States participation in,
or support for, the activities of the United Nations Human
Rights Council.
Sec. __. (a) Of the amounts appropriated or otherwise made
available for the Secretary of State for each of fiscal years
2006 and 2007 to pay the United States share of assessed
contributions for the regular budget of the United Nations,
$4,300,000 shall be withheld from such payment, and shall be
available instead for the purposes described in subsection
(b).
(b) The purposes referred to in subsection (a) are the
establishment and operation of a state-of-the-art advanced
training skills facility to rehabilitate injured veterans at
Brooke Army Medical Center in San Antonio, Texas.
(c) Amounts withheld under subsection (a) shall remain
available until expended for the purposes described in
subsection (b).
______

SA 3693. Mr. OBAMA (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

LIMITS ON ADMINISTRATIVE COSTS UNDER FEDERAL CONTRACTS

Sec. 7032. None of the funds appropriated by this Act may
be used by an executive agency to enter into any Federal
contract (including any subcontract or follow-on contract)
for which the administrative overhead and contract management
expenses exceed the reasonable industry standard as published
by the Director of the Office of Management and Budget
unless, not later than 3 days before entering into the
contract, the head of the executive agency provides to the
chair and ranking member of the relevant oversight committees
of the Senate and the House of Representatives a copy of the
contract, any other documentation requested by Congress, and
a justification for excessive overhead expense.
______

SA 3694. Mr. OBAMA (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

ACCOUNTABILITY IN HURRICANE RECOVERY CONTRACTING

Sec. 7032. None of the funds appropriated by this Act that
are made available for relief and recovery efforts related to
Hurricane Katrina and the other hurricanes of the 2005 season
may be used by an executive agency to enter into any Federal
contract (including any follow-on contract) exceeding
$1,000,000 through the use of procedures other than
competitive procedures as required by the Federal Acquisition
Regulation and, as applicable, section 303(a) of the Federal
Property and Administrative Services Act of 1949 (41 U.S.C.
253(a)) or section 2304(a) of title 10, United States Code,
unless the Director of the Office of Management and Budget
specifically approves the use of such procedures for such
contract, and not later than 7 days

[[Page S3732]]

after entering into the contract, the executive agency
provides to the chair and ranking member of the relevant
oversight committees of the Senate and the House of
Representatives a copy of the contract, the justification for
the procedures used, the date when the contract will end, and
the steps being taken to ensure that any future contracts for
the product or service or with the same vendor will follow
the appropriate competitive procedures.
______

SA 3695. Mr. OBAMA (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

FINANCIAL TRANSPARENCY IN HURRICANE RECOVERY CONTRACTING

Sec. 7032. None of the funds appropriated by this Act that
are made available for relief and recovery efforts related to
Hurricane Katrina and other hurricanes of the 2005 season may
be used by an executive agency to enter into any Federal
contract (including any follow-on contract) exceeding
$250,000 unless the Director of the Office of Management and
Budget publishes on an accessible Federal Internet website an
electronically searchable monthly report that includes an
electronic mail address and phone number that can be used to
report waste, fraud, or abuse, the number and outcome of
fraud investigations related to such recovery efforts
conducted by executive agencies, and for each entity that has
received more than $250,000 in amounts appropriated or
otherwise made available by this Act, the name of the entity
and a unique identifier, the total amount of Federal funds
that the entity has received since August 25, 2005, the
geographic location and official tax domicile of the entity
and the primary location of performance of contracts paid for
with such amounts, and an itemized breakdown of each contract
exceeding $100,000 that specifies the funding agency, program
source, contract type, number of bids received, and a
description of the purpose of the contract.
______

SA 3696. Mr. OBAMA (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

On page 253, between lines 19 and 20, insert the following:

ACCOUNTABILITY IN HURRICANE RECOVERY CONTRACTING

Sec. 7032. (a) None of the funds appropriated by this Act
that are made available for relief and recovery efforts
related to Hurricane Katrina and the other hurricanes of the
2005 season may be used by an executive agency to enter into
any Federal contract (including any follow-on contract)
exceeding $1,000,000 through the use of procedures other than
competitive procedures as required by the Federal Acquisition
Regulation and, as applicable, section 303(a) of the Federal
Property and Administrative Services Act of 1949 (41 U.S.C.
253(a)) or section 2304(a) of title 10, United States Code,
unless the Director of the Office of Management and Budget
specifically approves the use of such procedures for such
contract, and not later than 7 days after entering into the
contract, the executive agency provides to the chair and
ranking member of the relevant oversight committees of the
Senate and the House of Representatives a copy of the
contract, the justification for the procedures used, the date
when the contract will end, and the steps being taken to
ensure that any future contracts for the product or service
or with the same vendor will follow the appropriate
competitive procedures.
(b) None of the funds appropriated by this Act may be used
by an executive agency to enter into any Federal contract
(including any subcontract or follow-on contract) for which
the administrative overhead and contract management expenses
exceed the reasonable industry standard as published by the
Director of the Office of Management and Budget unless, not
later than 3 days before entering into the contract, the head
of the executive agency provides to the chair and ranking
member of the relevant oversight committees of the Senate and
the House of Representatives a copy of the contract, any
other documentation requested by Congress, and a
justification for excessive overhead expense.
(c) None of the funds appropriated by this Act that are
made available for relief and recovery efforts related to
Hurricane Katrina and other hurricanes of the 2005 season may
be used by an executive agency to enter into any Federal
contract (including any follow-on contract) exceeding
$250,000 unless the Director of the Office of Management and
Budget publishes on an accessible Federal Internet website an
electronically searchable monthly report that includes an
electronic mail address and phone number that can be used to
report waste, fraud, or abuse, the number and outcome of
fraud investigations related to such recovery efforts
conducted by executive agencies, and for each entity that has
received more than $250,000 in amounts appropriated or
otherwise made available by this Act, the name of the entity
and a unique identifier, the total amount of Federal funds
that the entity has received since August 25, 2005, the
geographic location and official tax domicile of the entity
and the primary location of performance of contracts paid for
with such amounts, and an itemized breakdown of each contract
exceeding $100,000 that specifies the funding agency, program
source, contract type, number of bids received, and a
description of the purpose of the contract.
______

SA 3697. Mr. OBAMA (for himself and Mr. Coburn) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

TITLE VII--EMERGENCY RECOVERY SPENDING OVERSIGHT

SEC. 8001. SHORT TITLE.

This title may be cited as the ``Oversight of Vital
Emergency Recovery Spending Enhancement and Enforcement Act
of 2006''.

SEC. 8002. DEFINITIONS.

(a) Chief Financial Officer.--The term ``Chief Financial
Officer'' means the Hurricane Katrina Recovery Chief
Financial Officer.
(b) Office.--The term ``Office'' means the Office of the
Hurricane Katrina Recovery Chief Financial Officer.

SEC. 8003. ESTABLISHMENT AND FUNCTIONS.

(a) Establishment.--There is established within the
Executive Office of the President, the Office of the
Hurricane Katrina Recovery Chief Financial Officer.
(b) Chief Financial Officer.--
(1) Appointment.--The Hurricane Katrina Recovery Chief
Financial Officer shall be the head of the Office. The Chief
Financial Officer shall be appointed by the President, by and
with the advice and consent of the Senate.
(2) Qualifications.--The Chief Financial Officer shall--
(A) have the qualifications required under section
901(a)(3) of title 31, United States Code; and
(B) have knowledge of Federal contracting and policymaking
functions.
(c) Authorities and Functions.--
(1) In general.--The Chief Financial Officer shall--
(A) be responsible for the efficient and effective use of
Federal funds in all activities relating to the recovery from
Hurricane Katrina;
(B) strive to ensure that--
(i) priority in the distribution of Federal relief funds is
given to individuals and organizations most in need of
financial assistance; and
(ii) priority in the distribution of Federal reconstruction
funds is given to business entities that are based in
Louisiana, Mississippi, Alabama, or Florida or business
entities that hire workers who resided in those States on
August 24, 2005;
(C) perform risk assessments of all programs and operations
related to recovery from Hurricane Katrina and implement
internal controls and program oversight based on risk of
waste, fraud, or abuse;
(D) oversee all financial management activities relating to
the programs and operations of the Hurricane Katrina recovery
effort;
(E) develop and maintain an integrated accounting and
financial management system, including financial reporting
and internal controls, which--
(i) complies with applicable accounting principles,
standards, and requirements, and internal control standards;
(ii) complies with such policies and requirements as may be
prescribed by the Director of the Office of Management and
Budget;
(iii) complies with any other requirements applicable to
such systems; and
(iv) provides for--

(I) complete, reliable, consistent, and timely information
which is prepared on a uniform basis and which is responsive
to the financial information needs of the Office;
(II) the development and reporting of cost information;
(III) the integration of accounting and budgeting
information; and
(IV) the systematic measurement of performance;

(F) monitor the financial execution of the budget of
Federal agencies relating to recovery from Hurricane Katrina
in relation to actual expenditures;
(G) have access to all records, reports, audits, reviews,
documents, papers, recommendations, or other material which
are the property of Federal agencies or which are available
to the agencies, and which relate to programs and operations
with respect to which the Chief Financial Officer has
responsibilities;
(H) request such information or assistance as may be
necessary for carrying out the duties and responsibilities
provided by this section from any Federal, State, or local
governmental entity, including any Chief Financial Officer
under section 902 of title 31, United States Code, and, upon
receiving such request, insofar as is practicable and not in
contravention of any existing law, any such Federal
Governmental entity or Chief Financial Officer under section
902 shall cooperate

[[Page S3733]]

and furnish such requested information or assistance;
(I) to the extent and in such amounts as may be provided in
advance by appropriations Acts, be authorized to--
(i) enter into contracts and other arrangements with public
agencies and with private persons for the preparation of
financial statements, studies, analyses, and other services;
and
(ii) make such payments as may be necessary to carry out
the provisions of this section;
(J) for purposes of the Improper Payments Information Act
of 2002 (31 U.S.C. 3321 note), perform, in consultation with
the Office of Management and Budget, the functions of the
head of an agency for any activity relating to the recovery
from Hurricane Katrina that is not currently the
responsibility of the head of an agency under that Act; and
(K) transmit a report, on a quarterly basis, regarding any
program or activity identified by the Chief Financial Officer
as susceptible to significant improper payments under section
2(a) of the Improper Payments Information Act of 2002 (31
U.S.C. 3321 note) to the appropriate inspector general.
(2) Access.--Except as provided in paragraph (1)(H), this
subsection does not provide to the Chief Financial Officer
any access greater than permitted under any other law to
records, reports, audits, reviews, documents, papers,
recommendations, or other material of any Office of Inspector
General established under the Inspector General Act of 1978
(5 U.S.C. App.).
(3) Coordination of agencies.--In the performance of the
authorities and functions under paragraph (1) by the Chief
Financial Officer the President (or the President's designee)
shall act as the head of the Office and the Chief Financial
Officer shall have management and oversight of all agencies
performing activities relating to the recovery from Hurricane
Katrina.
(4) Regular reports.--
(A) In general.--Every month the Chief Financial Officer
shall submit a financial report on the activities for which
the Chief Financial Officer has management and oversight
responsibilities to--
(i) the Committee on Homeland Security and Governmental
Affairs of the Senate;
(ii) the Committee on Homeland Security of the House of
Representatives;
(iii) the Committees on Appropriations of the Senate and
House of Representatives; and
(iv) the Committee on Government Reform of the House of
Representatives.
(B) Contents.--Each report under this paragraph shall
include--
(i) the extent to which Federal relief funds have been
given to individuals and organizations most in need of
financial assistance;
(ii) the extent to which Federal reconstruction funds have
been made available to business entities that are based in
Louisiana, Mississippi, Alabama, or Florida or business
entities that hire workers who resided in those States on
August 24, 2005;
(iii) the extent to which Federal agencies have made use of
sole source, no-bid or cost-plus contracts; and
(iv) an assessment of the financial execution of the budget
of Federal agencies relating to recovery from Hurricane
Katrina in relation to actual expenditures.
(C) First report.--The first report under this paragraph
shall be submitted for the first full month for which a Chief
Financial Officer has been appointed.
(d) Responsibilities of Chief Financial Officers.--Nothing
in this Act shall be construed to relieve the
responsibilities of any Chief Financial Officer under section
902 of title 31, United States Code.
(e) Availability of Records.--Upon request to the Chief
Financial Officer, the Office shall make the records of the
Office available to the Inspector General of any Federal
agency performing recovery activities relating to Hurricane
Katrina, or to any Special Inspector General designated to
investigate such activities, for the purpose of performing
the duties of that Inspector General under the Inspector
General Act of 1978 (5 U.S.C. App.).

SEC. 8004. REPORTS OF THE GOVERNMENT ACCOUNTABILITY OFFICE.

The Government Accountability Office shall provide
quarterly reports to the committees described under section
8003(c)(4)(A) relating to all activities and expenditures
overseen by the Office, including--
(1) the accuracy of reports submitted by the Chief
Financial Officer to Congress;
(2) the extent to which agencies performing activities
relating to the recovery from Hurricane Katrina have made use
of sole source, no-bid or cost-plus contracts;
(3) whether Federal funds expended by State and local
government agencies were spent for their intended use;
(4) the extent to which Federal relief funds have been
distributed to individuals and organizations most affected by
Hurricane Katrina and Federal reconstruction funds have been
made available to business entities that are based in
Louisiana, Mississippi, Alabama, or Florida or business
entities that hire workers who resided in those States on
August 24, 2005; and
(5) the extent to which internal controls to prevent waste,
fraud, or abuse exist in the use of Federal funds relating to
the recovery from Hurricane Katrina.

SEC. 8005. ADMINISTRATIVE AND SUPPORT SERVICES.

(a) In General.--The President shall provide administrative
and support services (including office space) for the Office
and the Chief Financial Officer.
(b) Personnel.--The President shall provide for personnel
for the Office through the detail of Federal employees. Any
Federal employee may be detailed to the Office without
reimbursement, and such detail shall be without interruption
or loss of civil service status or privilege.

SEC. 8006. AUTHORIZATION OF APPROPRIATIONS.

There are authorized to be appropriated such sums as
necessary to carry out this title.

SEC. 8007. TERMINATION OF OFFICE.

(a) In General.--The Office and position of Chief Financial
Officer shall terminate 1 year after the date of the
enactment of this Act.
(b) Extension.--The President may extend the date of
termination annually under subsection (a) to any date
occurring before 5 years after the date of the enactment of
this Act.
(c) Notification.--The President shall notify the
committees described under section 8003(c)(4)(A) 60 days
before any extension of the date of termination under this
section.
______

SA 3698. Mr. BURNS (for himself and Mr. Rockefeller) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

At the appropriate place, insert the following:

SEC. ------. EXTENSION OF REQUIREMENT FOR AIR CARRIERS TO
HONOR TICKETS FOR SUSPENDED AIR PASSENGER
SERVICE.

Section 145(c) of the Aviation and Transportation Security
Act (49 U.S.C. 40101 note) is amended by striking ``November
19, 2005.'' and inserting ``November 30, 2007.''.
______

SA 3699. Mr. CORNYN (for himself, Ms. Landrieu, Mrs. Hutchison, and
Mr. Nelson of Florida) submitted an amendment intended to be proposed
by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; as follows:

On page 200, line 21, insert ``Provided further, That as
long as $5,200,000,000 is provided under this heading no
State shall be allocated less than 3.5 percent of the amount
provided under this heading:'' after ``impacted areas:''.
______

SA 3700. Mr. DOMENICI (for himself, Mr. Grassley, and Mr. Stevens)
submitted an amendment intended to be proposed by him to the bill H.R.
4939, making emergency supplemental appropriations for the fiscal year
ending September 30, 2006, and for other purposes; which was ordered to
lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

TITLE VIII--GAS TAX RELIEF AND REBATE

Subtitle A--Fuel Tax Holiday Rebate

SEC. 8101. FUEL TAX HOLIDAY REBATE.

(a) In General.--Subchapter B of chapter 65 of the Internal
Revenue Code of 1986 (relating to rules of special
application in the case of abatements, credits, and refunds)
is amended by adding at the end the following new section:

``SEC. 6430. FUEL TAX HOLIDAY REBATE.

``(a) General Rule.--Except as otherwise provided in this
section, each individual shall be treated as having made a
payment against the tax imposed by chapter 1 for the taxable
year beginning in 2006 in an amount equal to $100.
``(b) Remittance of Payment.--The Secretary shall remit to
each taxpayer the payment described in subsection (a) not
later than August 30, 2006.
``(c) Certain Persons Not Eligible.--This section shall not
apply to--
``(1) any taxpayer who did not have any adjusted gross
income for the preceding taxable year or whose adjusted gross
income for such preceding taxable year exceeded the threshold
amount (as determined under section 151(d)(3)(C) for such
preceding taxable year),
``(2) any individual with respect to whom a deduction under
section 151 is allowable to another taxpayer for the taxable
year beginning in 2006,
``(3) any estate or trust, or
``(4) any nonresident alien individual.''.
(b) Conforming Amendment.--Section 1324(b)(2) of title 31,
United States Code, is amended by inserting before the period
``, or from section 6430 of such Code''.
(c) Clerical Amendment.--The table of sections for
subchapter B of chapter 65 of the Internal Revenue Code of
1986 is amended by adding at the end the following new item:

``Sec. 6430. Fuel tax holiday rebate.''.

(d) Effective Date.--The amendments made by this section
shall take effect on the date of the enactment of this Act.

Subtitle B--Price Gouging

SEC. 8201. SHORT TITLE.

This subtitle may be cited as the ``Gasoline Consumer Anti-
Price-Gouging Protection Act''.

SEC. 8202. PROTECTION OF CONSUMERS AGAINST PRICE GOUGING.

It is unlawful for any person to increase the price at
which that person sells, or offers

[[Page S3734]]

to sell, gasoline or petroleum distillates to the public (for
purposes other than resale) in, or for use in, an area
covered by an emergency proclamation by an unconscionable
amount while the proclamation is in effect.

SEC. 8203. JUSTIFIABLE PRICE INCREASES.

(a) In General.--The prohibition in section 8202 does not
apply to the extent that the increase in the retail price of
the gasoline or petroleum distillate is attributable to--
(1) an increase in the wholesale cost of gasoline and
petroleum distillates for the region in which the area to
which a proclamation under section 8202 applies is located;
(2) an increase in the replacement costs for gasoline or
petroleum distillate sold;
(3) an increase in operational costs; or
(4) regional, national, or international market conditions.
(b) Other Mitigating Factors.--In determining whether a
violation of section 8202 has occurred, there also shall be
taken into account, among other factors, the price that would
reasonably equate supply and demand in a competitive and
freely functioning market and whether the price at which the
gasoline or petroleum distillate was sold reasonably reflects
additional costs, not within the control of the seller, that
were paid or incurred by the seller.

SEC. 8204. FEDERAL AND STATE PROCLAMATIONS.

(a) In General.--For purposes of this subtitle--
(1) the President may issue an emergency proclamation for
any area within the United States in which an abnormal market
disruption has occurred or is reasonably expected to occur;
and
(2) the chief executive officer of any State may issue an
emergency proclamation for any such area within that State.
(b) Scope and Duration.--
(1) In general.--An emergency proclamation issued under
subsection (a) shall specify with particularity--
(A) the geographic area to which it applies;
(B) the period for which the proclamation applies; and
(C) the event, circumstance, or condition that is the
reason such a proclamation is determined to be necessary.
(2) Limitations.--An emergency proclamation issued under
subsection (a)--
(A) may not apply for a period of more than 30 consecutive
days (renewable for a consecutive period of not more than 30
days); and
(B) may apply to a period of not more than 7 days preceding
the occurrence of an event, circumstance, or condition that
is the reason such a proclamation is determined to be
necessary.

SEC. 8205. ENFORCEMENT BY FEDERAL TRADE COMMISSION.

(a) Violation Is Unfair or Deceptive Act or Practice.--This
subtitle shall be enforced by the Federal Trade Commission as
if the violation of section 8202 were an unfair or deceptive
act or practice proscribed under a rule issued under section
18(a)(1)(B) of the Federal Trade Commission Act (15 U.S.C.
57a(a)(1)(B)).
(b) Actions by the Commission.--The Commission shall
prevent any person from violating this subtitle in the same
manner, by the same means, and with the same jurisdiction,
powers, and duties as though all applicable terms and
provisions of the Federal Trade Commission Act (15 U.S.C. 41
et seq.) were incorporated into and made a part of this
subtitle. Any entity that violates any provision of this
subtitle is subject to the penalties and entitled to the
privileges and immunities provided in the Federal Trade
Commission Act in the same manner, by the same means, and
with the same jurisdiction, power, and duties as though all
applicable terms and provisions of the Federal Trade
Commission Act were incorporated into and made a part of this
subtitle.
(c) Regulations.--Not later than 180 days after the date of
enactment of this Act, the Federal Trade Commission shall
prescribe such regulations as may be necessary or appropriate
to implement this subtitle.

SEC. 8206. ENFORCEMENT BY STATES.

(a) In General.--A State, as parens patriae, may bring a
civil action on behalf of its residents in an appropriate
district court of the United States to enforce the provisions
of this subtitle, whenever the chief legal officer of the
State has reason to believe that the interests of the
residents of the State have been or are being threatened or
adversely affected by a violation of this subtitle or a
regulation under this subtitle.
(b) Notice.--The State shall serve written notice to the
Federal Trade Commission of any civil action under subsection
(a) prior to initiating such civil action. The notice shall
include a copy of the complaint to be filed to initiate such
civil action, except that if it is not feasible for the State
to provide such prior notice, the State shall provide such
notice immediately upon instituting such civil action.
(c) Authority To Intervene.--Upon receiving the notice
required by subsection (b), the Commission may intervene in
such civil action and upon intervening--
(1) be heard on all matters arising in such civil action;
and
(2) file petitions for appeal of a decision in such civil
action.
(d) Construction.--For purposes of bringing any civil
action under subsection (a), nothing in this section shall
prevent the chief legal officer of a State from exercising
the powers conferred on that officer by the laws of such
State to conduct investigations or to administer oaths or
affirmations or to compel the attendance of witnesses or the
production of documentary and other evidence.
(e) Venue; Service of Process.--In a civil action brought
under subsection (a)--
(1) the venue shall be a judicial district in which the
violation occurred;
(2) process may be served without regard to the territorial
limits of the district or of the State in which the civil
action is instituted; and
(3) a person who participated in an alleged violation that
is being litigated in the civil action may be joined in the
civil action without regard to the residence of the person.
(f) Limitation on State Action While Federal Action Is
Pending.--If the Commission has instituted a civil action or
an administrative action for violation of this subtitle, the
chief legal officer of the State in which the violation
occurred may not bring an action under this section during
the pendency of that action against any defendant named in
the complaint of the Commission or the other agency for any
violation of this subtitle alleged in the complaint.
(g) Enforcement of State Law.--Nothing contained in this
section shall prohibit an authorized State official from
proceeding in State court to enforce a civil or criminal
statute of such State.

SEC. 8207. PENALTIES.

(a) Civil Penalty.--
(1) In general.--In addition to any penalty applicable
under the Federal Trade Commission Act any person who
violates this subtitle is punishable by a civil penalty of--
(A) not more than $500,000, in the case of an independent
small business marketer of gasoline (within the meaning of
section 324(c) of the Clean Air Act (42 U.S.C. 7625(c)); and
(B) not more than $5,000,000 in the case of any other
person.
(2) Method of assessment.--The penalty provided by
paragraph (1) shall be assessed in the same manner as civil
penalties imposed under section 5 of the Federal Trade
Commission Act (15 U.S.C. 45).
(3) Multiple offenses; mitigating factors.--In assessing
the penalty provided by subsection (a)--
(A) each day of a continuing violation shall be considered
a separate violation; and
(B) the Commission shall take into consideration the
seriousness of the violation and the efforts of the person
committing the violation to remedy the harm caused by the
violation in a timely manner.
(b) Criminal Penalty.--
(1) In general.--In addition to any penalty applicable
under the Federal Trade Commission Act, the violation of this
subtitle is punishable by a fine of not more than $1,000,000,
imprisonment for not more than 2 years, or both.
(2) Enforcement.--The criminal penalty provided by
paragraph (1) may be imposed only pursuant to a criminal
action brought by the Attorney General or other officer of
the Department of Justice, or any attorney specially
appointed by the Attorney General of the United States, in
accordance with section 515 of title 28, United States Code.

SEC. 8208. DEFINITIONS.

In this subtitle:
(1) Abnormal market disruption.--The term ``abnormal market
disruption'' means there is a reasonable likelihood that, in
the absence of a proclamation under section 8204(a), there
will be an increase in the average retail price of gasoline
or petroleum distillates in the area to which the
proclamation applies as a result of a change in the market,
whether actual or imminently threatened, resulting from
weather, a natural disaster, strike, civil disorder, war,
military action, a national or local emergency, or other
similar cause, that adversely affects the availability or
delivery gasoline or petroleum distillates.
(2) State.--The term ``State'' means the several States of
the United States and the District of Columbia.
(3) Unconscionable amount.--The term ``unconscionable
amount'' means, with respect to any person to whom section
8202 applies, a significant increase in the price at which
gasoline or petroleum distillates are sold or offered for
sale by that person that increases the price, for the same
grade of gasoline or petroleum distillate, to an amount
that--
(A) substantially exceeds the average price at which
gasoline or petroleum distillates were sold or offered for
sale by that person during the 30-day period immediately
preceding the sale or offer; and
(B) cannot be justified by taking into account the factors
described in section --03(b).

SEC. 8209. EFFECTIVE DATE.

This subtitle shall take effect on the date on which a
final rule issued by the Federal Trade Commission under
section 8205(c) is published in the Federal Register.

Subtitle C--Tax Provisions

SEC. 8301. REPEAL OF THE LIMITATION ON NUMBER OF NEW
QUALIFIED HYBRID AND ADVANCED LEAN -BURN
TECHNOLOGY VEHICLES ELIGIBLE FOR CREDIT.

(a) In General.--Subsection (f) of section 30B of the
Internal Revenue Code of 1986 is repealed.
(b) Effective Date.--The amendment made by this section
shall take effect as if included in the amendment made by
section 1341(a) of the Energy Policy Act of 2005.

[[Page S3735]]

SEC. 8302. EXCEPTION FROM DEPRECIATION LIMITATION FOR CERTAIN
ALTERNATIVE AND ELECTRIC PASSENGER AUTOMOBILES.

(a) In General.--Paragraph (1) of section 280F(a) of the
Internal Revenue Code of 1986 (relating to limitation) is
amended by adding at the end the following new subparagraph:
``(D) Special rule for certain alternative motor vehicles
and qualified electric vehicles.--Subparagraph (A) shall not
apply to any motor vehicle for which a credit is allowable
under section 30 or 30B.''.
(b) Conforming Amendment.--Subparagraph (C) of section
280F(a)(1) of the Internal Revenue Code of 1986 is amended by
striking clause (ii) and by redesignating clause (iii) as
clause (ii).
(c) Effective Date.--The amendments made by this section
shall apply to property placed in service after the date of
the enactment of this Act.

SEC. 8303. EXTENSION OF ELECTION TO EXPENSE CERTAIN
REFINERIES.

(a) In General.--Section 179C(c)(1) of the Internal Revenue
Code of 1986 (defining qualified refinery property) is
amended--
(1) by striking ``and before January 1, 2012'' in
subparagraph (B) and inserting ``and, in the case of any
qualified refinery described in subsection (d)(1), before
January 1, 2012'', and
(2) by inserting ``if described in subsection (d)(1)''
after ``of which'' in subparagraph (F)(i).
(b) Conforming Amendment.--Subsection (d) of section 179C
of the Internal Revenue Code of 1986 is amended to read as
follows:
``(d) Qualified Refinery.--For purposes of this section,
the term `qualified refinery' means any refinery located in
the United States which is designed to serve the primary
purpose of processing liquid fuel from--
``(1) crude oil, or
``(2) qualified fuels (as defined in section 45K(c)).''.
(c) Effective Date.--The amendments made by this section
shall take effect as if included in the amendment made by
section 1323(a) of the Energy Policy Act of 2005.

SEC. 8304. 5-YEAR AMORTIZATION OF GEOLOGICAL AND GEOPHYSICAL
EXPENDITURES FOR CERTAIN MAJOR INTEGRATED OIL
COMPANIES.

(a) In General.--Section 167(h) of the Internal Revenue
Code of 1986 (relating to amortization of geological and
geophysical expenditures) is amended by adding at the end the
following new paragraph:
``(5) Special rule for major integrated oil companies.--
``(A) In general.--In the case of an integrated oil company
described in subparagraph (B), paragraphs (1) and (4) shall
be applied by substituting `5-year' for `24 month'.
``(B) Integrated oil company described.--An integrated oil
company is described in this subparagraph if such company is
an integrated oil company (as defined in section 291(b)(4))
which--
``(i) has an average daily worldwide production of crude
oil of at least 500,000 barrels for the taxable year,
``(ii) had gross receipts in excess of $1,000,000,000 for
its last taxable year ending during calendar year 2005, and
``(iii) has an ownership interest (within the meaning of
section 613A(d)(3)) in crude oil refiner of 15 percent or
more.

For purposes of the preceding sentence, all persons treated
as a single employer under subsections (a) and (b) of section
shall be treated as 1 person and, in case of a short taxable
year, the rule under section 448(c)(3)(B) shall apply''.
(b) Effective Date.--The amendment made by this section
shall take effect as if included in the amendment made by
section 1329 of the Energy Policy Act of 2005.

SEC. 8305. REPEAL OF LIFO METHOD OF INVENTORY ACCOUNTING.

(a) In General.--Sections 472, 473, and 474 of the Internal
Revenue Code of 1986 are repealed.
(b) Conforming Amendments.--
(1) Section 56(g)(4)(D)(iii) of such Code is repealed.
(2) Section 312(n)(4) of such Code is repealed.
(3) Section 1363(d) of such Code is repealed.
(c) Effective Date.--The repeals made by this section shall
apply to taxable years beginning after the date of the
enactment of this Act.
(d) Change in Method of Accounting.--In the case of any
taxpayer required by the repeals made by subsection (a) to
change its method accounting for its first taxable year
beginning after the date of the enactment of this Act--
(1) such change shall be treated as initiated by the
taxpayer,
(2) such change shall be treated as made with the consent
of the Secretary of the Treasury, and
(3) the net amount of the adjustments required to be taken
into account by the taxpayer under section 481 of the
Internal Revenue Code of 1986 shall be taken into account
ratably over the 20-taxable year period beginning with the
first taxable year beginning after such date of enactment.

Subtitle D--CAFE Standards

SEC. 8401. CLARIFICATION OF AUTHORITY OF SECRETARY OF
TRANSPORTATION TO AMEND FUEL ECONOMY STANDARDS
FOR PASSENGER VEHICLES.

Section 32902(c) of title 49, United States Code, is
amended--
(1) in paragraph (1), by striking ``(1) Subject to
paragraph (2) of this subsection, the'' and inserting
``The''; and
(2) by striking paragraph (2).

Subtitle E--Alternative Fuels

SEC. 8501. PRODUCTION INCENTIVES FOR CELLULOSIC BIOFUELS.

Section 942(f) of the Energy Policy Act of 2005 (42 U.S.C.
16251(f)) is amended by striking ``$250,000,000'' and
inserting ``$150,000,000 for fiscal year 2007, $200,000,000
for fiscal year 2008, and $250,000,000 for each of fiscal
years 2009 through 2011''.

SEC. 8502. ADVANCED ENERGY INITIATIVE FOR VEHICLES.

(a) Purposes.--The purposes of this section are--
(1) to enable and promote, in partnership with industry,
comprehensive development, demonstration, and
commercialization of a wide range of electric drive
components, systems, and vehicles using diverse electric
drive transportation technologies;
(2) to make critical public investments to help private
industry, institutions of higher education, National
Laboratories, and research institutions to expand innovation,
industrial growth, and jobs in the United States;
(3) to expand the availability of the existing electric
infrastructure for fueling light duty transportation and
other on-road and nonroad vehicles that are using petroleum
and are mobile sources of emissions--
(A) including the more than 3,000,000 reported units (such
as electric forklifts, golf carts, and similar nonroad
vehicles) in use on the date of enactment of this Act; and
(B) with the goal of enhancing the energy security of the
United States, reduce dependence on imported oil, and reduce
emissions through the expansion of grid-supported mobility;
(4) to accelerate the widespread commercialization of all
types of electric drive vehicle technology into all sizes and
applications of vehicles, including commercialization of
plug-in hybrid electric vehicles and plug-in hybrid fuel cell
vehicles; and
(5) to improve the energy efficiency of and reduce the
petroleum use in transportation.
(b) Definitions.--In this section:
(1) Battery.--The term ``battery'' means an energy storage
device used in an on-road or nonroad vehicle powered in whole
or in part using an off-board or on-board source of
electricity.
(2) Electric drive transportation technology.--The term
``electric drive transportation technology'' means--
(A) a vehicle that--
(i) uses an electric motor for all or part of the motive
power of the vehicle; and
(ii) may use off-board electricity, including battery
electric vehicles, fuel cell vehicles, engine dominant hybrid
electric vehicles, plug-in hybrid electric vehicles, plug-in
hybrid fuel cell vehicles, and electric rail; or
(B) equipment relating to transportation or mobile sources
of air pollution that uses an electric motor to replace an
internal combustion engine for all or part of the work of the
equipment, including corded electric equipment linked to
transportation or mobile sources of air pollution.
(3) Engine dominant hybrid electric vehicle.--The term
``engine dominant hybrid electric vehicle'' means an on-road
or nonroad vehicle that--
(A) is propelled by an internal combustion engine or heat
engine using--
(i) any combustible fuel; and
(ii) an on-board, rechargeable storage device; and
(B) has no means of using an off-board source of
electricity.
(4) Fuel cell vehicle.--The term ``fuel cell vehicle''
means an on-road or nonroad vehicle that uses a fuel cell (as
defined in section 803 of the Energy Policy Act of 2005 (42
U.S.C. 16152)).
(5) Initiative.--The term ``Initiative'' means the Advanced
Battery Initiative established by the Secretary under
subsection (f)(1).
(6) Nonroad vehicle.--The term ``nonroad vehicle'' has the
meaning given the term in section 216 of the Clean Air Act
(42 U.S.C. 7550).
(7) Plug-in hybrid electric vehicle.--The term ``plug-in
hybrid electric vehicle'' means an on-road or nonroad vehicle
that is propelled by an internal combustion engine or heat
engine using--
(A) any combustible fuel;
(B) an on-board, rechargeable storage device; and
(C) a means of using an off-board source of electricity.
(8) Plug-in hybrid fuel cell vehicle.--The term ``plug-in
hybrid fuel cell vehicle'' means a fuel cell vehicle with a
battery powered by an off-board source of electricity.
(9) Industry alliance.--The term ``Industry Alliance''
means the entity selected by the Secretary under subsection
(f)(2).
(10) Institution of higher education.--The term
``institution of higher education'' has the meaning given the
term in section 2 of the Energy Policy Act of 2005 (42 U.S.C.
15801).
(11) Secretary.--The term ``Secretary'' means the Secretary
of Energy.
(c) Goals.--The goals of the electric drive transportation
technology program established under subsection (e) shall be
to develop, in partnership with industry and institutions of
higher education, projects that focus on--
(1) innovative electric drive technology developed in the
United States;
(2) growth of employment in the United States in electric
drive design and manufacturing;

[[Page S3736]]

(3) validation of the plug-in hybrid potential through
fleet demonstrations; and
(4) acceleration of fuel cell commercialization through
comprehensive development and commercialization of the
electric drive technology systems that are the foundational
technology of the fuel cell vehicle system.
(d) Assessment.--Not later than 120 days after the date of
enactment of this Act, the Secretary shall offer to enter
into an arrangement with the National Academy of Sciences--
(1) to conduct an assessment (in cooperation with industry,
standards development organizations, and other entities, as
appropriate), of state-of-the-art battery technologies with
potential application for electric drive transportation;
(2) to identify knowledge gaps in the scientific and
technological bases of battery manufacture and use;
(3) to identify fundamental research areas that would
likely have a significant impact on the development of
superior battery technologies for electric drive vehicle
applications; and
(4) to recommend steps to the Secretary to accelerate the
development of battery technologies for electric drive
transportation.
(e) Program.--The Secretary shall conduct a program of
research, development, demonstration, and commercial
application for electric drive transportation technology,
including--
(1) high-capacity, high-efficiency batteries;
(2) high-efficiency on-board and off-board charging
components;
(3) high-powered drive train systems for passenger and
commercial vehicles and for nonroad equipment;
(4) control system development and power train development
and integration for plug-in hybrid electric vehicles, plug-in
hybrid fuel cell vehicles, and engine dominant hybrid
electric vehicles, including--
(A) development of efficient cooling systems;
(B) analysis and development of control systems that
minimize the emissions profile when clean diesel engines are
part of a plug-in hybrid drive system; and
(C) development of different control systems that optimize
for different goals, including--
(i) battery life;
(ii) reduction of petroleum consumption; and
(iii) green house gas reduction;
(5) nanomaterial technology applied to both battery and
fuel cell systems;
(6) large-scale demonstrations, testing, and evaluation of
plug-in hybrid electric vehicles in different applications
with different batteries and control systems, including--
(A) military applications;
(B) mass market passenger and light-duty truck
applications;
(C) private fleet applications; and
(D) medium- and heavy-duty applications;
(7) a nationwide education strategy for electric drive
transportation technologies providing secondary and high
school teaching materials and support for education offered
by institutions of higher education that is focused on
electric drive system and component engineering;
(8) development, in consultation with the Administrator of
the Environmental Protection Agency, of procedures for
testing and certification of criteria pollutants, fuel
economy, and petroleum use for light-,
medium-, and heavy-duty vehicle applications, including
consideration of--
(A) the vehicle and fuel as a system, not just an engine;
and
(B) nightly off-board charging; and
(9) advancement of battery and corded electric
transportation technologies in mobile source applications
by--
(A) improvement in battery, drive train, and control system
technologies; and
(B) working with industry and the Administrator of the
Environmental Protection Agency--
(i) to understand and inventory markets; and
(ii) to identify and implement methods of removing barriers
for existing and emerging applications.
(f) Advanced Battery Initiative.--
(1) In general.--The Secretary shall establish and carry
out an Advanced Battery Initiative in accordance with this
subsection to support research, development, demonstration,
and commercial application of battery technologies.
(2) Industry alliance.--Not later than 180 days after the
date of enactment of this Act, the Secretary shall
competitively select an Industry Alliance to represent
participants who are private, for-profit firms, the primary
business of which is the manufacturing of batteries.
(3) Research.--
(A) Grants.--The Secretary shall carry out research
activities of the Initiative through competitively-awarded
grants to--
(i) researchers, including Industry Alliance participants;
(ii) small businesses;
(iii) National Laboratories; and
(iv) institutions of higher education.
(B) Industry alliance.--The Secretary shall annually
solicit from the Industry Alliance--
(i) comments to identify advanced battery technology needs
relevant to electric drive technology;
(ii) an assessment of the progress of research activities
of the Initiative; and
(iii) assistance in annually updating advanced battery
technology roadmaps.
(4) Availability to the public.--The information and
roadmaps developed under this subsection shall be available
to the public.
(5) Preference.--In making awards under this subsection,
the Secretary shall give preference to participants in the
Industry Alliance.
(g) Cost Sharing.--In carrying out this section, the
Secretary shall require cost sharing in accordance with
section 988 of the Energy Policy Act of 2005 (42 U.S.C.
16352).
(h) Authorization of Appropriations.--There is authorized
to be appropriated to carry out this section $300,000,000 for
each of fiscal years 2007 through 2012.

Subtitle F--Strategic Petroleum Reserve

SEC. 8601. STRATEGIC PETROLEUM RESERVE.

(a) Findings.--The Senate finds that--
(1) the Strategic Petroleum Reserve, as established by the
Energy Policy and Conservation Act (42 U.S.C. 6201 et seq.),
provides the United States with an emergency crude oil supply
reserve that ensures that a disruption in commercial oil
supplies will not threaten the United States economy;
(2) the Energy Policy Act of 2005 (42 U.S.C. 15801 et seq.)
strengthened the Strategic Petroleum Reserve by authorizing a
capacity of 1,000,000,000 barrels of crude oil;
(3) as of the date of enactment of this Act, the inventory
in the Strategic Petroleum Reserve is sufficiently large
enough to guard against supply disruptions during the time
period for the temporary cessation of deposits described in
subsection (b)(1); and
(4) the cessation of deposits to the Strategic Petroleum
Reserve will add approximately 2,000,000 barrels of crude oil
supply into the market.
(b) Sense of the Senate.--It is the sense of the Senate
that--
(1) consistent with the authority granted under the Energy
Policy and Conservation Act (42 U.S.C. 6201 et seq.), the
Secretary of Energy should cease deposits to the Strategic
Petroleum Reserve for a period of not less than 6 months;
(2) the Secretary of Energy should continue to work toward
establishing the infrastructure necessary to achieve the
1,000,0000,0000 barrels of crude oil capacity authorized
under the Energy Policy Act of 2005 (42 U.S.C. 15801 et
seq.); and
(3) after the temporary cessation of deposits to the
Strategic Petroleum Reserve, the Secretary of Energy should
continue to increase the inventory of crude oil in the
Strategic Petroleum Reserve to work toward meeting the
authorized capacity level to enhance the energy security of
the United States.

Subtitle G--Arctic Coastal Plain Domestic Energy

SEC. 8701. SHORT TITLE.

This subtitle may be cited as the ``Arctic Coastal Plain
Domestic Energy Security Act of 2006''.

SEC. 8702. DEFINITIONS.

In this subtitle:
(1) Coastal plain.--The term ``Coastal Plain'' means that
area identified as such in the map entitled ``Arctic National
Wildlife Refuge'', dated August 1980, as referenced in
section 1002(b) of the Alaska National Interest Lands
Conservation Act of 1980 (16 U.S.C. 3142(b)(1)), comprising
approximately 1,549,000 acres, and as described in appendix I
to part 37 of title 50, Code of Federal Regulations.
(2) Secretary.--The term ``Secretary'', except as otherwise
provided, means the Secretary of the Interior or the
Secretary's designee.

SEC. 8703. LEASING PROGRAM FOR LANDS WITHIN THE COASTAL
PLAIN.

(a) In General.--The Secretary shall take such actions as
are necessary--
(1) to establish and implement in accordance with this Act
a competitive oil and gas leasing program under the Mineral
Leasing Act (30 U.S.C. 181 et seq.) that will result in an
environmentally sound program for the exploration,
development, and production of the oil and gas resources of
the Coastal Plain; and
(2) to administer the provisions of this subtitle through
regulations, lease terms, conditions, restrictions,
prohibitions, stipulations, and other provisions that ensure
the oil and gas exploration, development, and production
activities on the Coastal Plain will result in no significant
adverse effect on fish and wildlife, their habitat,
subsistence resources, and the environment, and including, in
furtherance of this goal, by requiring the application of the
best commercially available technology for oil and gas
exploration, development, and production to all exploration,
development, and production operations under this subtitle in
a manner that ensures the receipt of fair market value by the
public for the mineral resources to be leased.
(b) Repeal.--Section 1003 of the Alaska National Interest
Lands Conservation Act of 1980 (16 U.S.C. 3143) is repealed.
(c) Compliance With Requirements Under Certain Other
Laws.--
(1) Compatibility.--For purposes of the National Wildlife
Refuge System Administration Act of 1966, the oil and gas
leasing program and activities authorized by this section in
the Coastal Plain are deemed to be compatible with the
purposes for which the Arctic National Wildlife Refuge was
established, and that no further findings or decisions are
required to implement this determination.

[[Page S3737]]

(2) Adequacy of the department of the interior's
legislative environmental impact statement.--The ``Final
Legislative Environmental Impact Statement'' (April 1987) on
the Coastal Plain prepared pursuant to section 1002 of the
Alaska National Interest Lands Conservation Act of 1980 (16
U.S.C. 3142) and section 102(2)(C) of the National
Environmental Policy Act of 1969 (42 U.S.C. 4332(2)(C)) is
deemed to satisfy the requirements under the National
Environmental Policy Act of 1969 that apply with respect to
actions authorized to be taken by the Secretary to develop
and promulgate the regulations for the establishment of a
leasing program authorized by this subtitle before the
conduct of the first lease sale.
(3) Compliance with nepa for other actions.--Before
conducting the first lease sale under this subtitle, the
Secretary shall prepare an environmental impact statement
under the National Environmental Policy Act of 1969 with
respect to the actions authorized by this subtitle that are
not referred to in paragraph (2). Notwithstanding any other
law, the Secretary is not required to identify nonleasing
alternative courses of action or to analyze the environmental
effects of such courses of action. The Secretary shall only
identify a preferred action for such leasing and a single
leasing alternative, and analyze the environmental effects
and potential mitigation measures for those two alternatives.
The identification of the preferred action and related
analysis for the first lease sale under this subtitle shall
be completed within 18 months after the date of the enactment
of this Act. The Secretary shall only consider public
comments that specifically address the Secretary's preferred
action and that are filed within 20 days after publication of
an environmental analysis. Notwithstanding any other law,
compliance with this paragraph is deemed to satisfy all
requirements for the analysis and consideration of the
environmental effects of proposed leasing under this
subtitle.
(d) Relationship to State and Local Authority.--Nothing in
this subtitle shall be considered to expand or limit State
and local regulatory authority.
(e) Special Areas.--
(1) In general.--The Secretary, after consultation with the
State of Alaska, the city of Kaktovik, and the North Slope
Borough, may designate up to a total of 45,000 acres of the
Coastal Plain as a Special Area if the Secretary determines
that the Special Area is of such unique character and
interest so as to require special management and regulatory
protection. The Secretary shall designate as such a Special
Area the Sadlerochit Spring area, comprising approximately
4,000 acres as depicted on such map as shall be identified by
the Secretary.
(2) Management.--Each such Special Area shall be managed so
as to protect and preserve the area's unique and diverse
character including its fish, wildlife, and subsistence
resource values.
(3) Exclusion from leasing or surface occupancy.--The
Secretary may exclude any Special Area from leasing. If the
Secretary leases a Special Area, or any part thereof, for
purposes of oil and gas exploration, development, production,
and related activities, there shall be no surface occupancy
of the lands comprising the Special Area.
(4) Directional drilling.--Notwithstanding the other
provisions of this subsection, the Secretary may lease all or
a portion of a Special Area under terms that permit the use
of horizontal drilling technology from sites on leases
located outside the area.
(f) Limitation on Closed Areas.--The Secretary's sole
authority to close lands within the Coastal Plain to oil and
gas leasing and to exploration, development, and production
is that set forth in this subtitle.
(g) Regulations.--
(1) In general.--The Secretary shall prescribe such
regulations as may be necessary to carry out this subtitle,
including rules and regulations relating to protection of the
fish and wildlife, their habitat, subsistence resources, and
environment of the Coastal Plain, by no later than 15 months
after the date of the enactment of this Act.
(2) Revision of regulations.--The Secretary shall
periodically review and, if appropriate, revise the rules and
regulations issued under subsection (a) to reflect any
significant biological, environmental, or engineering data
that come to the Secretary's attention.

SEC. 8704. LEASE SALES.

(a) In General.--Lands may be leased pursuant to this
subtitle to any person qualified to obtain a lease for
deposits of oil and gas under the Mineral Leasing Act (30
U.S.C. 181 et seq.).
(b) Procedures.--The Secretary shall, by regulation,
establish procedures for--
(1) receipt and consideration of sealed nominations for any
area in the Coastal Plain for inclusion in, or exclusion (as
provided in subsection (c)) from, a lease sale;
(2) the holding of lease sales after such nomination
process; and
(3) public notice of and comment on designation of areas to
be included in, or excluded from, a lease sale.
(c) Lease Sale Bids.--Bidding for leases under this
subtitle shall be by sealed competitive cash bonus bids.
(d) Acreage Minimum in First Sale.--In the first lease sale
under this subtitle, the Secretary shall offer for lease
those tracts the Secretary considers to have the greatest
potential for the discovery of hydrocarbons, taking into
consideration nominations received pursuant to subsection
(b)(1), but in no case less than 200,000 acres.
(e) Timing of Lease Sales.--The Secretary shall--
(1) conduct the first lease sale under this subtitle within
22 months after the date of the enactment of this Act; and
(2) conduct additional sales so long as sufficient interest
in development exists to warrant, in the Secretary's
judgment, the conduct of such sales.

SEC. 8705. GRANT OF LEASES BY THE SECRETARY.

(a) In General.--The Secretary may grant to the highest
responsible qualified bidder in a lease sale conducted
pursuant to section 8704 any lands to be leased on the
Coastal Plain upon payment by the lessee of such bonus as may
be accepted by the Secretary.
(b) Subsequent Transfers.--No lease issued under this
subtitle may be sold, exchanged, assigned, sublet, or
otherwise transferred except with the approval of the
Secretary. Prior to any such approval the Secretary shall
consult with, and give due consideration to the views of, the
Attorney General.

SEC. 8706. LEASE TERMS AND CONDITIONS.

(a) In General.--An oil or gas lease issued pursuant to
this subtitle shall--
(1) provide for the payment of a royalty of not less than
12\1/2\ percent in amount or value of the production removed
or sold from the lease, as determined by the Secretary under
the regulations applicable to other Federal oil and gas
leases;
(2) provide that the Secretary may close, on a seasonal
basis, portions of the Coastal Plain to exploratory drilling
activities as necessary to protect caribou calving areas and
other species of fish and wildlife;
(3) require that the lessee of lands within the Coastal
Plain shall be fully responsible and liable for the
reclamation of lands within the Coastal Plain and any other
Federal lands that are adversely affected in connection with
exploration, development, production, or transportation
activities conducted under the lease and within the Coastal
Plain by the lessee or by any of the subcontractors or agents
of the lessee;
(4) provide that the lessee may not delegate or convey, by
contract or otherwise, the reclamation responsibility and
liability to another person without the express written
approval of the Secretary;
(5) provide that the standard of reclamation for lands
required to be reclaimed under this subtitle shall be, as
nearly as practicable, a condition capable of supporting the
uses which the lands were capable of supporting prior to any
exploration, development, or production activities, or upon
application by the lessee, to a higher or better use as
approved by the Secretary;
(6) contain terms and conditions relating to protection of
fish and wildlife, their habitat, and the environment as
required pursuant to section 8703(a)(2);
(7) provide that the lessee, its agents, and its
contractors use best efforts to provide a fair share, as
determined by the level of obligation previously agreed to in
the 1974 agreement implementing section 29 of the Federal
Agreement and Grant of Right of Way for the Operation of the
Trans-Alaska Pipeline, of employment and contracting for
Alaska Natives and Alaska Native Corporations from throughout
the State;
(8) prohibit the export of oil produced under the lease;
and
(9) contain such other provisions as the Secretary
determines necessary to ensure compliance with the provisions
of this subtitle and the regulations issued under this
subtitle.
(b) Project Labor Agreements.--The Secretary, as a term and
condition of each lease under this subtitle and in
recognizing the Government's proprietary interest in labor
stability and in the ability of construction labor and
management to meet the particular needs and conditions of
projects to be developed under the leases issued pursuant to
this subtitle and the special concerns of the parties to such
leases, shall require that the lessee and its agents and
contractors negotiate to obtain a project labor agreement for
the employment of laborers and mechanics on production,
maintenance, and construction under the lease.

SEC. 8707. COASTAL PLAIN ENVIRONMENTAL PROTECTION.

(a) No Significant Adverse Effect Standard to Govern
Authorized Coastal Plain Activities.--The Secretary shall,
consistent with the requirements of section 8703, administer
the provisions of this subtitle through regulations, lease
terms, conditions, restrictions, prohibitions, stipulations,
and other provisions that--
(1) ensure the oil and gas exploration, development, and
production activities on the Coastal Plain will result in no
significant adverse effect on fish and wildlife, their
habitat, and the environment;
(2) require the application of the best commercially
available technology for oil and gas exploration,
development, and production on all new exploration,
development, and production operations; and
(3) ensure that the maximum amount of surface acreage
covered by production and support facilities, including
airstrips and any areas covered by gravel berms or piers for
support of pipelines, does not exceed 2,000 acres on the
Coastal Plain.
(b) Site-Specific Assessment and Mitigation.--The Secretary
shall also require, with respect to any proposed drilling and
related activities, that--

[[Page S3738]]

(1) a site-specific analysis be made of the probable
effects, if any, that the drilling or related activities will
have on fish and wildlife, their habitat, and the
environment;
(2) a plan be implemented to avoid, minimize, and mitigate
(in that order and to the extent practicable) any significant
adverse effect identified under paragraph (1); and
(3) the development of the plan shall occur after
consultation with the agency or agencies having jurisdiction
over matters mitigated by the plan.
(c) Regulations to Protect Coastal Plain Fish and Wildlife
Resources, Subsistence Users, and the Environment.--Before
implementing the leasing program authorized by this subtitle,
the Secretary shall prepare and promulgate regulations, lease
terms, conditions, restrictions, prohibitions, stipulations,
and other measures designed to ensure that the activities
undertaken on the Coastal Plain under this subtitle are
conducted in a manner consistent with the purposes and
environmental requirements of this subtitle.
(d) Compliance With Federal and State Environmental Laws
and Other Requirements.--The proposed regulations, lease
terms, conditions, restrictions, prohibitions, and
stipulations for the leasing program under this subtitle
shall require compliance with all applicable provisions of
Federal and State environmental law and shall also require
the following:
(1) Standards at least as effective as the safety and
environmental mitigation measures set forth in items 1
through 29 at pages 167 through 169 of the ``Final
Legislative Environmental Impact Statement'' (April 1987) on
the Coastal Plain.
(2) Seasonal limitations on exploration, development, and
related activities, where necessary, to avoid significant
adverse effects during periods of concentrated fish and
wildlife breeding, denning, nesting, spawning, and migration.
(3) That exploration activities, except for surface
geological studies, be limited to the period between
approximately November 1 and May 1 each year and that
exploration activities shall be supported by ice roads,
winter trails with adequate snow cover, ice pads, ice
airstrips, and air transport methods, except that such
exploration activities may occur at other times, if the
Secretary finds that such exploration will have no
significant adverse effect on the fish and wildlife, their
habitat, and the environment of the Coastal Plain.
(4) Design safety and construction standards for all
pipelines and any access and service roads, that--
(A) minimize, to the maximum extent possible, adverse
effects upon the passage of migratory species such as
caribou; and
(B) minimize adverse effects upon the flow of surface water
by requiring the use of culverts, bridges, and other
structural devices.
(5) Prohibitions on public access and use on all pipeline
access and service roads.
(6) Stringent reclamation and rehabilitation requirements,
consistent with the standards set forth in this subtitle,
requiring the removal from the Coastal Plain of all oil and
gas development and production facilities, structures, and
equipment upon completion of oil and gas production
operations, except that the Secretary may exempt from the
requirements of this paragraph those facilities, structures,
or equipment that the Secretary determines would assist in
the management of the Arctic National Wildlife Refuge and
that are donated to the United States for that purpose.
(7) Appropriate prohibitions or restrictions on access by
all modes of transportation.
(8) Appropriate prohibitions or restrictions on sand and
gravel extraction.
(9) Consolidation of facility siting.
(10) Appropriate prohibitions or restrictions on use of
explosives.
(11) Avoidance, to the extent practicable, of springs,
streams, and river system; the protection of natural surface
drainage patterns, wetlands, and riparian habitats; and the
regulation of methods or techniques for developing or
transporting adequate supplies of water for exploratory
drilling.
(12) Avoidance or reduction of air traffic-related
disturbance to fish and wildlife.
(13) Treatment and disposal of hazardous and toxic wastes,
solid wastes, reserve pit fluids, drilling muds and cuttings,
and domestic wastewater, including an annual waste management
report, a hazardous materials tracking system, and a
prohibition on chlorinated solvents, in accordance with
applicable Federal and State environmental law.
(14) Fuel storage and oil spill contingency planning.
(15) Research, monitoring, and reporting requirements.
(16) Field crew environmental briefings.
(17) Avoidance of significant adverse effects upon
subsistence hunting, fishing, and trapping by subsistence
users.
(18) Compliance with applicable air and water quality
standards.
(19) Appropriate seasonal and safety zone designations
around well sites, within which subsistence hunting and
trapping shall be limited.
(20) Reasonable stipulations for protection of cultural and
archeological resources.
(21) All other protective environmental stipulations,
restrictions, terms, and conditions deemed necessary by the
Secretary.
(e) Considerations.--In preparing and promulgating
regulations, lease terms, conditions, restrictions,
prohibitions, and stipulations under this section, the
Secretary shall consider the following:
(1) The stipulations and conditions that govern the
National Petroleum Reserve-Alaska leasing program, as set
forth in the 1999 Northeast National Petroleum Reserve-Alaska
Final Integrated Activity Plan/Environmental Impact
Statement.
(2) The environmental protection standards that governed
the initial Coastal Plain seismic exploration program under
parts 37.31 to 37.33 of title 50, Code of Federal
Regulations.
(3) The land use stipulations for exploratory drilling on
the KIC-ASRC private lands that are set forth in Appendix 2
of the August 9, 1983, agreement between Arctic Slope
Regional Corporation and the United States.
(f) Facility Consolidation Planning.--
(1) In general.--The Secretary shall, after providing for
public notice and comment, prepare and update periodically a
plan to govern, guide, and direct the siting and construction
of facilities for the exploration, development, production,
and transportation of Coastal Plain oil and gas resources.
(2) Objectives.--The plan shall have the following
objectives:
(A) Avoiding unnecessary duplication of facilities and
activities.
(B) Encouraging consolidation of common facilities and
activities.
(C) Locating or confining facilities and activities to
areas that will minimize impact on fish and wildlife, their
habitat, and the environment.
(D) Utilizing existing facilities wherever practicable.
(E) Enhancing compatibility between wildlife values and
development activities.
(g) Access to Public Lands.--The Secretary shall--
(1) manage public lands in the Coastal Plain subject to
section subsections (a) and (b) of section 811 of the Alaska
National Interest Lands Conservation Act (16 U.S.C. 3121);
and
(2) ensure that local residents shall have reasonable
access to public lands in the Coastal Plain for traditional
uses.

SEC. 8708. EXPEDITED JUDICIAL REVIEW.

(a) Filing of Complaint.--
(1) Deadline.--Subject to paragraph (2), any complaint
seeking judicial review of any provision of this subtitle or
any action of the Secretary under this subtitle shall be
filed in any appropriate district court of the United
States--
(A) except as provided in subparagraph (B), within the 90-
day period beginning on the date of the action being
challenged; or
(B) in the case of a complaint based solely on grounds
arising after such period, within 90 days after the
complainant knew or reasonably should have known of the
grounds for the complaint.
(2) Venue.--Any complaint seeking judicial review of an
action of the Secretary under this subtitle may be filed only
in the United States Court of Appeals for the District of
Columbia.
(3) Limitation on scope of certain review.--Judicial review
of a Secretarial decision to conduct a lease sale under this
subtitle, including the environmental analysis thereof, shall
be limited to whether the Secretary has complied with the
terms of this subtitle and shall be based upon the
administrative record of that decision. The Secretary's
identification of a preferred course of action to enable
leasing to proceed and the Secretary's analysis of
environmental effects under this subtitle shall be presumed
to be correct unless shown otherwise by clear and convincing
evidence to the contrary.
(b) Limitation on Other Review.--Actions of the Secretary
with respect to which review could have been obtained under
this section shall not be subject to judicial review in any
civil or criminal proceeding for enforcement.

SEC. 8709. FEDERAL AND STATE DISTRIBUTION OF REVENUES.

(a) In General.--Notwithstanding any other provision of
law, of the amount of adjusted bonus, rental, and royalty
revenues from oil and gas leasing and operations authorized
under this subtitle--
(1) 50 percent shall be paid to the State of Alaska; and
(2) except as provided in section 712(d), the balance shall
be deposited into the Treasury as miscellaneous receipts.
(b) Payments to Alaska.--Payments to the State of Alaska
under this section shall be made semiannually.
(c) Use of Bonus Payments for Low-Income Home Energy
Assistance.--Amounts that are received by the United States
as bonuses for leases under this subtitle and deposited into
the Treasury under subsection (a)(2) may be appropriated to
the Secretary of the Health and Human Services, in addition
to amounts otherwise available, to provide assistance under
the Low-Income Home Energy Assistance Act of 1981 (42 U.S.C.
8621 et seq.).

SEC. 8710. RIGHTS-OF-WAY ACROSS THE COASTAL PLAIN.

(a) Exemption.--Title XI of the Alaska National Interest
Lands Conservation Act of 1980 (16 U.S.C. 3161 et seq.) shall
not apply to the issuance by the Secretary under section 28
of the Mineral Leasing Act (30 U.S.C. 185) of rights-of-way
and easements across the Coastal Plain for the transportation
of oil and gas.
(b) Terms and Conditions.--The Secretary shall include in
any right-of-way or easement referred to in subsection (a)
such terms and conditions as may be necessary to ensure that
transportation of oil and gas does

[[Page S3739]]

not result in a significant adverse effect on the fish and
wildlife, subsistence resources, their habitat, and the
environment of the Coastal Plain, including requirements that
facilities be sited or designed so as to avoid unnecessary
duplication of roads and pipelines.
(c) Regulations.--The Secretary shall include in
regulations under section 8703(g) provisions granting rights-
of-way and easements described in subsection (a) of this
section.

SEC. 8711. CONVEYANCE.

In order to maximize Federal revenues by removing clouds on
title to lands and clarifying land ownership patterns within
the Coastal Plain, the Secretary, notwithstanding the
provisions of section 1302(h)(2) of the Alaska National
Interest Lands Conservation Act (16 U.S.C. 3192(h)(2)), shall
convey--
(1) to the Kaktovik Inupiat Corporation the surface estate
of the lands described in paragraph 1 of Public Land Order
6959, to the extent necessary to fulfill the Corporation's
entitlement under section 12 of the Alaska Native Claims
Settlement Act (43 U.S.C. 1611) in accordance with the terms
and conditions of the Agreement between the Department of the
Interior, the United States Fish and Wildlife Service, the
Bureau of Land Management, and the Kaktovik Inupiat
Corporation effective January 22, 1993; and
(2) to the Arctic Slope Regional Corporation the remaining
subsurface estate to which it is entitled pursuant to the
August 9, 1983, agreement between the Arctic Slope Regional
Corporation and the United States of America.

SEC. 8712. LOCAL GOVERNMENT IMPACT AID AND COMMUNITY SERVICE
ASSISTANCE.

(a) Financial Assistance Authorized.--
(1) In general.--The Secretary may use amounts available
from the Coastal Plain Local Government Impact Aid Assistance
Fund established by subsection (d) to provide timely
financial assistance to entities that are eligible under
paragraph (2) and that are directly impacted by the
exploration for or production of oil and gas on the Coastal
Plain under this subtitle.
(2) Eligible entities.--The North Slope Borough, Kaktovik,
and other boroughs, municipal subdivisions, villages, and any
other community organized under Alaska State law shall be
eligible for financial assistance under this section.
(b) Use of Assistance.--Financial assistance under this
section may be used only for--
(1) planning for mitigation of the potential effects of oil
and gas exploration and development on environmental, social,
cultural, recreational and subsistence values;
(2) implementing mitigation plans and maintaining
mitigation projects;
(3) developing, carrying out, and maintaining projects and
programs that provide new or expanded public facilities and
services to address needs and problems associated with such
effects, including firefighting, police, water, waste
treatment, medivac, and medical services; and
(4) establishment of a coordination office, by the North
Slope Borough, in the City of Kaktovik, which shall--
(A) coordinate with and advise developers on local
conditions, impact, and history of the areas utilized for
development; and
(B) provide to the Committee on Resources of the Senate and
the Committee on Energy and Resources of the Senate an annual
report on the status of coordination between developers and
the communities affected by development.
(c) Application.--
(1) In general.--Any community that is eligible for
assistance under this section may submit an application for
such assistance to the Secretary, in such form and under such
procedures as the Secretary may prescribe by regulation.
(2) North slope borough communities.--A community located
in the North Slope Borough may apply for assistance under
this section either directly to the Secretary or through the
North Slope Borough.
(3) Application assistance.--The Secretary shall work
closely with and assist the North Slope Borough and other
communities eligible for assistance under this section in
developing and submitting applications for assistance under
this section.
(d) Establishment of Fund.--
(1) In general.--There is established in the Treasury the
Coastal Plain Local Government Impact Aid Assistance Fund.
(2) Use.--Amounts in the fund may be used only for
providing financial assistance under this section.
(3) Deposits.--Subject to paragraph (4), there shall be
deposited into the fund amounts received by the United States
as revenues derived from rents, bonuses, and royalties under
on leases and lease sales authorized under this subtitle.
(4) Limitation on deposits.--The total amount in the fund
may not exceed $11,000,000.
(5) Investment of balances.--The Secretary of the Treasury
shall invest amounts in the fund in interest bearing
government securities.
(e) Authorization of Appropriations.--To provide financial
assistance under this section there is authorized to be
appropriated to the Secretary from the Coastal Plain Local
Government Impact Aid Assistance Fund $5,000,000 for each
fiscal year.
______

SA 3701. Mr. ALLARD (for himself, Mr. Durbin, and Ms. Mikulski)
submitted an amendment intended to be proposed by him to the bill H.R.
4939, making emergency supplemental appropriations for the fiscal year
ending September 30, 2006, and for other purposes; as follows:

At the appropriate place, insert the following:

TITLE __--OTHER MATTERS

LEGISLATIVE BRANCH

ARCHITECT OF THE CAPITOL

Capitol Power Plant

For an additional amount for ``Capitol Power Plant'',
$27,600,000, to remain available until September 30, 2011:
Provided, That the amount provided under this heading is
designated as an emergency requirement pursuant to section
402 of H. Con. Res. 95 (109th Congress), the concurrent
resolution on the budget for fiscal year 2006.
______

SA 3702. Mr. CHAMBLISS (for himself and Mr. Isakson) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

COMPREHENSIVE REVIEW ON PROCEDURES OF THE DEPARTMENT OF DEFENSE ON
MORTUARY AFFAIRS

Sec. 7032. (a) Report.--As soon as practicable after the
completion of the comprehensive review of the procedures of
the Department of Defense on mortuary affairs, the Secretary
of Defense shall submit to the congressional defense
committees a report on the review.
(b) Additional Elements.--In conducting the comprehensive
review described in subsection (a), the Secretary shall also
address, in addition to any other matters covered by the
review, the following:
(1) The utilization of additional or increased
refrigeration (including icing) in combat theaters in order
to enhance preservation of remains.
(2) The relocation of refrigeration assets further forward
in the field.
(3) Specific time standards for the movement of remains
from combat units.
(4) The forward location of autopsy and embalming
operations.
(5) Any other matters that the Secretary considers
appropriate in order to speed the return of remains to the
United States in a non-decomposed state.
(c) Additional Element of Policy on Casualty Assistance to
Survivors of Military Decedents.--Section 562(b) of the
National Defense Authorization Act for Fiscal Year 2006
(Public Law 109-163; 119 Stat. 3267; 10 U.S.C. 1475 note) is
amended by adding at the end the following new paragraph:
``(12) The process by which the Department of Defense, upon
request, briefs survivors of military decedents on the cause
of, and any investigation into, the death of such military
decedents and on the disposition and transportation of the
remains of such decedents, which process shall--
``(A) provide for the provision of such briefings by fully
qualified Department personnel;
``(B) ensure briefings take place as soon as possible after
death and updates are provided in a timely manner when new
information becomes available;
``(C) ensure that--
``(i) such briefings and updates relate the most complete
and accurate information available at the time of such
briefings or updates, as the case may be; and
``(ii) incomplete or unverified information is identified
as such during the course of such briefings or updates; and
``(D) include procedures by which such survivors shall,
upon request, receive updates or supplemental information on
such briefings or updates from qualified Department
personnel.''.
______

SA 3703. Mr. KOHL submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

TITLE ____

GENERIC DRUG APPLICATIONS

DEPARTMENT OF HEALTH AND HUMAN SERVICES

Food and Drug Administration

SALARIES AND EXPENSES

For an additional amount for the Food and Drug
Administration, Office of Generic Drugs and related
activities, $20,000,000, to remain available until expended:
Provided, That the amount provided under this heading shall
be applied to the Office of Generic Drugs and related
activities to reduce the number of generic drug applications
awaiting action by the Food and Drug Administration: Provided
further, That the amount provided under this heading is
designated as an emergency requirement pursuant to section
402 of H. Con. Res. 95 (109th Congress), the concurrent
resolution on the budget for fiscal year 2006.
______

SA 3704. Mr. THUNE submitted an amendment intended to be proposed by

[[Page S3740]]

him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

MEDICAL FACILITIES, DEPARTMENT OF VETERANS AFFAIRS

Sec. 7032. (a) Availability of Amount.--There is
appropriated for the Department of Veterans Affairs for the
Veterans Health Administration for Medical Facilities,
$20,000,000, with the entire amount designated as an
emergency requirement pursuant to section 402 of H. Con. Res
95 (109th Congress), the concurrent resolution on the budget
for fiscal year 2006.
(b) Offset.--The amount appropriated by chapter 7 of title
II of this Act under the heading ``National and Community
Service Programs, Operating Expenses'' is hereby reduced by
$20,000,000.
______

SA 3705. Mr. OBAMA submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

REVIEW OF RECONSTRUCTION DESIGN, LAKE MICHIGAN SHORELINE, ILLINOIS

Sec. 7__. The District Engineers of the Buffalo and Seattle
Districts of the Corps of Engineers shall use $150,000 of
amounts made available for investigations of the Corps of
Engineers pursuant to title I of Public Law 109-103 (119
Stat. 2247), to conduct an immediate review of a
reconstruction design with the review based on the standards
under section 68 of title 36, Code of Federal Regulations (or
a successor regulation), for the portion between 54th and
57th Street of Reach 4 of the storm damage reduction project
authorized by section 101(a)(12) of the Water Resources
Development Act of 1996 (110 Stat. 3664; 113 Stat. 302).
______

SA 3706. Mr. LEVIN (for himself, Mr. Dorgan, Ms. Stabenow, and Mr.
Conrad) submitted an amendment intended to be proposed by him to the
bill H.R. 4939, making emergency supplemental appropriations for the
fiscal year ending September 30, 2006, and for other purposes; which
was ordered to lie on the table; as follows:

On page 126, between lines 14 and 15, insert the following:

Customs and Border Protection

For an additional amount for ``Air and Marine Interdiction,
Operations, Maintenance, and Procurement'', $12,000,000, for
the Northern Border airwings in Michigan and North Dakota:
Provided, That the amount provided under this heading is
designated as an emergency requirement under section 402 of
H. Con. Res. 95 (109th Congress), the concurrent resolution
on the budget for fiscal year 2006.

______

SA 3707. Mr. FRIST submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:
Sec. __. None of the funds appropriated or otherwise made
available by this Act or any other Act may be obligated or
expended in connection with United States participation in,
or support for, the activities of the United Nations Human
Rights Council.
Sec. __. (a) Of the amounts appropriated or otherwise made
available for the Secretary of State for each of fiscal years
2006 and 2007 to pay the United States share of assessed
contributions for the regular budget of the United Nations,
$4,300,000 shall be withheld from such payment, and shall be
transferred to the Department of the Army and available
instead for the purposes described in subsection (b).
(b) The purposes referred to in subsection (a) are the
establishment and operation of a state-of-the-art advanced
training skills facility to rehabilitate injured service
persons at Brooke Army Medical Center in San Antonio, Texas.
(c) Amounts withheld under subsection (a) shall remain
available until expended for the purposes described in
subsection (b).
______

SA 3708. Mr. BYRD submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
as follows:

At the appropriate place, insert the following:

TITLE ----

DISASTER MANAGEMENT AND MITIGATION

EMERGENCY MANAGEMENT PERFORMANCE GRANTS

For an additional amount for necessary expenses for
``Emergency Management Performance Grants'', as authorized by
the National Flood Insurance Act of 1968 and the Flood
Disaster Protection Act of 1973 (42 U.S.C. 4001 et seq.), the
Robert T. Stafford Disaster Relief and Emergency Assistance
Act (42 U.S.C. 5121 et seq.), the Earthquake Hazards
Reductions Act of 1977 (42 U.S.C. 7701 et seq.), and
Reorganization Plan No. 3 of 1978 (5 U.S.C. App.),
$130,000,000, to remain available until expended: Provided,
That the total costs in administering such grants shall not
exceed 3 percent of the amounts provided in this heading:
Provided further, That the amount provided under this heading
is designated as an emergency requirement pursuant to section
402 of H. Con. Res. 95 (109th Congress), the current
resolution on the budget for fiscal year 2006.

FLOOD MAP MODERNIZATION FUND

For an additional amount for ``Flood Map Modernization
Fund'' for necessary expenses pursuant to section 1360 of the
National Flood Insurance Act of 1968 (42 U.S.C. 4001 et
seq.), $50,000,000, and such additional sums as may be
provided by State and local governments or other political
subdivisions for cost-shared mapping activities under section
1360(f)(2) of such Act, to remain available until expended:
Provided, That the total costs in administering such funds
shall not exceed 3 percent of the amounts provided in this
heading: Provided further, That the amount provided under
this heading is designated as an emergency requirement
pursuant to section 402 of H. Con. Res. 95 (109th Congress),
the current resolution on the budget for fiscal year 2006.

NATIONAL PREDISASTER MITIGATION FUND

For an additional amount for ``National Predisaster
Mitigation Fund'' for the pre-disaster mitigation grant
program pursuant to title II of the Robert T. Stafford
Disaster Relief and Emergency Assistance Act (42 U.S.C. 5131
et seq.), $100,000,000, to remain available until expended:
Provided, That grants made for pre-disaster mitigation shall
be awarded on a competitive basis subject to the criteria in
section 203(g) of the Robert T. Stafford Disaster Relief and
Emergency Assistance Act (42 U.S.C. 5133(g)), and
notwithstanding section 203(f) of such Act, shall be made
without reference to State allocations, quotas, or other
formula-based allocation of funds: Provided further, That the
total costs in administering such funds shall not exceed 3
percent of the amounts provided in this heading: Provided
further, That the amount provided under this heading is
designated as an emergency requirement pursuant to section
402 of H. Con. Res. 95 (109th Congress), the current
resolution on the budget for fiscal year 2006.
Sec. --001. Notwithstanding any other provision of this
Act, the amount provided for ``Diplomatic and Consular
Programs'' shall be $1,172,600,000.
______

SA 3709. Mr. BYRD (for himself, Mr. Carper, and Mr. Lautenberg)
proposed an amendment to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; as follows:

On page 117, between lines 9 and 10, insert the following:

SENSE OF SENATE ON REQUESTS FOR FUNDS FOR MILITARY OPERATIONS IN IRAQ
AND AFGHANISTAN FOR FISCAL YEARS AFTER FISCAL YEAR 2007

Sec. 1312. (a) Findings.--The Senate makes the following
findings:
(1) Title IX of the Department of Defense Appropriations
Act, 2006 (division A of Public Law 109-148) appropriated
$50,000,000,000 for the cost of ongoing military operations
overseas in fiscal year 2006, although those funds were not
requested by the President.
(2) The President on February 16, 2006, submitted to
Congress a request for supplemental appropriations in the
amount of $67,600,000,000 for ongoing military operations in
fiscal year 2006, none of which supplemental appropriations
was included in the concurrent resolution on the budget for
fiscal year 2006, as agreed to in the Senate on April 28,
2005.
(3) The President on February 6, 2006, included a
$50,000,000,000 allowance for ongoing military operations in
fiscal year 2007, but did not formally request the funds or
provide any detail on how the allowance may be used.
(4) The concurrent resolution on the budget for fiscal year
2007, as agreed to in the Senate on March 16, 2007,
anticipates as much as $86,300,000,000 in emergency spending
in fiscal year 2007, indicating that the Senate expects to
take up another supplemental appropriations bill to fund
ongoing military operations during fiscal year 2007.
(b) Sense of Senate.--It is the sense of the Senate that--
(1) any request for funds for a fiscal year after fiscal
year 2007 for ongoing military operations in Afghanistan and
Iraq should be included in the annual budget of the President
for such fiscal year as submitted to Congress under section
1105(a) of title 31, United States Code;
(2) any request for funds for such a fiscal year for
ongoing military operations should provide an estimate of all
funds required in that fiscal year for such operations;
(3) any request for funds for ongoing military operations
should include a detailed justification of the anticipated
use of such funds for such operations; and
(4) any funds provided for ongoing military operations
overseas should be provided in appropriations Acts for such
fiscal year

[[Page S3741]]

through appropriations to specific accounts set forth in such
appropriations Acts.
______

SA 3710. Mr. LEVIN (for himself, Ms. Collins, and Mr. Reed) submitted
an amendment intended to be proposed by him to the bill H.R. 4939,
making emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 126, between lines 12 and 13, insert the following:

REPORTS ON POLICY AND POLITICAL DEVELOPMENTS IN IRAQ

Sec. 1406. (a) Reports Required.--The President shall, not
later than 30 days after the date of the enactment of this
Act and every 30 days thereafter until a national unity
government has been formed in Iraq and the Iraq Constitution
has been amended in a manner that makes it a unifying
document, submit to Congress a report on United States policy
and political developments in Iraq.
(b) Elements.--Each report under subsection (a) shall
include the following information:
(1) Whether the Administration has told the Iraqi
political, religious, and tribal leaders that agreement by
the Iraqis on a government of national unity, and subsequent
agreement to amendments to the Iraq Constitution to make it
more inclusive, within the deadlines that the Iraqis set for
themselves in their Constitution, is a condition for the
continued presence of United States military forces in Iraq.
(2) The progress that has been made in the formation of a
national unity government and the obstacles, if any, that
remain.
(3) The progress that has been made in the amendment of the
Iraq Constitution to make it more of a unifying document and
the obstacles, if any, that remain.
(4) An assessment of the effect that the formation of, or
failure to form, a unity government, and the amendment of, or
failure to amend, the Iraq Constitution, will have on the
``significant transition to full Iraqi sovereignty, with
Iraqi security forces taking the lead for the security of a
free and sovereign Iraq, thereby creating the conditions for
the phased redeployment of United States forces from Iraq''
as expressed in the United States Policy in Iraq Act (section
1227 of the National Defense Authorization Act for Fiscal
Year 2006 (Public Law 109-163; 119 Stat. 3465; 50 U.S.C. 1541
note)).
(5) The specific conditions on the ground, including the
capability and leadership of Iraqi security forces, that
would lead to the phased redeployment of United States ground
combat forces from Iraq.
______

SA 3711. Mr. NELSON of Florida submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

SATELLITE ALERT FACILITY, CAPE CANAVERAL AIR STATION, FLORIDA

Sec. 7032. The amount appropriated by the Military Quality
of Life and Veterans Affairs Appropriations Act, 2006 (Public
Law 109-114) for the Air Force for military construction that
remains available for the Satellite Processing Operations
Support Facility at Cape Canaveral Air Station, Florida,
shall be made available instead solely for the Satellite
Alert Facility at Cape Canaveral Air Station, Florida.
______

SA 3712. Mr. ALLARD submitted an amendment intended to be proposed to
amendment SA 3645 proposed by Mr. Salazar (for himself and Mr. Baucus)
to the bill H.R. 4939, making emergency supplemental appropriations for
the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

Strike all after line 2 and insert the following:

REPORT ON FIRE SEASON

Sec. ____. Not later than June 1, 2006, the Secretary of
the Interior shall submit to Congress a report that--
(1) assesses the projected severity of the pending fire
season;
(2) taking into consideration drought, hazardous fuel
buildup, and insect infestation, identifies the areas in
which the threat of the pending fire season is the most
serious;
(3) describes any actions recommended by the Secretary of
the Interior to mitigate the threat of the pending fire
season; and
(4) specifies the amount of funds that would be necessary
to carry out the actions recommended by the Secretary under
paragraph (3).
______

SA 3713. Mr. BURR proposed an amendment to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 238, line 23, strike ``Control and Prevention,
and'' and insert ``Control and Prevention, $5,000,000 shall
be for the Smithsonian Institution to carry out global and
domestic disease surveillance, and''.
______

SA 3714. Mrs. MURRAY (for Mr. Harkin) proposed an amendment to the
bill H.R. 4939, making emergency supplemental appropriations for the
fiscal year ending September 30, 2006, and for other purposes; as
follows:

On page 126, between lines 12 and 13, insert the following:

UNITED STATES INSTITUTE OF PEACE PROGRAMS IN IRAQ AND AFGHANISTAN

Sec. 1406. (a) The amount appropriated by this chapter for
other bilateral assistance under the heading ``Economic
Support Fund'' is hereby increased by $8,500,000.
(b) Of the amount appropriated by this chapter for other
bilateral assistance under the heading ``Economic Support
Fund'', as increased by subsection (a), $8,500,000 shall be
made available to the United States Institute of Peace for
programs in Iraq and Afghanistan.
(c) Of the funds made available by chapter 2 of title II of
division A of the Emergency Supplemental Appropriations Act
for Defense, the Global War on Terror, and Tsunami Relief,
2005'' (Public Law 109-13) for military assistance under the
heading ``Peacekeeping Operations'' and available for the
Coalition Solidarity Initiative, $8,500,000 is rescinded.
______

SA 3715. Mr. CONRAD (for himself, Mrs. Clinton, and Mr. Dodd)
proposed an amendment to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; as follows:

On page 253, between lines 19 and 20, insert the following:

TITLE VIII--REVENUE PROVISIONS

SEC. 8000. AMENDMENT OF CODE; TABLE OF CONTENTS.

(a) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this title an amendment or repeal is
expressed in terms of an amendment to, or repeal of, a
section or other provision, the reference shall be considered
to be made to a section or other provision of the Internal
Revenue Code of 1986.
(b) Table of Contents.--The table of contents for this
title is as follows:

TITLE VIII--REVENUE PROVISIONS

Sec. 8000. Amendment of Code; table of contents.

Subtitle A--Provisions Relating to Tax Shelters

Sec. 8101. Clarification of economic substance doctrine.
Sec. 8102. Penalty for understatements attributable to transactions
lacking economic substance, etc.
Sec. 8103. Denial of deduction for interest on underpayments
attributable to noneconomic substance transactions.
Sec. 8104. Modifications of effective dates of leasing provisions of
the American Jobs Creation Act of 2004.
Sec. 8105. Revaluation of LIFO inventories of large integrated oil
companies.
Sec. 8106. Modification of effective date of exception from suspension
rules for certain listed and reportable transactions.
Sec. 8107. Doubling of certain penalties, fines, and interest on
underpayments related to certain offshore financial
arrangements.
Sec. 8108. Penalty for aiding and abetting the understatement of tax
liability.

Subtitle B--Provisions to Close Corporate and Individual Loopholes

Sec. 8111. Tax treatment of inverted entities.
Sec. 8112. Grant of Treasury regulatory authority to address foreign
tax credit transactions involving inappropriate
separation of foreign taxes from related foreign income.
Sec. 8113. Treatment of contingent payment convertible debt
instruments.
Sec. 8114. Application of earnings stripping rules to partners which
are corporations.
Sec. 8115. Denial of deduction for certain fines, penalties, and other
amounts.
Sec. 8116. Disallowance of deduction for punitive damages.
Sec. 8117. Limitation of employer deduction for certain entertainment
expenses.
Sec. 8118. Imposition of mark-to-market tax on individuals who
expatriate.
Sec. 8119. Tax treatment of controlled foreign corporations established
in tax havens.
Sec. 8120. Modification of exclusion for citizens living abroad.
Sec. 8121. Limitation on annual amounts which may be deferred under
nonqualified deferred compensation arrangements.
Sec. 8122. Increase in age of minor children whose unearned income is
taxed as if parent's income.
Sec. 8123. Taxation of income of controlled foreign corporations
attributable to imported property.

Subtitle C--Oil and Gas Provisions

Sec. 8131. Extension of superfund taxes.

[[Page S3742]]

Sec. 8132. Modifications of foreign tax credit rules applicable to dual
capacity taxpayers.
Sec. 8133. Rules relating to foreign oil and gas income.
Sec. 8134. Modification of credit for producing fuel from a
nonconventional source.
Sec. 8135. Elimination of amortization of geological and geophysical
expenditures for major integrated oil companies.

Subtitle D--Tax Administration Provisions

Sec. 8141. Imposition of withholding on certain payments made by
government entities.
Sec. 8142. Increase in certain criminal penalties.
Sec. 8143. Repeal of suspension of interest and certain penalties where
Secretary fails to contact taxpayer.
Sec. 8144. Increase in penalty for bad checks and money orders.
Sec. 8145. Frivolous tax submissions.
Sec. 8146. Partial payments required with submission of offers-in-
compromise.
Sec. 8147. Waiver of user fee for installment agreements using
automated withdrawals.
Sec. 8148. Termination of installment agreements.

Subtitle E--Additional Provisions

Sec. 8151. Loan and redemption requirements on pooled financing
requirements.
Sec. 8152. Repeal of the scheduled phaseout of the limitations on
personal exemptions and itemized deductions.

Subtitle A--Provisions Relating to Tax Shelters

SEC. 8101. CLARIFICATION OF ECONOMIC SUBSTANCE DOCTRINE.

(a) In General.--Section 7701 is amended by redesignating
subsection (o) as subsection (p) and by inserting after
subsection (n) the following new subsection:
``(o) Clarification of Economic Substance Doctrine; Etc.--
``(1) General rules.--
``(A) In general.--In any case in which a court determines
that the economic substance doctrine is relevant for purposes
of this title to a transaction (or series of transactions),
such transaction (or series of transactions) shall have
economic substance only if the requirements of this paragraph
are met.
``(B) Definition of economic substance.--For purposes of
subparagraph (A)--
``(i) In general.--A transaction has economic substance
only if--

``(I) the transaction changes in a meaningful way (apart
from Federal tax effects) the taxpayer's economic position,
and
``(II) the taxpayer has a substantial nontax purpose for
entering into such transaction and the transaction is a
reasonable means of accomplishing such purpose.

In applying subclause (II), a purpose of achieving a
financial accounting benefit shall not be taken into account
in determining whether a transaction has a substantial nontax
purpose if the origin of such financial accounting benefit is
a reduction of income tax.
``(ii) Special rule where taxpayer relies on profit
potential.--A transaction shall not be treated as having
economic substance by reason of having a potential for profit
unless--

``(I) the present value of the reasonably expected pre-tax
profit from the transaction is substantial in relation to the
present value of the expected net tax benefits that would be
allowed if the transaction were respected, and
``(II) the reasonably expected pre-tax profit from the
transaction exceeds a risk-free rate of return.

``(C) Treatment of fees and foreign taxes.--Fees and other
transaction expenses and foreign taxes shall be taken into
account as expenses in determining pre-tax profit under
subparagraph (B)(ii).
``(2) Special rules for transactions with tax-indifferent
parties.--
``(A) Special rules for financing transactions.--The form
of a transaction which is in substance the borrowing of money
or the acquisition of financial capital directly or
indirectly from a tax-indifferent party shall not be
respected if the present value of the deductions to be
claimed with respect to the transaction is substantially in
excess of the present value of the anticipated economic
returns of the person lending the money or providing the
financial capital. A public offering shall be treated as a
borrowing, or an acquisition of financial capital, from a
tax-indifferent party if it is reasonably expected that at
least 50 percent of the offering will be placed with tax-
indifferent parties.
``(B) Artificial income shifting and basis adjustments.--
The form of a transaction with a tax-indifferent party shall
not be respected if--
``(i) it results in an allocation of income or gain to the
tax-indifferent party in excess of such party's economic
income or gain, or
``(ii) it results in a basis adjustment or shifting of
basis on account of overstating the income or gain of the
tax-indifferent party.
``(3) Definitions and special rules.--For purposes of this
subsection--
``(A) Economic substance doctrine.--The term `economic
substance doctrine' means the common law doctrine under which
tax benefits under subtitle A with respect to a transaction
are not allowable if the transaction does not have economic
substance or lacks a business purpose.
``(B) Tax-indifferent party.--The term `tax-indifferent
party' means any person or entity not subject to tax imposed
by subtitle A. A person shall be treated as a tax-indifferent
party with respect to a transaction if the items taken into
account with respect to the transaction have no substantial
impact on such person's liability under subtitle A.
``(C) Exception for personal transactions of individuals.--
In the case of an individual, this subsection shall apply
only to transactions entered into in connection with a trade
or business or an activity engaged in for the production of
income.
``(D) Treatment of lessors.--In applying paragraph
(1)(B)(ii) to the lessor of tangible property subject to a
lease--
``(i) the expected net tax benefits with respect to the
leased property shall not include the benefits of--

``(I) depreciation,
``(II) any tax credit, or
``(III) any other deduction as provided in guidance by the
Secretary, and

``(ii) subclause (II) of paragraph (1)(B)(ii) shall be
disregarded in determining whether any of such benefits are
allowable.
``(4) Other common law doctrines not affected.--Except as
specifically provided in this subsection, the provisions of
this subsection shall not be construed as altering or
supplanting any other rule of law, and the requirements of
this subsection shall be construed as being in addition to
any such other rule of law.
``(5) Regulations.--The Secretary shall prescribe such
regulations as may be necessary or appropriate to carry out
the purposes of this subsection. Such regulations may include
exemptions from the application of this subsection.''.
(b) Effective Date.--The amendments made by this section
shall apply to transactions entered into after the date of
the enactment of this Act.

SEC. 8102. PENALTY FOR UNDERSTATEMENTS ATTRIBUTABLE TO
TRANSACTIONS LACKING ECONOMIC SUBSTANCE, ETC.

(a) In General.--Subchapter A of chapter 68 is amended by
inserting after section 6662A the following new section:

``SEC. 6662B. PENALTY FOR UNDERSTATEMENTS ATTRIBUTABLE TO
TRANSACTIONS LACKING ECONOMIC SUBSTANCE, ETC.

``(a) Imposition of Penalty.--If a taxpayer has an
noneconomic substance transaction understatement for any
taxable year, there shall be added to the tax an amount equal
to 40 percent of the amount of such understatement.
``(b) Reduction of Penalty for Disclosed Transactions.--
Subsection (a) shall be applied by substituting `20 percent'
for `40 percent' with respect to the portion of any
noneconomic substance transaction understatement with respect
to which the relevant facts affecting the tax treatment of
the item are adequately disclosed in the return or a
statement attached to the return.
``(c) Noneconomic Substance Transaction Understatement.--
For purposes of this section--
``(1) In general.--The term `noneconomic substance
transaction understatement' means any amount which would be
an understatement under section 6662A(b)(1) if section 6662A
were applied by taking into account items attributable to
noneconomic substance transactions rather than items to which
section 6662A would apply without regard to this paragraph.
``(2) Noneconomic substance transaction.--The term
`noneconomic substance transaction' means any transaction
if--
``(A) there is a lack of economic substance (within the
meaning of section 7701(o)(1)) for the transaction giving
rise to the claimed benefit or the transaction was not
respected under section 7701(o)(2), or
``(B) the transaction fails to meet the requirements of any
similar rule of law.
``(d) Rules Applicable to Compromise of Penalty.--
``(1) In general.--If the 1st letter of proposed deficiency
which allows the taxpayer an opportunity for administrative
review in the Internal Revenue Service Office of Appeals has
been sent with respect to a penalty to which this section
applies, only the Commissioner of Internal Revenue may
compromise all or any portion of such penalty.
``(2) Applicable rules.--The rules of paragraphs (2) and
(3) of section 6707A(d) shall apply for purposes of paragraph
(1).
``(e) Coordination With Other Penalties.--Except as
otherwise provided in this part, the penalty imposed by this
section shall be in addition to any other penalty imposed by
this title.
``(f) Cross References.--
``(1) For coordination of penalty with understatements
under section 6662 and other special rules, see section
6662A(e)
``(2) For reporting of penalty imposed under this section
to the Securities and Exchange Commission, see section
6707A(e)''.
(b) Coordination With Other Understatements and
Penalties.--
(1) The second sentence of section 6662(d)(2)(A) is amended
by inserting ``and without regard to items with respect to
which a penalty is imposed by section 6662B'' before the
period at the end.
(2) Subsection (e) of section 6662A is amended--

[[Page S3743]]

(A) in paragraph (1), by inserting ``and noneconomic
substance transaction understatements'' after ``reportable
transaction understatements'' both places it appears,
(B) in paragraph (2)(A), by inserting ``and a noneconomic
substance transaction understatement'' after ``reportable
transaction understatement'',
(C) in paragraph (2)(B), by inserting ``6662B or'' before
``6663'',
(D) in paragraph (2)(C)(i), by inserting ``or section
6662B'' before the period at the end,
(E) in paragraph (2)(C)(ii), by inserting ``and section
6662B'' after ``This section'',
(F) in paragraph (3), by inserting ``or noneconomic
substance transaction understatement'' after ``reportable
transaction understatement'', and
(G) by adding at the end the following new paragraph:
``(4) Noneconomic substance transaction understatement.--
For purposes of this subsection, the term `noneconomic
substance transaction understatement' has the meaning given
such term by section 6662B(c).''.
(3) Subsection (e) of section 6707A is amended--
(A) by striking ``or'' at the end of subparagraph (B), and
(B) by striking subparagraph (C) and inserting the
following new subparagraphs:
``(C) is required to pay a penalty under section 6662B with
respect to any noneconomic substance transaction, or
``(D) is required to pay a penalty under section 6662(h)
with respect to any transaction and would (but for section
6662A(e)(2)(C)) have been subject to penalty under section
6662A at a rate prescribed under section 6662A(c) or under
section 6662B,''.
(c) Clerical Amendment.--The table of sections for part II
of subchapter A of chapter 68 is amended by inserting after
the item relating to section 6662A the following new item:

``Sec. 6662B. Penalty for understatements attributable to transactions
lacking economic substance, etc''.

(d) Effective Date.--The amendments made by this section
shall apply to transactions entered into after the date of
the enactment of this Act.

SEC. 8103. DENIAL OF DEDUCTION FOR INTEREST ON UNDERPAYMENTS
ATTRIBUTABLE TO NONECONOMIC SUBSTANCE
TRANSACTIONS.

(a) In General.--Section 163(m) (relating to interest on
unpaid taxes attributable to nondisclosed reportable
transactions) is amended--
(1) by striking ``attributable'' and all that follows and
inserting the following: ``attributable to--
``(1) the portion of any reportable transaction
understatement (as defined in section 6662A(b)) with respect
to which the requirement of section 6664(d)(2)(A) is not met,
or
``(2) any noneconomic substance transaction understatement
(as defined in section 6662B(c)).'', and
(2) by inserting ``and Noneconomic Substance Transactions''
in the heading thereof after ``Transactions''.
(b) Effective Date.--The amendments made by this section
shall apply to transactions after the date of the enactment
of this Act in taxable years ending after such date.

SEC. 8104. MODIFICATIONS OF EFFECTIVE DATES OF LEASING
PROVISIONS OF THE AMERICAN JOBS CREATION ACT OF
2004.

(a) In General.--Section 849(b) of the American Jobs
Creation Act of 2004 is amended by striking paragraphs (1)
and (2), by redesignating paragraphs (3) and (4) as
paragraphs (1) and (2), respectively, and by adding at the
end the following new paragraph:
``(3) Leases to foreign entities.--In the case of tax-
exempt use property leased to a tax-exempt entity which is a
foreign person or entity, the amendments made by this part
shall apply to taxable years beginning after December 31,
2004, with respect to leases entered into on or before March
12, 2004.''.
(b) Effective Date.--The amendments made by this section
shall take effect as if included in the enactment of the
American Jobs Creation Act of 2004.

SEC. 8105. REVALUATION OF LIFO INVENTORIES OF LARGE
INTEGRATED OIL COMPANIES.

(a) General Rule.--Notwithstanding any other provision of
law, if a taxpayer is an applicable integrated oil company
for its last taxable year ending in calendar year 2005, the
taxpayer shall--
(1) increase, effective as of the close of such taxable
year, the value of each historic LIFO layer of inventories of
crude oil, natural gas, or any other petroleum product
(within the meaning of section 4611) by the layer adjustment
amount, and
(2) decrease its cost of goods sold for such taxable year
by the aggregate amount of the increases under paragraph (1).

If the aggregate amount of the increases under paragraph (1)
exceed the taxpayer's cost of goods sold for such taxable
year, the taxpayer's gross income for such taxable year shall
be increased by the amount of such excess.
(b) Layer Adjustment Amount.--For purposes of this
section--
(1) In general.--The term ``layer adjustment amount''
means, with respect to any historic LIFO layer, the product
of--
(A) $18.75, and
(B) the number of barrels of crude oil (or in the case of
natural gas or other petroleum products, the number of
barrel-of-oil equivalents) represented by the layer.
(2) Barrel-of-oil equivalent.--The term ``barrel-of-oil
equivalent'' has the meaning given such term by section
29(d)(5) (as in effect before its redesignation by the Energy
Tax Incentives Act of 2005).
(c) Application of Requirement.--
(1) No change in method of accounting.--Any adjustment
required by this section shall not be treated as a change in
method of accounting.
(2) Underpayments of estimated tax.--No addition to the tax
shall be made under section 6655 of the Internal Revenue Code
of 1986 (relating to failure by corporation to pay estimated
tax) with respect to any underpayment of an installment
required to be paid with respect to the taxable year
described in subsection (a) to the extent such underpayment
was created or increased by this section.
(d) Applicable Integrated Oil Company.--For purposes of
this section, the term ``applicable integrated oil company''
means an integrated oil company (as defined in section
291(b)(4) of the Internal Revenue Code of 1986) which--
(1) had gross receipts in excess of $1,000,000,000 for its
last taxable year ending during calendar year 2005, and
(2) uses the last-in, first-out (LIFO) method of accounting
with respect to its crude oil inventories for such taxable
year.

For purposes of paragraph (1), all persons treated as a
single employer under subsections (a) and (b) of section 52
of the Internal Revenue Code of 1986 shall be treated as 1
person and, in the case of a short taxable year, the rule
under section 448(c)(3)(B) shall apply.

SEC. 8106. MODIFICATION OF EFFECTIVE DATE OF EXCEPTION FROM
SUSPENSION RULES FOR CERTAIN LISTED AND
REPORTABLE TRANSACTIONS.

(a) In General.--Paragraph (2) of section 903(d) of the
American Jobs Creation Act of 2004 is amended to read as
follows:
``(2) Exception for reportable or listed transactions.--
``(A) In general.--The amendments made by subsection (c)
shall apply with respect to interest accruing after October
3, 2004.
``(B) Special rule for certain listed and reportable
transactions.--
``(i) In general.--Except as provided in clause (ii), the
amendments made by subsection (c) shall also apply with
respect to interest accruing on or before October 3, 2004.
``(ii) Participants in settlement initiatives.--Clause (i)
shall not apply to any transaction if, as of January 23,
2006--

``(I) the taxpayer is participating in a settlement
initiative described in Internal Revenue Service Announcement
2005-80 with respect to such transaction, or
``(II) the taxpayer has entered into a settlement agreement
pursuant to such an initiative.

``(iii) Termination of exception.--Clause (ii)(I) shall not
apply to any taxpayer if, after January 23, 2006, the
taxpayer withdraws from, or terminates, participation in the
initiative or the Secretary of the Treasury or the
Secretary's delegate determines that a settlement agreement
will not be reached pursuant to the initiative within a
reasonable period of time.''.
(b) Effective Date.--The amendment made by this section
shall take effect as if included in the provisions of the
American Jobs Creation Act of 2004 to which it relates.

SEC. 8107. DOUBLING OF CERTAIN PENALTIES, FINES, AND INTEREST
ON UNDERPAYMENTS RELATED TO CERTAIN OFFSHORE
FINANCIAL ARRANGEMENTS.

(a) Determination of Penalty.--
(1) In general.--Notwithstanding any other provision of
law, in the case of an applicable taxpayer--
(A) the determination as to whether any interest or
applicable penalty is to be imposed with respect to any
arrangement described in paragraph (2), or to any
underpayment of Federal income tax attributable to items
arising in connection with any such arrangement, shall be
made without regard to the rules of subsections (b), (c), and
(d) of section 6664 of the Internal Revenue Code of 1986, and
(B) if any such interest or applicable penalty is imposed,
the amount of such interest or penalty shall be equal to
twice that determined without regard to this section.
(2) Applicable taxpayer.--For purposes of this subsection--
(A) In general.--The term ``applicable taxpayer'' means a
taxpayer which--
(i) has underreported its United States income tax
liability with respect to any item which directly or
indirectly involves--

(I) any financial arrangement which in any manner relies on
the use of offshore payment mechanisms (including credit,
debit, or charge cards) issued by banks or other entities in
foreign jurisdictions, or
(II) any offshore financial arrangement (including any
arrangement with foreign banks, financial institutions,
corporations, partnerships, trusts, or other entities), and

(ii) has neither signed a closing agreement pursuant to the
Voluntary Offshore Compliance Initiative established by the
Department of the Treasury under Revenue Procedure 2003-11
nor voluntarily disclosed its participation in such
arrangement by notifying the Internal Revenue Service of such
arrangement prior to the issue being raised by

[[Page S3744]]

the Internal Revenue Service during an examination.
(B) Authority to waive.--The Secretary of the Treasury or
the Secretary's delegate may waive the application of
paragraph (1) to any taxpayer if the Secretary or the
Secretary's delegate determines that the use of such offshore
payment mechanisms is incidental to the transaction and, in
addition, in the case of a trade or business, such use is
conducted in the ordinary course of the type of trade or
business of the taxpayer.
(C) Issues raised.--For purposes of subparagraph (A)(ii),
an item shall be treated as an issue raised during an
examination if the individual examining the return--
(i) communicates to the taxpayer knowledge about the
specific item, or
(ii) has made a request to the taxpayer for information and
the taxpayer could not make a complete response to that
request without giving the examiner knowledge of the specific
item.
(b) Definitions and Rules.--For purposes of this section--
(1) Applicable penalty.--The term ``applicable penalty''
means any penalty, addition to tax, or fine imposed under
chapter 68 of the Internal Revenue Code of 1986.
(2) Fees and expenses.--The Secretary of the Treasury may
retain and use an amount not in excess of 25 percent of all
additional interest, penalties, additions to tax, and fines
collected under this section to be used for enforcement and
collection activities of the Internal Revenue Service. The
Secretary shall keep adequate records regarding amounts so
retained and used. The amount credited as paid by any
taxpayer shall be determined without regard to this
paragraph.
(c) Report by Secretary.--The Secretary shall each year
conduct a study and report to Congress on the implementation
of this section during the preceding year, including
statistics on the number of taxpayers affected by such
implementation and the amount of interest and applicable
penalties asserted, waived, and assessed during such
preceding year.
(d) Effective Date.--The provisions of this section shall
apply to interest, penalties, additions to tax, and fines
with respect to any taxable year if, as of the date of the
enactment of this Act, the assessment of any tax, penalty, or
interest with respect to such taxable year is not prevented
by the operation of any law or rule of law.

SEC. 8108. PENALTY FOR AIDING AND ABETTING THE UNDERSTATEMENT
OF TAX LIABILITY.

(a) In General.--Section 6701(a) (relating to imposition of
penalty) is amended--
(1) by inserting ``the tax liability or'' after ``respect
to,'' in paragraph (1),
(2) by inserting ``aid, assistance, procurement, or advice
with respect to such'' before ``portion'' both places it
appears in paragraphs (2) and (3), and
(3) by inserting ``instance of aid, assistance,
procurement, or advice or each such'' before ``document'' in
the matter following paragraph (3).
(b) Amount of Penalty.--Subsection (b) of section 6701
(relating to penalties for aiding and abetting understatement
of tax liability) is amended to read as follows:
``(b) Amount of Penalty; Calculation of Penalty; Liability
for Penalty.--
``(1) Amount of penalty.--The amount of the penalty imposed
by subsection (a) shall not exceed 100 percent of the gross
income derived (or to be derived) from such aid, assistance,
procurement, or advice provided by the person or persons
subject to such penalty.
``(2) Calculation of penalty.--The penalty amount
determined under paragraph (1) shall be calculated with
respect to each instance of aid, assistance, procurement, or
advice described in subsection (a), each instance in which
income was derived by the person or persons subject to such
penalty, and each person who made such an understatement of
the liability for tax.
``(3) Liability for penalty.--If more than 1 person is
liable under subsection (a) with respect to providing such
aid, assistance, procurement, or advice, all such persons
shall be jointly and severally liable for the penalty under
such subsection.''.
(c) Penalty Not Deductible.--Section 6701 is amended by
adding at the end the following new subsection:
``(g) Penalty Not Deductible.--The payment of any penalty
imposed under this section or the payment of any amount to
settle or avoid the imposition of such penalty shall not be
deductible by the person who is subject to such penalty or
who makes such payment.''.
(d) Effective Date.--The amendments made by this section
shall apply to activities after the date of the enactment of
this Act.

Subtitle B--Provisions to Close Corporate and Individual Loopholes

SEC. 8111. TAX TREATMENT OF INVERTED ENTITIES.

(a) In General.--Section 7874 is amended--
(1) by striking ``March 4, 2003'' in subsection
(a)(2)(B)(i) and in the matter following subsection
(a)(2)(B)(iii) and inserting ``March 20, 2002'',
(2) by striking ``at least 60 percent'' in subsection
(a)(2)(B)(ii) and inserting ``more than 50 percent'',
(3) by striking ``80 percent'' in subsection (b) and
inserting ``at least 80 percent'',
(4) by striking ``60 percent'' in subsection (b) and
inserting ``more than 50 percent'',
(5) by adding at the end of subsection (a)(2) the following
new sentence: ``Except as provided in regulations, an
acquisition of properties of a domestic corporation shall not
be treated as described in subparagraph (B) if none of the
corporation's stock was readily tradeable on an established
securities market at any time during the 4-year period ending
on the date of the acquisition.'', and
(6) by redesignating subsection (g) as subsection (h) and
by inserting after subsection (f) the following new
subsection:
``(g) Special Rules Applicable to Expatriated Entities.--
``(1) Increases in accuracy-related penalties.--In the case
of any underpayment of tax of an expatriated entity--
``(A) section 6662(a) shall be applied with respect to such
underpayment by substituting `30 percent' for `20 percent',
and
``(B) if such underpayment is attributable to one or more
gross valuation understatements, the increase in the rate of
penalty under section 6662(h) shall be to 50 percent rather
than 40 percent.
``(2) Modifications of limitation on interest deduction.--
In the case of an expatriated entity, section 163(j) shall be
applied--
``(A) without regard to paragraph (2)(A)(ii) thereof, and
``(B) by substituting `25 percent' for `50 percent' each
place it appears in paragraph (2)(B) thereof.''.
(b) Effective Date.--The amendments made by this section
shall apply to taxable years ending after March 20, 2002.

SEC. 8112. GRANT OF TREASURY REGULATORY AUTHORITY TO ADDRESS
FOREIGN TAX CREDIT TRANSACTIONS INVOLVING
INAPPROPRIATE SEPARATION OF FOREIGN TAXES FROM
RELATED FOREIGN INCOME.

(a) In General.--Section 901 (relating to taxes of foreign
countries and of possessions of United States) is amended by
redesignating subsection (m) as subsection (n) and by
inserting after subsection (l) the following new subsection:
``(m) Regulations.--The Secretary may prescribe regulations
disallowing a credit under subsection (a) for all or a
portion of any foreign tax, or allocating a foreign tax among
2 or more persons, in cases where the foreign tax is imposed
on any person in respect of income of another person or in
other cases involving the inappropriate separation of the
foreign tax from the related foreign income.''.
(b) Effective Date.--The amendments made by this section
shall apply to transactions entered into after the date of
the enactment of this Act.

SEC. 8113. TREATMENT OF CONTINGENT PAYMENT CONVERTIBLE DEBT
INSTRUMENTS.

(a) In General.--Section 1275(d) (relating to regulation
authority) is amended--
(1) by striking ``The Secretary'' and inserting the
following:
``(1) In general.--The Secretary'', and
(2) by adding at the end the following new paragraph:
``(2) Treatment of contingent payment convertible debt.--
``(A) In general.--In the case of a debt instrument which--
``(i) is convertible into stock of the issuing corporation,
into stock or debt of a related party (within the meaning of
section 267(b) or 707(b)(1)), or into cash or other property
in an amount equal to the approximate value of such stock or
debt, and
``(ii) provides for contingent payments,

any regulations which require original issue discount to be
determined by reference to the comparable yield of a
noncontingent fixed-rate debt instrument shall be applied as
if the regulations require that such comparable yield be
determined by reference to a noncontingent fixed-rate debt
instrument which is convertible into stock.
``(B) Special rule.--For purposes of subparagraph (A), the
comparable yield shall be determined without taking into
account the yield resulting from the conversion of a debt
instrument into stock.''.
(b) Cross Reference.--Section 163(e)(6) (relating to cross
references) is amended by adding at the end the following:
``For the treatment of contingent payment convertible debt,
see section 1275(d)(2).''.
(c) Effective Date.--The amendments made by this section
shall apply to debt instruments issued on or after the date
of the enactment of this Act.

SEC. 8114. APPLICATION OF EARNINGS STRIPPING RULES TO
PARTNERS WHICH ARE CORPORATIONS.

(a) In General.--Section 163(j) (relating to limitation on
deduction for interest on certain indebtedness) is amended by
redesignating paragraph (8) as paragraph (9) and by inserting
after paragraph (7) the following new paragraph:
``(8) Treatment of corporate partners.--Except to the
extent provided by regulations, in applying this subsection
to a corporation which owns (directly or indirectly) an
interest in a partnership--
``(A) such corporation's distributive share of interest
income paid or accrued to such partnership shall be treated
as interest income paid or accrued to such corporation,
``(B) such corporation's distributive share of interest
paid or accrued by such partnership shall be treated as
interest paid or accrued by such corporation, and
``(C) such corporation's share of the liabilities of such
partnership shall be treated as liabilities of such
corporation.''.
(b) Additional Regulatory Authority.--Section 163(j)(9)
(relating to regulations), as redesignated by subsection (a),
is amended by striking ``and'' at the end of subparagraph
(B), by striking the period at the end of subparagraph (C)
and inserting ``, and'', and by

[[Page S3745]]

adding at the end the following new subparagraph:
``(D) regulations providing for the reallocation of shares
of partnership indebtedness, or distributive shares of the
partnership's interest income or interest expense, as may be
appropriate to carry out the purposes of this subsection.''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning on or after the date
of the enactment of this Act.

SEC. 8115. DENIAL OF DEDUCTION FOR CERTAIN FINES, PENALTIES,
AND OTHER AMOUNTS.

(a) In General.--Subsection (f) of section 162 (relating to
trade or business expenses) is amended to read as follows:
``(f) Fines, Penalties, and Other Amounts.--
``(1) In general.--Except as provided in paragraph (2), no
deduction otherwise allowable shall be allowed under this
chapter for any amount paid or incurred (whether by suit,
agreement, or otherwise) to, or at the direction of, a
government or entity described in paragraph (4) in relation
to the violation of any law or the investigation or inquiry
by such government or entity into the potential violation of
any law.
``(2) Exception for amounts constituting restitution or
paid to come into compliance with law.--Paragraph (1) shall
not apply to any amount which--
``(A) the taxpayer establishes--
``(i) constitutes restitution (including remediation of
property) for damage or harm caused by or which may be caused
by the violation of any law or the potential violation of any
law, or
``(ii) is paid to come into compliance with any law which
was violated or involved in the investigation or inquiry, and
``(B) is identified as restitution or as an amount paid to
come into compliance with the law, as the case may be, in the
court order or settlement agreement.

Identification pursuant to subparagraph (B) alone shall not
satisfy the requirement under subparagraph (A). This
paragraph shall not apply to any amount paid or incurred as
reimbursement to the government or entity for the costs of
any investigation or litigation.
``(3) Exception for amounts paid or incurred as the result
of certain court orders.--Paragraph (1) shall not apply to
any amount paid or incurred by order of a court in a suit in
which no government or entity described in paragraph (4) is a
party.
``(4) Certain nongovernmental regulatory entities.--An
entity is described in this paragraph if it is--
``(A) a nongovernmental entity which exercises self-
regulatory powers (including imposing sanctions) in
connection with a qualified board or exchange (as defined in
section 1256(g)(7)), or
``(B) to the extent provided in regulations, a
nongovernmental entity which exercises self-regulatory powers
(including imposing sanctions) as part of performing an
essential governmental function.
``(5) Exception for taxes due.--Paragraph (1) shall not
apply to any amount paid or incurred as taxes due.''.
(b) Reporting of Deductible Amounts.--
(1) In general.--Subpart B of part III of subchapter A of
chapter 61 is amended by inserting after section 6050T the
following new section:

``SEC. 6050U. INFORMATION WITH RESPECT TO CERTAIN FINES,
PENALTIES, AND OTHER AMOUNTS.

``(a) Requirement of Reporting.--
``(1) In general.--The appropriate official of any
government or entity which is described in section 162(f)(4)
which is involved in a suit or agreement described in
paragraph (2) shall make a return in such form as determined
by the Secretary setting forth--
``(A) the amount required to be paid as a result of the
suit or agreement to which paragraph (1) of section 162(f)
applies,
``(B) any amount required to be paid as a result of the
suit or agreement which constitutes restitution or
remediation of property, and
``(C) any amount required to be paid as a result of the
suit or agreement for the purpose of coming into compliance
with any law which was violated or involved in the
investigation or inquiry.
``(2) Suit or agreement described.--
``(A) In general.--A suit or agreement is described in this
paragraph if--
``(i) it is--

``(I) a suit with respect to a violation of any law over
which the government or entity has authority and with respect
to which there has been a court order, or
``(II) an agreement which is entered into with respect to a
violation of any law over which the government or entity has
authority, or with respect to an investigation or inquiry by
the government or entity into the potential violation of any
law over which such government or entity has authority, and

``(ii) the aggregate amount involved in all court orders
and agreements with respect to the violation, investigation,
or inquiry is $600 or more.
``(B) Adjustment of reporting threshold.--The Secretary may
adjust the $600 amount in subparagraph (A)(ii) as necessary
in order to ensure the efficient administration of the
internal revenue laws.
``(3) Time of filing.--The return required under this
subsection shall be filed not later than--
``(A) 30 days after the date on which a court order is
issued with respect to the suit or the date the agreement is
entered into, as the case may be, or
``(B) the date specified Secretary.
``(b) Statements to Be Furnished to Individuals Involved in
the Settlement.--Every person required to make a return under
subsection (a) shall furnish to each person who is a party to
the suit or agreement a written statement showing--
``(1) the name of the government or entity, and
``(2) the information supplied to the Secretary under
subsection (a)(1).

The written statement required under the preceding sentence
shall be furnished to the person at the same time the
government or entity provides the Secretary with the
information required under subsection (a).
``(c) Appropriate Official Defined.--For purposes of this
section, the term `appropriate official' means the officer or
employee having control of the suit, investigation, or
inquiry or the person appropriately designated for purposes
of this section.''.
(2) Conforming amendment.--The table of sections for
subpart B of part III of subchapter A of chapter 61 is
amended by inserting after the item relating to section 6050T
the following new item:

``Sec. 6050U. Information with respect to certain fines, penalties, and
other amounts.''.

(c) Effective Date.--The amendments made by this section
shall apply to amounts paid or incurred on or after the date
of the enactment of this Act, except that such amendments
shall not apply to amounts paid or incurred under any binding
order or agreement entered into before such date. Such
exception shall not apply to an order or agreement requiring
court approval unless the approval was obtained before such
date.

SEC. 8116. DISALLOWANCE OF DEDUCTION FOR PUNITIVE DAMAGES.

(a) Disallowance of Deduction.--
(1) In general.--Section 162(g) (relating to treble damage
payments under the antitrust laws) is amended--
(A) by redesignating paragraphs (1) and (2) as
subparagraphs (A) and (B), respectively,
(B) by striking ``If'' and inserting:
``(1) Treble damages.--If'', and
(C) by adding at the end the following new paragraph:
``(2) Punitive damages.--No deduction shall be allowed
under this chapter for any amount paid or incurred for
punitive damages in connection with any judgment in, or
settlement of, any action. This paragraph shall not apply to
punitive damages described in section 104(c).''.
(2) Conforming amendment.--The heading for section 162(g)
is amended by inserting ``or Punitive Damages'' after
``Laws''.
(b) Inclusion in Income of Punitive Damages Paid by Insurer
or Otherwise.--
(1) In general.--Part II of subchapter B of chapter 1
(relating to items specifically included in gross income) is
amended by adding at the end the following new section:

``SEC. 91. PUNITIVE DAMAGES COMPENSATED BY INSURANCE OR
OTHERWISE.

``Gross income shall include any amount paid to or on
behalf of a taxpayer as insurance or otherwise by reason of
the taxpayer's liability (or agreement) to pay punitive
damages.''.
(2) Reporting requirements.--Section 6041 (relating to
information at source) is amended by adding at the end the
following new subsection:
``(f) Section to Apply to Punitive Damages Compensation.--
This section shall apply to payments by a person to or on
behalf of another person as insurance or otherwise by reason
of the other person's liability (or agreement) to pay
punitive damages.''.
(3) Conforming amendment.--The table of sections for part
II of subchapter B of chapter 1 is amended by adding at the
end the following new item:

``Sec. 91. Punitive damages compensated by insurance or otherwise.''.
(c) Effective Date.--The amendments made by this section
shall apply to damages paid or incurred on or after the date
of the enactment of this Act.

SEC. 8117. LIMITATION OF EMPLOYER DEDUCTION FOR CERTAIN
ENTERTAINMENT EXPENSES.

(a) In General.--Paragraph (2) of section 274(e) (relating
to expenses treated as compensation) is amended to read as
follows:
``(2) Expenses treated as compensation.--Expenses for
goods, services, and facilities, to the extent that the
expenses do not exceed the amount of the expenses which are
treated by the taxpayer, with respect to the recipient of the
entertainment, amusement, or recreation, as compensation to
an employee on the taxpayer's return of tax under this
chapter and as wages to such employee for purposes of chapter
24 (relating to withholding of income tax at source on
wages).''.
(b) Persons Not Employees.--Paragraph (9) of section 274(e)
is amended by striking ``to the extent that the expenses are
includible in the gross income'' and inserting ``to the
extent that the expenses do not exceed the amount of the
expenses which are includible in the gross income''.
(c) Effective Date.--The amendments made by this section
shall apply to expenses incurred after the date of the
enactment of this Act.

SEC. 8118. IMPOSITION OF MARK-TO-MARKET TAX ON INDIVIDUALS
WHO EXPATRIATE.

(a) In General.--Subpart A of part II of subchapter N of
chapter 1 is amended by inserting after section 877 the
following new section:

[[Page S3746]]

``SEC. 877A. TAX RESPONSIBILITIES OF EXPATRIATION.

``(a) General Rules.--For purposes of this subtitle--
``(1) Mark to market.--Except as provided in subsections
(d) and (f), all property of a covered expatriate to whom
this section applies shall be treated as sold on the day
before the expatriation date for its fair market value.
``(2) Recognition of gain or loss.--In the case of any sale
under paragraph (1)--
``(A) notwithstanding any other provision of this title,
any gain arising from such sale shall be taken into account
for the taxable year of the sale, and
``(B) any loss arising from such sale shall be taken into
account for the taxable year of the sale to the extent
otherwise provided by this title, except that section 1091
shall not apply to any such loss.

Proper adjustment shall be made in the amount of any gain or
loss subsequently realized for gain or loss taken into
account under the preceding sentence.
``(3) Exclusion for certain gain.--
``(A) In general.--The amount which, but for this
paragraph, would be includible in the gross income of any
individual by reason of this section shall be reduced (but
not below zero) by $600,000. For purposes of this paragraph,
allocable expatriation gain taken into account under
subsection (f)(2) shall be treated in the same manner as an
amount required to be includible in gross income.
``(B) Cost-of-living adjustment.--
``(i) In general.--In the case of an expatriation date
occurring in any calendar year after 2005, the $600,000
amount under subparagraph (A) shall be increased by an amount
equal to--

``(I) such dollar amount, multiplied by
``(II) the cost-of-living adjustment determined under
section 1(f)(3) for such calendar year, determined by
substituting `calendar year 2004' for `calendar year 1992' in
subparagraph (B) thereof.

``(ii) Rounding rules.--If any amount after adjustment
under clause (i) is not a multiple of $1,000, such amount
shall be rounded to the next lower multiple of $1,000.
``(4) Election to continue to be taxed as united states
citizen.--
``(A) In general.--If a covered expatriate elects the
application of this paragraph--
``(i) this section (other than this paragraph and
subsection (i)) shall not apply to the expatriate, but
``(ii) in the case of property to which this section would
apply but for such election, the expatriate shall be subject
to tax under this title in the same manner as if the
individual were a United States citizen.
``(B) Requirements.--Subparagraph (A) shall not apply to an
individual unless the individual--
``(i) provides security for payment of tax in such form and
manner, and in such amount, as the Secretary may require,
``(ii) consents to the waiver of any right of the
individual under any treaty of the United States which would
preclude assessment or collection of any tax which may be
imposed by reason of this paragraph, and
``(iii) complies with such other requirements as the
Secretary may prescribe.
``(C) Election.--An election under subparagraph (A) shall
apply to all property to which this section would apply but
for the election and, once made, shall be irrevocable. Such
election shall also apply to property the basis of which is
determined in whole or in part by reference to the property
with respect to which the election was made.
``(b) Election to Defer Tax.--
``(1) In general.--If the taxpayer elects the application
of this subsection with respect to any property treated as
sold by reason of subsection (a), the payment of the
additional tax attributable to such property shall be
postponed until the due date of the return for the taxable
year in which such property is disposed of (or, in the case
of property disposed of in a transaction in which gain is not
recognized in whole or in part, until such other date as the
Secretary may prescribe).
``(2) Determination of tax with respect to property.--For
purposes of paragraph (1), the additional tax attributable to
any property is an amount which bears the same ratio to the
additional tax imposed by this chapter for the taxable year
solely by reason of subsection (a) as the gain taken into
account under subsection (a) with respect to such property
bears to the total gain taken into account under subsection
(a) with respect to all property to which subsection (a)
applies.
``(3) Termination of postponement.--No tax may be postponed
under this subsection later than the due date for the return
of tax imposed by this chapter for the taxable year which
includes the date of death of the expatriate (or, if earlier,
the time that the security provided with respect to the
property fails to meet the requirements of paragraph (4),
unless the taxpayer corrects such failure within the time
specified by the Secretary).
``(4) Security.--
``(A) In general.--No election may be made under paragraph
(1) with respect to any property unless adequate security is
provided to the Secretary with respect to such property.
``(B) Adequate security.--For purposes of subparagraph (A),
security with respect to any property shall be treated as
adequate security if--
``(i) it is a bond in an amount equal to the deferred tax
amount under paragraph (2) for the property, or
``(ii) the taxpayer otherwise establishes to the
satisfaction of the Secretary that the security is adequate.
``(5) Waiver of certain rights.--No election may be made
under paragraph (1) unless the taxpayer consents to the
waiver of any right under any treaty of the United States
which would preclude assessment or collection of any tax
imposed by reason of this section.
``(6) Elections.--An election under paragraph (1) shall
only apply to property described in the election and, once
made, is irrevocable. An election may be made under paragraph
(1) with respect to an interest in a trust with respect to
which gain is required to be recognized under subsection
(f)(1).
``(7) Interest.--For purposes of section 6601--
``(A) the last date for the payment of tax shall be
determined without regard to the election under this
subsection, and
``(B) section 6621(a)(2) shall be applied by substituting
`5 percentage points' for `3 percentage points' in
subparagraph (B) thereof.
``(c) Covered Expatriate.--For purposes of this section--
``(1) In general.--Except as provided in paragraph (2), the
term `covered expatriate' means an expatriate.
``(2) Exceptions.--An individual shall not be treated as a
covered expatriate if--
``(A) the individual--
``(i) became at birth a citizen of the United States and a
citizen of another country and, as of the expatriation date,
continues to be a citizen of, and is taxed as a resident of,
such other country, and
``(ii) has not been a resident of the United States (as
defined in section 7701(b)(1)(A)(ii)) during the 5 taxable
years ending with the taxable year during which the
expatriation date occurs, or
``(B)(i) the individual's relinquishment of United States
citizenship occurs before such individual attains age 18\1/
2\, and
``(ii) the individual has been a resident of the United
States (as so defined) for not more than 5 taxable years
before the date of relinquishment.
``(d) Exempt Property; Special Rules for Pension Plans.--
``(1) Exempt property.--This section shall not apply to the
following:
``(A) United states real property interests.--Any United
States real property interest (as defined in section
897(c)(1)), other than stock of a United States real property
holding corporation which does not, on the day before the
expatriation date, meet the requirements of section
897(c)(2).
``(B) Specified property.--Any property or interest in
property not described in subparagraph (A) which the
Secretary specifies in regulations.
``(2) Special rules for certain retirement plans.--
``(A) In general.--If a covered expatriate holds on the day
before the expatriation date any interest in a retirement
plan to which this paragraph applies--
``(i) such interest shall not be treated as sold for
purposes of subsection (a)(1), but
``(ii) an amount equal to the present value of the
expatriate's nonforfeitable accrued benefit shall be treated
as having been received by such individual on such date as a
distribution under the plan.
``(B) Treatment of subsequent distributions.--In the case
of any distribution on or after the expatriation date to or
on behalf of the covered expatriate from a plan from which
the expatriate was treated as receiving a distribution under
subparagraph (A), the amount otherwise includible in gross
income by reason of the subsequent distribution shall be
reduced by the excess of the amount includible in gross
income under subparagraph (A) over any portion of such amount
to which this subparagraph previously applied.
``(C) Treatment of subsequent distributions by plan.--For
purposes of this title, a retirement plan to which this
paragraph applies, and any person acting on the plan's
behalf, shall treat any subsequent distribution described in
subparagraph (B) in the same manner as such distribution
would be treated without regard to this paragraph.
``(D) Applicable plans.--This paragraph shall apply to--
``(i) any qualified retirement plan (as defined in section
4974(c)),
``(ii) an eligible deferred compensation plan (as defined
in section 457(b)) of an eligible employer described in
section 457(e)(1)(A), and
``(iii) to the extent provided in regulations, any foreign
pension plan or similar retirement arrangements or programs.
``(e) Definitions.--For purposes of this section--
``(1) Expatriate.--The term `expatriate' means--
``(A) any United States citizen who relinquishes
citizenship, and
``(B) any long-term resident of the United States who--
``(i) ceases to be a lawful permanent resident of the
United States (within the meaning of section 7701(b)(6)), or
``(ii) commences to be treated as a resident of a foreign
country under the provisions of a tax treaty between the
United States and the foreign country and who does not waive
the benefits of such treaty applicable to residents of the
foreign country.
``(2) Expatriation date.--The term `expatriation date'
means--
``(A) the date an individual relinquishes United States
citizenship, or

[[Page S3747]]

``(B) in the case of a long-term resident of the United
States, the date of the event described in clause (i) or (ii)
of paragraph (1)(B).
``(3) Relinquishment of citizenship.--A citizen shall be
treated as relinquishing United States citizenship on the
earliest of--
``(A) the date the individual renounces such individual's
United States nationality before a diplomatic or consular
officer of the United States pursuant to paragraph (5) of
section 349(a) of the Immigration and Nationality Act (8
U.S.C. 1481(a)(5)),
``(B) the date the individual furnishes to the United
States Department of State a signed statement of voluntary
relinquishment of United States nationality confirming the
performance of an act of expatriation specified in paragraph
(1), (2), (3), or (4) of section 349(a) of the Immigration
and Nationality Act (8 U.S.C. 1481(a)(1)-(4)),
``(C) the date the United States Department of State issues
to the individual a certificate of loss of nationality, or
``(D) the date a court of the United States cancels a
naturalized citizen's certificate of naturalization.

Subparagraph (A) or (B) shall not apply to any individual
unless the renunciation or voluntary relinquishment is
subsequently approved by the issuance to the individual of a
certificate of loss of nationality by the United States
Department of State.
``(4) Long-term resident.--The term `long-term resident'
has the meaning given to such term by section 877(e)(2).
``(f) Special Rules Applicable to Beneficiaries' Interests
in Trust.--
``(1) In general.--Except as provided in paragraph (2), if
an individual is determined under paragraph (3) to hold an
interest in a trust on the day before the expatriation date--
``(A) the individual shall not be treated as having sold
such interest,
``(B) such interest shall be treated as a separate share in
the trust, and
``(C)(i) such separate share shall be treated as a separate
trust consisting of the assets allocable to such share,
``(ii) the separate trust shall be treated as having sold
its assets on the day before the expatriation date for their
fair market value and as having distributed all of its assets
to the individual as of such time, and
``(iii) the individual shall be treated as having
recontributed the assets to the separate trust.

Subsection (a)(2) shall apply to any income, gain, or loss of
the individual arising from a distribution described in
subparagraph (C)(ii). In determining the amount of such
distribution, proper adjustments shall be made for
liabilities of the trust allocable to an individual's share
in the trust.
``(2) Special rules for interests in qualified trusts.--
``(A) In general.--If the trust interest described in
paragraph (1) is an interest in a qualified trust--
``(i) paragraph (1) and subsection (a) shall not apply, and
``(ii) in addition to any other tax imposed by this title,
there is hereby imposed on each distribution with respect to
such interest a tax in the amount determined under
subparagraph (B).
``(B) Amount of tax.--The amount of tax under subparagraph
(A)(ii) shall be equal to the lesser of--
``(i) the highest rate of tax imposed by section 1(e) for
the taxable year which includes the day before the
expatriation date, multiplied by the amount of the
distribution, or
``(ii) the balance in the deferred tax account immediately
before the distribution determined without regard to any
increases under subparagraph (C)(ii) after the 30th day
preceding the distribution.
``(C) Deferred tax account.--For purposes of subparagraph
(B)(ii)--
``(i) Opening balance.--The opening balance in a deferred
tax account with respect to any trust interest is an amount
equal to the tax which would have been imposed on the
allocable expatriation gain with respect to the trust
interest if such gain had been included in gross income under
subsection (a).
``(ii) Increase for interest.--The balance in the deferred
tax account shall be increased by the amount of interest
determined (on the balance in the account at the time the
interest accrues), for periods after the 90th day after the
expatriation date, by using the rates and method applicable
under section 6621 for underpayments of tax for such periods,
except that section 6621(a)(2) shall be applied by
substituting `5 percentage points' for `3 percentage points'
in subparagraph (B) thereof.
``(iii) Decrease for taxes previously paid.--The balance in
the tax deferred account shall be reduced--

``(I) by the amount of taxes imposed by subparagraph (A) on
any distribution to the person holding the trust interest,
and
``(II) in the case of a person holding a nonvested
interest, to the extent provided in regulations, by the
amount of taxes imposed by subparagraph (A) on distributions
from the trust with respect to nonvested interests not held
by such person.

``(D) Allocable expatriation gain.--For purposes of this
paragraph, the allocable expatriation gain with respect to
any beneficiary's interest in a trust is the amount of gain
which would be allocable to such beneficiary's vested and
nonvested interests in the trust if the beneficiary held
directly all assets allocable to such interests.
``(E) Tax deducted and withheld.--
``(i) In general.--The tax imposed by subparagraph (A)(ii)
shall be deducted and withheld by the trustees from the
distribution to which it relates.
``(ii) Exception where failure to waive treaty rights.--If
an amount may not be deducted and withheld under clause (i)
by reason of the distributee failing to waive any treaty
right with respect to such distribution--

``(I) the tax imposed by subparagraph (A)(ii) shall be
imposed on the trust and each trustee shall be personally
liable for the amount of such tax, and
``(II) any other beneficiary of the trust shall be entitled
to recover from the distributee the amount of such tax
imposed on the other beneficiary.

``(F) Disposition.--If a trust ceases to be a qualified
trust at any time, a covered expatriate disposes of an
interest in a qualified trust, or a covered expatriate
holding an interest in a qualified trust dies, then, in lieu
of the tax imposed by subparagraph (A)(ii), there is hereby
imposed a tax equal to the lesser of--
``(i) the tax determined under paragraph (1) as if the day
before the expatriation date were the date of such cessation,
disposition, or death, whichever is applicable, or
``(ii) the balance in the tax deferred account immediately
before such date.

Such tax shall be imposed on the trust and each trustee shall
be personally liable for the amount of such tax and any other
beneficiary of the trust shall be entitled to recover from
the covered expatriate or the estate the amount of such tax
imposed on the other beneficiary.
``(G) Definitions and special rules.--For purposes of this
paragraph--
``(i) Qualified trust.--The term `qualified trust' means a
trust which is described in section 7701(a)(30)(E).
``(ii) Vested interest.--The term `vested interest' means
any interest which, as of the day before the expatriation
date, is vested in the beneficiary.
``(iii) Nonvested interest.--The term `nonvested interest'
means, with respect to any beneficiary, any interest in a
trust which is not a vested interest. Such interest shall be
determined by assuming the maximum exercise of discretion in
favor of the beneficiary and the occurrence of all
contingencies in favor of the beneficiary.
``(iv) Adjustments.--The Secretary may provide for such
adjustments to the bases of assets in a trust or a deferred
tax account, and the timing of such adjustments, in order to
ensure that gain is taxed only once.
``(v) Coordination with retirement plan rules.--This
subsection shall not apply to an interest in a trust which is
part of a retirement plan to which subsection (d)(2) applies.
``(3) Determination of beneficiaries' interest in trust.--
``(A) Determinations under paragraph (1).--For purposes of
paragraph (1), a beneficiary's interest in a trust shall be
based upon all relevant facts and circumstances, including
the terms of the trust instrument and any letter of wishes or
similar document, historical patterns of trust distributions,
and the existence of and functions performed by a trust
protector or any similar adviser.
``(B) Other determinations.--For purposes of this section--
``(i) Constructive ownership.--If a beneficiary of a trust
is a corporation, partnership, trust, or estate, the
shareholders, partners, or beneficiaries shall be deemed to
be the trust beneficiaries for purposes of this section.
``(ii) Taxpayer return position.--A taxpayer shall clearly
indicate on its income tax return--

``(I) the methodology used to determine that taxpayer's
trust interest under this section, and
``(II) if the taxpayer knows (or has reason to know) that
any other beneficiary of such trust is using a different
methodology to determine such beneficiary's trust interest
under this section.

``(g) Termination of Deferrals, Etc.--In the case of any
covered expatriate, notwithstanding any other provision of
this title--
``(1) any period during which recognition of income or gain
is deferred shall terminate on the day before the
expatriation date, and
``(2) any extension of time for payment of tax shall cease
to apply on the day before the expatriation date and the
unpaid portion of such tax shall be due and payable at the
time and in the manner prescribed by the Secretary.
``(h) Imposition of Tentative Tax.--
``(1) In general.--If an individual is required to include
any amount in gross income under subsection (a) for any
taxable year, there is hereby imposed, immediately before the
expatriation date, a tax in an amount equal to the amount of
tax which would be imposed if the taxable year were a short
taxable year ending on the expatriation date.
``(2) Due date.--The due date for any tax imposed by
paragraph (1) shall be the 90th day after the expatriation
date.
``(3) Treatment of tax.--Any tax paid under paragraph (1)
shall be treated as a payment of the tax imposed by this
chapter for the taxable year to which subsection (a) applies.
``(4) Deferral of tax.--The provisions of subsection (b)
shall apply to the tax imposed by this subsection to the
extent attributable to gain includible in gross income by
reason of this section.

[[Page S3748]]

``(i) Special Liens for Deferred Tax Amounts.--
``(1) Imposition of lien.--
``(A) In general.--If a covered expatriate makes an
election under subsection (a)(4) or (b) which results in the
deferral of any tax imposed by reason of subsection (a), the
deferred amount (including any interest, additional amount,
addition to tax, assessable penalty, and costs attributable
to the deferred amount) shall be a lien in favor of the
United States on all property of the expatriate located in
the United States (without regard to whether this section
applies to the property).
``(B) Deferred amount.--For purposes of this subsection,
the deferred amount is the amount of the increase in the
covered expatriate's income tax which, but for the election
under subsection (a)(4) or (b), would have occurred by reason
of this section for the taxable year including the
expatriation date.
``(2) Period of lien.--The lien imposed by this subsection
shall arise on the expatriation date and continue until--
``(A) the liability for tax by reason of this section is
satisfied or has become unenforceable by reason of lapse of
time, or
``(B) it is established to the satisfaction of the
Secretary that no further tax liability may arise by reason
of this section.
``(3) Certain rules apply.--The rules set forth in
paragraphs (1), (3), and (4) of section 6324A(d) shall apply
with respect to the lien imposed by this subsection as if it
were a lien imposed by section 6324A.
``(j) Regulations.--The Secretary shall prescribe such
regulations as may be necessary or appropriate to carry out
the purposes of this section.''.
(b) Inclusion in Income of Gifts and Bequests Received by
United States Citizens and Residents From Expatriates.--
Section 102 (relating to gifts, etc. not included in gross
income) is amended by adding at the end the following new
subsection:
``(d) Gifts and Inheritances From Covered Expatriates.--
``(1) In general.--Subsection (a) shall not exclude from
gross income the value of any property acquired by gift,
bequest, devise, or inheritance from a covered expatriate
after the expatriation date. For purposes of this subsection,
any term used in this subsection which is also used in
section 877A shall have the same meaning as when used in
section 877A.
``(2) Exceptions for transfers otherwise subject to estate
or gift tax.--Paragraph (1) shall not apply to any property
if either--
``(A) the gift, bequest, devise, or inheritance is--
``(i) shown on a timely filed return of tax imposed by
chapter 12 as a taxable gift by the covered expatriate, or
``(ii) included in the gross estate of the covered
expatriate for purposes of chapter 11 and shown on a timely
filed return of tax imposed by chapter 11 of the estate of
the covered expatriate, or
``(B) no such return was timely filed but no such return
would have been required to be filed even if the covered
expatriate were a citizen or long-term resident of the United
States.''.
(c) Definition of Termination of United States
Citizenship.--Section 7701(a) is amended by adding at the end
the following new paragraph:
``(49) Termination of united states citizenship.--
``(A) In general.--An individual shall not cease to be
treated as a United States citizen before the date on which
the individual's citizenship is treated as relinquished under
section 877A(e)(3).
``(B) Dual citizens.--Under regulations prescribed by the
Secretary, subparagraph (A) shall not apply to an individual
who became at birth a citizen of the United States and a
citizen of another country.''.
(d) Ineligibility for Visa or Admission to United States.--
(1) In general.--Section 212(a)(10)(E) of the Immigration
and Nationality Act (8 U.S.C. 1182(a)(10)(E)) is amended to
read as follows:
``(E) Former citizens not in compliance with expatriation
revenue provisions.--Any alien who is a former citizen of the
United States who relinquishes United States citizenship
(within the meaning of section 877A(e)(3) of the Internal
Revenue Code of 1986) and who is not in compliance with
section 877A of such Code (relating to expatriation).''.
(2) Availability of information.--
(A) In general.--Section 6103(l) (relating to disclosure of
returns and return information for purposes other than tax
administration) is amended by adding at the end the following
new paragraph:
``(21) Disclosure to deny visa or admission to certain
expatriates.--Upon written request of the Attorney General or
the Attorney General's delegate, the Secretary shall disclose
whether an individual is in compliance with section 877A (and
if not in compliance, any items of noncompliance) to officers
and employees of the Federal agency responsible for
administering section 212(a)(10)(E) of the Immigration and
Nationality Act solely for the purpose of, and to the extent
necessary in, administering such section 212(a)(10)(E).''.
(B) Safeguards.--Section 6103(p)(4) (relating to
safeguards) is amended by striking ``or (20)'' each place it
appears and inserting ``(20), or (21)''.
(3) Effective dates.--The amendments made by this
subsection shall apply to individuals who relinquish United
States citizenship on or after the date of the enactment of
this Act.
(e) Conforming Amendments.--
(1) Section 877 is amended by adding at the end the
following new subsection:
``(h) Application.--This section shall not apply to an
expatriate (as defined in section 877A(e)) whose expatriation
date (as so defined) occurs on or after the date of the
enactment of this subsection.''.
(2) Section 2107 is amended by adding at the end the
following new subsection:
``(f) Application.--This section shall not apply to any
expatriate subject to section 877A.''.
(3) Section 2501(a)(3) is amended by adding at the end the
following new subparagraph:
``(C) Application.--This paragraph shall not apply to any
expatriate subject to section 877A.''.
(4) Section 6039G(a) is amended by inserting ``or 877A''
after ``section 877(b)''.
(5) The second sentence of section 6039G(d) is amended by
inserting ``or who relinquishes United States citizenship
(within the meaning of section 877A(e)(3))'' after ``section
877(a))''.
(f) Clerical Amendment.--The table of sections for subpart
A of part II of subchapter N of chapter 1 is amended by
inserting after the item relating to section 877 the
following new item:

``Sec. 877A. Tax responsibilities of expatriation.''.

(g) Effective Date.--
(1) In general.--Except as provided in this subsection, the
amendments made by this section shall apply to expatriates
(within the meaning of section 877A(e) of the Internal
Revenue Code of 1986, as added by this section) whose
expatriation date (as so defined) occurs on or after the date
of the enactment of this Act.
(2) Gifts and bequests.--Section 102(d) of the Internal
Revenue Code of 1986 (as added by subsection (b)) shall apply
to gifts and bequests received on or after the date of the
enactment of this Act, from an individual or the estate of an
individual whose expatriation date (as so defined) occurs
after such date.
(3) Due date for tentative tax.--The due date under section
877A(h)(2) of the Internal Revenue Code of 1986, as added by
this section, shall in no event occur before the 90th day
after the date of the enactment of this Act.

SEC. 8119. TAX TREATMENT OF CONTROLLED FOREIGN CORPORATIONS
ESTABLISHED IN TAX HAVENS.

(a) In General.--Subchapter C of chapter 80 (relating to
provisions affecting more than one subtitle) is amended by
adding at the end the following new section:

``SEC. 7875. CONTROLLED FOREIGN CORPORATIONS IN TAX HAVENS
TREATED AS DOMESTIC CORPORATIONS.

``(a) General Rule.--If a controlled foreign corporation is
a tax-haven CFC, then, notwithstanding section 7701(a)(4),
such corporation shall be treated for purposes of this title
as a domestic corporation.
``(b) Tax-Haven CFC.--For purposes of this section--
``(1) In general.--The term `tax-haven CFC' means, with
respect to any taxable year, a foreign corporation which--
``(A) was created or organized under the laws of a tax-
haven country, and
``(B) is a controlled foreign corporation (determined
without regard to this section) for an uninterrupted period
of 30 days or more during the taxable year.
``(2) Exception.--The term `tax-haven CFC' does not include
a foreign corporation for any taxable year if substantially
all of its income for the taxable year is derived from the
active conduct of trades or businesses within the country
under the laws of which the corporation was created or
organized.
``(c) Tax-Haven Country.--For purposes of this section--
``(1) In general.--The term `tax-haven country' means any
of the following:

``Andorra
Anguilla
Antigua and Barbuda
Aruba
Commonwealth of the Bahamas
Bahrain
Barbados
Belize
Bermuda
British Virgin Islands
Cayman Islands
Cook Islands
Cyprus
Commonwealth of the Dominica
Gibraltar
Grenada
Guernsey
Isle of Man
Jersey
Liberia
Principality of Liechtenstein
Republic of the Maldives
Malta
Republic of the Marshall Islands
Mauritius
Principality of Monaco
Montserrat
Republic of Nauru
Netherlands
Antilles
Niue
Panama
Samoa
San Marino
Federation of Saint Christopher and Nevis
Saint Lucia
Saint Vincent and the Grenadines
Republic of the Seychelles
Tonga
Turks and Caicos
Republic of Vanuatu

``(2) Secretarial authority.--The Secretary may remove or
add a foreign jurisdiction from the list of tax-haven
countries under paragraph (1) if the Secretary determines
such removal or addition is consistent with the purposes of
this section.''.
(b) Conforming Amendment.--The table of sections for
subchapter C of chapter 80 is amended by adding at the end
the following new item:

``Sec. 7875. Controlled foreign corporations in tax havens treated as
domestic corporations.''.

(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2007.

[[Page S3749]]

SEC. 8120. MODIFICATION OF EXCLUSION FOR CITIZENS LIVING
ABROAD.

(a) Inflation Adjustment of Foreign Earned Income
Limitation.--Clause (ii) of section 911(b)(2)(D) (relating to
inflation adjustment) is amended--
(1) by striking ``2007'' and inserting ``2005'', and
(2) by striking ``2006'' in subclause (II) and inserting
``2004''.
(b) Modification of Housing Cost Amount.--
(1) Minimum amount.--Clause (i) of section 911(c)(1)(B) is
amended to read as follows:
``(i) 16 percent of the amount (computed on a daily basis)
in effect under subsection (b)(2)(D) for the calendar year in
which such taxable year begins, multiplied by''.
(2) Maximum amount of exclusion.--
(A) In general.--Subparagraph (A) of section 911(c)(1) is
amended by inserting ``to the extent such expenses do not
exceed the amount determined under paragraph (2)'' after
``the taxable year''.
(B) Limitation.--Subsection (c) of section 911 is amended
by redesignating paragraphs (2) and (3) as paragraphs (3) and
(4), respectively, and by inserting after paragraph (1) the
following new paragraph:
``(2) Limitation.--The amount determined under this
paragraph is an amount equal to the product of--
``(A) 30 percent of the amount (computed on a daily basis)
in effect under subsection (b)(2)(D) for the calendar year in
which the taxable year of the individual begins, multiplied
by
``(B) the number of days of such taxable year within the
applicable period described in subparagraph (A) or (B) of
subsection (d)(1).''.
(C) Conforming amendments.--
(i) Section 911(d)(4) is amended by striking ``and
(c)(1)(B)(ii)'' and inserting ``, (c)(1)(B)(ii), and
(c)(2)(B)''
(ii) Section 911(d)(7) is amended by striking ``subsection
(c)(3)'' and inserting ``subsection (c)(4)''.
(c) Rates of Tax Applicable to Nonexcluded Income.--Section
911 (relating to exclusion of certain income of citizens and
residents of the United States living abroad) is amended by
redesignating subsection (f) as subsection (g) and by
inserting after subsection (e) the following new subsection:
``(f) Determination of Tax Liability on Nonexcluded
Amounts.--If any amount is excluded from the gross income of
a taxpayer under subsection (a) for any taxable year, then,
notwithstanding section 1 or 55--
``(1) the tax imposed by section 1 on the taxpayer for such
taxable year shall be equal to the excess (if any) of--
``(A) the tax which would be imposed by section 1 for the
taxable year if the taxpayer's taxable income were equal to
the sum of--
``(i) the taxpayer's taxable income for the taxable year
(determined without regard to this subsection), plus
``(ii) the amount excluded under subsection (a) for the
taxable year, over
``(B) the tax which would be imposed by section 1 for the
taxable year if the taxpayer's taxable income were equal to
the amount excluded under subsection (a) for the taxable
year, and
``(2) the tax imposed by section 55 for such taxable year
shall be equal to the excess (if any) of--
``(A) the amount which would be the tentative minimum tax
under section 55 for the taxable year if the taxpayer's
alternative minimum taxable income were equal to the sum of--
``(i) the taxpayer's alternative minimum taxable income for
the taxable year (determined without regard to this
subsection), plus
``(ii) the amount excluded under subsection (a) for the
taxable year, over
``(B) the sum of--
``(i) the amount which would be the tentative minimum tax
under section 55 for the taxable year if the taxpayer's
alternative minimum taxable income were equal to the amount
excluded under subsection (a) for the taxable year, plus
``(ii) the amount which would be the regular tax for the
taxable year if the tax imposed by section 1 were the tax
computed under paragraph (1).

For purposes of this subsection, the amount excluded under
subsection (a) shall be reduced by the aggregate amount of
any deductions or exclusions disallowed under subsection
(d)(6) with respect to such excluded amount.''.
(d) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.

SEC. 8121. LIMITATION ON ANNUAL AMOUNTS WHICH MAY BE DEFERRED
UNDER NONQUALIFIED DEFERRED COMPENSATION
ARRANGEMENTS.

(a) In General.--Section 409A (relating to inclusion of
gross income under nonqualified deferred compensation plans)
is amended by redesignating subsections (c), (d), and (e) as
subsections (d), (e), and (f), respectively, and by inserting
after subsection (b) the following new subsection:
``(c) Annual Limitation on Aggregate Deferred Amounts.--
``(1) Limitation.--If the aggregate amount of compensation
which--
``(A) is deferred for any taxable year with respect to a
participant under 1 or more nonqualified deferred
compensation plans maintained by the same employer, and
``(B) is not otherwise includible in gross income of the
participant for the taxable year,

exceeds the applicable dollar amount for the taxable year,
then such excess shall be included in the participant's gross
income for the taxable year.
``(2) Inclusion of earnings.--If--
``(A) an amount is includible under paragraph (1) in the
gross income of a participant for any taxable year, and
``(B) any portion of any assets set aside in a trust or
other arrangement under a nonqualified deferred compensation
plan are properly allocable to such amount,

then any increase in value in, or earnings with respect to,
such portion for the taxable year or any succeeding taxable
year shall be included in gross income of the participant for
such taxable year or succeeding taxable year.
``(3) Applicable dollar amount.--For purposes of this
subsection--
``(A) In general.--The term `applicable dollar amount'
means, with respect to any participant, the lesser of--
``(i) the average annual compensation which--

``(I) was payable during the base period to the participant
by the employer described in paragraph (1)(A), and
``(II) was includible in the participant's gross income for
taxable years in the base period, or

``(ii) $1,000,000.
``(B) Base period.--The term `base period' means, with
respect to any computation year, the 5-taxable year period
ending with the taxable year preceding the taxable year in
which the election described in subsection (a)(4)(B) is made
by the participant to have compensation for services
performed in the computation year deferred under a
nonqualified deferred compensation plan, except that if the
election is made after the beginning of the computation year,
such period shall be the 5-taxable year period ending with
the taxable year preceding the computation year. For purposes
of this subparagraph, the term `computation year' means any
taxable year of the participant for which the limitation
under paragraph (1) is being determined.''.
(b) Conforming Amendments.--Sections 6041(g)(1) and
6051(a)(13) are each amended by striking ``409A(d)'' and
inserting ``409A(e)''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005, except that taxable years beginning on or before such
date shall be taken into account in determining the average
annual compensation of a participant during any base period
for purposes of section 409A(c)(2) of the Internal Revenue
Code of 1986 (as added by such amendments).

SEC. 8122. INCREASE IN AGE OF MINOR CHILDREN WHOSE UNEARNED
INCOME IS TAXED AS IF PARENT'S INCOME.

(a) In General.--Section 1(g)(2)(A) (relating to child to
whom subsection applies) is amended by striking ``age 14''
and inserting ``age 18''.
(b) Treatment of Distributions From Qualified Disability
Trusts.--Section 1(g)(4) (relating to net unearned income) is
amended by adding at the end the following new subparagraph:
``(C) Treatment of distributions from qualified disability
trusts.--For purposes of this subsection, in the case of any
child who is a beneficiary of a qualified disability trust
(as defined in section 642(b)(2)(C)(ii)), any amount included
in the income of such child under sections 652 and 662 during
a taxable year shall be considered earned income of such
child for such taxable year.''.
(c) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.

SEC. 8123. TAXATION OF INCOME OF CONTROLLED FOREIGN
CORPORATIONS ATTRIBUTABLE TO IMPORTED PROPERTY.

(a) General Rule.--Subsection (a) of section 954 (defining
foreign base company income) is amended by striking ``and''
at the end of paragraph (4), by striking the period at the
end of paragraph (5) and inserting ``, and'', and by adding
at the end the following new paragraph:
``(6) imported property income for the taxable year
(determined under subsection (j) and reduced as provided in
subsection (b)(5)).''.
(b) Definition of Imported Property Income.--Section 954 is
amended by adding at the end the following new subsection:
``(j) Imported Property Income.--
``(1) In general.--For purposes of subsection (a)(6), the
term `imported property income' means income (whether in the
form of profits, commissions, fees, or otherwise) derived in
connection with--
``(A) manufacturing, producing, growing, or extracting
imported property;
``(B) the sale, exchange, or other disposition of imported
property; or
``(C) the lease, rental, or licensing of imported property.
Such term shall not include any foreign oil and gas
extraction income (within the meaning of section 907(c)) or
any foreign oil related income (within the meaning of section
907(c)).
``(2) Imported property.--For purposes of this subsection--
``(A) In general.--Except as otherwise provided in this
paragraph, the term `imported property' means property which
is imported into the United States by the controlled foreign
corporation or a related person.
``(B) Imported property includes certain property imported
by unrelated persons.--The term `imported property' includes
any property imported into the

[[Page S3750]]

United States by an unrelated person if, when such property
was sold to the unrelated person by the controlled foreign
corporation (or a related person), it was reasonable to
expect that--
``(i) such property would be imported into the United
States; or
``(ii) such property would be used as a component in other
property which would be imported into the United States.
``(C) Exception for property subsequently exported.--The
term `imported property' does not include any property which
is imported into the United States and which--
``(i) before substantial use in the United States, is sold,
leased, or rented by the controlled foreign corporation or a
related person for direct use, consumption, or disposition
outside the United States; or
``(ii) is used by the controlled foreign corporation or a
related person as a component in other property which is so
sold, leased, or rented.
``(3) Definitions and special rules.--
``(A) Import.--For purposes of this subsection, the term
`import' means entering, or withdrawal from warehouse, for
consumption or use. Such term includes any grant of the right
to use intangible property (as defined in section
936(h)(3)(B)) in the United States.
``(B) United states.--For purposes of this subsection, the
term `United States' includes the Commonwealth of Puerto
Rico, the Virgin Islands of the United States, Guam, American
Samoa, and the Commonwealth of the Northern Mariana Islands.
``(C) Unrelated person.--For purposes of this subsection,
the term `unrelated person' means any person who is not a
related person with respect to the controlled foreign
corporation.
``(D) Coordination with foreign base company sales
income.--For purposes of this section, the term `foreign base
company sales income' shall not include any imported property
income.''.
(c) Separate Application of Limitations on Foreign Tax
Credit for Imported Property Income.--
(1) Before 2007.--
(A) In general.--Paragraph (1) of section 904(d) (relating
to separate application of section with respect to certain
categories of income), as in effect for taxable years
beginning before January 1, 2007, is amended by striking
``and'' at the end of subparagraph (H), by redesignating
subparagraph (I) as subparagraph (J), and by inserting after
subparagraph (H) the following new subparagraph:
``(I) imported property income, and''.
(B) Imported property income defined.--Paragraph (2) of
section 904(d), as so in effect, is amended by redesignating
subparagraphs (H) and (I) as subparagraphs (I) and (J),
respectively, and by inserting after subparagraph (G) the
following new subparagraph:
``(H) Imported property income.--The term `imported
property income' means any income received or accrued by any
person which is of a kind which would be imported property
income (as defined in section 954(j)).''.
(C) Look-thru rules to apply.--Subparagraph (F) of section
904(d)(3) of such Code, as so in effect, is amended by
striking ``or (D)'' and inserting ``(D), or (I)''.
(2) After 2006.--
(A) In general.--Paragraph (1) of section 904(d) (relating
to separate application of section with respect to certain
categories of income), as in effect for taxable years
beginning after December 31, 2006, is amended by striking
``and'' at the end of subparagraph (A), by redesignating
subparagraph (B) as subparagraph (C), and by inserting after
subparagraph (A) the following new subparagraph:
``(B) imported property income, and''.
(B) Imported property income defined.--Paragraph (2) of
section 904(d), as so in effect, is amended by redesignating
subparagraphs (J) and (K) as subparagraphs (K) and (L),
respectively, and by inserting after subparagraph (I) the
following new subparagraph:
``(J) Imported property income.--The term `imported
property income' means any income received or accrued by any
person which is of a kind which would be imported property
income (as defined in section 954(j)).''.
(C) Conforming amendment.--Clause (ii) of section
904(d)(2)(A), as so in effect, is amended by inserting ``or
imported property income'' after ``passive category income''.
(d) Technical Amendments.--
(1) Clause (iii) of section 952(c)(1)(B) (relating to
certain prior year deficits may be taken into account) is
amended--
(A) by redesignating subclauses (II), (III), (IV), and (V)
as subclauses (III), (IV), (V), and (VI), and
(B) by inserting after subclause (I) the following new
subclause:

``(II) imported property income,''.

(2) Paragraph (5) of section 954(b) (relating to deductions
to be taken into account) is amended by striking ``and the
foreign base company oil related income'' and inserting ``the
foreign base company oil related income, and the imported
property income''.
(e) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
of foreign corporations beginning after the date of the
enactment of this Act, and to taxable years of United States
shareholders within which or with which such taxable years of
such foreign corporations end.
(2) Subsection (c).--The amendments made by subsection
(c)(1) shall apply to taxable years beginning after the date
of the enactment of this Act and before January 1, 2007, and
the amendments made by subsection (c)(2) shall apply to
taxable years beginning after December 31, 2006.

Subtitle C--Oil and Gas Provisions

SEC. 8131. EXTENSION OF SUPERFUND TAXES.

(a) Excise Taxes.--Section 4611(e) is amended to read as
follows:
``(e) Application of Hazardous Substance Superfund
Financing Rate.--The Hazardous Substance Superfund financing
rate under this section shall apply after December 31, 1986,
and before January 1, 1996, and after December 31, 2005, and
before January 1, 2015.''
(b) Corporate Environmental Income Tax.--Section 59A(e) is
amended to read as follows:
``(e) Application of Tax.--The tax imposed by this section
shall apply to taxable years beginning after December 31,
1986, and before January 1, 1996, and to taxable years
beginning after December 31, 2005, and before January 1,
2015.''
(c) Effective Dates.--
(1) Excise taxes.--The amendments made by subsection (a)
shall take effect on the date of the enactment of this Act.
(2) Income tax.--The amendment made by subsection (b) shall
apply to taxable years beginning after December 31, 2005.

SEC. 8132. MODIFICATIONS OF FOREIGN TAX CREDIT RULES
APPLICABLE TO DUAL CAPACITY TAXPAYERS.

(a) In General.--Section 901 (relating to credit for taxes
of foreign countries and of possessions of the United States)
is amended by redesignating subsection (m) as subsection (n)
and by inserting after subsection (l) the following new
subsection:
``(m) Special Rules Relating To Dual Capacity Taxpayers.--
``(1) General rule.--Notwithstanding any other provision of
this chapter, any amount paid or accrued by a dual capacity
taxpayer to a foreign country or possession of the United
States for any period shall not be considered a tax--
``(A) if, for such period, the foreign country or
possession does not impose a generally applicable income tax,
or
``(B) to the extent such amount exceeds the amount
(determined in accordance with regulations) which--
``(i) is paid by such dual capacity taxpayer pursuant to
the generally applicable income tax imposed by the country or
possession, or
``(ii) would be paid if the generally applicable income tax
imposed by the country or possession were applicable to such
dual capacity taxpayer.

Nothing in this paragraph shall be construed to imply the
proper treatment of any such amount not in excess of the
amount determined under subparagraph (B).
``(2) Dual capacity taxpayer.--For purposes of this
subsection, the term `dual capacity taxpayer' means, with
respect to any foreign country or possession of the United
States, a person who--
``(A) is subject to a levy of such country or possession,
and
``(B) receives (or will receive) directly or indirectly a
specific economic benefit (as determined in accordance with
regulations) from such country or possession.
``(3) Generally applicable income tax.--For purposes of
this subsection--
``(A) In general.--The term `generally applicable income
tax' means an income tax (or a series of income taxes) which
is generally imposed under the laws of a foreign country or
possession on income derived from the conduct of a trade or
business within such country or possession.
``(B) Exceptions.--Such term shall not include a tax unless
it has substantial application, by its terms and in practice,
to--
``(i) persons who are not dual capacity taxpayers, and
``(ii) persons who are citizens or residents of the foreign
country or possession.''
(b) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to taxes paid or accrued in taxable years beginning
after the date of the enactment of this Act.
(2) Contrary treaty obligations upheld.--The amendments
made by this section shall not apply to the extent contrary
to any treaty obligation of the United States.

SEC. 8133. RULES RELATING TO FOREIGN OIL AND GAS INCOME.

(a) Separate Basket for Foreign Tax Credit.--
(1) Separate basket.--
(A) Years before 2007.--Paragraph (1) of section 904(d)
(relating to separate application of section with respect to
certain categories of income), as in effect for years
beginning before 2007and as amended by this Act, is amended
by striking ``and'' at the end of subparagraph (I), by
redesignating subparagraph (J) as subparagraph (K), and by
inserting after subparagraph (I) the following new
subparagraph:
``(J) foreign oil and gas income, and''.
(B) 2007 and after.--Paragraph (1) of section 904(d), as in
effect for years beginning after 2006 and as amended by this
Act, is amended by striking ``and'' at the end of
subparagraph (B), by striking the period at the end of
subparagraph (C) and inserting ``, and'', and by adding at
the end the following:
``(D) foreign oil and gas income.''
(2) Definition.--

[[Page S3751]]

(A) Years before 2007.--Paragraph (2) of section 904(d), as
in effect for years beginning before 2007 and as amended by
this Act, is amended by redesignating subparagraphs (I) and
(J) as subparagraphs (J) and (K), respectively, and by
inserting after subparagraph (H) the following new
subparagraph:
``(I) Foreign oil and gas income.--The term `foreign oil
and gas income' has the meaning given such term by section
954(g).''
(B) 2007 and after.--Section 904(d)(2), as in effect for
years after 2006 and as amended by this Act, is amended by
redesignating subparagraphs (K) and (L) as subparagraphs (L)
and (M) and by inserting after subparagraph (J) the
following:
``(K) Foreign oil and gas income.--For purposes of this
section--
``(i) In general.--The term `foreign oil and gas income'
has the meaning given such term by section 954(g).
``(ii) Coordination.--Passive category income and general
category income shall not include foreign oil and gas income
(as so defined).''
(3) Conforming amendments.--
(A) Section 904(d)(3)(F)(i) is amended by striking ``or
(E)'' and inserting ``(E), or (J)''.
(B) Section 907(a) is hereby repealed.
(C) Section 907(c)(4) is hereby repealed.
(D) Section 907(f) is hereby repealed.
(4) Effective dates.--
(A) In general.--The amendments made by this section shall
apply to taxable years beginning after the date of the
enactment of this Act.
(B) Years after 2006.--The amendments made by paragraphs
(1)(B) and (2)(B) shall apply to taxable years beginning
after December 31, 2006.
(C) Transitional rules.--
(i) Separate basket treatment.--Any taxes paid or accrued
in a taxable year beginning on or before the date of the
enactment of this Act, with respect to income which was
described in subparagraph (I) of section 904(d)(1) of such
Code (as in effect on the day before the date of the
enactment of this Act), shall be treated as taxes paid or
accrued with respect to foreign oil and gas income to the
extent the taxpayer establishes to the satisfaction of the
Secretary of the Treasury that such taxes were paid or
accrued with respect to foreign oil and gas income.
(ii) Carryovers.--Any unused oil and gas extraction taxes
which under section 907(f) of such Code (as so in effect)
would have been allowable as a carryover to the taxpayer's
first taxable year beginning after the date of the enactment
of this Act (without regard to the limitation of paragraph
(2) of such section 907(f) for first taxable year) shall be
allowed as carryovers under section 904(c) of such Code in
the same manner as if such taxes were unused taxes under such
section 904(c) with respect to foreign oil and gas extraction
income.
(iii) Losses.--The amendment made by paragraph (3)(C) shall
not apply to foreign oil and gas extraction losses arising in
taxable years beginning on or before the date of the
enactment of this Act.
(b) Elimination of Deferral for Foreign Oil and Gas
Extraction Income.--
(1) General rule.--Paragraph (1) of section 954(g)
(defining foreign base company oil related income) is amended
to read as follows:
``(1) In general.--Except as otherwise provided in this
subsection, the term `foreign oil and gas income' means any
income of a kind which would be taken into account in
determining the amount of--
``(A) foreign oil and gas extraction income (as defined in
section 907(c)), or
``(B) foreign oil related income (as defined in section
907(c)).''
(2) Conforming amendments.--
(A) Subsections (a)(5), (b)(5), and (b)(6) of section 954,
and section 952(c)(1)(B)(ii)(I), are each amended by striking
``base company oil related income'' each place it appears
(including in the heading of subsection (b)(8)) and inserting
``oil and gas income''.
(B) Subsection (b)(4) of section 954 is amended by striking
``base company oil-related income'' and inserting ``oil and
gas income''.
(C) The subsection heading for subsection (g) of section
954 is amended by striking ``Foreign Base Company Oil Related
Income'' and inserting ``Foreign Oil and Gas Income''.
(D) Subparagraph (A) of section 954(g)(2) is amended by
striking ``foreign base company oil related income'' and
inserting ``foreign oil and gas income''.
(3) Effective date.--The amendments made by this subsection
shall apply to taxable years of foreign corporations
beginning after the date of the enactment of this Act, and to
taxable years of United States shareholders ending with or
within such taxable years of foreign corporations.

SEC. 8134. MODIFICATION OF CREDIT FOR PRODUCING FUEL FROM A
NONCONVENTIONAL SOURCE.

(a) Taxable Years Ending Before 2006.--
(1) Modification of phaseout.--
(A) In general.--Section 29(b)(1)(A) is amended by
inserting ``the calendar year preceding'' before ``the
calendar year''.
(B) Conforming amendments.--Section 29(b)((2) is amended--
(i) by striking ``The'' and inserting ``With respect to any
calendar year, the'', and
(ii) by striking ``for the calendar year in which the sale
occurs'' and inserting ``for such calendar year''.
(2) No inflation adjustment for the credit amount in
2005.--Section 29(b)(2), as amended by paragraph (1), is
amended by adding at the end the following new sentence:
``This paragraph shall not apply with respect to the $3
amount in subsection (a) for calendar year 2005 and the
amount in effect under subsection (a) for sales in such
calendar year shall be the amount which was in effect for
sales in calendar year 2004.''.
(b) Taxable Years Ending After 2005.--
(1) Modification of phaseout.--
(A) In general.--Section 45K(b)(1)(A) is amended by
inserting ``the calendar year preceding'' before ``the
calendar year''.
(B) Conforming amendments.--Section 45K(b)((2) is amended--
(i) by striking ``The'' and inserting ``With respect to any
calendar year, the'', and
(ii) by striking ``for the calendar year in which the sale
occurs'' and inserting ``for such calendar year''.
(2) No inflation adjustment for the credit amount in 2005,
2006, and 2007.--Section 45K(b)(2), as amended by paragraph
(1), is amended by adding at the end the following new
sentence: ``This paragraph shall not apply with respect to
the $3 amount in subsection (a) for calendar years 2005,
2006, and 2007 and the amount in effect under subsection (a)
for sales in each such calendar year shall be the amount
which was in effect for sales in calendar year 2004.''.
(3) Treatment of coke and coke gas.--
(A) Nonapplication of phaseout.--Section 45K(g)(2) is
amended by adding at the end the following new subparagraph:
``(D) Nonapplication of phaseout.--Subsection (b)(1) shall
not apply.''.
(B) Application of inflation adjustment.--Section
45K(g)(2)(B) is amended by inserting ``and the last sentence
of subsection (b)(2) shall not apply.''.
(C) Clarification of qualifying facility.--Section
45K(g)(1) is amended by inserting ``(other than from
petroleum based products)'' after ``coke or coke gas''.
(c) Effective Date.--The amendments made by this section
shall apply to fuel sold after December 31, 2004.

SEC. 8135. ELIMINATION OF AMORTIZATION OF GEOLOGICAL AND
GEOPHYSICAL EXPENDITURES FOR MAJOR INTEGRATED
OIL COMPANIES.

(a) In General.--Section 167(h) is amended by adding at the
end the following new paragraph:
``(5) Nonapplication to major integrated oil companies.--
This subsection shall not apply with respect to any expenses
paid or incurred for any taxable year by any integrated oil
company (as defined in section 291(b)(4)) which has an
average daily worldwide production of crude oil of at least
500,000 barrels for such taxable year.''.
(b) Effective Date.--The amendment made by this section
shall take effect as if included in the amendment made by
section 1329(a) of the Energy Policy Act of 2005.

Subtitle D--Tax Administration Provisions

SEC. 8141. IMPOSITION OF WITHHOLDING ON CERTAIN PAYMENTS MADE
BY GOVERNMENT ENTITIES.

(a) In General.--Section 3402 is amended by adding at the
end the following new subsection:
``(t) Extension of Withholding to Certain Payments Made by
Government Entities.--
``(1) General rule.--The Government of the United States,
every State, every political subdivision thereof, and every
instrumentality of the foregoing (including multi-State
agencies) making any payment for goods and services which is
subject to withholding shall deduct and withhold form such
payment a tax in an amount equal to 3 percent of such
payment.
``(2) Exceptions.--Paragraph (1) shall not apply to any
payment--
``(A) except as provided in subparagraph (B), which is
subject to withholding under any other provision of this
chapter or chapter 3,
``(B) which is subject to withholding under section 3406
and from which amounts are being withheld under such section,
``(C) of interest,
``(D) for real property,
``(E) to any tax-exempt entity, foreign government, or
other entity subject to the requirements of paragraph (1),
``(F) made pursuant to a classified or confidential
contract (as defined in section 6050M(e)(3)), and
``(G) made by a political subdivision of a State (or any
instrumentality thereof) which makes less than $100,000,000
of such payments annually.
``(3) Coordination with other sections.--For purposes of
sections 3403 and 3404 and for purposes of so much of
subtitle F (except section 7205) as relates to this chapter,
payments to any person of any payment for goods and services
which is subject to withholding shall be treated as if such
payments were wages paid by an employer to an employee.''.
(b) Effective Date.--The amendment made by this section
shall apply to payments made after December 31, 2005.

SEC. 8142. INCREASE IN CERTAIN CRIMINAL PENALTIES.

(a) In General.--Section 7206 (relating to fraud and false
statements) is amended--
(1) by striking ``Any person who--'' and inserting ``(a) In
General.--Any person who--'', and
(2) by adding at the end the following new subsection:
``(b) Increase in Monetary Limitation for Underpayment or
Overpayment of Tax Due to Fraud.--If any portion of any
underpayment (as defined in section 6664(a)) or

[[Page S3752]]

overpayment (as defined in section 6401(a)) of tax required
to be shown on a return is attributable to fraudulent action
described in subsection (a), the applicable dollar amount
under subsection (a) shall in no event be less than an amount
equal to such portion. A rule similar to the rule under
section 6663(b) shall apply for purposes of determining the
portion so attributable.''.
(b) Increase in Penalties.--
(1) Attempt to evade or defeat tax.--Section 7201 is
amended--
(A) by striking ``$100,000'' and inserting ``$500,000'',
(B) by striking ``$500,000'' and inserting ``$1,000,000'',
and
(C) by striking ``5 years'' and inserting ``10 years''.
(2) Willful failure to file return, supply information, or
pay tax.--Section 7203 is amended--
(A) in the first sentence--
(i) by striking ``Any person'' and inserting the following:
``(a) In General.--Any person'', and
(ii) by striking ``$25,000'' and inserting ``$50,000'',
(B) in the third sentence, by striking ``section'' and
inserting ``subsection'', and
(C) by adding at the end the following new subsection:
``(b) Aggravated Failure to File.--
``(1) In general.--In the case of any failure described in
paragraph (2), the first sentence of subsection (a) shall be
applied by substituting--
``(A) `felony' for `misdemeanor',
``(B) `$500,000 ($1,000,000' for `$25,000 ($100,000', and
``(C) `10 years' for `1 year'.
``(2) Failure described.--A failure described in this
paragraph is a failure to make a return described in
subsection (a) for a period of 3 or more consecutive taxable
years.''.
(3) Fraud and false statements.--Section 7206(a) (as
redesignated by subsection (a)) is amended--
(A) by striking ``$100,000'' and inserting ``$500,000'',
(B) by striking ``$500,000'' and inserting ``$1,000,000'',
and
(C) by striking ``3 years'' and inserting ``5 years''.
(c) Effective Date.--The amendments made by this section
shall apply to actions, and failures to act, occurring after
the date of the enactment of this Act.

SEC. 8143. REPEAL OF SUSPENSION OF INTEREST AND CERTAIN
PENALTIES WHERE SECRETARY FAILS TO CONTACT
TAXPAYER.

(a) In General.--Section 6404 (relating to abatements) is
amended by striking subsection (g) and by redesignating
subsections (h) and (i) as subsections (g) and (h),
respectively.
(b) Effective Date.--The amendments made by this section
shall apply to returns of tax filed after December 31, 2005.

SEC. 8144. INCREASE IN PENALTY FOR BAD CHECKS AND MONEY
ORDERS.

(a) In General.--Section 6657 (relating to bad checks) is
amended--
(1) by striking ``$750'' and inserting ``$1,250'', and
(2) by striking ``$15'' and inserting ``$25''.
(b) Effective Date.--The amendments made by this section
apply to checks or money orders received after the date of
the enactment of this Act.

SEC. 8145. FRIVOLOUS TAX SUBMISSIONS.

(a) Civil Penalties.--Section 6702 is amended to read as
follows:

``SEC. 6702. FRIVOLOUS TAX SUBMISSIONS.

``(a) Civil Penalty for Frivolous Tax Returns.--A person
shall pay a penalty of $5,000 if--
``(1) such person files what purports to be a return of a
tax imposed by this title but which--
``(A) does not contain information on which the substantial
correctness of the self-assessment may be judged, or
``(B) contains information that on its face indicates that
the self-assessment is substantially incorrect; and
``(2) the conduct referred to in paragraph (1)--
``(A) is based on a position which the Secretary has
identified as frivolous under subsection (c), or
``(B) reflects a desire to delay or impede the
administration of Federal tax laws.
``(b) Civil Penalty for Specified Frivolous Submissions.--
``(1) Imposition of penalty.--Except as provided in
paragraph (3), any person who submits a specified frivolous
submission shall pay a penalty of $5,000.
``(2) Specified frivolous submission.--For purposes of this
section--
``(A) Specified frivolous submission.--The term `specified
frivolous submission' means a specified submission if any
portion of such submission--
``(i) is based on a position which the Secretary has
identified as frivolous under subsection (c), or
``(ii) reflects a desire to delay or impede the
administration of Federal tax laws.
``(B) Specified submission.--The term `specified
submission' means--
``(i) a request for a hearing under--

``(I) section 6320 (relating to notice and opportunity for
hearing upon filing of notice of lien), or
``(II) section 6330 (relating to notice and opportunity for
hearing before levy), and

``(ii) an application under--

``(I) section 6159 (relating to agreements for payment of
tax liability in installments),
``(II) section 7122 (relating to compromises), or
``(III) section 7811 (relating to taxpayer assistance
orders).

``(3) Opportunity to withdraw submission.--If the Secretary
provides a person with notice that a submission is a
specified frivolous submission and such person withdraws such
submission within 30 days after such notice, the penalty
imposed under paragraph (1) shall not apply with respect to
such submission.
``(c) Listing of Frivolous Positions.--The Secretary shall
prescribe (and periodically revise) a list of positions which
the Secretary has identified as being frivolous for purposes
of this subsection. The Secretary shall not include in such
list any position that the Secretary determines meets the
requirement of section 6662(d)(2)(B)(ii)(II).
``(d) Reduction of Penalty.--The Secretary may reduce the
amount of any penalty imposed under this section if the
Secretary determines that such reduction would promote
compliance with and administration of the Federal tax laws.
``(e) Penalties in Addition to Other Penalties.--The
penalties imposed by this section shall be in addition to any
other penalty provided by law.''.
(b) Treatment of Frivolous Requests for Hearings Before
Levy.--
(1) Frivolous requests disregarded.--Section 6330 (relating
to notice and opportunity for hearing before levy) is amended
by adding at the end the following new subsection:
``(g) Frivolous Requests for Hearing, Etc.--Notwithstanding
any other provision of this section, if the Secretary
determines that any portion of a request for a hearing under
this section or section 6320 meets the requirement of clause
(i) or (ii) of section 6702(b)(2)(A), then the Secretary may
treat such portion as if it were never submitted and such
portion shall not be subject to any further administrative or
judicial review.''.
(2) Preclusion from raising frivolous issues at hearing.--
Section 6330(c)(4) is amended--
(A) by striking ``(A)'' and inserting ``(A)(i)'';
(B) by striking ``(B)'' and inserting ``(ii)'';
(C) by striking the period at the end of the first sentence
and inserting ``; or''; and
(D) by inserting after subparagraph (A)(ii) (as so
redesignated) the following:
``(B) the issue meets the requirement of clause (i) or (ii)
of section 6702(b)(2)(A).''.
(3) Statement of grounds.--Section 6330(b)(1) is amended by
striking ``under subsection (a)(3)(B)'' and inserting ``in
writing under subsection (a)(3)(B) and states the grounds for
the requested hearing''.
(c) Treatment of Frivolous Requests for Hearings Upon
Filing of Notice of Lien.--Section 6320 is amended--
(1) in subsection (b)(1), by striking ``under subsection
(a)(3)(B)'' and inserting ``in writing under subsection
(a)(3)(B) and states the grounds for the requested hearing'',
and
(2) in subsection (c), by striking ``and (e)'' and
inserting ``(e), and (g)''.
(d) Treatment of Frivolous Applications for Offers-in-
Compromise and Installment Agreements.--Section 7122 is
amended by adding at the end the following new subsection:
``(e) Frivolous Submissions, Etc.--Notwithstanding any
other provision of this section, if the Secretary determines
that any portion of an application for an offer-in-compromise
or installment agreement submitted under this section or
section 6159 meets the requirement of clause (i) or (ii) of
section 6702(b)(2)(A), then the Secretary may treat such
portion as if it were never submitted and such portion shall
not be subject to any further administrative or judicial
review.''.
(e) Clerical Amendment.--The table of sections for part I
of subchapter B of chapter 68 is amended by striking the item
relating to section 6702 and inserting the following new
item:

``Sec. 6702. Frivolous tax submissions.''.

(f) Effective Date.--The amendments made by this section
shall apply to submissions made and issues raised after the
date on which the Secretary first prescribes a list under
section 6702(c) of the Internal Revenue Code of 1986, as
amended by subsection (a).

SEC. 8146. PARTIAL PAYMENTS REQUIRED WITH SUBMISSION OF
OFFERS-IN-COMPROMISE.

(a) In General.--Section 7122 (relating to compromises), as
amended by this Act, is amended by redesignating subsections
(c), (d), and (e) as subsections (d), (e), and (f),
respectively, and by inserting after subsection (b) the
following new subsection:
``(c) Rules for Submission of Offers-in-Compromise.--
``(1) Partial payment required with submission.--
``(A) Lump-sum offers.--
``(i) In general.--The submission of any lump-sum offer-in-
compromise shall be accompanied by the payment of 20 percent
of amount of such offer.
``(ii) Lump-sum offer-in-compromise.--For purposes of this
section, the term `lump-sum offer-in-compromise' means any
offer of payments made in 5 or fewer installments.
``(B) Periodic payment offers.--The submission of any
periodic payment offer-in-compromise shall be accompanied by
the payment of the amount of the first proposed installment
and each proposed installment due during the period such
offer is being evaluated for acceptance and has not been
rejected by the Secretary. Any failure to

[[Page S3753]]

make a payment required under the preceding sentence shall be
deemed a withdrawal of the offer-in-compromise.
``(2) Rules of application.--
``(A) Use of payment.--The application of any payment made
under this subsection to the assessed tax or other amounts
imposed under this title with respect to such tax may be
specified by the taxpayer.
``(B) No user fee imposed.--Any user fee which would
otherwise be imposed under this section shall not be imposed
on any offer-in-compromise accompanied by a payment required
under this subsection.
``(C) Waiver authority.--The Secretary may issue
regulations waiving any payment required under paragraph (1)
in a manner consistent with the practices established in
accordance with the requirements under subsection (d)(3).''.
(b) Additional Rules Relating to Treatment of Offers.--
(1) Unprocessable offer if payment requirements are not
met.--Paragraph (3) of section 7122(d) (relating to standards
for evaluation of offers), as redesignated by subsection (a),
is amended by striking ``; and'' at the end of subparagraph
(A) and inserting a comma, by striking the period at the end
of subparagraph (B) and inserting ``, and'', and by adding at
the end the following new subparagraph:
``(C) any offer-in-compromise which does not meet the
requirements of subsection (c) shall be returned to the
taxpayer as unprocessable.''.
(2) Deemed acceptance of offer not rejected within certain
period.--Section 7122, as amended by subsection (a), is
amended by adding at the end the following new subsection:
``(g) Deemed Acceptance of Offer Not Rejected Within
Certain Period.--Any offer-in-compromise submitted under this
section shall be deemed to be accepted by the Secretary if
such offer is not rejected by the Secretary before the date
which is 24 months after the date of the submission of such
offer (12 months for offers-in-compromise submitted after the
date which is 5 years after the date of the enactment of this
subsection). For purposes of the preceding sentence, any
period during which any tax liability which is the subject of
such offer-in-compromise is in dispute in any judicial
proceeding shall not be taken in to account in determining
the expiration of the 24-month period (or 12-month period, if
applicable).''.
(c) Effective Date.--The amendments made by this section
shall apply to offers-in-compromise submitted on and after
the date which is 60 days after the date of the enactment of
this Act.

SEC. 8147. WAIVER OF USER FEE FOR INSTALLMENT AGREEMENTS
USING AUTOMATED WITHDRAWALS.

(a) In General.--Section 6159 (relating to agreements for
payment of tax liability in installments) is amended by
redesignating subsection (e) as subsection (f) and by
inserting after subsection (d) the following:
``(e) Waiver of User Fees for Installment Agreements Using
Automated Withdrawals.--In the case of a taxpayer who enters
into an installment agreement in which automated installment
payments are agreed to, the Secretary shall waive the fee (if
any) for entering into the installment agreement.''.
(b) Effective Date.--The amendments made by this section
shall apply to agreements entered into on or after the date
which is 180 days after the date of the enactment of this
Act.

SEC. 8148. TERMINATION OF INSTALLMENT AGREEMENTS.

(a) In General.--Section 6159(b)(4) (relating to failure to
pay an installment or any other tax liability when due or to
provide requested financial information) is amended by
striking ``or'' at the end of subparagraph (B), by
redesignating subparagraph (C) as subparagraph (E), and by
inserting after subparagraph (B) the following:
``(C) to make a Federal tax deposit under section 6302 at
the time such deposit is required to be made,
``(D) to file a return of tax imposed under this title by
its due date (including extensions), or''.
(b) Conforming Amendment.--The heading for section
6159(b)(4) is amended by striking ``Failure to pay an
installment or any other tax liability when due or to provide
requested financial information'' and inserting ``Failure to
make payments or deposits or file returns when due or to
provide requested financial information''.
(c) Effective Date.--The amendments made by this section
shall apply to failures occurring on or after the date of the
enactment of this Act.

Subtitle E--Additional Provisions

SEC. 8151. LOAN AND REDEMPTION REQUIREMENTS ON POOLED
FINANCING REQUIREMENTS.

(a) Strengthened Reasonable Expectation Requirement.--
Subparagraph (A) of section 149(f)(2) (relating to reasonable
expectation requirement) is amended to read as follows:
``(A) In general.--The requirements of this paragraph are
met with respect to an issue if the issuer reasonably expects
that--
``(i) as of the close of the 1-year period beginning on the
date of issuance of the issue, at least 50 percent of the net
proceeds of the issue (as of the close of such period) will
have been used directly or indirectly to make or finance
loans to ultimate borrowers, and
``(ii) as of the close of the 3-year period beginning on
such date of issuance, at least 95 percent of the net
proceeds of the issue (as of the close of such period) will
have been so used.''.
(b) Written Loan Commitment and Redemption Requirements.--
Section 149(f) (relating to treatment of certain pooled
financing bonds) is amended by redesignating paragraphs (4)
and (5) as paragraphs (6) and (7), respectively, and by
inserting after paragraph (3) the following new paragraphs:
``(4) Written loan commitment requirement.--
``(A) In general.--The requirement of this paragraph is met
with respect to an issue if the issuer receives prior to
issuance written loan commitments identifying the ultimate
potential borrowers of at least 50 percent of the net
proceeds of such issue.
``(B) Exception.--Subparagraph (A) shall not apply with
respect to any issuer which is a State (or an integral part
of a State) issuing pooled financing bonds to make or finance
loans to subordinate governmental units of such State or to
State-created entities providing financing for water-
infrastructure projects through the federally-sponsored State
revolving fund program.
``(5) Redemption requirement.--The requirement of this
paragraph is met if to the extent that less than the
percentage of the proceeds of an issue required to be used
under clause (i) or (ii) of paragraph (2)(A) is used by the
close of the period identified in such clause, the issuer
uses an amount of proceeds equal to the excess of--
``(A) the amount required to be used under such clause,
over
``(B) the amount actually used by the close of such period,

to redeem outstanding bonds within 90 days after the end of
such period.''.
(c) Elimination of Disregard of Pooled Bonds in Determining
Eligibility for Small Issuer Exception to Arbitrage Rebate.--
Section 148(f)(4)(D)(ii) (relating to aggregation of issuers)
is amended by striking subclause (II) and by redesignating
subclauses (III) and (IV) as subclauses (II) and (III),
respectively.
(d) Conforming Amendments.--
(1) Section 149(f)(1) is amended by striking ``paragraphs
(2) and (3)'' and inserting ``paragraphs (2), (3), (4), and
(5)''.
(2) Section 149(f)(7)(B), as redesignated by subsection
(b), is amended by striking ``paragraph (4)(A)'' and
inserting ``paragraph (6)(A)''.
(3) Section 54(l)(2) is amended by striking ``section
149(f)(4)(A)'' and inserting ``section 149(f)(6)(A)''.
(e) Effective Date.--The amendments made by this section
shall apply to bonds issued after the date of the enactment
of this Act.

SEC. 8152. REPEAL OF THE SCHEDULED PHASEOUT OF THE
LIMITATIONS ON PERSONAL EXEMPTIONS AND ITEMIZED
DEDUCTIONS.

(a) In General.--The Internal Revenue Code of 1986 is
amended--
(1) by striking subparagraphs (E) and (F) of section
151(d)(3), and
(2) by striking subsections (f) and (g) of section 68.
(b) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.
(c) Application of EGTRRA Sunset.--The amendments made by
this section shall be subject to title IX of the Economic
Growth and Tax Relief Reconciliation Act of 2001 to the same
extent and in the same manner as the provision of such Act to
which such amendment relates.
______

SA 3716. Mrs. MURRAY (for Mr. Kennedy (for himself, Mr. Biden, and
Mr. Leahy)) proposed an amendment to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

On page 126, between lines 12 and 13, insert the following:

UNITED STATES STRATEGY TO PROMOTE DEMOCRACY IN IRAQ

Sec. 1406. (a) Of the funds provided in this chapter for
the Economic Support Fund, not less than $96,000,000 should
be made available through the Bureau of Democracy, Human
Rights, and Labor of the Department of State, in coordination
with the United States Agency for International Development
where appropriate, to United States nongovernmental
organizations for the purpose of supporting broad-based
democracy assistance programs in Iraq that promote the long
term development of civil society, political parties,
election processes, and parliament in that country.
______

SA 3717. Mr. BIDEN submitted an amendment intended to be proposed by
him to the bill H.R. 4939, making emergency supplemental appropriations
for the fiscal year ending September 30, 2006, and for other purposes;
which was ordered to lie on the table; as follows:

On page 253, between lines 19 and 20, insert the following:

PROHIBITION ON USE OF FUNDS FOR CERTAIN PURPOSES IN IRAQ

Sec. 7032. None of the funds made available by title I of
this Act may be made available to establish permanent
military bases in Iraq or to exercise control over the oil
infrastructure or oil resources of Iraq.
______

SA 3718. Mr. BIDEN (for himself and Mr. DeWine) submitted an
amendment

[[Page S3754]]

intended to be proposed by him to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; which was ordered to lie on the table; as
follows:

On page 117, between lines 9 and 10, insert the following:

ASSISTANCE FOR NATO ACTIVITIES IN SUPPORT OF AFRICAN UNION AND UNITED
NATIONS OPERATIONS TO STOP GENOCIDE IN DARFUR, SUDAN

Sec. 1312. (a) Amounts appropriated by this chapter for the
Department of Defense for operation and maintenance may be
used to provide assistance, including supplies, services,
transportation, including airlifts, and logistical support,
to the North Atlantic Treaty Organization (NATO), and allies
working in support of NATO, for activities undertaken to
support African Union and United Nations peacekeeping
operations to stop genocide in Darfur, Sudan.
(b) The Secretary of Defense shall provide quarterly
reports on support provided under subsection (a) to the
Committee on Appropriations, the Committee on Armed Services,
and the Committee on Foreign Relations of the Senate and the
Committee on Appropriations, the Committee on Armed Services,
and the Committee on International Relations of the House of
Representatives.
______

SA 3719. Mr. BIDEN (for himself and Mr. DeWine) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

On page 88, line 7, insert after ``Provided,'' the
following: ``That of the funds available under this heading,
not less than $250,000 shall be made available for the
establishment and support of an office of a special envoy for
Sudan with a mandate of pursuing, in conjunction with the
African Union, a sustainable peace settlement to end the
conflict in Darfur, Sudan, assisting the parties to the
Comprehensive Peace Agreement for Sudan with implementation
of the Agreement, pursuing efforts at conflict resolution in
eastern Sudan, northern Uganda, and Chad, facilitating, in
cooperation with the people of Darfur and the African Union,
a dialogue within Darfur to promote conflict resolution and
reconciliation at the grass roots level, and developing a
common policy approach among international partners to
address such issues: Provided further,''.
______

SA 3720. Mr. NELSON of Florida submitted an amendment intended to be
proposed by him to the bill H.R. 4939, making emergency supplemental
appropriations for the fiscal year ending September 30, 2006, and for
other purposes; which was ordered to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. ENERGY SECURITY AND INDEPENDENCE.

(a) Department of Defense Matters.--
(1) Additional amount for procurement, defense-wide.--The
amount appropriated by chapter 3 of title I of this Act under
the heading ``Procurement, Defense-Wide'' is hereby increased
by $25,000,000.
(2) Procurement of hybrid vehicles.--Of the amount
appropriated by chapter 3 of title I of this Act under the
heading ``Procurement, Defense-Wide'', as increased by
paragraph (1), $25,000,000 shall be available for the
procurement of--
(A) alternative fuel vehicles;
(B) hybrid vehicles;
(C) flex-fuel vehicles; and
(D) alternative fuel supply and related vehicle fleet
infrastructure.
(b) Department of Energy Matters.--
(1) Procurement of alternative fuel, hybrid, and flex-fuel
vehicles.--
(A) Additional amount.--For an additional amount for
``Departmental Administration'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$25,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Departmental
Administration'', as increased by subparagraph (A),
$25,000,000 shall be available for procurement of alternative
fuel, hybrid, and flex-fuel vehicles and for related
alternative fuel supply and related fleet infrastructure.
(2) Advanced vehicle research and deployment programs.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$150,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$150,000,000 shall be available for advanced vehicle research
and deployment programs, including research and deployment
related to acceleration of hybrid vehicle technologies, fuel
cell school and transit buses, biodiesel engines, procurement
of fuel cells, and vehicle efficiency.
(3) Clean cities program.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$350,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$350,000,000 shall be available for the Clean Cities Program
established under sections 405, 409, and 505 of the Energy
Policy Act of 1992 (42 U.S.C. 13231, 13235, 13256), including
development of common and voluntary standards that will
accelerate--
(i) the market penetration of flex-fuel, alternative fuel,
hybrid and plug-in hybrid vehicles, and related fueling
infrastructure; and
(ii) installation of E-85, biodiesel, and other alternative
fuel stations and infrastructure.
(4) Biomass research and development.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$100,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$100,000,000 shall be available for implementation of the
Biomass Research and Development Act of 2000 (Public Law 106-
224; 7 U.S.C. 7624 note).
(c) Department of Agriculture Matters.--
(1) Production incentives for cellulosic biofuels.--
(A) Additional amount for farm service agency--bioenergy
program.--The amount appropriated by chapter 1 of title II
under the heading ``Farm Service Agency--Bioenergy Program''
is hereby increased by $250,000,000.
(B) Implementation of the biomass research and development
initiative.--Of the amount appropriated by chapter 1 of title
II under the heading ``Farm Service Agency--Bioenergy
Program'', as increased by subparagraph (A), $250,000,000
shall be available for production incentives for cellulosic
biofuels.
(d) Environmental Protection Agency.--
(1) Additional amount.--For an additional amount for
``Science and Technology'' of title III of the Department of
the Interior, Environment, and Related Agencies
Appropriations Act, 2006 (Public Law 109-54; 119 Stat. 499),
$25,000,000, to remain available until expended.
(2) Use.--Of the amount appropriated for ``Science and
Technology'', as increased by paragraph (1), $25,000,000
shall be available for sugar cane ethanol research and
development.
(e) Emergency Designation.--The amounts provided under this
section are designated as an emergency requirement pursuant
to section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.
______

SA 3721. Mr. NELSON of Florida (for himself, Mr. Menendez, Mr.
Lieberman, Mr. Lautenberg, Mr. Kerry, and Mr. Reid) submitted an
amendment intended to be proposed by him to the bill H.R. 4939, making
emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; which was ordered to lie on
the table; as follows:

At the appropriate place, insert the following:

SEC. __. ENERGY SECURITY AND INDEPENDENCE.

(a) Department of Defense Matters.--
(1) Procurement of hybrid vehicles.--
(A) Additional amount for procurement, defense-wide.--The
amount appropriated by chapter 3 of title I of this Act under
the heading ``Procurement, Defense-Wide'' is hereby increased
by $25,000,000.
(B) Procurement of hybrid vehicles.--Of the amount
appropriated by chapter 3 of title I of this Act under the
heading ``Procurement, Defense-Wide'', as increased by
subparagraph (A), $25,000,000 shall be available for the
procurement of--
(i) alternative fuel vehicles;
(ii) hybrid vehicles;
(iii) flex-fuel vehicles; and
(iv) alternative fuel supply and related vehicle fleet
infrastructure.
(2) Alternative energy generation and vehicle
technologies.--
(A) Additional amount for research, development, test, and
evaluation, army.--The amount appropriated by chapter 3 of
title I of this Act under the heading ``Research,
Development, Test, and Evaluation, Army'' is hereby increased
by $200,000,000.
(B) Alternative energy generation and vehicle
technologies.--Of the amount appropriated by chapter 3 of
title I of this Act under the heading ``Research,
Development, Test, and Evaluation, Army'' , as increased by
subparagraph (A), $200,000,000 shall be available for
activities to achieve the following:
(i) The development and deployment of energy efficient,
renewable, and clean alternative energy generation sources
and vehicle technologies suitable for the missions and
activities of the Department of Defense.
(ii) The establishment of workforce training and education
programs relating to the

[[Page S3755]]

development and deployment of such sources and technologies.
(iii) The development of enhanced domestic production of
such sources and technologies, including activities in
concert with the private sector.
(3) Non-petroleum aviation and bunker fuels and systems.--
(A) Additional amount for research, development, test, and
evaluation, air force.--The amount appropriated by chapter 3
of title I of this Act under the heading ``Research,
Development, Test, and Evaluation, Air Force'' is hereby
increased by $50,000,000.
(B) Non-petroleum aviation and bunker fuels and systems.--
Of the amount appropriated by chapter 3 of title I of this
Act under the heading ``Research, Development, Test, and
Evaluation, Air Force'', as increased by subparagraph (A),
$50,000,000 shall be available for the development of non-
petroleum aviation fuels and bunker fuels and systems that
utilize renewable energy supplies and sources or reduce net
greenhouse gas emissions.
(4) Improvement of fuel and energy supply systems.--
(A) Additional amount for research, development, test, and
evaluation, defense-wide.--The amount appropriated by chapter
3 of title I of this Act under the heading ``Research,
Development, Test, and Evaluation, Defense-Wide'' is hereby
increased by $10,000,000.
(B) Improvement of fuel and energy supply systems.--Of the
amount appropriated by chapter 3 of title I of this Act under
the heading ``Research, Development, Test, and Evaluation,
Defense-Wide'', as increased by subparagraph (A), $10,000,000
shall be available for activities to improve the petroleum,
fossil fuel, and energy supply systems of the Department of
Defense to achieve one or more of the following:
(i) Increased security of such systems.
(ii) Reduction in greenhouse gas emissions attributable to
such systems.
(iii) Reduction in the costs of energy for the Department
of Defense.
(5) Energy efficiency.--
(A) Additional amount for operation and maintenance,
defense-wide.--The amount appropriated by chapter 3 of title
I of this Act under the heading ``Operation and Maintenance,
Defense-Wide'' is hereby increased by $215,000,000.
(B) Energy efficiency.--Of the amount appropriated by
chapter 3 of title I of this Act under the heading
``Operation and Maintenance, Defense-Wide'', as increased by
paragraph (A), $215,000,000 shall be available for activities
relating to energy efficiency, of which--
(i) $200,000,000 shall be available for the procurement and
installation of renewable and low-emission, clean energy
distributed electricity generation systems at military
installations and other facilities of the Department of
Defense; and
(ii) $15,000,000 shall be available for energy efficiency
and renewable energy projects at the Pentagon Reservation,
and at other military installations and facilities of the
Department of Defense.
(b) Department of Energy Matters.--
(1) Procurement of alternative fuel, hybrid, and flex-fuel
vehicles.--
(A) Additional amount.--For an additional amount for
``Departmental Administration'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$25,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Departmental
Administration'', as increased by subparagraph (A),
$25,000,000 shall be available for procurement of alternative
fuel, hybrid, and flex-fuel vehicles and for related
alternative fuel supply and related fleet infrastructure.
(2) Advanced vehicle research and deployment programs.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$150,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$150,000,000 shall be available for advanced vehicle research
and deployment programs, including research and deployment
related to acceleration of hybrid vehicle technologies, fuel
cell school and transit buses, biodiesel engines, procurement
of fuel cells, and vehicle efficiency.
(3) Clean cities program.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$350,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$350,000,000 shall be available for the Clean Cities Program
established under sections 405, 409, and 505 of the Energy
Policy Act of 1992 (42 U.S.C. 13231, 13235, 13256), including
development of common and voluntary standards that will
accelerate--
(i) the market penetration of flex-fuel, alternative fuel,
hybrid and plug-in hybrid vehicles, and related fueling
infrastructure; and
(ii) installation of E-85, biodiesel, and other alternative
fuel stations and infrastructure.
(4) Clean coal power initiative.--
(A) Additional amount.--For an additional amount for
``Clean Coal Technology'' under the heading ``DEPARTMENT OF
ENERGY'' of title III of the Energy and Water Development
Appropriations Act, 2006 (Public Law 109-103), $175,000,000,
to remain available until expended.
(B) Use.--Of the amount appropriated for ``Clean Coal
Technology'', as increased by subparagraph (A), $175,000,000
shall be available for the Clean Coal Power Initiative of the
Department of Energy for large-scale--
(i) geologic carbon dioxide sequestration demonstrations;
(ii) sequestration-ready gasification demonstrations;
(iii) liquid fuels, substitute natural gas, and hydrogen
projects related to sequestration-ready plants; and
(iv) carbon dioxide combustion control demonstrations.
(5) Biomass research and development.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$100,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$100,000,000 shall be available for implementation of the
Biomass Research and Development Act of 2000 (Public Law 106-
224; 7 U.S.C. 7624 note).
(6) Cellulosic biomass ethanol and municipal solid waste
loan guarantees.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$25,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$25,000,000 shall be available to make loan guarantees to
promote cellulosic biomass ethanol and improved treatment of
municipal solid waste.
(7) Electricity grid reliability improvements.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$50,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$50,000,000 shall be available for electricity grid
reliability improvements.
(8) Grants to state energy offices through the office of
electricity delivery and energy reliability.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$250,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$250,000,000 shall be available for grants to State energy
offices through the Office of Electricity Delivery and Energy
Reliability, in coordination with the Directorate for
Preparedness of the Department of Homeland Security, for
nonpetroleum-dependent or very low-emission distributed
energy projects at critical facilities to harden
infrastructure, strengthen first responders capabilities, and
enhance emergency preparedness, including $30,000,000 for
State energy programs.
(9) Energy efficiency programs.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$300,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$300,000,000 shall be available for energy efficiency
programs, including research and development, energy
conservation standards, State building code development
incentives, appliance rebates, the public information
initiative on energy efficiency, utility efficiency pilot
projects, Energy Star, industrial programs, State energy
programs, and low-income community pilot projects.
(10) Ultra-efficient aircraft engine technology research
and development.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$50,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$50,000,000 shall be available for research and development
on ultra-efficient aircraft engine technology.
(11) Renewable energy resource research and development.--

[[Page S3756]]

(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$150,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$150,000,000 shall be available for research and development
on renewable energy resources, including wind, biomass,
solar, hydroelectric, and geothermal resources and renewable
energy resource assessments, including development of
potential integrated renewable energy projects.
(12) Weatherization assistance grants.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$225,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$250,000,000 shall be available for grants under the
Weatherization Assistance Program for Low-Income Persons
established under part A of title IV of the Energy
Conservation and Production Act (42 U.S.C. 6861 et seq.).
(13) Renewable energy rebates for residential and small
business applications.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$125,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$125,000,000 shall be available for renewable energy rebates
for residential and small business applications.
(14) Renewable energy production incentives.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$50,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$50,000,000 shall be available for renewable energy
production incentives.
(15) Rural and remote communities electrification grants.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$50,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$50,000,000 shall be available to make rural and remote
communities electrification grants.
(16) Federal energy management programs.--
(A) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$25,000,000, to remain available until expended.
(B) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by subparagraph (A),
$25,000,000 shall be available for Federal energy management
measures carried out under part 3 of title V of the National
Energy Conservation Policy Act (42 U.S.C. 8251 et seq.).
(c) Department of Agriculture Matters.--
(1) Biomass research and development initiative.--
(A) Additional amount for agricultural research service.--
The amount appropriated by chapter 1 of title II under the
heading ``Agricultural Research Service'' is hereby increased
by $100,000,000.
(B) Implementation of the biomass research and development
initiative.--Of the amount appropriated by chapter 1 of title
II under the heading ``Agricultural Research Service'', as
increased by subparagraph (A), $100,000,000 shall be
available for implementation of the biomass research and
development initiative.
(2) Production incentives for cellulosic biofuels.--
(A) Additional amount for farm service agency--bioenergy
program.--The amount appropriated by chapter 1 of title II
under the heading ``Farm Service Agency--Bioenergy Program''
is hereby increased by $250,000,000.
(B) Implementation of the biomass research and development
initiative.--Of the amount appropriated by chapter 1 of title
II under the heading ``Farm Service Agency--Bioenergy
Program'', as increased by subparagraph (A), $250,000,000
shall be available for production incentives for cellulosic
biofuels.
(d) Environmental Protection Agency.--
(1) Additional amount.--For an additional amount for
``Science and Technology'' of title III of the Department of
the Interior, Environment, and Related Agencies
Appropriations Act, 2006 (Public Law 109-54; 119 Stat. 499),
$25,000,000, to remain available until expended.
(2) Use.--Of the amount appropriated for ``Science and
Technology'', as increased by paragraph (1), $25,000,000
shall be available for sugar cane ethanol research and
development.
(e) General Services Administration.--
(1) Additional amount.--For an additional amount for
``Operating Expenses'' under the heading ``GENERAL SERVICES
ADMINISTRATION'' under title VI of the Transportation,
Treasury, Housing and Urban Development, the Judiciary, the
District of Columbia, and Independent Agencies Appropriations
Act, 2006 (Public Law 109-115; 119 Stat. 2482), $25,000,000,
to remain available until expended.
(2) Use.--Of the amount appropriated for ``Operating
Expenses'' under paragraph (1), $25,000,000 shall be
available for the procurement of alternative fuel, hybrid,
and flex-fuel vehicles, and for related alternative fuel
supply and related fleet infrastructure.
(f) Emergency Designation.--The amounts provided under this
section are designated as an emergency requirement pursuant
to section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.
______

SA 3722. Mr. CORNYN (for himself and Mr. Kyl) proposed an amendment
to the bill H.R. 4939, making emergency supplemental appropriations for
the fiscal year ending September 30, 2006, and for other purposes; as
follows:

On page 253, between lines 19 and 20, insert the following:

TITLE VIII--IMMIGRATION INJUNCTION REFORM

SEC. 8001. SHORT TITLE.

This title may be cited as the ``Fairness in Immigration
Litigation Act of 2006''.

SEC. 8002. APPROPRIATE REMEDIES FOR IMMIGRATION LEGISLATION.

(a) Requirements for an Order Granting Prospective Relief
Against the Government.--
(1) In general.--If a court determines that prospective
relief should be ordered against the Government in any civil
action pertaining to the administration or enforcement of the
immigration laws of the United States, the court shall--
(A) limit the relief to the minimum necessary to correct
the violation of law;
(B) adopt the least intrusive means to correct the
violation of law;
(C) minimize, to the greatest extent practicable, the
adverse impact on national security, border security,
immigration administration and enforcement, and public
safety, and
(D) provide for the expiration of the relief on a specific
date, which is not later than the earliest date necessary for
the Government to remedy the violation.
(2) Written explanation.--The requirements described in
paragraph (1) shall be discussed and explained in writing in
the order granting prospective relief and must be
sufficiently detailed to allow review by another court.
(3) Expiration of preliminary injunctive relief.--
Preliminary injunctive relief shall automatically expire on
the date that is 90 days after the date on which such relief
is entered, unless the court--
(A) makes the findings required under paragraph (1) for the
entry of permanent prospective relief; and
(B) makes the order final before expiration of such 90-day
period.
(4) Requirements for order denying motion.--This subsection
shall apply to any order denying the Government's motion to
vacate, modify, dissolve or otherwise terminate an order
granting prospective relief in any civil action pertaining to
the administration or enforcement of the immigration laws of
the United States.
(b) Procedure for Motion Affecting Order Granting
Prospective Relief Against the Government.--
(1) In general.--A court shall promptly rule on the
Government's motion to vacate, modify, dissolve or otherwise
terminate an order granting prospective relief in any civil
action pertaining to the administration or enforcement of the
immigration laws of the United States.
(2) Automatic stays.--
(A) In general.--The Government's motion to vacate, modify,
dissolve, or otherwise terminate an order granting
prospective relief made in any civil action pertaining to the
administration or enforcement of the immigration laws of the
United States shall automatically, and without further order
of the court, stay the order granting prospective relief on
the date that is 15 days after the date on which such motion
is filed unless the court previously has granted or denied
the Government's motion.
(B) Duration of automatic stay.--An automatic stay under
subparagraph (A) shall continue until the court enters an
order granting or denying the Government's motion.
(C) Postponement.--The court, for good cause, may postpone
an automatic stay under subparagraph (A) for not longer than
15 days.
(D) Orders blocking automatic stays.--Any order staying,
suspending, delaying, or otherwise barring the effective date
of the automatic stay described in subparagraph (A), other
than an order to postpone the effective date of the automatic
stay for not longer than 15 days under subparagraph (C),
shall be--

[[Page S3757]]

(i) treated as an order refusing to vacate, modify,
dissolve or otherwise terminate an injunction; and
(ii) immediately appealable under section 1292(a)(1) of
title 28, United States Code.
(c) Settlements.--
(1) Consent decrees.--In any civil action pertaining to the
administration or enforcement of the immigration laws of the
United States, the court may not enter, approve, or continue
a consent decree that does not comply with subsection (a).
(2) Private settlement agreements.--Nothing in this section
shall preclude parties from entering into a private
settlement agreement that does not comply with subsection (a)
if the terms of that agreement are not subject to court
enforcement other than reinstatement of the civil proceedings
that the agreement settled.
(d) Expedited Proceedings.--It shall be the duty of every
court to advance on the docket and to expedite the
disposition of any civil action or motion considered under
this section.
(e) Definitions.--In this section:
(1) Consent decree.--The term ``consent decree''--
(A) means any relief entered by the court that is based in
whole or in part on the consent or acquiescence of the
parties; and
(B) does not include private settlements.
(2) Good cause.--The term ``good cause'' does not include
discovery or congestion of the court's calendar.
(3) Government.--The term ``Government'' means the United
States, any Federal department or agency, or any Federal
agent or official acting within the scope of official duties.
(4) Permanent relief.--The term ``permanent relief'' means
relief issued in connection with a final decision of a court.
(5) Private settlement agreement.--The term ``private
settlement agreement'' means an agreement entered into among
the parties that is not subject to judicial enforcement other
than the reinstatement of the civil action that the agreement
settled.
(6) Prospective relief.--The term ``prospective relief''
means temporary, preliminary, or permanent relief other than
compensatory monetary damages.

SEC. 8003. EFFECTIVE DATE.

(a) In General.--This title shall apply with respect to all
orders granting prospective relief in any civil action
pertaining to the administration or enforcement of the
immigration laws of the United States, whether such relief
was ordered before, on, or after the date of the enactment of
this Act.
(b) Pending Motions.--Every motion to vacate, modify,
dissolve or otherwise terminate an order granting prospective
relief in any such action, which motion is pending on the
date of the enactment of this Act, shall be treated as if it
had been filed on such date of enactment.
(c) Automatic Stay for Pending Motions.--
(1) In general.--An automatic stay with respect to the
prospective relief that is the subject of a motion described
in subsection (b) shall take effect without further order of
the court on the date which is 10 days after the date of the
enactment of this Act if the motion--
(A) was pending for 45 days as of the date of the enactment
of this Act; and
(B) is still pending on the date which is 10 days after
such date of enactment.
(2) Duration of automatic stay.--An automatic stay that
takes effect under paragraph (1) shall continue until the
court enters an order granting or denying the Government's
motion under section 8002(b). There shall be no further
postponement of the automatic stay with respect to any such
pending motion under section 8002(b)(2). Any order, staying,
suspending, delaying or otherwise barring the effective date
of this automatic stay with respect to pending motions
described in subsection (b) shall be an order blocking an
automatic stay subject to immediate appeal under section
8002(b)(2)(D).
______

SA 3723. Mr. SCHUMER (for himself and Mr. Reid) proposed an amendment
to the bill H.R. 4939, making emergency supplemental appropriations for
the fiscal year ending September 30, 2006, and for other purposes; as
follows:

At the appropriate place, insert the following:

SEC. __. MEASURES TO ADDRESS PRICE GOUGING AND MARKET
MANIPULATION.

(a) Federal Trade Commission.--
(1) Additional amount.--For an additional amount for
``Federal Trade Commission Salaries and Expenses'' under the
heading ``RELATED AGENCIES'' of title V of the Science,
State, Justice, Commerce, and Related Agencies Appropriations
Act, 2006 (Public Law 109-108), $10,000,000.
(2) Use.--Of the amount appropriated for ``Federal Trade
Commission Salaries and Expenses'', as increased by paragraph
(1), $10,000,000 shall be available to investigate and
enforce price gouging complaints and other market
manipulation activities by companies engaged in the wholesale
and retail sales of gasoline and petroleum distillates.
(b) Commodity Futures Trading Commission.--
(1) Additional amount.--For an additional amount for
``Commodity Futures Trading Commission'' under the heading
``RELATED AGENCIES AND FOOD AND DRUG ADMINISTRATION'' of
title VI of the Agriculture, Rural Development, Food and Drug
Administration, and Related Agencies Appropriations Act, 2006
(Public Law 109-97), $10,000,000.
(2) Use.--Of the amount appropriated for ``Commodity
Futures Trading Commission'', as increased by paragraph (1),
$10,000,000 shall be available for activities--
(A) to enhance investigation of energy derivatives markets;
(B) to ensure that speculation in those markets is
appropriate and reasonable; and
(C) for data systems and reporting programs that can
uncover real-time market manipulation activities.
(c) Securities and Exchange Commission.--
(1) Additional amount.--For an additional amount for
``Securities and Exchange Commission Salaries and Expenses ''
under the heading ``RELATED AGENCIES'' of title V of the
Science, State, Justice, Commerce, and Related Agencies
Appropriations Act, 2006 (Public Law 109-108), $5,000,000.
(2) Use.--Of the amount appropriated for ``Securities and
Exchange Commission Salaries and Expenses'', as increased by
paragraph (1), $5,000,000 shall be available for review and
analysis of major integrated oil and gas company reports and
filings for compliance with disclosure, corporate governance,
and related requirements.
(d) Energy Information Administration.--
(1) Additional amount.--For an additional amount for
``Energy Information Administration'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$10,000,000.
(2) Use.--Of the amount appropriated for ``Energy
Information Administration'', as increased by paragraph (1),
$10,000,000 shall be available for activities to ensure real-
time and accurate gasoline and energy price and supply data
collection.
(e) Energy Supply and Conservation.--
(1) Additional amount.--For an additional amount for
``Energy Supply and Conservation'' under the heading
``DEPARTMENT OF ENERGY'' of title III of the Energy and Water
Development Appropriations Act, 2006 (Public Law 109-103),
$315,000,000.
(2) Use.--Of the amount appropriated for ``Energy Supply
and Conservation'', as increased by paragraph (1),
$315,000,000 shall be available to provide grants to State
energy offices for--
(A) the development and deployment of real-time information
systems for energy price and supply data collection and
publication;
(B) programs and systems to help discover energy price
gouging and market manipulation;
(C) critical energy infrastructure protection;
(D) clean distributed energy projects that promote energy
security; and
(E) programs to encourage the adoption and implementation
of energy conservation and efficiency technologies and
standards.
(f) Government Accountability Office.--
(1) Additional amount.--For an additional amount for
``Salaries and Expenses'' under the heading ``GOVERNMENT
ACCOUNTABILITY OFFICE'' of title I of the Legislative Branch
Appropriations Act, 2006 (Public Law 109-55), $50,000.
(2) Use.--Of the amount appropriated for ``Salaries and
Expenses'', as increased by paragraph (1), $50,000 shall be
available to the Government Accountability for the
preparation of a report, to be submitted to the appropriate
committees of Congress not later than 90 days after the date
of enactment of this Act, that includes--
(A) a review of the mergers between Exxon and Mobil,
Chevron and Texaco, and Conoco and Phillips, and other
mergers of significant or comparable scale in the oil
industry that have occurred since 1990, including an
assessment of the impact of the mergers on--
(i) market concentration;
(ii) the ability of the companies to exercise market power;
(iii) wholesale prices of petroleum products; and
(iv) the retail prices of petroleum products;
(B) an assessment of the impact that vitiating the mergers
reviewed under subparagraph (A) would have on each of the
matters described in clauses (i) through (iv) of subparagraph
(A);
(C) an assessment of the impact of prohibiting any 1
company from simultaneously owning assets in each of the oil
industry sectors of exploration, refining and distribution,
and retail on each of the matters described in clauses (i)
through (iv) of subparagraph (A); and
(D) an assessment of--
(i) the effectiveness of divestitures ordered by the
Federal Trade Commission in preventing market concentration
as a result of oil industry mergers approved since 1995; and
(ii) the effectiveness of the Federal Trade Commission in
identifying and preventing--

(I) market manipulation;
(II) commodity withholding;
(III) collusion; and
(IV) other forms of market power abuse in the oil industry.

(g) Emergency Designation.--The amounts provided under this
section are designated as an emergency requirement pursuant
to section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.

[[Page S3758]]

______

SA 3724. Mr. SCHUMER proposed an amendment to the bill H.R. 4939,
making emergency supplemental appropriations for the fiscal year ending
September 30, 2006, and for other purposes; as follows:

At the appropriate place, insert the following:

SEC. __. MARITIME CONTAINER SECURITY.

(a) Maritime Container Inspections.--
(1) In general.--Beginning on the date on which regulations
are issued under subsection (d), a maritime cargo container
may not be shipped to the United States from any port
participating in the Container Security Initiative (CSI)
unless--
(A) the container has passed through a radiation detection
device;
(B) the container has been scanned using gamma-ray, x-ray,
or another internal imaging system;
(C) the container has been tagged and catalogued using an
on-container label, radio frequency identification, or global
positioning system tracking device; and
(D) the images created by the scans required under
subparagraph (B) have been reviewed and approved by the
Office of Container Evaluation and Enforcement established
under subsection (b).
(2) Model.--
(A) In general.--Except as provided under subparagraph (B),
the Secretary of Homeland Security shall model the inspection
system described in paragraph (1) after the Integrated
Container Inspection System established at the Port of Hong
Kong.
(B) New technology.--The Secretary is not required to use
the same companies or specific technologies installed at the
Port of Hong Kong if a more advanced technology is available.
(b) Container Evaluation and Enforcement Unit.--
(1) Establishment.--There is established, within Bureau of
Customs and Border Protection of the Department of Homeland
Security, the Office of Container Evaluation and Enforcement,
which shall receive and process images of maritime cargo
containers received from CSI ports.
(2) Authorization of appropriations.--There are
appropriated, out of any money in the Treasury not otherwise
appropriated, for the fiscal year ending September 30, 2006,
$5,000,000, to remain available until expended, to hire and
train customs inspectors to carry out the responsibilities
described in paragraph (1). The amount provided under this
heading is designated as an emergency requirement pursuant to
section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.
(c) Port Security Summit.--Not later than 90 days after the
date of the enactment of this Act, the Secretary of Homeland
Security shall convene a port security summit with
representatives from the major international shipping
companies to address--
(1) gaps in port security; and
(2) the means to implement the provisions of this section.
(d) Rulemaking.--
(1) Draft regulations.--Not later than 180 days after the
date of the enactment of this Act, the Secretary of Homeland
Security shall submit, to the Committee on Commerce, Science,
and Transportation of the Senate and the Committee on
Homeland Security of the House of Representatives, draft
regulations to carry out subsection (a) and a detailed plan
to implement such regulations.
(2) Final regulations.--Not later than 3 years after the
date of the enactment of this Act, the Secretary of Homeland
Security shall issue final regulations to carry out
subsection (a).
______

SA 3725. Mr. SMITH (for himself and Mr. Wyden) submitted an amendment
intended to be proposed by him to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; which was ordered to lie on the table; as
follows:

On page 141, between lines 5 and 6, insert the following:

EMERGENCY DISASTER ASSISTANCE

(a) The Secretary of Commerce shall make a direct payment
to the Pacific States Marine Fisheries Commission for
distribution to mitigate the economic losses caused by
Federal fisheries restrictions put in place to meet the needs
of Klamath River Fall Chinook Salmon. The money provided to
the Pacific States Marine Fisheries Commission shall be
distributed to--
(1) persons or entities, including federally recognized
Indian tribes, which have experienced significant economic
hardship as a result of Federal fisheries closures or fishing
restrictions;
(2) small businesses including fishermen, fish processors,
and related businesses serving the fishing industry
including, but not limited to, cold storage facilities, ice
houses, docks, and other related shore-side fishery support
facilities and infrastructure; and
(3) State and local governments adversely affected by
reductions in fish landing fees and other fishing-related
revenue.
(b) Payments authorized by this section may be used only in
areas declared by the Governor of a State to be in a state of
emergency due to Klamath River basin conditions and
limitations on ocean commercial and sport salmon fishing.
(c) Such payments may be made for the purposes described in
section 312(a)(2) of the Magnuson-Stevens Fishery
Conservation and Management Act (16 U.S.C. 1861a(a)(2)).
(d) Not more than 4 percent of such payments provided to
the Pacific States Marine Fisheries Commission for disaster
relief distributions may be used for administrative expenses,
and none of such payments may be used for lobbying activities
or representational expenses. Any funds not distributed by
the end of fiscal year 2008 shall be returned to the
Treasury.
(e) The Secretary of Commerce shall require the Pacific
States Marine Fisheries Commission to, not later than 6
months after receiving a payment authorized by this section,
and every 6 months thereafter, submit to the Secretary of
Commerce and the Committee on Appropriations of the House of
Representatives and the Senate a report listing the persons
and entities to whom the payment was distributed and the
rationale for such distributions.
______

SA 3726. Mr. SMITH (for himself and Mr. Wyden) submitted an amendment
intended to be proposed by him to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; which was ordered to lie on the table; as
follows:

On page 141, between lines 5 and 6, insert the following:

EMERGENCY DISASTER ASSISTANCE

(a) The Secretary of Commerce shall make a direct payment
to the Pacific States Marine Fisheries Commission for
distribution to mitigate the economic losses caused by
Federal fisheries restrictions put in place to meet the needs
of Klamath River Fall Chinook Salmon. The money provided to
the Pacific States Marine Fisheries Commission shall be
distributed to--
(1) persons or entities, including federally recognized
Indian tribes, which have experienced significant economic
hardship as a result of Federal fisheries closures or fishing
restrictions;
(2) small businesses including fishermen, fish processors,
and related businesses serving the fishing industry
including, but not limited to, cold storage facilities, ice
houses, docks, and other related shoreside fishery support
facilities and infrastructure; and
(3) State and local governments adversely affected by
reductions in fish landing fees and other fishing-related
revenue.
(b) Payments authorized by this section may be used only in
areas declared by the Governor of a State to be in a state of
emergency due to Klamath River basin conditions and
limitations on ocean commercial and sport salmon fishing.
(c) Such payments may be made for the purposes described in
section 312(a)(2) of the Magnuson-Stevens Fishery
Conservation and Management Act (16 U.S.C. 1861a(a)(2)).
(d) Not more than 4 percent of such payments provided to
the Pacific States Marine Fisheries Commission for disaster
relief distributions may be used for administrative expenses,
and none of such payments may be used for lobbying activities
or representational expenses. Any funds not distributed by
the end of fiscal year 2008 shall be returned to the
Treasury.
(e) The Secretary of Commerce shall require the Pacific
States Marine Fisheries Commission to, not later than 6
months after receiving a payment authorized by this section,
and every 6 months thereafter, submit to the Secretary of
Commerce and the Committee on Appropriations of the House of
Representatives and the Senate a report listing the persons
and entities to whom the payment was distributed and the
rationale for such distributions.
(f) For the purposes of the Internal Revenue Code of 1986--
(1) gross income shall not include any amount received as a
payment or distribution under subsection (a); and
(2) rules similar to the rules of subsections (g)(3) and
(h) of section 139 of such Code shall apply with respect to
any amount excluded under subparagraph (1).
(g) There is appropriated to the Secretary of Commerce
$81,000,000 to make payments under this section for fisheries
disaster assistance. The amount provided under this
subsection is designated as an emergency requirement pursuant
to section 402 of H. Con. Res. 95 (109th Congress), the
concurrent resolution on the budget for fiscal year 2006.
______

SA 3727. Mr. DODD (for himself and Mr. Lott) submitted an amendment
intended to be proposed by him to the bill H.R. 4939, making emergency
supplemental appropriations for the fiscal year ending September 30,
2006, and for other purposes; which was ordered to lie on the table; as
follows:

On page 203, strike line 8 and insert the following:

INDEPENDENT AGENCIES

Election Assistance Commission

Election Assistance

For purposes of making discretionary payments to States
affected by Hurricane Katrina and other hurricanes during the
2005 season to restore and replace supplies, materials,
records, equipment, and technology used in the administration
of Federal elections and to ensure the full participation of
individuals displaced by such hurricanes, $30,000,000:
Provided, That any such funds shall be used in a manner that
is consistent with title III of the Help America Vote Act

[[Page S3759]]

of 2002: Provided further, That the amount provided under
this heading is designated as an emergency requirement
pursuant to section 402 of H. Con. Res. 95 (109th Congress),
the concurrent resolution on the budget for fiscal year 2006.

____________________