American Jobs Creation Act of 2003
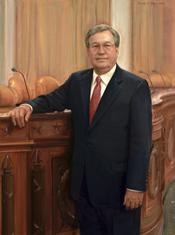 Rep. William M. Thomas (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Placed on the Union Calendar, Calendar No. 226.
November 21, 2003
View full timeline
Introduced in House
July 25, 2003
Referred to the House Committee on Ways and Means.
July 25, 2003
Committee Consideration and Mark-up Session Held.
October 28, 2003
Ordered to be Reported (Amended) by the Yeas and Nays: 24 - 15.
October 28, 2003
Reported (Amended) by the Committee on Ways and Means. H. Rept. 108-393.
November 21, 2003
Placed on the Union Calendar, Calendar No. 226.
November 21, 2003
Floor Debate
24 membersWhat members said about H.R. 2896 on the floor


 +19
Floor Debate
24 membersWhat members said about H.R. 2896 on the floor
Madam President, I see my colleague from Alabama who has been waiting patiently, as I have, throughout the day to speak. He only wants to speak for 5 minutes. I yield 5 minutes of my time, and then I…
I send an amendment to the desk. I ask for the yeas and nays. Mr. President, I yield the floor. Mr. President, last night the majority leader set up a process for moving this bill to a cloture vote.…
Madam President, finally, I have to respond to the outrageous charges made by colleagues on the other side of the aisle regarding the Medicare statement I delivered on the Senate floor yesterday. I…
Mr. Speaker, first let me compliment the gentleman from Missouri (Mr. Blunt), the sponsor of this legislation, and the gentleman from Tennessee (Mr. Ford) for reaching, I think, a fair compromise on…
Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, I am glad to be here to talk about this bill. This is a tax bill. It is a tax bill that really is an important step toward what we…
Show 8 more
Mr. Speaker, pursuant to House Resolution 370, I call up the bill (H.R. 7) to amend the Internal Revenue Code of 1986 to provide incentives for charitable contributions by individuals and businesses,…
Mr. Speaker, today, I am proud to introduce legislation that will protect American jobs and will create new job opportunities for those Americans in search of employment. The American Competition…
Mr. President, parliamentary inquiry. The parliamentary inquiry I would like to make is where are we right now on the bill? Are we on the motion to recommit, at this point? I understand also that a…
Mr. Speaker, first I want to thank the gentleman from Missouri (Mr. Blunt) and the gentleman from Tennessee (Mr. Ford) for their leadership on this bill. It is something that I have long waited to…
Mr. Speaker, on January 29, 2002, President Bush stood at this podium, and he told this Congress and the Nation ``our budget will run a deficit that will be small and short term.'' He had hardly…
Mr. Speaker, I rise today in support of H.R. 7, the Charitable Giving Act. This legislation takes an important step to help further the efforts begun nearly 40 years when President Johnson declared…
Mr. Speaker, will the gentlewoman yield? Mr. Speaker, I would ask, how much was the New York delegation asking, does the gentlewoman recall, for the help of the 9/ 11 victims? So that was over 10? So…
Mr. Speaker, I support this substitute. We have the largest deficit in American history which just 2 years ago was the largest surplus in American history, and we ought to do something about it, and…
Show 11 more
Mr. President, let me take a few moments to review where we are on this legislation. First, I don't want to sound melodramatic but this is an important bill. This bill would help to create and keep…

Mr. Speaker, I thank the gentlewoman for yielding me this time and for her leadership on so many important issues before this body. I rise in strong support of the underlying bill, but in opposition…
Mr. Speaker, I thank the gentleman from Missouri (Mr. Blunt) for yielding me this time. And I thank the leadership on my side, the gentleman from California (Mr. Stark) and the gentleman from…

Mr. Speaker, charitable organizations are vital to the health and well-being of American citizens. Charity benefits both the giver and the receiver in like proportions. The act of giving elevates the…
Mr. Speaker, I rise for the purpose of inquiring of the majority leader the schedule for the week to come. I yield to the gentleman from Texas. Mr. Speaker, I thank the gentleman for that…
Mr. Speaker, it is disconcerting when someone from the other side tries to tell us we are not taking care of problems when we are. Members will find that what was just stated was taken care of in a…
Mr. President, I thank the Senator from Louisiana for her courtesy. I will contain my time to 5 minutes and ask that I be notified at 4 minutes. I wish to say while the distinguished chairman of the…
Mr. Speaker, I always thought that charitable giving came from the heart and not through tax breaks in the Federal Tax Code. I come to the floor today to oppose this bill and I feel somewhat like the…
Mr. Speaker, I thank the gentleman from Georgia (Mr. Linder) for yielding me the customary 30 minutes, and I yield myself such time as I may consume. (Ms. SLAUGHTER asked and was given permission to…
Mr. Speaker, will the gentleman yield? Mr. Speaker, the House will convene on Tuesday at 12:30 for morning hour debates and 2 p.m. for legislative business. We will consider several measures under…
Mr. Speaker, I rise proudly as an original cosponsor of the Charitable Giving Act and also in strong support of Cardin-Doggett substitute. I signed on as an original cosponsor of H.R. 7 because our…
Bill Text
2 versions available
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 2896 Reported in House (RH)]

Union Calendar No. 226
108th CONGRESS
1st Session
H. R. 2896

[Report No. 108-393]

To amend the Internal Revenue Code of 1986 to remove impediments in
such Code and make our manufacturing, service, and high-technology
businesses and workers more competitive and productive both at home and
abroad.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

July 25, 2003

Mr. Thomas introduced the following bill; which was referred to the
Committee on Ways and Means

November 21, 2003

Reported with an amendment, committed to the Committee of the Whole
House on the State of the Union, and ordered to be printed
[Strike out all after the enacting clause and insert the part printed
in italic]
[For text of introduced bill, see copy of bill as introduced on July
25, 2003]

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to remove impediments in
such Code and make our manufacturing, service, and high-technology
businesses and workers more competitive and productive both at home and
abroad.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; ETC.

(a) Short Title.--This Act may be cited as the ``American Jobs
Creation Act of 2003''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this Act an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.
(c) Table of Contents.--

Sec. 1. Short title; etc.

TITLE I--CORPORATE REFORM AND GROWTH INCENTIVES

Subtitle A--Reduction in Corporate Income Tax Rates

Sec. 1001. Reduced corporate income tax rate for domestic production
activities income.
Sec. 1002. Reduced corporate income tax rate for small corporations.

Subtitle B--Small Business Expensing

Sec. 1011. 2-year extension of increased expensing for small business.

Subtitle C--Depreciation

Sec. 1021. Recovery period for depreciation of certain leasehold
improvements and restaurant property.

Subtitle D--Alternative Minimum Tax Relief

Sec. 1031. Net operating losses and foreign tax credit under
alternative minimum tax.
Sec. 1032. Expansion of exemption from alternative minimum tax for
small corporations.
Sec. 1033. Income averaging for farmers not to increase alternative
minimum tax.

Subtitle E--S Corporation Reform and Simplification

Sec. 1041. Members of family treated as 1 shareholder.
Sec. 1042. Increase in number of eligible shareholders to 100.
Sec. 1043. Expansion of bank S corporation eligible shareholders to
include IRAs.
Sec. 1044. Disregard of unexercised powers of appointment in
determining potential current beneficiaries
of ESBT.
Sec. 1045. Transfer of suspended losses incident to divorce, etc.
Sec. 1046. Use of passive activity loss and at-risk amounts by
qualified subchapter S trust income
beneficiaries.
Sec. 1047. Exclusion of investment securities income from passive
income test for bank S corporations.
Sec. 1048. Treatment of bank director shares.
Sec. 1049. Relief from inadvertently invalid qualified subchapter S
subsidiary elections and terminations.
Sec. 1050. Information returns for qualified subchapter S subsidiaries.
Sec. 1051. Repayment of loans for qualifying employer securities.

Subtitle F--Protecting Employee Benefits

Sec. 1061. Treatment of nonqualified deferred compensation plans.
Sec. 1062. Exclusion of incentive stock options and employee stock
purchase plan stock options from wages.
Sec. 1063. Extension of transfers of excess pension assets to retiree
health accounts.

Subtitle G--Treatment of Active Income

Sec. 1071. Member states of the European Union treated as a single
country for certain purposes
Sec. 1072. Look-thru treatment of payments between related controlled
foreign corporations under foreign personal
holding company income rules.
Sec. 1073. Look-thru treatment for sales of partnership interests.
Sec. 1074. Repeal of foreign personal holding company rules and foreign
investment company rules.
Sec. 1075. Clarification of treatment of pipeline transportation
income.
Sec. 1076. Determination of foreign personal holding company income
with respect to transactions in
commodities.
Sec. 1077. Repeal of CFC rules on foreign base company shipping income.
Sec. 1078. Modification of subpart F exemption for active financing.
Sec. 1079. Partial exclusion for income attributable to films used
outside the United States.

Subtitle H--Reduction of Double Taxation of Earnings

Sec. 1081. Interest expense allocation rules.
Sec. 1082. Recharacterization of overall domestic loss.
Sec. 1083. Reduction to 2 foreign tax credit baskets.
Sec. 1084. Look-thru rules to apply to dividends from noncontrolled
section 902 corporations.
Sec. 1085. Attribution of stock ownership through partnerships to apply
in determining section 902 and 960 credits.
Sec. 1086. Clarification of treatment of certain transfers of
intangible property.
Sec. 1087. United States property not to include certain assets
acquired by dealers in ordinary course of
trade or business.
Sec. 1088. Election not to use average exchange rate for foreign tax
paid other than in functional currency.
Sec. 1089. Repeal of withholding tax on dividends from certain foreign
corporations.
Sec. 1090. Provide equal treatment for interest paid by foreign
partnerships and foreign corporations.
Sec. 1091. Treatment of certain dividends of regulated investment
companies.

Subtitle I--Other Provisions

Sec. 1101. Special rules for livestock sold on account of weather-
related conditions.
Sec. 1102. Payment of dividends on stock of cooperatives without
reducing patronage dividends.
Sec. 1103. Vaccine tax to apply to Hepatitis A vaccine.
Sec. 1104. Expansion of human clinical trials qualifying for orphan
drug credit.
Sec. 1105. Distributions from publicly traded partnerships treated as
qualifying income of regulated investment
companies.
Sec. 1106. Improvements related to real estate investment trusts.
Sec. 1107. Simplification of excise tax imposed on bows and arrows.
Sec. 1108. Repeal of excise tax on fishing tackle boxes.
Sec. 1109. Income tax credit to distilled spirits wholesalers for cost
of carrying Federal excise taxes on bottled
distilled spirits.
Sec. 1110. Capital gain treatment under section 631(b) to apply to
outright sales by landowners.
Sec. 1111. Sonar devices suitable for finding fish.
Sec. 1112. Taxation of certain settlement funds.
Sec. 1113. Suspension of occupational taxes relating to distilled
spirits, wine, and beer.

TITLE II--PROVISIONS TO REDUCE TAX AVOIDANCE THROUGH CORPORATE EARNINGS
STRIPPING AND EXPATRIATION

Sec. 2001. Reduction in potential for earnings stripping by further
limiting deduction for interest on certain
indebtedness.
Sec. 2002. Tax treatment of expatriated entities and their foreign
parents.
Sec. 2003. Excise tax on stock compensation of insiders in expatriated
corporations.
Sec. 2004. Reinsurance of United States risks in foreign jurisdictions.
Sec. 2005. Revision of tax rules on expatriation of individuals.
Sec. 2006. Reporting of taxable mergers and acquisitions.
Sec. 2007. Studies.

TITLE III--PROVISIONS RELATING TO TAX SHELTERS

Subtitle A--Taxpayer-Related Provisions

Sec. 3001. Penalty for failing to disclose reportable transactions.
Sec. 3002. Accuracy-related penalty for listed transactions, other
reportable transactions having a
significant tax avoidance purpose, etc.
Sec. 3003. Tax shelter exception to confidentiality privileges relating
to taxpayer communications.
Sec. 3004. Statute of limitations for taxable years for which required
listed transactions not reported.
Sec. 3005. Disclosure of reportable transactions.
Sec. 3006. Failure to furnish information regarding reportable
transactions.
Sec. 3007. Modification of penalty for failure to maintain lists of
investors.
Sec. 3008. Penalty on promoters of tax shelters.
Sec. 3009. Modifications of substantial understatement penalty for
nonreportable transactions.
Sec. 3010. Modification of actions to enjoin certain conduct related to
tax shelters and reportable transactions.
Sec. 3011. Penalty on failure to report interests in foreign financial
accounts.
Sec. 3012. Regulation of individuals practicing before the Department
of the Treasury.

Subtitle B--Other Provisions

Sec. 3021. Treatment of stripped interests in bond and preferred stock
funds, etc.
Sec. 3022. Minimum holding period for foreign tax credit on withholding
taxes on income other than dividends.
Sec. 3023. Disallowance of certain partnership loss transfers.
Sec. 3024. No reduction of basis under section 734 in stock held by
partnership in corporate partner.
Sec. 3025. Repeal of special rules for FASITS.
Sec. 3026. Limitation on transfer of built-in losses on REMIC
residuals.
Sec. 3027. Clarification of banking business for purposes of
determining investment of earnings in
United States property.
Sec. 3028. Modifications related to certain small insurance companies.
Sec. 3029. Definition of insurance company for section 831.
Sec. 3030. Denial of deduction for interest on underpayments
attributable to nondisclosed reportable
transactions.
Sec. 3031. Clarification of rules for payment of estimated tax for
certain deemed asset sales.
Sec. 3032. Recognition of gain from the sale of a principal residence
acquired in a like-kind exchange within 5
years of sale.
Sec. 3033. Prevention of mismatching of interest and original issue
discount deductions and income inclusions
in transactions with related foreign
persons.
Sec. 3034. Exclusion from gross income for interest on overpayments of
income tax by individuals.
Sec. 3035. Deposits made to suspend running of interest on potential
underpayments.
Sec. 3036. Partial payment of tax liability in installment agreements.
Sec. 3037. Extension of IRS user fees.

TITLE IV--TRADE ENHANCEMENT AND COMPLIANCE PROVISIONS

Sec. 4001. Repeal of exclusion for extraterritorial income.
Sec. 4002. COBRA fees.

TITLE I--CORPORATE REFORM AND GROWTH INCENTIVES

Subtitle A--Reduction in Corporate Income Tax Rates

SEC. 1001. REDUCED CORPORATE INCOME TAX RATE FOR DOMESTIC PRODUCTION
ACTIVITIES INCOME.

(a) Limitation on Tax on Qualified Production Activities Income.--
Section 11 is amended by redesignating subsections (c) and (d) as
subsections (d) and (e), respectively, and by inserting after
subsection (b) the following new subsection:
``(c) Limitation on Tax on Qualified Production Activities
Income.--
``(1) In general.--If a corporation has qualified
production activities income for any taxable year, the tax
imposed by this section shall not exceed the sum of--
``(A) a tax computed at the rates and in the manner
as if this subsection had not been enacted on the
taxable income reduced by the amount of qualified
production activities income, plus
``(B) a tax equal to 32 percent (34 percent in the
case of taxable years beginning before January 1, 2007)
of the qualified production activities income (or, if
less, taxable income).
``(2) Qualified production activities income.--
``(A) In general.--The term `qualified production
activities income' for any taxable year means an amount
equal to the excess (if any) of--
``(i) the taxpayer's domestic production
gross receipts for such taxable year, over
``(ii) the sum of--
``(I) the cost of goods sold that
are allocable to such receipts,
``(II) other deductions, expenses,
or losses directly allocable to such
receipts, and
``(III) a ratable portion of other
deductions, expenses, and losses that
are not directly allocable to such
receipts or another class of income.
``(B) Allocation method.--The Secretary shall
prescribe rules for the proper allocation of items of
income, deduction, expense, and loss for purposes of
determining income attributable to domestic production
activities.
``(3) Domestic production gross receipts.--For purposes of
this subsection, the term `domestic production gross receipts'
means the gross receipts of the taxpayer which are derived
from--
``(A) any lease, rental, license, sale, exchange,
or other disposition of--
``(i) qualifying production property which
was manufactured, produced, grown, or extracted
in whole or in significant part by the taxpayer
within the United States, or
``(ii) any qualified film produced by the
taxpayer, or
``(B) construction, engineering, or architectural
services performed in the United States for
construction projects in the United States.
``(4) Qualifying production property.--For purposes of this
subsection, the term `qualifying production property' means--
``(A) tangible personal property,
``(B) any computer software, and
``(C) any property described in section 168(f)(4).
``(5) Qualified film.--For purposes of this subsection--
``(A) In general.--The term `qualified film' means
any property described in section 168(f)(3) if not less
than 50 percent of the total compensation relating to
the production of such property is compensation for
services performed in the United States by actors,
production personnel, directors, and producers.
``(B) Exception.--Such term does not include
property with respect to which records are required to
be maintained under section 2257 of title 18, United
States Code.
``(6) Related persons.--For purposes of this subsection--
``(A) In general.--The term `domestic production
gross receipts' shall not include any gross receipts of
the taxpayer derived from property leased, licensed, or
rented by the taxpayer for use by any related person.
``(B) Related person.--For purposes of subparagraph
(A), a person shall be treated as related to another
person if such persons are treated as a single employer
under subsection (a) or (b) of section 52 or subsection
(m) or (o) of section 414, except that determinations
under subsections (a) and (b) of section 52 shall be
made without regard to section 1563(b).''.
(b) Special Rule Relating to Election To Treat Cutting of Timber as
a Sale or Exchange.--In the case of a corporation, any election under
section 631(a) of the Internal Revenue Code of 1986 made for a taxable
year ending on or before the date of the enactment of this Act may be
revoked by the taxpayer for any taxable year ending after such date.
For purposes of determining whether such taxpayer may make a further
election under such section, such election (and any revocation under
this section) shall not be taken into account.
(c) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1002. REDUCED CORPORATE INCOME TAX RATE FOR SMALL CORPORATIONS.

(a) In General.--Subsection (b) of section 11 (relating to tax
imposed on corporations) is amended by redesignating paragraph (2) as
paragraph (6) and by striking paragraph (1) and inserting the following
new paragraphs:
``(1) For taxable years beginning after 2011.--In the case
of taxable years beginning after 2011, the amount of the tax
imposed by subsection (a) shall be determined in accordance
with the following table:

``If taxable income is:             The tax is:
Not over $50,000...............
15% of taxable income.
Over $50,000 but not over
$75,000.
$7,500, plus 25% of the excess
over $50,000.
Over $75,000 but not over
$20,000,000.
$13,750, plus 32% of the excess
over $75,000.
Over $20,000,000...............
$6,389,750, plus 35% of the
excess over
$20,000,000.
``(2) For taxable years beginning in 2009, 2010, or 2011.--
In the case of taxable years beginning in 2009, 2010, or 2011,
the amount of the tax imposed by subsection (a) shall be
determined in accordance with the following table:

``If taxable income is:             The tax is:
Not over $50,000...............
15% of taxable income.
Over $50,000 but not over
$75,000.
$7,500, plus 25% of the excess
over $50,000.
Over $75,000 but not over
$5,000,000.
$13,750, plus 32% of the excess
over $75,000.
Over $5,000,000 but not over
$10,000,000.
$1,589,750, plus 34% of the
excess over $5,000,000.
Over $10,000,000...............
$3,289,750, plus 35% of the
excess over
$10,000,000.
``(3) For taxable years beginning in 2007 or 2008.--In the
case of taxable years beginning in 2007 or 2008, the amount of
the tax imposed by subsection (a) shall be determined in
accordance with the following table:

``If taxable income is:             The tax is:
Not over $50,000...............
15% of taxable income.
Over $50,000 but not over
$75,000.
$7,500, plus 25% of the excess
over $50,000.
Over $75,000 but not over
$1,000,000.
$13,750, plus 32% of the excess
over $75,000.
Over $1,000,000 but not over
$10,000,000.
$309,750, plus 34% of the
excess over $1,000,000.
Over $10,000,000...............
$3,369,750, plus 35% of the
excess over
$10,000,000.
``(4) For taxable years beginning in 2004, 2005, or 2006.--
In the case of taxable years beginning in 2004, 2005, or 2006,
the amount of the tax imposed by subsection (a) shall be
determined in accordance with the following table:

``If taxable income is:             The tax is:
Not over $50,000...............
15% of taxable income.
Over $50,000 but not over
$75,000.
$7,500, plus 25% of the excess
over $50,000.
Over $75,000 but not over
$1,000,000.
$13,750, plus 33% of the excess
over $75,000.
Over $1,000,000 but not over
$10,000,000.
$319,000, plus 34% of the
excess over $1,000,000.
Over $10,000,000...............
$3,379,000, plus 35% of the
excess over
$10,000,000.
``(5) Phaseout of lower rates for certain taxpayers.--
``(A) General rule for years before 2012.--
``(i) In general.--In the case of taxable
years beginning before 2012 with respect to a
corporation which has taxable income in excess
of the applicable amount for any taxable year,
the amount of tax determined under paragraph
(1), (2), (3) or (4) for such taxable year
shall be increased by the lesser of (I) 5
percent of such excess, or (II) the maximum
increase amount.
``(ii) Maximum increase amount.--For
purposes of clause (i)--

------------------------------------------------------------------------
The maximum
``In the case of any taxable      The applicable    increase amount
year     beginning during:          amount is:            is:
------------------------------------------------------------------------
2004, 2005, or 2006...............      $1,000,000          $21,000
2007 or 2008......................      $1,000,000          $30,250
2009, 2010, or 2011...............      $5,000,000         $110,250.
------------------------------------------------------------------------

``(B) Higher income corporations.--In the case of a
corporation which has taxable income in excess of
$20,000,000 ($15,000,000 in the case of taxable years
beginning before 2012), the amount of the tax
determined under the foregoing provisions of this
subsection shall be increased by an additional amount
equal to the lesser of (i) 3 percent of such excess, or
(ii) $610,250 ($100,000 in the case of taxable years
beginning before 2012).''.
(b) Conforming Amendments.--
(1) Section 904(b)(3)(D)(ii) is amended to read as follows:
``(ii) in the case of a corporation,
section 1201(a) applies to such taxable
year.''.
(2) Section 1201(a) is amended by striking ``the last 2
sentences of section 11(b)(1)'' and inserting ``section
11(b)(5)''.
(3) Section 1561(a) is amended--
(A) by striking ``the last 2 sentences of section
11(b)(1)'' and inserting ``section 11(b)(5)'', and
(B) by striking ``such last 2 sentences'' and
inserting ``section 11(b)(5)''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

Subtitle B--Small Business Expensing

SEC. 1011. 2-YEAR EXTENSION OF INCREASED EXPENSING FOR SMALL BUSINESS.

Subsections (b), (c), and (d) of section 179 (as amended by the
Jobs and Growth Tax Relief Reconciliation Act of 2003) are each amended
by striking ``2006'' each place it appears and inserting ``2008''.

Subtitle C--Depreciation

SEC. 1021. RECOVERY PERIOD FOR DEPRECIATION OF CERTAIN LEASEHOLD
IMPROVEMENTS AND RESTAURANT PROPERTY.

(a) 15-Year Recovery Period.--Subparagraph (E) of section 168(e)(3)
(relating to classification of certain property) is amended by striking
``and'' at the end of clause (ii), by striking the period at the end of
clause (iii) and inserting a comma, and by adding at the end the
following new clauses:
``(iv) any qualified leasehold improvement
property placed in service before January 1,
2006, and
``(v) any qualified restaurant property
placed in service before January 1, 2006.''
(b) Qualified Leasehold Improvement Property.--Subsection (e) of
section 168 is amended by adding at the end the following new
paragraph:
``(6) Qualified leasehold improvement property.--The term
`qualified leasehold improvement property' has the meaning
given such term in section 168(k)(3) except that the following
special rules shall apply:
``(A) Improvements made by lessor.--In the case of
an improvement made by the person who was the lessor of
such improvement when such improvement was placed in
service, such improvement shall be qualified leasehold
improvement property (if at all) only so long as such
improvement is held by such person.
``(B) Exception for changes in form of business.--
Property shall not cease to be qualified leasehold
improvement property under subparagraph (A) by reason
of--
``(i) death,
``(ii) a transaction to which section
381(a) applies,
``(iii) a mere change in the form of
conducting the trade or business so long as the
property is retained in such trade or business
as qualified leasehold improvement property and
the taxpayer retains a substantial interest in
such trade or business,
``(iv) the acquisition of such property in
an exchange described in section 1031, 1033, or
1038 to the extent that the basis of such
property includes an amount representing the
adjusted basis of other property owned by the
taxpayer or a related person, or
``(v) the acquisition of such property by
the taxpayer in a transaction described in
section 332, 351, 361, 721, or 731 (or the
acquisition of such property by the taxpayer
from the transferee or acquiring corporation in
a transaction described in such section), to
the extent that the basis of the property in
the hands of the taxpayer is determined by
reference to its basis in the hands of the
transferor or distributor.''.
(c) Qualified Restaurant Property.--Subsection (e) of section 168
(as amended by subsection (b)) is further amended by adding at the end
the following new paragraph:
``(7) Qualified restaurant property.--The term `qualified
restaurant property' means any section 1250 property which is
an improvement to a building if--
``(A) such improvement is placed in service more
than 3 years after the date such building was first
placed in service, and
``(B) more than 50 percent of the building's square
footage is devoted to preparation of, and seating for
on-premises consumption of, prepared meals.''.
(d) Requirement To Use Straight Line Method.--
(1) Paragraph (3) of section 168(b) is amended by adding at
the end the following new subparagraphs:
``(G) Qualified leasehold improvement property
described in subsection (e)(6).
``(H) Qualified restaurant property described in
subsection (e)(7).''.
(2) Subparagraph (A) of section 168(b)(2) is amended by
inserting before the comma ``not referred to in paragraph
(3)''.
(e) Alternative System.--The table contained in section
168(g)(3)(B) is amended by adding at the end the following new items:

``(E)(iv)..................................       39
``(E)(v)...................................     39''.
(f) Effective Date.--The amendments made by this section shall
apply to property placed in service after the date of the enactment of
this Act.

Subtitle D--Alternative Minimum Tax Relief

SEC. 1031. NET OPERATING LOSSES AND FOREIGN TAX CREDIT UNDER
ALTERNATIVE MINIMUM TAX.

(a) Net Operating Losses.--
(1) In general.--Subparagraph (A) of section 56(d)(1) is
amended to read as follows:
``(A) the amount of such deduction shall not exceed
the applicable percentage (determined under paragraph
(3)) of the alternative minimum taxable income
determined without regard to such deduction, and''.
(2) Applicable percentage.--Subsection (d) of section 56 is
amended by adding at the end the following new paragraph:
``(3) Applicable percentage.--For purposes of paragraph
(1)(A)--

``For taxable years beginning
The applicable
in calendar year--
percentage is--
2005, 2006, or 2007............................      92
2008 or 2009...................................      94
2010...........................................      96
2011...........................................      98
2012 or thereafter.............................  100.''
(b) Foreign Tax Credit.--
(1) Subsection (a) of section 59 is amended by striking
paragraph (2) and by redesignating paragraphs (3) and (4) as
paragraphs (2) and (3), respectively.
(2) Section 53(d)(1)(B)(i)(II) is amended by striking ``and
if section 59(a)(2) did not apply''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 1032. EXPANSION OF EXEMPTION FROM ALTERNATIVE MINIMUM TAX FOR
SMALL CORPORATIONS.

(a) In General.--Subparagraphs (A) and (B) of section 55(e)(1) are
each amended by striking ``$7,500,000'' each place it appears and
inserting ``$20,000,000''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2004.

SEC. 1033. INCOME AVERAGING FOR FARMERS NOT TO INCREASE ALTERNATIVE
MINIMUM TAX.

(a) In General.--Subsection (c) of section 55 (defining regular
tax) is amended by redesignating paragraph (2) as paragraph (3) and by
inserting after paragraph (1) the following new paragraph:
``(2) Coordination with income averaging for farmers.--
Solely for purposes of this section, section 1301 (relating to
averaging of farm income) shall not apply in computing the
regular tax liability.''.
(b) Effective Date.--The amendment made by subsection (a) shall
apply to taxable years beginning after December 31, 2002.

Subtitle E--S Corporation Reform and Simplification

SEC. 1041. MEMBERS OF FAMILY TREATED AS 1 SHAREHOLDER.

(a) In General.--Paragraph (1) of section 1361(c) (relating to
special rules for applying subsection (b)) is amended to read as
follows:
``(1) Members of family treated as 1 shareholder.--
``(A) In general.--For purpose of subsection
(b)(1)(A)--
``(i) except as provided in clause (ii), a
husband and wife (and their estates) shall be
treated as 1 shareholder, and
``(ii) in the case of a family with respect
to which an election is in effect under
subparagraph (D), all members of the family
shall be treated as 1 shareholder.
``(B) Members of the family.--For purpose of
subparagraph (A)(ii)--
``(i) In general.--The term `members of the
family' means the common ancestor, lineal
descendants of the common ancestor, and the
spouses (or former spouses) of such lineal
descendants or common ancestor.
``(ii) Common Ancestor.--For purposes of
this paragraph, an individual shall not be
considered a common ancestor if, as of the
later of the effective date of this paragraph
or the time the election under section 1362(a)
is made, the individual is more than 3
generations removed from the youngest
generation of shareholders who would (but for
this clause) be members of the family. For
purposes of the preceding sentence, a spouse
(or former spouse) shall be treated as being of
the same generation as the individual to which
such spouse is (or was) married.
``(C) Effect of adoption, etc.--In determining
whether any relationship specified in subparagraph (B)
exists, the rules of section 152(b)(2) shall apply.
``(D) Election.--An election under subparagraph
(A)(ii)--
``(i) may, except as otherwise provided in
regulations prescribed by the Secretary, be
made by any member of the family, and
``(ii) shall remain in effect until
terminated as provided in regulations
prescribed by the Secretary.''.
(b) Relief From Inadvertent Invalid Election or Termination.--
Section 1362(f) (relating to inadvertent invalid elections or
terminations), as amended by section 1049, is amended--
(1) by inserting ``or section 1361(c)(1)(A)(ii)'' after
``section 1361(b)(3)(B)(ii),'' in paragraph (1), and
(2) by inserting ``or section 1361(c)(1)(D)(iii)'' after
``section 1361(b)(3)(C),'' in paragraph (1)(B).
(c) Effective Dates.--
(1) Subsection (a).--The amendment made by subsection (a)
shall apply to taxable years beginning after December 31, 2003.
(2) Subsection (b).--The amendments made by subsection (b)
shall apply to elections and terminations made after December
31, 2003.

SEC. 1042. INCREASE IN NUMBER OF ELIGIBLE SHAREHOLDERS TO 100.

(a) In General.--Section 1361(b)(1)(A) (defining small business
corporation) is amended by striking ``75'' and inserting ``100''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1043. EXPANSION OF BANK S CORPORATION ELIGIBLE SHAREHOLDERS TO
INCLUDE IRAS.

(a) In General.--Section 1361(c)(2)(A) (relating to certain trusts
permitted as shareholders) is amended by inserting after clause (v) the
following new clause:
``(vi) In the case of a corporation which
is a bank (as defined in section 581), a trust
which constitutes an individual retirement
account under section 408(a), including one
designated as a Roth IRA under section 408A,
but only to the extent of the stock held by
such trust in such bank as of the date of the
enactment of this clause.''.
(b) Treatment as Shareholder.--Section 1361(c)(2)(B) (relating to
treatment as shareholders) is amended by adding at the end the
following new clause:
``(vi) In the case of a trust described in
clause (vi) of subparagraph (A), the individual
for whose benefit the trust was created shall
be treated as a shareholder.''.
(c) Sale of Bank Stock in IRA Relating to S Corporation Election
Exempt From Prohibited Transaction Rules.--Section 4975(d) (relating to
exemptions) is amended by striking ``or'' at the end of paragraph (14),
by striking the period at the end of paragraph (15) and inserting ``;
or'', and by adding at the end the following new paragraph:
``(16) a sale of stock held by a trust which constitutes an
individual retirement account under section 408(a) to the
individual for whose benefit such account is established if--
``(A) such stock is in a bank (as defined in
section 581),
``(B) such stock is held by such trust as of the
date of the enactment of this paragraph,
``(C) such sale is pursuant to an election under
section 1362(a) by such bank,
``(D) such sale is for fair market value at the
time of sale (as established by an independent
appraiser) and the terms of the sale are otherwise at
least as favorable to such trust as the terms that
would apply on a sale to an unrelated party,
``(E) such trust does not pay any commissions,
costs, or other expenses in connection with the sale,
and
``(F) the stock is sold in a single transaction for
cash not later than 120 days after the S corporation
election is made.''.
(d) Conforming Amendment.--Section 512(e)(1) is amended by
inserting ``1361(c)(2)(A)(vi) or'' before ``1361(c)(6)''.
(e) Effective Date.--The amendments made by this section shall take
effect on the date of the enactment of this Act.

SEC. 1044. DISREGARD OF UNEXERCISED POWERS OF APPOINTMENT IN
DETERMINING POTENTIAL CURRENT BENEFICIARIES OF ESBT.

(a) In General.--Section 1361(e)(2) (defining potential current
beneficiary) is amended--
(1) by inserting ``(determined without regard to any power
of appointment to the extent such power remains unexercised at
the end of such period)'' after ``of the trust'' in the first
sentence, and
(2) by striking ``60-day'' in the second sentence and
inserting ``1-year''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 1045. TRANSFER OF SUSPENDED LOSSES INCIDENT TO DIVORCE, ETC.

(a) In General.--Section 1366(d)(2) (relating to indefinite
carryover of disallowed losses and deductions) is amended to read as
follows:
``(2) Indefinite carryover of disallowed losses and
deductions.--
``(A) In general.--Except as provided in
subparagraph (B), any loss or deduction which is
disallowed for any taxable year by reason of paragraph
(1) shall be treated as incurred by the corporation in
the succeeding taxable year with respect to that
shareholder.
``(B) Transfers of stock between spouses or
incident to divorce.--In the case of any transfer
described in section 1041(a) of stock of an S
corporation, any loss or deduction described in
subparagraph (A) with respect such stock shall be
treated as incurred by the corporation in the
succeeding taxable year with respect to the
transferee.''
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1046. USE OF PASSIVE ACTIVITY LOSS AND AT-RISK AMOUNTS BY
QUALIFIED SUBCHAPTER S TRUST INCOME BENEFICIARIES.

(a) In General.--Section 1361(d)(1) (relating to special rule for
qualified subchapter S trust) is amended--
(1) by striking ``and'' at the end of subparagraph (A),
(2) by striking the period at the end of subparagraph (B)
and inserting ``, and'', and
(3) by adding at the end the following new subparagraph:
``(C) for purposes of applying sections 465 and 469
to the beneficiary of the trust, the disposition of the
S corporation stock by the trust shall be treated as a
disposition by such beneficiary.''.
(b) Effective Date.--The amendments made by this section shall
apply to transfers made after December 31, 2003.

SEC. 1047. EXCLUSION OF INVESTMENT SECURITIES INCOME FROM PASSIVE
INCOME TEST FOR BANK S CORPORATIONS.

(a) In General.--Section 1362(d)(3) (relating to where passive
investment income exceeds 25 percent of gross receipts for 3
consecutive taxable years and corporation has accumulated earnings and
profits) is amended by adding at the end the following new
subparagraph:
``(F) Exception for banks; etc.--In the case of a
bank (as defined in section 581), a bank holding
company (within the meaning of section 2(a) of the Bank
Holding Company Act of 1956 (12 U.S.C. 1841(a))), or a
financial holding company (within the meaning of
section 2(p) of such Act), the term `passive investment
income' shall not include--
``(i) interest income earned by such bank
or company, or
``(ii) dividends on assets required to be
held by such bank or company, including stock
in the Federal Reserve Bank, the Federal Home
Loan Bank, or the Federal Agricultural Mortgage
Bank or participation certificates issued by a
Federal Intermediate Credit Bank.''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1048. TREATMENT OF BANK DIRECTOR SHARES.

(a) In General.--Section 1361 (defining S corporation) is amended
by adding at the end the following new subsection:
``(f) Restricted Bank Director Stock.--
``(1) In general.--Restricted bank director stock shall not
be taken into account as outstanding stock of the S corporation
in applying this subchapter (other than section 1368(f)).
``(2) Restricted bank director stock.--For purposes of this
subsection, the term `restricted bank director stock' means
stock in a bank (as defined in section 581), a bank holding
company (within the meaning of section 2(a) of the Bank Holding
Company Act of 1956 (12 U.S.C. 1841(a))), or a financial
holding company (within the meaning of section 2(p) of such
Act), registered with the Federal Reserve System if such
stock--
``(A) is required to be held by an individual under
applicable Federal or State law in order to permit such
individual to serve as a director, and
``(B) is subject to an agreement with such bank or
company (or a corporation which controls (within the
meaning of section 368(c)) such bank or company)
pursuant to which the holder is required to sell back
such stock (at the same price as the individual
acquired such stock) upon ceasing to hold the office of
director.
``(3) Cross reference.--

``For treatment of certain
distributions with respect to restricted bank director stock, see
section 1368(f).''.
(b) Distributions.--Section 1368 (relating to distributions) is
amended by adding at the end the following new subsection:
``(f) Restricted Bank Director Stock.--If a director receives a
distribution (not in part or full payment in exchange for stock) from
an S corporation with respect to any restricted bank director stock (as
defined in section 1361(f)), the amount of such distribution--
``(1) shall be includible in gross income of the director,
and
``(2) shall be deductible by the corporation for the
taxable year of such corporation in which or with which ends
the taxable year in which such amount in included in the gross
income of the director.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 1049. RELIEF FROM INADVERTENTLY INVALID QUALIFIED SUBCHAPTER S
SUBSIDIARY ELECTIONS AND TERMINATIONS.

(a) In General.--Section 1362(f) (relating to inadvertent invalid
elections or terminations) is amended--
(1) by inserting ``, section 1361(b)(3)(B)(ii),'' after
``subsection (a)'' in paragraph (1),
(2) by inserting ``, section 1361(b)(3)(C),'' after
``subsection (d)'' in paragraph (1)(B),
(3) by amending paragraph (3)(A) to read as follows:
``(A) so that the corporation for which the
election was made is a small business corporation or a
qualified subchapter S subsidiary, as the case may be,
or'',
(4) by amending paragraph (4) to read as follows:
``(4) the corporation for which the election was made, and
each person who was a shareholder in such corporation at any
time during the period specified pursuant to this subsection,
agrees to make such adjustments (consistent with the treatment
of such corporation as an S corporation or a qualified
subchapter S subsidiary, as the case may be) as may be required
by the Secretary with respect to such period,'', and
(5) by inserting ``or a qualified subchapter S subsidiary,
as the case may be'' after ``S corporation'' in the matter
following paragraph (4).
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 1050. INFORMATION RETURNS FOR QUALIFIED SUBCHAPTER S SUBSIDIARIES.

(a) In General.--Section 1361(b)(3)(A) (relating to treatment of
certain wholly owned subsidiaries) is amended by inserting ``and in the
case of information returns required under part III of subchapter A of
chapter 61'' after ``Secretary''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1051. REPAYMENT OF LOANS FOR QUALIFYING EMPLOYER SECURITIES.

(a) In General.--Subsection (f) of section 4975 (relating to other
definitions and special rules) is amended by adding at the end the
following new paragraph:
``(7) S corporation repayment of loans for qualifying
employer securities.--A plan shall not be treated as violating
the requirements of section 401 or 409 or subsection (e)(7), or
as engaging in a prohibited transaction for purposes of
subsection (d)(3), merely by reason of any distribution (as
described in section 1368(a)) with respect to S corporation
stock that constitutes qualifying employer securities, which in
accordance with the plan provisions is used to make payments on
a loan described in subsection (d)(3) the proceeds of which
were used to acquire such qualifying employer securities
(whether or not allocated to participants). The preceding
sentence shall not apply in the case of a distribution which is
paid with respect to any employer security which is allocated
to a participant unless the plan provides that employer
securities with a fair market value of not less than the amount
of such distribution are allocated to such participant for the
year which (but for the preceding sentence) such distribution
would have been allocated to such participant.''.
(b) Effective Date.--The amendment made by this section shall apply
to distributions with respect to S corporation stock made after
December 31, 2003.

Subtitle F--Protecting Employee Benefits

SEC. 1061. TREATMENT OF NONQUALIFIED DEFERRED COMPENSATION PLANS.

(a) In General.--Subpart A of part I of subchapter D of chapter 1
is amended by adding at the end the following new section:

``SEC. 409A. INCLUSION IN GROSS INCOME OF DEFERRED COMPENSATION UNDER
NONQUALIFIED DEFERRED COMPENSATION PLANS.

``(a) Rules Relating to Constructive Receipt.--
``(1) In general.--
``(A) Gross income inclusion.--In the case of a
nonqualified deferred compensation plan, all
compensation deferred under the plan for all taxable
years (to the extent not subject to a substantial risk
of forfeiture and not previously included in gross
income) shall be includible in gross income for the
taxable year unless at all times during the taxable
year the plan meets the requirements of paragraphs (2),
(3), and (4) and is operated in accordance with such
requirements.
``(B) Interest on tax liability payable with
respect to previously deferred compensation.--
``(i) In general.--If compensation is
required to be included in gross income under
subparagraph (A) for a taxable year, the tax
imposed by this chapter for such taxable year
shall be increased by the amount of interest
determined under clause (ii).
``(ii) Interest.--For purposes of clause
(i), the interest determined under this clause
for any taxable year is the amount of interest
at the underpayment rate plus 1 percentage
point on the underpayments that would have
occurred had the deferred compensation been
includible in gross income for the taxable year
in which first deferred or, if later, the first
taxable year in which such deferred
compensation is not subject to a substantial
risk of forfeiture.
``(2) Distributions.--
``(A) In general.--The requirements of this
paragraph are met if the plan provides that
compensation deferred under the plan may not be
distributed earlier than--
``(i) separation from service as determined
by the Secretary (except as provided in
subparagraph (B)(i)),
``(ii) disability (as defined by section
223(d) of the Social Security Act),
``(iii) death,
``(iv) a specified time (or pursuant to a
fixed schedule) specified under the plan at the
date of the deferral of such compensation,
``(v) to the extent provided by the
Secretary, a change in the ownership or
effective control of the corporation, or in the
ownership of a substantial portion of the
assets of the corporation, or
``(vi) the occurrence of an unforeseeable
emergency.
``(B) Special rules.--
``(i) Specified employees.--In the case of
specified employees, the requirement of
subparagraph (A)(i) is met only if
distributions may not be made earlier than 6
months after the date of separation from
service. For purposes of the preceding
sentence, a specified employee is a key
employee (as defined in section 416(i)) of a
corporation the stock in which is publicly
traded on an established securities market or
otherwise.
``(ii) Unforeseeable emergency.--For
purposes of subparagraph (A)(vi)--
``(I) In general.--The term
`unforeseeable emergency' means a
severe financial hardship to the
participant resulting from a sudden and
unexpected illness or accident of the
participant, the participant's spouse,
or a dependent (as defined in section
152(a)) of the participant, loss of the
participant's property due to casualty,
or other similar extraordinary and
unforeseeable circumstances arising as
a result of events beyond the control
of the participant.
``(II) Limitation on
distributions.--The requirement of
subparagraph (A)(vi) is met only if, as
determined under regulations of the
Secretary, the amounts distributed with
respect to an emergency do not exceed
the amounts necessary to satisfy such
emergency plus amounts necessary to pay
taxes reasonably anticipated as a
result of the distribution, after
taking into account the extent to which
such hardship is or may be relieved
through reimbursement or compensation
by insurance or otherwise or by
liquidation of the participant's assets
(to the extent the liquidation of such
assets would not itself cause severe
financial hardship).
``(3) Acceleration of benefits.--The requirements of this
paragraph are met if the plan does not permit the acceleration
of the time or schedule of any payment under the plan, except
as provided in regulations by the Secretary.
``(4) Elections.--
``(A) In general.--The requirements of this
paragraph are met if the requirements of subparagraphs
(B) and (C) are met.
``(B) Initial deferral decision.--The requirements
of this subparagraph are met if the plan provides that
compensation for services performed during a taxable
year may be deferred at the participant's election only
if the election to defer such compensation is made
during the preceding taxable year or at such other time
as provided in regulations. In the case of the first
year in which a participant becomes eligible to
participate in the plan, such election may be made with
respect to services to be performed subsequent to the
election within 30 days after the date the participant
becomes eligible to participate in such plan.
``(C) Changes in time and form of distribution.--
The requirements of this subparagraph are met if, in
the case of a plan which permits under a subsequent
election a delay in a payment or a change in the form
of payment--
``(i) the plan requires that such election
may not take effect until at least 12 months
after the date on which the election is made,
``(ii) in the case an election related to a
payment not described in clause (ii), (iii), or
(vi) of paragraph (2)(A), the plan requires
that the first payment with respect to which
such election is made be deferred for a period
of not less than 5 years from the date such
payment would otherwise have been made, and
``(iii) the plan requires that any election
related to a payment described in paragraph
(2)(A)(iv) may not be made less than 12 months
prior to the date of the first scheduled
payment under such paragraph.
``(b) Rules Relating to Funding.--
``(1) Offshore property in a trust.--In the case of assets
held in a trust or set aside (directly or indirectly) in
another arrangement, as determined by the Secretary, for
purposes of paying deferred compensation under a nonqualified
deferred compensation plan, for purposes of section 83 such
assets shall be treated as property transferred in connection
with the performance of services whether or not such assets are
available to satisfy claims of general creditors--
``(A) at the time set aside if such assets are
located outside of the United States, or
``(B) at the time transferred if such assets are
subsequently transferred outside of the United States.
``(2) Employer's financial health.--In the case of a
nonqualified deferred compensation plan, there is a transfer of
property within the meaning of section 83 as of the earlier
of--
``(A) the date on which the plan first provides
that assets will become restricted to the provision of
benefits under the plan in connection with a change in
the employer's financial health, or
``(B) the date on which assets are so restricted.
``(3) Income inclusion for offshore trusts and employer's
financial health.--For each taxable year that assets treated as
transferred under this subsection remain set aside in a trust
or other arrangement subject to paragraph (1) or (2), any
increase in value in, or earnings with respect to, such assets
shall be treated as an additional transfer of property under
this subsection (to the extent not previously included in
income).
``(4) Interest on tax liability payable with respect to
transferred property.--
``(A) In general.--If amounts are required to be
included in gross income by reason of paragraph (1) or
(2) for a taxable year, the tax imposed by this chapter
for such taxable year shall be increased by the amount
of interest determined under subparagraph (B).
``(B) Interest.--The interest determined under this
subparagraph for any taxable year is the amount of
interest at the underpayment rate plus 1 percentage
point on the underpayments that would have occurred had
the amounts so required to be included in gross income
by paragraph (1) or (2) been includible in gross income
for the taxable year in which such assets were first
set aside (directly or indirectly) in a trust (or other
arrangement determined by the Secretary) for purposes
of the nonqualified deferred compensation plan.
``(c) No Inference on Earlier Income Inclusion or Requirement of
Later Inclusion.--Nothing in this section shall be construed to prevent
the inclusion of amounts in gross income under any other provision of
this chapter or any other rule of law earlier than the time provided in
this section. Any amount included in gross income under this section
shall not be required to be included in gross income under any other
provision of this chapter or any other rule of law later than the time
provided in this section.
``(d) Other Definitions and Special Rules.--For purposes of this
section--
``(1) Nonqualified deferred compensation plan.--The term
`nonqualified deferred compensation plan' means any plan that
provides for the deferral of compensation, other than--
``(A) a qualified employer plan, and
``(B) any bona fide vacation leave, sick leave,
compensatory time, disability pay, or death benefit
plan.
``(2) Qualified employer plan.--The term `qualified
employer plan' means--
``(A) any plan, contract, pension, account, or
trust described in subparagraph (A) or (B) of section
219(g)(5), and
``(B) any eligible deferred compensation plan
(within the meaning of section 457(b)) of an employer
described in section 457(e)(1)(A).
``(3) Plan includes arrangements, etc.--The term `plan'
includes any agreement or arrangement, including an agreement
or arrangement that includes one person.
``(4) Substantial risk of forfeiture.--The rights of a
person to compensation are subject to a substantial risk of
forfeiture if such person's rights to such compensation are
conditioned upon the future performance of substantial services
by any individual.
``(5) Treatment of earnings.--References to deferred
compensation shall be treated as including references to income
(whether actual or notional) attributable to such compensation
or such income.
``(e) Regulations.--The Secretary shall prescribe such regulations
as may be necessary or appropriate to carry out the purposes of this
section, including regulations--
``(1) providing for the determination of amounts of
deferral in the case of a nonqualified deferred compensation
plan which is a defined benefit plan,
``(2) relating to changes in the ownership and control of a
corporation or assets of a corporation for purposes of
subsection (a)(2)(A)(v),
``(3) exempting arrangements from the application of
subsection (b) if such arrangements will not result in an
improper deferral of United States tax and will not result in
assets being effectively beyond the reach of creditors,
``(4) defining financial health for purposes of subsection
(b)(2), and
``(5) disregarding a substantial risk of forfeiture in
cases where necessary to carry out the purposes of this
section.''.
(b) W-2 Forms.--
(1) In general.--Subsection (a) of section 6051 (relating
to receipts for employees) is amended by striking ``and'' at
the end of paragraph (10), by striking the period at the end of
paragraph (11) and inserting ``, and'', and by inserting after
paragraph (11) the following new paragraph:
``(12) the total amount of deferrals under a nonqualified
deferred compensation plan (within the meaning of section
409A(d)).''.
(2) Threshold.--Subsection (a) of section 6051 is amended
by adding at the end the following: ``In the case of the
amounts required to be shown by paragraph (12), the Secretary
(by regulation) may establish a minimum amount of deferrals
below which paragraph (12) does not apply and may provide that
paragraph (12) does not apply with respect to amounts of
deferrals which are not reasonably ascertainable.''.
(c) Conforming and Clerical Amendments.--
(1) Section 414(b) is amended by inserting ``409A,'' after
``408(p),''.
(2) Section 414(c) is amended by inserting ``409A,'' after
``408(p),''.
(3) The table of sections for such subpart A of part I of
subchapter D of chapter 1 is amended by adding at the end the
following new item:

``Sec. 409A. Inclusion in gross income of
deferred compensation under
nonqualified deferred
compensation plans.''.
(d) Effective Date.--
(1) In general.--Except as otherwise provided in this
subsection, the amendments made by this section shall apply to
amounts deferred in taxable years beginning after December 31,
2003.
(2) Amounts deferred in 2004 under certain irrevocable
elections and binding arrangements.--The amendments made by
this section shall not apply to amounts deferred in taxable
years beginning after December 31, 2003, and before January 1,
2005, pursuant to an irrevocable election or binding
arrangement made before October 24, 2003.
(3) Earnings attributable to amount previously deferred.--
The amendments made by this section shall apply to earnings on
deferred compensation only to the extent that such amendments
apply to such compensation.
(e) Guidance Relating to Change of Ownership or Control.--Not later
than 90 days after the date of the enactment of this Act, the Secretary
of the Treasury shall issue guidance on what constitutes a change in
ownership or effective control for purposes of section 409A of the
Internal Revenue Code of 1986, as added by this section.
(f) Guidance Relating to Termination of Certain Existing
Arrangements.--Not later than 90 days after the date of the enactment
of this Act, the Secretary of the Treasury shall issue guidance
providing a limited period during which an individual participating in
a nonqualified deferred compensation plan adopted on or before December
31, 2003, may, without violating the requirements of paragraphs (2),
(3), and (4) of section 409A(a)(2) of the Internal Revenue Code of 1986
(as added by this section), terminate participation or cancel an
outstanding deferral election with regard to amounts earned after
December 31, 2003, if such amounts are includible in income as earned.

SEC. 1062. EXCLUSION OF INCENTIVE STOCK OPTIONS AND EMPLOYEE STOCK
PURCHASE PLAN STOCK OPTIONS FROM WAGES.

(a) Exclusion From Employment Taxes.--
(1) Social security taxes.--
(A) Section 3121(a) (relating to definition of
wages) is amended by striking ``or'' at the end of
paragraph (20), by striking the period at the end of
paragraph (21) and inserting ``; or'', and by inserting
after paragraph (21) the following new paragraph:
``(22) remuneration on account of--
``(A) a transfer of a share of stock to any
individual pursuant to an exercise of an incentive
stock option (as defined in section 422(b)) or under an
employee stock purchase plan (as defined in section
423(b)), or
``(B) any disposition by the individual of such
stock.''.
(B) Section 209(a) of the Social Security Act is
amended by striking ``or'' at the end of paragraph
(17), by striking the period at the end of paragraph
(18) and inserting ``; or'', and by inserting after
paragraph (18) the following new paragraph:
``(19) Remuneration on account of--
``(A) a transfer of a share of stock to any
individual pursuant to an exercise of an incentive
stock option (as defined in section 422(b) of the
Internal Revenue Code of 1986) or under an employee
stock purchase plan (as defined in section 423(b) of
such Code), or
``(B) any disposition by the individual of such
stock.''.
(2) Railroad retirement taxes.--Subsection (e) of section
3231 is amended by adding at the end the following new
paragraph:
``(11) Qualified stock options.--The term `compensation'
shall not include any remuneration on account of--
``(A) a transfer of a share of stock to any
individual pursuant to an exercise of an incentive
stock option (as defined in section 422(b)) or under an
employee stock purchase plan (as defined in section
423(b)), or
``(B) any disposition by the individual of such
stock.''.
(3) Unemployment taxes.--Section 3306(b) (relating to
definition of wages) is amended by striking ``or'' at the end
of paragraph (16), by striking the period at the end of
paragraph (17) and inserting ``; or'', and by inserting after
paragraph (17) the following new paragraph:
``(18) remuneration on account of--
``(A) a transfer of a share of stock to any
individual pursuant to an exercise of an incentive
stock option (as defined in section 422(b)) or under an
employee stock purchase plan (as defined in section
423(b)), or
``(B) any disposition by the individual of such
stock.''.
(b) Wage Withholding Not Required on Disqualifying Dispositions.--
Section 421(b) (relating to effect of disqualifying dispositions) is
amended by adding at the end the following new sentence: ``No amount
shall be required to be deducted and withheld under chapter 24 with
respect to any increase in income attributable to a disposition
described in the preceding sentence.''.
(c) Wage Withholding Not Required on Compensation Where Option
Price Is Between 85 Percent and 100 Percent of Value of Stock.--Section
423(c) (relating to special rule where option price is between 85
percent and 100 percent of value of stock) is amended by adding at the
end the following new sentence: ``No amount shall be required to be
deducted and withheld under chapter 24 with respect to any amount
treated as compensation under this subsection.''.
(d) Effective Date.--The amendments made by this section shall
apply to stock acquired pursuant to options exercised after the date of
the enactment of this Act.

SEC. 1063. EXTENSION OF TRANSFERS OF EXCESS PENSION ASSETS TO RETIREE
HEALTH ACCOUNTS.

Paragraph (5) of section 420(b) (relating to expiration) is amended
by striking ``December 31, 2005'' and inserting ``December 31, 2013''.

Subtitle G--Treatment of Active Income

SEC. 1071. MEMBER STATES OF THE EUROPEAN UNION TREATED AS A SINGLE
COUNTRY FOR CERTAIN PURPOSES.

(a) In General.--Subsection (d) of section 954 is amended by adding
at the end the following new paragraph:
``(5) Treatment of member states of the european union.--
For purposes of this subsection and subsection (e), in the case
of a controlled foreign corporation which is created or
organized under the laws of a member state of the European
Union, all member states of the European Union shall be treated
as 1 country.''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years of foreign corporations beginning after December 31,
2008, and to taxable years of United States shareholders with or within
which such taxable years of foreign corporations end.

SEC. 1072. LOOK-THRU TREATMENT OF PAYMENTS BETWEEN RELATED CONTROLLED
FOREIGN CORPORATIONS UNDER FOREIGN PERSONAL HOLDING
COMPANY INCOME RULES.

(a) In General.--Subsection (c) of section 954 is amended by adding
after paragraph (3) the following new paragraph:
``(4) Look-thru in the case of related controlled foreign
corporations.--For purposes of this subsection, dividends,
interest, rents, and royalties received or accrued from a
controlled foreign corporation which is a related person (as
defined in subsection (d)(3)) shall not be treated as foreign
personal holding company income to the extent attributable or
properly allocable (determined under rules similar to the rules
of subparagraphs (C) and (D) of section 904(d)(3)) to income of
the related person which is not subpart F income (as defined in
section 952). The Secretary shall prescribe such regulations as
may be appropriate to prevent the abuse of the purposes of this
paragraph.''
(b) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2006, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1073. LOOK-THRU TREATMENT FOR SALES OF PARTNERSHIP INTERESTS.

(a) In General.--Section 954(c) (defining foreign personal holding
company income) is amended by adding after paragraph (4) the following
new paragraph:
``(5) Look-thru rule for certain partnership sales.--
``(A) In general.--In the case of any sale by a
controlled foreign corporation of an interest in a
partnership with respect to which such corporation is a
25-percent owner, such corporation shall be treated for
purposes of this subsection as selling the
proportionate share of the assets of the partnership
attributable to such interest.
``(B) 25-percent owner.--For purposes of this
paragraph, the term `25-percent owner' means a
controlled foreign corporation which owns (within the
meaning of section 958(a)) 25 percent or more of the
capital or profits interest in the partnership.''
(b) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2006, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1074. REPEAL OF FOREIGN PERSONAL HOLDING COMPANY RULES AND FOREIGN
INVESTMENT COMPANY RULES.

(a) General Rule.--The following provisions are hereby repealed:
(1) Part III of subchapter G of chapter 1 (relating to
foreign personal holding companies).
(2) Section 1246 (relating to gain on foreign investment
company stock).
(3) Section 1247 (relating to election by foreign
investment companies to distribute income currently).
(b) Exemption of Foreign Corporations From Personal Holding Company
Rules.--
(1) In general.--Subsection (c) of section 542 (relating to
exceptions) is amended--
(A) by striking paragraph (5) and inserting the
following:
``(5) a foreign corporation,'',
(B) by striking paragraphs (7) and (10) and by
redesignating paragraphs (8) and (9) as paragraphs (7)
and (8), respectively,
(C) by inserting ``and'' at the end of paragraph
(7) (as so redesignated), and
(D) by striking ``; and'' at the end of paragraph
(8) (as so redesignated) and inserting a period.
(2) Treatment of income from personal service contracts.--
Paragraph (1) of section 954(c) is amended by adding at the end
the following new subparagraph:
``(H) Personal service contracts.--
``(i) Amounts received under a contract
under which the corporation is to furnish
personal services if--
``(I) some person other than the
corporation has the right to designate
(by name or by description) the
individual who is to perform the
services, or
``(II) the individual who is to
perform the services is designated (by
name or by description) in the
contract, and
``(ii) amounts received from the sale or
other disposition of such a contract.
This subparagraph shall apply with respect to amounts
received for services under a particular contract only
if at some time during the taxable year 25 percent or
more in value of the outstanding stock of the
corporation is owned, directly or indirectly, by or for
the individual who has performed, is to perform, or may
be designated (by name or by description) as the one to
perform, such services.''
(c) Conforming Amendments.--
(1) Clause (iii) of section 1(h)(11)(C) is amended by
striking ``a foreign personal holding company (as defined in
section 552), a foreign investment company (as defined in
section 1246(b)), or''.
(2) Paragraph (2) of section 171(c) is amended--
(A) by striking ``, or by a foreign personal
holding company, as defined in section 552'', and
(B) by striking ``or foreign personal holding
company''.
(3) Paragraph (2) of section 245(a) is amended by striking
``foreign personal holding company or''.
(4) Section 312 is amended by striking subsection (j).
(5) Subsection (m) of section 312 is amended by striking
``, a foreign investment company (within the meaning of section
1246(b)), or a foreign personal holding company (within the
meaning of section 552)''.
(6) Subsection (e) of section 443 is amended by striking
paragraph (3) and by redesignating paragraphs (4) and (5) as
paragraphs (3) and (4), respectively.
(7) Subparagraph (B) of section 465(c)(7) is amended by
adding ``or'' at the end of clause (i), by striking clause
(ii), and by redesignating clause (iii) as clause (ii).
(8) Paragraph (1) of section 543(b) is amended by inserting
``and'' at the end of subparagraph (A), by striking ``, and''
at the end of subparagraph (B) and inserting a period, and by
striking subparagraph (C).
(9) Paragraph (1) of section 562(b) is amended by striking
``or a foreign personal holding company described in section
552''.
(10) Section 563 is amended--
(A) by striking subsection (c),
(B) by redesignating subsection (d) as subsection
(c), and
(C) by striking ``subsection (a), (b), or (c)'' in
subsection (c) (as so redesignated) and inserting
``subsection (a) or (b)''.
(11) Subsection (d) of section 751 is amended by adding
``and'' at the end of paragraph (2), by striking paragraph (3),
by redesignating paragraph (4) as paragraph (3), and by
striking ``paragraph (1), (2), or (3)'' in paragraph (3) (as so
redesignated) and inserting ``paragraph (1) or (2)''.
(12) Paragraph (2) of section 864(d) is amended by striking
subparagraph (A) and by redesignating subparagraphs (B) and (C)
as subparagraphs (A) and (B), respectively.
(13)(A) Subparagraph (A) of section 898(b)(1) is amended to
read as follows:
``(A) which is treated as a controlled foreign
corporation for any purpose under subpart F of part III
of this subchapter, and''.
(B) Subparagraph (B) of section 898(b)(2) is amended by
striking ``and sections 551(f) and 554, whichever are
applicable,''.
(C) Paragraph (3) of section 898(b) is amended to read as
follows:
``(3) United states shareholder.--The term `United States
shareholder' has the meaning given to such term by section
951(b), except that, in the case of a foreign corporation
having related person insurance income (as defined in section
953(c)(2)), the Secretary may treat any person as a United
States shareholder for purposes of this section if such person
is treated as a United States shareholder under section
953(c)(1).''
(D) Subsection (c) of section 898 is amended to read as
follows:
``(c) Determination of Required Year.--
``(1) In general.--The required year is--
``(A) the majority U.S. shareholder year, or
``(B) if there is no majority U.S. shareholder
year, the taxable year prescribed under regulations.
``(2) 1-month deferral allowed.--A specified foreign
corporation may elect, in lieu of the taxable year under
paragraph (1)(A), a taxable year beginning 1 month earlier than
the majority U.S. shareholder year.
``(3) Majority u.s. shareholder year.--
``(A) In general.--For purposes of this subsection,
the term `majority U.S. shareholder year' means the
taxable year (if any) which, on each testing day,
constituted the taxable year of--
``(i) each United States shareholder
described in subsection (b)(2)(A), and
``(ii) each United States shareholder not
described in clause (i) whose stock was treated
as owned under subsection (b)(2)(B) by any
shareholder described in such clause.
``(B) Testing day.--The testing days shall be--
``(i) the first day of the corporation's
taxable year (determined without regard to this
section), or
``(ii) the days during such representative
period as the Secretary may prescribe.''
(14) Clause (ii) of section 904(d)(2)(A) is amended to read
as follows:
``(ii) Certain amounts included.--Except as
provided in clause (iii), the term `passive
income' includes, except as provided in
subparagraph (E)(iii) or paragraph (3)(I), any
amount includible in gross income under section
1293 (relating to certain passive foreign
investment companies).''
(15)(A) Subparagraph (A) of section 904(g)(1) is amended by
adding ``or'' at the end of clause (i), by striking clause
(ii), and by redesignating clause (iii) as clause (ii).
(B) The paragraph heading of paragraph (2) of section
904(g) is amended by striking ``foreign personal holding or''.
(16) Section 951 is amended by striking subsections (c) and
(d) and by redesignating subsections (e) and (f) as subsections
(c) and (d), respectively.
(17) Paragraph (3) of section 989(b) is amended by striking
``, 551(a),''.
(18) Paragraph (5) of section 1014(b) is amended by
inserting ``and before January 1, 2008,'' after ``August 26,
1937,''.
(19) Subsection (a) of section 1016 is amended by striking
paragraph (13).
(20)(A) Paragraph (3) of section 1212(a) is amended to read
as follows:
``(3) Special rules on carrybacks.--A net capital loss of a
corporation shall not be carried back under paragraph (1)(A) to
a taxable year--
``(A) for which it is a regulated investment
company (as defined in section 851), or
``(B) for which it is a real estate investment
trust (as defined in section 856).''
(B) The amendment made by subparagraph (A) shall apply to
taxable years beginning after December 31, 2006.
(21) Section 1223 is amended by striking paragraph (10) and
by redesignating the following paragraphs accordingly.
(22) Subsection (d) of section 1248 is amended by striking
paragraph (5) and by redesignating paragraphs (6) and (7) as
paragraphs (5) and (6), respectively.
(23) Paragraph (2) of section 1260(c) is amended by
striking subparagraphs (H) and (I) and by redesignating
subparagraph (J) as subparagraph (H).
(24)(A) Subparagraph (F) of section 1291(b)(3) is amended
by striking ``551(d), 959(a),'' and inserting ``959(a)''.
(B) Subsection (e) of section 1291 is amended by inserting
``(as in effect on the day before the date of the enactment of
the American Jobs Creation Act of 2003)'' after ``section
1246''.
(25) Paragraph (2) of section 1294(a) is amended to read as
follows:
``(2) Election not permitted where amounts otherwise
includible under section 951.--The taxpayer may not make an
election under paragraph (1) with respect to the undistributed
PFIC earnings tax liability attributable to a qualified
electing fund for the taxable year if any amount is includible
in the gross income of the taxpayer under section 951 with
respect to such fund for such taxable year.''
(26) Section 6035 is hereby repealed.
(27) Subparagraph (D) of section 6103(e)(1) is amended by
striking clause (iv) and redesignating clauses (v) and (vi) as
clauses (iv) and (v), respectively.
(28) Subparagraph (B) of section 6501(e)(1) is amended to
read as follows:
``(B) Constructive dividends.--If the taxpayer
omits from gross income an amount properly includible
therein under section 951(a), the tax may be assessed,
or a proceeding in court for the collection of such tax
may be done without assessing, at any time within 6
years after the return was filed.''
(29) Subsection (a) of section 6679 is amended--
(A) by striking ``6035, 6046, or 6046A'' in
paragraph (1) and inserting ``6046 or 6046A'', and
(B) by striking paragraph (3).
(30) Sections 170(f)(10)(A), 508(d), 4947, and 4948(c)(4)
are each amended by striking ``556(b)(2),'' each place it
appears.
(31) The table of parts for subchapter G of chapter 1 is
amended by striking the item relating to part III.
(32) The table of sections for part IV of subchapter P of
chapter 1 is amended by striking the items relating to sections
1246 and 1247.
(33) The table of sections for subpart A of part III of
subchapter A of chapter 61 is amended by striking the item
relating to section 6035.
(34) Sections 163(e)(3)(B)(i) and 267(a)(3)(B)(i) are each
amended by--
(A) striking ``a foreign personal holding company
(as defined in section 552),'', and
(B) striking the comma after ``(as defined in
section 957)''.
(d) Effective Date.--Except as otherwise provided in this section,
the amendments made by this section shall apply to taxable years of
foreign corporations beginning after December 31, 2006, and to taxable
years of United States shareholders with or within which such taxable
years of foreign corporations end.

SEC. 1075. CLARIFICATION OF TREATMENT OF PIPELINE TRANSPORTATION
INCOME.

(a) In General.--Section 954(g)(1) (defining foreign base company
oil related income) is amended by striking ``or'' at the end of
subparagraph (A), by striking the period at the end of subparagraph (B)
and inserting ``, or'', and by inserting after subparagraph (B) the
following new subparagraph:
``(C) the pipeline transportation of oil or gas
within such foreign country.''
(b) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2004, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1076. DETERMINATION OF FOREIGN PERSONAL HOLDING COMPANY INCOME
WITH RESPECT TO TRANSACTIONS IN COMMODITIES.

(a) In General.--Clauses (i) and (ii) of section 954(c)(1)(C)
(relating to commodity transactions) are amended to read as follows:
``(i) arise out of commodity hedging
transactions (as defined in paragraph (6)(A)),
``(ii) are active business gains or losses
from the sale of commodities, but only if
substantially all of the controlled foreign
corporation's commodities are property
described in paragraph (1), (2), or (8) of
section 1221(a), or''.
(b) Definition and Special Rules.--Subsection (c) of section 954 is
amended by adding after paragraph (5) the following new paragraph:
``(6) Definition and special rules relating to commodity
transactions.--
``(A) Commodity hedging transactions.--For purposes
of paragraph (1)(C)(i), the term `commodity hedging
transaction' means any transaction with respect to a
commodity if such transaction--
``(i) is a hedging transaction as defined
in section 1221(b)(2), determined--
``(I) without regard to
subparagraph (A)(ii) thereof,
``(II) by applying subparagraph
(A)(i) thereof by substituting
`ordinary property or property
described in section 1231(b)' for
`ordinary property', and
``(III) by substituting `controlled
foreign corporation' for `taxpayer'
each place it appears, and
``(ii) is clearly identified as such in
accordance with section 1221(a)(7).
``(B) Regulations.--The Secretary shall prescribe
such regulations as are appropriate to carry out the
purposes of paragraph (1)(C) in the case of
transactions involving related persons.''
(c) Effective Date.--The amendments made by this section shall
apply to transactions entered into after December 31, 2004.

SEC. 1077. REPEAL OF CFC RULES ON FOREIGN BASE COMPANY SHIPPING INCOME.

(a) Elimination of Foreign Base Company Shipping Income.--Section
954 (relating to foreign base company income) is amended--
(1) by striking paragraph (4) of subsection (a) (relating
to foreign base company shipping income), and
(2) by striking subsection (f) (relating to foreign base
company shipping income).
(b) Safe Harbor for Certain Leasing Activities.--Subparagraph (A)
of section 954(c)(2) is amended by adding at the end the following new
sentence: ``For purposes of the preceding sentence, rents derived from
leasing an aircraft or vessel in foreign commerce shall not fail to be
treated as derived in the active conduct of a trade or business if, as
determined under regulations prescribed by the Secretary, the active
leasing expenses are not less than 10 percent of the profit on the
lease.''
(c) Conforming Amendments.--
(1) Section 952(c)(1)(B)(iii) is amended by striking
subclause (I) and redesignating subclauses (II) through (VI) as
subclauses (I) through (V), respectively.
(2) Subsection (b) of section 954 is amended--
(A) by striking ``the foreign base company shipping
income,'' in paragraph (5),
(B) by striking paragraphs (6) and (7), and
(C) by redesignating paragraph (8) as paragraph
(6).
(d) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2004, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1078. MODIFICATION OF SUBPART F EXEMPTION FOR ACTIVE FINANCING.

(a) In General.--Section 954(h)(3) is amended by adding at the end
the following:
``(E) Direct conduct of activities.--For purposes
of subparagraph (A)(ii)(II), an activity shall be
treated as conducted directly by an eligible controlled
foreign corporation or qualified business unit in its
home country if the activity is performed by employees
of a related person and--
``(i) the related person is an eligible
controlled foreign corporation the home country
of which is the same as the home country of the
corporation or unit to which subparagraph
(A)(ii)(II) is being applied,
``(ii) the activity is performed in the
home country of the related person, and
``(iii) the related person is compensated
on an arm's-length basis for the performance of
the activity by its employees and such
compensation is treated as earned by such
person in its home country for purposes of the
home country's tax laws.''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2004, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1079. PARTIAL EXCLUSION FOR INCOME ATTRIBUTABLE TO FILMS USED
OUTSIDE THE UNITED STATES.

(a) In General.--Part III of subchapter B of chapter 1 (relating to
items specifically excluded from gross income) is amended by inserting
after section 139 the following new section:

``SEC. 139A. INCOME ATTRIBUTABLE TO FILMS USED OUTSIDE THE UNITED
STATES.

``(a) Exclusion.--
``(1) In general.--There shall be excluded from gross
income an amount equal to the applicable percentage of
qualified film income.
``(2) Applicable percentage.--For purposes of paragraph
(1), the applicable percentage shall be determined in
accordance with the following table:

``For taxable years ending
The applicable
in calendar year--
percentage is--
2007...................................          1
2008...................................          2
2009...................................          3
2010...................................          5
2011...................................          8
2012...................................          9
2013 or thereafter.....................         10.
``(b) Qualified Film Income.--For purposes of this section--
``(1) In general.--The term `qualified film income' means
gross income from a license of a qualified film in the ordinary
course of a trade or business for the exploitation or direct
use outside the United States less any associated film costs.
``(2) Exceptions.--
``(A) Certain uses.--Such term does not include
exploitation of characters, soundtracks, designs,
scripts, scores, or any other ancillary intangibles
associated with the qualified film.
``(B) Related person license.--
``(i) In general.--Such term does not
include any amount from the license of a
qualified film to a related person.
``(ii) Exception.--Clause (i) shall not
apply if such film is held for license by such
related person to an unrelated person for the
direct use or exploitation by such unrelated
person outside the United States.
``(iii) Related person.--For purposes of
this subparagraph, a person shall be related to
another person if such persons are treated as a
single employer under subsection (a) or (b) of section 52 or subsection
(m) or (o) of section 414, except that determinations under subsections
(a) and (b) of section 52 shall be made without regard to section
1563(b).
``(c) Other Definitions.--For purposes of this section--
``(1) Qualified Film.--The term `qualified film' means
property described in section 168(f)(3) the original use of
which commences after December 31, 2006, if not less than 50
percent of the total compensation relating to the production of
such property is compensation for services performed in the
United States by actors, production personnel, directors, and
producers. Such term does not include property with respect to
which records are required to be maintained under section 2257
of title 18, United States Code.
``(2) Associated film costs.--The term `associated film
costs' means any expense properly apportioned and allocated to
income taken into account under subsection (b)(1), determined
as provided under regulations prescribed by the Secretary.
``(d) Election.--The taxpayer may elect not to apply this section
to a qualified film. Such election shall be made by the due date
(including extensions of time) for filing the return for the taxable
year in which such film is placed in service, and, once made for such
film, such election shall be irrevocable.
``(e) Denial of Foreign Tax Credit.--
``(1) In general.--No credit shall be allowed under section
901 for any taxes paid or accrued (or treated as paid or
accrued) with respect to the excludable portion of any
qualified film income. No deduction shall be allowed under this
chapter for any tax for which credit is not allowable by reason
of the preceding sentence.
``(2) Excludable portion.--For purposes of paragraph (1),
the taxes paid or accrued (or treated as paid or accrued) with
respect to the excludable portion is the amount which bears the
same ratio to the amount of taxes paid or accrued (or treated
as paid or accrued) with respect to qualified film income as
the amount excluded under subsection (a) for the taxable year
bears to the qualified film income for such year.''.
(b) Clerical Amendment.--The table of sections for part III of
subchapter B of chapter 1 is amended by inserting after the item
relating to section 139 the following new item:

``Sec. 139A. Income attributable to films
used outside the United
States.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years ending after December 31, 2006.

Subtitle H--Reduction of Double Taxation of Earnings

SEC. 1081. INTEREST EXPENSE ALLOCATION RULES.

(a) Election To Allocate on Worldwide Basis.--Section 864 is
amended by redesignating subsection (f) as subsection (g) and by
inserting after subsection (e) the following new subsection:
``(f) Election To Allocate Interest, etc. on Worldwide Basis.--For
purposes of this subchapter, at the election of the worldwide
affiliated group--
``(1) Allocation and apportionment of interest expense.--
``(A) In general.--The taxable income of each
domestic corporation which is a member of a worldwide
affiliated group shall be determined by allocating and
apportioning interest expense of each member as if all
members of such group were a single corporation.
``(B) Treatment of worldwide affiliated group.--The
taxable income of the domestic members of a worldwide
affiliated group from sources outside the United States
shall be determined by allocating and apportioning the
interest expense of such domestic members to such
income in an amount equal to the excess (if any) of--
``(i) the total interest expense of the
worldwide affiliated group multiplied by the
ratio which the foreign assets of the worldwide
affiliated group bears to all the assets of the
worldwide affiliated group, over
``(ii) the interest expense of all foreign
corporations which are members of the worldwide
affiliated group to the extent such interest
expense of such foreign corporations would have
been allocated and apportioned to foreign
source income if this subsection were applied
to a group consisting of all the foreign
corporations in such worldwide affiliated
group.
``(C) Worldwide affiliated group.--For purposes of
this paragraph, the term `worldwide affiliated group'
means a group consisting of--
``(i) the includible members of an
affiliated group (as defined in section
1504(a), determined without regard to
paragraphs (2) and (4) of section 1504(b)), and
``(ii) all controlled foreign corporations
in which such members in the aggregate meet the
ownership requirements of section 1504(a)(2)
either directly or indirectly through applying
paragraph (2) of section 958(a) or through
applying rules similar to the rules of such
paragraph to stock owned directly or indirectly
by domestic partnerships, trusts, or estates.
``(2) Allocation and apportionment of other expenses.--
Expenses other than interest which are not directly allocable
or apportioned to any specific income producing activity shall
be allocated and apportioned as if all members of the
affiliated group were a single corporation. For purposes of the
preceding sentence, the term `affiliated group' has the meaning
given such term by section 1504 (determined without regard to paragraph
(4) of section 1504(b)).
``(3) Treatment of tax-exempt assets; basis of stock in
nonaffiliated 10-percent owned corporations.--The rules of
paragraphs (3) and (4) of subsection (e) shall apply for
purposes of this subsection; except that paragraph (4) shall be
applied on worldwide affiliated group basis.
``(4) Treatment of certain financial institutions.--
``(A) In general.--For purposes of paragraph (1),
any corporation described in subparagraph (B) shall be
treated as an includible corporation for purposes of
section 1504 only for purposes of applying this
subsection separately to corporations so described.
``(B) Description.--A corporation is described in
this subparagraph if--
``(i) such corporation is a financial
institution described in section 581 or 591,
``(ii) the business of such financial
institution is predominantly with persons other
than related persons (within the meaning of
subsection (d)(4)) or their customers, and
``(iii) such financial institution is
required by State or Federal law to be operated
separately from any other entity which is not
such an institution.
``(C) Treatment of bank holding companies.--To the
extent provided in regulations--
``(i) a bank holding company (within the
meaning of section 2(a) of the Bank Holding
Company Act of 1956 (12 U.S.C. 1841(a))),
``(ii) a financial holding company (within
the meaning of section 2(p) of such Act), and
``(iii) any subsidiary of a financial
institution described in section 581 or 591, or
any such bank or financial holding company, if
such subsidiary is predominantly engaged
(directly or indirectly) in the active conduct
of a banking, financing, or similar business,
shall be treated as a corporation described in
subparagraph (B).
``(5) Election to expand financial institution group of
worldwide group.--
``(A) In general.--If a worldwide affiliated group
elects the application of this subsection, all
financial corporations which--
``(i) are members of such worldwide
affiliated group, but
``(ii) are not corporations described in
paragraph (4)(B),
shall be treated as described in paragraph (4)(B) for
purposes of applying paragraph (4)(A). This subsection
(other than this paragraph) shall apply to any such
group in the same manner as this subsection (other than
this paragraph) applies to the pre-election worldwide
affiliated group of which such group is a part.
``(B) Financial corporation.--For purposes of this
paragraph, the term `financial corporation' means any
corporation if at least 80 percent of its gross income
is income described in section 904(d)(2)(D)(ii) and the
regulations thereunder which is derived from
transactions with persons who are not related (within
the meaning of section 267(b) or 707(b)(1)) to the
corporation. For purposes of the preceding sentence,
there shall be disregarded any item of income or gain
from a transaction or series of transactions a
principal purpose of which is the qualification of any
corporation as a financial corporation.
``(C) Antiabuse rules.--In the case of a
corporation which is a member of an electing financial
institution group, to the extent that such
corporation--
``(i) distributes dividends or makes other
distributions with respect to its stock after
the date of the enactment of this paragraph to
any member of the pre-election worldwide
affiliated group (other than to a member of the
electing financial institution group) in excess
of the greater of--
``(I) its average annual dividend
(expressed as a percentage of current
earnings and profits) during the 5-
taxable-year period ending with the
taxable year preceding the taxable
year, or
``(II) 25 percent of its average
annual earnings and profits for such 5-
taxable-year period, or
``(ii) deals with any person in any manner
not clearly reflecting the income of the
corporation (as determined under principles
similar to the principles of section 482),
an amount of indebtedness of the electing financial
institution group equal to the excess distribution or
the understatement or overstatement of income, as the
case may be, shall be recharacterized (for the taxable
year and subsequent taxable years) for purposes of this
paragraph as indebtedness of the worldwide affiliated
group (excluding the electing financial institution
group). If a corporation has not been in existence for
5 taxable years, this subparagraph shall be applied
with respect to the period it was in existence.
``(D) Election.--An election under this paragraph
with respect to any financial institution group may be
made only by the common parent of the pre-election
worldwide affiliated group and may be made only for the
first taxable year beginning after December 31, 2008,
in which such affiliated group includes 1 or more
financial corporations. Such an election, once made,
shall apply to all financial corporations which are
members of the electing financial institution group for
such taxable year and all subsequent years unless
revoked with the consent of the Secretary.
``(E) Definitions relating to groups.--For purposes
of this paragraph--
``(i) Pre-election worldwide affiliated
group.--The term `pre-election worldwide
affiliated group' means, with respect to a
corporation, the worldwide affiliated group of
which such corporation would (but for an
election under this paragraph) be a member for
purposes of applying paragraph (1).
``(ii) Electing financial institution
group.--The term `electing financial
institution group' means the group of
corporations to which this subsection applies
separately by reason of the application of
paragraph (4)(A) and which includes financial
corporations by reason of an election under
subparagraph (A).
``(F) Regulations.--The Secretary shall prescribe
such regulations as may be appropriate to carry out
this subsection, including regulations--
``(i) providing for the direct allocation
of interest expense in other circumstances
where such allocation would be appropriate to
carry out the purposes of this subsection,
``(ii) preventing assets or interest
expense from being taken into account more than
once, and
``(iii) dealing with changes in members of
any group (through acquisitions or otherwise)
treated under this paragraph as an affiliated
group for purposes of this subsection.
``(6) Election.--An election to have this subsection apply
with respect to any worldwide affiliated group may be made only
by the common parent of the domestic affiliated group referred
to in paragraph (1)(C) and may be made only for the first
taxable year beginning after December 31, 2008, in which a
worldwide affiliated group exists which includes such
affiliated group and at least one foreign corporation. Such an
election, once made, shall apply to such common parent and all
other corporations which are members of such worldwide
affiliated group for such taxable year and all subsequent years
unless revoked with the consent of the Secretary.''.
(b) Expansion of Regulatory Authority.--Paragraph (7) of section
864(e) is amended--
(1) by inserting before the comma at the end of
subparagraph (B) ``and in other circumstances where such
allocation would be appropriate to carry out the purposes of
this subsection'', and
(2) by striking ``and'' at the end of subparagraph (E), by
redesignating subparagraph (F) as subparagraph (G), and by
inserting after subparagraph (E) the following new
subparagraph:
``(F) preventing assets or interest expense from
being taken into account more than once, and''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2008.

SEC. 1082. RECHARACTERIZATION OF OVERALL DOMESTIC LOSS.

(a) General Rule.--Section 904 is amended by redesignating
subsections (g), (h), (i), (j), and (k) as subsections (h), (i), (j),
(k), and (l) respectively, and by inserting after subsection (f) the
following new subsection:
``(g) Recharacterization of Overall Domestic Loss.--
``(1) General rule.--For purposes of this subpart and
section 936, in the case of any taxpayer who sustains an
overall domestic loss for any taxable year beginning after
December 31, 2005, that portion of the taxpayer's taxable
income from sources within the United States for each
succeeding taxable year which is equal to the lesser of--
``(A) the amount of such loss (to the extent not
used under this paragraph in prior taxable years), or
``(B) 50 percent of the taxpayer's taxable income
from sources within the United States for such
succeeding taxable year,
shall be treated as income from sources without the United
States (and not as income from sources within the United
States).
``(2) Overall domestic loss defined.--For purposes of this
subsection--
``(A) In general.--The term `overall domestic loss'
means any domestic loss to the extent such loss offsets
taxable income from sources without the United States
for the taxable year or for any preceding taxable year
by reason of a carryback. For purposes of the preceding
sentence, the term `domestic loss' means the amount by
which the gross income for the taxable year from
sources within the United States is exceeded by the sum
of the deductions properly apportioned or allocated
thereto (determined without regard to any carryback
from a subsequent taxable year).
``(B) Taxpayer must have elected foreign tax credit
for year of loss.--The term `overall domestic loss'
shall not include any loss for any taxable year unless
the taxpayer chose the benefits of this subpart for
such taxable year.
``(3) Characterization of subsequent income.--
``(A) In general.--Any income from sources within
the United States that is treated as income from
sources without the United States under paragraph (1)
shall be allocated among and increase the income
categories in proportion to the loss from sources
within the United States previously allocated to those
income categories.
``(B) Income category.--For purposes of this
paragraph, the term `income category' has the meaning
given such term by subsection (f)(5)(E)(i).
``(4) Coordination with subsection (f).--The Secretary
shall prescribe such regulations as may be necessary to
coordinate the provisions of this subsection with the
provisions of subsection (f).''
(b) Conforming Amendments.--
(1) Section 535(d)(2) is amended by striking ``section
904(g)(6)'' and inserting ``section 904(h)(6)''.
(2) Subparagraph (A) of section 936(a)(2) is amended by
striking ``section 904(f)'' and inserting ``subsections (f) and
(g) of section 904''.
(c) Effective Date.--The amendments made by this section shall
apply to losses sustained for taxable years beginning after December
31, 2005.

SEC. 1083. REDUCTION TO 2 FOREIGN TAX CREDIT BASKETS.

(a) In General.--Paragraph (1) of section 904(d) (relating to
separate application of section with respect to certain categories of
income) is amended to read as follows:
``(1) In general.--The provisions of subsections (a), (b),
and (c) and sections 902, 907, and 960 shall be applied
separately with respect to--
``(A) passive category income, and
``(B) general category income.''
(b) Categories.--Paragraph (2) of section 904(d) is amended by
striking subparagraph (B), by redesignating subparagraph (A) as
subparagraph (B), and by inserting before subparagraph (B) (as so
redesignated) the following new subparagraph:
``(A) Categories.--
``(i) Passive category income.--The term
`passive category income' means passive income
and specified passive category income.
``(ii) General category income.--The term
`general category income' means income other
than passive category income.''
(c) Specified Passive Category Income.--Subparagraph (B) of section
904(d)(2), as so redesignated, is amended by adding at the end the
following new clause:
``(v) Specified passive category income.--
The term `specified passive category income'
means--
``(I) dividends from a DISC or
former DISC (as defined in section
992(a)) to the extent such dividends
are treated as income from sources
without the United States,
``(II) taxable income attributable
to foreign trade income (within the
meaning of section 923(b)), and
``(III) distributions from a FSC
(or a former FSC) out of earnings and
profits attributable to foreign trade
income (within the meaning of section
923(b)) or interest or carrying charges
(as defined in section 927(d)(1))
derived from a transaction which
results in foreign trade income (as
defined in section 923(b)).''
(d) Treatment of Financial Services.--Paragraph (2) of section
904(d) is amended by striking subparagraph (D), by redesignating
subparagraph (C) as subparagraph (D), and by inserting before
subparagraph (D) (as so redesignated) the following new subparagraph:
``(C) Treatment of financial services income and
companies.--
``(i) In general.--Financial services
income shall be treated as general category
income in the case of--
``(I) a member of a financial
services group, and
``(II) any other person if such
person is predominantly engaged in the
active conduct of a banking, insurance,
financing, or similar business.
``(ii) Financial services group.--The term
`financial services group' means any affiliated
group (as defined in section 1504(a) without
regard to paragraphs (2) and (3) of section
1504(b)) which is predominantly engaged in the
active conduct of a banking, insurance,
financing, or similar business. In determining
whether such a group is so engaged, there shall
be taken into account only the income of
members of the group that are--
``(I) United States corporations,
or
``(II) controlled foreign
corporations in which such United
States corporations own, directly or
indirectly, at least 80 percent of the
total voting power and value of the
stock.
``(iii) Pass-thru entities.--The Secretary
shall by regulation specify for purposes of
this subparagraph the treatment of financial
services income received or accrued by
partnerships and by other pass-thru entities
which are not members of a financial services
group.''
(e) Conforming Amendments.--
(1) Clause (iii) of section 904(d)(2)(B) (relating to
exceptions from passive income), as so redesignated, is amended
by striking subclause (I) and by redesignating subclauses (II)
and (III) as subclauses (I) and (II), respectively.
(2) Clause (i) of section 904(d)(2)(D) (defining financial
services income), as so redesignated, is amended by adding
``or'' at the end of subclause (I) and by striking subclauses
(II) and (III) and inserting the following new subclause:
``(II) passive income (determined
without regard to subparagraph
(B)(iii)(II)).''
(3) Section 904(d)(2)(D) (defining financial services
income), as so redesignated, is amended by striking clause
(iii).
(4) Paragraph (3) of section 904(d) is amended to read as
follows:
``(3) Look-thru in case of controlled foreign
corporations.--
``(A) In general.--Except as otherwise provided in
this paragraph, dividends, interest, rents, and
royalties received or accrued by the taxpayer from a
controlled foreign corporation in which the taxpayer is
a United States shareholder shall not be treated as
passive category income.
``(B) Subpart f inclusions.--Any amount included in
gross income under section 951(a)(1)(A) shall be
treated as passive category income to the extent the
amount so included is attributable to passive category
income.
``(C) Interest, rents, and royalties.--Any
interest, rent, or royalty which is received or accrued
from a controlled foreign corporation in which the
taxpayer is a United States shareholder shall be
treated as passive category income to the extent it is
properly allocable (under regulations prescribed by the
Secretary) to passive category income of the controlled
foreign corporation.
``(D) Dividends.--Any dividend paid out of the
earnings and profits of any controlled foreign
corporation in which the taxpayer is a United States
shareholder shall be treated as passive category income
in proportion to the ratio of--
``(i) the portion of the earnings and
profits attributable to passive category
income, to
``(ii) the total amount of earnings and
profits.
``(E) Look-thru applies only where subpart f
applies.--If a controlled foreign corporation meets the
requirements of section 954(b)(3)(A) (relating to de
minimis rule) for any taxable year, for purposes of
this paragraph, none of its foreign base company income
(as defined in section 954(a) without regard to section
954(b)(5)) and none of its gross insurance income (as
defined in section 954(b)(3)(C)) for such taxable year
shall be treated as passive category income, except
that this sentence shall not apply to any income which
(without regard to this sentence) would be treated as
financial services income. Solely for purposes of
applying subparagraph (D), passive income of a
controlled foreign corporation shall not be treated as
passive category income if the requirements of section
954(b)(4) are met with respect to such income.
``(F) Coordination with high-taxed income
provisions.--
``(i) In determining whether any income of
a controlled foreign corporation is passive
category income, subclause (II) of paragraph
(2)(B)(iii) shall not apply.
``(ii) Any income of the taxpayer which is
treated as passive category income under this
paragraph shall be so treated notwithstanding
any provision of paragraph (2); except that the
determination of whether any amount is high-
taxed income shall be made after the
application of this paragraph.
``(G) Dividend.--For purposes of this paragraph,
the term `dividend' includes any amount included in
gross income in section 951(a)(1)(B). Any amount
included in gross income under section 78 to the extent
attributable to amounts included in gross income in
section 951(a)(1)(A) shall not be treated as a dividend
but shall be treated as included in gross income under
section 951(a)(1)(A).
``(H) Look-thru applies to passive foreign
investment company inclusion.--If--
``(i) a passive foreign investment company
is a controlled foreign corporation, and
``(ii) the taxpayer is a United States
shareholder in such controlled foreign
corporation,
any amount included in gross income under section 1293
shall be treated as income in a separate category to
the extent such amount is attributable to income in
such category.''
(5) Treatment of income tax base differences.--Paragraph
(2) of section 904(d) is amended by redesignating subparagraphs
(H) and (I) as subparagraphs (I) and (J), respectively, and by
inserting after subparagraph (G) the following new
subparagraph:
``(H) Treatment of income tax base differences.--
Tax imposed under the law of a foreign country or
possession of the United States on an amount which does
not constitute income under United States tax
principles shall be treated as imposed on income
described in paragraph (1)(B).''
(6) Paragraph (2) of section 904(d) is amended by adding at
the end the following new subparagraph:
``(K) Transitional rules for 2005 changes.--For
purposes of paragraph (1)--
``(i) taxes carried from any taxable year
beginning before January 1, 2005, to any
taxable year beginning on or after such date,
with respect to any item of income, shall be
treated as described in the subparagraph of
paragraph (1) in which such income would be
described were such taxes paid or accrued in a
taxable year beginning on or after such date,
and
``(ii) the Secretary may by regulations
provide for the allocation of any carryback of
taxes with respect to income to such a taxable
year for purposes of allocating such income
among the separate categories in effect for
such taxable year.''.
(7) Section 904(j)(3)(A)(i) is amended by striking
``subsection (d)(2)(A)'' and inserting ``subsection
(d)(2)(B)''.
(f) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 1084. LOOK-THRU RULES TO APPLY TO DIVIDENDS FROM NONCONTROLLED
SECTION 902 CORPORATIONS.

(a) In General.--Section 904(d)(4) (relating to look-thru rules
apply to dividends from noncontrolled section 902 corporations) is
amended to read as follows:
``(4) Look-thru applies to dividends from noncontrolled
section 902 corporations.--
``(A) In general.--For purposes of this subsection,
any dividend from a noncontrolled section 902
corporation with respect to the taxpayer shall be
treated as income described in a subparagraph of
paragraph (1) in proportion to the ratio of--
``(i) the portion of earnings and profits
attributable to income described in such
subparagraph, to
``(ii) the total amount of earnings and
profits.
``(B) Special rules.--For purposes of this
paragraph--
``(i) Earnings and profits.--
``(I) In general.--The rules of
section 316 shall apply.
``(II) Regulations.--The Secretary
may prescribe regulations regarding the
treatment of distributions out of
earnings and profits for periods before
the taxpayer's acquisition of the stock
to which the distributions relate.
``(ii) Inadequate substantiation.--If the
Secretary determines that the proper
subparagraph of paragraph (1) in which a
dividend is described has not been
substantiated, such dividend shall be treated
as income described in paragraph (1)(A).
``(iii) Look-thru with respect to
carryforwards of credit.--Rules similar to
subparagraph (A) also shall apply to any
carryforward under subsection (c) from a
taxable year beginning before January 1, 2003,
of tax allocable to a dividend from a
noncontrolled section 902 corporation with
respect to the taxpayer. The Secretary may by
regulations provide for the allocation of any
carryback of tax allocable to a dividend from a
noncontrolled section 902 corporation to such a
taxable year for purposes of allocating such
dividend among the separate categories in
effect for such taxable year.
``(iv) Coordination with high-taxed income
provisions.--Rules similar to the rules of
paragraph (3)(F) shall apply for purposes of
this paragraph.''.
(b) Conforming Amendments.--
(1) Section 904(d)(2)(E) is amended--
(A) by inserting ``or (4)'' after ``paragraph (3)''
in clause (i), and
(B) by striking clauses (ii) and (iv) and by
redesignating clause (iii) as clause (ii).
(2) Clause (i) of section 864(d)(5)(A) is amended to read
as follows:
``(i) Subclause (I) of section
904(d)(2)(B)(iii).''
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 1085. ATTRIBUTION OF STOCK OWNERSHIP THROUGH PARTNERSHIPS TO APPLY
IN DETERMINING SECTION 902 AND 960 CREDITS.

(a) In General.--Subsection (c) of section 902 is amended by
redesignating paragraph (7) as paragraph (8) and by inserting after
paragraph (6) the following new paragraph:
``(7) Constructive ownership through partnerships.--Stock
owned, directly or indirectly, by or for a partnership shall be
considered as being owned proportionately by its partners.
Stock considered to be owned by a person by reason of the
preceding sentence shall, for purposes of applying such
sentence, be treated as actually owned by such person. The
Secretary may prescribe such regulations as may be necessary to
carry out the purposes of this paragraph, including rules to
account for special partnership allocations of dividends,
credits, and other incidents of ownership of stock in
determining proportionate ownership.''
(b) Clarification of Comparable Attribution Under Section
901(b)(5).--Paragraph (5) of section 901(b) is amended by striking
``any individual'' and inserting ``any person''.
(c) Effective Date.--The amendments made by this section shall
apply to taxes of foreign corporations for taxable years of such
corporations beginning after the date of the enactment of this Act.

SEC. 1086. CLARIFICATION OF TREATMENT OF CERTAIN TRANSFERS OF
INTANGIBLE PROPERTY.

(a) In General.--Subparagraph (C) of section 367(d)(2) is amended
by adding at the end the following new sentence: ``For purposes of
applying section 904(d), any such amount shall be treated in the same
manner as if such amount were a royalty.''
(b) Effective Date.--The amendment made by this section shall apply
to amounts treated as received pursuant to section 367(d)(2) of the
Internal Revenue Code of 1986 on or after August 5, 1997.

SEC. 1087. UNITED STATES PROPERTY NOT TO INCLUDE CERTAIN ASSETS
ACQUIRED BY DEALERS IN ORDINARY COURSE OF TRADE OR
BUSINESS.

(a) In General.--Section 956(c)(2) (relating to exceptions from
property treated as United States property) is amended by striking
``and'' at the end of subparagraph (J), by striking the period at the
end of subparagraph (K) and inserting ``; and'', and by adding at the
end the following new subparagraph:
``(L) securities acquired and held by a controlled
foreign corporation in the ordinary course of its
business as a dealer in securities if--
``(i) the dealer accounts for the
securities as securities held primarily for
sale to customers in the ordinary course of
business, and
``(ii) the dealer disposes of the
securities (or such securities mature while
held by the dealer) within a period consistent
with the holding of securities for sale to
customers in the ordinary course of business.''
(b) Conforming Amendment.--Section 956(c)(2) is amended by striking
``and (K)'' in the last sentence and inserting ``, (K), and (L)''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years of foreign corporations beginning after December
31, 2004, and to taxable years of United States shareholders with or
within which such taxable years of foreign corporations end.

SEC. 1088. ELECTION NOT TO USE AVERAGE EXCHANGE RATE FOR FOREIGN TAX
PAID OTHER THAN IN FUNCTIONAL CURRENCY.

(a) In General.--Paragraph (1) of section 986(a) (relating to
determination of foreign taxes and foreign corporation's earnings and
profits) is amended by redesignating subparagraph (D) as subparagraph
(E) and by inserting after subparagraph (C) the following new
subparagraph:
``(D) Elective exception for taxes paid other than
in functional currency.--
``(i) In general.--At the election of the
taxpayer, subparagraph (A) shall not apply to
any foreign income taxes the liability for
which is denominated in any currency other than
in the taxpayer's functional currency.
``(ii) Application to qualified business
units.--An election under this subparagraph may
apply to foreign income taxes attributable to a
qualified business unit in accordance with
regulations prescribed by the Secretary.
``(iii) Election.--Any such election shall
apply to the taxable year for which made and
all subsequent taxable years unless revoked
with the consent of the Secretary.''
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2004.

SEC. 1089. REPEAL OF WITHHOLDING TAX ON DIVIDENDS FROM CERTAIN FOREIGN
CORPORATIONS.

(a) In General.--Paragraph (2) of section 871(i) (relating to tax
not to apply to certain interest and dividends) is amended by adding at
the end the following new subparagraph:
``(D) Dividends paid by a foreign corporation which
are treated under section 861(a)(2)(B) as income from
sources within the United States.''.
(b) Effective Date.--The amendment made by this section shall apply
to payments made after December 31, 2004.

SEC. 1090. PROVIDE EQUAL TREATMENT FOR INTEREST PAID BY FOREIGN
PARTNERSHIPS AND FOREIGN CORPORATIONS.

(a) In General.--Paragraph (1) of section 861(a) is amended by
striking ``and'' at the end of subparagraph (A), by striking the period
at the end of subparagraph (B) and inserting ``, and'', and by adding
at the end the following new subparagraph:
``(C) in the case of a foreign partnership in which
United States persons do not hold directly or
indirectly 20 percent or more of either the capital or
profits interests, any interest not paid by a trade or
business engaged in by the partnership in the United
States and not allocable to income which is effectively
connected (or treated as effectively connected) with
the conduct of a trade or business in the United
States.''
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 1091. TREATMENT OF CERTAIN DIVIDENDS OF REGULATED INVESTMENT
COMPANIES.

(a) Treatment of Certain Dividends.--
(1) Nonresident alien individuals.--Section 871 (relating
to tax on nonresident alien individuals) is amended by
redesignating subsection (k) as subsection (l) and by inserting
after subsection (j) the following new subsection:
``(k) Exemption for Certain Dividends of Regulated Investment
Companies.--
``(1) Interest-related dividends.--
``(A) In general.--Except as provided in
subparagraph (B), no tax shall be imposed under
paragraph (1)(A) of subsection (a) on any interest-
related dividend received from a regulated investment
company.
``(B) Exceptions.--Subparagraph (A) shall not
apply--
``(i) to any interest-related dividend
received from a regulated investment company by
a person to the extent such dividend is
attributable to interest (other than interest
described in subparagraph (E) (i) or (iii))
received by such company on indebtedness issued
by such person or by any corporation or
partnership with respect to which such person
is a 10-percent shareholder,
``(ii) to any interest-related dividend
with respect to stock of a regulated investment
company unless the person who would otherwise
be required to deduct and withhold tax from
such dividend under chapter 3 receives a
statement (which meets requirements similar to
the requirements of subsection (h)(5)) that the
beneficial owner of such stock is not a United
States person, and
``(iii) to any interest-related dividend
paid to any person within a foreign country (or
any interest-related dividend payment addressed
to, or for the account of, persons within such
foreign country) during any period described in
subsection (h)(6) with respect to such country.
Clause (iii) shall not apply to any dividend with
respect to any stock which was acquired on or before
the date of the publication of the Secretary's
determination under subsection (h)(6).
``(C) Interest-related dividend.--For purposes of
this paragraph, an interest-related dividend is any
dividend (or part thereof) which is designated by the
regulated investment company as an interest-related
dividend in a written notice mailed to its shareholders
not later than 60 days after the close of its taxable
year. If the aggregate amount so designated with
respect to a taxable year of the company (including
amounts so designated with respect to dividends paid
after the close of the taxable year described in
section 855) is greater than the qualified net interest
income of the company for such taxable year, the
portion of each distribution which shall be an
interest-related dividend shall be only that portion of
the amounts so designated which such qualified net
interest income bears to the aggregate amount so
designated.
``(D) Qualified net interest income.--For purposes
of subparagraph (C), the term `qualified net interest
income' means the qualified interest income of the
regulated investment company reduced by the deductions
properly allocable to such income.
``(E) Qualified interest income.--For purposes of
subparagraph (D), the term `qualified interest income'
means the sum of the following amounts derived by the
regulated investment company from sources within the
United States:
``(i) Any amount includible in gross income
as original issue discount (within the meaning
of section 1273) on an obligation payable 183
days or less from the date of original issue
(without regard to the period held by the
company).
``(ii) Any interest includible in gross
income (including amounts recognized as
ordinary income in respect of original issue
discount or market discount or acquisition
discount under part V of subchapter P and such
other amounts as regulations may provide) on an
obligation which is in registered form; except
that this clause shall not apply to--
``(I) any interest on an obligation
issued by a corporation or partnership
if the regulated investment company is
a 10-percent shareholder in such
corporation or partnership, and
``(II) any interest which is
treated as not being portfolio interest
under the rules of subsection (h)(4).
``(iii) Any interest referred to in
subsection (i)(2)(A) (without regard to the
trade or business of the regulated investment
company).
``(iv) Any interest-related dividend
includable in gross income with respect to
stock of another regulated investment company.
``(F) 10-percent shareholder.--For purposes of this
paragraph, the term `10-percent shareholder' has the
meaning given such term by subsection (h)(3)(B).
``(2) Short-term capital gain dividends.--
``(A) In general.--Except as provided in
subparagraph (B), no tax shall be imposed under
paragraph (1)(A) of subsection (a) on any short-term
capital gain dividend received from a regulated
investment company.
``(B) Exception for aliens taxable under subsection
(a)(2).--Subparagraph (A) shall not apply in the case
of any nonresident alien individual subject to tax
under subsection (a)(2).
``(C) Short-term capital gain dividend.--For
purposes of this paragraph, a short-term capital gain
dividend is any dividend (or part thereof) which is
designated by the regulated investment company as a
short-term capital gain dividend in a written notice
mailed to its shareholders not later than 60 days after
the close of its taxable year. If the aggregate amount
so designated with respect to a taxable year of the
company (including amounts so designated with respect
to dividends paid after the close of the taxable year
described in section 855) is greater than the qualified
short-term gain of the company for such taxable year,
the portion of each distribution which shall be a
short-term capital gain dividend shall be only that
portion of the amounts so designated which such
qualified short-term gain bears to the aggregate amount
so designated.
``(D) Qualified short-term gain.--For purposes of
subparagraph (C), the term `qualified short-term gain'
means the excess of the net short-term capital gain of
the regulated investment company for the taxable year
over the net long-term capital loss (if any) of such
company for such taxable year. For purposes of this
subparagraph--
``(i) the net short-term capital gain of
the regulated investment company shall be
computed by treating any short-term capital
gain dividend includible in gross income with
respect to stock of another regulated
investment company as a short-term capital
gain, and
``(ii) the excess of the net short-term
capital gain for a taxable year over the net
long-term capital loss for a taxable year (to
which an election under section 4982(e)(4) does
not apply) shall be determined without regard
to any net capital loss or net short-term
capital loss attributable to transactions after
October 31 of such year, and any such net
capital loss or net short-term capital loss
shall be treated as arising on the 1st day of
the next taxable year.
To the extent provided in regulations, clause (ii)
shall apply also for purposes of computing the taxable
income of the regulated investment company.''
(2) Foreign corporations.--Section 881 (relating to tax on
income of foreign corporations not connected with United States
business) is amended by redesignating subsection (e) as
subsection (f) and by inserting after subsection (d) the
following new subsection:
``(e) Tax Not To Apply to Certain Dividends of Regulated Investment
Companies.--
``(1) Interest-related dividends.--
``(A) In general.--Except as provided in
subparagraph (B), no tax shall be imposed under
paragraph (1) of subsection (a) on any interest-related
dividend (as defined in section 871(k)(1)) received
from a regulated investment company.
``(B) Exception.--Subparagraph (A) shall not
apply--
``(i) to any dividend referred to in
section 871(k)(1)(B), and
``(ii) to any interest-related dividend
received by a controlled foreign corporation
(within the meaning of section 957(a)) to the
extent such dividend is attributable to
interest received by the regulated investment
company from a person who is a related person
(within the meaning of section 864(d)(4)) with
respect to such controlled foreign corporation.
``(C) Treatment of dividends received by controlled
foreign corporations.--The rules of subsection
(c)(5)(A) shall apply to any interest-related dividend
received by a controlled foreign corporation (within
the meaning of section 957(a)) to the extent such
dividend is attributable to interest received by the
regulated investment company which is described in
clause (ii) of section 871(k)(1)(E) (and not described
in clause (i) or (iii) of such section).
``(2) Short-term capital gain dividends.--No tax shall be
imposed under paragraph (1) of subsection (a) on any short-term
capital gain dividend (as defined in section 871(k)(2))
received from a regulated investment company.''
(3) Withholding taxes.--
(A) Section 1441(c) (relating to exceptions) is
amended by adding at the end the following new
paragraph:
``(12) Certain dividends received from regulated investment
companies.--
``(A) In general.--No tax shall be required to be
deducted and withheld under subsection (a) from any
amount exempt from the tax imposed by section
871(a)(1)(A) by reason of section 871(k).
``(B) Special rule.--For purposes of subparagraph
(A), clause (i) of section 871(k)(1)(B) shall not apply
to any dividend unless the regulated investment company
knows that such dividend is a dividend referred to in
such clause. A similar rule shall apply with respect to
the exception contained in section 871(k)(2)(B).''
(B) Section 1442(a) (relating to withholding of tax
on foreign corporations) is amended--
(i) by striking ``and the reference in
section 1441(c)(10)'' and inserting ``the
reference in section 1441(c)(10)'', and
(ii) by inserting before the period at the
end the following: ``, and the references in
section 1441(c)(12) to sections 871(a) and
871(k) shall be treated as referring to
sections 881(a) and 881(e) (except that for
purposes of applying subparagraph (A) of
section 1441(c)(12), as so modified,
clause (ii) of section 881(e)(1)(B) shall not apply to any dividend
unless the regulated investment company knows that such dividend is a
dividend referred to in such clause)''.
(b) Estate Tax Treatment of Interest in Certain Regulated
Investment Companies.--Section 2105 (relating to property without the
United States for estate tax purposes) is amended by adding at the end
the following new subsection:
``(d) Stock in a RIC.--
``(1) In general.--For purposes of this subchapter, stock
in a regulated investment company (as defined in section 851)
owned by a nonresident not a citizen of the United States shall
not be deemed property within the United States in the
proportion that, at the end of the quarter of such investment
company's taxable year immediately preceding a decedent's date
of death (or at such other time as the Secretary may designate
in regulations), the assets of the investment company that were
qualifying assets with respect to the decedent bore to the
total assets of the investment company.
``(2) Qualifying assets.--For purposes of this subsection,
qualifying assets with respect to a decedent are assets that,
if owned directly by the decedent, would have been--
``(A) amounts, deposits, or debt obligations
described in subsection (b) of this section,
``(B) debt obligations described in the last
sentence of section 2104(c), or
``(C) other property not within the United
States.''
(c) Treatment of Regulated Investment Companies Under Section
897.--
(1) Paragraph (1) of section 897(h) is amended by striking
``REIT'' each place it appears and inserting ``qualified
investment entity''.
(2) Paragraphs (2) and (3) of section 897(h) are amended to
read as follows:
``(2) Sale of stock in domestically controlled entity not
taxed.--The term `United States real property interest' does
not include any interest in a domestically controlled qualified
investment entity.
``(3) Distributions by domestically controlled qualified
investment entities.--In the case of a domestically controlled
qualified investment entity, rules similar to the rules of
subsection (d) shall apply to the foreign ownership percentage
of any gain.''
(3) Subparagraphs (A) and (B) of section 897(h)(4) are
amended to read as follows:
``(A) Qualified investment entity.--The term
`qualified investment entity' means any real estate
investment trust and any regulated investment company.
``(B) Domestically controlled.--The term
`domestically controlled qualified investment entity'
means any qualified investment entity in which at all
times during the testing period less than 50 percent in
value of the stock was held directly or indirectly by
foreign persons.''
(4) Subparagraphs (C) and (D) of section 897(h)(4) are each
amended by striking ``REIT'' and inserting ``qualified
investment entity''.
(5) The subsection heading for subsection (h) of section
897 is amended by striking ``REITS'' and inserting ``Certain
Investment Entities''.
(d) Effective Date.--
(1) In general.--Except as otherwise provided in this
subsection, the amendments made by this section shall apply to
dividends with respect to taxable years of regulated investment
companies beginning after the date of the enactment of this
Act.
(2) Estate tax treatment.--The amendment made by subsection
(b) shall apply to estates of decedents dying after the date of
the enactment of this Act.
(3) Certain other provisions.--The amendments made by
subsection (c) (other than paragraph (1) thereof) shall take
effect on the date of the enactment of this Act.

Subtitle I--Other Provisions

SEC. 1101. SPECIAL RULES FOR LIVESTOCK SOLD ON ACCOUNT OF WEATHER-
RELATED CONDITIONS.

(a) Rules for Replacement of Involuntarily Converted Livestock.--
Subsection (e) of section 1033 (relating to involuntary conversions) is
amended--
(1) by striking ``Conditions.--For purposes'' and inserting
``Conditions.--
``(1) In general.--For purposes'', and
(2) by adding at the end the following new paragraph:
``(2) Extension of replacement period.--
``(A) In general.--In the case of drought, flood,
or other weather-related conditions described in
paragraph (1) which result in the area being designated
as eligible for assistance by the Federal Government,
subsection (a)(2)(B) shall be applied with respect to
any converted property by substituting `4 years' for `2
years'.
``(B) Further extension by secretary.--The
Secretary may extend on a regional basis the period for
replacement under this section (after the application
of subparagraph (A)) for such additional time as the
Secretary determines appropriate if the weather-related
conditions which resulted in such application continue
for more than 3 years.''.
(b) Income Inclusion Rules.--Subsection (e) of section 451
(relating to special rule for proceeds from livestock sold on account
of drought, flood, or other weather-related conditions) is amended by
adding at the end the following new paragraph:
``(3) Special election rules.--If section 1033(e)(2)
applies to a sale or exchange of livestock described in
paragraph (1), the election under paragraph (1) shall be deemed
valid if made during the replacement period described in such
section.''.
(c) Effective Date.--The amendments made by this section shall
apply to any taxable year with respect to which the due date (without
regard to extensions) for the return is after December 31, 2002.

SEC. 1102. PAYMENT OF DIVIDENDS ON STOCK OF COOPERATIVES WITHOUT
REDUCING PATRONAGE DIVIDENDS.

(a) In General.--Subsection (a) of section 1388 (relating to
patronage dividend defined) is amended by adding at the end the
following: ``For purposes of paragraph (3), net earnings shall not be
reduced by amounts paid during the year as dividends on capital stock
or other proprietary capital interests of the organization to the
extent that the articles of incorporation or bylaws of such
organization or other contract with patrons provide that such dividends
are in addition to amounts otherwise payable to patrons which are
derived from business done with or for patrons during the taxable
year.''.
(b) Effective Date.--The amendment made by this section shall apply
to distributions in taxable years beginning after the date of the
enactment of this Act.

SEC. 1103. VACCINE TAX TO APPLY TO HEPATITIS A VACCINE.

(a) In General.--Paragraph (1) of section 4132(a) (defining taxable
vaccine) is amended by redesignating subparagraphs (I), (J), (K), and
(L) as subparagraphs (J), (K), (L), and (M), respectively, and by
inserting after subparagraph (H) the following new subparagraph:
``(I) Any vaccine against hepatitis A.''
(b) Effective Date.--
(1) Sales, etc.--The amendments made by subsection (a)
shall apply to sales and uses on or after the first day of the
first month which begins more than 4 weeks after the date of
the enactment of this Act.
(2) Deliveries.--For purposes of paragraph (1) and section
4131 of the Internal Revenue Code of 1986, in the case of sales
on or before the effective date described in such paragraph for
which delivery is made after such date, the delivery date shall
be considered the sale date.

SEC. 1104. EXPANSION OF HUMAN CLINICAL TRIALS QUALIFYING FOR ORPHAN
DRUG CREDIT.

(a) In General.--Paragraph (2) of section 45C(b) (relating to
qualified clinical testing expenses) is amended by adding at the end
the following new subparagraph:
``(C) Treatment of certain expenses incurred before
designation.--For purposes of subparagraph (A)(ii)(I),
if a drug is designated under section 526 of the
Federal Food, Drug, and Cosmetic Act not later than the
due date (including extensions) for filing the return
of tax under this subtitle for the taxable year in
which the application for such designation of such drug
was filed, such drug shall be treated as having been
designated on the date that such application was
filed.''.
(b) Effective Date.--The amendment made by subsection (a) shall
apply to expenses incurred after the date of the enactment of this Act.

SEC. 1105. DISTRIBUTIONS FROM PUBLICLY TRADED PARTNERSHIPS TREATED AS
QUALIFYING INCOME OF REGULATED INVESTMENT COMPANIES.

(a) In General.--Paragraph (2) of section 851(b) (defining
regulated investment company) is amended to read as follows:
``(2) at least 90 percent of its gross income is derived
from--
``(A) dividends, interest, payments with respect to
securities loans (as defined in section 512(a)(5)), and
gains from the sale or other disposition of stock or
securities (as defined in section 2(a)(36) of the
Investment Company Act of 1940, as amended) or foreign
currencies, or other income (including but not limited
to gains from options, futures or forward contracts)
derived with respect to its business of investing in
such stock, securities, or currencies, and
``(B) distributions or other income derived from an
interest in a qualified publicly traded partnership (as
defined in subsection (h)); and''.
(b) Source Flow-Through Rule Not To Apply.--The last sentence of
section 851(b) is amended by inserting ``(other than a qualified
publicly traded partnership as defined in subsection (h))'' after
``derived from a partnership''.
(c) Limitation on Ownership.--Subsection (c) of section 851 is
amended by redesignating paragraph (5) as paragraph (6) and inserting
after paragraph (4) the following new paragraph:
``(5) The term `outstanding voting securities of such
issuer' shall include the equity securities of a qualified
publicly traded partnership (as defined in subsection (h)).''.
(d) Definition of Qualified Publicly Traded Partnership.--Section
851 is amended by adding at the end the following new subsection:
``(h) Qualified Publicly Traded Partnership.--For purposes of this
section, the term `qualified publicly traded partnership' means a
publicly traded partnership described in section 7704(b) other than a
partnership which would satisfy the gross income requirements of
section 7704(c)(2) if qualifying income included only income described
in subsection (b)(2)(A).''.
(e) Definition of Qualifying Income.--Section 7704(d)(4) is amended
by striking ``section 851(b)(2)'' and inserting ``section
851(b)(2)(A)''.
(f) Limitation on Composition of Assets.--Subparagraph (B) of
section 851(b)(3) is amended to read as follows:
``(B) not more than 25 percent of the value of its
total assets is invested in--
``(i) the securities (other than Government
securities or the securities of other regulated
investment companies) of any one issuer,
``(ii) the securities (other than the
securities of other regulated investment
companies) of two or more issuers which the
taxpayer controls and which are determined,
under regulations prescribed by the Secretary,
to be engaged in the same or similar trades or
businesses or related trades or businesses, or
``(iii) the securities of one or more
qualified publicly traded partnerships (as
defined in subsection (h)).''.
(g) Application of Special Passive Activity Rule to Regulated
Investment Companies.--Subsection (k) of section 469 (relating to
separate application of section in case of publicly traded
partnerships) is amended by adding at the end the following new
paragraph:
``(4) Application to regulated investment companies.--For
purposes of this section, a regulated investment company (as
defined in section 851) holding an interest in a qualified
publicly traded partnership (as defined in section 851(h))
shall be treated as a taxpayer described in subsection (a)(2)
with respect to items attributable to such interest.''.
(h) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after the date of the enactment of
this Act.

SEC. 1106. IMPROVEMENTS RELATED TO REAL ESTATE INVESTMENT TRUSTS.

(a) Expansion of Straight Debt Safe Harbor.--Section 856 (defining
real estate investment trust) is amended--
(1) in subsection (c) by striking paragraph (7), and
(2) by adding at the end the following new subsection:
``(m) Safe Harbor in Applying Subsection (c)(4).--
``(1) In general.--In applying subclause (III) of
subsection (c)(4)(B)(iii), except as otherwise determined by
the Secretary in regulations, the following shall not be
considered securities held by the trust:
``(A) Straight debt securities of an issuer which
meet the requirements of paragraph (2).
``(B) Any loan to an individual or an estate.
``(C) Any section 467 rental agreement (as defined
in section 467(d)), other than with a person described
in subsection (d)(2)(B).
``(D) Any obligation to pay rents from real
property (as defined in subsection (d)(1)).
``(E) Any security issued by a State or any
political subdivision thereof, the District of
Columbia, a foreign government or any political
subdivision thereof, or the Commonwealth of Puerto
Rico, but only if the determination of any payment
received or accrued under such security does not depend
in whole or in part on the profits of any entity not
described in this subparagraph or payments on any
obligation issued by such an entity,
``(F) Any security issued by a real estate
investment trust.
``(G) Any other arrangement as determined by the
Secretary.
``(2) Special rules relating to straight debt securities.--
``(A) In general.--For purposes of paragraph
(1)(A), securities meet the requirements of this
paragraph if such securities are straight debt, as
defined in section 1361(c)(5) (without regard to
subparagraph (B)(iii) thereof).
``(B) Special rules relating to certain
contingencies.--For purposes of subparagraph (A), any
interest or principal shall not be treated as failing
to satisfy section 1361(c)(5)(B)(i) solely by reason of
the fact that the time of payment of such interest or
principal is subject to a contingency, but only if--
``(i) any such contingency does not have
the effect of changing the effective yield to
maturity, as determined under section 1272,
other than a change in the annual yield to
maturity which either--
``(I) does not exceed the greater
of \1/4\ of 1 percent or 5 percent of
the annual yield to maturity, or
``(II) results solely from a
default or the exercise of a prepayment
right by the issuer of the debt, or
``(ii) neither the aggregate issue price
nor the aggregate face amount of the issuer's
debt instruments held by the trust exceeds
$1,000,000 and not more than 12 months of
unaccrued interest can be required to be
prepaid thereunder.
``(C) Special rules relating to corporate or
partnership issuers.--In the case of an issuer which is
a corporation or a partnership, securities that
otherwise would be described in paragraph (1)(A) shall
be considered not to be so described if the trust
holding such securities and any of its controlled
taxable REIT subsidiaries (as defined in subsection
(d)(8)(A)(iv)) hold any securities of the issuer
which--
``(i) are not described in paragraph (1)
(prior to the application of this
subparagraph), and
``(ii) have an aggregate value greater than
1 percent of the issuer's outstanding
securities determined without regard to
paragraph (3)(A)(i).
``(3) Look-through rule for partnership securities.--
``(A) In general.--For purposes of applying
subclause (III) of subsection (c)(4)(B)(iii)--
``(i) a trust's interest as a partner in a
partnership (as defined in section 7701(a)(2))
shall not be considered a security, and
``(ii) the trust shall be deemed to own its
proportionate share of each of the assets of
the partnership.
``(B) Determination of trust's interest in
partnership assets.--For purposes of subparagraph (A),
with respect to any taxable year beginning after the
date of the enactment of this subparagraph--
``(i) the trust's interest in the
partnership assets shall be the trust's
proportionate interest in any securities issued
by the partnership (determined without regard
to subparagraph (A)(i) and paragraph (4),
but not including securities described in paragraph (1)), and
``(ii) the value of any debt instrument
shall be the adjusted issue price thereof, as
defined in section 1272(a)(4).
``(4) Certain partnership debt instruments not treated as a
security.--For purposes of applying subclause (III) of
subsection (c)(4)(B)(iii)--
``(A) any debt instrument issued by a partnership
and not described in paragraph (1) shall not be
considered a security to the extent of the trust's
interest as a partner in the partnership, and
``(B) any debt instrument issued by a partnership
and not described in paragraph (1) shall not be
considered a security if at least 75 percent of the
partnership's gross income (excluding gross income from
prohibited transactions) is derived from sources
referred to in subsection (c)(3).
``(5) Secretarial guidance.--The Secretary is authorized to
provide guidance (including through the issuance of a written
determination, as defined in section 6110(b)) that an
arrangement shall not be considered a security held by the
trust for purposes of applying subclause (III) of subsection
(c)(4)(B)(iii) notwithstanding that such arrangement otherwise
could be considered a security under subparagraph (F) of
subsection (c)(5).''.
(b) Clarification of Application of Limited Rental Exception.--
Subparagraph (A) of section 856(d)(8) (relating to special rules for
taxable REIT subsidiaries) is amended to read as follows:
``(A) Limited rental exception.--
``(i) In general.--The requirements of this
subparagraph are met with respect to any
property if at least 90 percent of the leased
space of the property is rented to persons
other than taxable REIT subsidiaries of such
trust and other than persons described in
paragraph (2)(B).
``(ii) Rents must be substantially
comparable.--Clause (i) shall apply only to the
extent that the amounts paid to the trust as
rents from real property (as defined in
paragraph (1) without regard to paragraph
(2)(B)) from such property are substantially
comparable to such rents paid by the other
tenants of the trust's property for comparable
space.
``(iii) Times for testing rent
comparability.--The substantial comparability
requirement of clause (ii) shall be treated as
met with respect to a lease to a taxable REIT
subsidiary of the trust if such requirement is
met under the terms of the lease--
``(I) at the time such lease is
entered into,
``(II) at the time of each
extension of the lease, including a
failure to exercise a right to
terminate, and
``(III) at the time of any
modification of the lease between the
trust and the taxable REIT subsidiary
if the rent under such lease is
effectively increased pursuant to such
modification.
With respect to subclause (III), if the taxable
REIT subsidiary of the trust is a controlled
taxable REIT subsidiary of the trust, the term
`rents from real property' shall not in any
event include rent under such lease to the
extent of the increase in such rent on account
of such modification.
``(iv) Controlled taxable reit
subsidiary.--For purposes of clause (iii), the
term `controlled taxable REIT subsidiary'
means, with respect to any real estate
investment trust, any taxable REIT subsidiary
of such trust if such trust owns directly or
indirectly--
``(I) stock possessing more than 50
percent of the total voting power of
the outstanding stock of such
subsidiary, or
``(II) stock having a value of more
than 50 percent of the total value of
the outstanding stock of such
subsidiary.
``(v) Continuing qualification based on
third party actions.--If the requirements of
clause (i) are met at a time referred to in
clause (iii), such requirements shall continue
to be treated as met so long as there is no
increase in the space leased to any taxable
REIT subsidiary of such trust or to any person
described in paragraph (2)(B).
``(vi) Correction period.--If there is an
increase referred to in clause (v) during any
calendar quarter with respect to any property,
the requirements of clause (iii) shall be
treated as met during the quarter and the
succeeding quarter if such requirements are met
at the close of such succeeding quarter.''.
(c) Deletion of Customary Services Exception.--Subparagraph (B) of
section 857(b)(7) (relating to redetermined rents) is amended by
striking clause (ii) and by redesignating clauses (iii), (iv), (v),
(vi), and (vii) as clauses (ii), (iii), (iv), (v), and (vi),
respectively.
(d) Conformity With General Hedging Definition.--Subparagraph (G)
of section 856(c)(5) (relating to treatment of certain hedging
instruments) is amended to read as follows:
``(G) Treatment of certain hedging instruments.--
Except to the extent provided by regulations, any
income of a real estate investment trust from a hedging
transaction (as defined in clause (ii) or (iii) of
section 1221(b)(2)(A)) which is clearly identified
pursuant to section 1221(a)(7), including gain from the
sale or disposition of such a transaction, shall not
constitute gross income under paragraph (2) to the
extent that the transaction hedges any indebtedness
incurred or to be incurred by the trust to acquire or
carry real estate assets.''.
(e) Conformity With Regulated Investment Company Rules.--Clause (i)
of section 857(b)(5)(A) (relating to imposition of tax in case of
failure to meet certain requirements) is amended by striking ``90
percent'' and inserting ``95 percent''.
(f) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
beginning after December 31, 2000.
(2) Subparagraphs (c) through  (e).--The amendments made by
subsections (c), (d), and (e) shall apply to taxable years
beginning after the date of the enactment of this Act.

SEC. 1107. SIMPLIFICATION OF EXCISE TAX IMPOSED ON BOWS AND ARROWS.

(a) Bows.--Paragraph (1) of section 4161(b) (relating to bows) is
amended to read as follows:
``(1) Bows.--
``(A) In general.--There is hereby imposed on the
sale by the manufacturer, producer, or importer of any
bow which has a peak draw weight of 30 pounds or more,
a tax equal to 11 percent of the price for which so sold.
``(B) Archery equipment.--There is hereby imposed
on the sale by the manufacturer, producer, or
importer--
``(i) of any part or accessory suitable for
inclusion in or attachment to a bow described
in subparagraph (A), and
``(ii) of any quiver or broadhead suitable
for use with an arrow described in paragraph
(3),
a tax equal to 11 percent of the price for which so
sold.''.
(b) Arrows.--Subsection (b) of section 4161 (relating to bows and
arrows, etc.) is amended by redesignating paragraph (3) as paragraph
(4) and inserting after paragraph (2) the following:
``(3) Arrows.--
``(A) In general.--There is hereby imposed on the
sale by the manufacturer, producer, or importer of any
arrow, a tax equal to 12 percent of the price for which
so sold.
``(B) Exception.--The tax imposed by subparagraph
(A) on an arrow shall not apply if the arrow contains
an arrow shaft with respect to which tax was paid under
paragraph (2).
``(C) Arrow.--For purposes of this paragraph, the
term `arrow' means any shaft described in paragraph (2)
to which additional components are attached.''.
(c) Conforming Amendments.--(1) Section 4161(b)(2) is amended by
inserting ``(other than a broadhead)'' after ``point''.
(2) The heading of section 4161(b)(2) is amended by striking
``Arrows.--'' and inserting ``Arrow components.--''.
(d) Effective Date.--The amendments made by this section shall
apply to articles sold by the manufacturer, producer, or importer after
December 31, 2003.

SEC. 1108. REPEAL OF EXCISE TAX ON FISHING TACKLE BOXES.

(a) Repeal.--Paragraph (6) of section 4162(a) (defining sport
fishing equipment) is amended by striking subparagraph (C) and by
redesignating subparagraphs (D) through (J) as subparagraphs (C)
through (I), respectively.
(b) Effective Date.--The amendments made this section shall apply
to articles sold by the manufacturer, producer, or importer after
December 31, 2003.

SEC. 1109. INCOME TAX CREDIT TO DISTILLED SPIRITS WHOLESALERS FOR COST
OF CARRYING FEDERAL EXCISE TAXES ON BOTTLED DISTILLED
SPIRITS.

(a) In General.--Subpart A of part I of subchapter A of chapter 51
(relating to gallonage and occupational taxes) is amended by adding at
the end the following new section:

``SEC. 5011. INCOME TAX CREDIT FOR WHOLESALER'S AVERAGE COST OF
CARRYING EXCISE TAX.

``(a) In General.--For purposes of section 38, in the case of an
eligible wholesaler, the amount of the distilled spirits wholesalers
credit for any taxable year is the amount equal to the product of--
``(1) the number of cases of bottled distilled spirits--
``(A) which were bottled in the United States, and
``(B) which are purchased by such wholesaler during
the taxable year directly from the bottler of such
spirits, and
``(2) the average tax-financing cost per case for the most
recent calendar year ending before the beginning of such
taxable year.
``(b) Eligible Wholesaler.--For purposes of this section, the term
`eligible wholesaler' means any person who holds a permit under the
Federal Alcohol Administration Act as a wholesaler of distilled
spirits.
``(c) Average Tax-Financing Cost.--
``(1) In general.--For purposes of this section, the
average tax-financing cost per case for any calendar year is
the amount of interest which would accrue at the deemed
financing rate during a 60-day period on an amount equal to the
deemed Federal excise per case.
``(2) Deemed financing rate.--For purposes of paragraph
(1), the deemed financing rate for any calendar year is the
average of the corporate overpayment rates under paragraph (1)
of section 6621(a) (determined without regard to the last
sentence of such paragraph) for calendar quarters of such year.
``(3) Deemed federal excise tax based on case of 12 80-
proof 750ml bottles.--For purposes of paragraph (1), the deemed
Federal excise tax per case is $22.83.
``(4) Number of cases in lot.--For purposes of this
section, the number of cases in any lot of distilled spirits
shall be determined by dividing the number of liters in such
lot by 9.''
(b) Conforming Amendments.--
(1) Subsection (b) of section 38 is amended by striking
``plus'' at the end of paragraph (14), by striking the period
at the end of paragraph (15) and inserting ``, plus'', and by
adding at the end the following new paragraph:
``(16) in the case of an eligible wholesaler (as defined in
section 5011(b)), the distilled spirits wholesaler credit
determined under section 5011(a).''
(2) Subsection (d) of section 39 (relating to carryback and
carryforward of unused credits) is amended by adding at the end
the following new paragraph:
``(11) No carryback of section 5011 credit before january
1, 2004.--No portion of the unused business credit for any
taxable year which is attributable to the credit determined
under section 5011(a) may be carried back to a taxable year
beginning before January 1, 2004.''.
(3) The table of sections for subpart A of part I of
subchapter A of chapter 51 is amended by adding at the end the
following new item:

``Sec. 5011. Income tax credit for
wholesaler's average cost of
carrying excise tax.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 1110. CAPITAL GAIN TREATMENT UNDER SECTION 631(B) TO APPLY TO
OUTRIGHT SALES BY LANDOWNERS.

(a) In General.--The first sentence of section 631(b) (relating to
disposal of timber with a retained economic interest) is amended by
striking ``retains an economic interest in such timber'' and inserting
``either retains an economic interest in such timber or makes an
outright sale of such timber''.
(b) Conforming Amendments.--
(1) The third sentence of section 631(b) is amended by
striking ``The date of disposal'' and inserting ``In the case
of disposal of timber with a retained economic interest, the
date of disposal''.
(2) The heading for section 631(b) is amended by striking
``With a Retained Economic Interest''.
(c) Effective Date.--The amendments made by this section shall
apply to sales after December 31, 2003.

SEC. 1111. SONAR DEVICES SUITABLE FOR FINDING FISH.

(a) Not Treated as Sport Fishing Equipment.--Subsection (a) of
section 4162 (relating to sport fishing equipment defined) is amended
by inserting ``and'' at the end of paragraph (8), by striking ``, and''
at the end of paragraph (9) and inserting a period, and by striking
paragraph (10).
(b) Conforming Amendment.--Section 4162 is amended by striking
subsection (b) and by redesignating subsection (c) as subsection (b).
(c) Effective Date.--The amendments made this section shall apply
to articles sold by the manufacturer, producer, or importer after
December 31, 2003.

SEC. 1112. TAXATION OF CERTAIN SETTLEMENT FUNDS.

(a) In General.--Subsection (g) of section 468B (relating to
clarification of taxation of certain funds) is amended to read as
follows:
``(g) Clarification of Taxation of Certain Funds.--
``(1) In general.--Except as provided in paragraph (2),
nothing in any provision of law shall be construed as providing
that an escrow account, settlement fund, or similar fund is not
subject to current income tax. The Secretary shall prescribe
regulations providing for the taxation of any such account or
fund whether as a grantor trust or otherwise.
``(2) Exemption from tax for certain settlement funds.--An
escrow account, settlement fund, or similar fund shall be
treated as beneficially owned by the United States and shall be
exempt from taxation under this subtitle if--
``(A) it is established pursuant to a consent
decree entered by a judge of a United States District
Court,
``(B) it is created for the receipt of settlement
payments as directed by a government entity for the
sole purpose of resolving or satisfying one or more
claims asserting liability under the Comprehensive
Environmental Response, Compensation, and Liability Act
of 1980,
``(C) the authority and control over the
expenditure of funds therein (including the expenditure
of contributions thereto and any net earnings thereon)
is with such government entity, and
``(D) upon termination, any remaining funds will be
disbursed upon instructions by such government entity
in accordance with applicable law.
For purposes of this paragraph, the term `government entity'
means the United States, any State or political subdivision
thereof, the District of Columbia, any possession of the United
States, and any agency or instrumentality of any of the
foregoing.''.
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 1113. SUSPENSION OF OCCUPATIONAL TAXES RELATING TO DISTILLED
SPIRITS, WINE, AND BEER.

(a) In General.--Subpart G of part II of subchapter A of chapter 51
is amended by redesignating section 5148 as section 5149 and by
inserting after section 5147 the following new section:

``SEC. 5148. SUSPENSION OF OCCUPATIONAL TAX.

``(a) In General.--Notwithstanding sections 5081, 5091, 5111, 5121,
and 5131, the rate of tax imposed under such sections for the
suspension period shall be zero. During such period, persons engaged in
or carrying on a trade or business covered by such sections shall
register under section 5141 and shall comply with the recordkeeping
requirements under this part.
``(b) Suspension Period.--For purposes of subsection (a), the
suspension period is the period beginning on July 1, 2004, and ending
on June 30, 2007.''.
(b) Conforming Amendment.--Section 5117 is amended by adding at the
end the following new subsection:
``(d) Special Rule During Suspension Period.--Except as provided by
the Secretary, during the suspension period (as defined in section
5148) it shall be unlawful for any dealer to purchase distilled spirits
for resale from any person other than a wholesale dealer in liquors who
is required to keep records under section 5114.''.
(c) Clerical Amendment.--The table of sections for subpart G of
part II of subchapter A of chapter 51 is amended by striking the last
item and inserting the following new items:

``Sec. 5148. Suspension of occupational
tax.
``Sec. 5149. Cross references.''.
(d) Effective Date.--The amendments made by this section shall take
effect on the date of the enactment of this Act.

TITLE II--PROVISIONS TO REDUCE TAX AVOIDANCE THROUGH CORPORATE EARNINGS
STRIPPING AND EXPATRIATION

SEC. 2001. REDUCTION IN POTENTIAL FOR EARNINGS STRIPPING BY FURTHER
LIMITING DEDUCTION FOR INTEREST ON CERTAIN INDEBTEDNESS.

(a) Reduction in Potential for Earnings Stripping.--
(1) In general.--Section 163(j) is amended by striking
paragraphs (1) and (2), by redesignating paragraphs (3) through
(8) as paragraphs (4) through (9), respectively, and by
inserting before paragraph (4), as so redesignated, the following new
paragraphs:
``(1) Limitation.--
``(A) In general.--In the case of a corporation, no
deduction shall be allowed under this chapter for
disqualified interest paid or accrued during the
taxable year.
``(B) Maximum disallowance.--The amount disallowed
under subparagraph (A) shall not exceed the sum of--
``(i) the corporation's excess interest
expense for the taxable year, and
``(ii) the corporation's excess related
party interest expense for such year.
In no event shall the disallowance under subparagraph
(A) reduce the deduction for interest below the sum of
the amount of interest includible in the gross income
of the taxpayer for such taxable year and an amount
equal to 25 percent of adjusted taxable income (35
percent in the case of the first taxable year beginning
after December 31, 2003).
``(C) Disallowed amount carried to succeeding
taxable year.--
``(i) In general.--Any amount disallowed
under subparagraph (A) for any taxable year
shall be treated as paid or accrued in the
succeeding taxable year and in the 2nd through
10th succeeding taxable years to the extent not
previously taken into account under this
subparagraph.
``(ii) Limitation on amount carried to
year.--A carryforward amount may not be taken
into account for any such succeeding taxable
year to the extent that such amount, when added
to amounts carried to such succeeding taxable
year from taxable years preceding the taxable
year from which the amount is being carried
forward, would result in (or increase) a
disallowance under subparagraph (A).
``(iii) Carryover applied separately to
categories of disqualified interest.--Clauses
(i) and (ii) shall be applied separately to
disqualified interest described in paragraph
(3)(A) and to disqualified interest described
in paragraph (3)(B). For purposes of this
subparagraph, any amount disallowed under
subparagraph (A) for any taxable year shall be
treated as disqualified interest described in
paragraph (3)(A) to the extent thereof and then
as disqualified interest described in paragraph
(3)(B).
``(2) Excess interest expense; excess related party
interest expense.--For purposes of this subsection--
``(A) Excess interest expense.--The term `excess
interest expense' means the excess (if any) of--
``(i) the corporation's net interest
expense, over
``(ii) 50 percent of the adjusted taxable
income of the corporation.
``(B) Excess related party interest expense.--The
term `excess related party interest expense' means the
excess (if any) of--
``(i) the lesser of--
``(I) the amount of disqualified
interest described in paragraph (3)(A),
or
``(II) the corporation's net
interest expense, over
``(ii) 25 percent (35 percent in the case
of the first taxable year beginning after
December 31, 2003) of the adjusted taxable
income of the corporation.
``(3) Alternative maximum disallowance.--
``(A) In general.--In the case of a corporation
with respect to which an election is in effect under
subparagraph (B), the amount disallowed under paragraph
(1)(A) shall not exceed the excess (if any) of--
``(i) the corporation's net interest
expense, over
``(ii) 30 percent of the adjusted taxable
income of the corporation.
``(B) Election.--A corporation may make a one-time
irrevocable election to have the alternative maximum
disallowance described in subparagraph (A) apply for
purposes of this subsection in lieu of paragraph
(1)(B). An election under this subparagraph shall not
apply with respect to any taxable year beginning before
January 1, 2005.
``(C) Limitation.--Subparagraph (B) shall not apply
with respect to any corporation which is--
``(i) a surrogate foreign corporation (as
defined in section 7874(a)(2)(B)),
``(ii) a corporation which would be a
surrogate foreign corporation (as so defined)
if ``December 31, 1996'' were substituted for
``March 4, 2003'' in section 7874(a), or
``(iii) a corporation which is an
expatriated entity (as defined in section
7874(a)) with respect to a corporation
described in clause (i) or (ii).''.
(2) Conforming amendment.--Paragraph (5)(B)(ii) of section
163(j), as redesignated by paragraph (1), is amended by
striking ``paragraph (5)(B)'' and inserting ``paragraph
(6)(B)''.
(b) Maintenance of Current Law for Interest Paid by Taxable REIT
Subsidiaries to REIT.--
(1) Exception from 163(j).--Paragraph (4) of section
163(j), as redesignated by subsection (a), is amended by
inserting ``and'' at the end of subparagraph (A), by striking
``, and'' at the end of subparagraph (B) and inserting a
period, and by striking subparagraph (C).
(2) Disallowance.--Section 856 is amended by adding at the
end the following new subsection:
``(n) Limitation on Deduction for Interest on Certain Indebtedness
of Taxable REIT Subsidiary.--
``(1) Limitation.--
``(A) In general.--If this subsection applies to
any taxable REIT subsidiary for any taxable year, no
deduction shall be allowed under this chapter for
disqualified interest paid or accrued by such
subsidiary during such taxable year. The amount
disallowed under the preceding sentence shall not
exceed the subsidiary's excess interest expense for the
taxable year.
``(B) Disallowed amount carried to succeeding
taxable year.--Any amount disallowed under subparagraph
(A) for any taxable year shall be treated as
disqualified interest paid or accrued in the succeeding
taxable year (and clause (ii) of paragraph (2)(A) shall
not apply for purposes of applying this subsection to
the amount so treated).
``(2) Subsidiaries to which subsection applies.--
``(A) In general.--This subsection shall apply to
any taxable REIT subsidiary for any taxable year if--
``(i) such subsidiary has excess interest
expense for such taxable year, and
``(ii) the ratio of debt to equity of such
subsidiary as of the close of such taxable year
(or on any other day during the taxable year as
the Secretary may by regulations prescribe)
exceeds 1.5 to 1.
``(B) Excess interest expense.--
``(i) In general.--For purposes of this
subsection, the term `excess interest expense'
means the excess (if any) of--
``(I) the taxable REIT subsidiary's
net interest expense, over
``(II) the sum of 50 percent of the
adjusted taxable income of the
subsidiary plus any excess limitation
carryforward under clause (ii).
``(ii) Excess limitation carryforward.--If
a taxable REIT subsidiary has an excess
limitation for any taxable year, the amount of
such excess limitation shall be an excess
limitation carryforward to the 1st succeeding
taxable year and to the 2nd and 3rd succeeding
taxable years to the extent not previously
taken into account under this clause. The
amount of such a carryforward taken into
account for any such succeeding taxable year
shall not exceed the excess interest expense
for such succeeding taxable year (determined
without regard to the carryforward from the
taxable year of such excess limitation).
``(iii) Excess limitation.--For purposes of
clause (ii), the term `excess limitation' means
the excess (if any) of--
``(I) 50 percent of the adjusted
taxable income of the subsidiary, over
``(II) the subsidiary's net
interest expense.
``(C) Ratio of debt to equity.--For purposes of
this paragraph, the term `ratio of debt to equity'
means the ratio which the total indebtedness of the
subsidiary bears to the sum of its money and all other
assets reduced (but not below zero) by such total
indebtedness. The rules of section 163(j)(6)(E) shall
apply for purposes of the preceding sentence.
``(3) Disqualified interest.--For purposes of this
subsection, the term `disqualified interest' means any interest
paid or accrued (directly or indirectly) by a taxable REIT
subsidiary of a real estate investment trust to such trust.
``(4) Other rules to apply.--Rules similar to the rules of
paragraphs (7), (8), and (9) of section 163(j) shall apply for
purposes of this subsection.''
(c) Effective Date.--
(1) In general.--Except as otherwise provided in this
subsection, the amendments made by this section shall apply to
taxable years beginning after December 31, 2003.
(2) Earlier effective date with respect to expatriated
corporations, etc.--The amendments made by this section shall
apply to taxable years ending after March 4, 2003, in the case
of a taxpayer which is--
(A) a surrogate foreign corporation, as defined in
section 7874(a)(2)(B) of the Internal Revenue Code of
1986, as added by section 2002,
(B) a corporation which would be a surrogate
foreign corporation (as so defined) if ``December 31,
1996'' were substituted for ``March 4, 2003'' in such
section 7874(a), or
(C) a corporation which is an expatriated entity
(as defined in such section 7874(a)) with respect to a
corporation described in subparagraph (A) or (B).
In applying such amendments to a taxpayer described in the
preceding sentence, subparagraph (B) of section 163(j)(2) of
such Code, as amended by this section, shall be applied by
substituting ``25 percent'' for ``35 percent''.
(3) Limitation on carryover of disallowed interest.--
(A) In general.--Except in the case of a taxpayer
described in paragraph (2), for purposes of applying
section 163(j)(1)(C) of the Internal Revenue Code of
1986 (as added by this section), amounts carried from a
taxable year beginning before January 1, 2004, to any
taxable year beginning after December 31, 2003, shall
be treated as disqualified interest described in
section 163(j)(3)(B) of such Code which is disallowed
for the most recent taxable year beginning before
January 1, 2004.
(B) Expatriated corporations.--In the case of a
taxpayer described in paragraph (2), a rule similar to
the rule of subparagraph (A) shall apply to amounts
carried from a taxable year ending on or before March
5, 2003.

SEC. 2002. TAX TREATMENT OF EXPATRIATED ENTITIES AND THEIR FOREIGN
PARENTS.

(a) In General.--Subchapter C of chapter 80 (relating to provisions
affecting more than one subtitle) is amended by adding at the end the
following new section:

``SEC. 7874. RULES RELATING TO EXPATRIATED ENTITIES AND THEIR FOREIGN
PARENTS.

``(a) Tax on Inversion Gain of Expatriated Entities.--
``(1) In general.--The taxable income of an expatriated
entity for any taxable year which includes any portion of the
applicable period shall in no event be less than the inversion
gain of the entity for the taxable year.
``(2) Expatriated entity.--For purposes of this
subsection--
``(A) In general.--The term `expatriated entity'
means--
``(i) the domestic corporation or
partnership referred to in subparagraph (B)(i)
with respect to which a foreign corporation is
a surrogate foreign corporation, and
``(ii) any United States person who is
related (within the meaning of section 267(b)
or 707(b)(1)) to a domestic corporation or
partnership described in clause (i).
``(B) Surrogate foreign corporation.--A foreign
corporation shall be treated as a surrogate foreign
corporation if, pursuant to a plan (or a series of
related transactions)--
``(i) the entity completes after March 4,
2003, the direct or indirect acquisition of
substantially all of the properties held
directly or indirectly by a domestic
corporation or substantially all of the
properties constituting a trade or business of
a domestic partnership,
``(ii) after the acquisition at least 60
percent of the stock (by vote or value) of the
entity is held--
``(I) in the case of an acquisition
with respect to a domestic corporation,
by former shareholders of the domestic
corporation by reason of holding stock
in the domestic corporation, or
``(II) in the case of an
acquisition with respect to a domestic
partnership, by former partners of the
domestic partnership by reason of
holding a capital or profits interest
in the domestic partnership, and
``(iii) after the acquisition the expanded
affiliated group which includes the entity does
not have substantial business activities in the
foreign country in which, or under the law of
which, the entity is created or organized, when
compared to the total business activities of
such expanded affiliated group.
An entity otherwise described in clause (i) with
respect to any domestic corporation or partnership
trade or business shall be treated as not so described
if, on or before March 4, 2003, such entity acquired
directly or indirectly more than half of the properties
held directly or indirectly by such corporation or more
than half of the properties constituting such
partnership trade or business, as the case may be.
``(b) Definitions and Special Rules.--
``(1) Expanded affiliated group.--The term `expanded
affiliated group' means an affiliated group as defined in
section 1504(a) but without regard to section 1504(b)(3),
except that section 1504(a) shall be applied by substituting
`more than 50 percent' for `at least 80 percent' each place it
appears.
``(2) Certain stock disregarded.--There shall not be taken
into account in determining ownership under subsection
(a)(2)(B)(ii)--
``(A) stock held by members of the expanded
affiliated group which includes the foreign
corporation, or
``(B) stock of such foreign corporation which is
sold in a public offering related to the acquisition
described in subsection (a)(2)(B)(i).
``(3) Plan deemed in certain cases.--If a foreign
corporation acquires directly or indirectly substantially all
of the properties of a domestic corporation or partnership
during the 4-year period beginning on the date which is 2 years
before the ownership requirements of subsection (a)(2)(B)(ii)
are met, such actions shall be treated as pursuant to a plan.
``(4) Certain transfers disregarded.--The transfer of
properties or liabilities (including by contribution or
distribution) shall be disregarded if such transfers are part
of a plan a principal purpose of which is to avoid the purposes
of this section.
``(5) Special rule for related partnerships.--For purposes
of applying subsection (a)(2)(B)(ii) to the acquisition of a
trade or business of a domestic partnership, except as provided
in regulations, all partnerships which are under common control
(within the meaning of section 482) shall be treated as 1
partnership.
``(6) Regulations.--The Secretary shall prescribe such
regulations as may be appropriate to determine whether a
corporation is a surrogate foreign corporation, including
regulations--
``(A) to treat warrants, options, contracts to
acquire stock, convertible debt interests, and other
similar interests as stock, and
``(B) to treat stock as not stock.
``(c) Other Definitions.--For purposes of this section--
``(1) Applicable period.--The term `applicable period'
means the period--
``(A) beginning on the first date properties are
acquired as part of the acquisition described in
subsection (a)(2)(B)(i), and
``(B) ending on the date which is 10 years after
the last date properties are acquired as part of such
acquisition.
``(2) Inversion gain.--The term `inversion gain' means the
income or gain recognized by reason of the transfer during the
applicable period of stock or other properties by an
expatriated entity, and any income received or accrued during
the applicable period by reason of a license of any property by
an expatriated entity--
``(A) as part of the acquisition described in
subsection (a)(2)(B)(i), or
``(B) after such acquisition if the transfer or
license is to a foreign related person.
Subparagraph (B) shall not apply to property described in
section 1221(a)(1) in the hands of the expatriated entity.
``(3) Foreign related person.--The term `foreign related
person' means, with respect to any expatriated entity, a
foreign person which--
``(A) is related (within the meaning of section
267(b) or 707(b)(1)) to such entity, or
``(B) is under the same common control (within the
meaning of section 482) as such entity.
``(d) Special Rules.--
``(1) Credits not allowed against tax on inversion gain.--
Credits (other than the credit allowed by section 901) shall be
allowed against the tax imposed by this chapter on an
expatriated entity for any taxable year described in subsection
(a) only to the extent such tax exceeds the product of--
``(A) the amount of the inversion gain for the
taxable year, and
``(B) the highest rate of tax specified in section
11(b)(1).
For purposes of determining the credit allowed by section 901,
inversion gain shall be treated as from sources within the
United States.
``(2) Special rules for partnerships.--In the case of an
expatriated entity which is a partnership--
``(A) subsection (a)(1) shall apply at the partner
rather than the partnership level,
``(B) the inversion gain of any partner for any
taxable year shall be equal to the sum of--
``(i) the partner's distributive share of
inversion gain of the partnership for such
taxable year, plus
``(ii) gain recognized for the taxable year
by the partner by reason of the transfer during
the applicable period of any partnership
interest of the partner in such partnership to
the surrogate foreign corporation, and
``(C) the highest rate of tax specified in the rate
schedule applicable to the partner under this chapter
shall be substituted for the rate of tax referred to in
paragraph (1).
``(3) Coordination with section 172 and minimum tax.--Rules
similar to the rules of paragraphs (3) and (4) of section
860E(a) shall apply for purposes of subsection (a).
``(4) Statute of limitations.--
``(A) In general.--The statutory period for the
assessment of any deficiency attributable to the
inversion gain of any taxpayer for any pre-inversion
year shall not expire before the expiration of 3 years
from the date the Secretary is notified by the taxpayer
(in such manner as the Secretary may prescribe) of the
acquisition described in subsection (a)(2)(B)(i) to
which such gain relates and such deficiency may be
assessed before the expiration of such 3-year period
notwithstanding the provisions of any other law or rule
of law which would otherwise prevent such assessment.
``(B) Pre-inversion year.--For purposes of
subparagraph (A), the term `pre-inversion year' means
any taxable year if--
``(i) any portion of the applicable period
is included in such taxable year, and
``(ii) such year ends before the taxable
year in which the acquisition described in
subsection (a)(2)(B)(i) is completed.
``(e) Special Rule for Treaties.--Nothing in section 894 or 7852(d)
or in any other provision of law shall be construed as permitting an
exemption, by reason of any treaty obligation of the United States
heretofore or hereafter entered into, from the provisions of this
section.
``(f) Regulations.--The Secretary shall provide such regulations as
are necessary to carry out this section, including regulations
providing for such adjustments to the application of this section as
are necessary to prevent the avoidance of the purposes of this section,
including the avoidance of such purposes through--
``(1) the use of related persons, pass-through or other
noncorporate entities, or other intermediaries, or
``(2) transactions designed to have persons cease to be (or
not become) members of expanded affiliated groups or related
persons.''.
(b) Conforming Amendment.--The table of sections for subchapter C
of chapter 80 is amended by adding at the end the following new item:

``Sec. 7874. Rules relating to
expatriated entities and their
foreign parents.''
(c) Effective Date.--The amendments made by this section shall
apply to taxable years ending after March 4, 2003.

SEC. 2003. EXCISE TAX ON STOCK COMPENSATION OF INSIDERS IN EXPATRIATED
CORPORATIONS.

(a) In General.--Subtitle D is amended by inserting after chapter
44 end the following new chapter:

``CHAPTER 45--PROVISIONS RELATING TO EXPATRIATED ENTITIES

``Sec. 4985. Stock compensation of
insiders in expatriated
corporations.

``SEC. 4985. STOCK COMPENSATION OF INSIDERS IN EXPATRIATED
CORPORATIONS.

``(a) Imposition of Tax.--In the case of an individual who is a
disqualified individual with respect to any expatriated corporation,
there is hereby imposed on such person a tax equal to 15 percent of the
value (determined under subsection (b)) of the specified stock
compensation held (directly or indirectly) by or for the benefit of
such individual or a member of such individual's family (as defined in
section 267) at any time during the 12-month period beginning on the
date which is 6 months before the expatriation date.
``(b) Value.--For purposes of subsection (a)--
``(1) In general.--The value of specified stock
compensation shall be--
``(A) in the case of a stock option (or other
similar right) or a stock appreciation right, the fair
value of such option or right, and
``(B) in any other case, the fair market value of
such compensation.
``(2) Date for determining value.--The determination of
value shall be made--
``(A) in the case of specified stock compensation
held on the expatriation date, on such date,
``(B) in the case of such compensation which is
canceled during the 6 months before the expatriation
date, on the day before such cancellation, and
``(C) in the case of such compensation which is
granted after the expatriation date, on the date such
compensation is granted.
``(c) Tax To Apply Only if Shareholder Gain Recognized.--Subsection
(a) shall apply to any disqualified individual with respect to an
expatriated corporation only if gain (if any) on any stock in such
corporation is recognized in whole or part by any shareholder by reason
of the acquisition referred to in section 7874(a)(2)(B)(i) with respect
to such corporation.
``(d) Exception Where Gain Recognized on Compensation.--Subsection
(a) shall not apply to--
``(1) any stock option which is exercised on the
expatriation date or during the 6-month period before such date
and to the stock acquired in such exercise, if income is
recognized under section 83 on or before the expatriation date
with respect to the stock acquired pursuant to such exercise,
and
``(2) any other specified stock compensation which is
exercised, sold, exchanged, distributed, cashed-out, or
otherwise paid during such period in a transaction in which
income, gain, or loss is recognized in full.
``(e) Definitions.--For purposes of this section--
``(1) Disqualified individual.--The term `disqualified
individual' means, with respect to a corporation, any
individual who, at any time during the 12-month period
beginning on the date which is 6 months before the expatriation
date--
``(A) is subject to the requirements of section
16(a) of the Securities Exchange Act of 1934 with
respect to such corporation or any member of the
expanded affiliated group which includes such
corporation, or
``(B) would be subject to such requirements if such
corporation or member were an issuer of equity
securities referred to in such section.
``(2) Expatriated corporation; expatriation date.--
``(A) Expatriated corporation.--The term
`expatriated corporation' means any corporation which
is an expatriated entity (as defined in section
7874(a)(2)). Such term includes any predecessor or
successor of such a corporation.
``(B) Expatriation date.--The term `expatriation
date' means, with respect to a corporation, the date on
which the corporation first becomes an expatriated
corporation.
``(3) Specified stock compensation.--
``(A) In general.--The term `specified stock
compensation' means payment (or right to payment)
granted by the expatriated corporation (or by any
member of the expanded affiliated group which includes
such corporation) to any person in connection with the
performance of services by a disqualified individual
for such corporation or member if the value of such
payment or right is based on (or determined by
reference to) the value (or change in value) of stock
in such corporation (or any such member).
``(B) Exceptions.--Such term shall not include--
``(i) any option to which part II of
subchapter D of chapter 1 applies, or
``(ii) any payment or right to payment from
a plan referred to in section 280G(b)(6).
``(4) Expanded affiliated group.--The term `expanded
affiliated group' means an affiliated group (as defined in
section 1504(a) without regard to section 1504(b)(3)); except
that section 1504(a) shall be applied by substituting `more
than 50 percent' for `at least 80 percent' each place it
appears.
``(f) Special Rules.--For purposes of this section--
``(1) Cancellation of restriction.--The cancellation of a
restriction which by its terms will never lapse shall be
treated as a grant.
``(2) Payment or reimbursement of tax by corporation
treated as specified stock compensation.--Any payment of the
tax imposed by this section directly or indirectly by the
expatriated corporation or by any member of the expanded
affiliated group which includes such corporation--
``(A) shall be treated as specified stock
compensation, and
``(B) shall not be allowed as a deduction under any
provision of chapter 1.
``(3) Certain restrictions ignored.--Whether there is
specified stock compensation, and the value thereof, shall be
determined without regard to any restriction other than a
restriction which by its terms will never lapse.
``(4) Property transfers.--Any transfer of property shall
be treated as a payment and any right to a transfer of property
shall be treated as a right to a payment.
``(5) Other administrative provisions.--For purposes of
subtitle F, any tax imposed by this section shall be treated as
a tax imposed by subtitle A.
``(g) Regulations.--The Secretary shall prescribe such regulations
as may be necessary or appropriate to carry out the purposes of this
section.''
(b) Denial of Deduction.--
(1) In general.--Paragraph (6) of section 275(a) is amended
by inserting ``45,'' before ``46,''.
(2) $1,000,000 limit on deductible compensation reduced by
payment of excise tax on specified stock compensation.--
Paragraph (4) of section 162(m) is amended by adding at the end
the following new subparagraph:
``(G) Coordination with excise tax on specified
stock compensation.--The dollar limitation contained in
paragraph (1) with respect to any covered employee
shall be reduced (but not below zero) by the amount of
any payment (with respect to such employee) of the tax
imposed by section 4985 directly or indirectly by the
expatriated corporation (as defined in such section) or
by any member of the expanded affiliated group (as
defined in such section) which includes such
corporation.''
(c) Conforming Amendments.--
(1) The last sentence of section 3121(v)(2)(A) is amended
by inserting before the period ``or to any specified stock
compensation (as defined in section 4985) on which tax is
imposed by section 4985''.
(2) The table of chapters for subtitle D is amended by
inserting after the item relating to chapter 44 the following
new item:

``Chapter 45. Provisions relating to
expatriated entities.''
(d) Effective Date.--The amendments made by this section shall take
effect on March 4, 2003; except that periods before such date shall not
be taken into account in applying the periods in subsections (a) and
(e)(1) of section 4985 of the Internal Revenue Code of 1986, as added
by this section.

SEC. 2004. REINSURANCE OF UNITED STATES RISKS IN FOREIGN JURISDICTIONS.

(a) In General.--Section 845(a) (relating to allocation in case of
reinsurance agreement involving tax avoidance or evasion) is amended by
striking ``source and character'' and inserting ``amount, source, or
character''.
(b) Effective Date.--The amendments made by this section shall
apply to any risk reinsured after the date of the enactment of this
Act.

SEC. 2005. REVISION OF TAX RULES ON EXPATRIATION OF INDIVIDUALS.

(a) Expatriation To Avoid Tax.--
(1) In general.--Subsection (a) of section 877 (relating to
treatment of expatriates) is amended to read as follows:
``(a) Treatment of Expatriates.--
``(1) In general.--Every nonresident alien individual to
whom this section applies and who, within the 10-year period
immediately preceding the close of the taxable year, lost
United States citizenship shall be taxable for such taxable
year in the manner provided in subsection (b) if the tax
imposed pursuant to such subsection (after any reduction in
such tax under the last sentence of such subsection) exceeds
the tax which, without regard to this section, is imposed
pursuant to section 871.
``(2) Individuals subject to this section.--This section
shall apply to any individual if--
``(A) the average annual net income tax (as defined
in section 38(c)(1)) of such individual for the period
of 5 taxable years ending before the date of the loss
of United States citizenship is greater than $122,000,
``(B) the net worth of the individual as of such
date is $2,000,000 or more, or
``(C) such individual fails to certify under
penalty of perjury that he has met the requirements of
this title for the 5 preceding taxable years or fails
to submit such evidence of such compliance as the
Secretary may require.
In the case of the loss of United States citizenship in any
calendar year after 2003, such $122,000 amount shall be
increased by an amount equal to such dollar amount multiplied
by the cost-of-living adjustment determined under section
1(f)(3) for such calendar year by substituting `2002' for
`1992' in subparagraph (B) thereof. Any increase under the
preceding sentence shall be rounded to the nearest multiple of
$1,000.''.
(2) Revision of exceptions from alternative tax.--
Subsection (c) of section 877 (relating to tax avoidance not
presumed in certain cases) is amended to read as follows:
``(c) Exceptions.--
``(1) In general.--Subparagraphs (A) and (B) of subsection
(a)(2) shall not apply to an individual described in paragraph
(2) or (3).
``(2) Dual citizens.--
``(A) In general.--An individual is described in
this paragraph if--
``(i) the individual became at birth a
citizen of the United States and a citizen of
another country and continues to be a citizen
of such other country, and
``(ii) the individual has had no
substantial contacts with the United States.
``(B) Substantial contacts.--An individual shall be
treated as having no substantial contacts with the
United States only if the individual--
``(i) was never a resident of the United
States (as defined in section 7701(b)),
``(ii) has never held a United States
passport, and
``(iii) was not present in the United
States for more than 30 days during any
calendar year which is 1 of the 10 calendar
years preceding the individual's loss of United
States citizenship.
``(3) Certain minors.--An individual is described in this
paragraph if--
``(A) the individual became at birth a citizen of
the United States,
``(B) neither parent of such individual was a
citizen of the United States at the time of such birth,
``(C) the individual's loss of United States
citizenship occurs before such individual attains age
18\1/2\, and
``(D) the individual was not present in the United
States for more than 30 days during any calendar year
which is 1 of the 10 calendar years preceding the
individual's loss of United States citizenship.''.
(3) Conforming amendment.--Section 2107(a) is amended to
read as follows:
``(a) Treatment of Expatriates.--A tax computed in accordance with
the table contained in section 2001 is hereby imposed on the transfer
of the taxable estate, determined as provided in section 2106, of every
decedent nonresident not a citizen of the United States if the date
of death occurs during a taxable year with respect to which the
decedent is subject to tax under section 877(b).''.
(b) Special Rules for Determining When an Individual Is No Longer a
United States Citizen or Long-Term Resident.--Section 7701 (relating to
definitions) is amended by redesignating subsection (n) as subsection
(o) and by inserting after subsection (m) the following new subsection:
``(n) Special Rules for Determining When an Individual Is No Longer
a United States Citizen or Long-Term Resident.--An individual who would
(but for this subsection) cease to be treated as a citizen or resident
of the United States shall continue to be treated as a citizen or
resident of the United States, as the case may be, until such
individual--
``(1) gives notice of an expatriating act or termination of
residency (with the requisite intent to relinquish citizenship
or terminate residency) to the Secretary of State or the
Secretary of Homeland Security, and
``(2) provides a statement in accordance with section
6039G.''.
(c) Physical Presence in the United States for More Than 30 Days.--
Section 877 (relating to expatriation to avoid tax) is amended by
adding at the end the following new subsection:
``(g) Physical Presence.--
``(1) In general.--This section shall not apply to any
individual to whom this section would otherwise apply for any
taxable year during the 10-year period referred to in
subsection (a) in which such individual is physically present
in the United States at any time on more than 30 days in the
calendar year ending in such taxable year, and such individual
shall be treated for purposes of this title as a citizen or
resident of the United States, as the case may be, for such
taxable year.
``(2) Exception.--
``(A) In general.--In the case of an individual
described in any of the following subparagraphs of this
paragraph, a day of physical presence in the United
States shall be disregarded if the individual is
performing services in the United States on such day
for an employer. The preceding sentence shall not apply
if--
``(i) such employer is related (within the
meaning of section 267 and 707) to such
individual, or
``(ii) such employer fails to meet such
requirements as the Secretary may prescribe by
regulations to prevent the avoidance of the
purposes of this paragraph.
Not more than 30 days during any calendar year may be
disregarded under this subparagraph.
``(B) Individuals with ties to other countries.--An
individual is described in this subparagraph if--
``(i) the individual becomes (not later
than the close of a reasonable period after
loss of United States citizenship or
termination of residency) a citizen or resident
of the country in which--
``(I) such individual was born,
``(II) if such individual is
married, such individual's spouse was
born, or
``(III) either of such individual's
parents were born, and
``(ii) the individual becomes fully liable
for income tax in such country.
``(C) Minimal prior physical presence in the united
states.--An individual is described in this
subparagraph if, for each year in the 10-year period
ending on the date of loss of United States citizenship
or termination of residency, the individual was
physically present in the United States for 30 days or
less. The rule of section 7701(b)(3)(D)(ii) shall apply
for purposes of this subparagraph.''.
(d) Transfers Subject to Gift Tax.--
(1) In general.--Subsection (a) of section 2501 (relating
to taxable transfers) is amended by striking paragraph (4), by
redesignating paragraph (5) as paragraph (4), and by striking
paragraph (3) and inserting the following new paragraph:
``(3) Exception.--
``(A) Certain individuals.--Paragraph (2) shall not
apply in the case of a donor to whom section 877(b)
applies for the taxable year which includes the date of
the transfer.
``(B) Credit for foreign gift taxes.--The tax
imposed by this section solely by reason of this
paragraph shall be credited with the amount of any gift
tax actually paid to any foreign country in respect of
any gift which is taxable under this section solely by
reason of this paragraph.''
(2) Transfers of certain stock.--Subsection (a) of section
2501 is amended by adding at the end the following new
paragraph:
``(5) Transfers of certain stock.--
``(A) In general.--In the case of a transfer of
stock in a foreign corporation described in
subparagraph (B) by a donor to whom section 877(b)
applies for the taxable year which includes the date of
the transfer--
``(i) section 2511(a) shall be applied
without regard to whether such stock is
situated within the United States, and
``(ii) the value of such stock for purposes
of this chapter shall be its U.S.-asset value
determined under subparagraph (C).
``(B) Foreign corporation described.--A foreign
corporation is described in this subparagraph with
respect to a donor if--
``(i) the donor owned (within the meaning
of section 958(a)) at the time of such transfer
10 percent or more of the total combined voting
power of all classes of stock entitled to vote
of the foreign corporation, and
``(ii) such donor owned (within the meaning
of section 958(a)), or is considered to have
owned (by applying the ownership rules of
section 958(b)), at the time of such transfer,
more than 50 percent of--
``(I) the total combined voting
power of all classes of stock entitled
to vote of such corporation, or
``(II) the total value of the stock
of such corporation.
``(C) U.S.-asset value.--For purposes of
subparagraph (A), the U.S.-asset value of stock shall
be the amount which bears the same ratio to the fair
market value of such stock at the time of transfer as--
``(i) the fair market value (at such time)
of the assets owned by such foreign corporation
and situated in the United States, bears to
``(ii) the total fair market value (at such
time) of all assets owned by such foreign
corporation.''
(e) Enhanced Information Reporting From Individuals Losing United
States Citizenship.--
(1) In general.--Subsection (a) of section 6039G is amended
to read as follows:
``(a) In General.--Notwithstanding any other provision of law, any
individual to whom section 877(b) applies for any taxable year shall
provide a statement for such taxable year which includes the
information described in subsection (b).''.
(2) Information to be provided.--Subsection (b) of section
6039G is amended to read as follows:
``(b) Information To Be Provided.--Information required under
subsection (a) shall include--
``(1) the taxpayer's TIN,
``(2) the mailing address of such individual's principal
foreign residence,
``(3) the foreign country in which such individual is
residing,
``(4) the foreign country of which such individual is a
citizen,
``(5) information detailing the income, assets, and
liabilities of such individual,
``(6) the number of days during any portion of which that
the individual was physically present in the United States
during the taxable year, and
``(7) such other information as the Secretary may
prescribe.''.
(3) Increase in penalty.--Subsection (d) of section 6039G
is amended to read as follows:
``(d) Penalty.--If--
``(1) an individual is required to file a statement under
subsection (a) for any taxable year, and
``(2) fails to file such a statement with the Secretary on
or before the date such statement is required to be filed or
fails to include all the information required to be shown on
the statement or includes incorrect information,
such individual shall pay a penalty of $10,000 unless it is shown that
such failure is due to reasonable cause and not to willful neglect.''.
(4) Conforming amendment.--Section 6039G is amended by
striking subsections (c), (f), and (g) and by redesignating
subsections (d) and (e) as subsection (c) and (d),
respectively.
(f) Effective Date.--The amendments made by this section shall
apply to individuals who expatriate after February 27, 2003.

SEC. 2006. REPORTING OF TAXABLE MERGERS AND ACQUISITIONS.

(a) In General.--Subpart B of part III of subchapter A of chapter
61 is amended by inserting after section 6043 the following new
section:

``SEC. 6043A. RETURNS RELATING TO TAXABLE MERGERS AND ACQUISITIONS.

``(a) In General.--According to the forms or regulations prescribed
by the Secretary, the acquiring corporation in any taxable acquisition
shall make a return setting forth--
``(1) a description of the acquisition,
``(2) the name and address of each shareholder of the
acquired corporation who is required to recognize gain (if any)
as a result of the acquisition,
``(3) the amount of money and the fair market value of
other property transferred to each such shareholder as part of
such acquisition, and
``(4) such other information as the Secretary may
prescribe.
To the extent provided by the Secretary, the requirements of this
section applicable to the acquiring corporation shall be applicable to
the acquired corporation and not to the acquiring corporation.
``(b) Nominees.--According to the forms or regulations prescribed
by the Secretary--
``(1) Reporting.--Any person who holds stock as a nominee
for another person shall furnish in the manner prescribed by
the Secretary to such other person the information provided by
the corporation under subsection (d).
``(2) Reporting to nominees.--In the case of stock held by
any person as a nominee, references in this section (other than
in subsection (c)) to a shareholder shall be treated as a
reference to the nominee.
``(c) Taxable Acquisition.--For purposes of this section, the term
`taxable acquisition' means any acquisition by a corporation of stock
in or property of another corporation if any shareholder of the
acquired corporation is required to recognize gain (if any) as a result
of such acquisition.
``(d) Statements To Be Furnished to Shareholders.--According to the
forms or regulations prescribed by the Secretary, every person required
to make a return under subsection (a) shall furnish to each shareholder
whose name is required to be set forth in such return a written
statement showing--
``(1) the name, address, and phone number of the
information contact of the person required to make such return,
``(2) the information required to be shown on such return
with respect to such shareholder, and
``(3) such other information as the Secretary may
prescribe.
The written statement required under the preceding sentence shall be
furnished to the shareholder on or before January 31 of the year
following the calendar year during which the taxable acquisition
occurred.''
(b) Assessable Penalties.--
(1) Subparagraph (B) of section 6724(d)(1) (relating to
definitions) is amended by redesignating clauses (ii) through
(xviii) as clauses (iii) through (xix), respectively, and by
inserting after clause (i) the following new clause:
``(ii) section 6043A(a) (relating to
returns relating to taxable mergers and
acquisitions),''.
(2) Paragraph (2) of section 6724(d) is amended by
redesignating subparagraphs (F) through (BB) as subparagraphs
(G) through (CC), respectively, and by inserting after
subparagraph (E) the following new subparagraph:
``(F) subsections (b) and (d) of section 6043A
(relating to returns relating to taxable mergers and
acquisitions).''.
(c) Clerical Amendment.--The table of sections for subpart B of
part III of subchapter A of chapter 61 is amended by inserting after
the item relating to section 6043 the following new item:

``Sec. 6043A. Returns relating to taxable
mergers and acquisitions.''.
(d) Effective Date.--The amendments made by this section shall
apply to acquisitions after the date of the enactment of this Act.

SEC. 2007. STUDIES.

(a) Transfer Pricing Rules.--The Secretary of the Treasury or the
Secretary's delegate shall conduct a study regarding the effectiveness
of current transfer pricing rules and compliance efforts in ensuring
that cross-border transfers and other related-party transactions,
particularly transactions involving intangible assets, service
contracts, or leases cannot be used improperly to shift income out of
the United States. The study shall include a review of the
contemporaneous documentation and penalty rules under section 6662 of
the Internal Revenue Code of 1986, a review of the regulatory and
administrative guidance implementing the principles of section 482 of
such Code to transactions involving intangible property and services
and to cost-sharing arrangements, and an examination of whether
increased disclosure of cross-border transactions should be required.
The study shall set forth specific recommendations to address all
abuses identified in the study. Not later than June 30, 2004, such
Secretary or delegate shall submit to the Congress a report of such
study.
(b) Income Tax Treaties.--The Secretary of the Treasury or the
Secretary's delegate shall conduct a study of United States income tax
treaties to identify any inappropriate reductions in United States
withholding tax that provide opportunities for shifting income out of
the United States, and to evaluate whether existing anti-abuse
mechanisms are operating properly. The study shall include specific
recommendations to address all inappropriate uses of tax treaties. Not
later than June 30, 2004, such Secretary or delegate shall submit to
the Congress a report of such study.
(c) Impact of Corporate Expatriation Provisions.--The Secretary of
the Treasury or the Secretary's delegate shall conduct a study of the
impact of the provisions of this title on earnings stripping and
corporate expatriation. The study shall include such recommendations as
such Secretary or delegate may have to improve the impact of such
provisions in carrying out the purposes of this title. Not later than
December 31, 2005, such Secretary or delegate shall submit to the
Congress a report of such study.

TITLE III--PROVISIONS RELATING TO TAX SHELTERS

Subtitle A--Taxpayer-Related Provisions

SEC. 3001. PENALTY FOR FAILING TO DISCLOSE REPORTABLE TRANSACTIONS.

(a) In General.--Part I of subchapter B of chapter 68 (relating to
assessable penalties) is amended by inserting after section 6707 the
following new section:

``SEC. 6707A. PENALTY FOR FAILURE TO INCLUDE REPORTABLE TRANSACTION
INFORMATION WITH RETURN.

``(a) Imposition of Penalty.--Any person who fails to include on
any return or statement any information with respect to a reportable
transaction which is required under section 6011 to be included with
such return or statement shall pay a penalty in the amount determined
under subsection (b).
``(b) Amount of Penalty.--
``(1) In general.--Except as provided in paragraph (2), the
amount of the penalty under subsection (a) shall be--
``(A) $10,000 in the case of a natural person, and
``(B) $50,000 in any other case.
``(2) Listed transaction.--The amount of the penalty under
subsection (a) with respect to a listed transaction shall be--
``(A) $100,000 in the case of a natural person, and
``(B) $200,000 in any other case.
``(c) Definitions.--For purposes of this section--
``(1) Reportable transaction.--The term `reportable
transaction' means any transaction with respect to which
information is required to be included with a return or
statement because, as determined under regulations prescribed
under section 6011, such transaction is of a type which the
Secretary determines as having a potential for tax avoidance or
evasion.
``(2) Listed transaction.--The term `listed transaction'
means a reportable transaction which is the same as, or
substantially similar to, a transaction specifically identified
by the Secretary as a tax avoidance transaction for purposes of
section 6011.
``(d) Authority To Rescind Penalty.--
``(1) In general.--The Commissioner of Internal Revenue may
rescind all or any portion of any penalty imposed by this
section with respect to any violation if--
``(A) the violation is with respect to a reportable
transaction other than a listed transaction, and
``(B) rescinding the penalty would promote
compliance with the requirements of this title and
effective tax administration.
``(2) No judicial appeal.--Notwithstanding any other
provision of law, any determination under this subsection may
not be reviewed in any judicial proceeding.
``(3) Records.--If a penalty is rescinded under paragraph
(1), the Commissioner shall place in the file in the Office of
the Commissioner the opinion of the Commissioner or the head of
the Office of Tax Shelter Analysis with respect to the
determination, including--
``(A) a statement of the facts and circumstances
relating to the violation,
``(B) the reasons for the rescission, and
``(C) the amount of the penalty rescinded.
``(e) Coordination With Other Penalties.--The penalty imposed by
this section shall be in addition to any other penalty imposed by this
title.''
(b) Conforming Amendment.--The table of sections for part I of
subchapter B of chapter 68 is amended by inserting after the item
relating to section 6707 the following:

``Sec. 6707A. Penalty for failure to
include reportable transaction
information with return.''
(c) Effective Date.--The amendments made by this section shall
apply to returns and statements the due date for which is after the
date of the enactment of this Act.
(d) Report.--The Commissioner of Internal Revenue shall annually
report to the Committee on Ways and Means of the House of
Representatives and the Committee on Finance of the Senate--
(1) a summary of the total number and aggregate amount of
penalties imposed, and rescinded, under section 6707A of the
Internal Revenue Code of 1986, and
(2) a description of each penalty rescinded under section
6707(c) of such Code and the reasons therefor.

SEC. 3002. ACCURACY-RELATED PENALTY FOR LISTED TRANSACTIONS, OTHER
REPORTABLE TRANSACTIONS HAVING A SIGNIFICANT TAX
AVOIDANCE PURPOSE, ETC.

(a) In General.--Subchapter A of chapter 68 is amended by inserting
after section 6662 the following new section:

``SEC. 6662A. IMPOSITION OF ACCURACY-RELATED PENALTY ON UNDERSTATEMENTS
WITH RESPECT TO REPORTABLE TRANSACTIONS.

``(a) Imposition of Penalty.--If a taxpayer has a reportable
transaction understatement for any taxable year, there shall be added
to the tax an amount equal to 20 percent of the amount of such
understatement.
``(b) Reportable Transaction Understatement.--For purposes of this
section--
``(1) In general.--The term `reportable transaction
understatement' means the sum of--
``(A) the product of--
``(i) the amount of the increase (if any)
in taxable income which results from a
difference between the proper tax treatment of
an item to which this section applies and the
taxpayer's treatment of such item (as shown on
the taxpayer's return of tax), and
``(ii) the highest rate of tax imposed by
section 1 (section 11 in the case of a taxpayer
which is a corporation), and
``(B) the amount of the decrease (if any) in the
aggregate amount of credits determined under subtitle A
which results from a difference between the taxpayer's
treatment of an item to which this section applies (as
shown on the taxpayer's return of tax) and the proper
tax treatment of such item.
For purposes of subparagraph (A), any reduction of the excess
of deductions allowed for the taxable year over gross income
for such year, and any reduction in the amount of capital
losses which would (without regard to section 1211) be allowed
for such year, shall be treated as an increase in taxable
income.
``(2) Items to which section applies.--This section shall
apply to any item which is attributable to--
``(A) any listed transaction, and
``(B) any reportable transaction (other than a
listed transaction) if a significant purpose of such
transaction is the avoidance or evasion of Federal
income tax.
``(c) Higher Penalty for Nondisclosed Transactions.--Subsection (a)
shall be applied by substituting `30 percent' for `20 percent' with
respect to the portion of any reportable transaction understatement
with respect to which the requirement of section 6664(d)(2)(A) is not
met.
``(d) Definitions of Reportable and Listed Transactions.--For
purposes of this section, the terms `reportable transaction' and
`listed transaction' have the respective meanings given to such terms
by section 6707A(c).
``(e) Special Rules.--
``(1) Coordination with penalties, etc., on other
understatements.--In the case of an understatement (as defined
in section 6662(d)(2))--
``(A) the amount of such understatement (determined
without regard to this paragraph) shall be increased by
the aggregate amount of reportable transaction
understatements for purposes of determining whether
such understatement is a substantial understatement
under section 6662(d)(1), and
``(B) the addition to tax under section 6662(a)
shall apply only to the excess of the amount of the
substantial understatement (if any) after the
application of subparagraph (A) over the aggregate
amount of reportable transaction understatements.
``(2) Coordination with other penalties.--
``(A) Application of fraud penalty.--References to
an underpayment in section 6663 shall be treated as
including references to a reportable transaction
understatement.
``(B) No double penalty.--This section shall not
apply to any portion of an understatement on which a
penalty is imposed under section 6663.
``(3) Special rule for amended returns.--Except as provided
in regulations, in no event shall any tax treatment included
with an amendment or supplement to a return of tax be taken
into account in determining the amount of any reportable
transaction understatement if the amendment or supplement is
filed after the earlier of the date the taxpayer is first
contacted by the Secretary regarding the examination of the
return or such other date as is specified by the Secretary.''
(b) Determination of Other Understatements.--Subparagraph (A) of
section 6662(d)(2) is amended by adding at the end the following flush
sentence:
``The excess under the preceding sentence shall be
determined without regard to items to which section
6662A applies.''
(c) Reasonable Cause Exception.--
(1) In general.--Section 6664 is amended by adding at the
end the following new subsection:
``(d) Reasonable Cause Exception for Reportable Transaction
Understatements.--
``(1) In general.--No penalty shall be imposed under
section 6662A with respect to any portion of a reportable
transaction understatement if it is shown that there was a
reasonable cause for such portion and that the taxpayer acted
in good faith with respect to such portion.
``(2) Special rules.--Paragraph (1) shall not apply to any
reportable transaction understatement unless--
``(A) the relevant facts affecting the tax
treatment of the item are adequately disclosed in
accordance with the regulations prescribed under
section 6011,
``(B) there is or was substantial authority for
such treatment, and
``(C) the taxpayer reasonably believed that such
treatment was more likely than not the proper
treatment.
A taxpayer failing to adequately disclose in accordance with
section 6011 shall be treated as meeting the requirements of
subparagraph (A) if the penalty for such failure was rescinded
under section 6707A(d).
``(3) Rules relating to reasonable belief.--For purposes of
paragraph (2)(C)--
``(A) In general.--A taxpayer shall be treated as
having a reasonable belief with respect to the tax
treatment of an item only if such belief--
``(i) is based on the facts and law that
exist at the time the return of tax which
includes such tax treatment is filed, and
``(ii) relates solely to the taxpayer's
chances of success on the merits of such
treatment and does not take into account the
possibility that a return will not be audited,
such treatment will not be raised on audit, or
such treatment will be resolved through
settlement if it is raised.
``(B) Certain opinions may not be relied upon.--
``(i) In general.--An opinion of a tax
advisor may not be relied upon to establish the
reasonable belief of a taxpayer if--
``(I) the tax advisor is described
in clause (ii), or
``(II) the opinion is described in
clause (iii).
``(ii) Disqualified tax advisors.--A tax
advisor is described in this clause if the tax
advisor--
``(I) is a material advisor (within
the meaning of section 6111(b)(1)) and
participates in the organization,
management, promotion, or sale of the
transaction or is related (within the
meaning of section 267(b) or 707(b)(1))
to any person who so participates,
``(II) is compensated directly or
indirectly by a material advisor with
respect to the transaction,
``(III) has a fee arrangement with
respect to the transaction which is
contingent on all or part of the
intended tax benefits from the
transaction being sustained, or
``(IV) as determined under
regulations prescribed by the
Secretary, has a disqualifying
financial interest with respect to the
transaction.
``(iii) Disqualified opinions.--For
purposes of clause (i), an opinion is
disqualified if the opinion--
``(I) is based on unreasonable
factual or legal assumptions (including
assumptions as to future events),
``(II) unreasonably relies on
representations, statements, findings,
or agreements of the taxpayer or any
other person,
``(III) does not identify and
consider all relevant facts, or
``(IV) fails to meet any other
requirement as the Secretary may
prescribe.''
(2) Conforming amendments.--
(A) Paragraph (1) of section 6664(c) is amended by
striking ``this part'' and inserting ``section 6662 or
6663''.
(B) The heading for subsection (c) of section 6664
is amended by inserting ``for Underpayments'' after
``Exception''.
(d) Reduction in Penalty for Substantial Understatement of Income
Tax Not To Apply to Tax Shelters.--Subparagraph (C) of section
6662(d)(2) (relating to substantial understatement of income tax) is
amended to read as follows:
``(C) Reduction not to apply to tax shelters.--
``(i) In general.--Subparagraph (B) shall
not apply to any item attributable to a tax
shelter.
``(ii) Tax shelter.--For purposes of clause
(i), the term `tax shelter' means--
``(I) a partnership or other
entity,
``(II) any investment plan or
arrangement, or
``(III) any other plan or
arrangement,
if a significant purpose of such partnership,
entity, plan, or arrangement is the avoidance
or evasion of Federal income tax.''
(e) Conforming Amendments.--
(1) Sections 461(i)(3)(C), 1274(b)(3), and 7525(b) are each
amended by striking ``section 6662(d)(2)(C)(iii)'' and
inserting ``section 6662(d)(2)(C)(ii)''.
(2) The heading for section 6662 is amended to read as
follows:

``SEC. 6662. IMPOSITION OF ACCURACY-RELATED PENALTY ON UNDERPAYMENTS.''

(3) The table of sections for part II of subchapter A of
chapter 68 is amended by striking the item relating to section
6662 and inserting the following new items:

``Sec. 6662. Imposition of accuracy-
related penalty on
underpayments.
``Sec. 6662A. Imposition of accuracy-
related penalty on
understatements with respect to
reportable transactions.''
(f) Effective Date.--The amendments made by this section shall
apply to taxable years ending after the date of the enactment of this
Act.

SEC. 3003. TAX SHELTER EXCEPTION TO CONFIDENTIALITY PRIVILEGES RELATING
TO TAXPAYER COMMUNICATIONS.

(a) In General.--Section 7525(b) (relating to section not to apply
to communications regarding corporate tax shelters) is amended to read
as follows:
``(b) Section Not To Apply to Communications Regarding Tax
Shelters.--The privilege under subsection (a) shall not apply to any
written communication which is--
``(1) between a federally authorized tax practitioner and--
``(A) any person,
``(B) any director, officer, employee, agent, or
representative of the person, or
``(C) any other person holding a capital or profits
interest in the person, and
``(2) in connection with the promotion of the direct or
indirect participation of the person in any tax shelter (as
defined in section 6662(d)(2)(C)(ii)).''
(b) Effective Date.--The amendment made by this section shall apply
to communications made on or after the date of the enactment of this
Act.

SEC. 3004. STATUTE OF LIMITATIONS FOR TAXABLE YEARS FOR WHICH REQUIRED
LISTED TRANSACTIONS NOT REPORTED.

(a) In General.--Section 6501(c) (relating to exceptions) is
amended by adding at the end the following new paragraph:
``(10) Listed transactions.--If a taxpayer fails to include
on any return or statement for any taxable year any information
with respect to a listed transaction (as defined in section
6707A(c)(2)) which is required under section 6011 to be
included with such return or statement, the time for assessment
of any tax imposed by this title with respect to such
transaction shall not expire before the date which is 1 year
after the earlier of--
``(A) the date on which the Secretary is furnished
the information so required, or
``(B) the date that a material advisor (as defined
in section 6111) meets the requirements of section 6112
with respect to a request by the Secretary under
section 6112(b) relating to such transaction with
respect to such taxpayer.''
(b) Effective Date.--The amendment made by this section shall apply
to taxable years with respect to which the period for assessing a
deficiency did not expire before the date of the enactment of this Act.

SEC. 3005. DISCLOSURE OF REPORTABLE TRANSACTIONS.

(a) In General.--Section 6111 (relating to registration of tax
shelters) is amended to read as follows:

``SEC. 6111. DISCLOSURE OF REPORTABLE TRANSACTIONS.

``(a) In General.--Each material advisor with respect to any
reportable transaction shall make a return (in such form as the
Secretary may prescribe) setting forth--
``(1) information identifying and describing the
transaction,
``(2) information describing any potential tax benefits
expected to result from the transaction, and
``(3) such other information as the Secretary may
prescribe.
Such return shall be filed not later than the date specified by the
Secretary.
``(b) Definitions.--For purposes of this section--
``(1) Material advisor.--
``(A) In general.--The term `material advisor'
means any person--
``(i) who provides any material aid,
assistance, or advice with respect to
organizing, managing, promoting, selling,
implementing, or carrying out any reportable
transaction, and
``(ii) who directly or indirectly derives
gross income in excess of the threshold amount
(or such other amount as may be prescribed by
the Secretary) for such advice or assistance.
``(B) Threshold amount.--For purposes of
subparagraph (A), the threshold amount is--
``(i) $50,000 in the case of a reportable
transaction substantially all of the tax
benefits from which are provided to natural
persons, and
``(ii) $250,000 in any other case.
``(2) Reportable transaction.--The term `reportable
transaction' has the meaning given to such term by section
6707A(c).
``(c) Regulations.--The Secretary may prescribe regulations which
provide--
``(1) that only 1 person shall be required to meet the
requirements of subsection (a) in cases in which 2 or more
persons would otherwise be required to meet such requirements,
``(2) exemptions from the requirements of this section, and
``(3) such rules as may be necessary or appropriate to
carry out the purposes of this section.''
(b) Conforming Amendments.--
(1) The item relating to section 6111 in the table of
sections for subchapter B of chapter 61 is amended to read as
follows:

``Sec. 6111. Disclosure of reportable
transactions.''
(2) So much of section 6112 as precedes subsection (c)
thereof is amended to read as follows:

``SEC. 6112. MATERIAL ADVISORS OF REPORTABLE TRANSACTIONS MUST KEEP
LISTS OF ADVISEES, ETC.

``(a) In General.--Each material advisor (as defined in section
6111) with respect to any reportable transaction (as defined in section
6707A(c)) shall (whether or not required to file a return under section
6111 with respect to such transaction) maintain (in such manner as the
Secretary may by regulations prescribe) a list--
``(1) identifying each person with respect to whom such
advisor acted as a material advisor with respect to such
transaction, and
``(2) containing such other information as the Secretary
may by regulations require.''
(3) Section 6112 is amended--
(A) by redesignating subsection (c) as subsection
(b),
(B) by inserting ``written'' before ``request'' in
subsection (b)(1) (as so redesignated), and
(C) by striking ``shall prescribe'' in subsection
(b)(2) (as so redesignated) and inserting ``may
prescribe''.
(4) The item relating to section 6112 in the table of
sections for subchapter B of chapter 61 is amended to read as
follows:

``Sec. 6112. Material advisors of
reportable transactions must
keep lists of advisees, etc.''
(5)(A) The heading for section 6708 is amended to read as
follows:

``SEC. 6708. FAILURE TO MAINTAIN LISTS OF ADVISEES WITH RESPECT TO
REPORTABLE TRANSACTIONS.''

(B) The item relating to section 6708 in the table of
sections for part I of subchapter B of chapter 68 is amended to
read as follows:

``Sec. 6708. Failure to maintain lists of
advisees with respect to
reportable transactions.''
(c) Required Disclosure Not Subject to Claim of Confidentiality.--
Paragraph (1) of section 6112(b), as redesignated by subsection (b), is
amended by adding at the end the following new flush sentence:
``For purposes of this section, the identity of any person on
such list shall not be privileged.''.
(d) Effective Date.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to transactions
with respect to which material aid, assistance, or advice
referred to in section 6111(b)(1)(A)(i) of the Internal Revenue
Code of 1986 (as added by this section) is provided after the
date of the enactment of this Act.
(2) No claim of confidentiality against disclosure.--The
amendment made by subsection (c) shall take effect as if
included in the amendments made by section 142 of the Deficit
Reduction Act of 1984.

SEC. 3006. FAILURE TO FURNISH INFORMATION REGARDING REPORTABLE
TRANSACTIONS.

(a) In General.--Section 6707 (relating to failure to furnish
information regarding tax shelters) is amended to read as follows:

``SEC. 6707. FAILURE TO FURNISH INFORMATION REGARDING REPORTABLE
TRANSACTIONS.

``(a) In General.--If a person who is required to file a return
under section 6111(a) with respect to any reportable transaction--
``(1) fails to file such return on or before the date
prescribed therefor, or
``(2) files false or incomplete information with the
Secretary with respect to such transaction,
such person shall pay a penalty with respect to such return in the
amount determined under subsection (b).
``(b) Amount of Penalty.--
``(1) In general.--Except as provided in paragraph (2), the
penalty imposed under subsection (a) with respect to any
failure shall be $50,000.
``(2) Listed transactions.--The penalty imposed under
subsection (a) with respect to any listed transaction shall be
an amount equal to the greater of--
``(A) $200,000, or
``(B) 50 percent of the gross income derived by
such person with respect to aid, assistance, or advice
which is provided with respect to the listed
transaction before the date the return is filed under
section 6111.
Subparagraph (B) shall be applied by substituting `75 percent'
for `50 percent' in the case of an intentional failure or act
described in subsection (a).
``(c) Rescission Authority.--The provisions of section 6707A(d)
(relating to authority of Commissioner to rescind penalty) shall apply
to any penalty imposed under this section.
``(d) Reportable and Listed Transactions.--For purposes of this
section, the terms `reportable transaction' and `listed transaction'
have the respective meanings given to such terms by section 6707A(c).''
(b) Clerical Amendment.--The item relating to section 6707 in the
table of sections for part I of subchapter B of chapter 68 is amended
by striking ``tax shelters'' and inserting ``reportable transactions''.
(c) Effective Date.--The amendments made by this section shall
apply to returns the due date for which is after the date of the
enactment of this Act.

SEC. 3007. MODIFICATION OF PENALTY FOR FAILURE TO MAINTAIN LISTS OF
INVESTORS.

(a) In General.--Subsection (a) of section 6708 is amended to read
as follows:
``(a) Imposition of Penalty.--
``(1) In general.--If any person who is required to
maintain a list under section 6112(a) fails to make such list
available upon written request to the Secretary in accordance
with section 6112(b) within 20 business days after the date of
such request, such person shall pay a penalty of $10,000 for
each day of such failure after such 20th day.
``(2) Reasonable cause exception.--No penalty shall be
imposed by paragraph (1) with respect to the failure on any day
if such failure is due to reasonable cause.''.
(b) Effective Date.--The amendment made by this section shall apply
to requests made after the date of the enactment of this Act.

SEC. 3008. PENALTY ON PROMOTERS OF TAX SHELTERS.

(a) Penalty on Promoting Abusive Tax Shelters.--Section 6700(a) is
amended by adding at the end the following new sentence:
``Notwithstanding the first sentence, if an activity with respect to
which a penalty imposed under this subsection involves a statement
described in paragraph (2)(A), the amount of the penalty shall be equal
to 50 percent of the gross income derived (or to be derived) from such
activity by the person on which the penalty is imposed.''
(b) Effective Date.--The amendment made by this section shall apply
to activities after the date of the enactment of this Act.

SEC. 3009. MODIFICATIONS OF SUBSTANTIAL UNDERSTATEMENT PENALTY FOR
NONREPORTABLE TRANSACTIONS.

(a) Substantial Understatement of Corporations.--Section
6662(d)(1)(B) (relating to special rule for corporations) is amended to
read as follows:
``(B) Special rule for corporations.--In the case
of a corporation other than an S corporation or a
personal holding company (as defined in section 542),
there is a substantial understatement of income tax for
any taxable year if the amount of the understatement
for the taxable year exceeds the lesser of--
``(i) 10 percent of the tax required to be
shown on the return for the taxable year (or,
if greater, $10,000), or
``(ii) $10,000,000.''
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after the date of the enactment of this Act.

SEC. 3010. MODIFICATION OF ACTIONS TO ENJOIN CERTAIN CONDUCT RELATED TO
TAX SHELTERS AND REPORTABLE TRANSACTIONS.

(a) In General.--Section 7408 (relating to action to enjoin
promoters of abusive tax shelters, etc.) is amended by redesignating
subsection (c) as subsection (d) and by striking subsections (a) and
(b) and inserting the following new subsections:
``(a) Authority To Seek Injunction.--A civil action in the name of
the United States to enjoin any person from further engaging in
specified conduct may be commenced at the request of the Secretary. Any
action under this section shall be brought in the district court of the
United States for the district in which such person resides, has his
principal place of business, or has engaged in specified conduct. The
court may exercise its jurisdiction over such action (as provided in
section 7402(a)) separate and apart from any other action brought by
the United States against such person.
``(b) Adjudication and Decree.--In any action under subsection (a),
if the court finds--
``(1) that the person has engaged in any specified conduct,
and
``(2) that injunctive relief is appropriate to prevent
recurrence of such conduct,
the court may enjoin such person from engaging in such conduct or in
any other activity subject to penalty under this title.
``(c) Specified Conduct.--For purposes of this section, the term
`specified conduct' means any action, or failure to take action,
subject to penalty under section 6700, 6701, 6707, or 6708.''
(b) Conforming Amendments.--
(1) The heading for section 7408 is amended to read as
follows:

``SEC. 7408. ACTIONS TO ENJOIN SPECIFIED CONDUCT RELATED TO TAX
SHELTERS AND REPORTABLE TRANSACTIONS.''

(2) The table of sections for subchapter A of chapter 76 is
amended by striking the item relating to section 7408 and
inserting the following new item:

``Sec. 7408. Actions to enjoin specified conduct related to tax
shelters and reportable transactions.''
(c) Effective Date.--The amendment made by this section shall take
effect on the day after the date of the enactment of this Act.

SEC. 3011. PENALTY ON FAILURE TO REPORT INTERESTS IN FOREIGN FINANCIAL
ACCOUNTS.

(a) In General.--Section 5321(a)(5) of title 31, United States
Code, is amended to read as follows:
``(5) Foreign financial agency transaction violation.--
``(A) Penalty authorized.--The Secretary of the
Treasury may impose a civil money penalty on any person
who violates, or causes any violation of, any provision
of section 5314.
``(B) Amount of penalty.--
``(i) In general.--Except as provided in
subparagraph (C), the amount of any civil
penalty imposed under subparagraph (A) shall
not exceed $5,000.
``(ii) Reasonable cause exception.--No
penalty shall be imposed under subparagraph (A)
with respect to any violation if--
``(I) such violation was due to
reasonable cause, and
``(II) the amount of the
transaction or the balance in the
account at the time of the transaction
was properly reported.
``(C) Willful violations.--In the case of any
person willfully violating, or willfully causing any
violation of, any provision of section 5314--
``(i) the maximum penalty under
subparagraph (B)(i) shall be increased to the
greater of--
``(I) $25,000, or
``(II) the amount (not exceeding
$100,000) determined under subparagraph
(D), and
``(ii) subparagraph (B)(ii) shall not
apply.
``(D) Amount.--The amount determined under this
subparagraph is--
``(i) in the case of a violation involving
a transaction, the amount of the transaction,
or
``(ii) in the case of a violation involving
a failure to report the existence of an account
or any identifying information required to be
provided with respect to an account, the
balance in the account at the time of the
violation.''
(b) Effective Date.--The amendment made by this section shall apply
to violations occurring after the date of the enactment of this Act.

SEC. 3012. REGULATION OF INDIVIDUALS PRACTICING BEFORE THE DEPARTMENT
OF THE TREASURY.

(a) Censure; Imposition of Penalty.--
(1) In general.--Section 330(b) of title 31, United States
Code, is amended--
(A) by inserting ``, or censure,'' after
``Department'', and
(B) by adding at the end the following new flush
sentence:
``The Secretary may impose a monetary penalty on any representative
described in the preceding sentence. If the representative was acting
on behalf of an employer or any firm or other entity in connection with
the conduct giving rise to such penalty, the Secretary may impose a
monetary penalty on such employer, firm, or entity if it knew, or
reasonably should have known, of such conduct. Such penalty shall not
exceed the gross income derived (or to be derived) from the conduct
giving rise to the penalty. Any such penalty imposed on an individual
may be in addition to, or in lieu of, any suspension, disbarment, or
censure of such individual.''
(2) Effective date.--The amendments made by this subsection
shall apply to actions taken after the date of the enactment of
this Act.
(b) Tax Shelter Opinions, etc.--Section 330 of such title 31 is
amended by adding at the end the following new subsection:
``(d) Nothing in this section or in any other provision of law
shall be construed to limit the authority of the Secretary of the
Treasury to impose standards applicable to the rendering of written
advice with respect to any entity, transaction plan or arrangement, or
other plan or arrangement, which is of a type which the Secretary
determines as having a potential for tax avoidance or evasion.''

Subtitle B--Other Provisions

SEC. 3021. TREATMENT OF STRIPPED INTERESTS IN BOND AND PREFERRED STOCK
FUNDS, ETC.

(a) In General.--Section 1286 (relating to tax treatment of
stripped bonds) is amended by redesignating subsection (f) as
subsection (g) and by inserting after subsection (e) the following new
subsection:
``(f) Treatment of Stripped Interests in Bond and Preferred Stock
Funds, etc.--In the case of an account or entity substantially all of
the assets of which consist of bonds, preferred stock, or a combination
thereof, the Secretary may by regulations provide that rules similar to
the rules of this section and 305(e), as appropriate, shall apply to
interests in such account or entity to which (but for this subsection)
this section or section 305(e), as the case may be, would not apply.''
(b) Cross Reference.--Subsection (e) of section 305 is amended by
adding at the end the following new paragraph:
``(7) Cross reference.--

``For treatment of stripped interests
in certain accounts or entities holding preferred stock, see section
1286(f).''
(c) Effective Date.--The amendments made by this section shall
apply to purchases and dispositions after the date of the enactment of
this Act.

SEC. 3022. MINIMUM HOLDING PERIOD FOR FOREIGN TAX CREDIT ON WITHHOLDING
TAXES ON INCOME OTHER THAN DIVIDENDS.

(a) In General.--Section 901 is amended by redesignating subsection
(l) as subsection (m) and by inserting after subsection (k) the
following new subsection:
``(l) Minimum Holding Period for Withholding Taxes on Gain and
Income Other Than Dividends etc.--
``(1) In general.--In no event shall a credit be allowed
under subsection (a) for any withholding tax (as defined in
subsection (k)) on any item of income or gain with respect to any
property if--
``(A) such property is held by the recipient of the
item for 15 days or less during the 30-day period
beginning on the date which is 15 days before the date
on which the right to receive payment of such item
arises, or
``(B) to the extent that the recipient of the item
is under an obligation (whether pursuant to a short
sale or otherwise) to make related payments with
respect to positions in substantially similar or
related property.
This paragraph shall not apply to any dividend to which
subsection (k) applies.
``(2) Exception for taxes paid by dealers.--
``(A) In general.--Paragraph (1) shall not apply to
any qualified tax with respect to any property held in
the active conduct in a foreign country of a business
as a dealer in such property.
``(B) Qualified tax.--For purposes of subparagraph
(A), the term `qualified tax' means a tax paid to a
foreign country (other than the foreign country
referred to in subparagraph (A)) if--
``(i) the item to which such tax is
attributable is subject to taxation on a net
basis by the country referred to in
subparagraph (A), and
``(ii) such country allows a credit against
its net basis tax for the full amount of the
tax paid to such other foreign country.
``(C) Dealer.--For purposes of subparagraph (A),
the term `dealer' means--
``(i) with respect to a security, any
person to whom paragraphs (1) and (2) of
subsection (k) would not apply by reason of
paragraph (4) thereof if such security were
stock, and
``(ii) with respect to any other property,
any person with respect to whom such property
is described in section 1221(a)(1).
``(D) Regulations.--The Secretary may prescribe
such regulations as may be appropriate to carry out
this paragraph, including regulations to prevent the
abuse of the exception provided by this paragraph and
to treat other taxes as qualified taxes.
``(3) Exceptions.--The Secretary may by regulation provide
that paragraph (1) shall not apply to property where the
Secretary determines that the application of paragraph (1) to
such property is not necessary to carry out the purposes of
this subsection.
``(4) Certain rules to apply.--Rules similar to the rules
of paragraphs (5), (6), and (7) of subsection (k) shall apply
for purposes of this subsection.
``(5) Determination of holding period.--Holding periods
shall be determined for purposes of this subsection without
regard to section 1235 or any similar rule.''
(b) Conforming Amendment.--The heading of subsection (k) of section
901 is amended by inserting ``on Dividends'' after ``Taxes''.
(c) Effective Date.--The amendments made by this section shall
apply to amounts paid or accrued more than 30 days after the date of
the enactment of this Act.

SEC. 3023. DISALLOWANCE OF CERTAIN PARTNERSHIP LOSS TRANSFERS.

(a) Treatment of Contributed Property With Built-In Loss.--
Paragraph (1) of section 704(c) is amended by striking ``and'' at the
end of subparagraph (A), by striking the period at the end of
subparagraph (B) and inserting ``, and'', and by adding at the end the
following:
``(C) if any property so contributed has a built-in
loss--
``(i) such built-in loss shall be taken
into account only in determining the amount of
items allocated to the contributing partner,
and
``(ii) except as provided in regulations,
in determining the amount of items allocated to
other partners, the basis of the contributed
property in the hands of the partnership shall
be treated as being equal to its fair market
value at the time of contribution.
For purposes of subparagraph (C), the term `built-in loss'
means the excess of the adjusted basis of the property
(determined without regard to subparagraph (C)(ii)) over its
fair market value at the time of contribution.''
(b) Adjustment to Basis of Partnership Property on Transfer of
Partnership Interest if There Is Substantial Built-In Loss.--
(1) Adjustment required.--Subsection (a) of section 743
(relating to optional adjustment to basis of partnership
property) is amended by inserting before the period ``or unless
the partnership has a substantial built-in loss immediately
after such transfer''.
(2) Adjustment.--Subsection (b) of section 743 is amended
by inserting ``or with respect to which there is a substantial
built-in loss immediately after such transfer'' after ``section
754 is in effect''.
(3) Substantial built-in loss.--Section 743 is amended by
adding at the end the following new subsection:
``(d) Substantial Built-In Loss.--
``(1) In general.--For purposes of this section, a
partnership has a substantial built-in loss with respect to a
transfer of an interest in a partnership if the partnership's
adjusted basis in the partnership property exceeds by more than
$250,000 the fair market value of such property.
``(2) Regulations.--The Secretary shall prescribe such
regulations as may be appropriate to carry out the purposes of
paragraph (1) and section 734(d), including regulations
aggregating related partnerships and disregarding property
acquired by the partnership in an attempt to avoid such
purposes.''
(4) Clerical amendments.--
(A) The section heading for section 743 is amended
to read as follows:

``SEC. 743. ADJUSTMENT TO BASIS OF PARTNERSHIP PROPERTY WHERE SECTION
754 ELECTION OR SUBSTANTIAL BUILT-IN LOSS.''

(B) The table of sections for subpart C of part II
of subchapter K of chapter 1 is amended by striking the
item relating to section 743 and inserting the
following new item:

``Sec. 743. Adjustment to basis of
partnership property where
section 754 election or
substantial built-in loss.''
(c) Adjustment to Basis of Undistributed Partnership Property if
There Is Substantial Basis Reduction.--
(1) Adjustment required.--Subsection (a) of section 734
(relating to optional adjustment to basis of undistributed
partnership property) is amended by inserting before the period
``or unless there is a substantial basis reduction''.
(2) Adjustment.--Subsection (b) of section 734 is amended
by inserting ``or unless there is a substantial basis
reduction'' after ``section 754 is in effect''.
(3) Substantial basis reduction.--Section 734 is amended by
adding at the end the following new subsection:
``(d) Substantial Basis Reduction.--
``(1) In general.--For purposes of this section, there is a
substantial basis reduction with respect to a distribution if
the sum of the amounts described in subparagraphs (A) and (B)
of subsection (b)(2) exceeds $250,000.
``(2) Regulations.--

``For regulations to carry out this
subsection, see section 743(d)(2).''
(4) Clerical amendments.--
(A) The section heading for section 734 is amended
to read as follows:

``SEC. 734. ADJUSTMENT TO BASIS OF UNDISTRIBUTED PARTNERSHIP PROPERTY
WHERE SECTION 754 ELECTION OR SUBSTANTIAL BASIS
REDUCTION.''

(B) The table of sections for subpart B of part II
of subchapter K of chapter 1 is amended by striking the
item relating to section 734 and inserting the
following new item:

``Sec. 734. Adjustment to basis of
undistributed partnership
property where section 754
election or substantial basis
reduction.''
(d) Effective Dates.--
(1) Subsection (a).--The amendment made by subsection (a)
shall apply to contributions made after the date of the
enactment of this Act.
(2) Subsection (b).--The amendments made by subsection (b)
shall apply to transfers after the date of the enactment of
this Act.
(3) Subsection (c).--The amendments made by subsection (c)
shall apply to distributions after the date of the enactment of
this Act.

SEC. 3024. NO REDUCTION OF BASIS UNDER SECTION 734 IN STOCK HELD BY
PARTNERSHIP IN CORPORATE PARTNER.

(a) In General.--Section 755 is amended by adding at the end the
following new subsection:
``(c) No Allocation of Basis Decrease to Stock of Corporate
Partner.--In making an allocation under subsection (a) of any decrease
in the adjusted basis of partnership property under section 734(b)--
``(1) no allocation may be made to stock in a corporation
(or any person related (within the meaning of sections 267(b)
and 707(b)(1)) to such corporation) which is a partner in the
partnership, and
``(2) any amount not allocable to stock by reason of
paragraph (1) shall be allocated under subsection (a) to other
partnership property.
Gain shall be recognized to the partnership to the extent that the
amount required to be allocated under paragraph (2) to other
partnership property exceeds the aggregate adjusted basis of such other
property immediately before the allocation required by paragraph (2).''
(b) Effective Date.--The amendment made by this section shall apply
to distributions after the date of the enactment of this Act.

SEC. 3025. REPEAL OF SPECIAL RULES FOR FASITS.

(a) In General.--Part V of subchapter M of chapter 1 (relating to
financial asset securitization investment trusts) is hereby repealed.
(b) Conforming Amendments.--
(1) Paragraph (6) of section 56(g) is amended by striking
``REMIC, or FASIT'' and inserting ``or REMIC''.
(2) Clause (ii) of section 382(l)(4)(B) is amended by
striking ``a REMIC to which part IV of subchapter M applies, or
a FASIT to which part V of subchapter M applies,'' and
inserting ``or a REMIC to which part IV of subchapter M
applies,''.
(3) Paragraph (1) of section 582(c) is amended by striking
``, and any regular interest in a FASIT,''.
(4) Subparagraph (E) of section 856(c)(5) is amended by
striking the last sentence.
(5)(A) Section 860G(a)(1) is amended by adding at the end
the following new sentence: ``An interest shall not fail to
qualify as a regular interest solely because the specified
principal amount of the regular interest (or the amount of
interest accrued on the regular interest) can be reduced as a
result of the nonoccurrence of 1 or more contingent payments
with respect to any reverse mortgage loan held by the REMIC if,
on the startup day for the REMIC, the sponsor reasonably
believes that all principal and interest due under the regular
interest will be paid at or prior to the liquidation of the
REMIC.''.
(B) The last sentence of section 860G(a)(3) is amended by
inserting ``, and any reverse mortgage loan (and each balance
increase on such loan meeting the requirements of subparagraph
(A)(iii)) shall be treated as an obligation secured by an
interest in real property'' before the period at the end.
(6) Paragraph (3) of section 860G(a) is amended by adding
``and'' at the end of subparagraph (B), by striking ``, and''
at the end of subparagraph (C) and inserting a period, and by
striking subparagraph (D).
(7) Section 860G(a)(3) is amended by adding at the end the
following new sentence: ``For purposes of subparagraph (A), if
more than 50 percent of the obligations transferred to, or
purchased by, the REMIC are originated by the United States or
any State (or any political subdivision, agency, or
instrumentality of the United States or any State) and are
principally secured by an interest in real property, then each
obligation transferred to, or purchased by, the REMIC shall be treated
as secured by an interest in real property.''.
(8)(A) Section 860G(a)(3)(A) is amended by striking ``or''
at the end of clause (i), by inserting ``or'' at the end of
clause (ii), and by inserting after clause (ii) the following
new clause:
``(iii) represents an increase in the
principal amount under the original terms of an
obligation described in clause (i) or (ii) if--
``(I) such increase in the balance
is attributable to an advance made to
the obligor pursuant to the original
terms of the obligation,
``(II) such increase in the balance
occurs after the startup day, and
``(III) such increase in the
balance is purchased by the REMIC
pursuant to a fixed price contract in
effect on the startup day.''.
(B) Section 860G(a)(7)(B) is amended to read as follows:
``(B) Qualified reserve fund.--For purposes of
subparagraph (A), the term `qualified reserve fund'
means any reasonably required reserve to--
``(i) provide for full payment of expenses
of the REMIC or amounts due on regular
interests in the event of defaults on qualified
mortgages or lower than expected returns on
cash flow investments, or
``(ii) provide a source of funds for the
purchase of obligations described in clause
(ii) or (iii) of paragraph (3)(A).
The aggregate fair market value of the assets held in
any such reserve shall not exceed 50 percent of the
aggregate fair market value of all of the assets of the
REMIC on the startup day, and the amount of any such
reserve shall be promptly and appropriately reduced to
the extent the amount held in such reserve is no longer
reasonably required for purposes specified in clause
(i) or (ii) of paragraph (3)(A).''.
(9) Subparagraph (C) of section 1202(e)(4) is amended by
striking ``REMIC, or FASIT'' and inserting ``or REMIC''.
(10) Section 1272(a)(6)(B) is amended by adding at the end
the following new flush sentence:
``For purposes of clause (iii), the Secretary shall
prescribe regulations permitting the use of a current
prepayment assumption, determined as of the close of
the accrual period (or such other time as the Secretary
may prescribe during the taxable year in which the
accrual period ends).''.
(11) Subparagraph (C) of section 7701(a)(19) is amended by
adding ``and'' at the end of clause (ix), by striking ``, and''
at the end of clause (x) and inserting a period, and by
striking clause (xi).
(12) The table of parts for subchapter M of chapter 1 is
amended by striking the item relating to part V.
(c) Effective Date.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
beginning after December 31, 2003.
(2) Exception for existing fasits.--
(A) In general.--Paragraph (1) shall not apply to
any FASIT in existence on the date of the enactment of
this Act to the extent that regular interests issued by
the FASIT before such date continue to remain
outstanding in accordance with the original terms of
issuance.
(B) Transfer of additional assets not permitted.--
Except as provided in regulations prescribed by the
Secretary of the Treasury or the Secretary's delegate,
subparagraph (A) shall cease to apply as of the
earliest date after the date of the enactment of this
Act that any property is transferred to the FASIT.

SEC. 3026. LIMITATION ON TRANSFER OF BUILT-IN LOSSES ON REMIC
RESIDUALS.

(a) In General.--Section 362 (relating to basis to corporations) is
amended by adding at the end the following new subsection:
``(e) Limitation on Transfer of Built-in Losses on REMIC Residuals
in Section 351 Transactions.--If--
``(1) a residual interest (as defined in section
860G(a)(2)) in a REMIC is transferred in any transaction which
is described in subsection (a), and
``(2) the transferee's adjusted basis in such residual
interest would (but for this paragraph) exceed its fair market
value immediately after such transaction,
then, notwithstanding subsection (a), the transferee's adjusted basis
in such residual interest shall not exceed its fair market value
(whether or not greater than zero) immediately after such
transaction.''
(b) Effective Date.--The amendment made by this section shall apply
to transactions after the date of the enactment of this Act.

SEC. 3027. CLARIFICATION OF BANKING BUSINESS FOR PURPOSES OF
DETERMINING INVESTMENT OF EARNINGS IN UNITED STATES
PROPERTY.

(a) In General.--Subparagraph (A) of section 956(c)(2) is amended
to read as follows:
``(A) obligations of the United States, money, or
deposits with any corporation with respect to which a
bank holding company (within the meaning of section
2(a) of the Bank Holding Company Act of 1956 (12 U.S.C.
1841(a))) or financial holding company (within the
meaning of section 2(p) of such Act) owns directly or
indirectly more than 80 percent by vote or value of the
stock of such corporation;''.
(b) Effective Date.--The amendment made by this section shall take
effect on the date of the enactment of this Act.

SEC. 3028. MODIFICATIONS RELATED TO CERTAIN SMALL INSURANCE COMPANIES.

(a) Exemption for Small Property and Casualty Insurance
Companies.--
(1) In general.--Section 501(c)(15)(A) is amended to read
as follows:
``(A) Insurance companies (as defined in section
816(a)) other than life (including interinsurers and
reciprocal underwriters) if--
``(i) the gross receipts for the taxable
year do not exceed $600,000, and
``(ii) more than 50 percent of such gross
receipts consist of premiums.''.
(2) Controlled group rule.--Section 501(c)(15)(C) is
amended by inserting ``, except that in applying section 1563
for purposes of section 831(b)(2)(B)(ii), subparagraphs (B) and
(C) of section 1563(b)(2) shall be disregarded'' before the
period at the end.
(3) Conforming amendment.--Clause (i) of section
831(b)(2)(A) is amended by striking ``exceed $350,000 but''.
(b) Alternative Tax for Certain Small Insurance Companies.--
(1) Increased limitation.--Clause (i) of section
831(b)(2)(A) is amended by striking ``$1,200,000'' and
inserting ``$1,890,000''.
(2) Inflation adjustment.--Paragraph (2) of section 831(b)
is amended by adding at the end the following new subparagraph:
``(C) Inflation adjustment.--In the case of any
taxable year beginning in a calendar year after 2004,
the $1,890,000 amount in subparagraph (A) shall be
increased by an amount equal to--
``(i) $1,890,000, multiplied by
``(ii) the cost-of-living adjustment
determined under section 1(f)(3) for such
calendar year by substituting `calendar year
2003' for `calendar year 1992' in subparagraph
(B) thereof.
If the amount as adjusted under the preceding sentence
is not a multiple of $1,000, such amount shall be
rounded to the next lowest multiple of $1,000.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 3029. DEFINITION OF INSURANCE COMPANY FOR SECTION 831.

(a) In General.--Section 831 is amended by redesignating subsection
(c) as subsection (d) and by inserting after subsection (b) the
following new subsection:
``(c) Insurance Company Defined.--For purposes of this section, the
term `insurance company' has the meaning given to such term by section
816(a).''
(b) Effective Date.--The amendment made by this section shall apply
to taxable years beginning after December 31, 2003.

SEC. 3030. DENIAL OF DEDUCTION FOR INTEREST ON UNDERPAYMENTS
ATTRIBUTABLE TO NONDISCLOSED REPORTABLE TRANSACTIONS.

(a) In General.--Section 163 (relating to deduction for interest)
is amended by redesignating subsection (m) as subsection (n) and by
inserting after subsection (l) the following new subsection:
``(m) Interest on Unpaid Taxes Attributable to Nondisclosed
Reportable Transactions.--No deduction shall be allowed under this
chapter for any interest paid or accrued under section 6601 on any
underpayment of tax which is attributable to the portion of any
reportable transaction understatement (as defined in section 6662A(b))
with respect to which the requirement of section 6664(d)(2)(A) is not
met.''.
(b) Effective Date.--The amendments made by this section shall
apply to transactions in taxable years beginning after the date of the
enactment of this Act.

SEC. 3031. CLARIFICATION OF RULES FOR PAYMENT OF ESTIMATED TAX FOR
CERTAIN DEEMED ASSET SALES.

(a) In General.--Paragraph (13) of section 338(h) (relating to tax
on deemed sale not taken into account for estimated tax purposes) is
amended by adding at the end the following: ``The preceding sentence
shall not apply with respect to a qualified stock purchase for which an
election is made under paragraph (10).''.
(b) Effective Date.--The amendment made by subsection (a) shall
apply to transactions occurring after the date of the enactment of this
Act.

SEC. 3032. RECOGNITION OF GAIN FROM THE SALE OF A PRINCIPAL RESIDENCE
ACQUIRED IN A LIKE-KIND EXCHANGE WITHIN 5 YEARS OF SALE.

(a) In General.--Section 121(d) (relating to special rules for
exclusion of gain from sale of principal residence) is amended by
adding at the end the following new paragraph:
``(10) Property acquired in like-kind exchange.--If a
taxpayer acquired property in an exchange to which section 1031
applied, subsection (a) shall not apply to the sale or exchange
of such property if it occurs during the 5-year period
beginning with the date of the acquisition of such property.''.
(b) Effective Date.--The amendment made by this section shall apply
to sales or exchanges after the date of the enactment of this Act.

SEC. 3033. PREVENTION OF MISMATCHING OF INTEREST AND ORIGINAL ISSUE
DISCOUNT DEDUCTIONS AND INCOME INCLUSIONS IN TRANSACTIONS
WITH RELATED FOREIGN PERSONS.

(a) Original Issue Discount.--Section 163(e)(3) (relating to
special rule for original issue discount on obligation held by related
foreign person) is amended by redesignating subparagraph (B) as
subparagraph (C) and by inserting after subparagraph (A) the following
new subparagraph:
``(B) Special rule for certain foreign entities.--
``(i) In general.--In the case of any debt
instrument having original issue discount which
is held by a related foreign person which is a
foreign personal holding company (as defined in
section 552), a controlled foreign corporation
(as defined in section 957), or a passive
foreign investment company (as defined in
section 1297), a deduction shall be allowable to the issuer with
respect to such original issue discount for any taxable year before the
taxable year in which paid only to the extent such original issue
discount is included during such prior taxable year in the gross income
of a United States person who owns (within the meaning of section
958(a)) stock in such corporation.
``(ii) Secretarial authority.--The
Secretary may by regulation exempt transactions
from the application of clause (i), including
any transaction which is entered into by a
payor in the ordinary course of a trade or
business in which the payor is predominantly
engaged.''.
(b) Interest and Other Deductible Amounts.--Section 267(a)(3) is
amended--
(1) by striking ``The Secretary'' and inserting:
``(A) In general.--The Secretary'', and
(2) by adding at the end the following new subparagraph:
``(B) Special rule for certain foreign entities.--
``(i) In general.--Notwithstanding
subparagraph (A), in the case of any amount
payable to a foreign personal holding company
(as defined in section 552), a controlled
foreign corporation (as defined in section
957), or a passive foreign investment company
(as defined in section 1297), a deduction shall
be allowable to the payor with respect to such
amount for any taxable year before the taxable
year in which paid only to the extent such
amount is included during such prior taxable
year in the gross income of a United States
person who owns (within the meaning of section
958(a)) stock in such corporation.
``(ii) Secretarial authority.--The
Secretary may by regulation exempt transactions
from the application of clause (i), including
any transaction which is entered into by a
payor in the ordinary course of a trade or
business in which the payor is predominantly
engaged and in which the payment of the accrued
amounts occurs within 8\1/2\ months after
accrual or within such other period as the
Secretary may prescribe.''.
(c) Effective Date.--The amendments made by this section shall
apply to payments accrued on or after the date of the enactment of this
Act.

SEC. 3034. EXCLUSION FROM GROSS INCOME FOR INTEREST ON OVERPAYMENTS OF
INCOME TAX BY INDIVIDUALS.

(a) In General.--Part III of subchapter B of chapter 1 (relating to
items specifically excluded from gross income) is amended by inserting
after section 139A the following new section:

``SEC. 139B. EXCLUSION FROM GROSS INCOME FOR INTEREST ON OVERPAYMENTS
OF INCOME TAX BY INDIVIDUALS.

``(a) In General.--In the case of an individual, gross income shall
not include interest paid under section 6611 on any overpayment of tax
imposed by this subtitle.
``(b) Exception.--Subsection (a) shall not apply in the case of a
failure to claim items resulting in the overpayment on the original
return if the Secretary determines that the principal purpose of such
failure is to take advantage of subsection (a).
``(c) Special Rule for Determining Modified Adjusted Gross
Income.--For purposes of this title, interest not included in gross
income under subsection (a) shall not be treated as interest which is
exempt from tax for purposes of sections 32(i)(2)(B) and 6012(d) or any
computation in which interest exempt from tax under this title is added
to adjusted gross income.''.
(b) Clerical Amendment.--The table of sections for part III of
subchapter B of chapter 1 is amended by inserting after the item
relating to section 139A the following new item:

``Sec. 139B. Exclusion from gross income
for interest on overpayments of
income tax by individuals.''.
(c) Effective Date.--The amendments made by this section shall
apply to interest received in calendar years beginning after the date
of the enactment of this Act.

SEC. 3035. DEPOSITS MADE TO SUSPEND RUNNING OF INTEREST ON POTENTIAL
UNDERPAYMENTS.

(a) In General.--Subchapter A of chapter 67 (relating to interest
on underpayments) is amended by adding at the end the following new
section:

``SEC. 6603. DEPOSITS MADE TO SUSPEND RUNNING OF INTEREST ON POTENTIAL
UNDERPAYMENTS, ETC.

``(a) Authority To Make Deposits Other Than As Payment of Tax.--A
taxpayer may make a cash deposit with the Secretary which may be used
by the Secretary to pay any tax imposed under subtitle A or B or
chapter 41, 42, 43, or 44 which has not been assessed at the time of
the deposit. Such a deposit shall be made in such manner as the
Secretary shall prescribe.
``(b) No Interest Imposed.--To the extent that such deposit is used
by the Secretary to pay tax, for purposes of section 6601 (relating to
interest on underpayments), the tax shall be treated as paid when the
deposit is made.
``(c) Return of Deposit.--Except in a case where the Secretary
determines that collection of tax is in jeopardy, the Secretary shall
return to the taxpayer any amount of the deposit (to the extent not
used for a payment of tax) which the taxpayer requests in writing.
``(d) Payment of Interest.--
``(1) In general.--For purposes of section 6611 (relating
to interest on overpayments), a deposit which is returned to a
taxpayer shall be treated as a payment of tax for any period to
the extent (and only to the extent) attributable to a
disputable tax for such period. Under regulations prescribed by
the Secretary, rules similar to the rules of section 6611(b)(2)
shall apply.
``(2) Disputable tax.--
``(A) In general.--For purposes of this section,
the term `disputable tax' means the amount of tax
specified at the time of the deposit as the taxpayer's
reasonable estimate of the maximum amount of any tax attributable to
disputable items.
``(B) Safe harbor based on 30-day letter.--In the
case of a taxpayer who has been issued a 30-day letter,
the maximum amount of tax under subparagraph (A) shall
not be less than the amount of the proposed deficiency
specified in such letter.
``(3) Other definitions.--For purposes of paragraph (2)--
``(A) Disputable item.--The term `disputable item'
means any item of income, gain, loss, deduction, or
credit if the taxpayer--
``(i) has a reasonable basis for its
treatment of such item, and
``(ii) reasonably believes that the
Secretary also has a reasonable basis for
disallowing the taxpayer's treatment of such
item.
``(B) 30-day letter.--The term `30-day letter'
means the first letter of proposed deficiency which
allows the taxpayer an opportunity for administrative
review in the Internal Revenue Service Office of
Appeals.
``(4) Rate of interest.--The rate of interest allowable
under this subsection shall be the Federal short-term rate
determined under section 6621(b), compounded daily.
``(e) Use of Deposits.--
``(1) Payment of tax.--Except as otherwise provided by the
taxpayer, deposits shall be treated as used for the payment of
tax in the order deposited.
``(2) Returns of deposits.--Deposits shall be treated as
returned to the taxpayer on a last-in, first-out basis.''.
(b) Clerical Amendment.--The table of sections for subchapter A of
chapter 67 is amended by adding at the end the following new item:

``Sec. 6603. Deposits made to suspend
running of interest on
potential underpayments,
etc.''.
(c) Effective Date.--
(1) In general.--The amendments made by this section shall
apply to deposits made after the date of the enactment of this
Act.
(2) Coordination with deposits made under revenue procedure
84-58.--In the case of an amount held by the Secretary of the
Treasury or his delegate on the date of the enactment of this
Act as a deposit in the nature of a cash bond deposit pursuant
to Revenue Procedure 84-58, the date that the taxpayer
identifies such amount as a deposit made pursuant to section
6603 of the Internal Revenue Code (as added by this Act) shall
be treated as the date such amount is deposited for purposes of
such section 6603.

SEC. 3036. PARTIAL PAYMENT OF TAX LIABILITY IN INSTALLMENT AGREEMENTS.

(a) In General.--
(1) Section 6159(a) (relating to authorization of
agreements) is amended--
(A) by striking ``satisfy liability for payment
of'' and inserting ``make payment on'', and
(B) by inserting ``full or partial'' after
``facilitate''.
(2) Section 6159(c) (relating to Secretary required to
enter into installment agreements in certain cases) is amended
in the matter preceding paragraph (1) by inserting ``full''
before ``payment''.
(b) Requirement To Review Partial Payment Agreements Every Two
Years.--Section 6159 is amended by redesignating subsections (d) and
(e) as subsections (e) and (f), respectively, and inserting after
subsection (c) the following new subsection:
``(d) Secretary Required To Review Installment Agreements for
Partial Collection Every Two Years.--In the case of an agreement
entered into by the Secretary under subsection (a) for partial
collection of a tax liability, the Secretary shall review the agreement
at least once every 2 years.''.
(c) Effective Date.--The amendments made by this section shall
apply to agreements entered into on or after the date of the enactment
of this Act.

SEC. 3037. EXTENSION OF IRS USER FEES.

(a) In General.--Section 7528(c) (relating to termination) is
amended by striking ``December 31, 2004'' and inserting ``September 30,
2013''.
(b) Effective Date.--The amendment made by this section shall apply
to requests after the date of the enactment of this Act.

TITLE IV--TRADE ENHANCEMENT AND COMPLIANCE PROVISIONS

SEC. 4001. REPEAL OF EXCLUSION FOR EXTRATERRITORIAL INCOME.

(a) In General.--Section 114 is hereby repealed.
(b) Conforming Amendments.--
(1) Subpart E of part III of subchapter N of chapter 1
(relating to qualifying foreign trade income) is hereby
repealed.
(2) The table of subparts for such part III is amended by
striking the item relating to subpart E.
(3) The table of sections for part III of subchapter B of
chapter 1 is amended by striking the item relating to section
114.
(c) Effective Date.--Except as provided in subsection (d), the
amendments made by this section shall apply to transactions after
December 31, 2003.
(d) Transitional Rule for 2004, 2005, and 2006.--
(1) In general.--In the case of transactions during 2004,
2005, or 2006, the amount includible in gross income by reason
of the amendments made by this section shall not exceed the
applicable percentage of the amount which would have been so
included but for this subsection.
(2) Applicable percentage.--For purposes of paragraph (1),
the applicable percentage shall be as follows:
(A) For 2004, the applicable percentage shall be 20
percent.
(B) For 2005, the applicable percentage shall be 20
percent.
(C) For 2006, the applicable percentage shall be 40
percent.
(e) Revocation of Election To Be Treated as Domestic Corporation.--
If, during the 1-year period beginning on the date of the enactment of
this Act, a corporation for which an election is in effect under
section 943(e) of the Internal Revenue Code of 1986 revokes such
election, no gain or loss shall be recognized with respect to property
treated as transferred under clause (ii) of section 943(e)(4)(B) of
such Code to the extent such property--
(1) was treated as transferred under clause (i) thereof, or
(2) was acquired during a taxable year to which such
election applies and before May 1, 2003, in the ordinary course
of its trade or business.
The Secretary of the Treasury (or such Secretary's delegate) may
prescribe such regulations as may be necessary to prevent the abuse of
the purposes of this subsection.
(f) Binding Contracts.--The amendments made by this section shall
not apply to any transaction in the ordinary course of a trade or
business which occurs pursuant to a binding contract--
(1) which is between the taxpayer and a person who is not a
related person (as defined in section 943(b)(3) of such Code,
as in effect on the day before the date of the enactment of
this Act), and
(2) which is in effect on January 14, 2002, and at all
times thereafter.
For purposes of this subsection, a binding contract shall include a
purchase option, renewal option, or replacement option which is
included in such contract and which is enforceable against the seller
or lessor.

SEC. 4002. COBRA FEES.

(a) Use of Merchandise Processing Fee.--Section 13031(f) of the
Consolidated Omnibus Budget Reconciliation Act of 1985 (19 U.S.C.
58c(f)) is amended--
(1) in paragraph (1), by aligning subparagraph (B) with
subparagraph (A); and
(2) in paragraph (2), by striking ``commercial operations''
and all that follows through ``processing.'' and inserting
``customs revenue functions as defined in section 415 of the
Homeland Security Act of 2002 (other than functions performed
by the Office of International Affairs referred to in section
415(8) of that Act), and for automation (including the
Automation Commercial Environment computer system), and for no
other purpose. To the extent that funds in the Customs User Fee
Account are insufficient to pay the costs of such customs
revenue functions, customs duties in an amount equal to the
amount of such insufficiency shall be available, to the extent
provided for in appropriations Acts, to pay the costs of such
customs revenue functions in the amount of such insufficiency,
and shall be available for no other purpose. The provisions of
the first and second sentences of this paragraph specifying the
purposes for which amounts in the Customs User Fee Account may
be made available shall not be superseded except by a provision
of law which specifically modifies or supersedes such
provisions.''.
(b) Reimbursement of Appropriations From COBRA Fees.--Section
13031(f)(3) of the Consolidated Omnibus Budget Reconciliation Act of
1985 (19 U.S.C. 58c(f)(3)) is amended by adding at the end the
following:
``(E) Nothing in this paragraph shall be construed to preclude the
use of appropriated funds, from sources other than the fees collected
under subsection (a), to pay the costs set forth in clauses (i), (ii),
and (iii) of subparagraph (A).''.
(c) Sense of Congress; Effective Period for Collecting Fees;
Standard for Setting Fees.--
(1) Sense of congress.--The Congress finds that--
(A) the fees set forth in paragraphs (1) through
(8) of subsection (a) of section 13031 of the
Consolidated Omnibus Budget Reconciliation Act of 1985
have been reasonably related to the costs of providing
customs services in connection with the activities or
items for which the fees have been charged under such
paragraphs; and
(B) the fees collected under such paragraphs have
not exceeded, in the aggregate, the amounts paid for
the costs described in subsection (f)(3)(A) incurred in
providing customs services in connection with the
activities or items for which the fees were charged
under such paragraphs.
(2) Effective period; standard for setting fees.--Section
13031(j)(3) of the Consolidated Omnibus Budget Reconciliation
Act of 1985 is amended to read as follows:
``(3)(A) Fees may not be charged under paragraphs (9) and (10) of
subsection (a) after September 30, 2013.
``(B)(i) Subject to clause (ii), Fees may not be charged under
paragraphs (1) through (8) of subsection (a) after September 30, 2013.
``(ii) In fiscal year 2006 and in each succeeding fiscal year for
which fees under paragraphs (1) through (8) of subsection (a) are
authorized--
``(I) the Secretary of the Treasury shall charge fees under
each such paragraph in amounts that are reasonably related to
the costs of providing customs services in connection with the
activity or item for which the fee is charged under such
paragraph, except that in no case may the fee charged under any
such paragraph exceed by more than 10 percent the amount
otherwise prescribed by such paragraph;
``(II) the amount of fees collected under such paragraphs
may not exceed, in the aggregate, the amounts paid in that
fiscal year for the costs described in subsection (f)(3)(A)
incurred in providing customs services in connection with the
activity or item for which the fees are charged under such
paragraphs;
``(III) a fee may not be collected under any such paragraph
except to the extent such fee will be expended to pay the costs
described in subsection (f)(3)(A) incurred in providing customs
services in connection with the activity or item for which the
fee is charged under such paragraph; and
``(IV) any fee collected under any such paragraph shall be
available for expenditure only to pay the costs described in
subsection (f)(3)(A) incurred in providing customs services in
connection with the activity or item for which the fee is
charged under such paragraph.''.
(d) Clerical Amendments.--Section 13031 of the Consolidated Omnibus
Budget Reconciliation Act of 1985 is amended--
(1) in subsection (a)(5)(B), by striking ``$1.75'' and
inserting ``$1.75.'';
(2) in subsection (b)--
(A) in paragraph (1)(A), by aligning clause (iii)
with clause (ii);
(B) in paragraph (7), by striking ``paragraphs''
and inserting ``paragraph''; and
(C) in paragraph (9), by aligning subparagraph (B)
with subparagraph (A); and
(3) in subsection (e)(2), by aligning subparagraph (B) with
subparagraph (A).
(e) Study of All Fees Collected by Department of Homeland
Security.--The Secretary of the Treasury shall conduct a study of all
the fees collected by the Department of Homeland Security, and shall
submit to the Congress, not later than September 30, 2005, a report
containing the recommendations of the Secretary on--
(1) what fees should be eliminated;
(2) what the rate of fees retained should be; and
(3) any other recommendations with respect to the fees that
the Secretary considers appropriate.

Union Calendar No. 226

108th CONGRESS

1st Session

H. R. 2896

[Report No. 108-393]

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to remove impediments in
such Code and make our manufacturing, service, and high-technology
businesses and workers more competitive and productive both at home and
abroad.

_______________________________________________________________________

November 21, 2003

Reported with an amendment, committed to the Committee of the Whole
House on the State of the Union, and ordered to be printed